
 South America Gluten Free Foods and Beverages Market | 2026-2036
South America Gluten Free Foods and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
South America Gluten Free Foods and Beverages Market Analytics
Brazil's updated gluten-free labeling standards from ANVISA is hardening product formulation requirements across the region. Dr. Schär leverages its dedicated gluten-free manufacturing infrastructure to sustain premium positioning in Argentine supermarkets. Molinos Río de la Plata anchors regional supply through its integrated grain milling network. Nestlé S.A. competes via broad distribution reach spanning conventional retail and health food channels.
Gluten free foods and beverages comprise products formulated without wheat, barley, rye, or cross-contaminated oats, typically substituting rice flour, tapioca starch, or almond flour to achieve comparable texture and shelf stability. These products serve celiac patients, gluten-sensitive consumers, and health-oriented buyers seeking reduced-inflammatory diets. Bakery applications dominate current revenue due to bread and pasta replacement demand, while snack formulations represent the fastest-expanding category as portable formats penetrate convenience retail. Beverage segments command narrower volume but extract premium pricing through functional positioning with probiotic or protein fortification.
ANVISA in Brazil and Argentina's national food code regulator enforce gluten-free certification thresholds below 20 ppm, shaping import compliance costs and domestic production investments. Brazil's SINCA system tracks allergen-related adverse events, pressuring manufacturers toward third-party laboratory verification. Stakeholders must monitor evolving Mercosur harmonization talks, as unified standards would reshape cross-border manufacturing location decisions and tariff exposure.
Market Dynamics
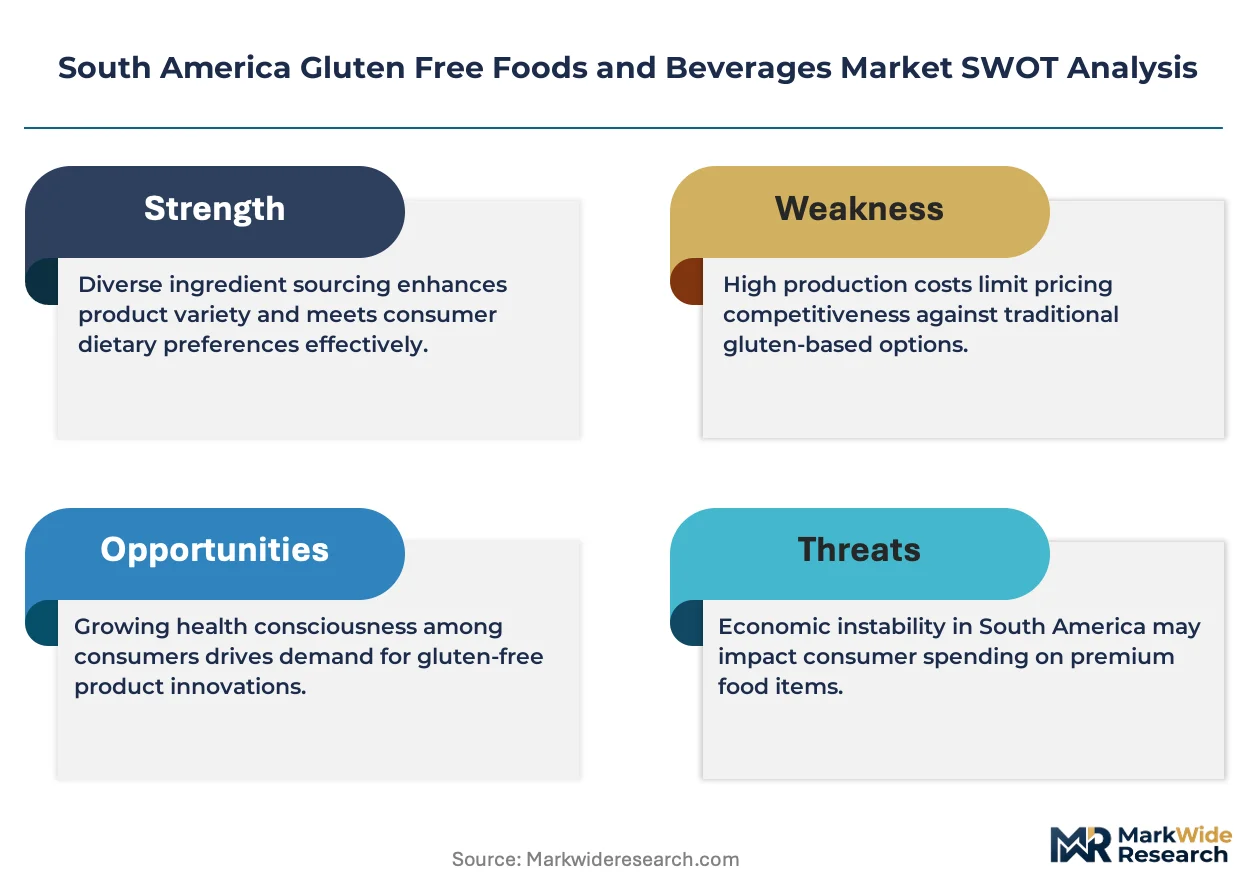
ANVISA's updated gluten-free labeling standards are compressing formulation tolerances across South American manufacturing, forcing producers to retest supply chains and recalibrate quality assurance protocols.
Growth Catalysts
- Celiac Disease Diagnoses:Rising clinical screening rates in Brazilian urban centers are expanding the addressable patient population beyond self-diagnosed consumers.
- ANVISA Certification Thresholds:Brazil's sub-20 ppm enforcement is legitimizing premium pricing for verified products and accelerating retail shelf-space allocation.
- São Paulo Metropolitan Demand:Concentrated health-conscious purchasing power in Brazil's southeast corridor is sustaining volume commitments from conventional supermarket chains.
Market Restraints
- Input Cost Volatility:Tapioca starch and rice flour prices fluctuate with Brazilian agricultural yields, compressing margin stability for mid-tier producers.
- Laboratory Verification Bottlenecks:Third-party gluten testing capacity concentrates in São Paulo and Buenos Aires, creating regional certification delays.
- Substitution Threat:Naturally gluten-free whole foods (quinoa, cassava, corn) compete directly with formulated products on price and perceived authenticity.
Strategic Opportunities
- Argentine Interior Expansion:Córdoba and Mendoza provinces show underpenetrated retail gluten-free shelf space relative to diagnosed celiac prevalence.
- Probiotic Beverage Fortification:Functional positioning combining gluten-free claims with gut health benefits commands price premiums in Brazilian pharmacy channels.
- Mercosur Harmonization:Pending unified standards would eliminate cross-border retesting burdens for manufacturers with multi-country distribution.
Industry Challenges
- Cross-Contamination Control:Shared milling infrastructure requires segregated production runs, extending batch cycle times and complicating scheduling.
- Ingredient Sourcing Integrity:Oat supply chains demand verified gluten-free cultivation and transport protocols, limiting supplier pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Gluten Free Foods and Beverages Market |
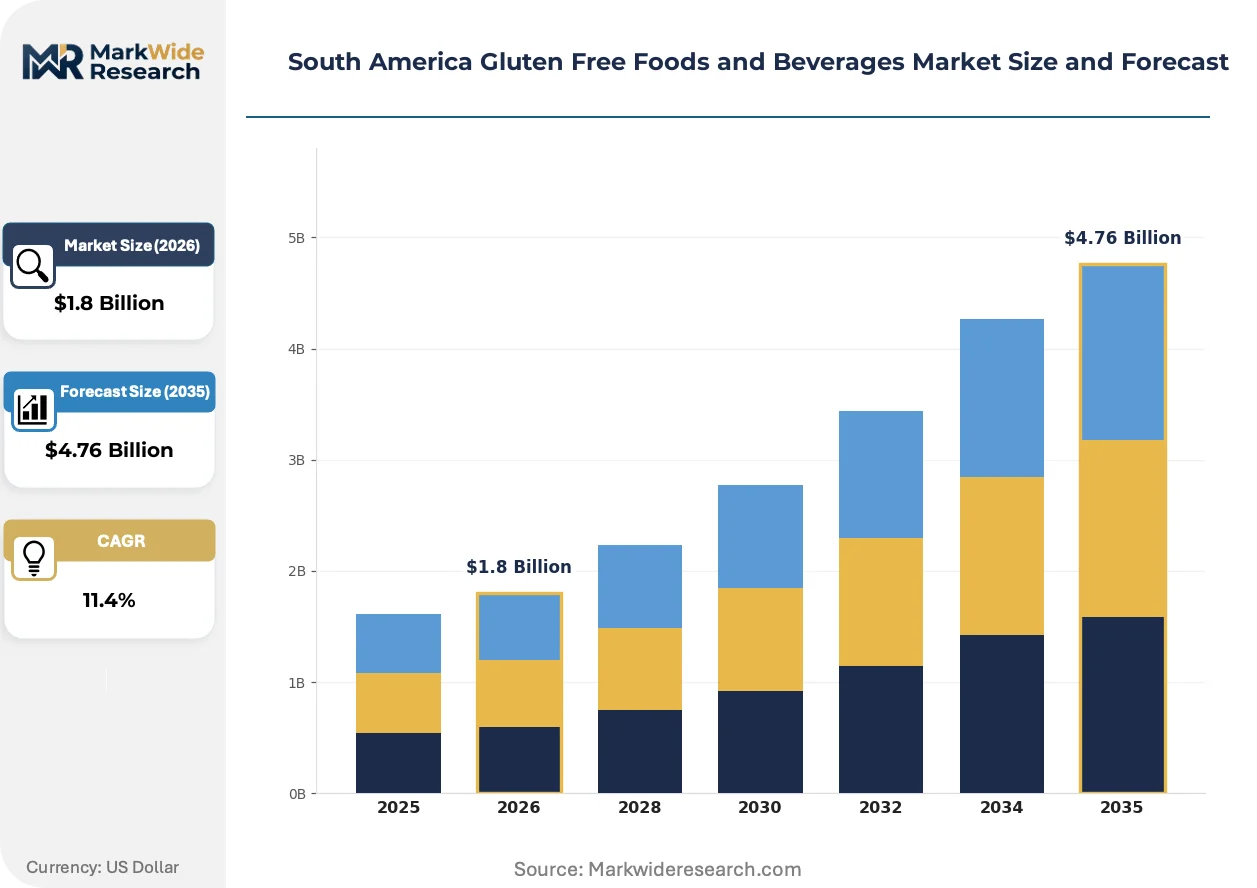
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Bakery, Beverages, Dairy End User: Retail Consumers, Food Service, Health-Conscious Individuals, Athletes Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores Ingredient Type: Rice Flour, Almond Flour, Corn Starch, Tapioca Starch |
| Companies Covered | Bob's Red Mill, Dr. Schär, General Mills Inc., Molinos Río de la Plata, The Kraft Heinz Company, The Hain Celestial Group, Barilla G. e R. Fratelli S.p.A., Nestlé S.A., Brazi Bites, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Gluten Free Foods and Beverages Market Evolving Landscape
Ingredient processing technologies and distribution channel evolution are restructuring how gluten-free products reach South American consumers. Three developments merit particular attention.
Extrusion technology for gluten-free pasta and snack matrices is modularizing production flexibility across Brazilian contract manufacturers. Mid-size bakeries in Rio de Janeiro and São Paulo are adopting compact extrusion lines to switch between rice-based and legume-based formulations within single shifts. This capability is compressing minimum viable batch sizes and enabling private-label proliferation without dedicated facilities.
Argentina's national food code updates are mandating clearer gluten-free iconography and stricter cross-contamination warnings on imported goods. The regulatory friction is redirecting Argentine supermarket procurement toward domestic suppliers with established in-country laboratory relationships. Brazilian exporters to Argentina are responding by pre-certifying production runs through Buenos Aires-based testing facilities.
Pharmacy channel penetration is accelerating as Brazilian consumers associate gluten-free claims with medical legitimacy rather than lifestyle preference. Drugstore chains in São Paulo are dedicating discrete shelf sections to certified products, displacing traditional health food store traffic. This channel rotation is most pronounced among diagnosed celiac patients seeking purchase reassurance through pharmacy credibility.
South America Gluten Free Foods and Beverages Market Segmentation
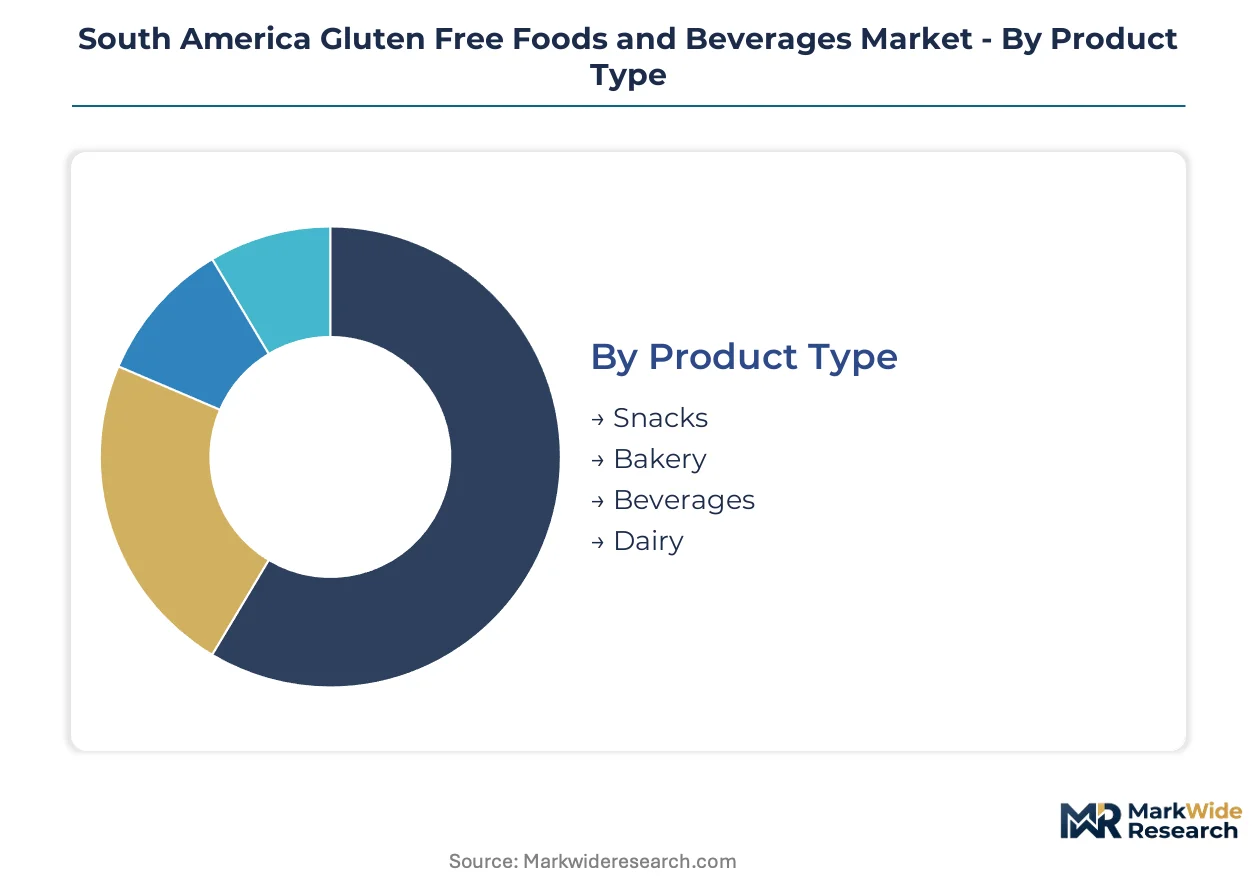
Segmentation in the South America gluten-free market reveals distinct capital requirements and margin profiles across product formats. Understanding these divisions enables manufacturers to align production investments with the specific compliance and distribution demands of each category.
Product Type:
Bakery commands the heaviest upfront investment due to dedicated extrusion lines and segregated milling infrastructure required for ANVISA certification.
- Bakery:Bread, pasta, and cake formulations rely on rice flour and tapioca starch matrices to replicate gluten's binding properties. São Paulo's metropolitan corridor sustains the highest per-capita consumption, though shelf-stable packaging requirements inflate working capital needs.
- Snacks:Extruded chips, crackers, and bars achieve faster batch cycles with modular equipment configurations. Rio de Janeiro's convenience retail density is driving portable format penetration, with probiotic fortification commanding pharmacy channel placement.
- Beverages:Functional positioning with protein or gut-health additives targets Brazilian pharmacy and health food channels.
- Dairy:Yogurt and milk alternatives with gluten-free claims serve lactose-intolerant crossover demand in Argentine supermarkets.
Bakery absorbs the bulk of installed capacity; snacks are expanding most quickly.
End User:
Customer type determines pricing power, with diagnosed medical users accepting steeper premiums than lifestyle-oriented buyers.
- Retail Consumers:Brazilian households in São Paulo and Rio de Janeiro metro areas drive volume through conventional supermarket channels. ANVISA's sub-20 ppm labeling enforcement has shifted purchase decisions toward certified SKUs with third-party verification marks.
- Health-Conscious Individuals:Self-diagnosed gluten-sensitive buyers in Argentina's Córdoba and Mendoza provinces prioritize clean-label ingredient lists over medical certification. This segment exhibits higher brand switching and price elasticity.
- Food Service:Restaurants and cafeterias in Brazilian urban centers require bulk formats with batch-traceable documentation.
- Athletes:Sports nutrition positioning with protein fortification targets gym-adjacent retail in Buenos Aires.
Retail consumers absorb the bulk of installed capacity; health-conscious individuals are climbing the fastest.
Distribution Channel:
Channel selection dictates margin structure, with pharmacy and online formats extracting premiums over mass retail.
- Supermarkets:Brazilian chains in the southeast corridor dedicate expanding shelf sections to certified gluten-free products. ANVISA compliance requirements have raised listing fees and slotting allowances for new entrants.
- Online Retail:Direct-to-consumer platforms serve Argentina's interior provinces with limited health food store penetration. Subscription models for diagnosed celiac patients reduce purchase friction through automated reordering.
- Health Food Stores:Buenos Aires and São Paulo specialty retailers emphasize curated assortments with full ingredient transparency.
- Convenience Stores:Portable snack formats target impulse purchase occasions in Brazilian urban transit corridors.
Supermarkets absorb the bulk of installed capacity; online retail is gaining share fastest.
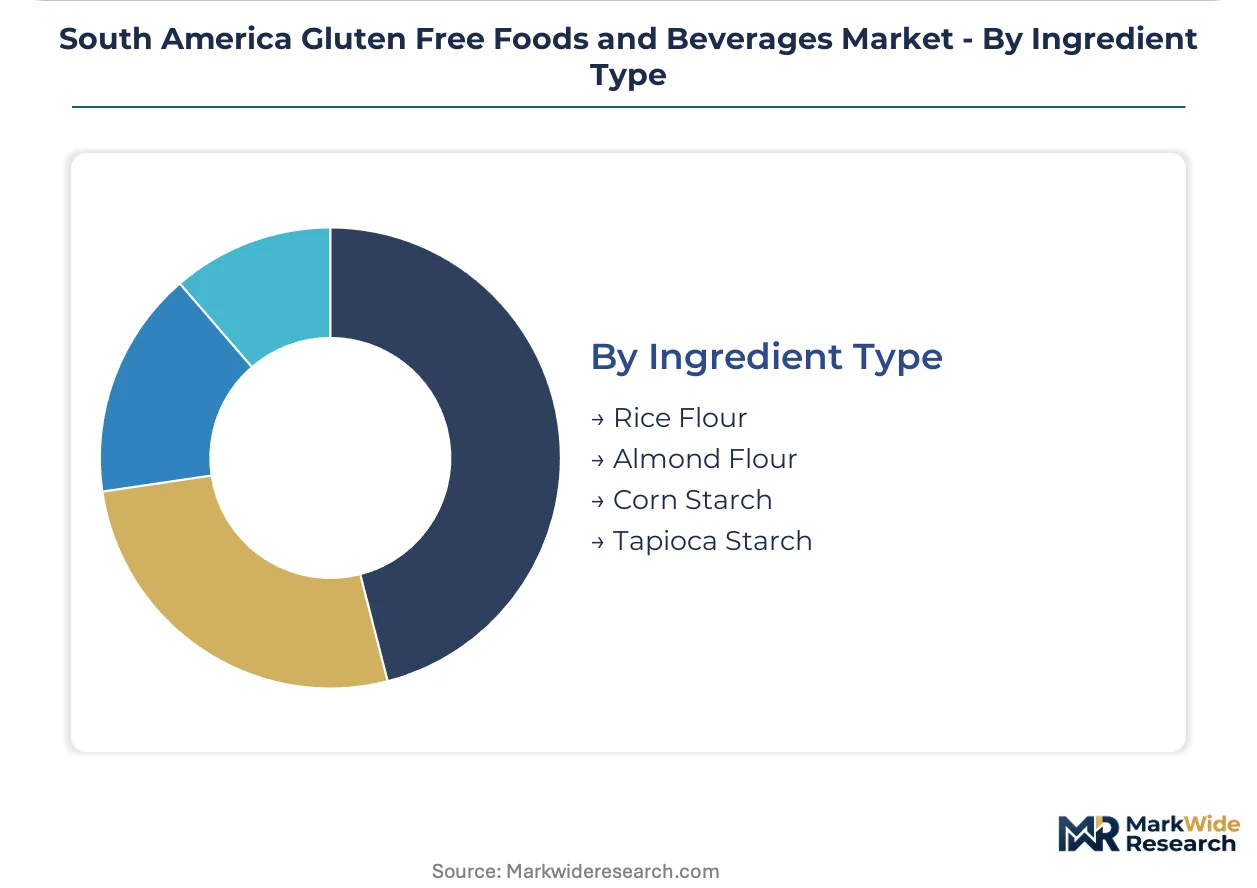
Ingredient Type:
Raw material sourcing geography shapes supply security, with Brazilian domestic crops offering cost advantages over imported alternatives.
- Rice Flour:Milled from Brazilian southern region harvests, this base ingredient dominates bakery applications for its neutral flavor and binding compatibility. Yield volatility in Rio Grande do Sul creates periodic price pressure.
- Tapioca Starch:Extracted from cassava root across Brazil's center-west agricultural belt, this component delivers the stretch and moisture retention critical for pasta textures. Processing capacity concentrates in Mato Grosso and Goiás.
- Almond Flour:Imported supply chains serve premium positioning in Argentine health food channels.
- Corn Starch:Argentine Pampas region production supports regional snack manufacturing with lower cost positioning.
Rice flour absorbs the bulk of installed capacity; tapioca starch is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors South American gluten-free demand through its dense metropolitan consumer base and concentrated retail infrastructure. Brazilian southeast corridor purchasing power sustains the region's highest per-capita certified product consumption.
Brazil
ANVISA's sub-20 ppm gluten-free certification enforcement legitimizes premium pricing and accelerates supermarket shelf-space allocation. São Paulo and Rio de Janeiro metropolitan corridors concentrate diagnosed celiac patients and health-conscious households driving volume. Third-party laboratory verification capacity clusters in São Paulo, creating regional certification bottlenecks for interior state producers.
Argentina
Córdoba and Mendoza provinces exhibit underpenetrated retail gluten-free shelf space relative to diagnosed celiac prevalence. National food code updates mandate clearer iconography and stricter cross-contamination warnings on imported goods. Buenos Aires anchors domestic supply chain relationships as Argentine supermarket procurement redirects toward local suppliers with established in-country laboratory networks.
Chile
Santiago's health food retail density supports pharmacy channel expansion for certified gluten-free products. The national food regulator enforces labeling thresholds aligned with Mercosur harmonization discussions. Valparaíso port logistics facilitate Brazilian and Argentine import flows while domestic milling capacity remains limited.
Colombia
Bogotá's emerging health-conscious consumer segment drives initial certified product penetration in premium supermarket channels. Regulatory frameworks for gluten-free claims remain less stringent than Brazilian ANVISA standards. Medellín pharmaceutical distributors test pharmacy channel placement for imported certified brands.
Peru
Lima's gastronomy-focused urban consumers generate niche demand for gluten-free restaurant and retail products. Quinoa and native grain production offers natural gluten-free whole food competition to formulated products. Coastal agricultural regions supply cassava starch inputs to regional snack manufacturers.
South America Gluten Free Foods and Beverages Market Competitive Landscape
The competitive structure tilts toward multinational packaged food conglomerates with dedicated gluten-free manufacturing infrastructure and regional distribution reach. Tiered positioning separates premium certified specialists from mass-market portfolio players leveraging existing retail relationships. Three archetypes dominate: dedicated gluten-free manufacturers with segregated production facilities, diversified food conglomerates with certified product lines, and regional grain millers with backward integration into gluten-free ingredient supply. Capacity expansion and certification pre-positioning for Mercosur harmonization constitute the dominant competitive moves.
Among dedicated gluten-free specialists, Dr. Schär and Bob's Red Mill occupy positions exemplifying premium certified positioning through manufacturing infrastructure investments. Nestlé S.A. and General Mills Inc. represent diversified conglomerate archetypes leveraging broad distribution networks across conventional retail and pharmacy channels. Molinos Río de la Plata anchors regional supply security through integrated grain milling capabilities serving Argentine and Brazilian manufacturing demand.
| Leading Market Players |
|---|
| Bob's Red Mill |
| Dr. Schär |
| General Mills Inc. |
| Molinos Río de la Plata |
| The Kraft Heinz Company |
| The Hain Celestial Group |
| Barilla G. e R. Fratelli S.p.A. |
| Nestlé S.A. |
| Brazi Bites |
| Others |
Value Network & Pricing Analysis
Diagnosed celiac patients in Brazilian pharmacy channels anchor premium pricing for certified gluten-free products, with ANVISA's sub-20 ppm verification legitimizing substantial markups over conventional alternatives. This buyer concentration reinforces value-based pricing tiers tied to medical certification rather than commodity cost structures.
Pricing Analysis
Medical certification outcomes command the dominant pricing anchor, with ANVISA-verified products extracting premiums through pharmacy channel credibility. Price differentiation separates certified pharmacy-tier SKUs from supermarket-certified and uncertified economy tiers. Cost compression in mid-tier supermarket segments is intensifying because tapioca starch and rice flour input volatility compresses producer margins. Self-diagnosed health-conscious buyers in Argentine interior provinces exhibit highest price sensitivity, while diagnosed patients accepting pharmacy premiums show least elasticity.
Supply Chain Analysis
Direct-to-supermarket channels handle Brazilian southeast corridor volume, with pharmacy and online retail serving specialized demand. Geographic supply concentrates in Brazil's center-west cassava belt, Rio Grande do Sul rice regions, and Argentine Pampas corn production. Raw material dependencies rest on tapioca starch, rice flour, and imported almond flour for premium positioning. Single-source vulnerability in São Paulo laboratory verification capacity creates certification bottlenecks for interior state manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extrusion technology for modular formulation switching is displacing dedicated gluten-free production lines, compressing capital barriers for new entrants while fragmenting incumbent manufacturing advantages.
For Market Incumbents: Lock in segregated production infrastructure through dedicated facility investments in São Paulo and Buenos Aires, eliminating cross-contamination risks that trigger ANVISA enforcement actions. Deepen backward integration into verified gluten-free oat cultivation to secure ingredient sourcing integrity against substitution threats from naturally gluten-free whole foods. For New Entrants and Emerging Players: Compact extrusion technology enabling single-shift formulation switching offers the most penetrable wedge against capital-intensive dedicated facilities. Target Argentine Córdoba and Mendoza provinces where retail shelf space lags diagnosed celiac prevalence. Pursue pharmacy channel placement first, leveraging medical certification credibility to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: The window for entry favors mid-size Brazilian contract manufacturers with modular extrusion capabilities and established ANVISA laboratory relationships. Long-term viability hinges on pre-positioning for Mercosur harmonization through multi-country certification infrastructure. Watch Mercosur regulatory negotiation momentum as the critical inflection signal for cross-border manufacturing location decisions.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Pre-Positioning | Secures pharmacy channel access ahead of competitors in Brazilian metropolitan corridors. |
| Backward Integration into Verified Oat Supply | Eliminates single-source vulnerability in gluten-free ingredient sourcing for bakery applications. |
| Modular Extrusion Capacity Expansion | Enables private-label proliferation without dedicated facility investments in Rio de Janeiro. |
| Argentine Interior Distribution Partnership | Captures underpenetrated shelf space in Córdoba and Mendoza provinces ahead of retail consolidation. |
| Probiotic Beverage Functional Positioning | Commands pharmacy channel premiums through gut-health additive combinations in São Paulo. |
Research Methodology
Document review covered ANVISA regulatory filings, Argentine national food code updates, and Mercosur harmonization documentation, complemented by interviews with gluten-free product manufacturers, supermarket category buyers, and third-party laboratory verification specialists. Secondary sources included customs trade records for tapioca starch and rice flour flows, retail audit data from Brazilian southeast corridor supermarkets, and pharmaceutical distributor channel reports. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, distribution channel, and ingredient type segmentation dimensions.
Cross-referencing historical certification adoption curves with panel input from regulatory affairs directors and supply chain managers informed the analytical framework across the projection horizon. Segmentation dimensions modeled included product format, customer medical status, channel format, and raw material sourcing geography. CAGRs derived from volume trajectory analysis incorporating ANVISA enforcement intensity assumptions and pharmacy channel penetration curves for certified products.
Several conditions sit outside the modeled scope, including potential Mercosur regulatory harmonization failure, catastrophic Brazilian agricultural yield disruption, and accelerated substitution toward naturally gluten-free whole foods. Forecasts reflect assumptions about certification threshold stability and laboratory capacity expansion. Periodic stress-testing of base assumptions against ANVISA enforcement patterns and input cost volatility is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Egg Allergy Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Celiac Disease Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Gluten Free Food Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Dyspepsia Market