
 Artificial Intelligence in IVD Market | 2026-2036
Artificial Intelligence in IVD Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in IVD Market Insights
Hospital procurement teams are redrawing vendor selection criteria around algorithmic accuracy and interoperability, displacing traditional instrument-centric purchasing. Siemens Healthineers anchors its position through deep learning integration across imaging and laboratory workflows. Roche differentiates by embedding AI into centralized diagnostics platforms that span molecular and blood testing segments. Abbott leverages its installed base of instruments to extend software subscription revenue across hospital networks.
Artificial Intelligence in IVD encompasses algorithmic systems that analyze in vitro diagnostic data to classify, quantify, or flag biological specimens without direct human pattern recognition. These systems typically process digital pathology slides, flow cytometry outputs, or mass spectrometry traces through trained neural networks to reduce turnaround time and inter-operator variability. Software Solutions command the dominant revenue share as laboratories prioritize cloud-deployed algorithms over capital-intensive hardware refreshes. Deep Learning within the Technology dimension attracts the fastest development investment, particularly for hematological malignancy screening where feature extraction complexity exceeds conventional machine learning capabilities. Molecular Testing under Application shows concentrated demand from oncology departments pursuing minimal residual disease monitoring through AI-enhanced sequencing interpretation.
The FDA's pre-certification program for software-based medical devices shapes product development roadmaps by allowing iterative algorithm updates without full resubmission. European manufacturers navigate the EU AI Act's risk classification system alongside MDR compliance for diagnostic device software. Health Canada and Japan's PMDA maintain distinct but converging frameworks for clinical decision support algorithms. Stakeholders must monitor how divergent validation requirements across these regulators affect deployment timelines and market access strategies.
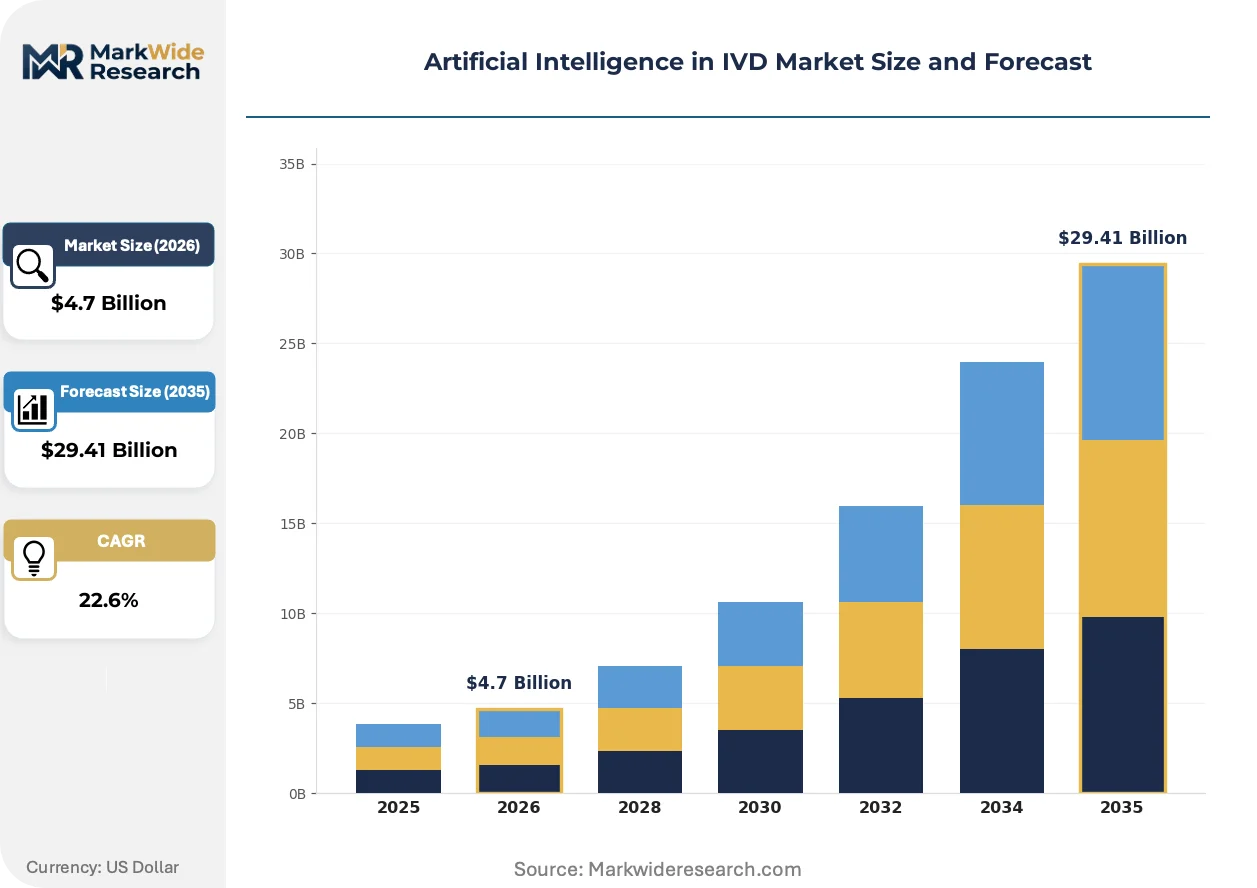
Market Dynamics
Cloud-deployed algorithm architectures are compressing capital expenditure requirements for clinical laboratories, redirecting procurement budgets toward recurring software licenses and API integration services rather than instrument hardware.
Growth Catalysts
- FDA Pre-Certification Program:Iterative algorithm updates proceed without full resubmission cycles, accelerating deployment timelines for hematology and pathology screening tools across US health systems.
- Deep Learning Architectures:Neural network feature extraction capabilities now exceed conventional machine learning for complex specimen classification, particularly in flow cytometry interpretation and mass spectrometry trace analysis.
- Oncology Department Demand:Minimal residual disease monitoring through AI-enhanced sequencing interpretation drives concentrated investment in molecular testing applications.
Market Restraints
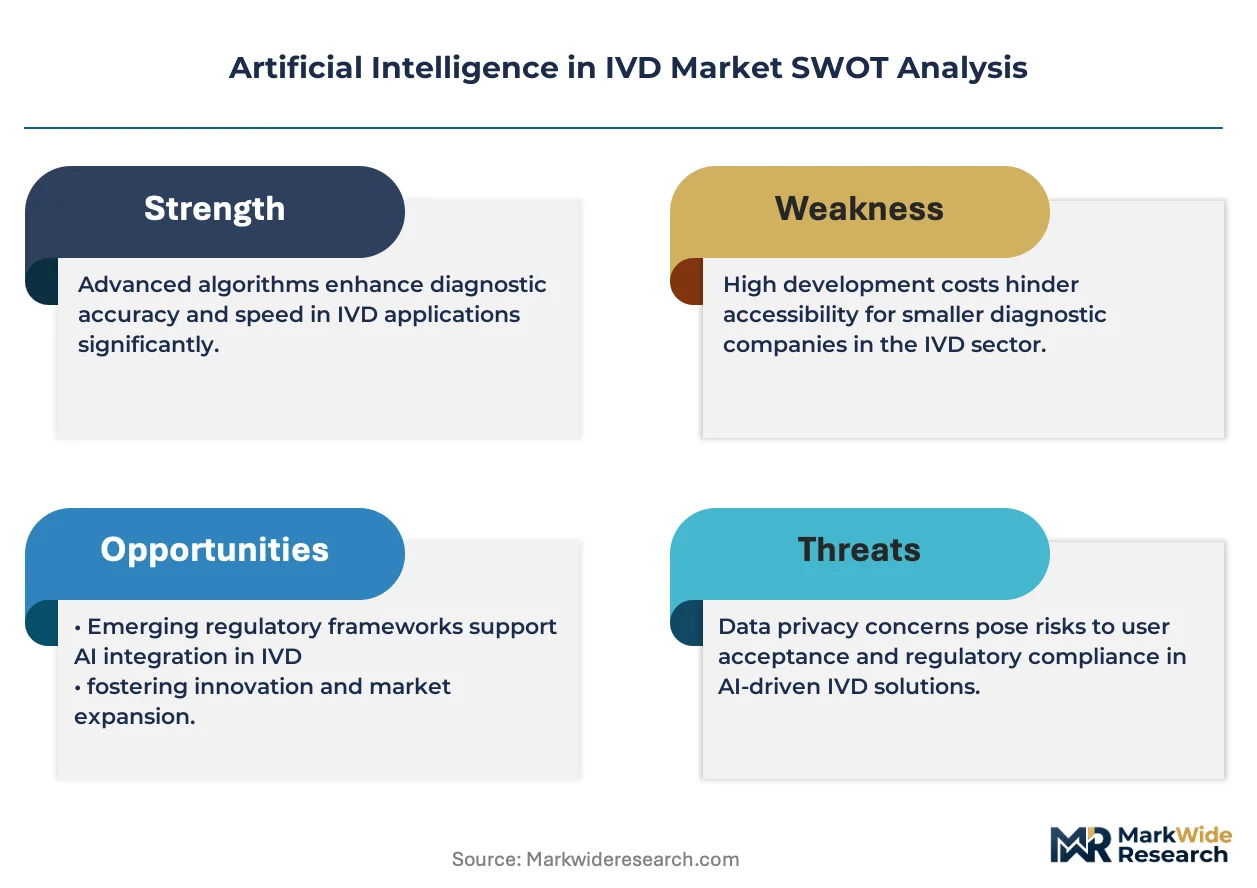
- Validation Cost Burden:Multi-site clinical studies required for algorithm performance verification impose substantial upfront expenditure before commercial deployment.
- EU AI Act Risk Classification:High-risk categorization for diagnostic decision-support software triggers enhanced conformity assessment procedures and extended regulatory timelines.
- Interoperability Fragmentation:Proprietary data formats across instrument manufacturers create integration friction that delays algorithm deployment in mixed-vendor laboratory environments.
Strategic Opportunities
- Point-of-Care Testing Expansion:Edge-computing inference capabilities enable algorithm deployment in decentralized settings previously constrained by cloud connectivity requirements.
- Japan PMDA Convergence:Alignment with international software-as-medical-device frameworks reduces duplicate validation burdens for manufacturers pursuing simultaneous US and Japanese market entry.
- Digital Pathology Slide Archives:Retrospective training datasets from accumulated whole-slide imaging repositories accelerate algorithm development without prospective collection costs.
Industry Challenges
- Computational Pathology Talent Scarcity:Cross-functional expertise spanning histopathology and machine learning engineering remains concentrated in academic medical centers and specialized vendors.
- Legacy LIS Integration Complexity:Hospital information systems built on decades-old architectures require custom middleware development for real-time algorithm output ingestion.
- Algorithm Drift Monitoring:Continuous performance validation across shifting patient populations and staining protocols demands dedicated quality infrastructure absent from traditional laboratory operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in IVD Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Test Kits, Platforms, Instruments End User: Clinics, Laboratories, Hospitals, Research Institutions Application: Diagnostic Imaging, Molecular Testing, Blood Testing, Pathology Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision |
| Companies Covered | Siemens Healthineers AG, F. Hoffmann-La Roche Ltd, Abbott Laboratories, Thermo Fisher Scientific Inc., Danaher Corporation, Sysmex Corporation, BioMérieux, Becton Dickinson and Company, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in IVD Market Trends and Innovations
Federated learning architectures and regulatory sandbox programs are redrawing how diagnostic algorithms develop, validate, and deploy across institutional boundaries.
Multimodal neural networks integrating digital pathology, genomic sequencing, and clinical metadata are fragmenting traditional diagnostic silos. Academic medical centers in Germany and the Netherlands adopt these architectures for integrated tumor board decision support. The technology is fragmenting vendor competitive positions previously built on single-modality dominance.
The EU AI Act's risk-based classification system imposes heightened transparency requirements on high-risk diagnostic algorithms. Manufacturers must maintain technical documentation and human oversight protocols that exceed previous CE marking obligations. European pathology laboratories are responding by consolidating vendor relationships around suppliers with established quality management systems.
Subscription-based algorithm licensing is displacing perpetual software purchases in hospital procurement. Health systems in the United States negotiate multi-year agreements that bundle model updates, regulatory maintenance, and cloud compute costs. This shift compresses switching costs and intensifies vendor accountability for ongoing algorithm performance.
Artificial Intelligence in IVD Market Segmentation
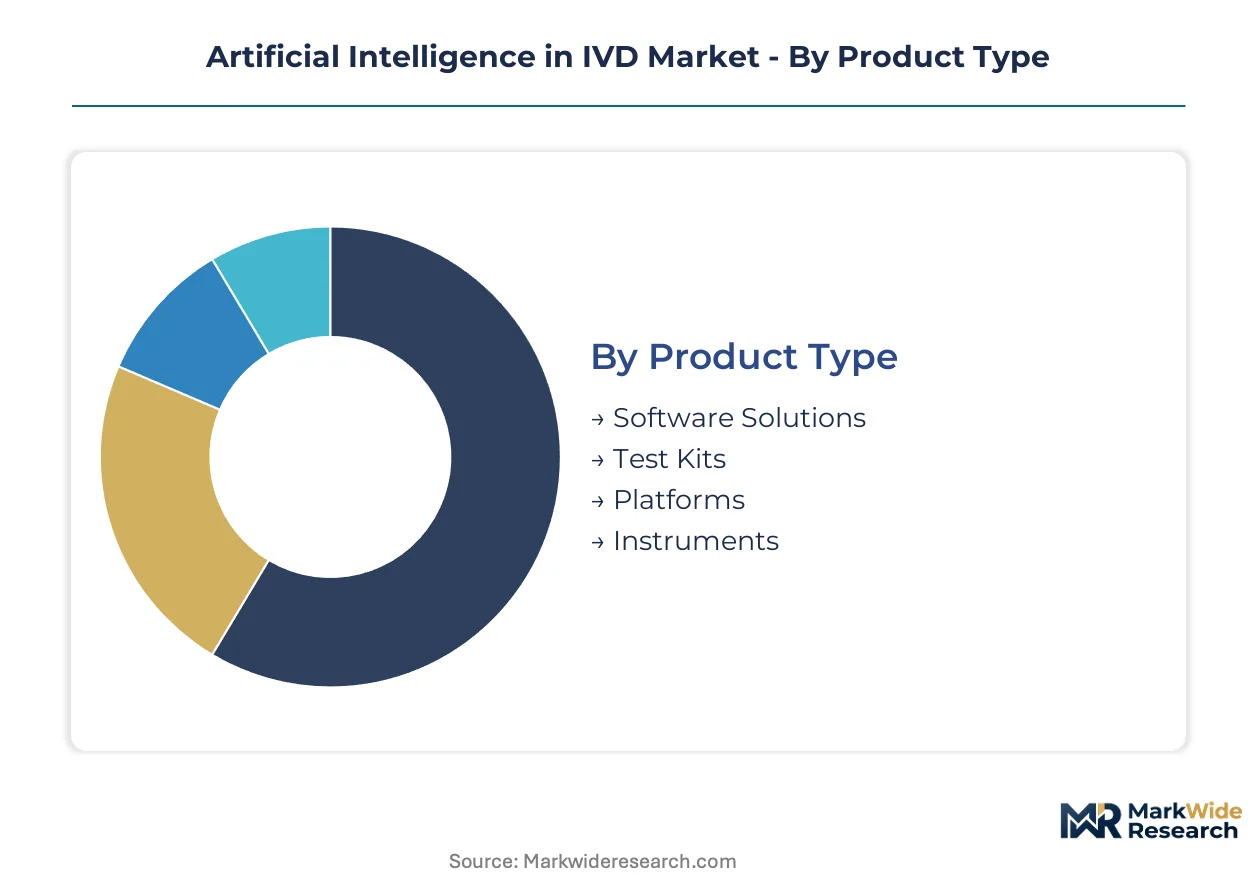
Laboratory procurement teams evaluate AI in IVD offerings through multiple lenses simultaneously. Product architecture determines capital versus operational expenditure profiles. End-user workflow requirements shape interoperability specifications and deployment models.
Product Type:
Cloud-deployed software licenses flow through subscription channels, while instruments and platforms concentrate in capital equipment procurement cycles.
- Software Solutions:Cloud-deployed algorithms analyze digital pathology slides, flow cytometry outputs, and mass spectrometry traces without hardware replacement. United States health systems prioritize these for workflow automation and reduced inter-operator variability in clinical laboratories.
- Test Kits:Consumable reagent systems integrate pre-trained inference models for point-of-care molecular diagnostics. Oncology departments in academic medical centers drive concentrated demand for minimal residual disease monitoring applications.
- Platforms:Integrated hardware-software systems centralize multi-modal diagnostic processing.
- Instruments:Capital-intensive analyzers embed edge-computing capabilities for decentralized settings.
By volume, Software Solutions leads. By growth pace, Test Kits is climbing the fastest.
End User:
Procurement authority and reimbursement pathways diverge sharply across customer types, with hospitals commanding enterprise licensing leverage and clinics seeking modular deployment.
- Laboratories:Clinical and reference laboratories deploy AI for automated pathology screening and high-throughput specimen classification. The FDA's pre-certification program accelerates algorithm updates for these settings without full resubmission cycles.
- Hospitals:Integrated delivery networks pursue workflow automation across imaging and laboratory silos. Siemens Healthineers and Roche embed AI into centralized diagnostics platforms serving these institutional buyers.
- Clinics:Smaller volumes favor API-integrated software subscriptions over capital purchases.
- Research Institutions:Retrospective training datasets from digital pathology archives accelerate algorithm development without prospective collection costs.
Laboratories capture the highest transaction frequency. Hospitals generate the largest contract values per deployment.
Application:
Reimbursement coding and regulatory validation requirements fragment commercial pathways across diagnostic domains.
- Molecular Testing:AI-enhanced sequencing interpretation supports minimal residual disease monitoring and therapeutic selection in oncology. Deep learning architectures exceed conventional machine learning for complex genomic feature extraction.
- Pathology:Whole-slide imaging algorithms reduce turnaround time and standardize classification across hematological malignancy screening. Academic medical centers in Germany and the Netherlands adopt multimodal neural networks for integrated tumor board decision support.
- Diagnostic Imaging:Radiological and laboratory imaging convergence creates multimodal diagnostic opportunities.
- Blood Testing:Automated hematology analyzers incorporate neural networks for cell population identification.
Molecular Testing commands premium pricing. Pathology shows the steepest expansion trajectory as digital slide archives mature.
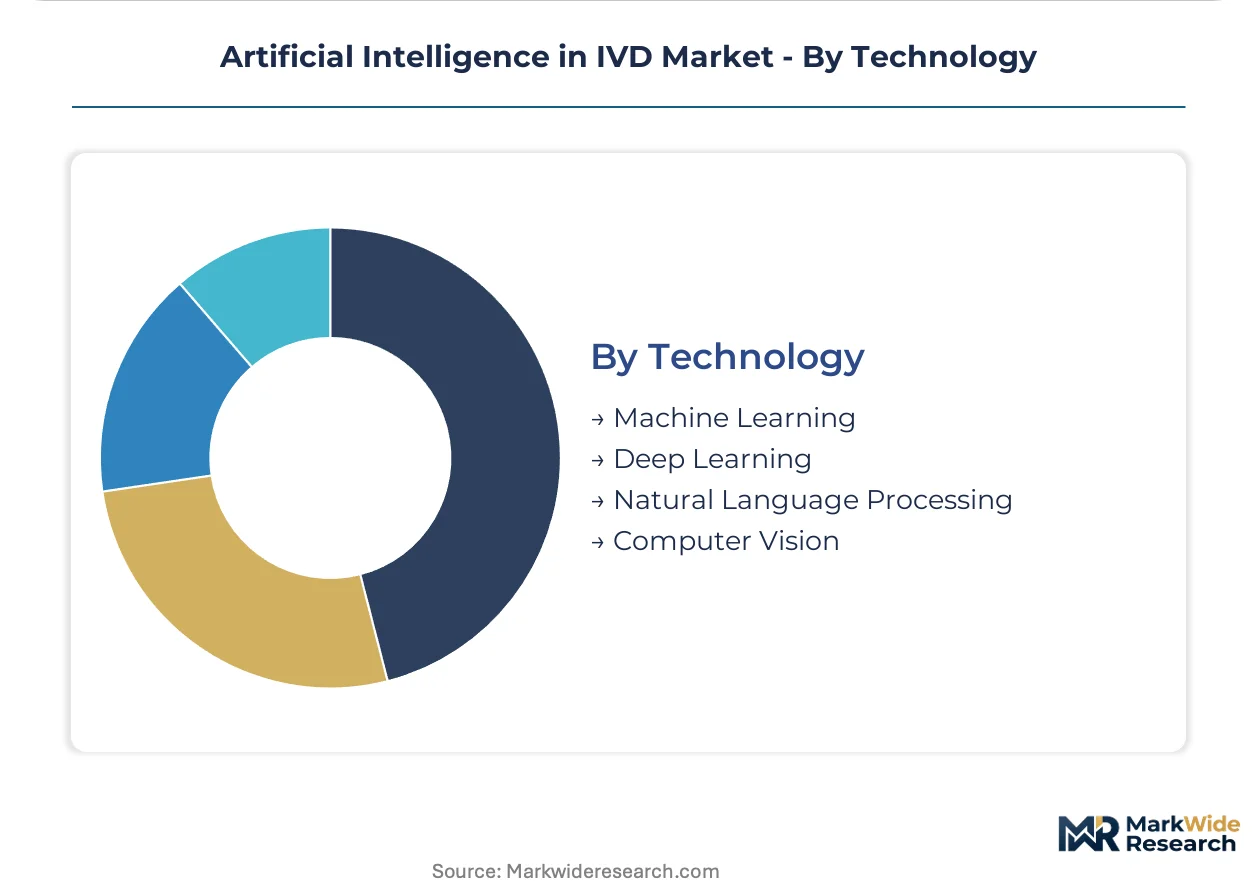
Technology:
Development investment concentrates where feature extraction complexity exceeds conventional algorithmic capabilities.
- Deep Learning:Neural network architectures process digital pathology, genomic sequencing, and clinical metadata through integrated pipelines. The EU AI Act's high-risk classification triggers enhanced conformity assessment for these diagnostic decision-support systems.
- Computer Vision:Image recognition algorithms classify cellular morphology and tissue architecture with reduced inter-operator variability. Federated learning architectures enable multi-site validation without centralized data pooling.
- Machine Learning:Conventional statistical methods persist in lower-complexity classification tasks.
- Natural Language Processing:Clinical report extraction and structured data generation support diagnostic workflow integration.
Deep Learning attracts the largest R&D allocation. Computer Vision delivers the most immediate deployment traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algorithm development clusters concentrate where regulatory frameworks for software-as-medical-device have matured and academic medical centers maintain substantial digital pathology archives. Venture funding for diagnostic AI flows disproportionately toward jurisdictions offering pre-certification pathways and reimbursement clarity.
United States
Hospital procurement teams at integrated delivery networks drive enterprise licensing for workflow automation tools. The FDA's pre-certification program permits iterative algorithm updates without full resubmission cycles, compressing deployment timelines for hematology screening applications. Academic medical centers in Boston and Stanford anchor multi-site validation studies for deep learning architectures in flow cytometry interpretation.
Germany
Pathology laboratories adopt multimodal neural networks integrating whole-slide imaging with genomic sequencing for tumor board decision support. The EU AI Act's high-risk classification for diagnostic decision-support software triggers enhanced conformity assessment procedures through notified bodies. Industrial clusters in Munich and Heidelberg concentrate federated learning research for multi-site algorithm validation without centralized data pooling.
Japan
PMDA convergence with international software-as-medical-device frameworks reduces duplicate validation burdens for manufacturers pursuing simultaneous US market entry. Health systems in Tokyo and Osaka prioritize cloud-deployed algorithms for blood testing automation. The country's national pharmaceutical regulator maintains distinct but aligning frameworks for clinical decision support algorithms.
Netherlands
Academic medical centers in Amsterdam and Rotterdam lead European adoption of integrated diagnostic platforms spanning molecular testing and digital pathology. National reimbursement pathways for AI-enhanced diagnostics create procurement incentives absent in neighboring jurisdictions. The country's healthcare system consolidates vendor relationships around suppliers with established quality management systems compliant with MDR requirements.
United Kingdom
NHS pathology networks pursue centralized procurement of algorithmic screening tools for hematological malignancy detection. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating distinct validation requirements for software-based devices. London-based research institutions maintain retrospective training datasets from accumulated whole-slide imaging repositories.
Artificial Intelligence in IVD Market Competitive Landscape
Concentration sits with diversified diagnostics conglomerates that embed AI across centralized laboratory platforms and imaging workflows. Three to five integrated players command procurement relationships with major health systems through bundled hardware-software offerings. Mid-scale specialists occupy niche positions in point-of-care molecular diagnostics and flow cytometry applications. Competitive moves center on strategic partnerships for cloud infrastructure and portfolio diversification into subscription-based algorithm licensing.
Within the integrated diagnostics tier, Siemens Healthineers AG, F. Hoffmann-La Roche Ltd, and Abbott Laboratories exemplify archetypes of platform-centric competition. Siemens Healthineers AG represents European-headquartered conglomerates with deep learning integration spanning imaging and laboratory silos. F. Hoffmann-La Roche Ltd occupies a position among Swiss pharmaceutical-diagnostics hybrids embedding AI into centralized platforms. Abbott Laboratories exemplifies US-based instrument manufacturers leveraging installed bases to extend software subscription revenue across hospital networks.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Sysmex Corporation |
| BioMérieux |
| Becton Dickinson and Company |
| Bio-Rad Laboratories, Inc. |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure substitution for on-premise hardware simultaneously redraws supply geography toward hyperscaler regions and compresses pricing economics through recurring software license models rather than capital-intensive instrument purchases.
Pricing Analysis
The FDA's pre-certification program dictates the pricing tier structure across algorithm-based diagnostics, separating premium validated platforms from standard cloud-deployed tools and economy API-access modules. Price differentiation hinges on FDA validation tier and interoperability certification level, with oncology decision-support commanding substantial premiums over routine hematology screening. Pricing pressure stems from EU AI Act compliance costs elevating European deployment expenses. Academic medical centers exhibit highest price sensitivity due to constrained capital budgets, while integrated delivery networks absorb premium tiers for enterprise workflow consolidation.
Supply Chain Analysis
The United States and Germany anchor algorithm development clusters, with Taiwan and South Korea supplying specialized GPU hardware for neural network training. Raw material dependencies center on cloud compute capacity, annotated pathology datasets, and regulatory consulting expertise. Supply chain risk concentrates in single-source vulnerability for FDA-qualified validation data providers. Distribution runs through direct enterprise sales to hospital procurement committees and GPO-negotiated software licensing frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial Intelligence in IVD sits in early-cycle expansion as FDA regulatory clarity accelerates health system procurement velocity beyond traditional diagnostic instrument replacement cycles.
For Market Incumbents: Secure algorithm update pathways through FDA pre-certification enrollment before emerging cloud-native vendors achieve comparable validation status. Deepen backward integration into digital pathology dataset curation to control training data quality and reduce dependency on academic medical center partnerships. Consolidate procurement relationships through bundled hardware-software subscription offerings that elevate switching costs for hospital laboratory directors. For New Entrants and Emerging Players: Point-of-care molecular diagnostics at decentralized clinics represents the most penetrable white-space target, as incumbents under-serve smaller volume settings with capital-intensive platform offerings. Federated learning architectures enable multi-site validation without centralized data pooling, reducing upfront compliance burdens. Pursue API-first go-to-market strategies that embed into existing laboratory information systems rather than displacing entrenched instrument footprints. For Investors and Strategic Acquirers: Capital is best deployed toward specialized computer vision vendors with established flow cytometry or mass spectrometry algorithm portfolios. Long-term viability across the projection horizon rests on regulatory moat depth rather than technical performance alone. Watch for inflection signals in CMS reimbursement coding decisions for AI-enhanced pathology screening as the decisive demand catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Enrollment | Accelerates algorithm iteration cycles without full resubmission, compressing deployment timelines for hematology applications. |
| Cloud Infrastructure Partnership | Redirects capital expenditure toward operational software licensing, reshaping procurement economics for hospital laboratories. |
| Digital Pathology Archive Licensing | Unlocks retrospective training datasets that reduce prospective collection costs and accelerate model development velocity. |
| EU AI Act Compliance Investment | Establishes quality management systems that satisfy notified body requirements for high-risk diagnostic decision-support software. |
| Hospital System GPO Alignment | Captures enterprise procurement channels through negotiated multi-year algorithm subscription agreements with integrated delivery networks. |
Research Methodology
Initial hypotheses were tested against primary input from hospital laboratory directors, FDA regulatory consultants, pathology informatics officers, and GPO contract managers and refined through secondary validation against FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up modeling of algorithm deployment volumes across end-user segments was cross-checked against top-down market sizing from cloud infrastructure expenditure disclosures and software licensing revenue patterns.
Variance decomposition across the projection horizon isolates volume, pricing, and mix effects within each segmentation dimension: product architecture, end-user procurement authority, diagnostic application domain, and underlying technology approach. CAGRs were derived from algorithm adoption curve analysis calibrated to historical digital pathology penetration patterns and regulatory approval velocity benchmarks. Model inputs incorporate health system IT budget allocations, laboratory staffing constraint indices, and reimbursement pathway maturation timelines.
Forecasts assume regulatory continuity in FDA pre-certification and EU AI Act implementation regimes; material policy shifts would require re-modeling deployment timelines and market access assumptions. Specific revision triggers include algorithm drift monitoring mandate changes, interoperability standard enforcement, and cloud compute cost volatility. Recalibration cycles align with material shifts in CMS reimbursement coding and notified body interpretation guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
India Molecular Diagnostic Controls Market
Diagnostics
Connected Diagnostics Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Sexually Transmitted Diseases Diagnostics Market
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
Breast Cancer Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Saudi Arabia in-Vitro Diagnostics (IVD) Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
DNA Probes - Based Diagnostics Market