
 Europe Breast Cancer Screening Tests Market | 2026-2036
Europe Breast Cancer Screening Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Breast Cancer Screening Tests Market Foresight
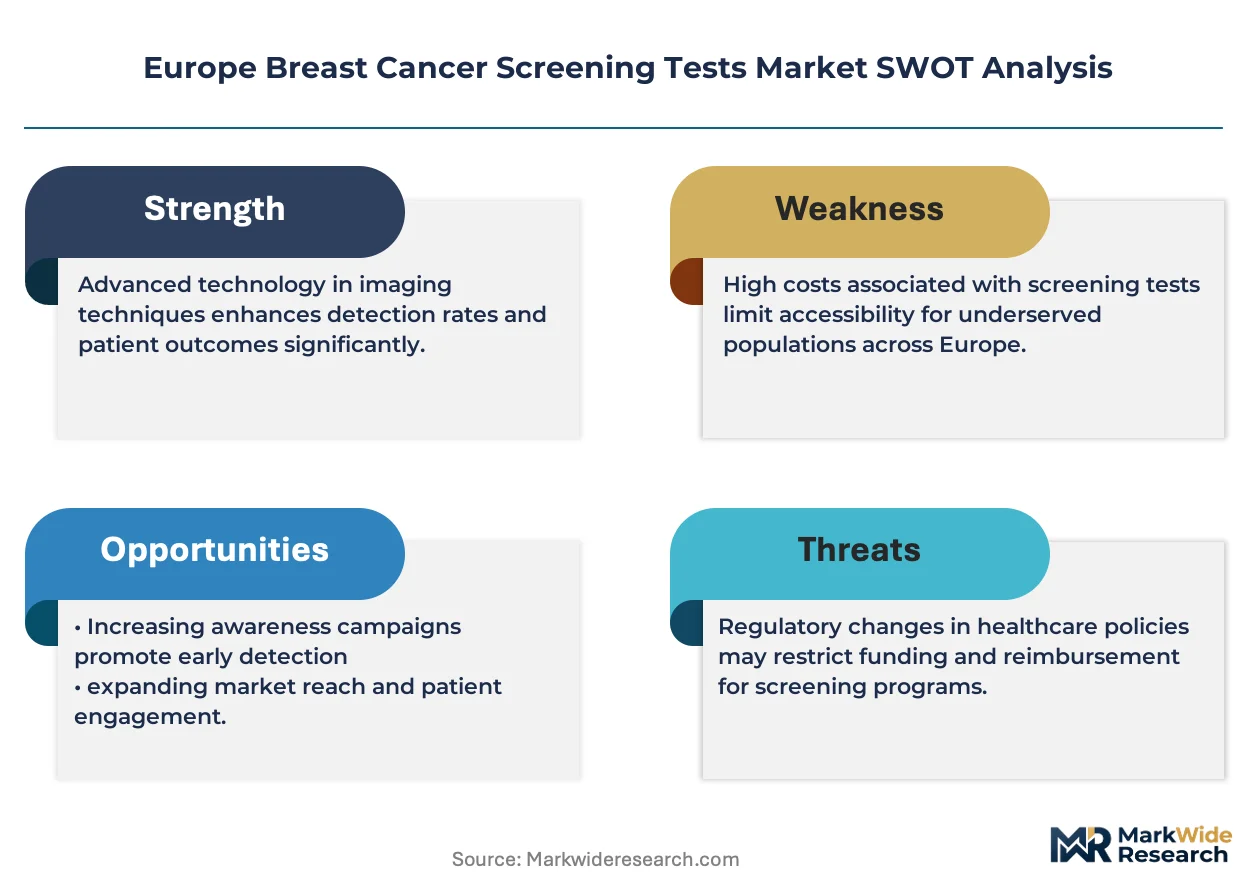
The EU Medical Device Regulation is consolidating cost-of-entry calculus for breast cancer screening equipment across European member states. Hologic Inc. leverages its installed base of digital mammography systems to sustain service revenue streams. Siemens Healthineers anchors its position through integrated diagnostic workflows spanning imaging and laboratory analytics. GE Healthcare competes on AI-enhanced detection algorithms embedded within its screening platforms.
Europe breast cancer screening tests encompass imaging modalities and tissue sampling procedures designed for early-stage malignancy detection in asymptomatic populations, typically employing ionizing radiation doses below 3 mGy per mammographic view or magnetic resonance protocols with gadolinium-based contrast agents to visualize vascularized lesions. These technologies serve the primary purpose of reducing stage-at-diagnosis and enabling less invasive treatment interventions. Mammography retains the largest patient throughput volume across national screening programs, while 3D tomosynthesis captures margin pools in premium-tier diagnostic centers seeking differentiation through reduced callback rates. Automated systems represent the fastest-growing technology segment as workforce shortages drive demand for streamlined image acquisition and computer-aided triage.
EMA guidelines on pharmacovigilance and the EU AI Act's risk-classification framework for diagnostic algorithms shape product development timelines and clinical evidence requirements for screening device manufacturers. CE marking under MDR mandates notified body involvement for Class IIa and above devices, extending regulatory lead times compared with the previous Medical Device Directive era. Stakeholders must monitor evolving reimbursement parity between digital breast tomosynthesis and conventional two-dimensional mammography within national health technology assessment processes.
Market Dynamics
The EU Medical Device Regulation is compressing market entry timelines while elevating clinical evidence requirements for breast cancer screening equipment, forcing manufacturers to restructure regulatory affairs functions and accelerate notified body engagement strategies.
Growth Catalysts
- Population-based screening mandates:Germany's national breast cancer screening program extends coverage to women aged 50-69, expanding addressable patient volumes for imaging equipment procurement.
- MDR conformity assessment elevation:Stricter CE marking requirements for Class IIa devices are filtering marginal suppliers and consolidating purchasing decisions toward established notified body relationships.
- 3D tomosynthesis substitution:Digital breast tomosynthesis is displacing conventional two-dimensional mammography in premium diagnostic centers seeking reduced callback rates and improved lesion characterization.
Market Restraints
- Radiologist workforce scarcity:Shortages of trained breast imaging specialists in France and Italy constrain throughput expansion regardless of equipment availability.
- Reimbursement parity gaps:Health technology assessment bodies in Spain and Portugal maintain differential reimbursement rates between digital breast tomosynthesis and conventional mammography, limiting upgrade incentives.
- Gadolinium contrast agent scrutiny:EMA pharmacovigilance guidelines on gadolinium retention are complicating MRI-based screening protocols and extending consent procedures.
Strategic Opportunities
- AI-embedded detection algorithms:The EU AI Act's risk-classification framework for diagnostic software creates first-mover advantages for manufacturers with pre-validated machine learning modules.
- Eastern European expansion:Poland and Romania present underpenetrated screening infrastructure relative to Western European coverage rates, with EU cohesion funds financing equipment procurement.
- Automated image acquisition systems:Workforce shortages are accelerating demand for streamlined positioning systems and computer-aided triage workflows in high-volume screening centers.
Industry Challenges
- Notified body capacity bottlenecks:MDR transition has concentrated conformity assessment demand on a reduced pool of designated bodies, extending certification timelines for new device submissions.
- Legacy PACS integration complexity:Screening equipment vendors face fragmented hospital information system environments requiring customized interoperability solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Breast Cancer Screening Tests Market |
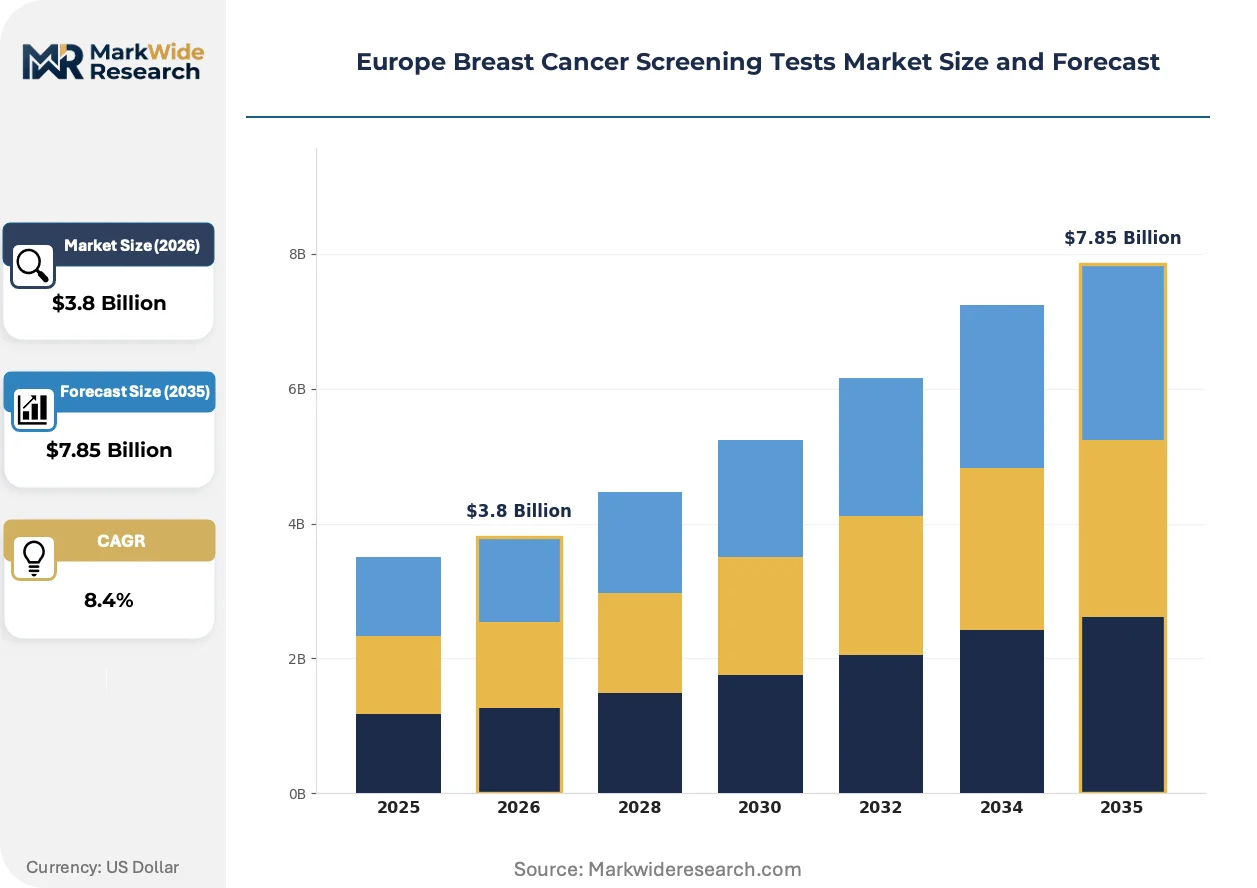
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Mammography, Ultrasound, MRI, Breast Biopsy End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Research Institutions Technology: Digital Imaging, 3D Tomosynthesis, Contrast-Enhanced, Automated Systems Age Group: 25-34 Years, 35-44 Years, 45-54 Years, 55+ Years |
| Companies Covered | Hologic Inc., Siemens Healthineers, GE Healthcare, Philips Healthcare, Myriad Genetics, Inc., Exact Sciences Corporation, Koninklijke Philips N.V., Canon Medical Systems, Fujifilm Holdings Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Breast Cancer Screening Tests Market Shifts & Advancements
Artificial intelligence integration is redrawing competitive boundaries in breast cancer screening, compressing detection workflow timelines while elevating algorithmic performance as a primary procurement criterion alongside hardware specifications.
Contrast-enhanced mammography is decentralizing vascularized lesion detection capabilities previously confined to MRI suites, enabling community-based screening centers in the Netherlands and Belgium to offer advanced diagnostic pathways without capital-intensive magnetic resonance infrastructure. Regional hospital networks are adopting this modality at accelerated procurement cycles. The technology is decentralizing patient flow away from tertiary referral centers and redistributing diagnostic capacity toward decentralized care settings.
The EU AI Act's risk-based classification system for diagnostic algorithms is mandating clinical validation frameworks that extend software development timelines but elevate barrier-to-entry for non-compliant suppliers. Device manufacturers must now submit conformity assessments for AI modules as distinct components within screening platforms. Mammography systems with embedded detection software face heightened scrutiny in Germany and France, where notified bodies are prioritizing algorithmic transparency documentation.
Subscription-based service models are displacing traditional capital equipment purchasing in Spanish and Italian public hospital networks, unbundling hardware acquisition from maintenance and software update commitments. Procurement departments are negotiating multi-year operational expenditure contracts that transfer obsolescence risk to vendors. This shift is most visible in regional screening programs where budget predictability outweighs ownership preferences.
Europe Breast Cancer Screening Tests Market Segmentation
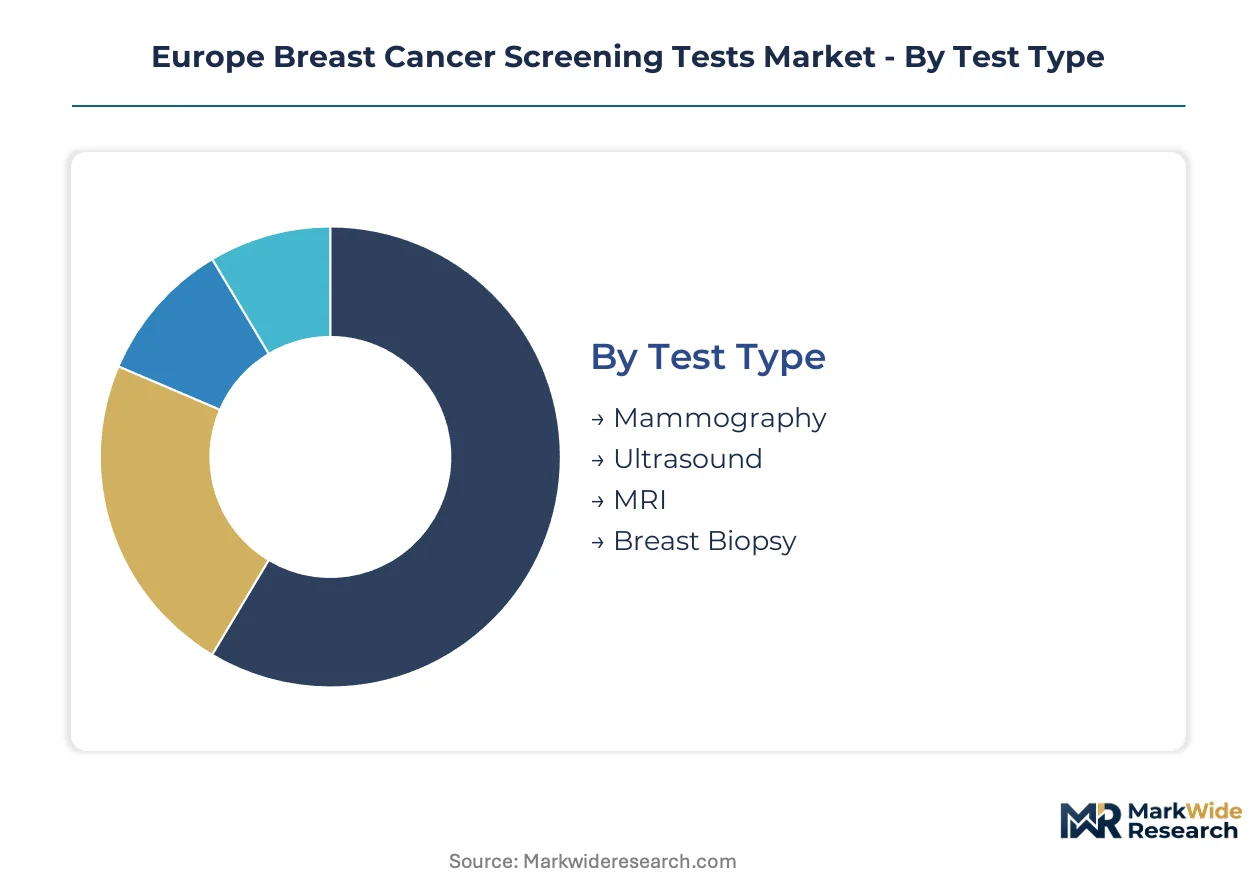
Segmentation in breast cancer screening tests reveals how regulatory pathways, reimbursement tiers, and clinical workflows fragment procurement decisions across European healthcare systems. Understanding these divides illuminates where MDR compliance burdens concentrate and which technology categories attract capital investment versus operational expenditure models.
Test Type:
CE marking under MDR imposes distinct clinical evidence requirements across modalities, with ionizing radiation devices facing additional dosimetry documentation and MRI systems confronting gadolinium retention protocols under EMA pharmacovigilance guidelines.
- Mammography:Digital and analog X-ray systems using compressed breast tissue imaging at sub-3 mGy doses per view. Demand concentrates in Germany's public screening program networks, where population-based mandates sustain high-throughput procurement cycles despite radiologist workforce constraints.
- Ultrasound:Non-ionizing acoustic imaging for dense breast tissue and supplemental screening. French diagnostic centers deploy this modality for callback resolution workflows, driven by differential reimbursement rates that favor rapid lesion characterization without radiation exposure.
- MRI:Magnetic resonance protocols with gadolinium-based contrast agents for high-risk surveillance. Belgium and Dutch hospital networks maintain specialized screening units for BRCA-positive cohorts.
- Breast Biopsy:Tissue sampling procedures including core needle and vacuum-assisted extraction. Spanish outpatient clinics integrate stereotactic guidance systems for same-day diagnostic pathways.
Mammography sits at the top of the volume ranking, with automated systems climbing the fastest as workforce shortages accelerate procurement of streamlined acquisition platforms.
End User:
Procurement authority and budget structures diverge sharply across facility types, with public hospital networks favoring capital equipment purchases while diagnostic centers migrate toward subscription-based operational expenditure models.
- Hospitals:Acute care institutions with integrated oncology departments and PACS infrastructure. German university hospitals anchor regional screening networks, consolidating image interpretation across multi-site patient flows.
- Diagnostic Centers:Specialized imaging facilities with dedicated breast health workflows. Italian private chains are negotiating multi-year service contracts that bundle hardware, maintenance, and AI software updates under predictable annual fees.
- Outpatient Clinics:Community-based facilities offering same-day screening and biopsy services. Polish primary care networks receive EU cohesion fund support for equipment modernization.
- Research Institutions:Academic medical centers conducting screening trial protocols and AI algorithm validation studies. French INSERM-affiliated sites generate clinical evidence for MDR conformity assessments.
Hospitals dominate installed base volumes, though diagnostic centers are gaining share fastest through operational expenditure contract structures that transfer obsolescence risk to vendors.
Technology:
Software-enabled detection capabilities now determine competitive positioning as much as hardware specifications, with AI modules requiring separate conformity assessments under the EU AI Act's risk-classification framework.
- Digital Imaging:Two-dimensional full-field digital mammography with computer-aided detection overlays. Portuguese public health programs maintain extensive FFDM fleets despite tomosynthesis reimbursement gaps.
- 3D Tomosynthesis:Tomographic reconstruction from multiple angular projections reducing tissue overlap artifacts. Premium-tier Belgian diagnostic centers deploy this technology for callback rate reduction and improved invasive cancer detection sensitivity.
- Contrast-Enhanced:Iodinated contrast protocols for vascularized lesion characterization without MRI infrastructure. Dutch community screening centers adopt this modality to decentralize advanced diagnostic capacity from tertiary referral hubs.
- Automated Systems:Robotic positioning and computer-aided triage workflows addressing radiologist scarcity. Italian high-volume screening programs prioritize procurement of streamlined acquisition platforms with embedded quality assurance.
Digital imaging retains the largest installed footprint, while contrast-enhanced mammography expands most quickly by redistributing diagnostic capacity toward decentralized care settings.
Age Group:
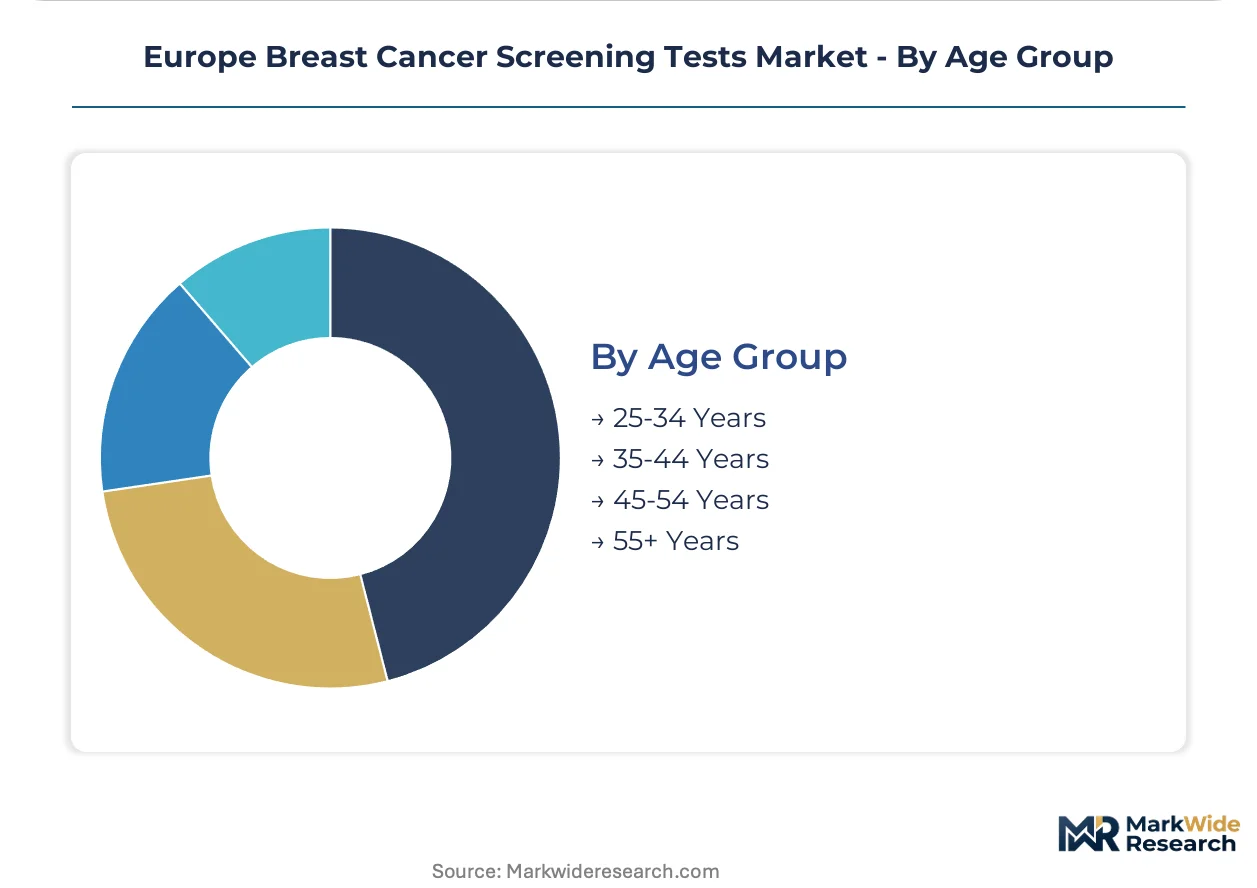
Screening program eligibility criteria and risk-stratified protocols create distinct demand profiles across demographic cohorts, with national guidelines varying on starting ages and intervals for asymptomatic surveillance.
- 25-34 Years:High-risk genetic screening and diagnostic workups for symptomatic presentation. French cancer centers manage BRCA mutation carriers through specialized surveillance protocols outside population-based programs.
- 35-44 Years:Dense breast tissue cohorts requiring supplemental imaging modalities. German statutory health insurance funds cover ultrasound adjuncts for selected risk profiles in this bracket.
- 45-54 Years:Perimenopausal transition period with increasing screening program enrollment. Spanish regional health services report rising callback rates in this group due to hormonally influenced tissue density variations.
- 55+ Years:Dominant population-based screening volume with established two-year interval programs. Polish national program extends coverage through age 69, sustaining equipment utilization rates in regional screening units.
The 55+ years segment commands the highest patient throughput volumes, with 35-44 years showing the steepest expansion trajectory as risk-stratified protocols expand supplemental imaging indications for dense breast tissue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiologist workforce density varies sharply across European member states, concentrating diagnostic capacity in German university hospital networks while Southern European markets struggle with specialist scarcity that constrains screening program expansion regardless of equipment availability.
Germany
Statutory health insurance funds sustain population-based screening mandates covering women aged 50-69, driving consistent procurement cycles for high-throughput mammography systems. The Federal Joint Committee (G-BA) governs reimbursement parity decisions between digital breast tomosynthesis and conventional two-dimensional mammography. Bavarian university hospitals anchor regional screening networks, consolidating image interpretation across multi-site patient flows in Munich and Nuremberg metropolitan clusters.
France
INSERM-affiliated academic medical centers generate clinical evidence packages required for MDR conformity assessments, positioning the country as a validation hub for AI-embedded detection algorithms. The National Agency for Food, Environmental and Occupational Health Safety (ANSES) oversees radiation protection standards for screening equipment deployment. The Île-de-France region concentrates diagnostic capacity, with Parisian hospital networks managing BRCA-positive cohort surveillance through specialized high-risk protocols outside standard population programs.
Italy
Private diagnostic chains negotiate multi-year operational expenditure contracts that bundle hardware, maintenance, and software updates under predictable annual fees, transferring obsolescence risk to vendors. The Italian Medicines Agency (AIFA) coordinates with notified bodies on CE marking timelines for Class IIa screening devices. Lombardy regional health authorities in Milan-Bergamo corridor prioritize automated image acquisition systems to address radiologist workforce gaps in high-volume screening centers.
Netherlands
Community-based screening centers adopt contrast-enhanced mammography to decentralize vascularized lesion detection capabilities previously confined to tertiary MRI suites, redistributing diagnostic capacity toward decentralized care settings. The Health and Youth Care Inspectorate (IGJ) enforces MDR compliance for screening equipment procurement in national program networks. The Randstad conurbation leads infrastructure modernization, with Rotterdam and Utrecht hospital networks pioneering same-day diagnostic pathways integrating stereotactic biopsy guidance.
Poland
EU cohesion funds finance equipment procurement for regional screening units, addressing underpenetrated infrastructure relative to Western European coverage rates. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products (URPL) serves as the designated notified body for domestic manufacturers seeking CE marking. Masovian Voivodeship screening programs in Warsaw metropolitan area extend national program coverage through age 69, sustaining equipment utilization rates that attract vendor service contract competition.
Europe Breast Cancer Screening Tests Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established notified body relationships and integrated diagnostic workflows spanning imaging and laboratory analytics. Equipment manufacturers with pre-validated AI modules capture first-mover advantages under the EU AI Act's risk-classification framework, while specialized diagnostic service providers consolidate through operational expenditure contract structures. Dominant competitive moves include strategic partnerships with academic medical centers for clinical evidence generation and geographic expansion into Eastern European markets via EU cohesion fund procurement channels.
Among US-based diversified health technology corporations, Hologic Inc. and GE Healthcare occupy positions exemplifying the installed base leverage archetype, where service revenue streams from legacy digital mammography systems sustain competitive positioning. Siemens Healthineers AG, a German multinational, represents the integrated workflow archetype through diagnostic platforms spanning imaging equipment and laboratory analytics. These three corporations anchor the premium-tier equipment segment where MDR compliance capabilities and notified body engagement timelines determine procurement eligibility in German and French public hospital networks.
| Leading Market Players |
|---|
| Hologic Inc. |
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Myriad Genetics, Inc. |
| Exact Sciences Corporation |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| Fujifilm Holdings Corporation |
| Others |
Supply & Pricing Matrix
Gadolinium price volatility cascades through MRI contrast agent supply chains into tiered service contracting structures, compressing margins for high-risk screening protocols while automated mammography platforms capture pricing power through workforce substitution economics.
Pricing Analysis
Subscription-based service contracts now split from traditional capital equipment purchases across Italian and Spanish hospital networks, creating a two-tier pricing structure across bundled operational expenditure and unbundled hardware acquisition models. Price differentiation hinges on CE marking tier under MDR Class IIa requirements and AI Act algorithmic risk classification, with premium tiers commanding 40-60% spreads over standard diagnostic packages. Cost compression in conventional two-dimensional mammography intensifies as 3D tomosynthesis achieves reimbursement parity in German and French statutory health insurance frameworks. Public hospital procurement committees exhibit highest price sensitivity, while private diagnostic chains prioritize total cost of ownership predictability over per-unit acquisition costs.
Supply Chain Analysis
Direct-to-hospital channels handle premium-tier imaging equipment deployment for German university hospital networks, while distributor-mediated pathways serve Polish and Romanian regional screening units financed through EU cohesion funds. Manufacturing concentration centers on Germany, the Netherlands, and the United States for digital mammography systems, with Japan and South Korea anchoring detector component supply. Gadolinium-based contrast agents, high-purity silicon detectors, and precision motion control systems constitute critical input dependencies. Single-source vulnerability in AI training dataset licensing creates procurement risk for algorithm-embedded platforms. Distribution runs through specialized medical device distributors with notified body liaison capabilities, particularly for MDR transition compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in automated image acquisition platforms where radiologist workforce scarcity enables premium pricing, while contrast-enhanced mammography decentralization opens service revenue streams previously captured by MRI suite operators.
For Market Incumbents: Deepen notified body engagement capabilities to compress MDR certification timelines, defending installed base positions against emerging AI-native entrants with pre-validated algorithmic modules. Prioritize backward integration into detector component manufacturing to offset silicon supply concentration risks. Anchor service contract renewals through PACS interoperability investments that elevate switching costs for German hospital network procurement committees. For New Entrants and Emerging Players: Begin with contrast-enhanced mammography platform deployment in Dutch and Belgian community screening centers, where vascularized lesion detection demand outpaces MRI infrastructure availability. Target Polish regional screening units receiving EU cohesion fund modernization allocations as the most penetrable geography. Pursue reimbursement strategy partnerships with national health technology assessment bodies to accelerate digital breast tomosynthesis parity decisions. For Investors and Strategic Acquirers: Asymmetric upside sits with automated positioning system specialists possessing FDA-cleared algorithms and established notified body relationships, positioned for MDR Class IIa transition consolidation. Long-term viability favors vendors with recurring service revenue exceeding 50% of total mix, insulating against hardware commoditization. Monitor EMA pharmacovigilance guideline evolution on gadolinium retention as inflection indicator for MRI-based screening protocol displacement toward contrast-enhanced mammography alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR conformity assessment compression secures procurement eligibility in German public hospital networks. |
| Hospital System Partnership | Multi-site service contracts with Bavarian university hospitals anchor regional screening network consolidation. |
| Software Companion Development | AI-embedded detection modules validated under EU AI Act risk framework capture premium-tier positioning. |
| Reimbursement Strategy | G-BA parity decisions between tomosynthesis and conventional mammography determine upgrade incentive structures. |
| Geographic Expansion | EU cohesion fund procurement channels in Poland and Romania address underpenetrated screening infrastructure. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads at notified bodies grounded qualitative assessment, cross-referenced against EMA pharmacovigilance databases, G-BA reimbursement decisions, hospital procurement records, and MDR conformity assessment filings. Bottom-up equipment shipment tracking and top-down healthcare expenditure modeling provided triangulation validation across the analysis window.
Bottom-up demand modeling segmented by imaging modality, end-user facility type, and technology tier informed volume projections, while top-down healthcare budget allocation analysis anchored value forecasts across the projection horizon. CAGRs derived from equipment replacement cycles, screening program expansion timelines, and reimbursement parity achievement patterns. AI Act implementation timelines and MDR notified body capacity constraints served as industry-specific forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory guideline revisions, abrupt gadolinium supply disruptions, and radiologist workforce strike actions. Forecasts reflect documented assumptions regarding reimbursement parity progression and MDR transition completion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
H. Pylori Breath Test Kit Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Immunodiagnostics Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Global Inflammatory Bowel Disease (IBD) Diagnostic Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
In-Vitro Diagnostics Enzymes Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Global Chlamydia Infection Diagnostics Market
Diagnostics
Precision Diagnostics Market
Diagnostics
North America Antinuclear Antibody Test Market
Diagnostics
Vision Screeners Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market