
 Acid Citrate Dextrose Tubes Market | 2026-2036
Acid Citrate Dextrose Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Acid Citrate Dextrose Tubes Market Outlook
Plastic resin formulations are decoupling Acid Citrate Dextrose tubes from traditional glass dependency, cutting unit weight and breakage rates in high-volume blood bank logistics. Becton Dickinson leverages its global distribution network to sustain hospital system contracts across North America and Europe. Greiner Bio-One International GmbH specializes in vacuum-stabilized plastic tube architectures that anchor its position in automated blood processing workflows. Terumo Corporation competes through integrated apheresis-to-storage system design that extends its reach from collection to transfusion.
Acid Citrate Dextrose tubes are sterile, evacuated containers pre-filled with a citrate-based anticoagulant solution formulated to chelate calcium ions and preserve platelet function at room temperature for up to five days. The 3 mL and 5 mL product types dominate routine venipuncture workflows, while 10 mL and 20 mL variants serve apheresis and large-volume blood component separation where anticoagulant-to-blood ratios must scale proportionally. Blood banks and hospitals represent the primary end-user concentration, with diagnostic laboratories representing a faster-growing segment as molecular hematology assays expand. Pre-filled kits command premium positioning against bulk packs due to reduced contamination risk and labor efficiency in high-throughput settings.
FDA blood product regulations and EMA's Medical Device Regulation shape material biocompatibility and anticoagulant potency validation requirements, while ISO 13485 quality management standards govern manufacturing consistency for tube producers seeking multi-regional market access. The EU F-Gas Regulation indirectly pressures cold-chain infrastructure decisions that affect storage tube specifications. Stakeholders must monitor evolving platelet additive solutions and extended storage claims that could redefine anticoagulant formulation requirements and tube compatibility standards.
Market Dynamics
Plastic resin substitution for borosilicate glass is compressing logistics costs and breakage losses across high-volume blood bank networks, while FDA and EMA shelf-life validation protocols are extending development timelines for new tube formulations.
Growth Catalysts
- Apheresis infrastructure scaling:Blood banks in the United States, Germany, and Japan are expanding automated platelet collection capacity, driving proportional demand for large-volume ACD tube configurations.
- EMA Medical Device Regulation harmonization:Unified biocompatibility standards across EU member states are streamlining multi-country market entry for tube manufacturers holding ISO 13485 certification.
- Cold-chain protocol extension:Five-day room-temperature platelet storage claims validated under FDA guidance are increasing per-patient tube consumption rates in hospital transfusion services.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil benchmarks, squeezing margin stability for plastic tube producers.
- Anticoagulant supply concentration:Citrate buffer production clusters in select chemical manufacturing regions create geographic vulnerability for tube pre-fill operations.
- Glass-to-plastic conversion limits:Certain molecular diagnostic assays still require glass tube substrates for optical clarity, fragmenting production scale economies.
Strategic Opportunities
- Diagnostic laboratory expansion:Molecular hematology and next-generation sequencing workflows in academic medical centers represent underpenetrated demand for specialized ACD tube formats.
- Pre-filled kit premiumization:Single-use sterile collection systems reduce contamination risk and labor overhead in high-throughput settings, commanding price premiums over bulk packaging.
- EU F-Gas Regulation compliance services:Cold-chain infrastructure redesign mandates create consultative revenue streams for tube suppliers offering storage specification guidance.
Industry Challenges
- Anticoagulant potency validation timelines:FDA stability testing protocols for calcium chelation efficacy extend new product qualification cycles beyond standard medical device pathways.
- Automation integration complexity:Vacuum-stabilized tube architectures must interface with diverse robotic venipuncture and processing platforms across blood bank networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acid Citrate Dextrose Tubes Market |
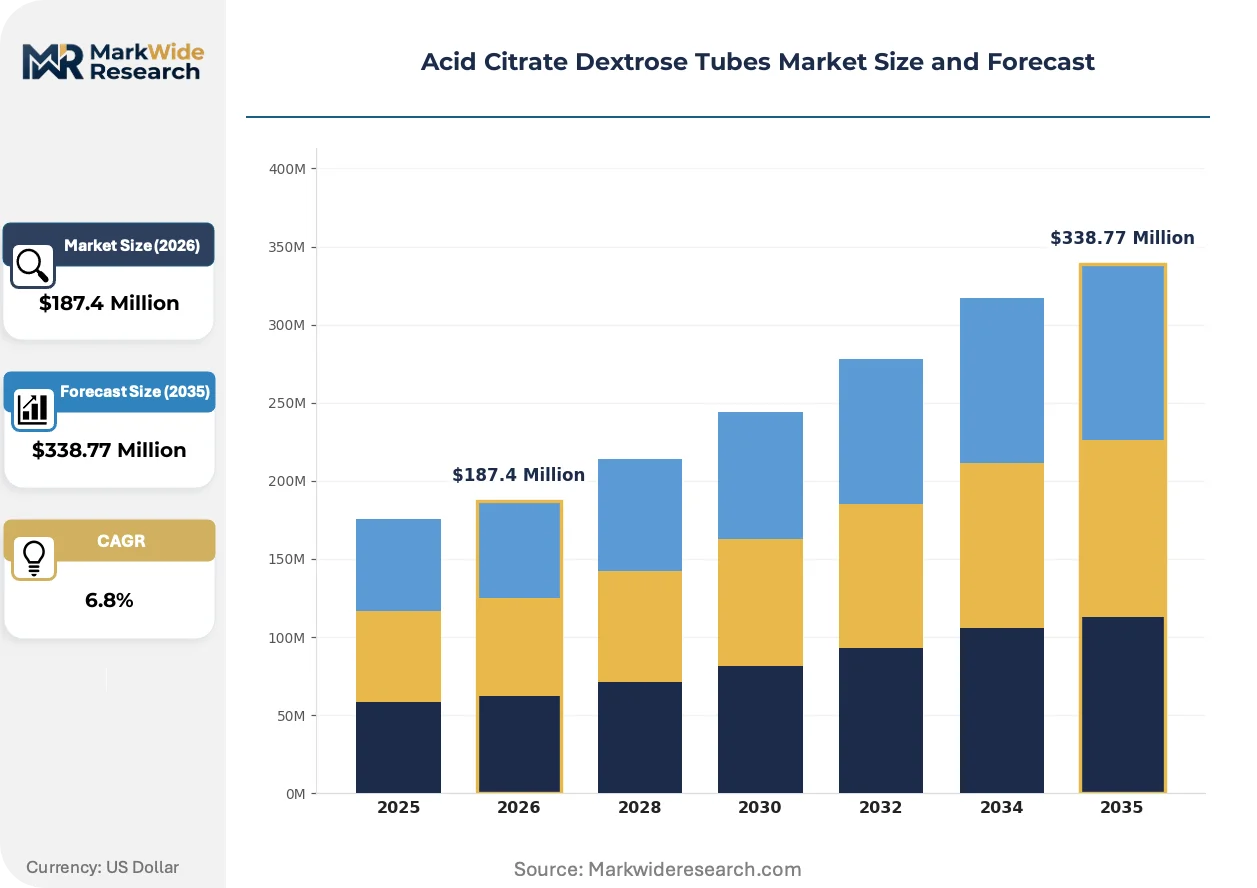
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3 mL, 5 mL, 10 mL, 20 mL End User: Blood Banks, Hospitals, Diagnostic Laboratories, Research Institutes Application: Blood Collection, Blood Storage, Blood Analysis, Transfusion Packaging Type: Sterile Containers, Bulk Packs, Pre-filled Kits, Single-use Units |
| Companies Covered | Becton Dickinson, Fisher Scientific UK, Greiner Bio-One International GmbH, Cryoquip LLC, Zimmer Biomet, Terumo Corporation, Cepham Life Sciences, GBUK Group, Skgmed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acid Citrate Dextrose Tubes Market Strategic Shifts
Material science advances and regulatory harmonization are converging to redefine tube performance specifications, while procurement models in healthcare systems are compressing supplier qualification cycles.
Co-extruded multilayer plastic barrier technologies are electrifying shelf-life extension claims for platelet concentrates. Blood banks in North America and Western Europe are adopting these substrates at accelerated replacement rates. The shift is electrifying competitive differentiation around gas permeability coefficients and moisture vapor transmission rates.
REACH substance restriction amendments targeting phthalate plasticizers are forcing reformulation of tube closure and cap materials across EU manufacturing facilities. Compounders must validate alternative elastomer formulations without compromising vacuum seal integrity. Diagnostic laboratories with EU export requirements are prioritizing CE-marked tubes with full material disclosure documentation.
Consolidated purchasing through group purchasing organizations is compressing vendor panels for hospital systems. Blood banks are replacing fragmented supplier relationships with single-source contracts spanning collection through storage. The United States exhibits the most pronounced concentration, with multi-hospital networks standardizing on two to three qualified tube suppliers.
Acid Citrate Dextrose Tubes Market Segmentation
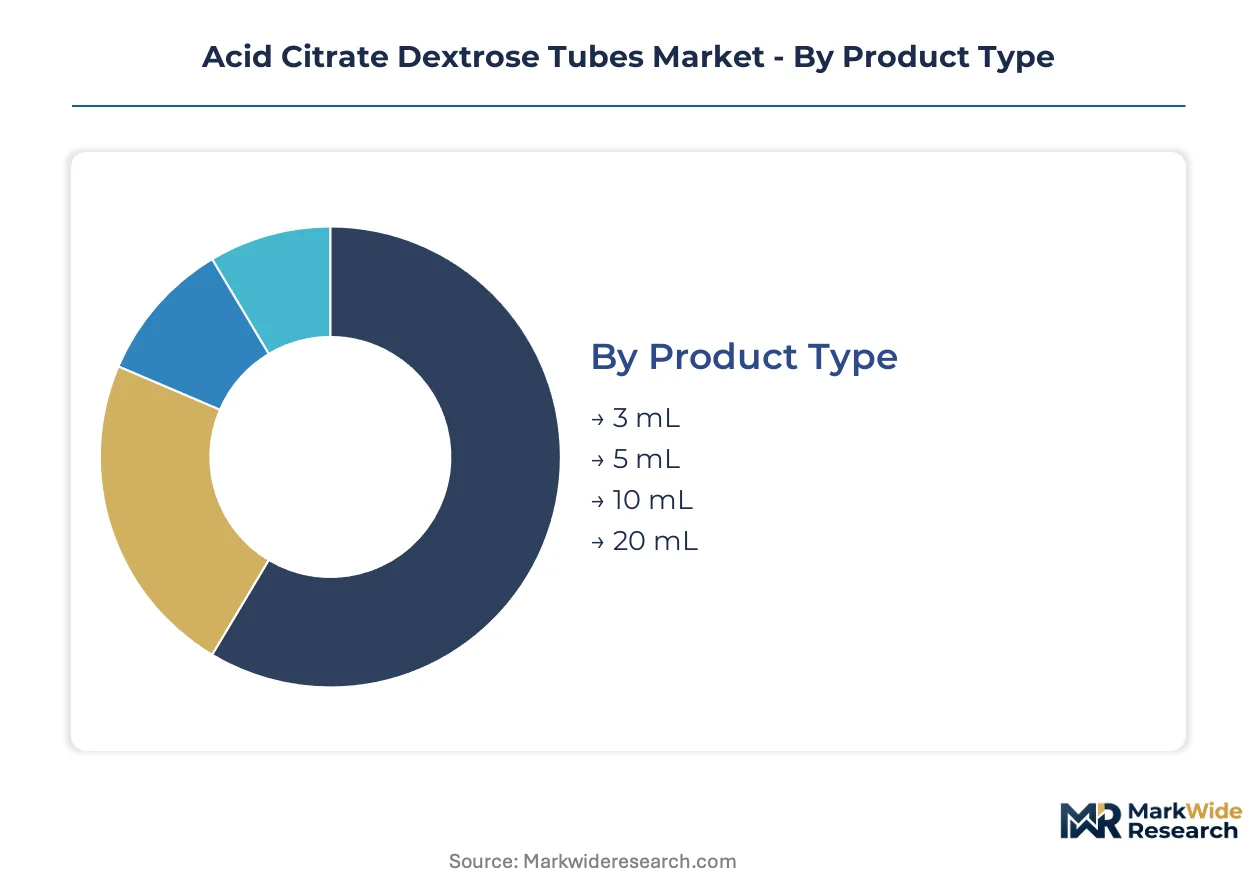
Tube specification choices cascade through anticoagulant dosing accuracy, cold-chain compatibility, and automation interface requirements. Procurement managers balance standardization economies against specialized formats demanded by molecular diagnostics and apheresis workflows.
Product Type:
Standardization dominates routine venipuncture while customization intensity rises with volume scaling and specialized collection protocols.
- 3 mL:These tubes contain precisely calibrated citrate-to-blood ratios optimized for standard coagulation panels and complete blood counts. Demand concentrates in hospital outpatient clinics across the United States and Germany where high-throughput phlebotomy operations prioritize handling uniformity. FDA guidance on minimum fill volumes drives specification tightening.
- 5 mL:The workhorse configuration bridges routine diagnostics and specialized hematology applications with expanded anticoagulant capacity. Blood banks in Japan favor this format for balanced platelet yield and storage efficiency. EMA shelf-life validation protocols apply uniformly across this mid-volume tier.
- 10 mL:Apheresis collection workflows and large-volume component separation require scaled anticoagulant reservoirs.
- 20 mL:Therapeutic apheresis and plasma exchange procedures utilize these maximum-capacity formats for extended collection cycles.
Most installed capacity flows through 5 mL tubes. Expansion is steepest in 10 mL configurations.
End User:
Customer sophistication varies from standardized bulk procurement to precision-engineered single-use systems with full traceability documentation.
- Blood Banks:These facilities operate the most stringent cold-chain protocols and demand vacuum-stabilized tubes with validated five-day platelet preservation claims. The United States, Germany, and Japan anchor procurement concentration as these nations scale automated collection infrastructure. ISO 13485 certification is mandatory for supplier qualification.
- Hospitals:Transfusion services and emergency departments prioritize breakage resistance and ergonomic handling in high-stress clinical environments. Group purchasing organization consolidation in the United States compresses vendor panels to two or three qualified suppliers per network.
- Diagnostic Laboratories:Molecular hematology and next-generation sequencing workflows are gaining share fastest in academic medical centers requiring optical-grade substrates and minimal extractable contaminants.
- Research Institutes:Cell therapy development and regenerative medicine protocols drive demand for customizable tube configurations with extended documentation packages.
Procurement volume concentrates in blood banks. Diagnostic laboratories are expanding most quickly.
Application:
Workflow integration depth separates commodity collection from value-added storage and analysis functions.
- Blood Collection:Venipuncture and apheresis systems require precise vacuum calibration and needle gauge compatibility. Automated collection platforms in Japanese blood centers demand tube architectures with robotic handling tolerances.
- Blood Storage:Five-day room-temperature platelet preservation claims validated under FDA guidance concentrate demand in North American hospital networks. Gas permeability coefficients determine substrate selection.
- Blood Analysis:Coagulation testing and hematology assays depend on consistent citrate concentration and pH stability. REACH substance restrictions on phthalate plasticizers are forcing EU laboratory suppliers toward full material disclosure documentation.
- Transfusion:Bedside administration protocols prioritize closed-system integrity and compatibility with blood warmers and infusion pumps.
Collection applications dominate installed base. Storage functionality is climbing the fastest.
Packaging Type:
Contamination risk tolerance and labor cost structures drive the sterile-to-bulk spectrum.
- Sterile Containers:Individual peel-pouch packaging satisfies operating room and sterile processing department requirements with full lot traceability. German hospital systems mandate this format for surgical blood salvage procedures.
- Bulk Packs:High-volume blood bank networks minimize per-unit cost through carton-level procurement with validated sterilization certificates. Standardization enables automated unpacking and loading into processing lines.
- Pre-filled Kits:Single-use collection systems integrate tube, needle, and holder with sterile field compatibility. These configurations command price premiums in the United States where labor efficiency and contamination reduction justify higher acquisition cost.
- Single-use Units:Point-of-care testing and emergency response applications favor individually wrapped tubes with immediate readiness and minimal preparation steps.
Bulk packs channel most volume. Pre-filled kits are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated platelet collection infrastructure in the United States, Germany, and Japan anchors procurement concentration for Acid Citrate Dextrose tubes. Blood banks across these markets are scaling cold-chain storage protocols and apheresis capacity. Regulatory validation requirements from FDA and EMA are tightening shelf-life standards.
United States
Hospital networks and blood centers in Texas, California, and the Northeast Corridor are consolidating vendor panels through group purchasing organizations. FDA guidance on five-day room-temperature platelet storage claims drives substrate specification upgrades. The Greater Boston cluster houses automated collection platform developers integrating tube architectures with robotic handling systems.
Germany
German hospital systems mandate sterile peel-pouch packaging for surgical blood salvage procedures, elevating premium format demand. EMA Medical Device Regulation harmonization streamlines multi-country market entry for ISO 13485-certified suppliers. The Baden-Württemberg industrial corridor concentrates vacuum-stabilized plastic tube manufacturing for automated blood processing workflows.
Japan
Japanese blood centers favor 5 mL tube configurations for balanced platelet yield and storage efficiency. METI standards govern material biocompatibility for medical device substrates. The Kanto region around Tokyo anchors apheresis infrastructure expansion with integrated collection-to-storage system deployment.
United Kingdom
Academic medical centers in London and the Southeast are expanding molecular hematology and next-generation sequencing workflows. REACH substance restrictions on phthalate plasticizers force laboratory suppliers toward full material disclosure documentation. The Cambridge-Oxford corridor drives demand for optical-grade tube substrates with minimal extractable contaminants.
India
Diagnostic laboratories in Maharashtra and Karnataka are adopting specialized ACD tube formats for molecular hematology assays. CDSCO regulations shape anticoagulant potency validation requirements for imported tube configurations. The Mumbai-Pune industrial belt concentrates bulk procurement for high-throughput hospital networks.
Acid Citrate Dextrose Tubes Market Competitive Environment
Capacity expansion dominates the current landscape as tube manufacturers scale plastic resin formulation capabilities to serve automated blood processing workflows. The vendor base clusters around three strategic archetypes: diversified medical device conglomerates with global distribution networks, specialized vacuum-stabilized tube architects, and integrated apheresis-to-storage system designers. M&A activity and strategic partnerships concentrate among firms seeking backward integration into citrate buffer supply chains and forward integration into pre-filled kit assembly.
Within the diversified conglomerate tier, Becton Dickinson and Terumo Corporation occupy positions anchored by hospital system contracts and integrated collection platform design. Among European specialists, Greiner Bio-One International GmbH exemplifies vacuum-stabilized plastic tube architecture focused on automated processing compatibility. These three entities represent distinct competitive vectors: scale-driven distribution, substrate engineering specialization, and end-to-end workflow integration.
| Leading Market Players |
|---|
| Becton Dickinson |
| Fisher Scientific UK |
| Greiner Bio-One International GmbH |
| Cryoquip LLC |
| Zimmer Biomet |
| Terumo Corporation |
| Cepham Life Sciences |
| GBUK Group |
| Skgmed |
| Others |
Value Chain & Pricing Dynamics
Group purchasing organization consolidation in United States hospital networks concentrates procurement volume among two to three qualified suppliers per network, locking in contract-based long-term offtake pricing with volume-scaled discounts. This buyer concentration shifts pricing power toward blood bank networks while squeezing margin flexibility for tube manufacturers navigating petrochemical feedstock volatility.
Pricing Analysis
Polypropylene and polyethylene resin cost pass-through clauses dominate contract structures, with quarterly adjustments tethering tube prices to crude oil benchmarks. Three-tier pricing structure across premium sterile peel-pouch, standard vacuum-stabilized, and economy bulk-pack formats differentiates by contamination risk tolerance and labor efficiency. Cost compression in economy tiers is intensifying because blood banks are standardizing on single-source contracts spanning collection through storage. Diagnostic laboratories with molecular hematology workflows exhibit the least price sensitivity due to optical-grade substrate requirements and minimal extractable contaminant specifications.
Supply Chain Analysis
Specialized polymer compounding expertise concentrates in Germany, the United States, and Japan, where workforce availability in medical device manufacturing exceeds generic plastics hubs. Citrate buffer production draws from select chemical manufacturing regions, while vacuum-stabilized tube assembly rests on precision molding capabilities clustered in Baden-Württemberg and the American Midwest. Single-source vulnerability in anticoagulant supply creates geographic concentration risk for pre-fill operations. Distribution runs through blood bank central procurement with direct manufacturer contracts, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Acid Citrate Dextrose tubes rests on plastic resin substitution decoupling production from glass dependency, cutting unit weight and breakage losses while enabling premium positioning for pre-filled sterile kits.
For Market Incumbents: Deepen backward integration into citrate buffer supply chains to offset anticoagulant production concentration risk in select chemical manufacturing regions. Expand vacuum-stabilized plastic tube capacity in Baden-Württemberg to serve EMA Medical Device Regulation harmonization demand. Lock in multi-year contracts with Japanese blood centers scaling apheresis infrastructure before competitor qualification cycles complete. For New Entrants and Emerging Players: Capture diagnostic laboratory demand in academic medical centers running molecular hematology and next-generation sequencing workflows, a segment expanding faster than blood bank procurement. Target United Kingdom REACH compliance services as laboratories force suppliers toward full material disclosure documentation. Lead with optical-grade substrate specialization and minimal extractable contaminant validation to bypass incumbent standard product lock-in. For Investors and Strategic Acquirers: Diversified medical device conglomerates with global distribution networks are the most active acquirers in this space, seeking vacuum-stabilized tube architects to fill automated processing workflow gaps. Long-term viability hinges on substrate engineering specialization that commands recurring revenue from cold-chain protocol extension mandates. Watch FDA guidance on extended platelet storage claims as the inflection signal for anticoagulant formulation upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrate Buffer Supply | Captive anticoagulant production mitigates geographic concentration risk in pre-fill operations. |
| Vacuum-Stabilized Plastic Tube Capacity Expansion | Baden-Württemberg manufacturing serves EMA harmonization and automated blood processing demand. |
| Pre-Filled Sterile Kit Assembly Investment | Single-use collection systems command price premiums in United States labor-efficient hospital networks. |
| Optical-Grade Substrate Development | Cambridge-Oxford corridor laboratories prioritize minimal extractable contaminants for sequencing workflows. |
| EU F-Gas Regulation Compliance Services | Consultative revenue streams emerge from cold-chain infrastructure redesign mandates in German hospital systems. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blood bank procurement managers, hospital GPO contracts managers, biomedical engineers, and diagnostic laboratory directors with secondary validation. FDA 510(k) filings, EMA Medical Device Regulation guidance documents, ISO 13485 certification registries, and hospital procurement database extracts anchored the secondary foundation. Bottom-up tube shipment estimates triangulated against top-down blood bank capacity expansion projections across the analysis window.
Segment-weighting approaches modeled product type splits, end-user concentration patterns, application workflow integration depth, and packaging format adoption curves. CAGRs were derived from installed base replacement rates and apheresis infrastructure scaling trajectories. Cold-chain protocol extension claims and REACH substance restriction amendments fed directly into substrate demand forecasts.
Petrochemical feedstock volatility, anticoagulant supply concentration events, and regulatory shelf-life validation timeline extensions are the dominant revision risks to modeled outputs. Practitioners should monitor FDA guidance evolution on platelet additive solutions and EU F-Gas Regulation implementation pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Smear Mask Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Tongue Depressors Market
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Europe Ostomy Care and Accessories Market