
 Antiscalants/Scale Inhibitors Market | 2026-2036
Antiscalants/Scale Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Antiscalants/Scale Inhibitors Market Analysis
Project finance for large desalination and power infrastructure is narrowing the competitive field to suppliers with balance-sheet capacity for multi-year chemical service contracts. Dow Chemical Company leverages its integrated polymer backbone to sustain cost advantages in phosphate-based formulations across Middle Eastern membrane plants. Kemira anchors its position through backward integration into phosphonate intermediates, while Solvay competes on specialty polymer architectures for high-salinity oil field brines.
Antiscalants and scale inhibitors comprise synthetic organic compounds—primarily phosphonates, polyacrylates, and polymaleic acids—typically dosed at 2–10 ppm to disrupt crystal nucleation and growth on heat-transfer and membrane surfaces. Their primary industrial purpose is to prevent mineral scale deposition of calcium carbonate, calcium sulfate, and barium sulfate in water-intensive processes. Organic antiscalants command the largest share of product type revenue due to decades of proven performance in reverse osmosis trains, while bio-derived scale inhibitors represent the fastest-expanding category as ESG procurement criteria harden in European water utilities. Among end users, oil and gas operations retain the highest per-unit dosing intensity, though power generation accounts for the broadest installed base of continuous-feed systems.
The EPA enforces discharge limits under the Clean Water Act that directly shape cooling tower blowdown chemistry requirements, while REACH registration in Europe constrains phosphonate import volumes and pushes reformulation toward biodegradable alternatives. China's MEE implements increasingly strict effluent standards for thermal power plants that mandate upgraded scale control programs. Stakeholders must monitor how regulatory divergence between jurisdictions fragments product registration portfolios and forces regional specialization in active ingredient supply.
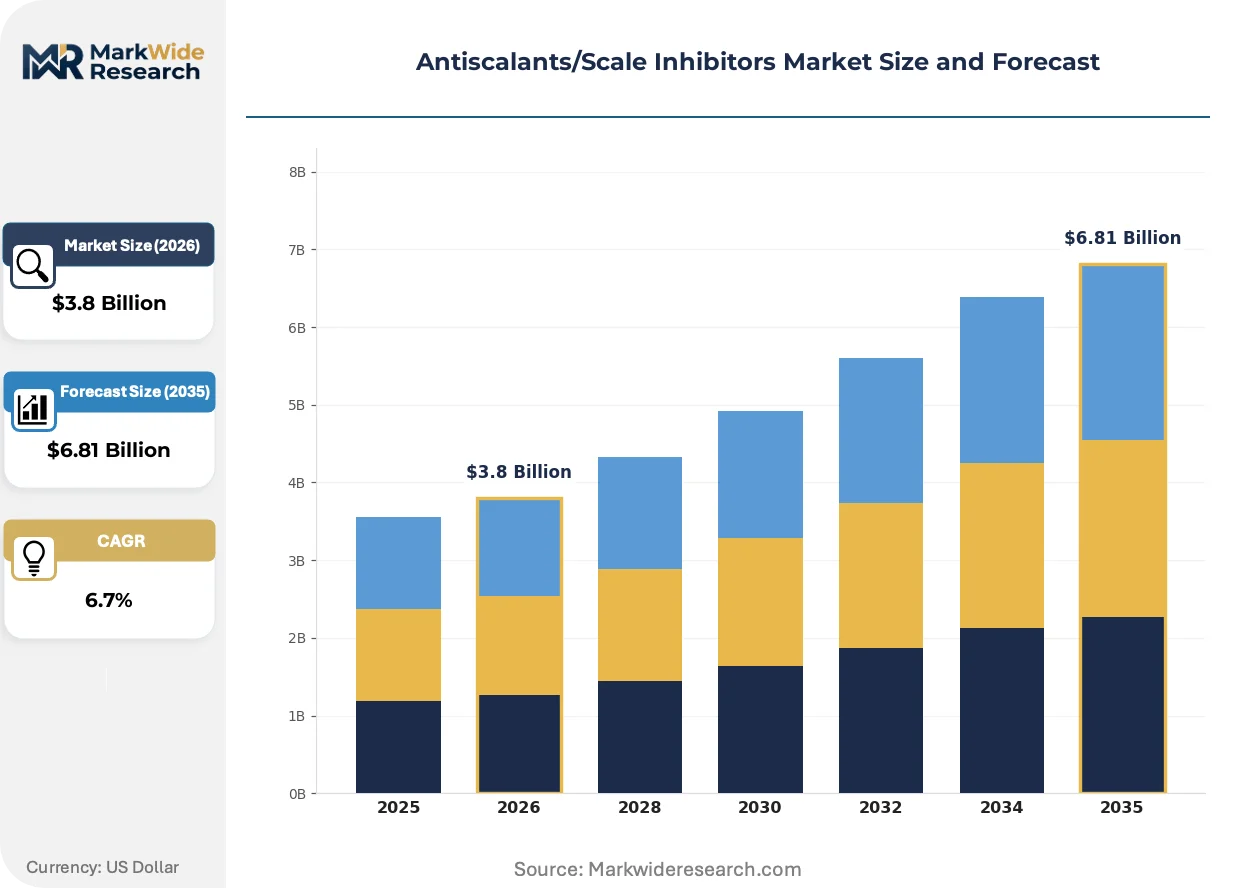
Market Dynamics
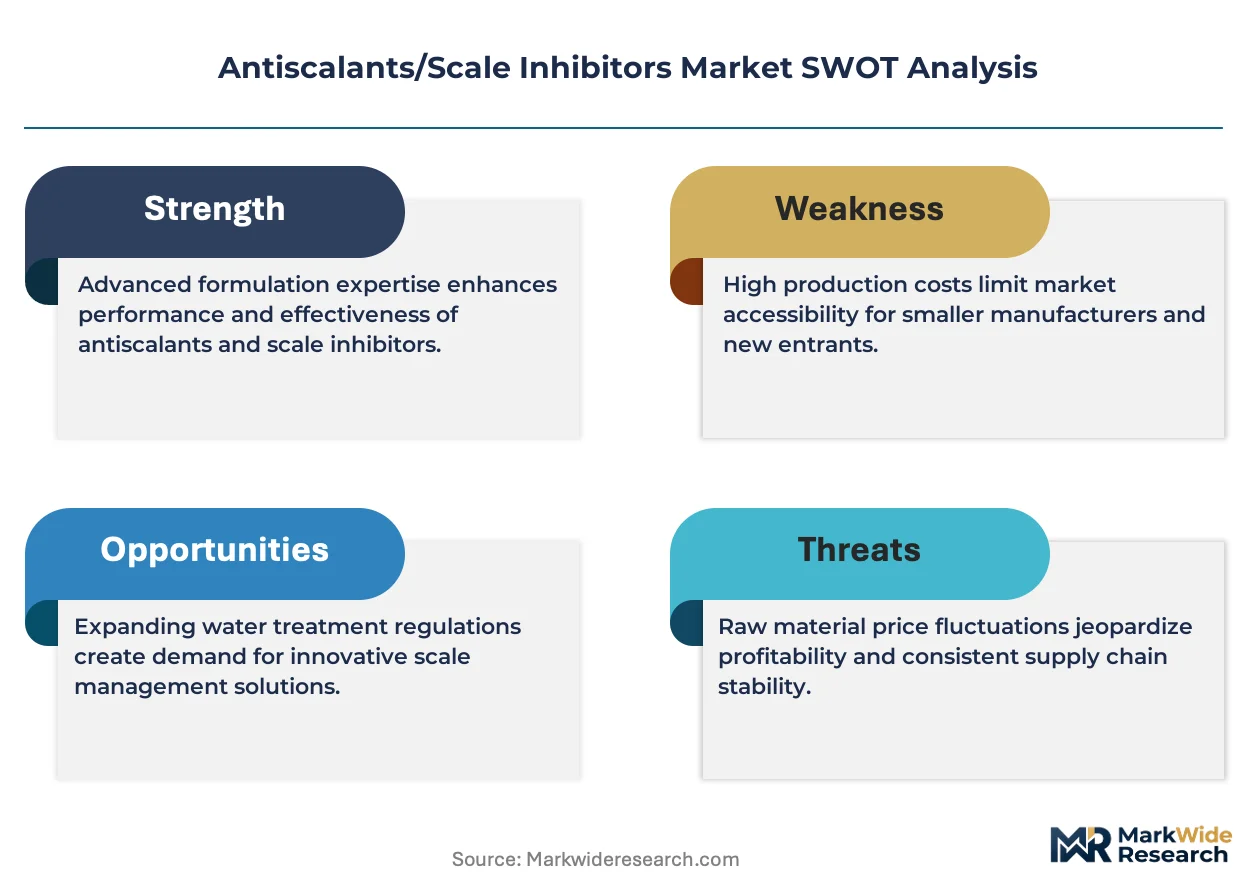
Phosphonate-based formulations face mounting substitution pressure as REACH registration constraints in Europe and China's MEE effluent mandates force reformulation toward biodegradable polymer architectures.
Growth Catalysts
- Thermal power capacity additions:China's industrial corridor cities require synchronized antiscalant procurement for new cooling infrastructure, concentrating demand in high-growth manufacturing clusters.
- EPA cooling water intake regulations:Tightened discharge limits in the United States drive upgraded scale control chemistry across power generation utilities protecting critical assets.
- Membrane plant expansion:Reverse osmosis train installations in Middle Eastern desalination facilities sustain organic antiscalant consumption at 2–10 ppm dosing protocols.
Market Restraints
- Phosphonate feedstock volatility:Phosphorus derivative pricing swings compress margin stability for manufacturers dependent on phosphate-based backbone chemistries.
- REACH registration bottlenecks:European phosphonate import volume constraints fragment product registration portfolios and force regional specialization in active ingredient supply.
- Biopolymer performance gaps:Bio-derived scale inhibitors exhibit inconsistent nucleation disruption kinetics against barium sulfate in high-salinity brines.
Strategic Opportunities
- ESG procurement hardening:European water utilities mandate biodegradable alternatives, creating premium positioning for polyaspartate and polymaleic acid formulations.
- Oil field brine specialization:High-salinity extraction chemistry in Middle Eastern reservoirs demands specialty polymer architectures with superior calcium sulfate inhibition.
- Multi-year service contracting:Project finance structures for desalination infrastructure favor suppliers with balance-sheet capacity for integrated chemical management programs.
Industry Challenges
- Formulation chemist scarcity:Expertise in crystal nucleation kinetics and polymer-surface interaction modeling concentrates among aging technical workforces.
- Legacy cooling system compatibility:Retrofitting continuous-feed antiscalant systems into existing power plant infrastructure requires custom engineering and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiscalants/Scale Inhibitors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Antiscalants, Inorganic Antiscalants, Bio-derived Scale Inhibitors, Multi-functional Inhibitors End User: Oil & Gas, Power Generation, Water Treatment, Chemical Processing Application: Cooling Systems, Reverse Osmosis, Boiler Systems, Oil Fields Technology: Polymer-based Solutions, Phosphate-based Solutions, Biomimetic Approaches, Others |
| Companies Covered | Solvay, Clariant, Dow Chemical Company, Avista Technologies, Kemira, Ecolab, Solenis, Innospec, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiscalants/Scale Inhibitors Market Emerging Trajectories
Active ingredient architectures are pivoting toward bio-based backbones as regulatory chemistry constraints harden across major industrial jurisdictions, reshaping R&D allocation and manufacturing asset deployment.
Phosphonate antiscalant chemistry is migrating from standard calcium carbonate inhibition toward multifunctional polymer blends engineered for simultaneous sulfate and silica control. Power generation utilities in the United States adopt these advanced formulations to meet EPA-mandated blowdown chemistry requirements. The shift compresses demand for single-mechanism products while expanding service contract complexity.
REACH registration in Europe constrains phosphonate import volumes and pushes active ingredient production toward biodegradable polyaspartate alternatives. Chemical manufacturers reconfigure supply chains to maintain European market access. Oil and gas operations face the steepest compliance costs due to highest per-unit dosing intensity.
Buyer concentration among large desalination project developers fragments procurement into long-term chemical service agreements. Traditional spot purchasing of commodity antiscalants loses share to integrated water chemistry management contracts. This pattern concentrates most visibly in Middle Eastern membrane plant expansions where project finance structures favor multi-year supplier commitments.
Antiscalants/Scale Inhibitors Market Segmentation
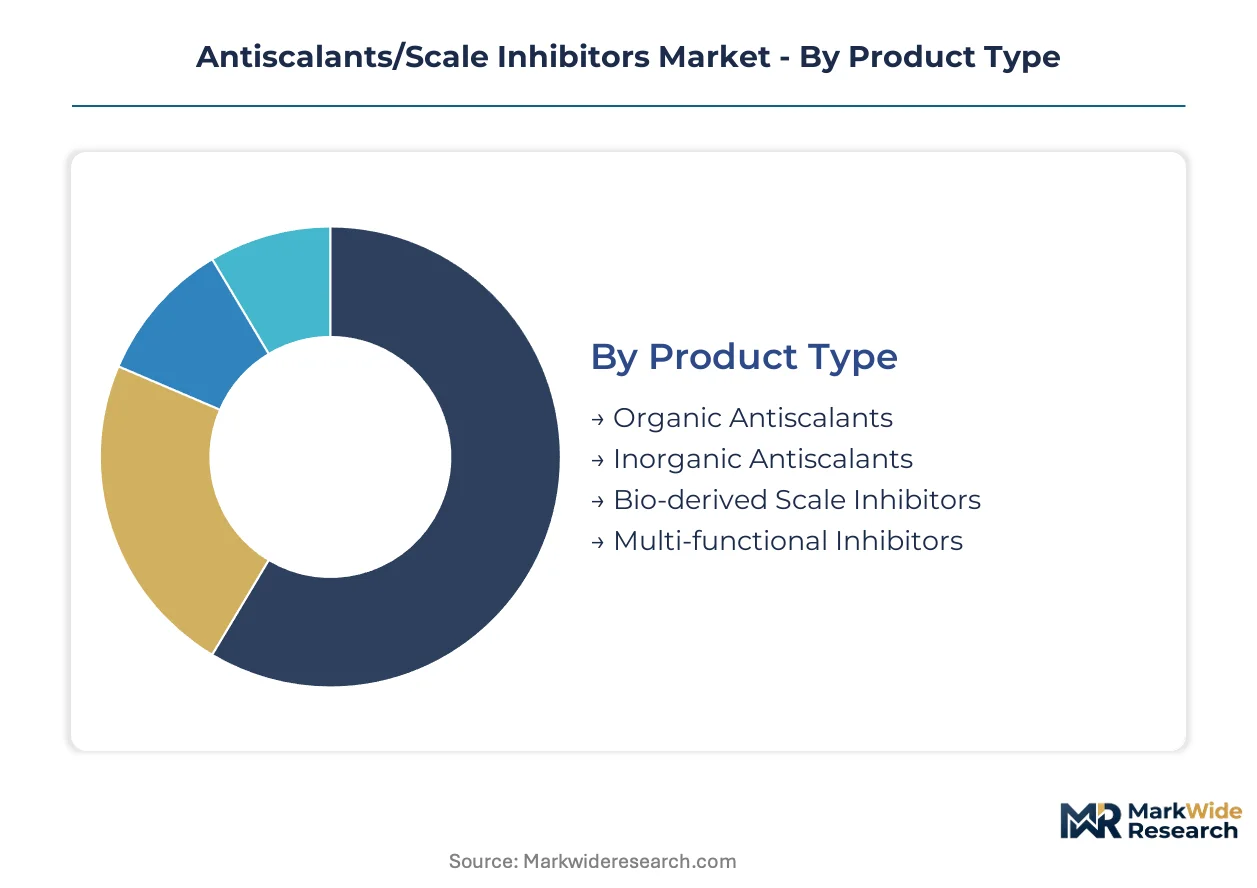
Antiscalant procurement patterns diverge sharply across product chemistries and end-use intensities. Service contract structures, dosing protocols, and regulatory compliance burdens create distinct margin profiles that reshape supplier priorities within each segment cluster.
Product Type:
After-sales service intensity escalates with formulation complexity as continuous dosing optimization and membrane performance monitoring become embedded in multi-year supply agreements.
- Organic Antiscalants:Synthetic phosphonates and polyacrylates formulated for 2–10 ppm dosing in reverse osmosis trains. Power generation utilities in the United States anchor organic antiscalant procurement through EPA-mandated cooling water chemistry upgrades that demand sustained technical support.
- Bio-derived Scale Inhibitors:Polyaspartate and polysaccharide-based formulations engineered for biodegradability under REACH constraints. European water utilities concentrate procurement here as ESG criteria harden, though inconsistent barium sulfate inhibition in high-salinity brines limits oil field penetration.
- Inorganic Antiscalants:Polyphosphate and silicate-based precipitants deployed in cost-sensitive boiler applications. China's thermal power corridor sustains volume procurement despite performance limitations against complex sulfate scales.
- Multi-functional Inhibitors:Polymer blends engineered for simultaneous carbonate, sulfate, and silica control. Middle Eastern desalination developers favor these for reduced chemical inventory complexity in membrane-intensive facilities.
By volume, Organic Antiscalants leads. By growth pace, Bio-derived Scale Inhibitors is climbing the fastest.
End User:
Customer concentration patterns segment the market into project-finance-driven bulk procurement versus fragmented spot purchasing.
- Oil & Gas:Highest per-unit dosing intensity across extraction, refining, and pipeline operations. Middle Eastern reservoir chemistry with extreme salinity and barium sulfate risk demands specialty polymer architectures with elevated service engagement.
- Power Generation:Broadest installed base of continuous-feed systems protecting critical cooling infrastructure. EPA cooling water intake regulations in the United States tighten discharge limits and force chemistry program upgrades across utility fleets.
- Water Treatment:Municipal and industrial membrane plants requiring synchronized antiscalant procurement with membrane replacement cycles. China's industrial corridor cities concentrate demand as thermal capacity additions accelerate.
- Chemical Processing:Process-specific scale control in evaporators and crystallizers. Formulation customization dominates procurement with lower standardization than power or desalination sectors.
Power Generation commands the widest supplier footprint. Oil & Gas extracts the steepest per-ton pricing premiums.
Application:
Equipment-specific performance requirements fragment active ingredient selection and dosing protocol design.
- Cooling Systems:Open-recirculating and once-through configurations in power plants and refineries. EPA-mandated blowdown chemistry in the United States drives reformulation toward multifunctional polymer blends.
- Reverse Osmosis:Membrane surface protection in desalination and wastewater reuse. Organic antiscalants dominate at 2–10 ppm dosing with real-time fouling monitoring embedded in service contracts.
- Boiler Systems:Steam generation scale control with temperature-stability requirements. Inorganic polyphosphates retain share in low-pressure applications despite organic polymer performance advantages.
- Oil Fields:Downhole and surface facility protection against calcium sulfate and barium sulfate deposition. High-salinity brine chemistry in Saudi Arabian and Kuwaiti reservoirs demands specialty polymer architectures with superior nucleation disruption kinetics.
Reverse Osmosis generates the most standardized procurement. Oil Fields requires the most customized formulation development.
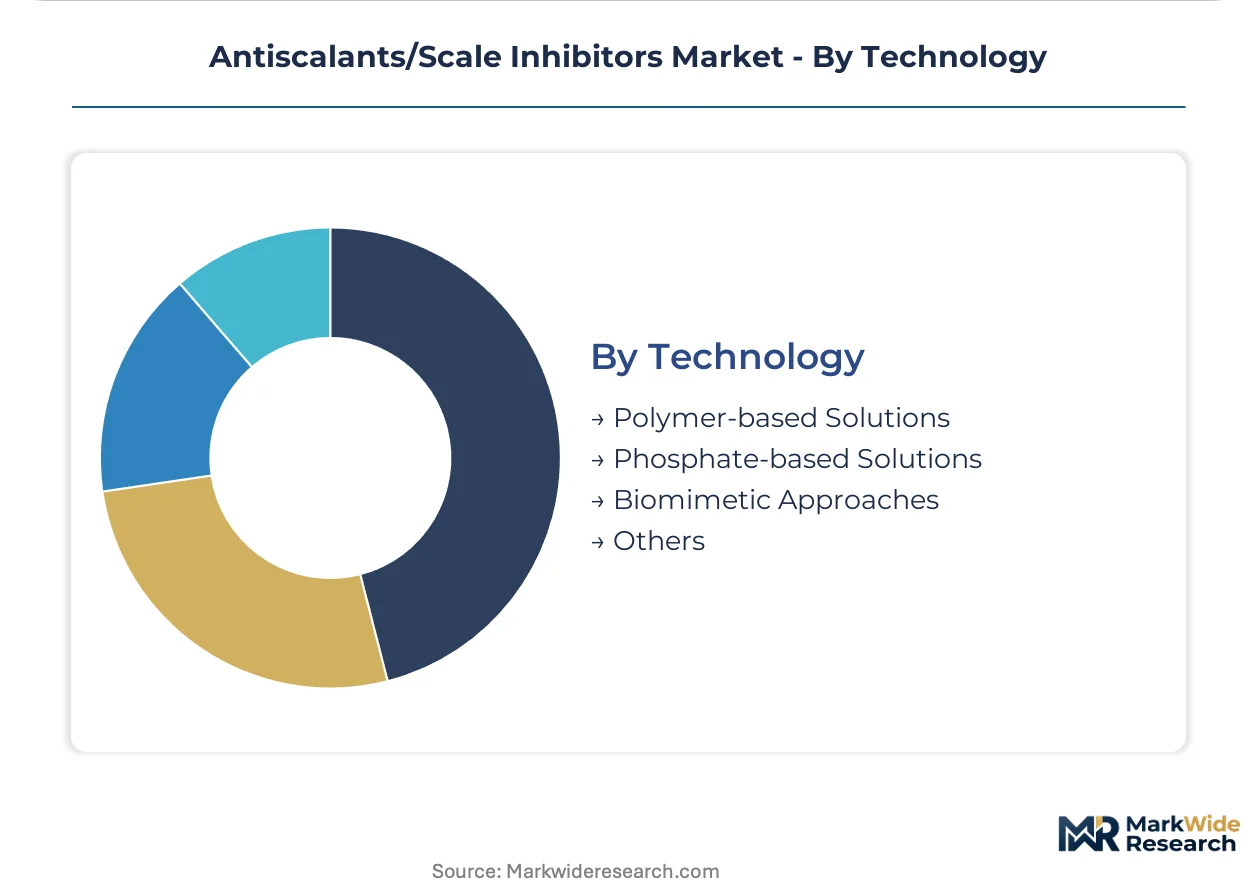
Technology:
Manufacturing asset configuration and feedstock integration depth separate competitive positions across technology platforms.
- Polymer-based Solutions:Polyacrylate, polymaleic acid, and polyaspartate backbones synthesized for specific scale inhibition mechanisms. REACH registration constraints in Europe accelerate biodegradable polymer R&D allocation.
- Phosphate-based Solutions:Phosphonate intermediates with decades of proven calcium carbonate inhibition performance. Phosphorus derivative pricing volatility compresses margin stability for non-integrated manufacturers.
- Biomimetic Approaches:Crystal growth modifiers derived from natural protein and polysaccharide templates. Early-stage commercialization with performance validation ongoing in European municipal water utilities.
- Others:Emerging chelant and dispersant technologies including green solvent carriers. Niche positioning pending regulatory approval trajectories in multiple jurisdictions.
Phosphate-based Solutions retains the largest production asset base. Polymer-based Solutions is gaining share fastest as regulatory chemistry constraints harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Project developers in water-stressed industrial corridors concentrate antiscalant procurement through multi-year chemical service contracts. Large desalination and power infrastructure financiers favor suppliers with balance-sheet capacity for integrated water chemistry management.
United States
Power generation utilities anchor demand through EPA-mandated cooling water chemistry upgrades. The EPA's cooling water intake regulations tighten discharge limits and force reformulation toward multifunctional polymer blends. Texas and Arizona industrial clusters sustain synchronized procurement for thermal power capacity additions.
China
Thermal power corridor cities require synchronized antiscalant procurement for new cooling infrastructure. The MEE implements increasingly strict effluent standards for thermal power plants that mandate upgraded scale control programs. Yangtze River Delta manufacturing clusters concentrate demand as industrial capacity accelerates.
Germany
European water utilities drive biodegradable antiscalant procurement as ESG criteria harden. REACH registration constraints phosphonate import volumes and push reformulation toward polyaspartate alternatives. Ruhr industrial basin chemical processors anchor specialty polymer demand for complex sulfate scale control.
Saudi Arabia
Desalination project developers concentrate procurement through integrated chemical management contracts. High-salinity reservoir chemistry in Eastern Province oil fields demands specialty polymer architectures with superior calcium sulfate inhibition. NEOM infrastructure development sustains premium antiscalant service agreements.
United Arab Emirates
Membrane plant expansions in Dubai and Abu Dhabi sustain organic antiscalant consumption at 2–10 ppm dosing protocols. Project finance structures favor suppliers with multi-year chemical service contract capacity. Desalination infrastructure developers anchor regional demand for continuous-feed system integration.
Antiscalants/Scale Inhibitors Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Large integrated chemical houses leverage backward integration into phosphonate intermediates and polymer backbones to sustain cost advantages in phosphate-based formulations. Specialty polymer architects compete on high-salinity oil field chemistry and biodegradable alternatives. Dominant competitive moves include multi-year service contracting for desalination infrastructure and reformulation toward REACH-compliant biodegradable architectures.
Within the integrated chemical tier, Dow Chemical Company and Solvay exemplify divergent strategic positions. Dow anchors its competitive stance through captive supply of polymer backbone chemistries serving Middle Eastern membrane plant demand. Solvay occupies a position as a specialty polymer architect targeting high-salinity extraction chemistry. Kemira represents the backward-integrated phosphonate intermediate model, securing feedstock control for European market access under REACH constraints. These three players illustrate how manufacturing asset configuration and regulatory chemistry expertise fragment competitive positioning across jurisdictions.
| Leading Market Players |
|---|
| Solvay |
| Clariant |
| Dow Chemical Company |
| Avista Technologies |
| Kemira |
| Ecolab |
| Solenis |
| Innospec |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Phosphorus derivative feedstock volatility compresses margin stability for non-integrated manufacturers and simultaneously widens pricing tier spreads between captive-supply leaders and spot-market dependent competitors while reshaping procurement toward multi-year chemical service contracts with indexation clauses.
Pricing Analysis
Cost-plus contracts with phosphoric acid indexation dominate procurement for phosphate-based formulations, anchoring pricing to commodity feedstock benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates specialty polymer architects serving Middle Eastern oil fields from commodity phosphonate suppliers to Chinese power utilities. Pricing pressure stems from REACH registration compliance costs that force reformulation toward biodegradable alternatives with uncertain performance premiums. Water treatment utilities exhibit highest price sensitivity due to municipal budget constraints, while oil and gas operations accept steepest per-ton premiums for barium sulfate inhibition reliability.
Supply Chain Analysis
Export-control regimes on phosphorus processing technology limit equipment flows to emerging manufacturing jurisdictions and concentrate active ingredient production in established chemical corridors. China, Germany, and the United States anchor phosphonate intermediate supply, while Saudi Arabia and the United Arab Emirates host downstream blending operations for desalination chemical service contracts. Phosphoric acid, phosphorous acid, and specialized polymer initiators constitute critical input dependencies. Single-source vulnerability runs through Chinese phosphorus derivative capacity that feeds global antiscalant backbone production. Distribution runs through integrated chemical management contracts rather than spot purchasing, with project developers consolidating procurement through multi-year supplier commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as bio-derived scale inhibitors displace synthetic phosphonates under hardening ESG procurement criteria across European water utilities.
For Market Incumbents: Insulate formulation portfolios through backward integration into phosphonate intermediates and accelerated R&D allocation toward polyaspartate biodegradability. Secure REACH registration assets ahead of competitor filings to maintain European market access. Anchor multi-year service contracts with Middle Eastern desalination developers to lock out emerging biopolymer specialists. For New Entrants and Emerging Players: Pursue white-space positioning in biomimetic crystal growth modifiers for European municipal utilities with mandated green procurement thresholds. Target oil field chemistry gaps where bio-derived inhibitors exhibit inconsistent barium sulfate nucleation disruption kinetics. Lead with performance-guarantee contracting to overcome incumbent reference advantages in continuous-feed system integration. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors backward-integrated phosphonate producers with balance-sheet capacity for multi-year chemical service contracting. Acquisition targets should demonstrate captive feedstock supply and established project finance relationships with desalination infrastructure developers. Monitor REACH registration completion rates as inflection indicator for European market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive phosphonate intermediate production insulates margin stability against phosphorus derivative volatility. |
| Biodegradable Formulation Transition | Polyaspartate R&D allocation secures European water utility procurement under REACH constraints. |
| Multi-year Service Contracting | Integrated chemical management agreements lock in desalination project developer relationships. |
| Specialty Polymer Architecture Development | High-salinity oil field chemistry commands premium pricing in Saudi Arabian and Kuwaiti reservoirs. |
| Regional Production Footprint Expansion | Proximity to China's Yangtze River Delta thermal power corridor reduces logistics costs for cooling system chemistry. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with water treatment plant managers, power generation utility procurement leads, oil field chemical specialists, and desalination project developers. Secondary validation drew from EPA cooling water intake regulation filings, MEE effluent standard updates, REACH registration databases, and trade flow data for phosphorus derivative imports. Bottom-up volume modeling triangulated against top-down market sizing across product chemistry, end-use intensity, and regional regulatory cluster dimensions.
Calibration against historical price realization data and contract announcement patterns anchored the analytical framework across the projection horizon. Segmentation modeling incorporated product type tiers, application equipment categories, technology platform differentiation, and regional regulatory stringency levels. CAGRs were derived from installed base expansion rates, dosing intensity trends, and substitution elasticity parameters for biodegradable alternatives. Forecast inputs included thermal power capacity addition pipelines, membrane plant commissioning schedules, and oil field brine chemistry specifications.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, phosphorus commodity pricing, or project finance availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology performance validation. Material shifts in REACH enforcement intensity or MEE effluent mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Peptone Market
Additives
Europe Choline Chloride Market
Additives
United States Betaine Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Deodorant and Antiperspirant Ingredients Market
Additives
Additives for Floor Coatings Market
Additives
Nucleating and Clarifying Agents Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Global Glass Additives Market
Additives
Potassium Nitrate Market
Additives
Europe Fuel Additives Market
Additives
Ascorbyl Stearate Market
Additives
Rosin Ester Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Printing Ink Additives Market
Additives
Glycol Acetate Market