
 Calcium Stearate Market | 2026-2036
Calcium Stearate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Stearate Market Intelligence
Project finance for specialty chemical expansion is tilting competitive dynamics toward firms with balance-sheet capacity for integrated manufacturing. Baerlocher GmbH leverages backward integration into stearic acid feedstock to control input costs across European operations. Valtris Specialty Chemicals anchors North American supply through multi-site production infrastructure. FACI Corporate S.p.A. competes on pharmaceutical-grade certification depth, while Peter Greven GmbH & Co. KG differentiates via tailored particle-size distributions for PVC stabilizer applications.
Calcium stearate, the calcium salt of stearic acid with melting point typically between 150°C and 160°C, functions primarily as a lubricant, acid scavenger, and release agent across polymer processing and consumer formulations. Industrial-grade material dominates volume throughput due to PVC pipe and profile extrusion demand, while pharmaceutical-grade commands premium positioning through USP-NF compliance burdens and limited qualified supply bases. Food-grade calcium stearate sees structural growth from anti-caking applications in powdered seasonings and baking mixes, though regulatory scrutiny on direct food additives constrains expansion pace relative to industrial segments.
REACH registration requirements in Europe elevate compliance costs for importers and favor regional producers with established dossiers, while FDA 21 CFR 184.1229 governs food-grade specifications in the United States. China's GB standards and evolving MEE environmental enforcement reshape export-oriented manufacturing economics. India's BIS certification mandates for industrial chemicals create additional market access filtration. Stakeholders must monitor regulatory divergence between jurisdictions as formulation standards tighten and supply chain documentation requirements expand.
Market Dynamics
REACH dossier maintenance costs and FDA food-contact recertification cycles are compressing margins for non-integrated producers while rewarding manufacturers with captive stearic acid supply and multi-jurisdictional compliance infrastructure.
Growth Catalysts
- Construction sector PVC demand:Pipe and profile extrusion in residential and commercial building drives industrial-grade calcium stearate volume through lubricant and acid scavenger functions.
- REACH registration moats:Established European producers leverage completed substance dossiers to block import competition from unregistered Asian suppliers.
- Food-grade anti-caking applications:Powdered seasonings and baking mixes under FDA 21 CFR 184.1229 create structural demand for compliant food additive grades.
Market Restraints
- Stearic acid feedstock volatility:Palm oil and tallow price swings transmit directly to calcium stearate production economics without hedging mechanisms for mid-scale processors.
- Pharmaceutical-grade supply concentration:USP-NF qualified manufacturing capacity clusters among three European and North American producers, creating qualification bottlenecks for new entrants.
- Zinc stearate substitution in rubber:Compounding applications in tire manufacturing increasingly favor zinc stearate for activator performance, displacing calcium variants in specific formulations.
Strategic Opportunities
- India BIS certification gap:Domestic industrial chemical certification mandates create protected market access for local producers with BIS-marked product lines.
- Bioplastic processing lubrication:PLA and PHA extrusion requires novel lubricant packages where calcium stearate formulations are being validated for thermal stability.
- China MEE environmental enforcement:Stricter wastewater and emissions standards are forcing consolidation among small Jiangsu and Shandong producers, opening share for compliant operators.
Industry Challenges
- Multi-jurisdictional formulation drift:Diverging purity specifications between USP-NF, EP, and JP pharmacopeias force SKU proliferation and inventory complexity for pharmaceutical-grade suppliers.
- Legacy PVC compounding equipment retrofit:Older extrusion lines lack precision temperature control needed for next-generation stabilizer packages, slowing formulation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Stearate Market |
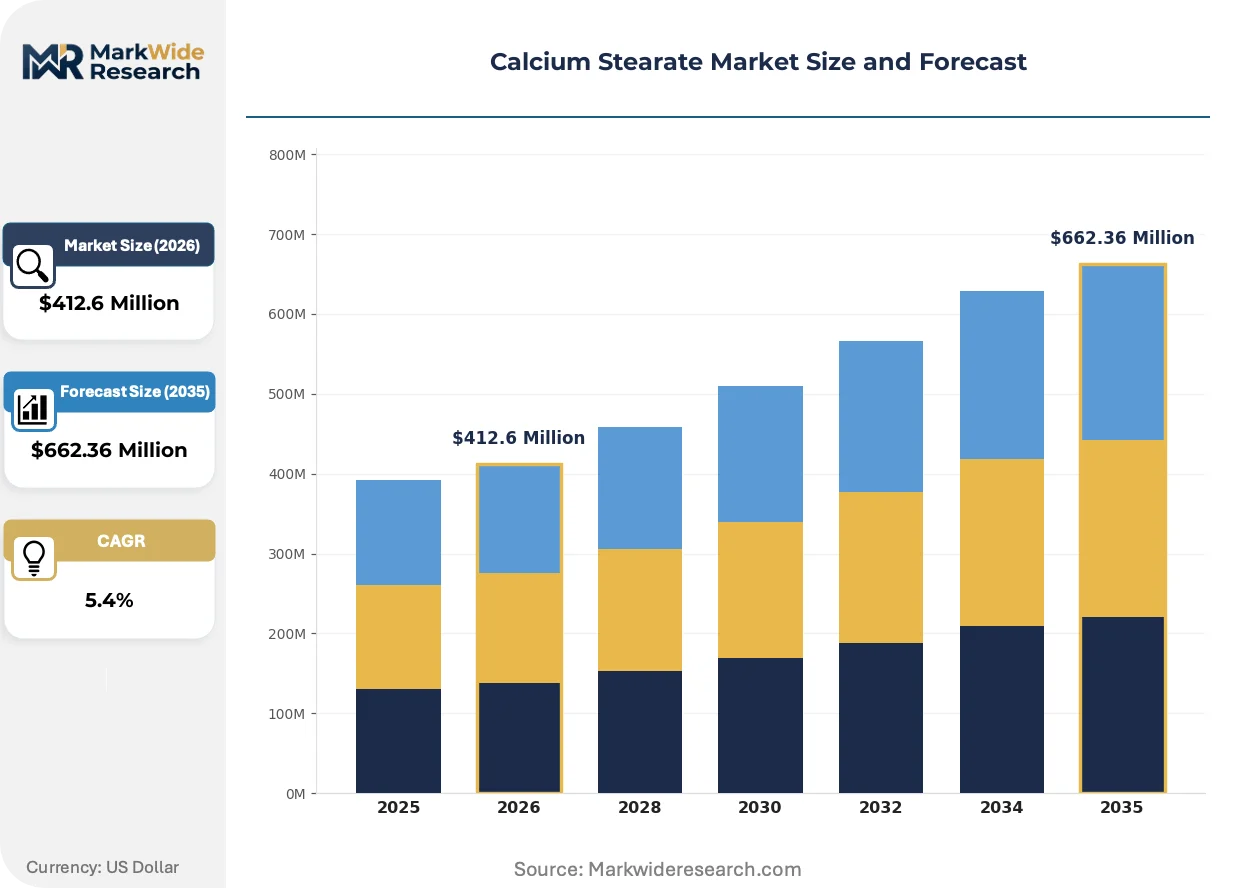
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $662.36 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Plastics, Personal Care, Food Preservation, Pharmaceuticals End User: Manufacturers, Distributors, Retailers, Service Providers Distribution Channel: Online, Offline, Wholesale, Direct Sales |
| Companies Covered | Baerlocher GmbH, Valtris Specialty Chemicals, FACI Corporate S.p.A., Peter Greven GmbH & Co. KG, Dover Chemical Corporation, PMC Biogenix, Inc., Norac Additives, Sun Ace Kakoh Pte. Ltd., FacI Asia Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Stearate Market Strategic Shifts & Innovations
Direct powder feeding systems and real-time rheology monitoring are compressing formulation development cycles while regulatory divergence between FDA, EFSA, and China's SAMR is fragmenting global product specifications.
Surface-modified calcium stearate with tailored particle size distributions below 10 microns enables reduced loading levels in high-fill PVC compounds without lubricant performance degradation. Pipe extruders in Germany and construction profile manufacturers in the US Gulf Coast are adopting these grades at 15-20% premium pricing. Traditional coarse-particle industrial grades are rendering obsolete for thin-wall applications where surface finish specifications have tightened.
China's evolving GB standards for food-contact additives under SAMR oversight are imposing heavy metal limits stricter than Codex Alimentarius baselines, forcing reformulation of export-oriented production. Domestic Chinese food-grade manufacturers are absorbing retesting and re-registration costs to maintain access to premium bakery and confectionery accounts. European importers are diverting sourcing to Indian BIS-certified suppliers as a compliance hedge against further GB tightening.
Specification-driven procurement contracts with embedded annual compliance audits are displacing spot-market purchasing for pharmaceutical and food-grade volumes. Large polymer compounders and multinational seasoning houses are consolidating supplier panels to three qualified sources with documented REACH and FDA master file access. This concentration is most visible in the US Northeast and Benelux chemical corridors where buyer consolidation has accelerated post-pandemic.
Calcium Stearate Market Segmentation
Calcium stearate's functional versatility across lubrication, acid scavenging, and release applications creates distinct specification tiers that command radically different compliance burdens and margin structures. Each segment category reflects a unique intersection of technical performance requirements and regulatory jurisdiction.
Product Type:
Industrial-grade formulations anchor mature volume throughput, while pharmaceutical and food-grade certifications represent emerging premium positioning with steep qualification barriers.
- Industrial Grade:Coarse-particle formulations with melting points between 150°C and 160°C dominate PVC pipe and profile extrusion. Construction sector demand in Germany and the US Gulf Coast drives bulk consumption through lubricant and acid scavenger functions in rigid vinyl compounds.
- Pharmaceutical Grade:USP-NF compliant material with controlled particle size below 10 microns and heavy metal limits stricter than industrial baselines. Manufacturing capacity concentrates among European and North American producers due to qualification bottlenecks and multi-jurisdictional pharmacopeia divergence between USP-NF, EP, and JP standards.
- Food Grade:Anti-caking agent under FDA 21 CFR 184.1229 for powdered seasonings and baking mixes. China's SAMR-imposed GB standards with heavy metal limits exceeding Codex baselines are forcing reformulation costs on export-oriented manufacturers.
- Cosmetic Grade:Purified stearic acid derivative for emulsion stabilization in skincare formulations. REACH registration requirements in Europe favor regional producers with established substance dossiers.
Industrial grade handles the majority of throughput; pharmaceutical grade is the fastest mover on share.
Application:
Volume concentration follows polymer processing intensity, with emerging bioplastic lubrication creating novel specification requirements.
- Plastics:PVC stabilizer packages consume the largest calcium stearate volumes across pipe, profile, and film extrusion. Surface-modified sub-10-micron grades enable reduced loading levels in high-fill compounds, commanding 15-20% premiums from German pipe extruders and US construction profile manufacturers.
- Food Preservation:Anti-caking functionality in powdered seasonings and baking mixes under FDA and FSSAI jurisdictions. Direct food additive scrutiny constrains expansion pace relative to industrial segments.
- Personal Care:Emulsifier and thickener in lotions and creams with cosmetic-grade purity requirements. European formulators leverage REACH-registered supply chains to ensure compliance documentation depth.
- Pharmaceuticals:Tablet lubricant and glidant with USP-NF, EP, and JP multi-pharmacopeia alignment burdens. Specification-driven procurement contracts with embedded annual compliance audits displace spot-market purchasing.
Plastics commands the dominant volume position; food preservation applications are climbing the fastest as clean-label anti-caking demand expands.
End User:
Procurement scale and technical integration depth separate the end-user landscape into specification-heavy direct buyers and logistics-focused intermediaries.
- Manufacturers:Polymer compounders, pharmaceutical tablet producers, and food processors with in-house formulation laboratories. Large multinational seasoning houses and PVC pipe extruders in the US Northeast and Benelux chemical corridors consolidate supplier panels to three qualified sources with documented REACH and FDA master file access.
- Distributors:Regional chemical distributors managing inventory complexity from multi-jurisdictional formulation drift. These intermediaries absorb SKU proliferation burdens for mid-scale processors lacking direct import capabilities.
- Retailers:Specialty chemical retailers serving small-batch cosmetic and food-grade buyers with packaged quantities. Limited to non-technical applications where specification documentation requirements remain minimal.
- Service Providers:Toll compounders and contract manufacturers integrating calcium stearate into customer-specified formulations. These operators prioritize supply security over price minimization due to penalty clauses in downstream contracts.
Manufacturers absorb the dominant procurement volume; service providers are gaining share fastest as outsourcing of compounding operations accelerates.
Distribution Channel:
Channel selection correlates directly with grade certification intensity and buyer technical sophistication.
- Direct Sales:Long-term supply agreements between producers and large polymer compounders or pharmaceutical manufacturers. Contracts embed annual compliance audits and documented REACH dossier access, eliminating spot-market price exposure.
- Wholesale:Bulk industrial-grade movement through chemical distribution hubs in Rotterdam, Houston, and Singapore. Volume discounts reflect pallet-scale purchasing with limited technical service attachment.
- Offline:Traditional distributor relationships with regional stocking points for construction sector PVC processors. Legacy extrusion equipment operators favor established supply relationships over channel experimentation.
- Online:E-procurement platforms for standardized industrial grades with published technical data sheets. Emerging channel for small-batch cosmetic and food-grade buyers seeking transparent pricing without distributor markups.
Direct sales captures the largest value flow; online channels are expanding most quickly as procurement digitization penetrates mid-scale chemical buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH dossier maintenance costs and China's MEE environmental enforcement are redrawing manufacturing footprints across major calcium stearate production zones. Producers with captive stearic acid supply and multi-jurisdictional compliance infrastructure capture expanding share as regulatory barriers intensify.
China
MEE wastewater and emissions standards are forcing consolidation among small Jiangsu and Shandong producers, opening market share for compliant operators with documented environmental permits. SAMR-imposed GB standards for food-contact additives impose heavy metal limits stricter than Codex Alimentarius baselines, forcing reformulation costs on export-oriented manufacturers. Yangtze River Delta chemical clusters around Shanghai and Nanjing concentrate the bulk of upgraded production capacity serving both domestic PVC processors and international pharmaceutical accounts.
Germany
Pipe and profile extruders in Bavaria and North Rhine-Westphalia drive industrial-grade volume through rigid vinyl compound demand in residential construction and infrastructure renewal. ECHA REACH registration requirements elevate compliance costs for importers and favor regional producers with established substance dossiers and backward-integrated stearic acid supply. The Cologne-Düsseldorf chemical corridor anchors European pharmaceutical-grade manufacturing, with USP-NF qualified capacity serving multinational tablet producers.
United States
Construction profile manufacturers along the US Gulf Coast and PVC compounders in the Northeast absorb the largest industrial-grade volumes through stabilizer package formulations. FDA 21 CFR 184.1229 governs food-grade specifications for anti-caking applications in powdered seasonings and baking mixes, with specification-driven procurement contracts displacing spot-market purchasing. Houston and Philadelphia chemical distribution hubs manage bulk inventory movement with embedded compliance documentation for downstream processors.
India
BIS certification mandates for industrial chemicals create protected market access for domestic producers with marked product lines serving construction sector PVC demand. FSSAI food-additive regulations parallel FDA frameworks while imposing additional heavy metal testing burdens on imported material. Gujarat and Maharashtra industrial clusters concentrate manufacturing capacity for both domestic consumption and export to Middle Eastern and African markets seeking compliance-hedged supply alternatives to Chinese sourcing.
Calcium Stearate Market Key Industry Players
Channel-controlling players compete with product-specialist players across three discernible tiers: integrated manufacturers with captive feedstock supply, regional compounders with formulation service capabilities, and import-dependent distributors managing inventory complexity. Consolidation favors producers with multi-site production infrastructure and documented REACH dossier access, while fragmentation persists among small-scale processors lacking environmental compliance certifications. Strategic archetypes include backward-integrated specialists, pharmaceutical-grade qualification holders, and regional distributors with BIS or FDA master file relationships. Capacity expansion in India and Southeast Asia accelerates as European producers defend position through compliance moats rather than price competition.
Within the integrated-manufacturer tier, Baerlocher GmbH and Valtris Specialty Chemicals exemplify archetypes of regional production anchoring and multi-site supply security. FACI Corporate S.p.A. occupies a position representing pharmaceutical-grade certification depth, while Peter Greven GmbH & Co. KG sits within the specialist segment focused on tailored particle-size distributions. These named entities serve as anchors for understanding how geographic origin and corporate structure correlate with competitive positioning, without ascribing specific strategic actions or market shares to individual firms.
| Leading Market Players |
|---|
| Baerlocher GmbH |
| Valtris Specialty Chemicals |
| FACI Corporate S.p.A. |
| Peter Greven GmbH & Co. KG |
| Dover Chemical Corporation |
| PMC Biogenix, Inc. |
| Norac Additives |
| Sun Ace Kakoh Pte. Ltd. |
| FacI Asia Pacific |
| Others |
Cost & Logistics Intelligence
Jiangsu and Shandong stearic acid refineries anchor upstream supply for Asian calcium stearate producers, concentrating margin capture among integrated operators with captive feedstock rather than toll-processors exposed to palm oil and tallow volatility. REACH dossier maintenance costs and FDA recertification cycles compound this dynamic, rewarding manufacturers with multi-jurisdictional compliance infrastructure while compressing returns for import-dependent distributors.
Pricing Analysis
Certification level creates the primary spread across calcium stearate tiers, with USP-NF pharmaceutical grades commanding substantial premiums over industrial formulations for PVC stabilization. Three-tier pricing structure across premium, standard, and economy levels reflects particle size distribution and heavy metal compliance burdens rather than commodity spot dynamics. Cost compression in food-grade segments is intensifying because SAMR-imposed GB standards in China force retesting expenditures on export-oriented manufacturers. Mid-scale polymer compounders exhibit the highest price sensitivity, while pharmaceutical tablet producers prioritize supply security and documented master file access over unit cost minimization.
Supply Chain Analysis
Export-control scrutiny on stearic acid feedstock derivatives has intensified documentation requirements for cross-border chemical shipments, though calcium stearate itself faces fewer direct restrictions than specialty metal soaps. Manufacturing concentrates in China, Germany, and India, with Yangtze River Delta clusters and Gujarat chemical corridors serving as primary export hubs. Production draws from palm oil and tallow derivatives, with hydrogenated vegetable oil alternatives gaining share amid sustainability pressures. Single-source vulnerability runs through Jiangsu wastewater treatment capacity, where MEE enforcement has shuttered smaller producers. Distribution runs through Rotterdam, Houston, and Singapore chemical hubs for bulk industrial grades, while pharmaceutical and food volumes move through direct sales channels with embedded compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium stearate procurement is consolidating around specification-driven platforms where REACH dossier access and FDA master file documentation function as interoperability credentials, favoring producers with integrated compliance infrastructure over spot-market traders.
For Market Incumbents: Build regulatory dossier moats by deepening backward integration into stearic acid feedstock and securing multi-pharmacopeia alignment across USP-NF, EP, and JP standards. Capacity expansion in India leverages BIS certification requirements to capture protected domestic demand. Zinc stearate substitution in tire compounding threatens calcium variant share in rubber applications, requiring formulation service capabilities to defend position. For New Entrants and Emerging Players: Establish a beachhead in bioplastic lubrication for PLA and PHA extrusion, where calcium stearate validation for thermal stability remains incomplete and qualification windows are open. India's industrial chemical sector offers the most penetrable geography due to BIS mandates screening unmarked imports. A toll-compounding partnership model with PVC pipe extruders in the US Gulf Coast provides go-to-market traction without immediate multi-site infrastructure investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European specialty chemical platforms that consolidated during REACH implementation and now face succession planning. The five-to-ten year viability thesis rests on regulatory compliance infrastructure becoming scarcer rather than capacity abundance. Watch for MEE enforcement waves in China as the inflection signal—accelerated small-producer consolidation there would validate premium pricing for compliant operators with documented environmental permits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stearic Acid Feedstock | Baerlocher GmbH's captive supply controls input costs across European REACH-registered operations. |
| Multi-Pharmacopeia Certification Investment | FACI Corporate S.p.A. aligns USP-NF, EP, and JP standards to serve multinational pharmaceutical tablet producers. |
| India BIS Certification Acquisition | Domestic marking requirements create protected market access for construction sector PVC stabilizer demand. |
| Bioplastic Lubricant Formulation Development | PLA and PHA extrusion validation opens specification windows before incumbent lock-in solidifies. |
| Long-term Supply Agreement with Seasoning Houses | Multinational food processors consolidate supplier panels to three qualified sources with embedded compliance audits. |
Research Approach
A standing panel of plant managers at PVC compounding facilities, procurement leads at polymer processors, distribution channel partners in Rotterdam and Singapore, and technical R&D directors at stearic acid refineries provided ongoing calibration against trade data and SEC filings. Primary interviews with construction profile manufacturers and pharmaceutical tablet producers combined with customs records, Cefic chemical industry reports, and FDA master file databases. Bottom-up volume estimates from grade-specific consumption patterns triangulated against top-down production capacity assessments across Yangtze River Delta and Gujarat chemical clusters.
Scenario bracketing around REACH dossier renewal timelines, MEE enforcement intensity, and palm oil price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include grade tier (industrial, pharmaceutical, food, cosmetic), end-use industry (plastics, food preservation, pharmaceuticals, personal care), packaging format (bulk, bags, drums), and regional production hub (China, Germany, India, United States). CAGRs derived from elasticity-adjusted demand curves incorporating PVC construction cycle correlation and pharmaceutical outsourcing rates.
Macroeconomic conditions sit as an overlay; deviation in residential construction spending, palm oil futures curves, or currency volatility in key manufacturing zones would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement continuity and feedstock price correlation patterns. Material shifts in SAMR food-contact standards or ECHA substance evaluation priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Anti-Block Additives Market
Additives
Isopropyl Acetate Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Defoaming Coating Additives Market
Additives
Dipotassium Guanylate Market
Additives
Alkyl Acetates Market
Additives
Friction Modifier Additives Market
Additives
Asia Pacific Plastic Additives Market
Additives
Glycol Acetate Market
Additives
Anti-Pollution Ingredients Market
Additives
Pearlizers Market
Additives
Propyl Gallate Market
Additives
Encapsulated Citric Acid Market
Additives
Europe Anti-Caking Market
Additives
Biosaccharide Gum Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market