
 Green Polymer Additive Market | 2026-2036
Green Polymer Additive Market Size, Share, and Industry Trends Forecast 2026-2036
Green Polymer Additive Market Intelligence
Polymer chemist talent is rotating from conventional petrochemical additive labs toward bio-based formulation teams, constraining legacy product pipelines while unlocking plant-derived stabilizer development. BASF SE leverages its Ludwigshafen research complex to sustain vertical integration across epoxidized soybean oil supply chains. Lanxess anchors European demand through specialized phosphorus-based flame retardants that meet automotive OEM specifications. Evonik Industries AG competes via amino acid-derived processing aids that reduce melt viscosity in recycled polyolefin streams.
Green polymer additives comprise bio-derived stabilizers, plasticizers, and fillers that replace petroleum-based counterparts in thermoplastic and thermoset matrices, typically incorporating vegetable oils, lignin, or cellulose derivatives at loadings between five and thirty weight percent to maintain mechanical performance while reducing fossil carbon content. Bio-based additives dominate current revenue pools due to established supply chains for epoxidized oils and citrate esters, though recycled fillers are gaining fastest as post-industrial polymer waste streams achieve food-contact purity grades. Natural fibers occupy niche positions in automotive interior panels where weight reduction and acoustic damping converge, while degradable polymers remain formulation-constrained by hydrolysis rate control in humid climates.
REACH authorization lists and EU Green Deal carbon-border adjustment mechanisms are tightening market access for conventional phthalate plasticizers, compelling reformulation toward bio-based alternatives certified under ECHA sustainability criteria. FDA food-contact notifications and EPA Safer Choice labeling extend compliance burdens for suppliers targeting dual-export markets, with ISO 17088 biodegradability testing becoming a de facto qualification threshold. Stakeholders must monitor pending amendments to EU Packaging and Packaging Waste Regulation that would mandate minimum recycled and renewable content thresholds across flexible film applications.
Market Dynamics
REACH authorization lists and EU Green Deal carbon-border mechanisms are forcing rapid reformulation away from phthalate plasticizers toward bio-derived alternatives, compressing legacy supply chains while opening procurement corridors for epoxidized vegetable oils and citrate esters.
Growth Catalysts
- Automotive OEM renewable mandates:German and Italian automakers specify minimum bio-based content thresholds for interior panels and wiring insulation, pulling demand toward epoxidized soybean oil stabilizers.
- REACH phthalate restrictions:ECHA authorization requirements block conventional plasticizers from food-contact and childcare applications, redirecting formulation R&D toward plant-derived substitutes certified under sustainability criteria.
- Post-industrial waste valorization:Bavarian and northern Italian compounding facilities achieve food-contact purity grades for recycled polymer fillers, unlocking circular material loops in flexible packaging films.
Market Restraints
- Epoxidized oil supply concentration:Soybean and linseed oil feedstock supply clusters in North American and South American agricultural belts, exposing European formulators to currency and crop-yield volatility.
- Performance-compromise thresholds:Bio-based plasticizers exhibit inferior low-temperature flexibility versus phthalate benchmarks, constraining adoption in automotive underhood applications where cold-crack resistance is specified.
- F-Gas Regulation phase-down friction:EU restrictions on fluorinated blowing agents create formulation gaps in rigid foam insulation, delaying thermal-performance parity for bio-based alternatives.
Strategic Opportunities
- Phosphorus-based flame retardant expansion:Lanxess specialty additives meet automotive OEM specifications for polyamide electrical housings, opening penetration into electric vehicle battery module enclosures.
- Amino acid-derived processing aids:Evonik Industries AG compounds reduce melt viscosity in recycled polyolefin streams, enabling higher loadings of post-consumer content without extrusion throughput penalties.
- EU Packaging and Packaging Waste Regulation amendments:Pending mandatory recycled and renewable content thresholds across flexible film applications will compel converter procurement shifts toward certified bio-additive supply chains.
Industry Challenges
- Polymer chemist talent rotation:Formulation expertise is migrating from petrochemical additive laboratories toward bio-based development teams, creating capability scarcity in legacy product pipeline maintenance.
- ISO 17088 biodegradability testing bottlenecks:Qualification timeline compression for food-contact notifications creates certification backlogs, delaying market entry for novel plant-derived stabilizer candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Polymer Additive Market |
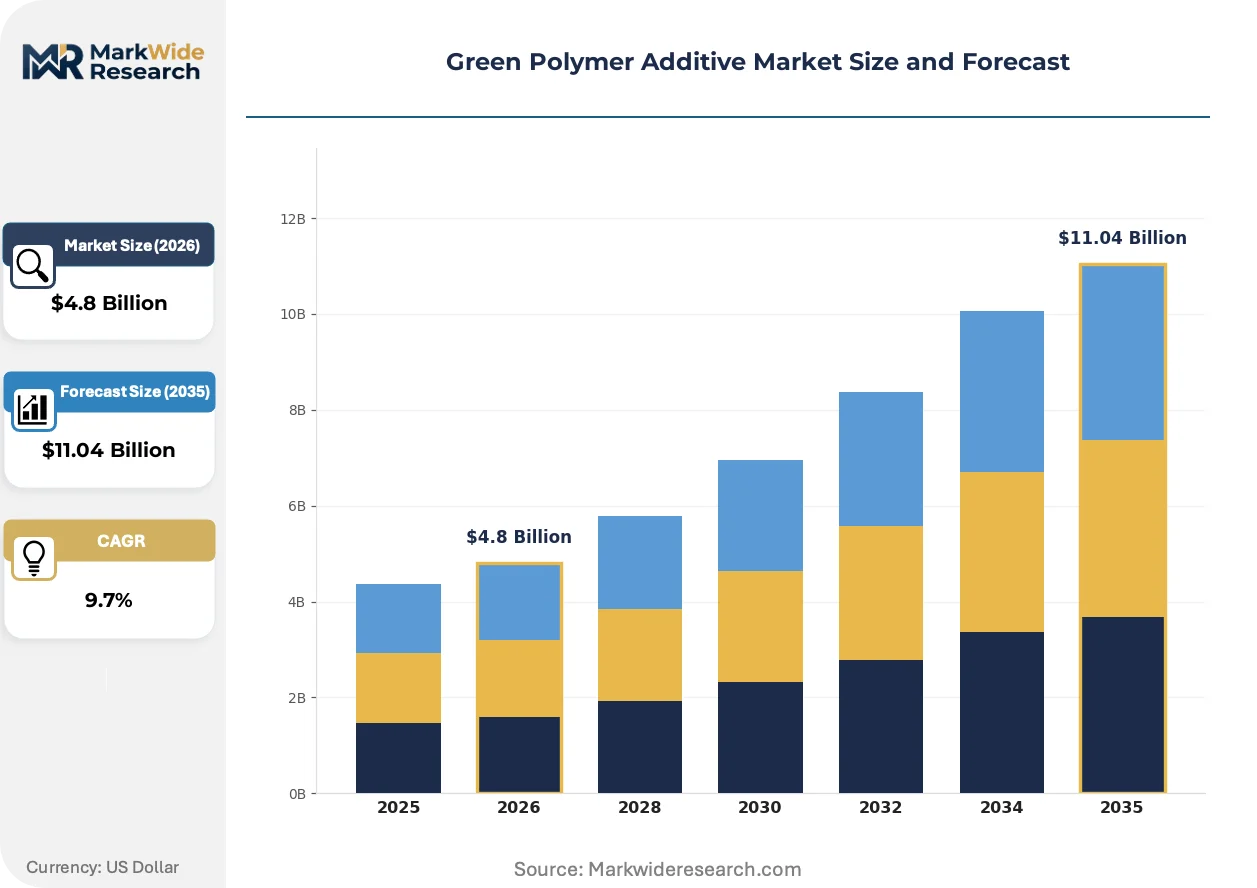
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-based Additives, Recycled Fillers, Degradable Polymers, Natural Fibers Application: Packaging, Agriculture, Coatings, Automotive Components End User: Manufacturers, Retailers, Distributors, Research Institutions Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Industrial Suppliers |
| Companies Covered | Lanxess, DuPont de Nemours, Inc., BASF SE, Emery Oleochemicals, Clariant AG, Dow, AkzoNobel NV, Arkema Inc, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Polymer Additive Market Strategic Shifts & Innovations
Formulation chemistry is pivoting from petroleum-derived stabilizers toward plant-based molecular architectures, with enzymatic modification and reactive extrusion emerging as core process innovations. This shift is compressing traditional additive supply hierarchies while opening new intellectual property terrain.
Epoxidized soybean oil is decomposing the conventional plasticizer market structure by offering equivalent thermal stability at renewable carbon loadings above fifteen weight percent. Packaging converters in Germany and France are scaling procurement volumes to meet EU Green Deal compliance deadlines. The technology is decomposing legacy phthalate supply relationships as REACH authorization lists tighten market access for petroleum-derived alternatives.
ECHA sustainability criteria and FDA food-contact notification requirements are tightening in parallel, compelling dual-certification strategies for suppliers targeting transatlantic markets. Formulators must now document bio-based carbon content through radiocarbon testing while maintaining mechanical performance parity. Automotive interior specifications in Bavarian manufacturing clusters are most affected, with OEMs demanding chain-of-custody documentation from additive suppliers.
Buyer concentration among European packaging converters is compressing supplier negotiation leverage, with tier-one compounders consolidating procurement decisions at the cluster level. Long-term offtake agreements for epoxidized oils are displacing spot-market purchasing in northern Italian facilities. This pattern is most visible across flexible film applications where compliance-driven specification changes are accelerating contract renegotiation cycles.
Green Polymer Additive Market Segmentation
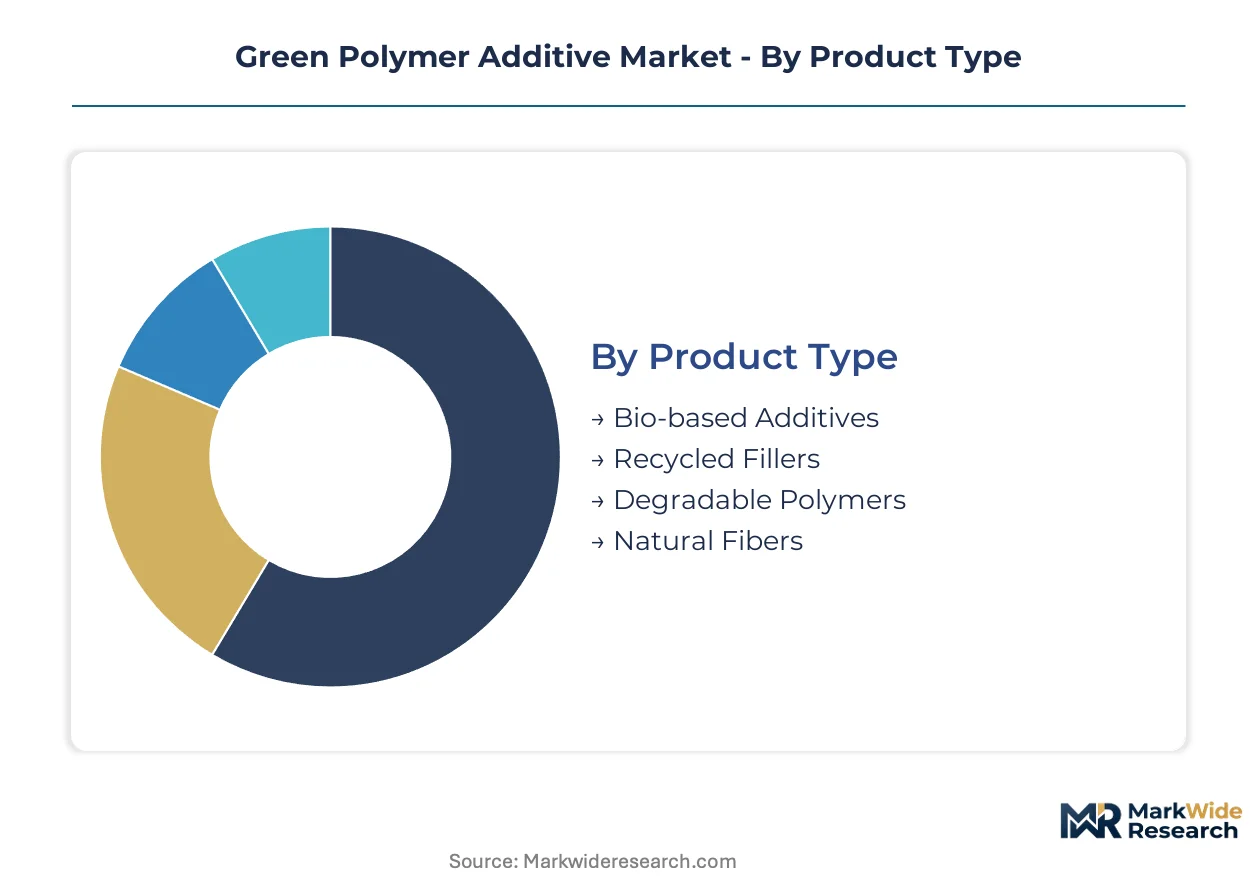
Segmentation in the Green Polymer Additive Market reveals how regulatory pressure and supply chain configuration reshape procurement patterns. Each dimension exposes different fault lines between established petroleum-derived formulations and emerging bio-based alternatives.
Product Type:
Channel-mix dynamics vary sharply across product categories, with bio-based additives flowing predominantly through direct sales to compounders while recycled fillers move via industrial supplier networks.
- Bio-based Additives:These incorporate epoxidized vegetable oils, citrate esters, and plant-derived stabilizers at loadings between five and thirty weight percent. German packaging converters in Bavarian chemical clusters are scaling procurement volumes to meet EU Green Deal compliance deadlines, with REACH authorization lists blocking conventional phthalate alternatives.
- Recycled Fillers:Post-industrial polymer waste streams achieve food-contact purity grades through advanced sorting and purification. Northern Italian compounding facilities are unlocking circular material loops in flexible packaging films, though supply concentration in North American agricultural belts exposes European formulators to currency volatility.
- Degradable Polymers:Formulation-constrained by hydrolysis rate control in humid climates, limiting deployment to controlled-environment applications.
- Natural Fibers:Niche positioning in automotive interior panels where weight reduction and acoustic damping converge.
By volume, bio-based additives lead. By growth pace, recycled fillers are expanding most quickly.
Application:
Cost tier stratification separates premium automotive specifications from commodity packaging grades, with coating applications occupying a mid-tier technical position.
- Packaging:Flexible film converters in Germany and France face pending EU Packaging and Packaging Waste Regulation amendments mandating minimum recycled and renewable content thresholds. ECHA sustainability criteria and FDA food-contact notification requirements compel dual-certification strategies for transatlantic suppliers.
- Automotive Components:German and Italian OEMs specify minimum bio-based content thresholds for interior panels and wiring insulation, pulling demand toward epoxidized soybean oil stabilizers with chain-of-custody documentation requirements.
- Agriculture:Mulch films and controlled-release matrices favor degradable polymer formulations where soil contact duration is predictable.
- Coatings:Architectural and industrial protective layers incorporate bio-based plasticizers for VOC reduction, constrained by outdoor durability specifications.
Packaging commands the largest volume share. Automotive applications are gaining share fastest as OEM renewable mandates tighten.
End User:
Customer-type concentration concentrates negotiation leverage among tier-one compounders, with research institutions serving as technology gatekeepers for qualification protocols.
- Manufacturers:Tier-one compounders in Bavarian and northern Italian facilities consolidate procurement decisions at the cluster level, displacing spot-market purchasing with long-term offtake agreements for epoxidized oils.
- Distributors:Industrial suppliers manage inventory and technical support for mid-tier converters lacking in-house formulation expertise.
- Retailers:Limited direct engagement, primarily private-label packaging specification influence.
- Research Institutions:ISO 17088 biodegradability testing and radiocarbon verification protocols create certification bottlenecks for novel plant-derived stabilizer candidates.
Manufacturers absorb the highest volume. Research institutions are expanding most rapidly as qualification requirements proliferate.
Distribution Channel:
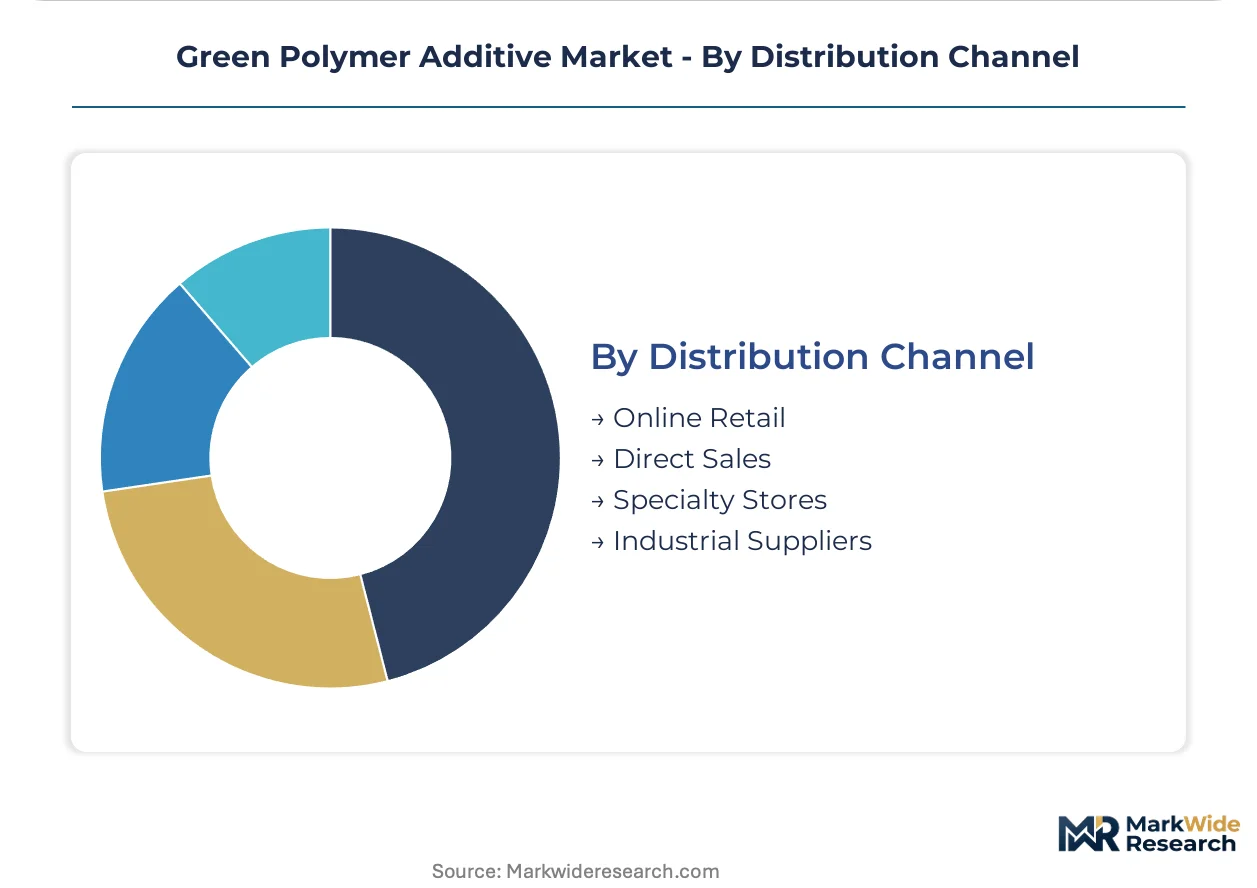
Supply concentration shapes channel selection, with direct sales dominating high-volume bio-additive contracts while specialty stores serve fragmented coating formulators.
- Direct Sales:Long-term offtake agreements for epoxidized soybean oil and citrate esters predominate, with BASF SE leveraging Ludwigshafen research complex integration to sustain captive supply relationships.
- Industrial Suppliers:Recycled filler distribution networks achieve food-contact purity grades through certified post-industrial waste streams.
- Online Retail:Limited to small-volume specialty additives and technical documentation access.
- Specialty Stores:Regional coating and adhesive formulators source bio-based plasticizers for VOC-compliant architectural applications.
Direct sales channels move the highest volumes. Industrial suppliers are climbing the fastest as circular material loops mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German packaging converters consume epoxidized soybean oil stabilizers at loadings above fifteen weight percent, while Italian automotive compounders prioritize chain-of-custody documentation for interior panel specifications. This consumption-mix differential separates compliance-driven flexible film demand from OEM-mandated renewable content verification.
Germany
Bavarian chemical clusters anchor European bio-based plasticizer procurement as converters scale volumes to meet EU Green Deal compliance deadlines. REACH authorization lists block conventional phthalate alternatives from food-contact applications, redirecting formulation R&D toward plant-derived substitutes. Ludwigshafen research complexes sustain captive supply relationships for epoxidized oils through backward integration into agricultural feedstock networks.
France
Packaging converters in northern French industrial zones face pending EU Packaging and Packaging Waste Regulation amendments mandating minimum recycled and renewable content thresholds. ECHA sustainability criteria tighten market access for petroleum-derived additives, compelling dual-certification strategies alongside FDA food-contact notifications. Parisian regulatory pressure accelerates contract renegotiation cycles for flexible film suppliers.
Italy
Northern Italian compounding facilities unlock circular material loops in flexible packaging films through post-industrial waste valorization achieving food-contact purity grades. Automotive OEMs in Turin and Milan specify minimum bio-based content thresholds for interior panels and wiring insulation. Long-term offtake agreements for epoxidized oils displace spot-market purchasing across tier-one compounder clusters.
United States
Midwest agricultural belts concentrate soybean and linseed oil feedstock supply, exposing European formulators to currency and crop-yield volatility. EPA Safer Choice labeling extends compliance burdens for suppliers targeting dual-export markets alongside FDA food-contact notifications. Chicago-area distribution hubs manage inventory for mid-tier converters lacking in-house formulation expertise.
China
Yangtze River Delta chemical processors expand epoxidized vegetable oil capacity to serve export-oriented packaging manufacturers. Dual carbon goals and GB standards accelerate domestic substitution of petroleum-derived plasticizers in flexible film applications. Shanghai-based compounders negotiate procurement corridors with North American agricultural suppliers to secure feedstock price stability.
Green Polymer Additive Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with consolidated research complexes commanding captive supply relationships while mid-scale compounders compete on certification agility. The structure rewards backward integration into agricultural feedstock networks and punishes spot-market dependency during currency volatility. Three archetypes dominate: diversified chemical conglomerates with vertical research integration, specialty additive houses focused on phosphorus-based flame retardants, and oleochemical processors leveraging proximity to oilseed crushing infrastructure. Competitive moves concentrate on long-term offtake agreements for epoxidized oils and dual-certification capacity for transatlantic regulatory compliance.
Within the integrated chemical tier, BASF SE anchors European supply through Ludwigshafen-based research and production coordination. Lanxess occupies a position exemplifying specialty additive concentration, with phosphorus-based flame retardants serving automotive electrical housing specifications. Evonik Industries AG represents the processing aid specialization vector, with amino acid-derived compounds reducing melt viscosity in recycled polyolefin streams. These three entities illustrate how competitive positioning diverges between feedstock-integrated, performance-specialized, and recycling-enabling strategic paths.
| Leading Market Players |
|---|
| Lanxess |
| DuPont de Nemours, Inc. |
| BASF SE |
| Emery Oleochemicals |
| Clariant AG |
| Dow |
| AkzoNobel NV |
| Arkema Inc |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for epoxidized soybean oil lock in supply access and price visibility for Bavarian packaging converters facing EU Green Deal compliance deadlines. These contracts insulate compounders from currency volatility in North American agricultural belts while exposing spot-market buyers to margin compression.
Pricing Analysis
Contract-based long-term offtake dominates pricing structure, with three-tier pricing stratification across food-contact certified, automotive-grade, and industrial-standard product levels. Price differentiation hinges on ECHA sustainability certification tier and volume scale, with bulk compounders commanding 15-20% discounts. Cost compression in industrial-grade tiers is intensifying because recycled filler supply expansion outpaces specification-grade demand. Small coating formulators exhibit highest price sensitivity due to fragmented order volumes and limited backward integration.
Supply Chain Analysis
Inventory lead times for epoxidized vegetable oils stretch 8-12 weeks due to agricultural harvest cycles and transoceanic logistics. Supply concentrates in United States, Brazil, and Argentina for soybean and linseed oil feedstocks, with European formulators exposed to currency volatility. Raw material dependencies center on oilseed crushing capacity, epoxidation reactor availability, and food-contact purification infrastructure. Single-source vulnerability in phosphorus-based flame retardant precursors creates formulation risk. Distribution runs through direct sales to tier-one compounders and industrial supplier networks for mid-tier converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one compounders in Bavarian and northern Italian clusters, consolidating procurement decisions and compressing supplier negotiation leverage across flexible film applications.
For Market Incumbents: Secure backward integration into oilseed crushing infrastructure or captive epoxidation capacity to defend margin position against feedstock volatility. Lock in ECHA dual-certification capacity for transatlantic regulatory compliance before pending EU Packaging and Packaging Waste Regulation amendments tighten qualification thresholds. Prioritize long-term offtake contract renewals with automotive OEMs specifying chain-of-custody documentation. For New Entrants and Emerging Players: Lead with amino acid-derived processing aids for recycled polyolefin applications where Evonik's patent position remains penetrable. Target northern Italian compounding facilities seeking alternatives to established supplier relationships. Pursue white-space in degradable polymer stabilizers for controlled-environment agriculture where hydrolysis rate control expertise creates differentiation. For Investors and Strategic Acquirers: Capital is best deployed toward specialty additive houses with phosphorus-based flame retardant portfolios and automotive OEM qualification relationships. Five-to-ten year viability favors compounders achieving food-contact purity grades for post-industrial waste streams. Watch for ISO 17088 certification backlog resolution as inflection signal for novel plant-derived stabilizer market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Supply | BASF's Ludwigshafen complex demonstrates captive supply security against Argentine crop-yield volatility. |
| ECHA-FDA Dual Certification Investment | Dual-certification capacity unlocks transatlantic procurement corridors for German packaging converters. |
| Post-Industrial Waste Valorization Scale-Up | Northern Italian facilities achieving food-contact purity grades establish circular material loop leadership. |
| Phosphorus-Based Flame Retardant Expansion | Lanxess specialty additives penetrate electric vehicle battery module enclosures beyond polyamide housings. |
| Amino Acid-Derived Processing Aid Development | Evonik's compounds enable higher post-consumer content loadings without extrusion throughput penalties. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across polymer chemists at bio-based formulation labs, procurement leads at Bavarian packaging converters, technical R&D directors at automotive OEMs, and plant managers at epoxidation facilities. Secondary validation drew from ECHA authorization lists, FDA food-contact notification databases, EU Green Deal policy documents, and SEC filings of listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Across the projection horizon, forecasts segmented by product type, application end-use, and geographic production hub were constructed. CAGRs derived from regression analysis of historical procurement volume trends and regulatory-driven specification shift timelines. Industry-specific inputs included automotive OEM renewable content mandate trajectories and REACH authorization list expansion schedules.
Forecasts assume regulatory continuity in EU Green Deal implementation and ECHA authorization processes; material policy shifts would require re-modeling. Crop-yield volatility in North American agricultural belts and currency fluctuation exposure represent primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
China Sodium Reduction Ingredient Market
Additives
North America Citric Acid Market
Additives
Ethoxyquin Market
Additives
Surface Modifiers Market
Additives
Nucleating Agents Market
Additives
Global Rheology Modifiers Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Global Glass Additives Market
Additives
Automotive Coolant Additives Market
Additives
Plastic Fillers Market
Additives
Global Polyurethane Additives Market
Additives
Deodorant and Antiperspirant Ingredients Market
Additives
Global Sizing Agents Market
Additives
Refining Additives Market
Additives
Allura Red AC Market
Additives
Europe Feed Additives Market