
 Conditioning Agent Market | 2026-2036
Conditioning Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Conditioning Agent Market Analysis
Modular formulation kits that pair conditioning actives with preservative-free delivery systems are recalibrating how cosmetics manufacturers evaluate ingredient suppliers. BASF SE leverages its integrated silicone portfolio to anchor long-term contracts with multinational hair care brands. Croda International Plc differentiates through biotechnology-derived conditioning polymers that meet clean-label requirements in European formulations. Evonik Industries AG specializes in amino acid-based quaternary compounds that command premium positioning in K-beauty supply chains.
Conditioning agents are surface-active or film-forming compounds, typically cationic surfactants, fatty alcohols, or silicone derivatives with molecular weights between 200 and 20,000 Daltons, designed to deposit on keratinous or cellulosic substrates to reduce friction and improve tactile properties. Silicone variants dominate current volume due to their instantaneous detangling performance, though fatty acid ester segments are gaining formulation share as brands reformulate to satisfy EU Green Deal biodegradability mandates. Emulsion formats capture the largest value pool because they accommodate high active loading while maintaining shelf stability for personal care applications.
REACH registration requirements and the EU F-Gas Regulation constrain silicone fluid sourcing for European conditioning agent producers, while China's GB standards for cosmetic raw materials impose additional safety documentation burdens on imports. FDA cosmetic ingredient oversight in the United States is intensifying post-MoCRA implementation, requiring brands to substantiate safety substantiation for leave-on conditioning products. Stakeholders must monitor how divergent biodegradability certifications across ECHA, EPA, and MEE jurisdictions reshape raw material qualification timelines and regional sourcing strategies.
Market Dynamics
REACH registration requirements and the EU F-Gas Regulation are compressing silicone fluid availability for European conditioning agent manufacturers, forcing accelerated reformulation cycles across cationic surfactant supply chains.
Growth Catalysts
- Biodegradability mandates:The EU Green Deal's tightening thresholds for aquatic toxicity are pulling fatty acid ester conditioning polymers into mainstream hair care formulations previously dominated by silicone derivatives.
- China's domestic brand expansion:Premium hair treatment lines from Chinese personal care manufacturers are concentrating procurement volumes for amino acid-based quaternary compounds.
- Modular formulation kits:Bundled conditioning actives with preservative-free delivery systems are simplifying supplier qualification for mid-tier cosmetics manufacturers.
Market Restraints
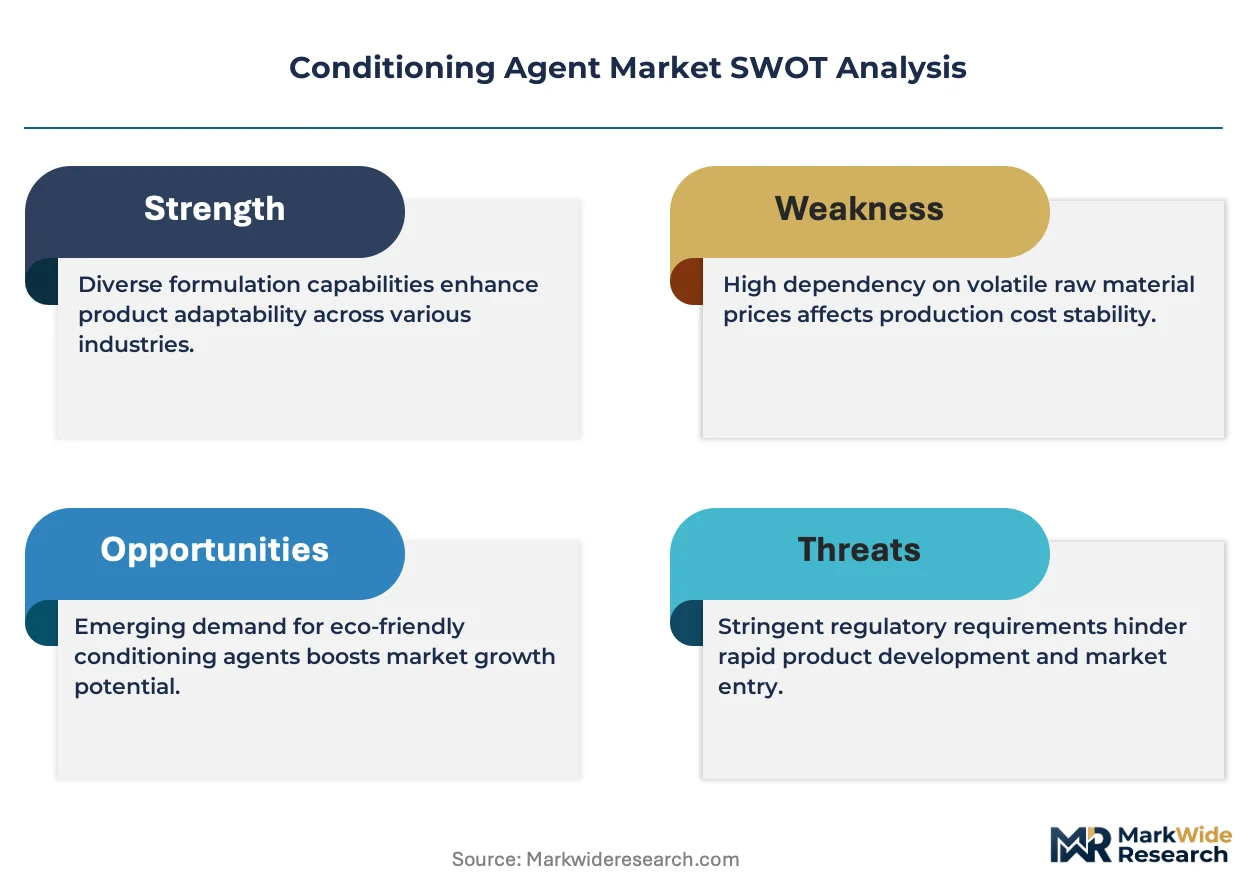
- Silicone feedstock volatility:D4 and D5 cyclic siloxane supply disruptions from German chemical clusters are elevating input cost uncertainty for European producers.
- Regulatory documentation burdens:China's GB standards for cosmetic raw materials impose extended safety substantiation timelines on imported conditioning agents.
- Technical performance gaps:Plant-derived conditioning polymers still exhibit inferior wet-combability scores versus silicone benchmarks in salon-professional blind testing.
Strategic Opportunities
- Scalp microbiome positioning:Conditioning actives paired with prebiotic claims are opening premium pricing tiers in K-beauty export markets.
- Biotechnology convergence:Fermentation-derived cationic polymers are enabling clean-label certification for European natural cosmetics brands.
- Direct-to-manufacturer platforms:Digital procurement channels are disintermediating regional distributors for mid-volume cosmetics formulators in Southeast Asia.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in silicone-polymer compatibility testing is concentrating among legacy German and Japanese technical service teams.
- Legacy equipment retrofit costs:Cold-process emulsion systems require capital outlays that strain mid-tier contract manufacturers transitioning from silicone-dependent workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conditioning Agent Market |
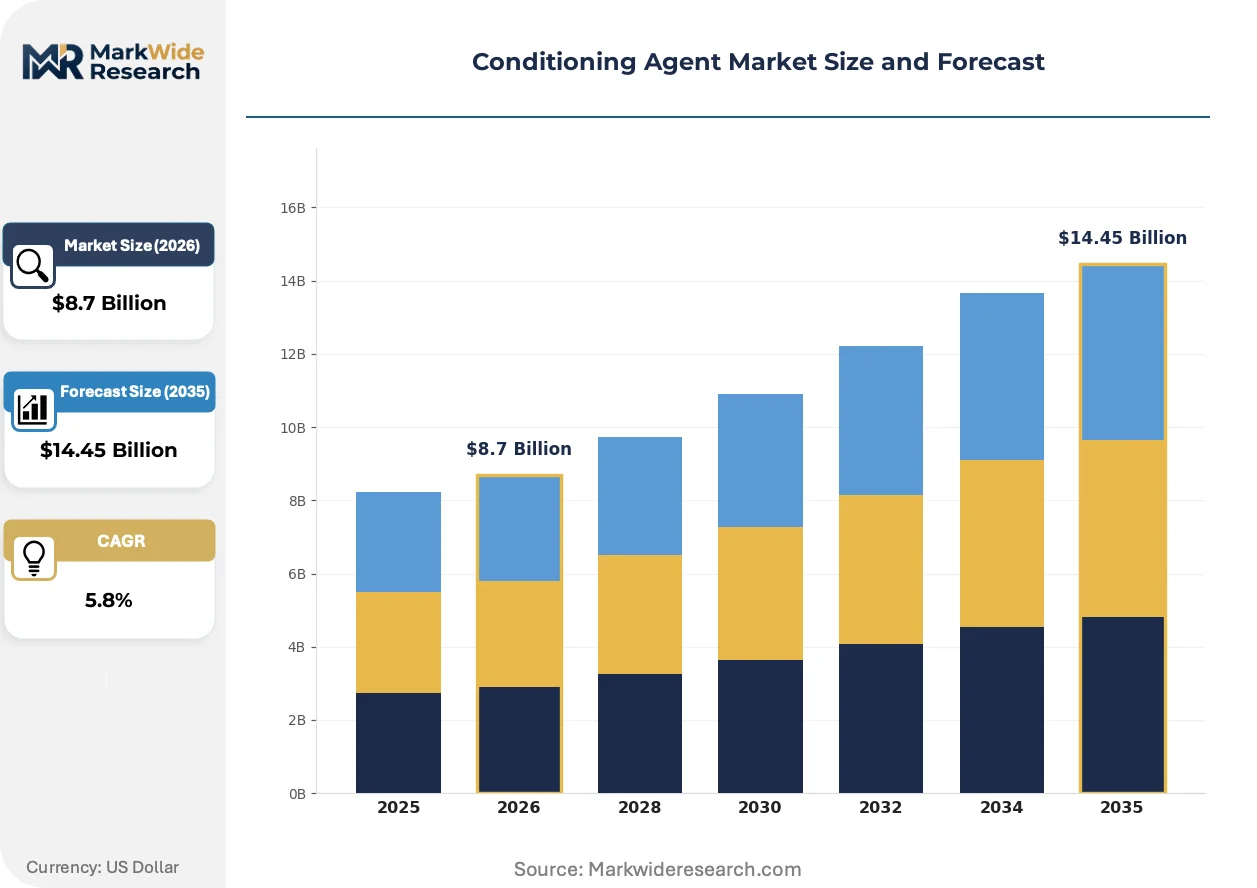
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Glycerin, Starch, Fatty Acid Ester Formulation: Liquid, Powder, Emulsion, Gel Application: Personal Care, Household Cleaning, Textile Treatment, Food Processing End User: Cosmetics Manufacturers, Food Industry, Textile Producers, Detergent Companies |
| Companies Covered | BASF SE, Dow Inc., Evonik Industries AG, Croda International Plc, Solvay S.A., Procter & Gamble Co., Henkel AG & Co. KGaA, L'Oréal S.A., Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conditioning Agent Market Emerging Trajectories
Biotechnology-derived actives and modular formulation architectures are fragmenting traditional supplier relationships in conditioning agent procurement. Manufacturers now prioritize technical service depth over commodity volume contracts.
Biotechnology platforms utilizing microbial fermentation for cationic polymer production are decentralizing raw material sourcing away from petrochemical feedstock dependence. Korean and Chinese cosmetics manufacturers are adopting these bio-derived actives at accelerated qualification cycles. This shift is decentralizing supply chain control from integrated silicone producers toward specialized fermentation houses with regional production footprints.
The EU F-Gas Regulation's phase-down schedules for fluorinated greenhouse gases are constraining volatile methylsiloxane availability for European conditioning agent formulators. Manufacturers are reformulating hair care lines toward biodegradable fatty alcohol quaternaries to preempt compliance gaps. German and French brands are absorbing higher raw material costs to maintain market access under REACH registration deadlines.
Ingredient sourcing decisions now hinge on biodegradability certification rather than performance metrics alone. Cosmetics manufacturers are unbundling technical service contracts from bulk supply agreements to access specialized formulation support. This pattern is most pronounced among mid-tier personal care brands in Italy and Spain seeking Ecolabel compliance for export positioning.
Conditioning Agent Market Segmentation
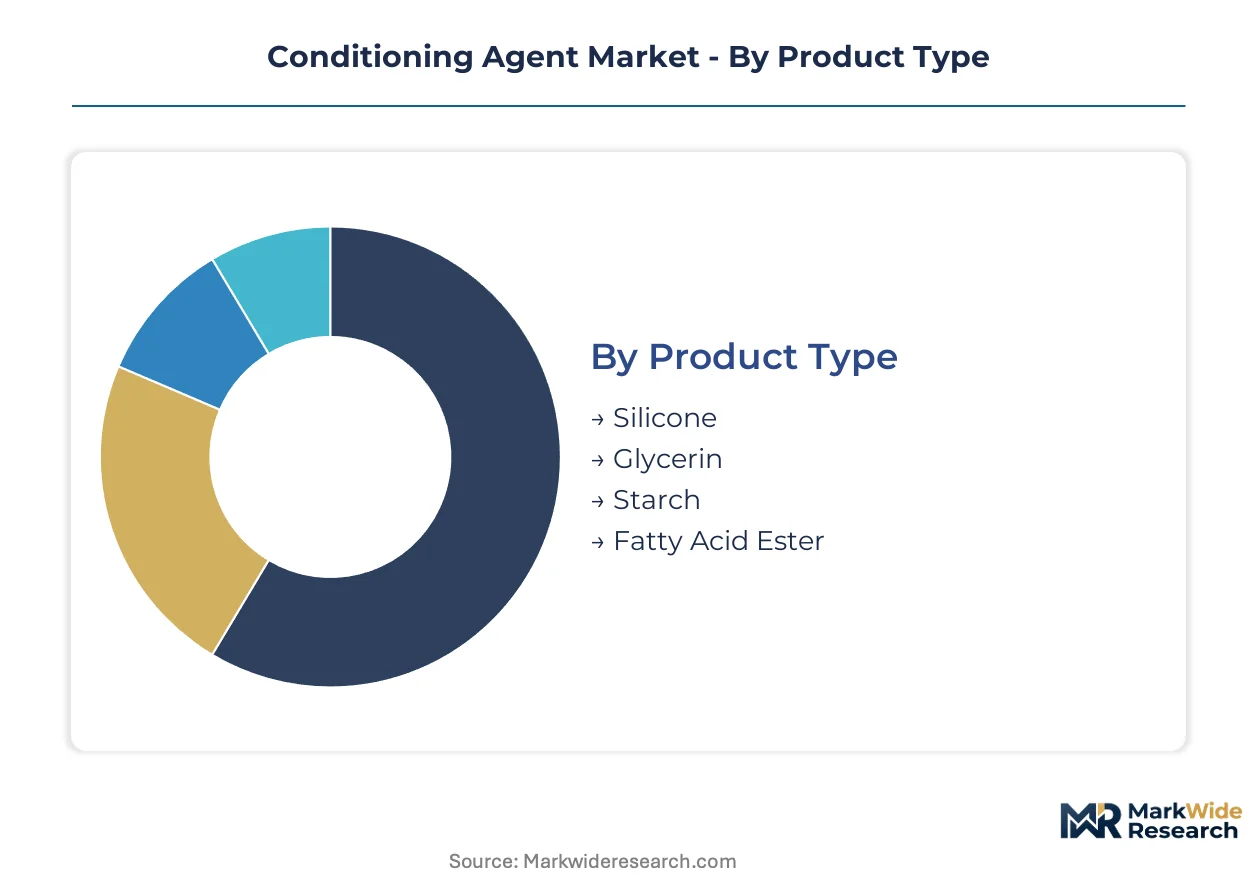
Conditioning agent procurement decisions hinge on formulation compatibility with existing manufacturing infrastructure and regulatory compliance pathways. Segmentation reveals where technical specifications diverge from commodity purchasing logic.
Product Type:
Standardization dominates silicone and glycerin supply chains, while fatty acid esters and starch derivatives demand customization for biodegradability certification and performance benchmarking.
- Silicone:Cyclic and linear polydimethylsiloxane fluids deliver instantaneous detangling through low surface energy deposition. Demand concentrates in Chinese premium hair care lines where salon-professional brands prioritize wet-combability scores over EU Green Deal compliance timelines.
- Fatty Acid Ester:Quaternized vegetable oil derivatives achieve cationic charge density without persistent aquatic toxicity. German and French formulators are absorbing higher raw material costs to maintain REACH-registered market access as D4/D5 cyclic siloxane availability tightens under the EU F-Gas Regulation.
- Glycerin:Humectant conditioning agent derived from biodiesel co-production streams.
- Starch:Cationic corn and potato derivatives for biodegradable film-forming in rinse-off applications.
Most installed capacity flows through silicone. Expansion is steepest in fatty acid ester as REACH registration deadlines approach.
Formulation:
Volume scale separates liquid and emulsion formats from powder and gel niches, with cold-process compatibility driving capital allocation decisions among contract manufacturers.
- Emulsion:Oil-in-water systems accommodate high active loading of cationic surfactants while maintaining shelf stability through controlled droplet size distribution. Italian and Spanish mid-tier brands seeking Ecolabel compliance are unbundling technical service contracts from bulk supply agreements to access specialized emulsion stabilization support.
- Liquid:Ready-to-dilute concentrates minimize handling steps for high-volume detergent producers. Southeast Asian direct-to-manufacturer procurement platforms are disintermediating regional distributors for these standardized formats.
- Powder:Spray-dried quaternary ammonium compounds for textile finishing bath applications.
- Gel:Thickened aqueous systems for leave-on hair treatment positioning.
Emulsion captures the largest value pool. Powder is climbing the fastest on textile export demand from Bangladesh and Vietnam.
Application:
End-use performance requirements create tiered specification regimes, with personal care demanding the deepest technical service engagement.
- Personal Care:Hair and skin conditioning applications require substantivity testing on keratinous substrates with documented friction reduction metrics. Korean cosmetics manufacturers are accelerating qualification cycles for fermentation-derived cationic polymers to anchor K-beauty export positioning around scalp microbiome claims.
- Household Cleaning:Fabric softener actives prioritize cost-per-wash efficiency over sensory performance. Chinese domestic detergent brands are scaling procurement volumes as premium laundry lines upgrade from standard quaternaries to amino acid-based variants.
- Textile Treatment:Fiber lubrication and antistatic finishing for synthetic yarn processing.
- Food Processing:Release agents and coating conditioners for confectionery and bakery applications.
Personal care commands premium pricing tiers. Food processing is gaining share fastest on clean-label emulsifier substitution trends.
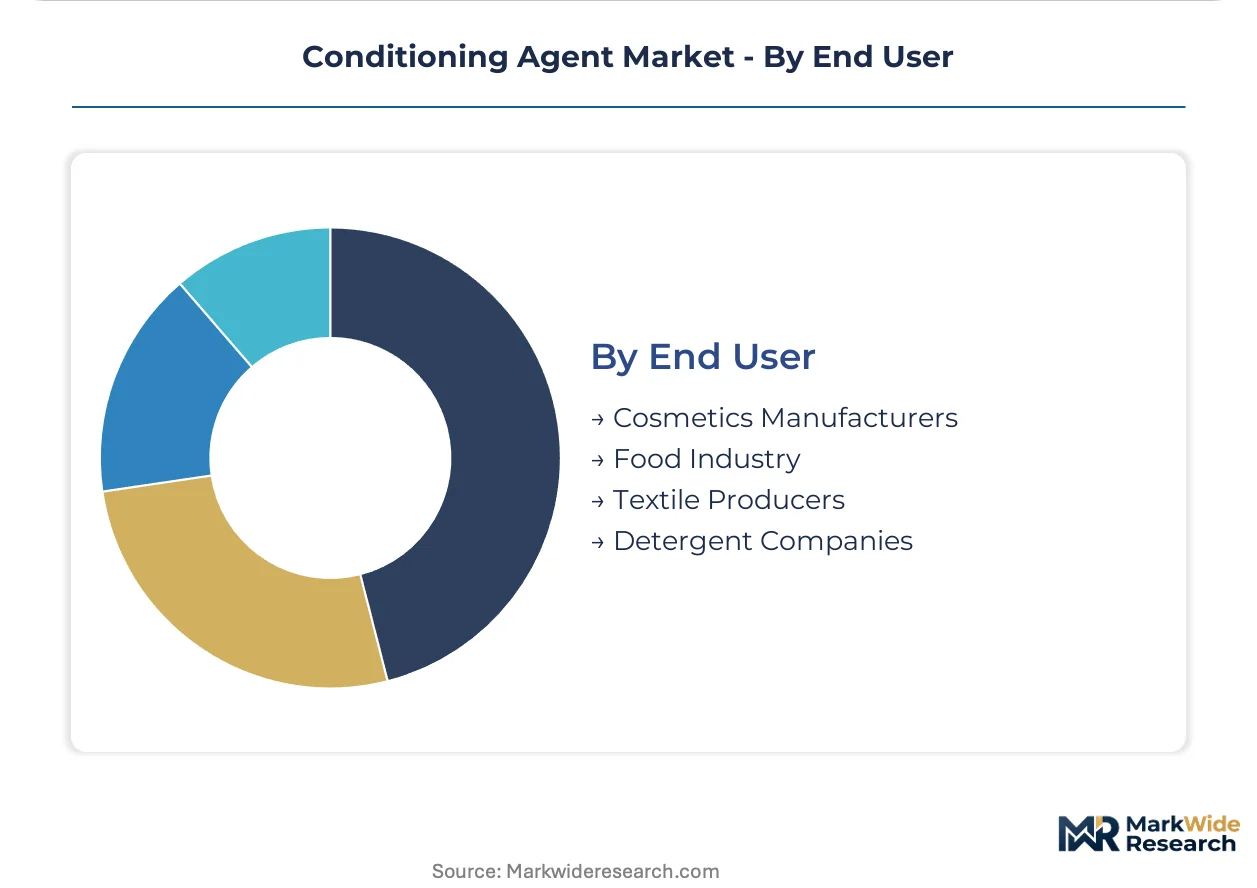
End User:
Customer scale determines whether procurement flows through integrated technical service relationships or commodity spot purchasing.
- Cosmetics Manufacturers:Multinational hair care brands anchor long-term contracts around integrated silicone portfolios with embedded formulation support. Modular formulation kits pairing conditioning actives with preservative-free delivery systems are simplifying supplier qualification for mid-tier personal care brands.
- Detergent Companies:High-volume laundry and dishwashing formulators prioritize feedstock security over performance differentiation. German chemical cluster disruptions in D4/D5 cyclic siloxane supply are elevating input cost uncertainty for European producers serving this segment.
- Food Industry:Bakery and confectionery processors seeking clean-label release agent alternatives.
- Textile Producers:Synthetic fiber processors in Bangladesh and Vietnam driving powder quaternary demand.
Cosmetics manufacturers absorb the deepest technical service costs. Detergent companies are expanding procurement most quickly on Southeast Asian capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The conditioning agent industry traces its modern scale to post-war German chemical engineering clusters that pioneered silicone polymerization for personal care applications. From those origins, production and formulation expertise dispersed across three continents. Today, procurement patterns diverge sharply by regulatory jurisdiction and domestic brand development stage.
Germany
Ludwigshafen and Leverkusen host integrated silicone production complexes serving European hair care formulators. ECHA registration deadlines under REACH compress reformulation timelines for D4/D5 cyclic siloxane alternatives. BASF SE anchors long-term supply contracts from these chemical clusters while absorbing higher fatty acid ester input costs to maintain market access.
China
Domestic personal care brands in Shanghai and Guangzhou scale premium hair treatment lines, concentrating procurement volumes for amino acid-based quaternary compounds. GB standards for cosmetic raw materials impose extended safety documentation burdens on imported conditioning agents. The Yangtze River Delta houses fermentation-derived cationic polymer capacity serving K-beauty export supply chains.
United States
Midland, Michigan and Philadelphia-area chemical corridors supply silicone fluids to North American cosmetics manufacturers. FDA cosmetic ingredient oversight intensifies post-MoCRA implementation, requiring brands to substantiate safety for leave-on conditioning products. EPA biodegradability certifications reshape raw material qualification timelines for brands targeting European export markets.
South Korea
Seoul Capital Area cosmetics manufacturers accelerate qualification cycles for biotechnology-derived conditioning polymers. MFDS cosmetic ingredient regulations align with scalp microbiome marketing claims in K-beauty export positioning. Busan-Ulsan chemical complexes house amino acid-based quaternary compound production serving regional formulators.
France
Paris-based luxury hair care brands absorb premium pricing for REACH-registered fatty acid ester alternatives to silicone benchmarks. ANSM cosmetic ingredient oversight converges with EU Green Deal biodegradability mandates. The Lyon chemical cluster specializes in cold-process emulsion systems for mid-tier personal care brands seeking Ecolabel compliance.
Conditioning Agent Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technical service depth and integrated formulation support. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive silicone portfolios, biotechnology specialists with fermentation-derived actives, and regional distributors serving standardized liquid concentrates. Consolidation pressure intensifies as cosmetics manufacturers unbundle technical service contracts from bulk supply agreements. Capacity expansion and strategic partnerships represent the dominant competitive moves as cold-process emulsion systems require capital outlays that strain mid-tier contract manufacturers.
Within the multinational chemical tier, BASF SE and Dow Inc. exemplify integrated portfolio positioning across silicone and biodegradable alternatives. Evonik Industries AG occupies a specialist position in amino acid-based quaternary compounds. These three entities anchor divergent sourcing strategies: German chemical clusters emphasize REACH compliance and formulation support, while US-based suppliers prioritize FDA-aligned documentation for MoCRA implementation.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Evonik Industries AG |
| Croda International Plc |
| Solvay S.A. |
| Procter & Gamble Co. |
| Henkel AG & Co. KGaA |
| L'Oréal S.A. |
| Kao Corporation |
| Others |
Supply Flow & Price Mechanics
Cold-process emulsion manufacturing is redrawing cost structures while compressing supply concentration around German and Chinese chemical clusters with captive fermentation capacity. This production-method transition simultaneously elevates capital barriers for mid-tier contract manufacturers and concentrates pricing power among integrated silicone producers and biotechnology specialists with regional technical service footprints.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered fatty acid esters from commodity silicone fluids and unverified imports. Price differentiation hinges on biodegradability certification grade and embedded formulation support depth. Cost compression in standard-grade silicone tiers is intensifying because D4/D5 cyclic siloxane supply disruptions from Ludwigshafen chemical clusters are elevating input uncertainty. Detergent companies exhibit highest price sensitivity due to volume procurement and thin margin structures, while cosmetics manufacturers absorb premium positioning for scalp microbiome-compatible actives.
Supply Chain Analysis
Freight cost differentials between German chemical clusters and Yangtze River Delta fermentation facilities are reshaping regional sourcing strategies for European formulators. Supply concentration rests on Germany, China, and South Korea as dominant production nodes. Raw material dependencies center on petrochemical feedstocks for silicone polymerization, vegetable oil derivatives for quaternized esters, and glucose substrates for microbial fermentation. Single-source vulnerability runs through German D4/D5 siloxane capacity constrained by EU F-Gas Regulation phase-down schedules. Distribution runs through integrated technical service relationships for premium tiers and direct-to-manufacturer digital platforms for standardized liquid concentrates in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH registration deadlines and EU Green Deal biodegradability mandates are accelerating demand displacement from silicone toward bio-derived alternatives.
For Market Incumbents: Deploy backward integration into fermentation-derived cationic polymer capacity to preempt substitution threats from Korean and Chinese biotechnology specialists. Anchor long-term contracts through embedded formulation support that mid-tier brands cannot replicate without cold-process emulsion capital outlays. Absorb higher fatty acid ester input costs to maintain REACH-registered market access as German silicone feedstock tightens. For New Entrants and Emerging Players: Fermentation-derived scalp microbiome actives offer the most penetrable white-space for qualification-accelerated entry into K-beauty export supply chains. Target mid-tier Italian and Spanish personal care brands seeking Ecolabel compliance through unbundled technical service contracts. Lead with modular formulation kits pairing conditioning actives with preservative-free delivery systems to bypass legacy silicone-polymer compatibility expertise scarcity. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors serving standardized liquid concentrates to detergent companies, as digital procurement platforms disintermediate their role. Long-term viability favors biotechnology specialists with captive fermentation capacity and clean-label certification pathways. Watch qualification cycle acceleration for amino acid-based quaternary compounds as the inflection signal for supply chain control shifts from petrochemical to bio-derived feedstocks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive bio-derived polymer production secures REACH compliance ahead of silicone feedstock constraints. |
| Cold-Process Emulsion System Deployment | Italian and Spanish contract manufacturers absorb capital outlays to access Ecolabel-compliant production. |
| Modular Formulation Kit Development | Mid-tier cosmetics brands simplify supplier qualification through bundled actives and delivery systems. |
| Direct-to-Manufacturer Platform Launch | Southeast Asian procurement channels disintermediate regional distributors for standardized liquid concentrates. |
| Scalp Microbiome Certification Investment | Korean cosmetics manufacturers anchor K-beauty export positioning around prebiotic-active marketing claims. |
Methodological Framework
Coverage spans Germany, China, South Korea, France, and the United States, with primary inputs from each regional chemical cluster. The analysis combines primary interviews with plant managers at integrated silicone producers, procurement leads at multinational hair care brands, technical R&D directors at fermentation houses, and regulatory affairs specialists navigating REACH and GB standards. Secondary validation draws from ECHA registration databases, Chinese customs trade data for cosmetic raw material imports, SEC 10-K filings from chemical conglomerates, and Cefic sector reports. Bottom-up capacity estimates triangulate against top-down demand projections from personal care and detergent end-use segments.
Rate-of-change decomposition separates volume drivers from value migration across the projection horizon. The analytical framework models segmentation dimensions including product type (silicone, fatty acid ester, glycerin, starch), formulation format (emulsion, liquid, powder, gel), application (personal care, household cleaning, textile treatment), and end-user scale (multinational cosmetics manufacturers, mid-tier brands, detergent companies). CAGRs derive from weighted average of historical trajectory and regulatory-mandated substitution elasticity. Industry-specific forecast inputs incorporate EU F-Gas Regulation phase-down schedules and Chinese domestic brand premium line expansion rates.
The model holds under stable regulatory enforcement timelines and continued fermentation capacity scaling; deviation in REACH registration deadline extensions or sudden silicone feedstock availability would shift substitution trajectories. Forecasts reflect documented assumptions about biodegradability certification adoption curves and cold-process equipment retrofit rates. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Refinery Process Additives Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Global Cement and Concrete Additives Market
Additives
Global Chelated Trace Minerals Market
Additives
Gasoline Additives Market
Additives
Viscosity Reducing Agents Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Extrusion Aids Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Tragacanth Market
Additives
China Citric Acid Market
Additives
Global PVC Stabilizer Market
Additives
Sodium Caprylate Market
Additives
Foundry Additives Market
Additives
Anti-Slip Additives Market
Additives
Calcium Diglutamate Market