
 Global Whey Protein Ingredients Market | 2026-2036
Global Whey Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Whey Protein Ingredients Market Outlook
Protein standardization to higher purity grades is rotating demand toward whey protein isolate and hydrolyzed variants. Fonterra Co-operative Group Limited leverages its New Zealand dairy cooperative structure to sustain grass-fed whey differentiation across export markets. Arla Foods Ingredients anchors European supply through specialized fractionation technology. Glanbia Nutritionals competes on sports nutrition channel control in North America.
Whey protein ingredients comprise milk-derived protein fractions separated during cheese manufacturing, typically containing beta-lactoglobulin, alpha-lactalbumin, and immunoglobulins with protein concentrations ranging from 34% to 90% depending on processing intensity. These ingredients function as emulsifiers, gelling agents, and complete amino acid sources across food, pharmaceutical, and nutritional applications. Whey protein isolate commands premium positioning due to its minimal lactose and fat content, while hydrolyzed whey protein is gaining traction in infant formula and medical nutrition where digestibility requirements are stringent. The powder form dominates manufacturing economics, though ready-to-drink liquid applications are expanding fastest in convenience-oriented consumer segments.
FDA protein labeling standards and EFSA health claim frameworks shape product positioning and market access requirements across major producing regions. China's NMPA and SAMR enforce stricter dairy import specifications that filter supplier eligibility for cross-border whey protein sales. ISO and IDF analytical standards govern protein content measurement methods that determine contract pricing and quality arbitration. Stakeholders must monitor evolving regulatory divergence between major importing jurisdictions to maintain formulation compliance and avoid customs detention risks.
Market Dynamics
Clean label verification requirements and protein content standardization are compressing supplier margins while rotating volume toward isolate and hydrolyzed grades. FDA protein labeling enforcement and EFSA health claim substantiation are filtering market access eligibility.
Growth Catalysts
- Ready-to-drink sports beverages:Brands are expanding whey protein into liquid formats for convenience-oriented consumers, creating new formulation demand for cold-stable isolates.
- EFSA health claim frameworks:Approved muscle maintenance and satiety claims enable premium positioning in European functional foods, driving isolate adoption.
- China's functional food manufacturing clusters:Domestic production capacity expansion in Shanghai and Tianjin is pulling imported whey protein concentrate for reprocessing.
Market Restraints
- Dairy input cost volatility:Fluid milk price swings in New Zealand and Europe transmit directly to whey protein contract pricing, compressing processor margins.
- Supply concentration in Oceania:Fonterra and Australian dairy cooperatives control disproportionate grass-fed whey volumes, creating single-source dependency risks.
- Plant protein substitution:Pea and rice protein isolates are capturing share in vegan-positioned sports nutrition, displacing whey in ethical-consumer segments.
Strategic Opportunities
- Medical nutrition underpenetration:Hydrolyzed whey protein for dysphagia and post-surgical recovery remains underserved in Germany's clinical nutrition channels.
- China's NMPA import pathway simplification:Streamlined dairy ingredient registration creates faster market access for compliant European and Oceania suppliers.
- Direct-to-consumer subscription models:Sports nutrition brands are bypassing retail intermediaries, enabling higher-margin isolate sales with personalized formulation.
Industry Challenges
- Fractionation technology skill scarcity:Specialized membrane filtration and chromatography expertise concentrates in Denmark and New Zealand, limiting capacity expansion elsewhere.
- ISO 17025 laboratory certification timelines:Protein content verification labs face 12-18 month accreditation backlogs, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Whey Protein Ingredients Market |
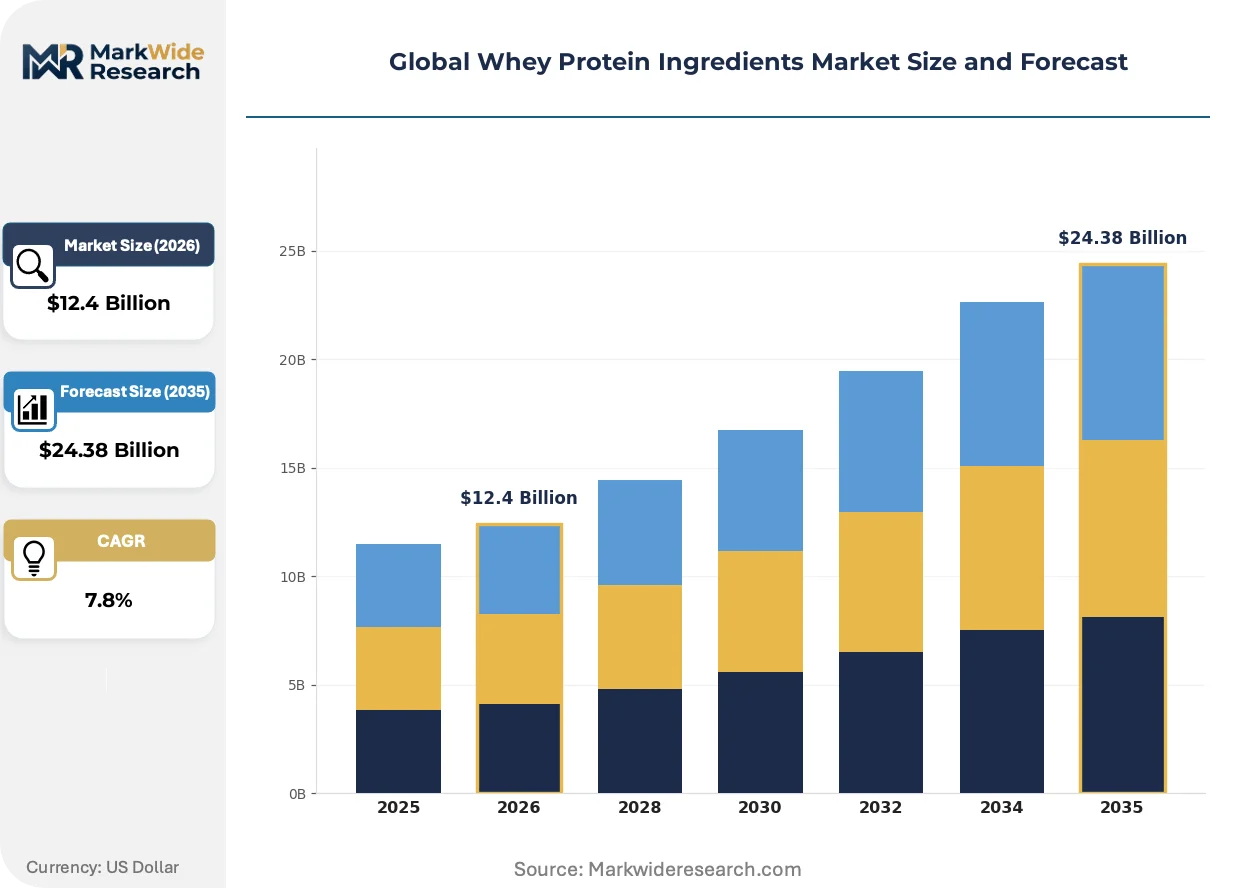
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $24.38 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Whey Protein Isolate, Hydrolyzed Whey Protein, Native Whey Protein End Use: Food & Beverage, Supplements, Bakery, Dairy Products Form: Powder, Liquid, Bars, Ready-to-Drink Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Hilmar Cheese Company, Lactalis Group, Fonterra Co-operative Group Limited, Milk Specialties Global, FrieslandCampina Ingredients, Arla Foods Ingredients, Saputo Inc., Carbery Group, Glanbia Nutritionals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Whey Protein Ingredients Market Strategic Shifts
Membrane filtration advances and enzymatic hydrolysis are reshaping protein purity economics, while regulatory verification requirements and channel disintermediation are compressing traditional supply relationships.
Microfiltration and ultrafiltration cascades are fragmenting the cost structure between commodity whey protein concentrate and premium isolates. Infant formula manufacturers in the Netherlands and Germany are adopting ceramic membrane systems for native whey protein preservation. This technology diffusion is fragmenting supplier tiers, separating capital-intensive fractionation specialists from toll processors.
China's SAMR dairy import registration renewal requirements are tightening documentation for whey protein suppliers. The 2024 implementation of extended shelf-life testing protocols has extended approval timelines for new entrants. European exporters are responding by pre-positioning inventory in Shanghai bonded zones to maintain supply continuity.
Sports nutrition procurement is consolidating through direct brand relationships with fractionators, bypassing traditional ingredient distributors. North American CrossFit and functional fitness communities are driving small-batch isolate demand through subscription platforms. This channel compression is most visible in California and Texas, where vertically integrated brands control formulation through contract manufacturing partnerships.
Global Whey Protein Ingredients Market Segmentation
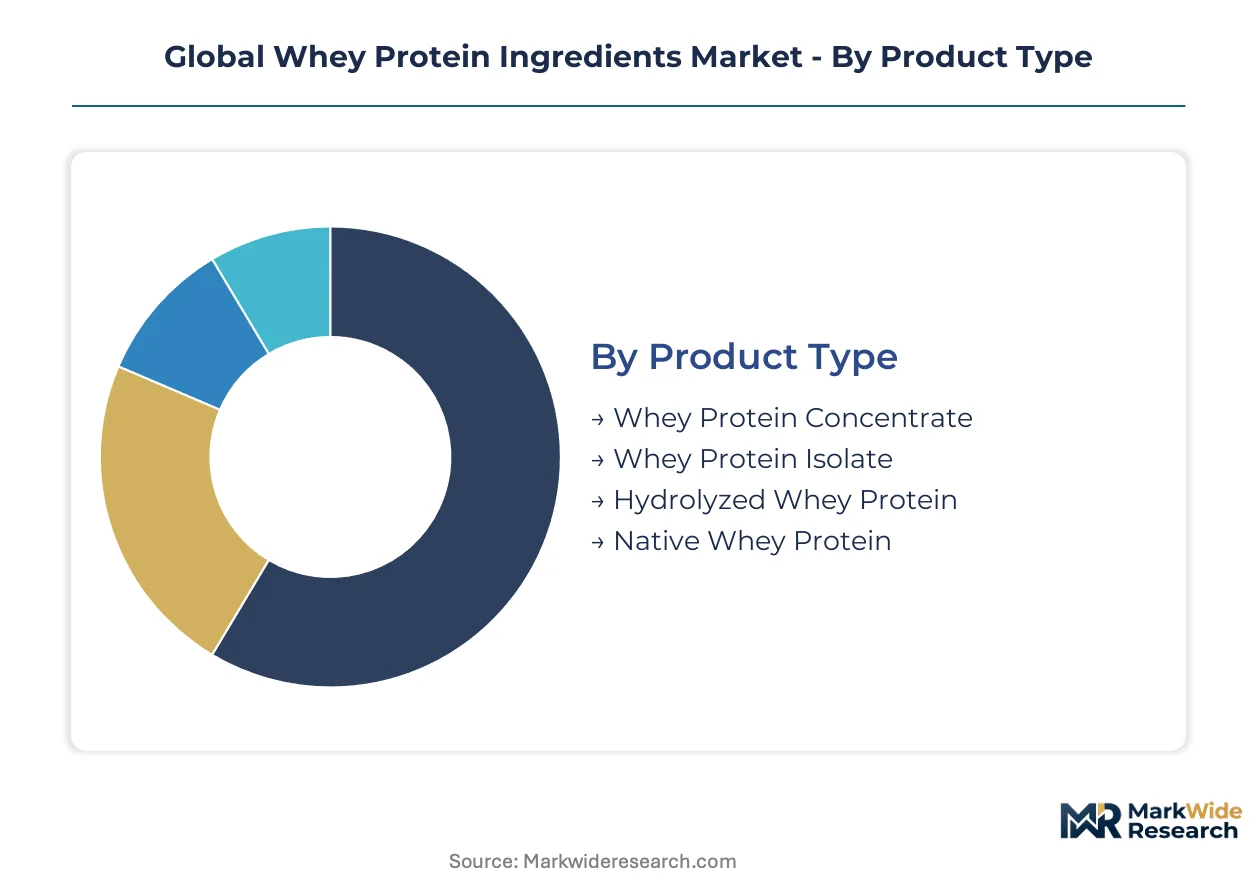
Whey protein ingredient flows fragment across distinct channel economics and purity specifications. Manufacturers must align fractionation investment with end-use concentration zones to optimize margin capture.
Product Type:
Channel mix varies sharply by protein grade: isolates and hydrolysates command premium placement in medical nutrition and sports nutrition direct channels, while concentrates flow through commodity food manufacturing procurement.
- Whey Protein Concentrate:Contains 34% to 80% protein with retained lactose and fat fractions, serving as the volume workhorse for bakery and processed food applications. Demand concentrates in China's reprocessing clusters and German dairy manufacturing where cost-sensitive formulation dominates procurement decisions.
- Whey Protein Isolate:Delivers 90%+ protein with minimal lactose through ion exchange or cross-flow microfiltration, enabling clean-label positioning in ready-to-drink beverages and clinical nutrition. Sports nutrition brands in California and Texas are pulling isolate volumes through subscription-direct channels that bypass traditional distribution.
- Hydrolyzed Whey Protein:Pre-digested peptide fractions manufactured through enzymatic hydrolysis for rapid absorption in infant formula and post-surgical recovery products.
- Native Whey Protein:Cold-processed undenatured fractions preserving bioactive immunoglobulins for premium functional food positioning in Netherlands and Germany.
By volume, Whey Protein Concentrate leads. By growth pace, Whey Protein Isolate is climbing the fastest.
End Use:
Application maturity determines margin tier: established food manufacturing segments compete on scale efficiency while emerging clinical and personalized nutrition channels reward purity premiums.
- Food & Beverage:Encompasses protein fortification in processed foods, beverages, and convenience products where emulsification and gelling functionality drive specification. China's functional food manufacturing expansion in Shanghai and Tianjin is pulling imported concentrate volumes for reprocessing into domestic branded products.
- Supplements:Sports nutrition powders, capsules, and personalized stacks where protein content verification and amino acid profiling determine supplier selection. North American CrossFit communities and functional fitness segments are consolidating procurement through vertically integrated brands that control formulation via contract manufacturing partnerships.
- Bakery:Protein-enhanced bread, pastry, and snack applications requiring heat-stable emulsification properties and Maillard reaction management.
- Dairy Products:Greek yogurt fortification, protein-enriched milk, and fermented product applications where native whey fractions preserve texture integrity.
Supplements command the highest purity premiums. Food & Beverage anchors absolute tonnage throughput.
Form:
Manufacturing economics and consumption occasion segmentation dictate format selection, with powder dominating ingredient trade and liquid formats capturing convenience-oriented end-consumers.
- Powder:Bulk ingredient format optimizing transport efficiency and shelf stability for manufacturing reconstitution. Powder dominates B2B procurement from New Zealand and European fractionators serving reprocessors in China and Germany.
- Liquid:Pre-solubilized protein solutions for ready-to-drink manufacturing and beverage fortification where cold-chain distribution infrastructure supports format viability.
- Bars:Extruded protein matrices combining whey with binding agents and coatings for portable snacking occasions in North American and European convenience retail.
- Ready-to-Drink:Single-serve beverages requiring cold-stable isolate grades and aseptic processing capabilities, expanding fastest through California and Texas fitness-oriented subscription platforms.
Powder retains manufacturing cost advantage. Ready-to-Drink formats are expanding most quickly in consumer-facing channels.
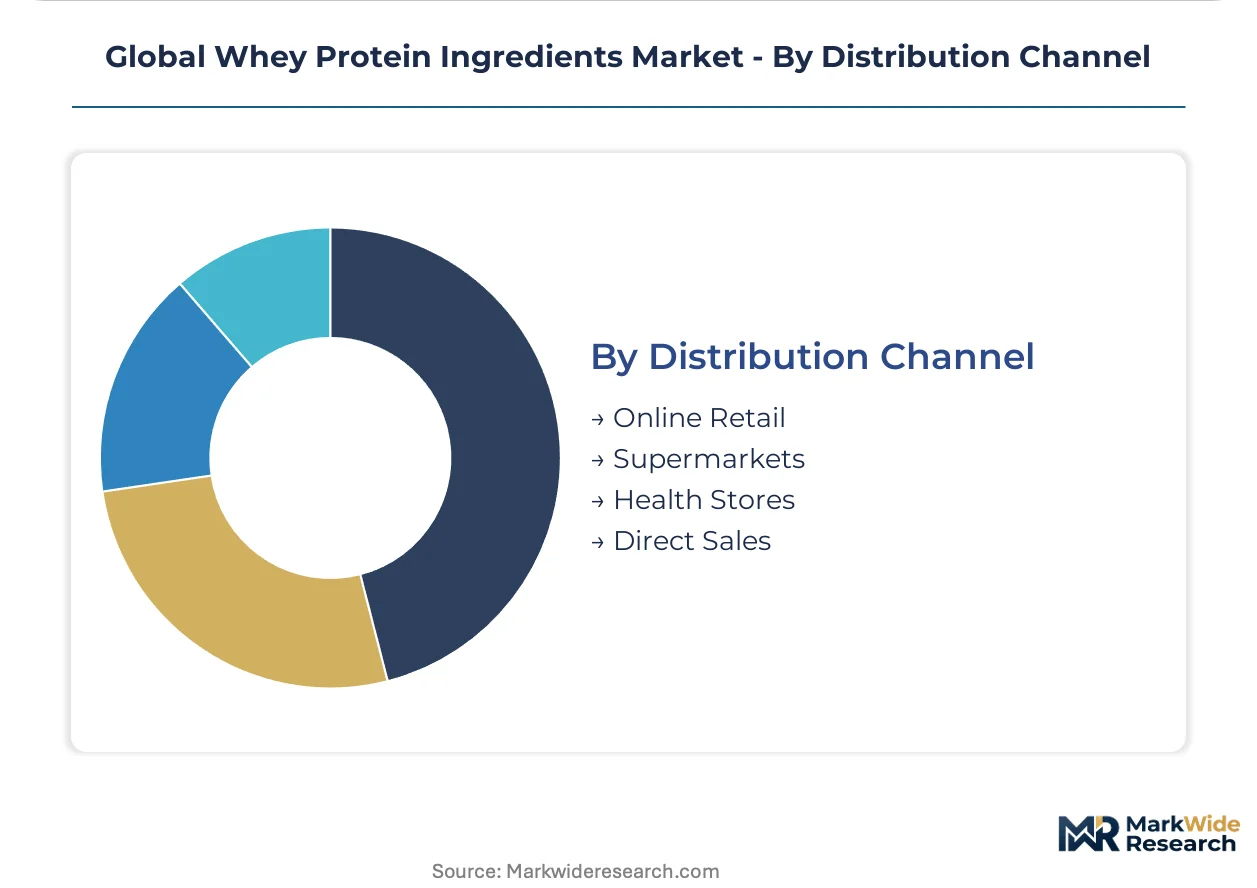
Distribution Channel:
Channel control is fragmenting as sports nutrition brands bypass intermediaries, compressing traditional ingredient distributor margins while rewarding direct fractionator relationships.
- Online Retail:E-commerce platforms and brand-direct subscription models enabling personalized formulation and higher-margin isolate sales. North American functional fitness communities are consolidating purchases through specialized platforms that bypass retail intermediaries entirely.
- Supermarkets:Mass retail placement for mainstream sports nutrition and fortified food products where shelf-space negotiation and promotional funding determine access.
- Health Stores:Specialty retail channels emphasizing clean-label verification and third-party certification for discerning consumers in Germany and United States urban centers.
- Direct Sales:B2B procurement relationships between fractionators and food manufacturers, plus multi-level marketing networks for personalized nutrition coaching in select Asian markets.
Supermarkets move the highest absolute volumes. Online Retail is gaining share fastest as subscription models consolidate repeat purchase behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from New Zealand and Europe dominate international whey protein trade, while import demand clusters in manufacturing hubs across three continents. Regional regulatory divergence is fragmenting supplier compliance requirements and reshaping inventory positioning strategies.
United States
Sports nutrition brands in California and Texas are consolidating isolate procurement through subscription-direct channels that bypass traditional distribution. FDA protein labeling enforcement and amino acid verification requirements filter supplier eligibility for domestic sales. Cold-chain infrastructure in the Pacific Northwest supports ready-to-drink manufacturing expansion.
China
Functional food manufacturing clusters in Shanghai and Tianjin are pulling imported whey protein concentrate volumes for domestic reprocessing into branded products. SAMR dairy import registration renewal requirements and extended shelf-life testing protocols are tightening documentation standards. Bonded zone inventory pre-positioning in Shanghai maintains supply continuity for compliant European and Oceania suppliers.
Germany
Clinical nutrition channels show underpenetration for hydrolyzed whey protein targeting dysphagia and post-surgical recovery applications. EFSA health claim frameworks for muscle maintenance and satiety enable premium positioning in functional foods. Ceramic membrane adoption in Dutch and German infant formula manufacturing preserves native whey protein fractions.
New Zealand
Fonterra's cooperative structure sustains grass-fed whey differentiation across export markets. Dairy input cost volatility in fluid milk markets transmits directly to whey protein contract pricing. Fractionation technology expertise concentrates in specialized membrane filtration and chromatography operations.
Netherlands
Specialized fractionation technology anchors European supply for high-purity isolate and hydrolyzed grades. EFSA health claim substantiation requirements shape product positioning for muscle maintenance applications. Infant formula manufacturers adopt advanced membrane systems for native whey protein preservation.
Global Whey Protein Ingredients Market Competitive Environment
Concentration sits with dairy cooperative structures and specialized fractionation specialists who control grass-fed sourcing and purity-grade production. The vendor base separates into three tiers: capital-intensive fractionation specialists with captive milk supply, toll processors dependent on third-party raw material flows, and vertically integrated sports nutrition brands controlling formulation through contract manufacturing partnerships. Competitive moves center on direct-to-brand procurement relationships and membrane filtration technology licensing.
Within the cooperative tier, Fonterra Co-operative Group Limited and Arla Foods Ingredients occupy positions defined by geographic sourcing advantages and fractionation capabilities. Glanbia Nutritionals exemplifies the North American sports nutrition channel control archetype. FrieslandCampina Ingredients and Lactalis Group represent European dairy processing scale. These entities anchor competitive dynamics through supply relationships with manufacturing clusters in China, Germany, and the United States.
| Leading Market Players |
|---|
| Hilmar Cheese Company |
| Lactalis Group |
| Fonterra Co-operative Group Limited |
| Milk Specialties Global |
| FrieslandCampina Ingredients |
| Arla Foods Ingredients |
| Saputo Inc. |
| Carbery Group |
| Glanbia Nutritionals |
| Others |
Value Chain & Pricing Dynamics
Fractionation capacity utilization above 85% in New Zealand and Denmark simultaneously concentrates supply-side pricing power and establishes protein purity grade floors that commodity processors cannot match. This scale dynamic compresses margins for toll processors while enabling membrane technology specialists to sustain premium positioning across whey protein isolate and hydrolyzed variants.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in whey protein procurement. Price differentiation hinges on ISO 17025 certification status and volume scale commitments, with certified isolates commanding substantial premiums over uncertified concentrates. Cost compression in standard-grade whey protein concentrate is intensifying because China's reprocessing clusters are consolidating purchase volumes. Sports nutrition brands show least price sensitivity, while bakery and processed food manufacturers exhibit highest elasticity to lactose and fat content adjustments.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes from Oceania to Shanghai and Tianjin are extending lead times for whey protein concentrate shipments. Raw material flows draw from fluid milk supplies in New Zealand, Germany, and the Netherlands, with enzymatic hydrolysis enzymes and ceramic membrane systems as critical processing inputs. Single-source vulnerability concentrates in Fonterra's grass-fed whey volumes from New Zealand cooperative structures. Distribution runs through bonded zone pre-positioning for compliant suppliers serving China's SAMR registration requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sports nutrition brand consolidation through direct-to-consumer subscription platforms has shifted procurement leverage toward buyers, fragmenting traditional ingredient distributor relationships. This buyer-power concentration rewards fractionators who bypass intermediaries entirely.
For Market Incumbents: Shield grass-fed differentiation through captive New Zealand and European milk supply agreements that plant protein substitutes cannot replicate. Invest in ISO 17025 laboratory certification ahead of FDA protein labeling enforcement timelines to filter competitor market access. Channel control through California and Texas contract manufacturing partnerships defends against direct-brand disintermediation.
For New Entrants and Emerging Players: Differentiate on native whey protein preservation using cold-processing technology for infant formula manufacturers in the Netherlands and Germany. Target China's NMPA streamlined registration pathway for compliant European and Oceania suppliers as the most penetrable access route. Pursue white-label manufacturing partnerships with vertically integrated sports nutrition brands seeking formulation flexibility.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane filtration specialists with installed ceramic and cross-flow microfiltration capacity over commodity toll processors. Long-term viability across the analysis window rests on fractionation technology licensing revenue streams and direct-brand procurement relationships. Watch EFSA health claim framework expansion for muscle maintenance and satiety as the signal for premium isolate demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Enables technology diffusion beyond Denmark and New Zealand concentration zones. |
| Direct-to-Consumer Subscription Launch | California and Texas fitness communities consolidate repeat isolate purchases. |
| ISO 17025 Laboratory Certification Investment | Accelerates FDA protein content verification compliance for market access. |
| Shanghai Bonded Zone Inventory Pre-positioning | Maintains supply continuity under SAMR extended shelf-life testing protocols. |
| Grass-Fed Supply Agreement Expansion | Secures Fonterra-style differentiation against plant protein substitution threats. |
Study Parameters
Desk research of dairy cooperative annual reports, FDA enforcement actions, and EFSA health claim registers preceded structured interviews with fractionation plant managers, sports nutrition brand procurement directors, and clinical nutrition formulary specialists. Secondary validation drew from Fonterra and Arla Foods Ingredients supply disclosures, Chinese customs import records, and IDF analytical standard documentation. Bottom-up volume modeling triangulated against top-down protein ingredient trade flow estimates.
Variance decomposition across the projection horizon isolates volume, price, and mix effects by whey protein grade tier, end-use application, and regional manufacturing cluster. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated membrane technology adoption curves, SAMR registration pipeline velocities, and CrossFit community subscription penetration patterns.
Forecasts assume regulatory continuity in FDA protein labeling standards and EFSA health claim frameworks; material policy shifts would require re-modeling. Dairy input cost volatility in Oceania and European fluid milk markets represents a specific revision risk. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Soy Protein Concentrate Market
Ingredients
Glucuronolactone Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Fermentation Ingredient Market
Ingredients
L-Arabinose Market
Ingredients
Mustard Oil Market
Ingredients
Hydrolyzed Vegetable Protein Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Lipids Market
Ingredients
Sunflower Meal Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Virginiamycin Market
Ingredients
Rice Starch Market
Ingredients
Potato Flour Market
Ingredients
Tryptose Market
Ingredients
Sweet Almond Oil Market