
 Hydrolyzed Whey Protein Market | 2026-2036
Hydrolyzed Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolyzed Whey Protein Market Analysis
New Zealand dairy processing capacity is broadening hydrolyzed whey availability for North American and Asian buyers. Fonterra Co-operative Group leverages its integrated milk supply to control raw material quality from farm to finished ingredient. Glanbia Nutritionals sustains R&D intensity around peptide fractionation technologies that enhance protein bioactivity. Arla Foods Ingredients anchors European supply through its Danish production network, while Kerry Group competes on flavor masking systems that improve the palatability of hydrolyzed formulations in ready-to-drink applications.
Hydrolyzed whey protein consists of whey proteins broken into smaller peptide chains through enzymatic hydrolysis, typically achieving 80-90% protein content with reduced allergenic potential and faster gastrointestinal absorption than intact whey. Manufacturers employ controlled enzymatic treatment followed by membrane filtration to achieve specific degrees of hydrolysis measured by peptide chain length. The sports nutrition application commands the largest volume position due to established consumer familiarity with post-workout recovery protocols. Clinical nutrition represents the fastest-expanding segment as hospitals and long-term care facilities adopt peptide-based enteral formulas for patients with compromised digestive function. Food grade material captures the dominant margin pool, while pharmaceutical grade commands premium pricing for neonatal and metabolic disorder applications.
The FDA exercises oversight through Current Good Manufacturing Practice regulations for dietary supplements, while the USDA monitors dairy ingredient safety through its Dairy Grading Branch inspection protocols. FERC indirectly influences production economics through electricity rate structures affecting energy-intensive membrane filtration operations. Stakeholders must monitor evolving peptide health claim substantiation requirements and decide whether to invest in clinical trial infrastructure or partner with academic research institutions for efficacy validation.
Market Dynamics
Enzymatic hydrolysis technology is concentrating production among processors with captive membrane filtration infrastructure, locking out smaller dairies and reshaping competitive access to peptide-grade raw material.
Growth Catalysts
- FDA Dietary Supplement Labeling Overhaul:Clean label mandates are pushing sports nutrition brands toward hydrolyzed whey with transparent peptide sourcing and minimal additive profiles.
- Enteral Nutrition Protocol Standardization:Hospital systems are adopting peptide-based clinical formulas for post-surgical and ICU patients with compromised digestive absorption capacity.
- Membrane Filtration Scale-Up:Advanced ultrafiltration and nanofiltration systems are reducing peptide fractionation costs and enabling food-grade processors to enter pharmaceutical-grade supply tiers.
Market Restraints
- Whey Protein Concentrate Substitution:Cost-sensitive sports nutrition brands are reverting to intact whey concentrates where rapid absorption is not clinically justified.
- New Zealand Supply Concentration:Fonterra and Glanbia control disproportionate global hydrolyzed whey capacity, creating single-source vulnerability for North American and Asian buyers.
- Degree of Hydrolysis Measurement Standardization Gaps:Inconsistent peptide chain length assays across ISO and AOAC methods create quality assurance friction in cross-border trade.
Strategic Opportunities
- Indian Clinical Nutrition Expansion:CDSCO accelerated approval pathways for imported enteral formulas are opening hospital procurement channels for peptide-based medical foods.
- Functional Beverage Channel Innovation:Ready-to-drink protein waters and clear protein RTDs are creating new consumption occasions beyond traditional powder formats.
- EU Green Deal Dairy Processing Incentives:Energy efficiency grants for membrane filtration retrofit projects are lowering capital barriers for European whey processors.
Industry Challenges
- Peptide Bioactivity Validation Expertise Scarcity:Manufacturers lack in-house clinical trial infrastructure to substantiate health claims for specific dipeptide and tripeptide fractions.
- Pharmaceutical Grade Certification Timelines:FDA Current Good Manufacturing Practice audits and USP-NF monograph compliance extend time-to-market by months for neonatal formula applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolyzed Whey Protein Market |
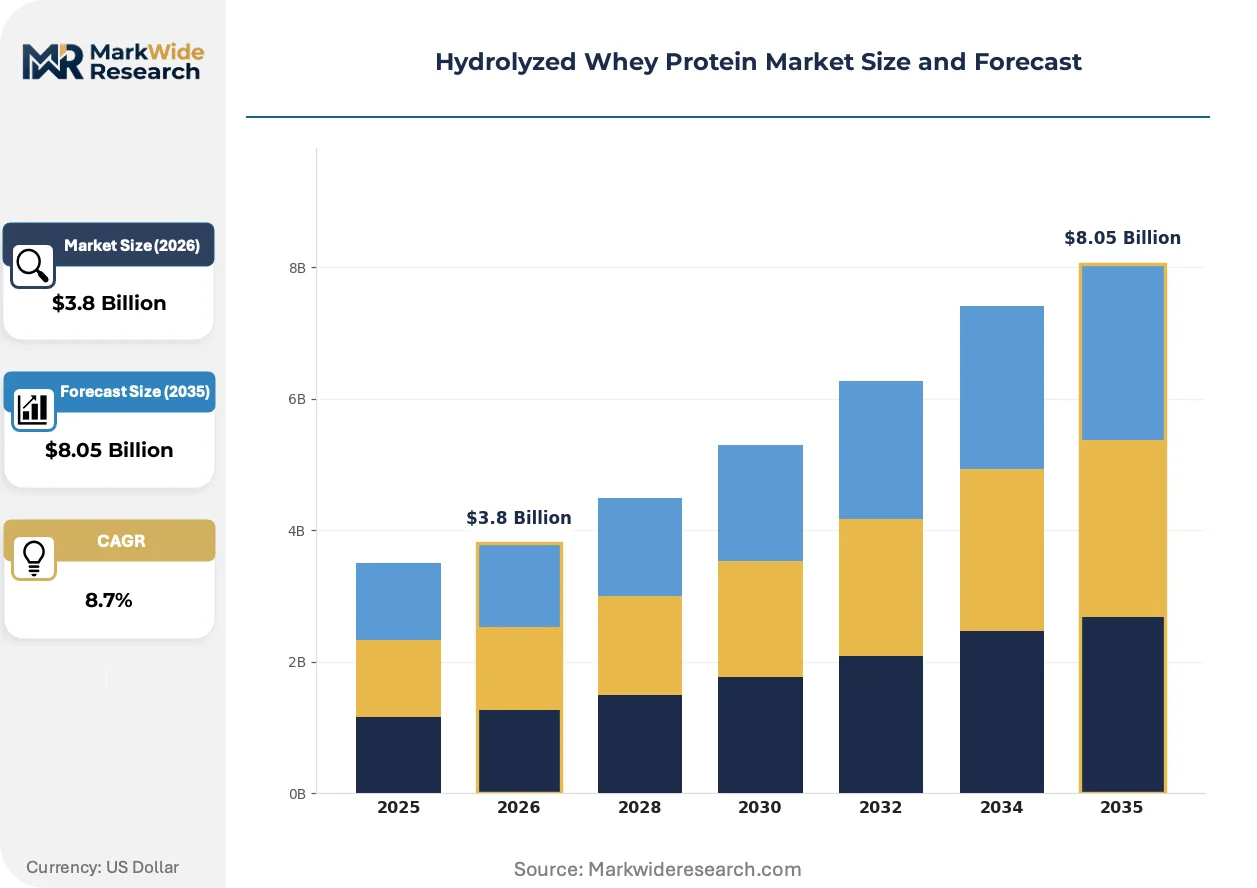
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolyzed, Blends End User: Athletes, Fitness Enthusiasts, Bodybuilders, General Consumers Application: Dietary Supplements, Sports Nutrition, Clinical Nutrition, Food & Beverages Grade: Food Grade, Pharmaceutical Grade, Feed Grade, Others |
| Companies Covered | Fonterra Co-operative Group, FrieslandCampina Ingredients, Arla Foods Ingredients, NZMP, Agropur, Glanbia Nutritionals, Kerry Group, Carbery Group, Hilmar Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolyzed Whey Protein Market Emerging Trajectories
Continuous enzymatic processing is displacing batch hydrolysis across commercial-scale installations, compressing production cycles and enabling real-time degree-of-hydrolysis monitoring that batch systems cannot match.
Electrodialysis with bipolar membranes is decentralizing mineral removal from hydrolyzed whey streams. Mid-scale processors in Denmark and the Netherlands are adopting this electrochemical separation technology to bypass centralized demineralization services. The shift is compressing supply chain stages and enabling regional processors to compete on pharmaceutical-grade material without legacy infrastructure investments.
REACH registration requirements for industrial enzyme formulations are tightening disclosure obligations for European hydrolyzed whey manufacturers. ECHA substance evaluation protocols now demand full toxicological profiles for protease enzymes used in food-contact applications. German and Dutch processors are responding by qualifying enzyme suppliers with pre-registered dossiers, excluding smaller biotech vendors from approved supplier lists.
Hospital procurement consolidation is compressing vendor qualification cycles for clinical nutrition suppliers. Group purchasing organizations in the United States are unbundling enteral formula contracts from device agreements, forcing peptide-based formula specialists to compete on unit economics rather than bundled service relationships. The shift favors processors with dedicated medical food sales infrastructure over commodity whey suppliers attempting vertical moves into clinical channels.
Hydrolyzed Whey Protein Market Segmentation
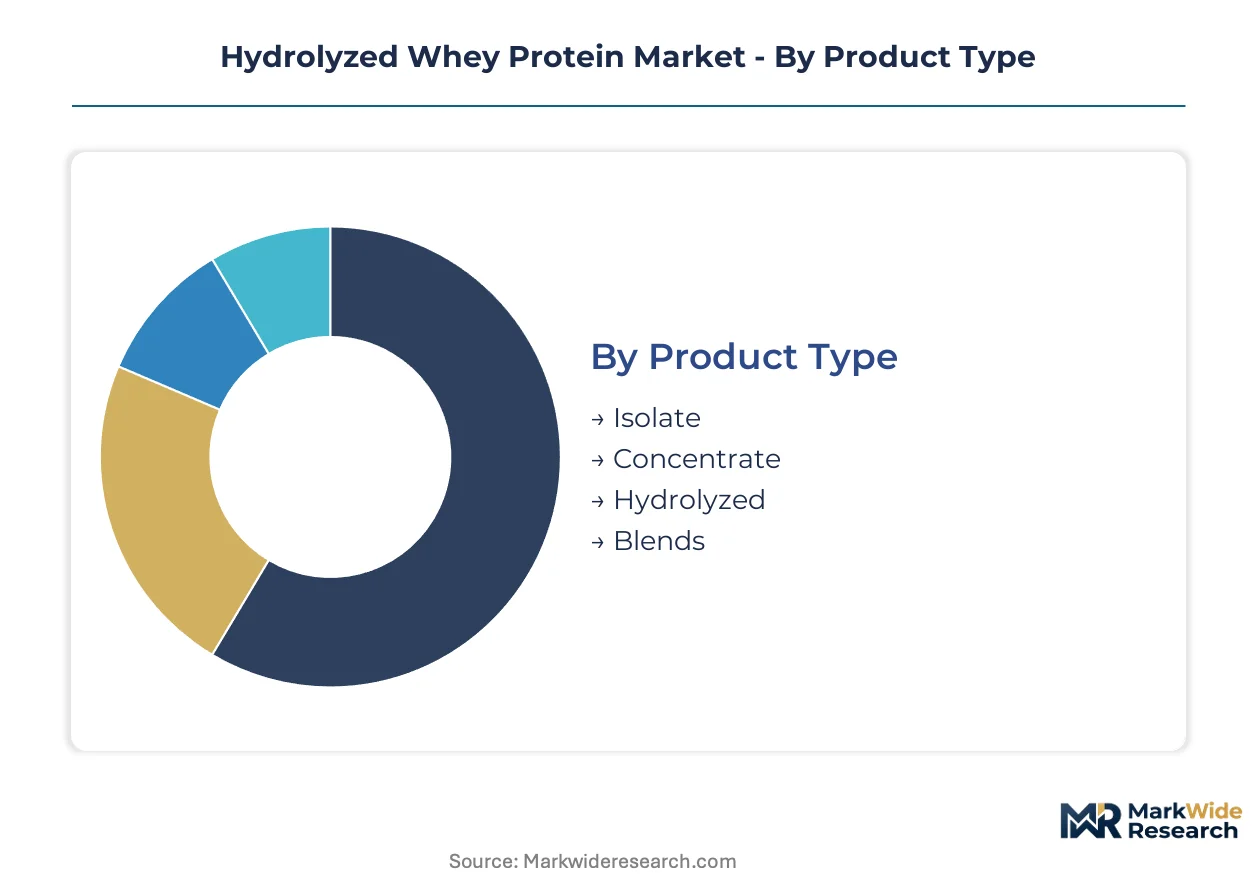
Segmentation in hydrolyzed whey protein reveals how capital requirements, regulatory thresholds, and absorption kinetics create divergent margin pools. Manufacturers configure enzymatic hydrolysis lines and membrane filtration capacity to serve distinct buyer specifications rather than universal commodity supply.
Product Type:
Capital intensity peaks with enzymatic processing infrastructure and peptide fractionation systems that smaller processors cannot finance.
- Hydrolyzed:Predigested peptide chains achieve 80-90% protein content with reduced allergenicity through controlled enzymatic treatment. Demand concentrates in United States sports nutrition channels where FDA labeling mandates favor transparent peptide sourcing and rapid absorption claims.
- Isolate:Cross-flow microfiltration yields 90%+ protein with minimal lactose and fat. United States functional beverage manufacturers specify isolate for clear protein RTDs where solubility and neutral flavor drive formulation decisions.
- Concentrate:Ultrafiltration produces 70-80% protein at lower processing cost. Cost-sensitive sports brands in emerging markets specify concentrate where absorption speed carries less clinical justification.
- Blends:Combinations balance cost, absorption kinetics, and mouthfeel. European processors blend hydrolyzed fractions with intact proteins to hit price points for mass-market powder SKUs.
Most installed capacity flows through Hydrolyzed. Expansion is steepest in Isolate as beverage applications multiply.
End User:
Volume distribution follows distinct consumption rituals and purchasing sophistication across user archetypes.
- Athletes:Collegiate and professional programs specify hydrolyzed formulations for post-workout windows where gastrointestinal stress limits intact protein tolerance. United States university athletic departments negotiate direct supply contracts bypassing retail markup.
- Bodybuilders:High-frequency consumption drives bulk purchasing and flavor fatigue tolerance. This segment absorbs commodity-grade hydrolyzed concentrate despite inferior peptide bioactivity versus pharmaceutical-grade alternatives.
- Fitness Enthusiasts:Weekend warriors and boutique gym members prioritize convenience and palatability over maximal absorption speed. Ready-to-drink formats capture disproportionate share versus powders.
- General Consumers:Aging populations and weight-management seekers enter via clinical recommendations or retail discovery. Hospital discharge protocols increasingly prescribe peptide-based home recovery nutrition.
Athletes command the highest per-capita spend. General Consumers are gaining share fastest as clinical channels expand.
Application:
Regulatory pathway complexity and reimbursement status fragment commercial access across use cases.
- Clinical Nutrition:Peptide-based enteral formulas serve post-surgical and ICU patients with compromised digestive function. United States hospital group purchasing organizations unbundle formula contracts from device agreements, forcing peptide specialists to compete on unit economics.
- Sports Nutrition:Post-workout recovery protocols dominate volume through established consumer familiarity. E-commerce direct-to-consumer subscriptions compress retail margin extraction.
- Dietary Supplements:Capsule and tablet formats target convenience-oriented users with lower daily dose requirements. FDA Current Good Manufacturing Practice audits extend time-to-market for novel peptide claims.
- Food & Beverages:Protein fortification of bars, baked goods, and dairy alternatives demands flavor masking and heat stability. Kerry Group competes on sensory systems that obscure hydrolyzed whey bitterness.
Sports Nutrition anchors installed capacity. Clinical Nutrition climbs the fastest as hospital procurement consolidates.
Grade:
Certification burden and audit intensity escalate pricing tiers by an order of magnitude.
- Pharmaceutical Grade:USP-NF monograph compliance and FDA Current Good Manufacturing Practice certification support neonatal and metabolic disorder applications. FDA audit timelines extend commercialization by months versus food-grade pathways.
- Food Grade:Standard safety and identity specifications capture dominant volume through sports nutrition and general food manufacturing. Membrane filtration scale-up enables mid-tier processors to enter this tier without legacy infrastructure.
- Feed Grade:Animal nutrition applications tolerate higher ash and mineral content with reduced peptide fractionation precision. Dairy processors divert substandard hydrolysis batches to feed channels.
- Others:Cosmetic and personal care applications utilize hydrolyzed whey for film-forming and moisturizing properties. REACH registration requirements for industrial enzyme formulations tighten European disclosure obligations.
Food Grade channels most production volume. Pharmaceutical Grade expands most quickly as neonatal formula applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as European REACH compliance costs push membrane filtration investments toward jurisdictions with streamlined enzyme registration pathways. Processors are relocating peptide fractionation capacity to exploit these cost-of-compliance gaps while maintaining quality equivalence.
United States
FDA Current Good Manufacturing Practice audits for dietary supplements are tightening peptide health claim substantiation requirements. Hospital group purchasing organizations in the Midwest and Southeast are unbundling enteral formula contracts from device agreements. Wisconsin and Idaho dairy processing clusters are expanding hydrolyzed whey output for sports nutrition brands seeking rapid-absorption formulations.
Germany
ECHA REACH registration requirements for industrial enzyme formulations are compressing approved supplier lists for protease vendors. Bavarian and North Rhine-Westphalian processors are qualifying pre-registered enzyme dossiers to maintain pharmaceutical-grade certification timelines. The country's membrane filtration infrastructure supports both food-grade and neonatal formula applications.
China
NMPA accelerated approval pathways for imported enteral formulas are opening procurement channels for peptide-based medical foods. Yangtze River Delta dairy processors are adopting continuous enzymatic hydrolysis systems to match European peptide bioactivity standards. Shanghai and Jiangsu province facilities are scaling ultrafiltration capacity for domestic sports nutrition brands.
India
CDSCO streamlined import regulations for clinical nutrition products are enabling hospital procurement of hydrolyzed whey-based enteral formulas. Maharashtra and Gujarat dairy cooperatives are investing in membrane filtration retrofit projects to enter pharmaceutical-grade supply tiers. Mumbai pharmaceutical clusters are partnering with European processors for peptide bioactivity validation expertise.
New Zealand
Fonterra's integrated farm-to-finished-ingredient supply chain controls disproportionate global hydrolyzed whey capacity. Waikato and Canterbury dairy processing regions anchor peptide fractionation infrastructure for North American and Asian export markets. The country's electricity rate structures from FERC-influenced grid pricing affect energy-intensive membrane filtration economics.
Hydrolyzed Whey Protein Market Vendor Landscape
New Zealand producers anchor one tier; European specialists hold certification-intensive positions; North American processors compete on flavor masking and beverage formulation integration. The market structure concentrates around integrated dairy cooperatives with captive milk supply and dedicated membrane filtration infrastructure. Three archetypes dominate: farm-to-ingredient integrators controlling raw material quality, peptide technology specialists investing in bioactivity validation, and sensory solution providers masking hydrolyzed protein bitterness. Competitive moves center on backward integration into milk supply and strategic partnerships with clinical trial institutions for health claim substantiation.
Within the integrated cooperative tier, Fonterra Co-operative Group and FrieslandCampina Ingredients exemplify the farm-to-finished-ingredient model with captive raw material control. Arla Foods Ingredients occupies a position representing European pharmaceutical-grade certification capabilities. These three entities anchor competitive dynamics through their respective geographic production networks and regulatory compliance infrastructures.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| FrieslandCampina Ingredients |
| Arla Foods Ingredients |
| NZMP |
| Agropur |
| Glanbia Nutritionals |
| Kerry Group |
| Carbery Group |
| Hilmar Ingredients |
| Others |
Supply Flow & Price Mechanics
Membrane filtration technicians in Wisconsin and Idaho command wage premiums that compress food-grade margins while pharmaceutical-grade spreads widen. Labor-cost differentials between these specialized dairy processing clusters and European counterparts with REACH compliance burdens feed directly into tiered pricing stratification across hydrolyzed whey grades.
Pricing Analysis
Distributor margins for ready-to-drink protein waters absorb 18-25 points before retail markup, while direct-to-OEM contracts for neonatal formula ingredients trade at steep discounts. Three-tier pricing structure across pharmaceutical, food, and feed grades separates USP-NF certified material from standard sports nutrition inputs and diverted substandard batches. Pricing pressure stems from whey protein concentrate substitution in cost-sensitive sports brands. Bodybuilders and bulk purchasers exhibit highest price sensitivity; hospital group purchasing organizations and neonatal formula manufacturers show lowest elasticity due to clinical protocol requirements.
Supply Chain Analysis
Regional distribution centers in Auckland, Waikato, and Canterbury anchor hub-and-spoke patterns radiating toward North American and Asian ports. New Zealand, Denmark, and the United States concentrate membrane filtration infrastructure for peptide fractionation. Raw material flows draw from integrated dairy cooperatives, protease enzyme suppliers with pre-registered REACH dossiers, and bipolar membrane electrodialysis systems. Single-source vulnerability concentrates in Fonterra's farm-to-finished-ingredient network. Distribution runs through specialized cold-chain logistics for pharmaceutical-grade material and standard freight for food-grade bulk powder.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA Current Good Manufacturing Practice audits for dietary supplements continuously ratchet peptide health claim substantiation thresholds, locking in demand for validated clinical trial infrastructure.
For Market Incumbents: Cement captive milk supply through cooperative equity structures in Wisconsin and Idaho processing clusters to defend against Fonterra's integrated cost position. Lock in peptide bioactivity validation partnerships with academic medical centers before CDSCO and NMPA accelerate enteral formula approval timelines in India and China, which will compress vendor qualification windows for clinical nutrition specialists lacking established clinical data packages. For New Entrants and Emerging Players: Boutique fitness enthusiasts seeking clear protein RTDs represent the most penetrable buyer archetype underserved by incumbent flavor masking capabilities. Target functional beverage co-manufacturers in the Yangtze River Delta with Kerry Group-competitive sensory systems. Enter through white-label partnerships for protein waters rather than competing directly for established sports nutrition powder shelf space. For Investors and Strategic Acquirers: Sports nutrition brands with direct-to-consumer subscription infrastructure are the most active acquirer in this space, seeking backward integration into peptide fractionation capacity. Position holdings for a 5-10 year window where hospital procurement consolidation favors dedicated medical food specialists over commodity whey suppliers attempting vertical moves. Monitor CDSCO and NMPA accelerated approval pathway implementation velocity as the critical inflection signal for clinical nutrition segment re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Bioactivity Validation Partnership | Academic medical center collaborations satisfy FDA health claim substantiation requirements ahead of competitor submissions. |
| Continuous Enzymatic Processing Retrofit | Real-time degree-of-hydrolysis monitoring from Danish and Dutch technology providers compresses production cycles versus batch systems. |
| Pharmaceutical Grade Certification Investment | USP-NF monograph compliance and FDA audit readiness unlocks neonatal formula premium pricing tiers. |
| Flavor Masking System Development | Kerry Group-competitive sensory solutions enable clear protein RTD expansion beyond traditional powder formats. |
| Membrane Filtration Capacity Expansion | Advanced ultrafiltration and nanofiltration systems reduce peptide fractionation costs for food-grade processors entering pharmaceutical tiers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with dairy processing plant managers, sports nutrition brand formulators, hospital procurement directors, and enteral formula regulatory affairs specialists informed demand-side assumptions. Secondary validation drew from FDA dietary supplement labeling guidance documents, ECHA REACH substance evaluation protocols, CDSCO clinical nutrition import regulations, and Fonterra cooperative financial disclosures. Bottom-up capacity modeling and top-down demand estimation triangulated volume figures.
Segment-weighting approaches distributed value across product type, end user, application, and grade dimensions with additional regional regulatory cluster differentiation. CAGRs derived from installed capacity expansion timelines, hospital procurement consolidation velocity, and functional beverage channel innovation rates across the projection horizon. Forecast inputs incorporated membrane filtration energy cost structures, enzyme registration compliance burdens, and peptide chain length assay standardization progress.
Inputs from regulatory filings and cooperative financial reports were available through the study window; gaps in real-time hospital procurement contract terms and proprietary peptide fractionation yield data introduce uncertainty bands around clinical nutrition segment projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Vitamin D Supplements Market
Nutritional Supplements
Europe Nutraceutical Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
Conjugated Linoleic Acid Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
North America Spirulina Extract Market