
 North America Whey Protein Market | 2026-2036
North America Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Whey Protein Market Intelligence
Canada is reshaping regional supply dynamics through expanded whey processing capacity at Quebec and Ontario dairy clusters. Glanbia plc leverages its ingredient technology platform to dominate isolate and hydrolyzed grades for sports nutrition formulators. Hilmar Cheese Company anchors West Coast supply with integrated cheese-making and whey recovery operations across California.
Whey protein comprises the soluble protein fraction separated during cheese manufacture, typically containing beta-lactoglobulin, alpha-lactalbumin, and immunoglobulins with protein concentrations ranging from 34% to 90% depending on processing intensity. Its primary commercial purpose centers on delivering complete amino acid profiles with rapid digestibility for muscle protein synthesis and satiety modulation. Whey Protein Isolate commands premium positioning due to higher purity and lower lactose content, while Hydrolyzed Whey Protein captures fastest growth in medical nutrition and infant formula applications where reduced allergenicity matters. Sports Nutrition end users generate the largest volume pull, though Functional Foods represents the emerging margin pool as CPG brands fortify mainstream grocery items.
FDA food additive regulations and USDA dairy plant inspection requirements govern manufacturing standards and interstate commerce eligibility across the United States. Health Canada and the Canadian Food Inspection Agency enforce parallel compositional standards that determine cross-border product equivalence and label claims validity. Stakeholders must monitor evolving protein content verification protocols and emerging state-level clean-label mandates that could reshape formulation requirements and sourcing specifications.
Market Dynamics
Dairy processing consolidation across the Upper Midwest and Great Plains is compressing whey supply chains into fewer integrated cheese-whey facilities, locking in volume commitments that reshape downstream ingredient availability for sports nutrition formulators.
Growth Catalysts
- Performance Nutrition Demand:Military procurement contracts and collegiate athletic programs are mandating higher-protein rations, pulling isolate-grade volumes through USDA-inspected channels into institutional foodservice.
- FDA Nutrition Labeling Modernization:Updated serving-size declarations and added-sugar line items are pushing CPG brands toward protein fortification as a clean-label strategy for macronutrient repositioning.
- Cross-Border Dairy Integration:USMCA tariff-rate quotas on Canadian skim milk powder are diverting Canadian fluid milk into cheese production, expanding whey byproduct recovery at Ontario and Quebec processing clusters.
Market Restraints
- Feed-Grade Whey Price Volatility:Chinese pig-herd restocking cycles and domestic ethanol policy swings create erratic demand for permeate and lower-grade concentrates, destabilizing processor margin pools.
- California Water Stress:Hilmar and Central Valley cheese-whey complexes face irrigation curtailments and discharge limits under State Water Resources Control Board regulations, capping expansion headroom.
- Plant Protein Substitution:Pea and fava protein isolates are capturing share in mass-market nutrition bars where complete amino acid profiles matter less than sustainability marketing claims.
Strategic Opportunities
- Medical Nutrition Formulation:Hydrolyzed whey fractions with reduced allergenic epitopes are penetrating enteral feeding and pediatric specialty nutrition, commanding 40-60% price premiums over standard concentrates.
- IRA Bioenergy Incentives:Biogas capture investments at large dairy-whey facilities qualify for production tax credits, offsetting anaerobic digester capital costs and lowering net energy inputs.
- DTC Subscription Channels:Direct-to-consumer isolate powders are bypassing brick-and-mortar sports nutrition retail, capturing recurring revenue with higher lifetime value than wholesale club distribution.
Industry Challenges
- Fractionation Specialist Shortage:Membrane filtration and chromatography technicians with dairy protein purification experience command 25-35% wage premiums over general food process operators, constraining plant utilization rates.
- Organic Certification Timelines:Transition periods for organic dairy sourcing stretch 24-36 months, locking processors out of fast-growing organic whey isolate segments despite demand pull.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Whey Protein Market |
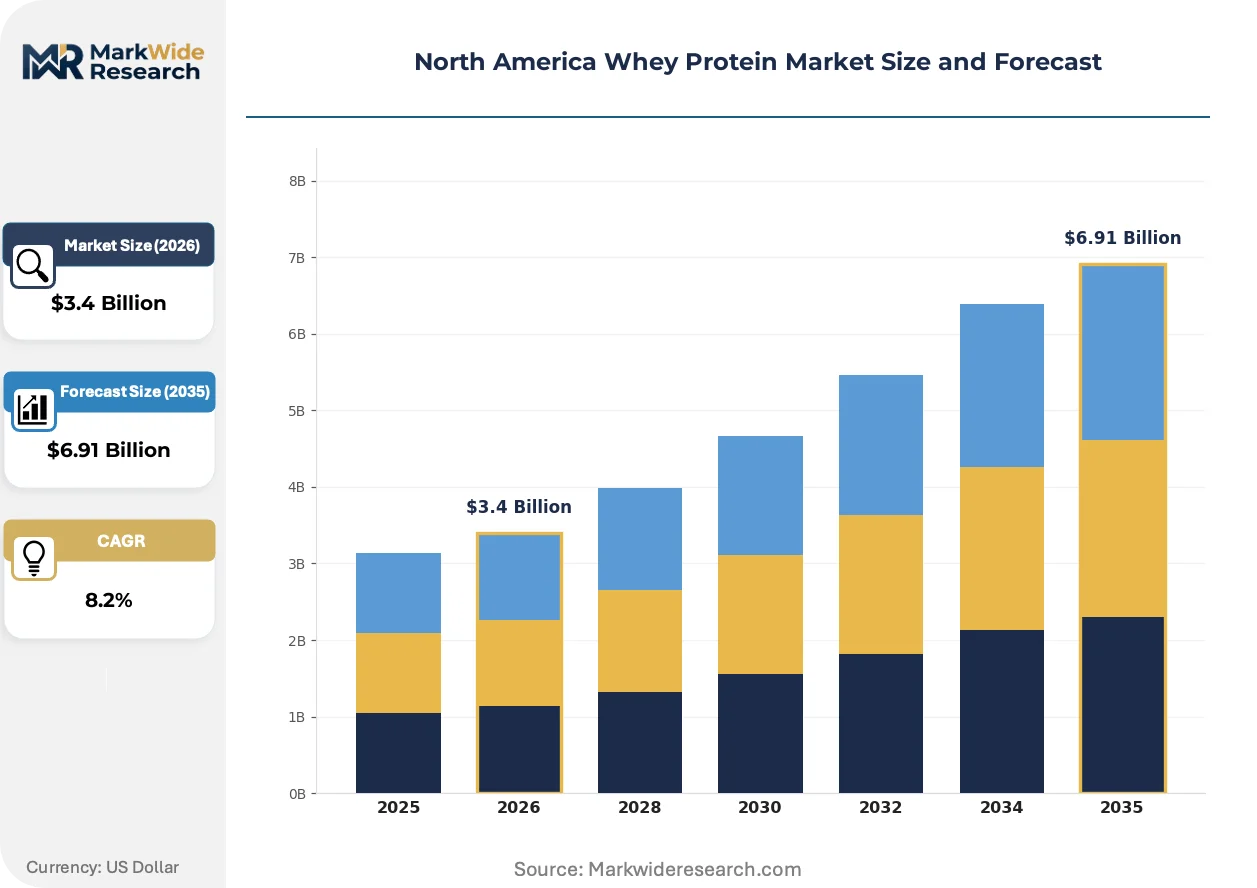
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.91 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Whey Protein Isolate, Hydrolyzed Whey Protein, Native Whey Protein End User: Sports Nutrition, Health Supplements, Functional Foods, Bakery Products Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Retailers Application: Muscle Recovery, Weight Management, Meal Replacement, Nutritional Beverages |
| Companies Covered | Fonterra Co-operative Group, Saputo Inc., Agropur Dairy Cooperative, Dairy Farmers of America, Arla Foods, Hilmar Cheese Company, Leprino Foods Company, Milk Specialties Global, Glanbia plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Whey Protein Market Strategic Shifts & Innovations
Membrane filtration advances and precision fermentation are compressing traditional whey processing economics while regulatory pressure on dairy sustainability metrics is forcing capital reallocation toward closed-loop water and energy systems.
Microfiltration-integrated ultrafiltration trains with ceramic membrane cascades are rendering obsolete older polymeric spiral-wound systems for native whey protein recovery. Sports nutrition contract manufacturers in Utah and Idaho are retrofitting plants at 18-month payback periods. This technology shift is concentrating premium isolate production among facilities with sufficient scale to amortize ceramic capital costs.
Health Canada's proposed front-of-package nutrition symbol regulations are forcing reformulation across imported and domestically produced protein-fortified foods. Products exceeding saturated fat thresholds lose shelf positioning regardless of protein content. US exporters are adjusting fat-standardized whey protein concentrate specifications to maintain Canadian retail eligibility.
Brand procurement teams are consolidating supplier panels from 8-12 vendors to 3-4 strategic partners with verified carbon accounting and regenerative dairy sourcing. This consolidation is most visible in Pacific Northwest and Northeast metro markets where B-Corp certification and Scope 3 disclosure requirements filter RFP eligibility. Long-term offtake agreements with fixed volume tiers are replacing spot-market purchasing for core isolate grades.
North America Whey Protein Market Segmentation
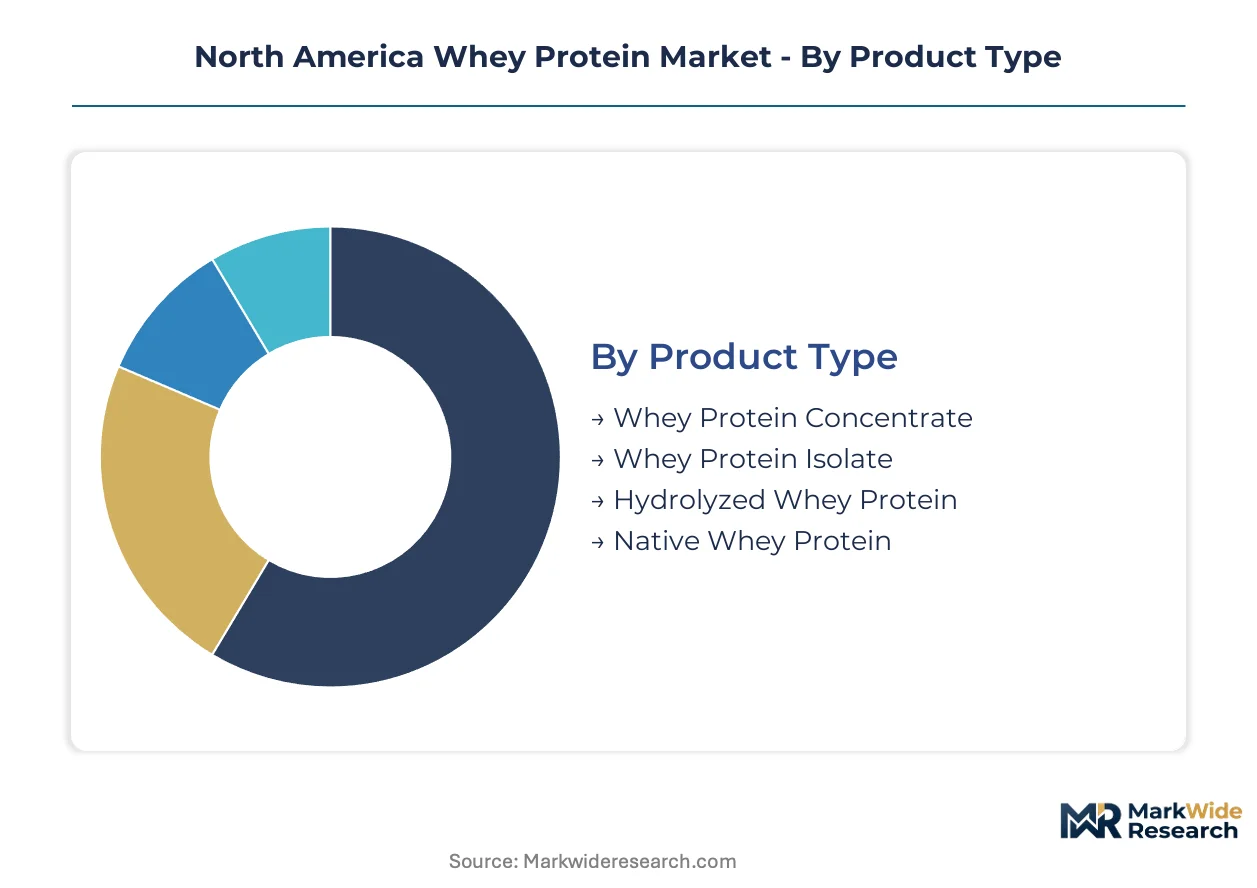
Product differentiation across whey protein grades demands distinct technical support protocols, with isolate and hydrolyzed variants requiring formulation guidance that concentrates and native forms rarely need. Segmentation clarity enables procurement teams to align supplier capabilities with end-use performance requirements.
Product Type:
After-sales intensity escalates with protein purity, as isolate and hydrolyzed grades require dedicated application laboratories to troubleshoot solubility and flavor masking in finished products.
- Whey Protein Concentrate:Contains 34-80% protein with retained lactose and lipids, delivering cost-efficient amino acid fortification for mass-market nutrition bars and ready-to-mix powders. Demand concentrates in value-positioned sports nutrition SKUs sold through warehouse clubs across the Upper Midwest, where price elasticity exceeds performance sensitivity.
- Whey Protein Isolate:Achieves 90%+ protein content through additional microfiltration and ion exchange, eliminating most lactose and fat for consumers with dairy sensitivities. Premium positioning in United States military procurement contracts and collegiate athletic programs mandates USDA-inspected processing and lot-level certificate of analysis documentation.
- Hydrolyzed Whey Protein:Pre-digested via enzymatic hydrolysis into smaller peptides for accelerated absorption and reduced allergenic potential. Medical nutrition formulators in pediatric and enteral feeding applications command 40-60% price premiums over standard concentrates.
- Native Whey Protein:Separated from fresh milk via microfiltration rather than cheese whey recovery, preserving undernatured protein structures and superior leucine bioavailability. Emerging demand from clean-label brands in Pacific Northwest metro markets seeking differentiation from commodity cheese-derived supply chains.
Whey Protein Concentrate holds the largest share; momentum sits with Hydrolyzed Whey Protein.
End User:
Cost tier stratification separates institutional volume buyers from premium direct-to-consumer brands, with sports nutrition commanding the steepest volume discounts and functional foods extracting the highest per-kilogram margins.
- Sports Nutrition:Protein powders, pre-workout formulations, and recovery drinks targeting athletes and fitness enthusiasts generate the largest absolute volume pull through the United States and Canada. Military and collegiate procurement contracts mandate isolate-grade specifications with verified banned-substance testing protocols.
- Health Supplements:Capsule and tablet applications targeting general wellness consumers emphasize digestibility claims and third-party certification. Distribution through practitioner channels in Ontario and British Columbia requires Health Canada Natural Product Number registration.
- Functional Foods:Protein fortification of mainstream grocery items including yogurt, cereal, and snack bars represents the emerging margin pool as CPG brands reposition macronutrient profiles. FDA Nutrition Labeling Modernization rules are accelerating reformulation timelines.
- Bakery Products:Whey proteins enhance dough handling, moisture retention, and Maillard browning in high-protein bread and pastry applications. Regional bakeries in Quebec leverage local dairy processing clusters for fresh whey concentrate supply.
Sports Nutrition holds the largest share; Functional Foods is climbing the fastest.
Distribution Channel:
Customer type fragmentation separates recurring subscription buyers from transactional retail purchasers, with lifetime value calculations favoring direct-channel investments over wholesale margin compression.
- Online Retail:Direct-to-consumer isolate powders bypass brick-and-mortar sports nutrition retail, capturing recurring revenue through subscription models. Utah and Idaho contract manufacturers operate dedicated fulfillment infrastructure for influencer-brand launches.
- Supermarkets:Mass-market protein fortification in conventional grocery channels depends on price-competitive concentrate grades with extended shelf stability. California retailers face supply constraints from Central Valley water stress affecting Hilmar Cheese Company production.
- Health Food Stores:Specialty retailers emphasize organic certification and regenerative dairy sourcing credentials that command 15-25% shelf price premiums. Pacific Northwest and Northeast metro markets filter RFP eligibility through B-Corp certification requirements.
- Specialty Retailers:Dedicated sports nutrition stores provide formulation consultation and flavor sampling that online channels cannot replicate. Canadian cross-border shoppers access United States SKUs through Detroit and Buffalo retail corridors.
Online Retail holds the largest share; Health Food Stores is gaining share fastest.
Application:
Supply concentration in medical nutrition and performance applications diverges from commodity beverage fortification, with fractionation specialists allocating ceramic membrane capacity to highest-margin segments.
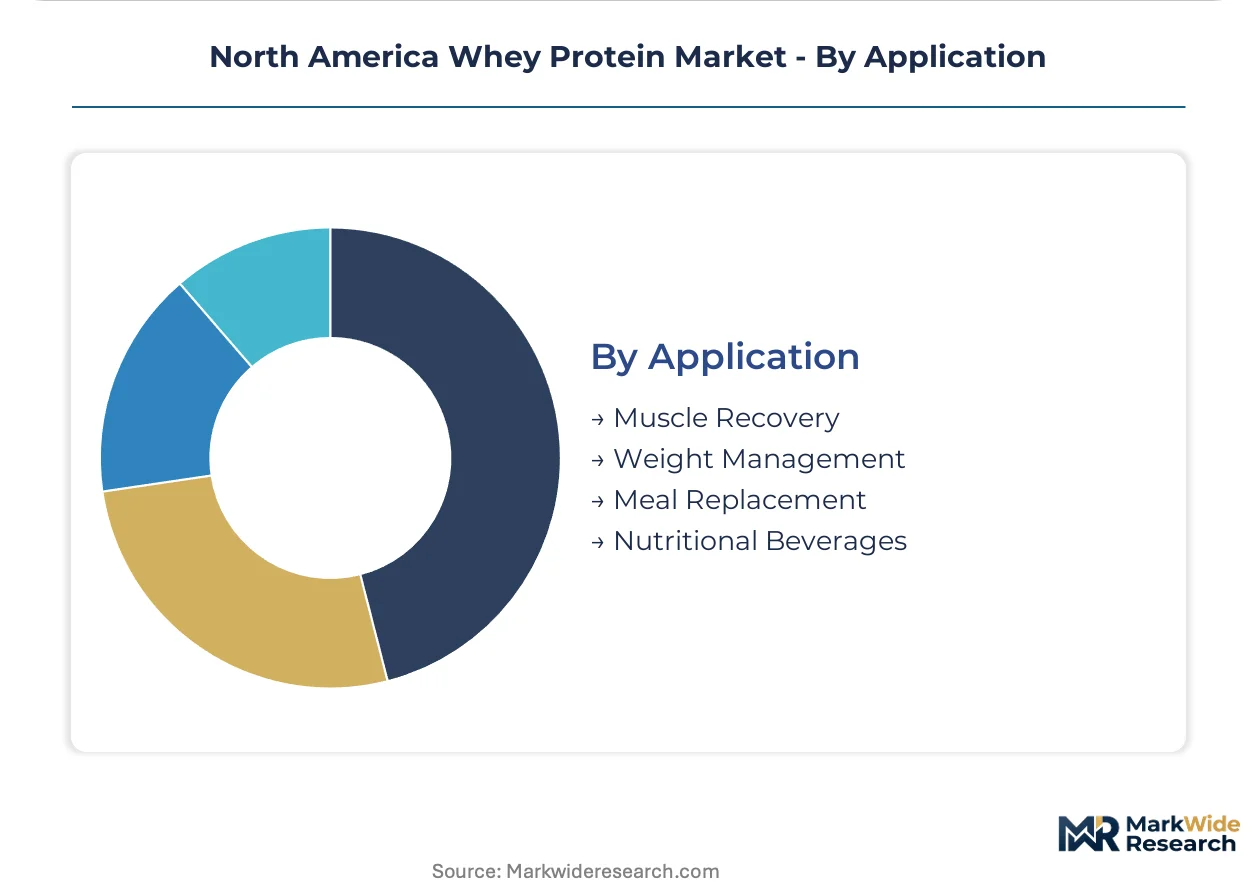
- Muscle Recovery:Rapidly absorbed whey fractions consumed within two hours post-exercise dominate sports nutrition formulation. Collegiate athletic programs across Texas and Florida mandate NSF Certified for Sport verification for all protein supplements.
- Weight Management:High-satiety protein fortification in meal replacements and portion-controlled snacks leverages whey's glucagon-like peptide-1 stimulation. Functional food brands reformulate to meet Health Canada front-of-package saturated fat thresholds.
- Meal Replacement:Complete macronutrient profiles with 20-30g protein per serving require flavor-stable isolate or hydrolyzed grades to mask off-notes in shelf-stable formats. Medical nutrition enteral feeding applications command stringent microbial specifications.
- Nutritional Beverages:Ready-to-drink protein shakes depend on cold-aseptic processing and extended shelf-life stability that concentrates struggle to deliver. California and New York beverage co-packers prioritize isolate supply for premium positioning.
Muscle Recovery holds the largest share; Nutritional Beverages shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Whey protein supply chains concentrate in dairy processing corridors where cheese-whey integration creates captive ingredient streams. FDA and USDA oversight governs interstate commerce eligibility, while Health Canada enforces parallel standards that determine cross-border product equivalence.
United States
Military procurement contracts and collegiate athletic programs mandate isolate-grade specifications with verified banned-substance testing protocols. FDA Nutrition Labeling Modernization rules accelerate CPG reformulation timelines toward protein fortification. Hilmar Cheese Company anchors West Coast supply through integrated cheese-making and whey recovery operations across California's Central Valley.
Canada
Quebec and Ontario dairy clusters expand whey processing capacity to reshape regional supply dynamics for North American formulators. Health Canada front-of-package nutrition symbol regulations force fat-standardized whey protein concentrate adjustments to maintain retail eligibility. Cross-border dairy integration under USMCA tariff-rate quotas diverts Canadian fluid milk into cheese production, expanding whey byproduct recovery.
Mexico
Industrial bakeries and nutritional beverage co-packers in Mexico City Metro and Nuevo León drive concentrate-grade demand for cost-efficient amino acid fortification. Mexican food safety authority COFEPRIS enforces compositional standards that align with FDA dairy plant inspection requirements. Bajío Region dairy cooperatives are upgrading filtration capacity to supply regional sports nutrition contract manufacturers.
North America Whey Protein Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in ingredient purification and fractionation. The vendor base spans integrated dairy cooperatives with captive whey streams, independent processors with membrane filtration expertise, and ingredient technology platforms serving sports nutrition formulators. Strategic archetypes include cheese-whey integrators, isolate-grade specialists, and medical nutrition fractionators. Competitive moves concentrate on ceramic membrane capacity expansion and long-term offtake agreements with fixed volume tiers.
Among North American dairy cooperatives, Fonterra Co-operative Group and Dairy Farmers of America exemplify scale-driven cheese-whey integration that locks in downstream ingredient availability. Glanbia plc occupies a position within the isolate and hydrolyzed grade specialist tier, leveraging ingredient technology platforms for sports nutrition formulators. These three represent distinct competitive archetypes: cooperative ownership structures, private processor scale, and premium-grade technology platforms.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Saputo Inc. |
| Agropur Dairy Cooperative |
| Dairy Farmers of America |
| Arla Foods |
| Hilmar Cheese Company |
| Leprino Foods Company |
| Milk Specialties Global |
| Glanbia plc |
| Others |
Cost & Logistics Intelligence
California's Central Valley cheese-whey complexes anchor North American isolate-grade supply, with Hilmar Cheese Company's integrated operations translating captive milk flows into pricing leverage over West Coast sports nutrition formulators. Water stress under State Water Resources Control Board regulations tightens expansion headroom, compressing spot-market availability and amplifying contract premiums for USDA-inspected volumes.
Pricing Analysis
FDA Nutrition Labeling Modernization dictates the pricing tier structure across concentrate, isolate, and hydrolyzed grades, with protein purity thresholds separating premium positioning from mass-market penetration. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence—NSF Certified for Sport verification commands 15-25% uplifts—while volume scale discounts concentrate in military and collegiate procurement channels. Cost compression in concentrate grades intensifies because Chinese pig-herd restocking cycles destabilize permeate offtake. Mass-market nutrition bars sold through warehouse clubs exhibit highest price sensitivity; medical nutrition formulators show least.
Supply Chain Analysis
Fluid milk availability from Upper Midwest dairy cooperatives, Quebec and Ontario processing clusters, and California's Central Valley anchors upstream feedstock security for North American whey fractionation. Membrane filtration equipment, ceramic membrane cascades, and enzymatic hydrolysis capacity constitute critical processing dependencies. Single-source vulnerability concentrates in ceramic membrane supply chains dominated by European and Japanese equipment vendors. Distribution runs through integrated cheese-whey facilities with captive ingredient streams, supplemented by independent processors with toll-manufacturing arrangements for isolate and hydrolyzed grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment—FDA and USDA inspection requirements create multi-year qualification barriers that lock out unapproved facilities and protect incumbent volume positions.
For Market Incumbents: Pre-empt plant protein substitution threats by securing long-term offtake agreements with regenerative dairy cooperatives in the Pacific Northwest, locking in carbon-accounting credentials that pea and fava isolates cannot replicate. Add ceramic membrane capacity at existing Utah and Idaho facilities before equipment lead times extend further, capturing hydrolyzed-grade premiums from medical nutrition formulators.
For New Entrants and Emerging Players: Pursue native whey protein positioning through direct microfiltration from fresh milk rather than cheese-whey recovery, targeting clean-label brands in Pacific Northwest metro markets willing to pay differentiation premiums. Enter through DTC subscription channels with influencer-brand partnerships, bypassing retail slotting fees that compress margins for wholesale club distribution.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because dairy processing consolidation across the Upper Midwest and Great Plains is compressing whey supply chains into fewer integrated facilities with captive downstream streams. Target acquisition candidates among independent membrane filtration specialists with Health Canada registration and existing sports nutrition contract manufacturing relationships. Watch ceramic membrane capacity utilization rates as the inflection signal—sustained above 85% indicates pricing power shift toward fractionation-constrained grades.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Membrane Capacity Expansion | Utah and Idaho retrofit investments capture 18-month payback periods while rendering polymeric systems obsolete. |
| Regenerative Dairy Sourcing Partnerships | Pacific Northwest B-Corp certification requirements filter RFP eligibility and command 15-25% shelf price premiums. |
| Medical Nutrition Grade Certification | Health Canada Natural Product Number registration opens practitioner channel distribution in Ontario and British Columbia. |
| Direct-to-Consumer Subscription Launch | Influencer-brand fulfillment infrastructure bypasses brick-and-mortar retail margin compression. |
| Biogas Capture Investment | IRA production tax credits offset anaerobic digester capital costs at large dairy-whey facilities. |
Research Approach
A standing panel of sports nutrition formulators, membrane filtration plant managers, Health Canada regulatory affairs specialists, and military procurement officers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA food additive regulation filings, USDA dairy plant inspection records, Health Canada front-of-package nutrition symbol proposals, and USMCA tariff-rate quota administration data. Bottom-up volume modeling triangulated against top-down protein fortification trend analysis.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product grade tier, end-use application, distribution channel type, and regional regulatory cluster. CAGRs derived from protein content verification protocol evolution and clean-label mandate diffusion curves. Forecast inputs incorporated collegiate athletic program procurement contract volumes and CPG reformulation timelines under FDA Nutrition Labeling Modernization.
Macroeconomic conditions sit as an overlay; deviation in dairy commodity price cycles, Chinese feed-grade whey import demand, or California water allocation rulings would shift the trajectory. Cross-checking against USDA National Agricultural Statistics Service dairy production benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
South Africa Collagen Peptides Market
Nutritional Supplements
Plant Based Iron Supplements Market
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Europe Nutrition and Supplements Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
Vitamin B12 Market
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Stress Relief Supplements Market