
 Whey Protein Concentrate Market | 2026-2036
Whey Protein Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Whey Protein Concentrate Market Outlook
Multi-source dairy procurement is repositioning supply strategies across the whey protein concentrate value chain. FrieslandCampina leverages its cooperative milk collection network across Northern Europe to secure raw material continuity. Glanbia Nutritionals anchors its ingredient supply through captive whey streams from Irish and US cheese operations. Arla Foods Ingredients competes on fractionation technology leadership, extending its protein purity capabilities into medical and infant nutrition grades.
Whey protein concentrate denotes a dairy-derived ingredient containing 34–80% protein by dry weight, obtained through ultrafiltration of cheese whey followed by spray drying to preserve functional properties such as emulsification and water-binding capacity. Protein supplements and dietary products dominate application volumes, though bakery goods represent the fastest-growing outlet as manufacturers reformulate for protein fortification in clean-label baked items. The concentrate segment itself commands the largest volume share among product types, while hydrolysate extracts premium pricing from clinical and specialized sports nutrition channels.
FDA nutrition labeling rules and EFSA health claim assessments shape permissible marketing language and product positioning across the United States and European Union, directly influencing R&D investment in clinical substantiation. China's SAMR and national food safety standards impose additional registration requirements on imported whey ingredients, filtering market access for non-domestic suppliers. Stakeholders must monitor evolving protein content thresholds and allergen disclosure mandates as regulatory divergence between major import jurisdictions intensifies compliance complexity.
Market Dynamics
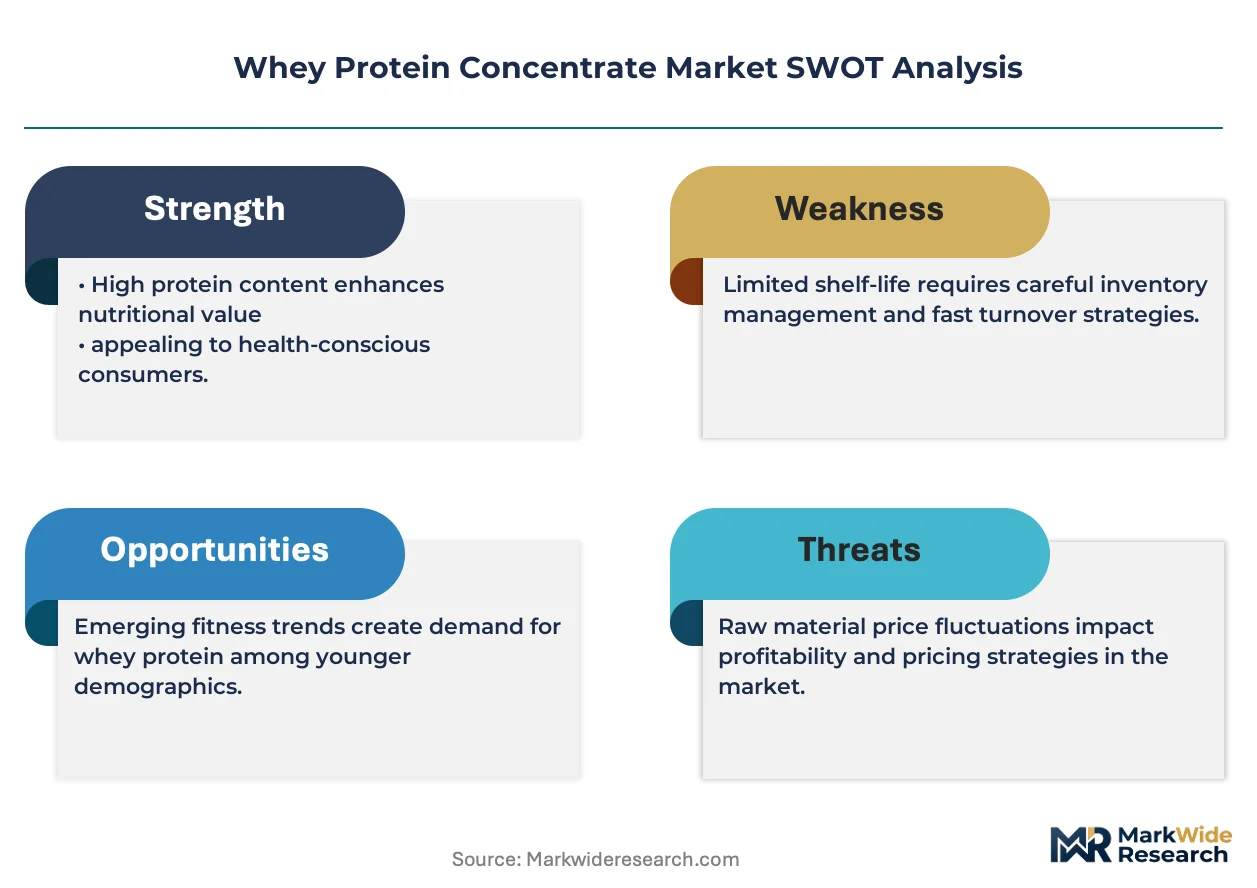
Clean-label formulation mandates from major retailers are compressing ingredient qualification timelines, forcing whey protein concentrate suppliers to accelerate certification documentation and traceability system investments.
Growth Catalysts
- Sports Nutrition Expansion:Functional beverage manufacturers in Germany and the United States are absorbing larger concentrate volumes for ready-to-drink protein formulations. EFSA health claim substantiation requirements are driving clinical investment that opens premium positioning.
- Bakery Protein Fortification:Clean-label bread and snack producers reformulate with whey concentrates to achieve protein content claims without synthetic additives. This application channel accelerates faster than traditional supplements.
- China SAMR Registration Pathways:Streamlined import registration for whey-derived ingredients is reducing market access friction for compliant foreign suppliers. Domestic gym penetration growth sustains underlying demand.
Market Restraints
- Milk Price Volatility:Raw milk input costs fluctuate with European Union dairy policy adjustments and New Zealand auction cycles, compressing margin predictability for non-integrated processors.
- Supply Concentration Risk:Fractionation technology leadership clusters among Irish and Dutch cooperative processors, creating bottleneck vulnerability for specialized medical-grade concentrates.
- Plant Protein Substitution:Pea and rice protein isolates achieve price parity in select sports nutrition segments, displacing whey concentrates in vegan-positioned product lines.
Strategic Opportunities
- Medical Nutrition Underpenetration:Clinical enteral and infant nutrition grades command premium pricing with limited qualified supply. Arla Foods Ingredients extends fractionation capabilities into these regulated segments.
- EU Green Deal Alignment:Dairy processors investing in methane reduction and renewable energy certification access preferential procurement terms from sustainability-scored food manufacturers.
- Direct-to-Consumer Channel Expansion:Sports nutrition brands bypass traditional distribution through subscription models, creating demand for customized concentrate blends with shorter lead times.
Industry Challenges
- Allergen Disclosure Complexity:Divergent lactose threshold definitions between FDA, EFSA, and China's GB standards force parallel label configurations and increase compliance documentation burden.
- Fractionation Talent Scarcity:Specialized membrane process engineering expertise concentrates among veteran technicians at established European suppliers, constraining capacity expansion at newer facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whey Protein Concentrate Market |
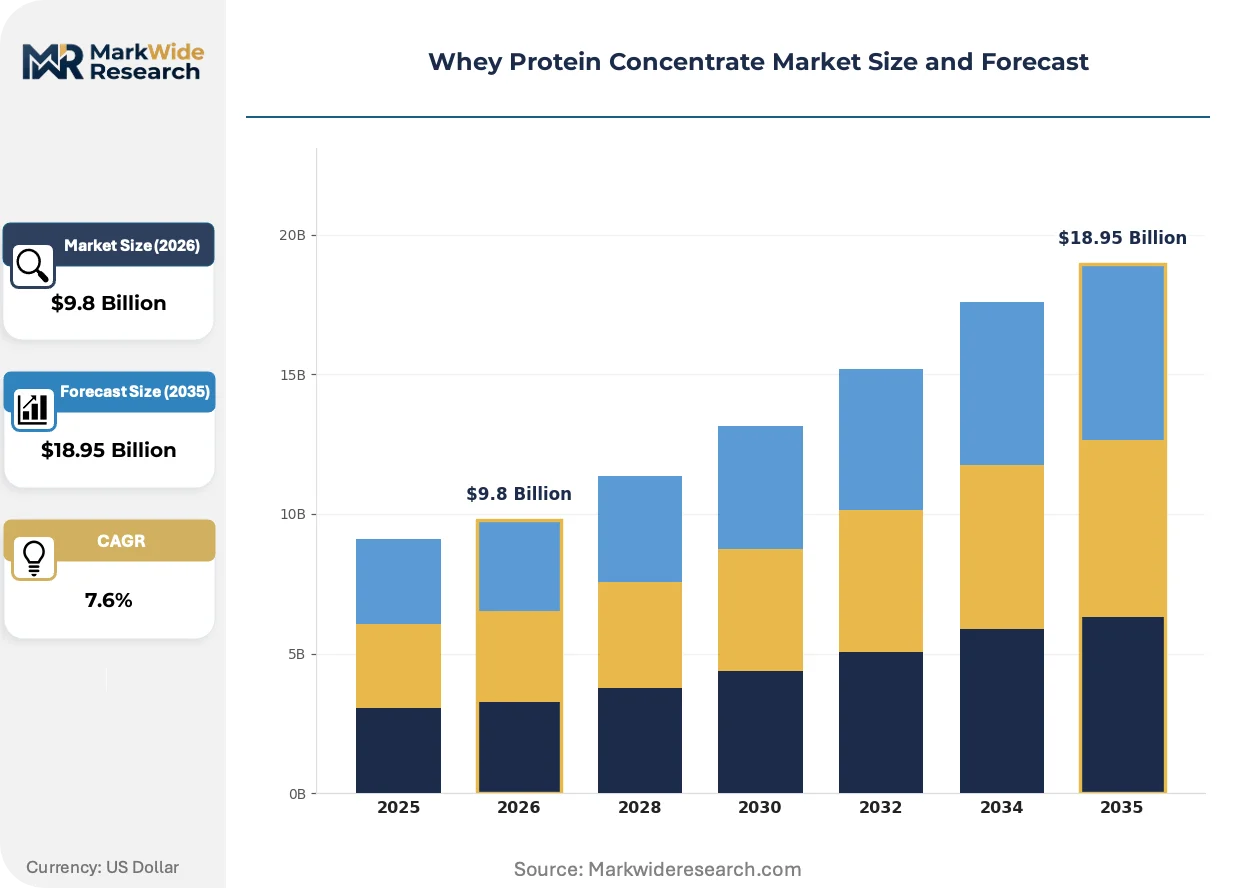
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolysate, Native End User: Fitness Enthusiasts, Bodybuilders, Athletes, Food Industry Application: Protein Supplements, Dietary Products, Bakery Goods, Beverages Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Hilmar Cheese Company, FrieslandCampina, Arla Foods Ingredients, Milk Specialties Global, Saputo Inc., Glanbia Nutritionals, Lactalis Ingredients, Carbery Group, Fonterra Co-operative Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whey Protein Concentrate Market Strategic Shifts
Membrane filtration advances and regulatory claim substantiation requirements are restructuring how whey protein concentrate suppliers differentiate and capture value across application segments.
Microfiltration and ultrafiltration system architectures are modularizing, enabling processors to reconfigure protein separation trains without complete line replacement. Bakery and beverage manufacturers adopt these flexible systems to switch between 34% and 80% protein grades based on formulation requirements. Equipment modularity is compressing capital recovery timelines and lowering entry barriers for mid-scale regional processors.
EFSA health claim assessments and FDA nutrition labeling rules are tightening permissible marketing language for protein content and muscle maintenance claims. Clinical substantiation investments now precede product launch rather than follow market entry. Sports nutrition brands operating across United States and European Union markets maintain parallel regulatory affairs teams to manage divergent approval timelines.
Subscription-based replenishment models are displacing traditional retail replenishment in direct-to-consumer sports nutrition channels. Younger demographic segments in United States metropolitan markets prioritize convenience and personalization over pharmacy and supermarket availability. This channel rotation concentrates volume with brands capable of customized flavor and protein concentration configurations.
Whey Protein Concentrate Market Segmentation
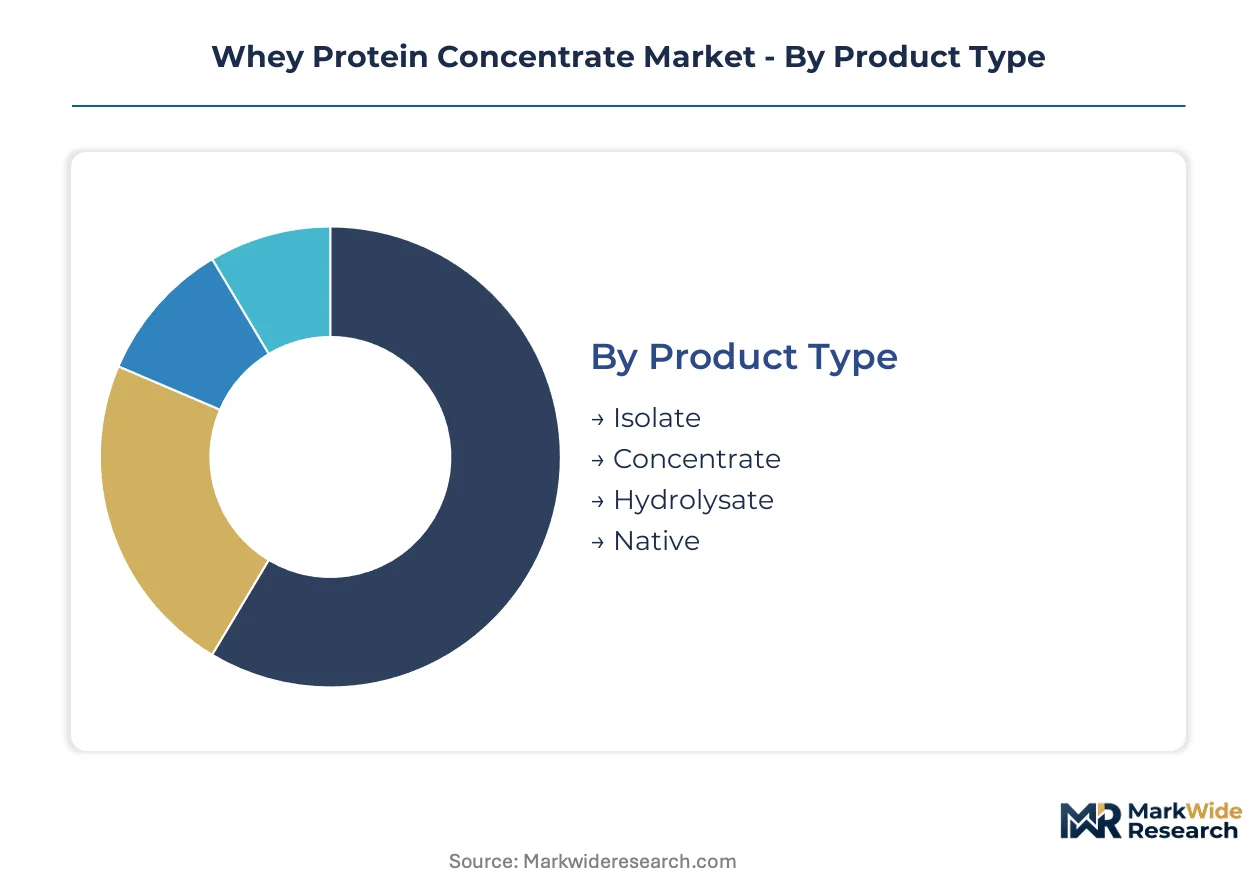
Protein concentration thresholds and fractionation capabilities determine supplier positioning across application tiers. Segmentation reveals where membrane technology investments concentrate and which channels absorb premium versus commodity grades.
Product Type:
Supply concentration clusters around processors with captive whey streams and fractionation expertise in Ireland and the Netherlands.
- Concentrate:Contains 34–80% protein by dry weight through ultrafiltration and spray drying. Bakery reformulation in Germany and the United States absorbs the largest volumes as clean-label protein fortification accelerates.
- Isolate:Achieves 90%+ protein purity via additional microfiltration and ion exchange steps. Sports nutrition brands in China pay premium pricing for EFSA-substantiated muscle maintenance claims.
- Hydrolysate:Pre-digested peptide forms for rapid absorption.
- Native:Cold-processed undenatured protein preserving bioactive fractions.
Concentrate absorbs the bulk of installed capacity; isolate is expanding most quickly.
End User:
Cost tier differentiation separates clinical-grade purchasers from mass-market consumers.
- Fitness Enthusiasts:Recreational exercisers seeking convenient protein supplementation. Direct-to-consumer subscription channels in United States metropolitan markets capture this demographic with customized flavor configurations.
- Bodybuilders:High-volume protein consumers prioritizing cost-per-gram efficiency. Online retail concentrates demand for bulk concentrate formats.
- Athletes:Competitive performers requiring batch-tested, contaminant-free products.
- Food Industry:Manufacturers reformulating for protein content claims without synthetic additives.
Fitness enthusiasts absorb the bulk of volume; food industry adoption is climbing the fastest.
Application:
Volume distribution reflects shifting reformulation priorities across packaged food categories.
- Protein Supplements:Powder and ready-to-drink formats dominate traditional sports nutrition. United States and German functional beverage manufacturers source concentrate for clean-label formulations.
- Bakery Goods:Bread and snack producers achieve protein fortification without texture degradation. This segment gains share fastest as retail clean-label mandates compress ingredient qualification timelines.
- Dietary Products:Meal replacement and weight management formulations.
- Beverages:Protein-fortified dairy alternatives and functional drinks.
Protein supplements absorb the bulk of volume; bakery goods is gaining share fastest.
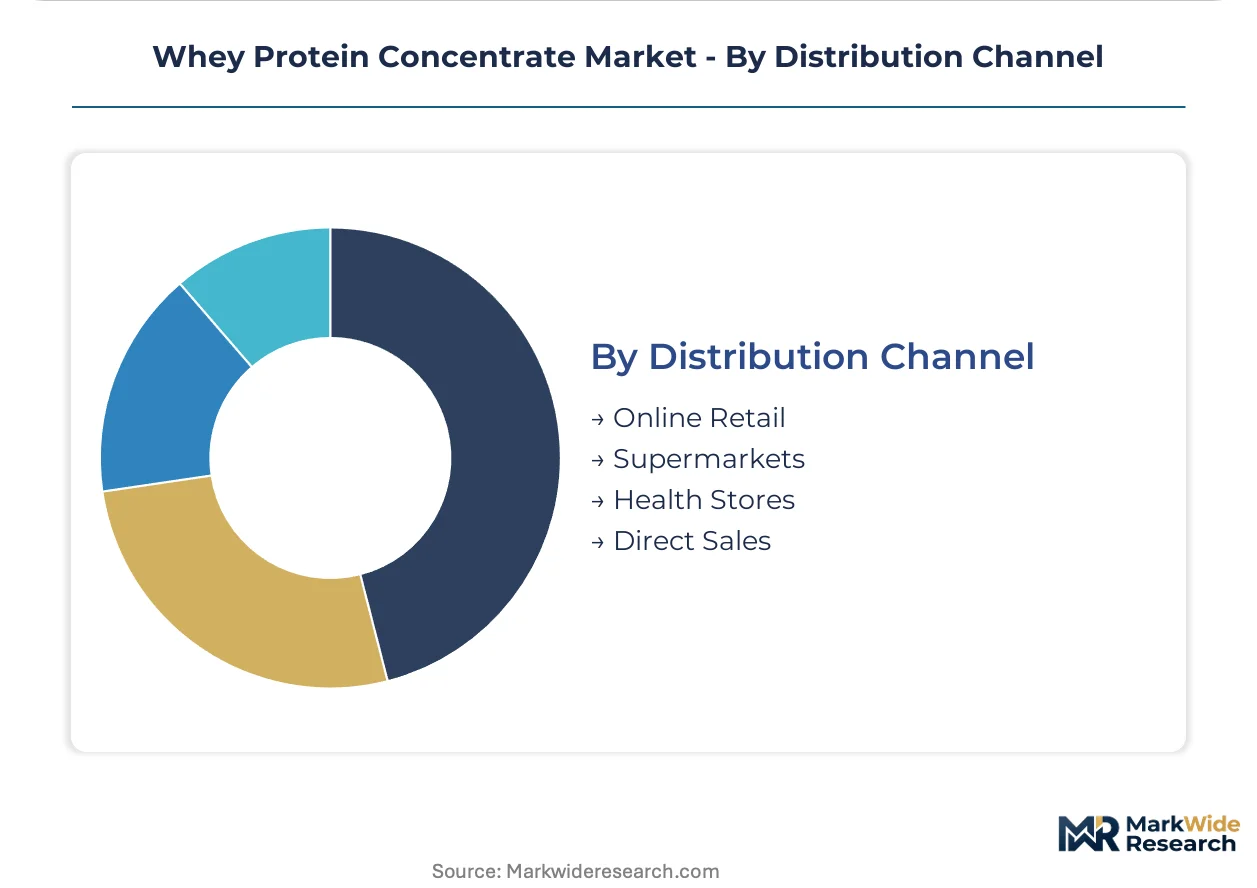
Distribution Channel:
Customer type fragmentation is restructuring procurement relationships and margin capture.
- Online Retail:E-commerce platforms and brand-direct websites. Subscription replenishment models in United States metropolitan markets displace traditional pharmacy and supermarket availability.
- Supermarkets:Mass-market retail requiring economy-tier pricing and large-format packaging.
- Health Stores:Specialty retailers emphasizing premium positioning and staff expertise.
- Direct Sales:Network marketing and institutional procurement.
Online retail absorbs the bulk of growth investment; health stores maintain the steepest margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Irish and Dutch dairy cooperatives anchor the whey protein concentrate supply base through captive whey streams from cheese manufacturing. German bakery reformulation and United States sports nutrition absorption drive demand concentration. China's SAMR registration pathways filter import access for foreign suppliers.
United States
Functional beverage manufacturers in California and Texas absorb concentrate volumes for ready-to-drink protein formulations. FDA nutrition labeling rules tighten permissible marketing language for muscle maintenance claims. Chicago and Denver metropolitan markets sustain direct-to-consumer subscription channel growth for customized concentrate blends.
Germany
Clean-label bread and snack producers in Bavaria and North Rhine-Westphalia reformulate with whey concentrates for protein fortification. EFSA health claim assessments require clinical substantiation investments before product launch. The Munich industrial cluster concentrates sports nutrition brand headquarters and formulation R&D facilities.
China
Gym penetration growth in Shanghai and Beijing sustains underlying demand for protein supplementation. SAMR streamlined import registration reduces market access friction for compliant foreign suppliers. The Yangtze River Delta cluster concentrates domestic whey processing capacity and functional food innovation labs.
Netherlands
FrieslandCampina's cooperative milk collection network secures raw material continuity across Northern European dairy farms. EU Green Deal methane reduction requirements shape processor investment in renewable energy certification. The Wageningen food technology corridor anchors fractionation research and medical-grade protein development.
Ireland
Glanbia Nutritionals anchors ingredient supply through captive whey streams from domestic and US cheese operations. Arla Foods Ingredients extends fractionation capabilities into infant and clinical nutrition grades. The Cork-Kerry dairy belt concentrates specialized membrane process engineering expertise among established suppliers.
Whey Protein Concentrate Market Competitive Environment
Global majors compete with regional champions across fractionation technology and captive whey access. The market structure tiers between integrated dairy cooperatives with backward control over milk supply and independent processors dependent on spot whey procurement. Two archetypes dominate: cooperative-owned entities leveraging collective milk collection networks, and publicly traded nutrition specialists optimizing ingredient yield from cheese manufacturing byproducts. Competitive moves concentrate on membrane technology licensing partnerships and medical-grade certification expansion.
Within the cooperative archetype, FrieslandCampina and Fonterra Co-operative Group exemplify member-owned structures securing raw material continuity across Northern Europe and Oceania dairy belts. Among publicly traded specialists, Glanbia Nutritionals occupies a position representing the ingredient optimization model. Arla Foods Ingredients sits within the fractionation technology leadership tier, extending capabilities into regulated medical and infant nutrition segments where protein purity thresholds command premium positioning.
| Leading Market Players |
|---|
| Hilmar Cheese Company |
| FrieslandCampina |
| Arla Foods Ingredients |
| Milk Specialties Global |
| Saputo Inc. |
| Glanbia Nutritionals |
| Lactalis Ingredients |
| Carbery Group |
| Fonterra Co-operative Group |
| Others |
Value Chain & Pricing Dynamics
Sports nutrition brands in Germany and the United States concentrate procurement volume and dictate contract structures. Their scale advantages compress supplier margins while rewarding certification investment with preferred supplier status.
Pricing Analysis
Certification bundling separates qualified suppliers from commodity traders, with EFSA-substantiated health claims and organic credentials commanding premium positioning. Three-tier pricing structure across medical-grade, sports nutrition, and economy bakery tiers reflects protein purity thresholds and clinical documentation depth. Cost compression in standard concentrate grades intensifies because plant protein isolates achieve parity in select vegan-positioned segments. Bodybuilders purchasing bulk formats exhibit highest price sensitivity, while clinical nutrition purchasers prioritize batch consistency over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from major sports nutrition brands mandate parallel qualification of Irish and Dutch cooperative processors alongside independent North American suppliers. Raw material flows draw from captive whey streams in Ireland, the Netherlands, and the United States, with spot market dependence creating vulnerability during New Zealand auction volatility. Single-source vulnerability concentrates in specialized membrane filtration equipment and veteran process engineering talent. Distribution runs through cooperative-owned collection networks feeding fractionation facilities, then onward to direct-to-consumer subscription channels and bakery ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration modularity is displacing fixed-line configurations, forcing legacy processors to reconfigure separation trains or cede reformulation-flexible accounts to adaptable competitors.
For Market Incumbents: Anchor medical-grade certification expansion against plant protein substitution threats in premium sports nutrition. Deepen backward integration into captive whey streams through cheese operation partnerships or cooperative membership expansion. Accelerate traceability system investment to meet compressed retailer qualification timelines. For New Entrants and Emerging Players: Enter via bakery protein fortification segments where clean-label mandates outpace incumbent certification documentation capacity. Target mid-scale regional processors in China seeking SAMR-compliant import partnerships. Pursue equipment modularity licensing to capture reformulation-flexible accounts without full fractionation facility capital requirements. For Investors and Strategic Acquirers: The window for entry favors membrane technology specialists with modular system architectures and medical-grade regulatory affairs capabilities. Acquisition candidates demonstrate installed fractionation capacity in underpenetrated clinical nutrition segments. Watch EFSA health claim approval velocity as inflection indicator for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Grade Certification Expansion | Arla Foods Ingredients extends fractionation capabilities into infant and clinical nutrition segments commanding premium positioning. |
| Membrane System Modularity Investment | Equipment reconfigurability enables processors to switch between protein grades without complete line replacement. |
| Cooperative Milk Network Integration | FrieslandCampina leverages collective collection across Northern Europe to secure raw material continuity. |
| Direct-to-Consumer Channel Development | Subscription models in Chicago and Denver metropolitan markets concentrate volume with customization-capable suppliers. |
| EFSA Health Claim Substantiation | Clinical investment precedes product launch, filtering market access to well-capitalized competitors. |
Study Parameters
Document review covered FDA nutrition labeling guidance, EFSA health claim assessments, China SAMR registration pathways, and EU dairy policy frameworks, complemented by interviews with membrane process engineers at Irish and Dutch fractionation facilities, procurement directors at German bakery reformulation companies, sports nutrition brand formulation scientists, and cooperative milk collection network managers. Secondary validation drew from customs trade data, dairy cooperative annual disclosures, and equipment manufacturer order backlogs. Bottom-up capacity modeling and top-down demand segmentation were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against panel input from ingredient procurement directors to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include protein concentration tier, application channel, end-user cost sensitivity, and regional regulatory cluster. CAGRs were derived from installed capacity expansion schedules, substitution elasticity estimates, and gym penetration growth curves.
Revisions become necessary when milk price volatility exceeds historical bands, plant protein isolate cost curves shift unexpectedly, or regulatory divergence between FDA, EFSA, and SAMR intensifies compliance burden. Deviation in EFSA health claim approval timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
China Collagen Peptides Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Raspberry Ketones Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
Red Ginseng Market
Nutritional Supplements
Europe Moringa Supplement Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
North America Vegan Supplements Market