
 Asia-Pacific Soy Protein Concentrate Market | 2026-2036
Asia-Pacific Soy Protein Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Soy Protein Concentrate Market Insights
Modular ingredient bundling is hardening as the dominant procurement pattern across Asia-Pacific food manufacturers. Cargill, Incorporated leverages its integrated oilseed crushing network to supply customized protein blends directly to plant-based meat formulators. Wilmar International Limited anchors regional supply through its crushing facilities in China and Southeast Asia. Shandong Yuxin Bio-Tech Co., Ltd. specializes in non-GMO concentrate grades for premium export channels.
Soy protein concentrate contains approximately 65-70% protein by weight, produced through aqueous alcohol washing of defatted soy flakes to remove soluble carbohydrates while retaining functional protein fractions; this ingredient serves primarily as a cost-efficient binder and emulsifier in processed foods and feed formulations. The powder form commands the deepest margin pools due to its extended shelf stability and ease of bulk handling in industrial settings. Textured soy protein competes most aggressively on price in animal feed applications across Southeast Asian markets.
China's SAMR enforces GB standards for plant protein labeling and purity thresholds, while Japan's Ministry of Health, Labour and Welfare applies stringent allergen disclosure rules that elevate compliance costs for imported concentrates. India's FSSAI has tightened protein content verification protocols for dietary supplement applications, redirecting some procurement toward certified domestic suppliers. Stakeholders must monitor how divergent national purity standards fragment cross-border trade and where regional harmonization efforts create new compliance pathways.
Market Dynamics
Modular ingredient bundling is hardening as the dominant procurement pattern across Asia-Pacific food manufacturers, with enzymatic extraction innovations from Chinese processing clusters reshaping product quality benchmarks and compressing supplier margins.
Growth Catalysts
- Plant-based meat formulation surge:Food and beverage manufacturers across China, Japan, and India are accelerating soy protein concentrate adoption as a cost-efficient binder in alternative protein products.
- GB standards modernization:China's SAMR updated food safety standards for plant proteins, creating compliance clarity that streamlines domestic production and export certification pathways.
- Enzymatic extraction advancement:Biotechnology improvements in aqueous alcohol washing processes are boosting protein retention rates and functional performance in defatted soy flake processing.
Market Restraints
- Input cost volatility:Soybean price fluctuations tied to weather patterns and trade flows in Brazil and Argentina squeeze concentrate processor margins unpredictably.
- Supply concentration risk:Eastern China dominates soybean processing clusters, creating geographic single-point vulnerability for Asia-Pacific procurement networks.
- Regulatory fragmentation:Divergent national purity standards between China's SAMR, Japan's Ministry of Health, Labour and Welfare allergen rules, and India's FSSAI verification protocols complicate cross-border trade.
Strategic Opportunities
- Underpenetrated Southeast Asian feed markets:Textured soy protein applications in Vietnamese and Indonesian animal feed formulations remain below saturation thresholds relative to protein demand growth.
- Premium non-GMO export channels:Certified domestic suppliers in Shandong and Jiangsu provinces can capture margin premiums from European and Japanese buyers demanding verified non-GMO concentrate grades.
- Dual carbon policy alignment:China's MEE carbon intensity targets incentivize low-energy enzymatic extraction investments that reduce processing emissions versus conventional solvent methods.
Industry Challenges
- Protein verification skill gaps:India's FSSAI tightened protocols require laboratory capabilities that many domestic testing facilities lack, slowing certification timelines for dietary supplement applications.
- Allergen labeling compliance complexity:Japan's stringent disclosure rules demand Japanese-language documentation and traceability systems that elevate operational costs for imported concentrate handlers.
- Legacy equipment retrofit requirements:Aqueous alcohol washing infrastructure upgrades to meet GB standards purity thresholds require capital deployment that mid-scale crushers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Soy Protein Concentrate Market |
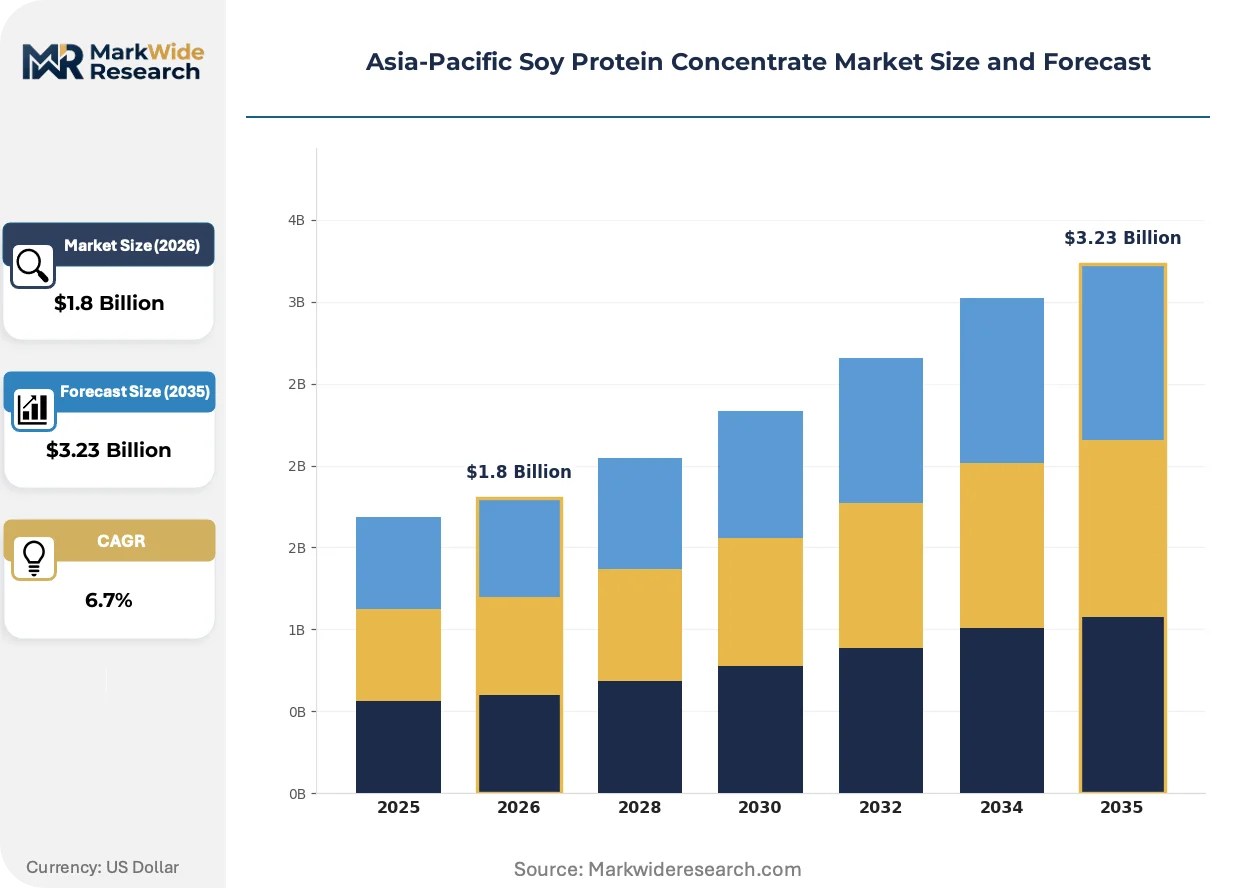
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein Isolate, Soy Protein Concentrate, Textured Soy Protein, Soy Flour End Use Industry: Food & Beverages, Animal Feed, Dietary Supplements, Pharmaceutical Form: Powder, Granules, Flakes, Liquids Distribution Channel: Online Sales, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Wilmar International Limited, Cargill, Incorporated, Bunge Limited, CHS Inc., COFCO Corporation, Crown Soya Protein Group Company, Shandong Yuxin Bio-Tech Co., Ltd., Linyi Shansong Biological Products Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Soy Protein Concentrate Market Trends and Innovations
Enzymatic extraction technologies and modular protein blending systems are compressing traditional supplier roles while regulatory divergence between national food safety frameworks forces compliance architecture investments.
Enzymatic processing is consolidating quality differentiation in the Asia-Pacific soy protein concentrate market. This biotechnology replaces conventional aqueous alcohol washing with targeted enzyme hydrolysis that preserves functional protein fractions more selectively. Plant-based meat formulators in Shanghai and Shenzhen are adopting these concentrates at accelerated pace for improved emulsification performance. The technology is consolidating supplier tiers by rewarding processors with in-house biotechnology capabilities while marginalizing commodity-grade producers.
Japan's Ministry of Health, Labour and Welfare allergen disclosure rules are elevating compliance infrastructure requirements for imported concentrates. The regulation mandates Japanese-language traceability documentation and dedicated allergen-control production lines for soy protein entering food applications. Cross-border traders serving Japanese food manufacturers face compressed margins from added certification and labeling costs. Premium concentrate grades with verified allergen-control protocols command price premiums that standard-grade imports cannot capture.
Direct procurement from crushing facilities is displacing traditional ingredient distributor networks across Asia-Pacific food manufacturing. Large plant-based meat formulators in eastern China now contract directly with Shandong and Jiangsu processing clusters for customized protein blends, bypassing regional distributors. This channel compression reduces working capital requirements for buyers while concentrating volume risk with fewer supplier relationships. The pattern is most visible in export-oriented food manufacturing zones near Shanghai and Qingdao port infrastructure.
Asia-Pacific Soy Protein Concentrate Market Segmentation
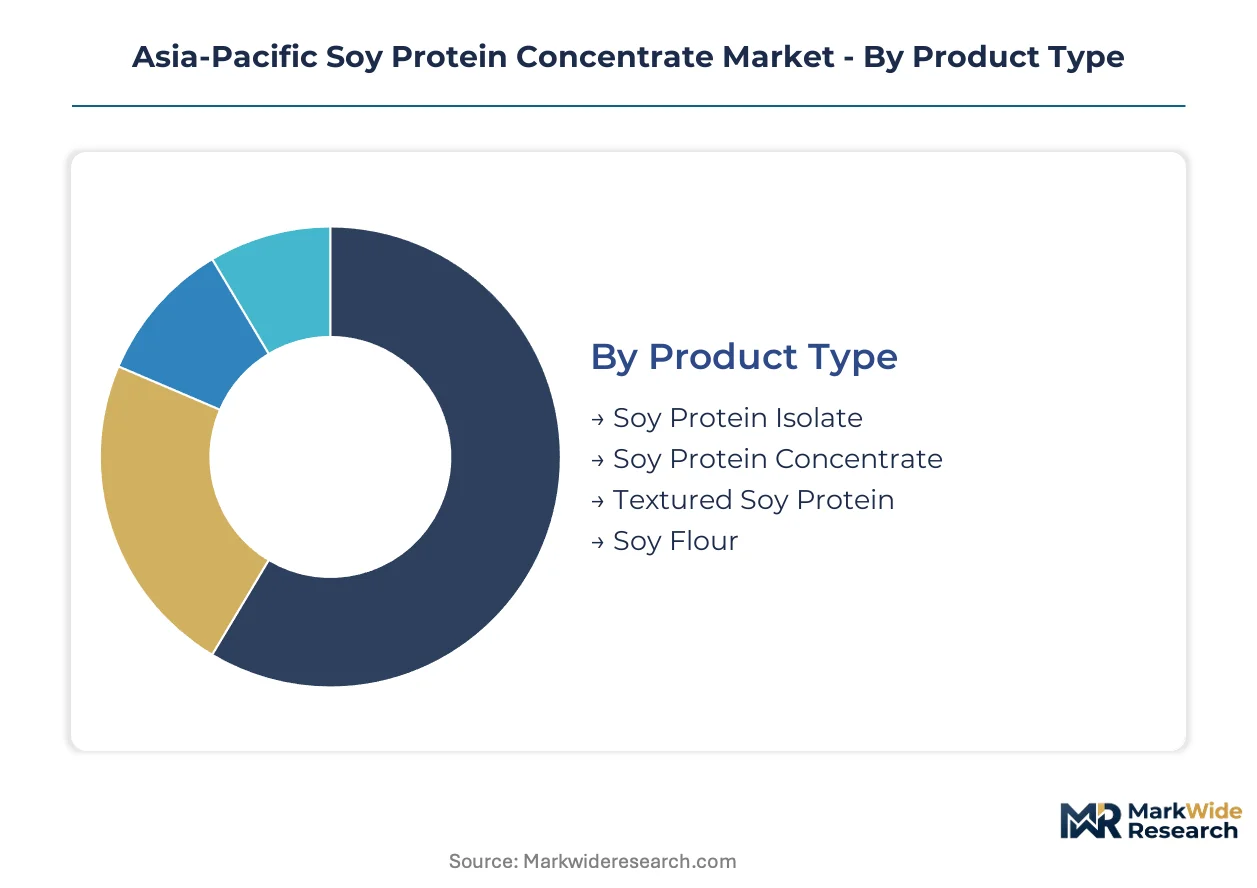
Segmentation in the Asia-Pacific soy protein concentrate market reveals how supply chain configuration and regulatory requirements fragment procurement patterns across protein grades and delivery formats. Manufacturers configure production assets around specific end-use purity thresholds and regional compliance frameworks.
Product Type:
Eastern China's crushing clusters concentrate supply-side leverage across protein grade tiers, with enzymatic extraction capabilities determining which processors capture premium formulation contracts versus commodity feed volumes.
- Soy Protein Isolate:Contains 90% protein minimum through isoelectric precipitation and membrane filtration, commanding premium positioning in Japanese pharmaceutical and high-performance sports nutrition applications where allergen documentation requirements from Japan's Ministry of Health, Labour and Welfare filter out standard-grade suppliers.
- Soy Protein Concentrate:The 65-70% protein workhorse produced via aqueous alcohol washing of defatted flakes, anchoring plant-based meat formulation demand in Shanghai and Shenzhen where Cargill and Wilmar International crushing networks supply customized blends directly to food manufacturers.
- Textured Soy Protein:Extruded concentrate with fibrous structure for meat analogs, penetrating Vietnamese and Indonesian feed markets below saturation thresholds relative to regional protein demand expansion.
- Soy Flour:Full-fat or defatted milled soybean product at 40-50% protein, serving cost-sensitive bakery and traditional food applications across India's FSSAI-regulated domestic supply chains.
Today's leader: Soy Protein Concentrate. Tomorrow's challenger: Soy Protein Isolate.
End Use Industry:
Application-driven purity requirements reshape margin architecture, with food-grade certification costs creating tiered entry barriers that concentrate volume among processors with dedicated allergen-control infrastructure.
- Food & Beverages:Plant-based meat alternatives in China, Japan, and India drive accelerated adoption of functional concentrates as cost-efficient binders and emulsifiers in processed formulations.
- Animal Feed:Textured soy protein competes aggressively on price in Southeast Asian aquaculture and poultry operations, with Vietnamese procurement networks sourcing from Shandong export channels.
- Dietary Supplements:India's FSSAI tightened protein content verification protocols redirect procurement toward certified domestic suppliers with laboratory capabilities many testing facilities currently lack.
- Pharmaceutical:Japan's stringent allergen disclosure rules and Japanese-language traceability documentation elevate compliance costs, compressing margins for imported concentrate handlers while rewarding verified allergen-control protocols with price premiums.
Food & Beverages commands current volume leadership. Dietary Supplements climbs fastest as India's verification protocols mature and sports nutrition demand accelerates.
Form:
Handling economics and shelf stability requirements segment procurement by operational scale, with powder formats dominating industrial volumes while liquid concentrates serve niche fresh processing applications.
- Powder:Extended shelf stability and bulk handling efficiency anchor deepest margin pools in industrial settings, with eastern China's soybean processing clusters dominating procurement for export-oriented food manufacturers near Shanghai and Qingdao port infrastructure.
- Granules:Intermediate particle size for controlled hydration in meat analog extrusion, gaining traction with plant-based meat formulators seeking texture optimization.
- Flakes:Defatted soy flake intermediate in aqueous alcohol washing processes, primarily captive to integrated crushing facilities rather than traded as finished product.
- Liquids:Slurry concentrates for fresh processing applications with limited regional penetration due to cold chain requirements and shortened shelf life constraining distribution radius.
Powder maintains supply dominance. Granules expand most quickly as extrusion technology adoption spreads across Asia-Pacific meat alternative manufacturing.
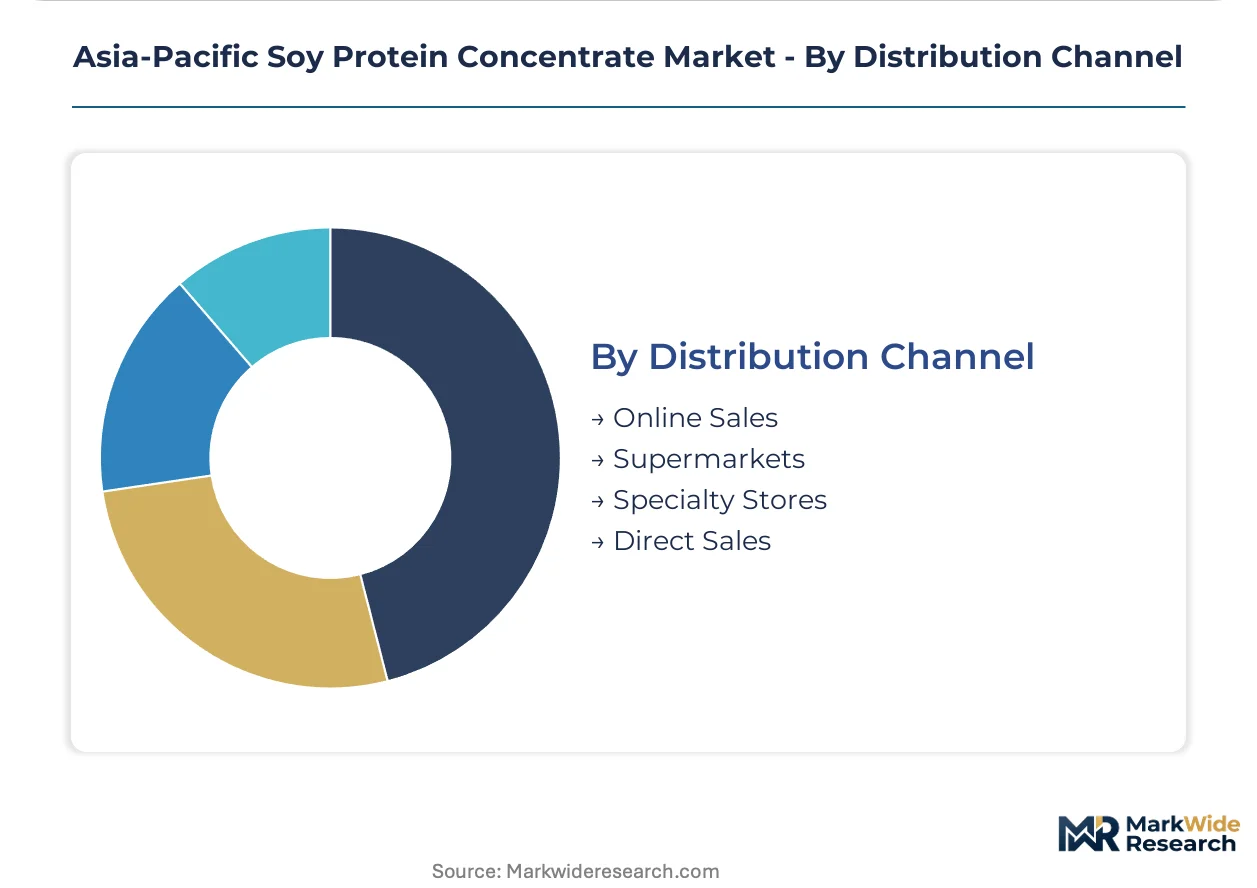
Distribution Channel:
Channel compression is displacing traditional distributor networks, with direct procurement from crushing facilities reducing working capital requirements while concentrating volume risk among fewer supplier relationships.
- Direct Sales:Large plant-based meat formulators contract directly with Shandong and Jiangsu processing clusters for customized protein blends, bypassing regional distributors entirely in export-oriented manufacturing zones.
- Online Sales:Digital procurement platforms serve mid-scale feed compounders and specialty food manufacturers seeking smaller batch flexibility with reduced minimum order quantities.
- Supermarkets:Retail channel for consumer-packaged soy protein ingredients, limited penetration in Asia-Pacific relative to North American and European markets.
- Specialty Stores:Health food and sports nutrition retailers catering to premium non-GMO concentrate grades for verified export channels targeting European and Japanese buyers.
Direct Sales leads transaction volume. Online Sales gains share fastest as digital procurement platforms aggregate fragmented mid-scale demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soy protein concentrate manufacturing first scaled in China's eastern processing corridors during the 1990s, establishing the region's dominance in aqueous alcohol washing infrastructure and export-oriented supply chains.
China
Shandong and Jiangsu crushing clusters supply customized protein blends directly to plant-based meat formulators in Shanghai and Shenzhen. SAMR's updated GB standards for plant protein labeling streamline domestic certification and export pathways. Eastern China's soybean processing concentration creates geographic single-point vulnerability for regional procurement networks.
Japan
Pharmaceutical and sports nutrition applications drive demand for soy protein isolate with minimum 90% protein content. The Ministry of Health, Labour and Welfare enforces stringent allergen disclosure rules requiring Japanese-language traceability documentation. Premium concentrate grades with verified allergen-control protocols capture price premiums unavailable to standard-grade imports.
India
Dietary supplement applications accelerate fastest as sports nutrition demand expands in urban centers. FSSAI tightened protein content verification protocols redirect procurement toward certified domestic suppliers with laboratory capabilities. Maharashtra and Gujarat processing facilities struggle with certification timelines due to testing infrastructure gaps.
Vietnam
Aquaculture and poultry feed operations source textured soy protein below regional saturation thresholds. Feed compounders procure through Shandong export channels with price-sensitive specifications dominating procurement criteria. Ho Chi Minh City logistics hubs aggregate fragmented mid-scale demand for digital procurement platforms.
Indonesia
Animal feed formulations represent underpenetrated volume opportunity relative to protein demand growth trajectory. Poultry sector expansion in Java drives concentrate adoption as cost-efficient protein binders. Surabaya processing zones develop regional distribution infrastructure for imported concentrate grades.
Asia-Pacific Soy Protein Concentrate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and functional-performance dimensions. The vendor base stratifies between integrated oilseed crushers with biotechnology capabilities and regional processors serving price-sensitive feed applications. Three archetypes dominate: multinational agribusiness conglomerates with captive crushing networks, Chinese provincial specialists in non-GMO certification, and Southeast Asian feed-grade compounders. Capacity expansion in enzymatic extraction capabilities and direct procurement relationships with plant-based meat formulators constitute the dominant competitive moves reshaping supplier tiers.
Among multinational agribusiness conglomerates, Cargill, Incorporated and Wilmar International Limited anchor the integrated-crushing archetype with direct supply relationships to food manufacturers. Shandong Yuxin Bio-Tech Co., Ltd. occupies a position within the Chinese provincial specialist tier, representing non-GMO certification-focused suppliers targeting premium export channels. These three entities exemplify how geographic origin and corporate structure align with divergent margin architectures across the regional market.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Wilmar International Limited |
| Cargill, Incorporated |
| Bunge Limited |
| CHS Inc. |
| COFCO Corporation |
| Crown Soya Protein Group Company |
| Shandong Yuxin Bio-Tech Co., Ltd. |
| Linyi Shansong Biological Products Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between allergen-verified concentrates and commodity feed grades splits procurement economics across eastern China's crushing clusters, with Japanese pharmaceutical buyers paying premiums that Vietnamese feed compounders cannot absorb while Shandong processors reconfigure lines to capture both tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs concentrate transactions, with GB standards compliance and enzymatic extraction capability separating price bands. Food-grade certification from SAMR-registered facilities commands 15-25% premiums over feed-grade output. Cost compression in standard-tier volumes is intensifying because Brazilian soybean price volatility squeezes processor margins. Vietnamese aquaculture buyers exhibit highest price sensitivity, while Japanese pharmaceutical formulators show least elasticity for verified allergen-control documentation.
Supply Chain Analysis
China's domestic-content requirements for plant protein labeling redirect procurement toward SAMR-certified crushing facilities in Shandong and Jiangsu provinces. Geographic supply concentration centers on China, with secondary sourcing from India's FSSAI-certified domestic suppliers and Vietnam's emerging feed-grade import channels. Raw material dependencies rest on Brazilian and Argentinian soybean flows, aqueous alcohol processing chemicals, and enzymatic biotechnology inputs. Single-source vulnerability concentrates in eastern China's processing corridor. Distribution runs through direct procurement relationships with plant-based meat formulators, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where plant-based meat formulators in Shanghai and Shenzhen now specify functional performance thresholds that commodity-grade suppliers cannot meet, compressing volume into certified processors with enzymatic capabilities.
For Market Incumbents: To counter margin compression from enzymatic extraction technology diffusion, Cargill and Wilmar International must deepen biotechnology R&D partnerships with Chinese crushing clusters while securing dedicated allergen-control production lines for Japanese pharmaceutical channels. Backward integration into non-GMO soybean origination in Shandong and Jiangsu provinces protects premium-grade supply security.
For New Entrants and Emerging Players: Mid-scale feed compounders in Indonesia's Java poultry corridor represent an underserved buyer archetype seeking textured soy protein below saturation thresholds relative to regional protein demand expansion. Digital procurement platforms aggregating fragmented Vietnamese and Indonesian demand offer lowest-friction market entry, with certified non-GMO export channels to European buyers providing margin upside.
For Investors and Strategic Acquirers: Consolidation pressure builds where laboratory verification capabilities lag behind FSSAI protocol tightening, stranding uncertified Indian processors and creating acquisition targets with compliant infrastructure. Long-term viability favors processors with dual carbon policy alignment and enzymatic extraction assets. Watch India's dietary supplement certification timelines as inflection indicator for domestic supplier valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Technology Deployment | SAMR-registered facilities in Shandong capture premium formulation contracts from plant-based meat innovators. |
| Non-GMO Certification Investment | Verified supply chains unlock European and Japanese export channels with 20-30% margin premiums over commodity grades. |
| Direct Procurement Relationship Development | Bypassing distributor networks reduces working capital requirements for Shanghai and Shenzhen formulators. |
| Dual Carbon Policy Alignment | Low-energy enzymatic processes secure MEE compliance advantages versus solvent-based competitors. |
| FSSAI Laboratory Capability Buildout | Certified testing infrastructure captures redirected procurement from India's dietary supplement acceleration. |
Research Methodology
Coverage spans China, Japan, India, Vietnam, and Indonesia, with primary inputs from each market combining interviews with crushing facility operations managers, plant-based meat formulator procurement leads, FSSAI regulatory compliance officers, and Japanese pharmaceutical quality assurance directors. Secondary validation draws from SAMR GB standards documentation, FSSAI protein verification protocols, Japanese Ministry of Health allergen disclosure guidelines, customs trade data for soybean concentrate flows, and SEC filings from listed agribusiness conglomerates. Bottom-up volume estimates from processing facility capacity and top-down demand calibration from end-use industry consumption patterns undergo triangulation.
Rate-of-change decomposition separates volume growth drivers from price evolution across the projection horizon. Segmentation dimensions modeled include protein grade tier, end-use industry application, powder versus granule form factor, and direct versus distributor channel structure. CAGRs derive from regression analysis against soybean input cost indices, plant-based meat formulation adoption curves, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporate enzymatic extraction technology penetration rates and FSSAI laboratory certification timelines.
Underlying measurement precision varies by segment; food-grade concentrate volumes carry tighter precision than feed-grade estimates due to SAMR registration transparency. Forecasts reflect assumptions around soybean price volatility, regulatory enforcement intensity, and biotechnology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Dietary Fibers Market
Ingredients
Plant-Based API Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Murumuru Butter Market
Ingredients
High Protein Flour Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Tapioca Pearls Market
Ingredients
Wheat Malt Market
Ingredients
Mexico Sodium Reduction Ingredients Market
Ingredients
Baobab Powder Market
Ingredients
Confectionery Ingredients Market
Ingredients
Sodium Caseinate Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Wheat Germ Oil Market
Ingredients
Farnesene Market