
 Fermentation Ingredient Market | 2026-2036
Fermentation Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Fermentation Ingredient Market Analysis
Commodity-grade amino acid margins is narrowing as specialty enzyme and precision-fermentation protein segments capture higher value pools. BASF SE leverages its integrated biotechnology platform to sustain cost leadership in bulk fermentation outputs. Chr. Hansen A/S anchors its position through microbial strain libraries that differentiate performance in dairy and probiotic applications. Ajinomoto Co. Inc. dominates nucleotide and umami ingredient supply chains across Asian food manufacturing corridors.
Fermentation ingredients comprise viable microbial cultures, enzymatic catalysts, and growth media substrates produced through controlled anaerobic or aerobic bioprocessing, typically requiring pH ranges of 4.5–7.0 and temperatures between 25°C and 42°C for optimal metabolite yield. These inputs serve as functional biocatalysts or nutritional additives across food, pharmaceutical, and industrial biotechnology value chains. Yeast-derived segments occupy mature volume positions in baking and brewing applications where manufacturing scale drives unit economics. Enzyme categories represent the fastest-growing product pool as biofuel producers and textile processors adopt biocatalytic process replacements. Pharmaceutical-grade bacteria strains command premium positioning due to stringent cGMP compliance and strain documentation requirements that limit supplier pools.
EFSA novel food assessments in Europe, FDA GRAS self-determination pathways in the United States, and China's SAMR food additive registration requirements collectively shape market access timelines and safety documentation burdens for fermentation-derived ingredients. REACH chemical registration in Europe and EPA biotechnology regulations under the Toxic Substances Control Act further constrain strain deployment and commercial scale-up for novel microbial products. Stakeholders must monitor evolving precision-fermentation regulatory classifications that could reclassify cell-cultured proteins and bio-identical compounds under novel food or biologic frameworks, fundamentally altering compliance investment requirements and competitive entry barriers.
Market Dynamics
Precision fermentation is virtualizing protein production, collapsing the capital intensity gap between biotech startups and incumbent chemical manufacturers while forcing strain IP to become the primary competitive moat.
Growth Catalysts
- Clean-label mandates:EFSA novel food pathways accelerate approval timelines for bio-identical ingredients, pulling dairy and meat alternatives into mainstream retail formulations across European markets.
- Carbon pricing mechanisms:EU Green Deal border adjustments penalize petrochemical-derived inputs, redirecting procurement budgets toward microbially produced surfactants and polymer precursors.
- Traditional fermentation clusters:China's Zhejiang and Shandong provinces combine heritage koji and tempeh expertise with industrial bioreactor infrastructure, compressing scale-up timelines for new entrants.
Market Restraints
- Feedstock volatility:Molasses and corn steep liquor prices swing with Brazilian sugarcane harvests, squeezing margins for bulk amino acid producers dependent on agricultural carbohydrate streams.
- Strain documentation burdens:FDA GRAS self-determination requires whole-genome sequencing and toxicology packages that cost mid-tier suppliers twelve to eighteen months of regulatory runway.
- Enzyme substitution pressure:Cellulase cocktails from Trichoderma reesei face displacement by engineered variants from Novozymes and DuPont, concentrating performance-tier supply among patent-heavy incumbents.
Strategic Opportunities
- Precision fermentation white space:India's PLI scheme for biotechnology manufacturing offers twenty percent capex subsidies for greenfield fermentation facilities, attracting contract manufacturers serving European pharma clients.
- Biocatalytic process replacement:Textile processors in Bangladesh and Vietnam adopt transglutaminase and laccase enzymes to eliminate hypochlorite bleaching, opening volume contracts for specialty enzyme suppliers.
- Regulatory tailwinds:China's SAMR streamlined food additive registration for microbially derived nucleotides, reducing approval cycles from thirty-six to eighteen months for qualified applicants.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates among veterans of Genentech and Lonza, forcing newcomers to recruit from academic labs or competing CDMOs at premium compensation.
- cGMP facility certification timelines:Pharmaceutical-grade bacteria production requires ISO 14644 cleanroom validation and FDA pre-approval inspections that delay commercial launches by fourteen to twenty-four months.
- Legacy ERP integration friction:Batch record systems from Wonderware and OSIsoft lack native APIs for cloud-based metabolic modeling tools, forcing manual data transcription and compliance audit gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermentation Ingredient Market |
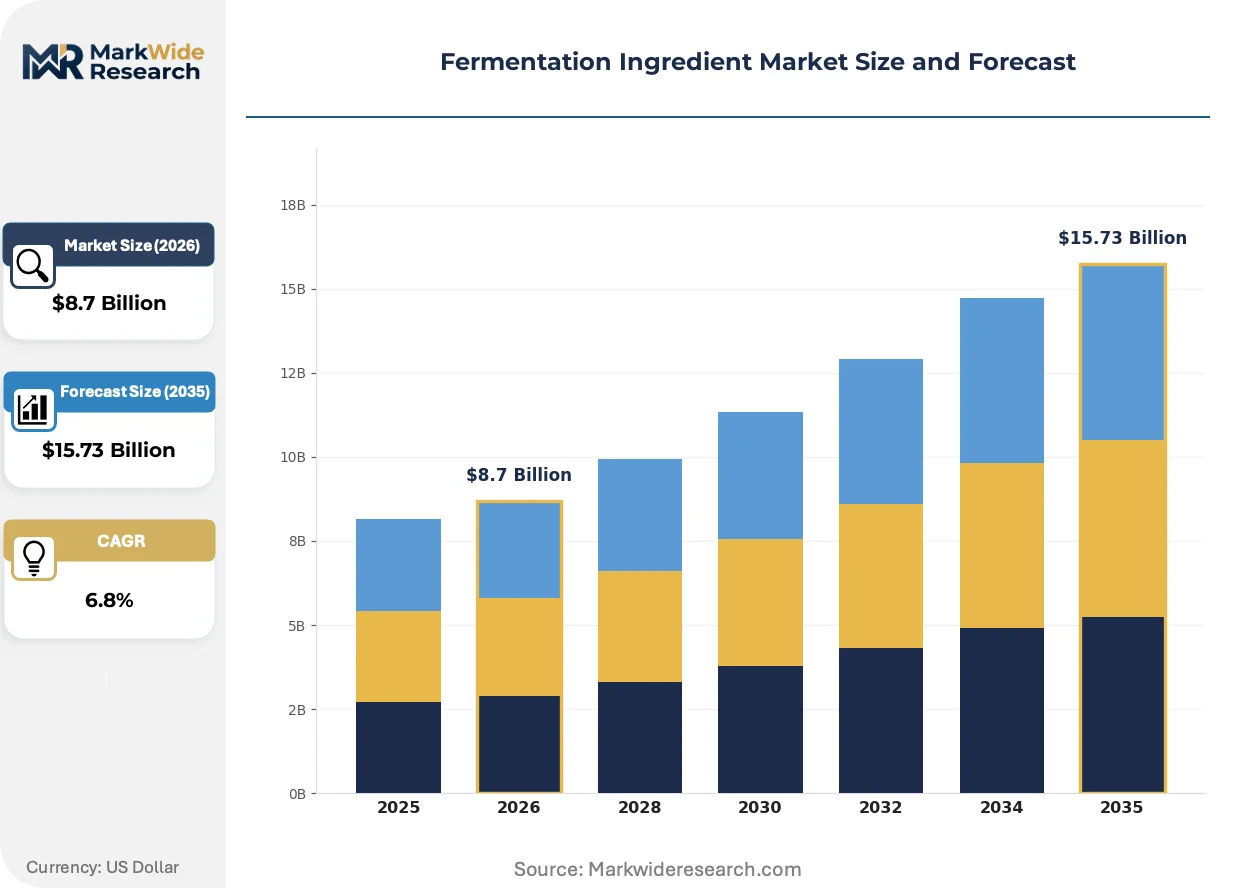
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast, Bacteria, Enzymes, Nutrients Application: Food Production, Beverage Manufacturing, Biofuel Production, Pharmaceutical End User: Food Industry, Beverage Industry, Biotechnology Companies, Research Institutions Distribution Channel: Direct Sales, Online Sales, Retail, Distributors |
| Companies Covered | AngelYeast Co., Ltd., Lallemand Inc., Cargill, Incorporated, Chr. Hansen A/S, Associated British Foods Plc., BASF SE, Ajinomoto Co. Inc., DuPont, Perfect Day, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermentation Ingredient Market Emerging Trajectories
Digital twins and AI-guided strain optimization are compressing the discovery-to-pilot timeline from years to months, while regulatory frameworks struggle to classify novel microbial outputs.
Continuous fermentation technology is virtualizing the traditional fed-batch paradigm in amino acid manufacturing. Lysine and threonine producers in China's Heilongjiang province deploy perfusion bioreactors with real-time metabolite sensors, cutting downtime between batches by sixty percent. This shift is virtualizing the capital efficiency advantage historically held by massive single-batch facilities, enabling mid-scale players to achieve comparable unit economics.
REACH chemical registration in Europe now captures engineered microbial strains as "substances of very high concern" when genetic modifications exceed natural strain variability thresholds. Industrial enzyme suppliers face expanded toxicology dossier requirements for CRISPR-edited production hosts, adding eighteen to thirty months to commercialization timelines. Food-grade applications encounter lighter scrutiny than technical enzymes, creating a regulatory divergence that steers R&D investment toward culinary and feed additive segments.
Buyers in the baking and brewing sectors consolidate supplier relationships around full-service fermentation partnerships rather than transactional ingredient purchases. Large European millers now demand strain customization, technical support, and co-developed application protocols bundled into multi-year contracts. This bundling is most visible in Germany and the Netherlands, where industrial bakeries have reduced their viable supplier pools from twelve to four over the past five years.
Fermentation Ingredient Market Segmentation
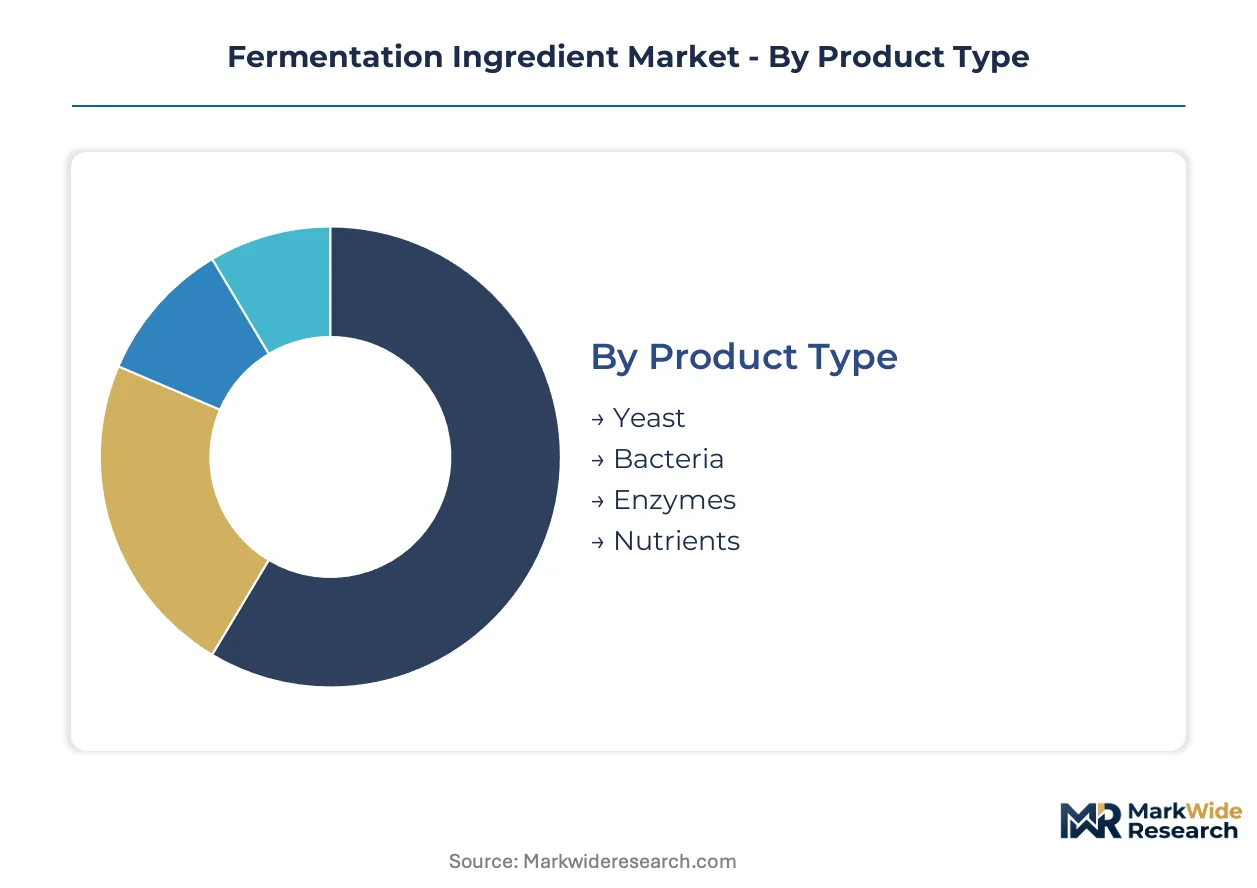
Fermentation ingredient buyers segment procurement by metabolic function, regulatory pathway, and scale-up complexity. Each dimension reveals distinct margin structures and compliance burdens that reshape supplier selection criteria across food, pharma, and industrial biotechnology verticals.
Product Type:
Biocatalytic performance and strain documentation requirements create divergent value pools across microbial categories.
- Yeast:Saccharomyces cerevisiae and Kluyveromyces marxianus strains dominate ethanol fermentation and baking applications where manufacturing scale drives unit economics. Demand concentrates in China's Shandong province and Germany's North Rhine-Westphalia, where heritage brewing expertise intersects with industrial bioreactor infrastructure.
- Enzymes:Cellulase, amylase, and protease catalysts enable biocatalytic process replacements in textile bleaching and biofuel pretreatment. Bangladeshi and Vietnamese textile processors adopt transglutaminase and laccase variants to eliminate hypochlorite, opening volume contracts for specialty suppliers.
- Bacteria:Lactobacillus and Bacillus strains serve dairy fermentation and probiotic formulations requiring cGMP compliance and whole-genome sequencing documentation.
- Nutrients:Peptone, yeast extract, and mineral salt blends constitute growth media substrates for biopharmaceutical cell culture applications.
The dominant share belongs to Yeast, while Enzymes is closing the gap fastest.
Application:
Regulatory classification intensity varies sharply across end-use categories, with pharmaceutical pathways demanding twelve to twenty-four month approval timelines.
- Food Production:Clean-label ingredient mandates in Europe and Asia-Pacific accelerate bio-identical dairy and meat alternative formulations. EFSA novel food pathways compress approval timelines for precision-fermented proteins entering mainstream retail.
- Pharmaceutical:cGMP bacteria strains command premium positioning due to ISO 14644 cleanroom validation and FDA pre-approval inspection requirements that limit supplier pools. Contract manufacturers in India serve European pharma clients from PLI-subsidized greenfield facilities.
- Beverage Manufacturing:Traditional koji and tempeh expertise in China's Zhejiang province merges with industrial scale-up for craft brewing and functional beverage applications.
- Biofuel Production:Cellulase cocktails from Trichoderma reesei face displacement pressure from engineered patent-protected variants, concentrating supply among incumbent enzyme houses.
Pharmaceutical commands the steepest margin tier, though Food Production exhibits the broadest geographic expansion.
End User:
Procurement sophistication separates commodity bulk buyers from precision-fermentation partners seeking strain customization and co-development protocols.
- Food Industry:European industrial bakeries consolidate supplier relationships around full-service partnerships bundling strain customization, technical support, and multi-year application protocols.
- Biotechnology Companies:Precision-fermentation startups virtualize protein production through contract manufacturing, collapsing capital intensity gaps with incumbent chemical producers.
- Beverage Industry:Large millers in Germany and the Netherlands reduced viable supplier pools from twelve to four over five years through bundled partnership demands.
- Research Institutions:Academic labs supply talent pipelines for scale-up engineering roles, forcing newcomers to recruit at premium compensation.
Biotechnology Companies drive the steepest contract value growth, while Food Industry maintains the deepest incumbent relationships.
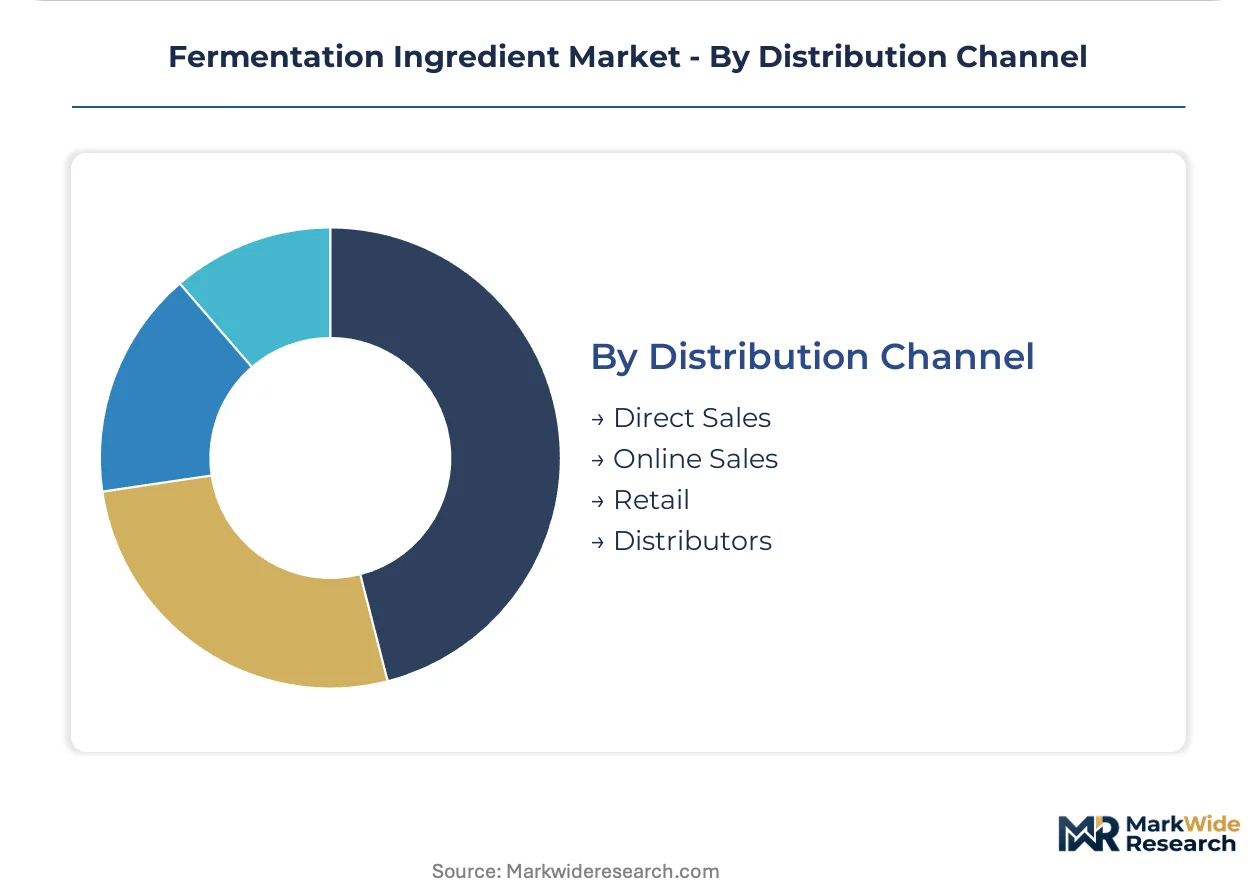
Distribution Channel:
Channel selection reflects batch size, technical support needs, and regulatory documentation requirements.
- Direct Sales:Multi-year contracts with strain customization and co-developed application protocols dominate European baking and brewing procurement.
- Distributors:Regional networks serve mid-tier amino acid and bulk enzyme buyers in fragmented Asian food manufacturing corridors.
- Online Sales:Research-grade nutrients and small-batch cultures reach biotechnology startups and academic labs through digital catalog platforms.
- Retail:Consumer-facing probiotic and baking yeast products move through packaged goods channels with limited technical service attachment.
Direct Sales captures the highest contract value per transaction, while Distributors retain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for commodity-grade amino acids peaks in Asian bulk manufacturing corridors, while pharmaceutical-grade bacteria strains command premium tolerance in European and North American procurement budgets.
China
Industrial-scale lysine and threonine production clusters in Heilongjiang province deploy continuous perfusion bioreactors with real-time metabolite sensors. SAMR streamlined food additive registration for microbially derived nucleotides, cutting approval cycles from thirty-six to eighteen months. Zhejiang and Shandong provinces merge heritage koji expertise with industrial bioreactor infrastructure for craft brewing scale-up.
Germany
Industrial bakeries in North Rhine-Westphalia consolidate supplier relationships around bundled strain customization and multi-year technical service contracts. EFSA novel food pathways accelerate bio-identical dairy alternative approvals, pulling precision-fermented proteins into mainstream retail. The region's brewing heritage intersects with pharmaceutical-grade cGMP facility investments serving European pharma clients.
United States
Precision-fermentation startups virtualize protein production through contract manufacturing partnerships, collapsing capital intensity gaps with incumbent chemical producers. FDA GRAS self-determination pathways require whole-genome sequencing and toxicology packages that cost mid-tier suppliers twelve to eighteen months of regulatory runway. Greater Boston and San Francisco Bay Area biotechnology clusters anchor strain IP development and metabolic engineering talent pipelines.
India
Pharmaceutical contract manufacturers serve European clients from PLI-subsidized greenfield fermentation facilities with twenty percent capex subsidies. FSSAI and CDSCO alignment with international cGMP standards enables export-oriented bacteria strain production. Maharashtra and Gujarat host expanding industrial biotechnology infrastructure targeting biocatalytic enzyme supply to Bangladeshi and Vietnamese textile processors.
Brazil
Molasses feedstock volatility from sugarcane harvest swings squeezes margins for bulk amino acid producers dependent on agricultural carbohydrate streams. ANVISA pharmaceutical-grade microbial culture regulations limit supplier pools through stringent strain documentation requirements. São Paulo state anchors South American fermentation ingredient distribution networks serving regional food manufacturing corridors.
Fermentation Ingredient Market Vendor Landscape
Integrated biotechnology platforms and specialized microbial strain libraries split the market between cost leadership in bulk outputs and premium positioning in performance-tier applications. The vendor base organizes around three archetypes: diversified chemical conglomerates with captive fermentation capacity, dedicated microbial culture specialists with documented strain libraries, and precision-fermentation startups commercializing novel protein architectures. Dominant competitive moves include backward integration into feedstock supply chains and technology licensing partnerships that accelerate strain deployment timelines.
Within the integrated chemical tier, BASF SE exemplifies cost leadership through captive biotechnology infrastructure spanning bulk amino acid and enzyme outputs. Chr. Hansen A/S and Ajinomoto Co. Inc. occupy differentiated positions anchored by microbial strain documentation and nucleotide supply chain control respectively. These three entities represent the spectrum from commodity-scale fermentation to specialty ingredient premiumization that defines competitive positioning across food, pharmaceutical, and industrial biotechnology verticals.
| Leading Market Players |
|---|
| AngelYeast Co., Ltd. |
| Lallemand Inc. |
| Cargill, Incorporated |
| Chr. Hansen A/S |
| Associated British Foods Plc. |
| BASF SE |
| Ajinomoto Co. Inc. |
| DuPont |
| Perfect Day, Inc. |
| Others |
Supply Flow & Price Mechanics
Heilongjiang province's continuous perfusion bioreactor installations for lysine and threonine production compress batch turnaround times by sixty percent, translating into downstream pricing power for mid-scale amino acid suppliers challenging legacy bulk manufacturers. This capacity virtualization collapses the unit economics advantage historically held by massive single-batch facilities, reshaping margin structures across commodity-grade fermentation outputs.
Pricing Analysis
Technical service contracts and multi-year application protocol bundles now drive lifetime value for specialty enzyme suppliers serving European industrial bakeries. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade certification levels separates cGMP bacteria strains commanding premium positioning from commodity yeast extracts. Cost compression in bulk amino acid segments is intensifying because Brazilian sugarcane harvest volatility feeds molasses price swings. Food manufacturers in Asia-Pacific manufacturing corridors exhibit the highest price sensitivity, while pharmaceutical contract manufacturers in India tolerate premium positioning for documented strain libraries.
Supply Chain Analysis
Tariff exposure between China and European Union markets dominates supply chain risk planning for nucleotide and umami ingredient suppliers. Manufacturing gravity centers on China, India, and Germany, with Heilongjiang and Zhejiang provinces anchoring amino acid and koji-derived outputs respectively. Feedstock supply draws from Brazilian sugarcane molasses, American corn steep liquor, and European beet sugar derivatives. Single-source vulnerability concentrates in CRISPR-edited production strains facing REACH substance-of-very-high-concern classification delays. Distribution runs through direct sales partnerships for strain-customized accounts and regional distributor networks for mid-tier bulk buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation represents an early-cycle expansion story as bio-identical protein production virtualizes capital requirements and EFSA novel food pathways accelerate mainstream retail penetration.
For Market Incumbents: Entrench market position through backward integration into feedstock supply chains and captive strain documentation infrastructure that mid-tier competitors cannot replicate. Precision-fermentation startups threaten premium positioning by collapsing capital intensity gaps. Certification investment in FDA GRAS self-determination pathways and EFSA novel food dossiers builds regulatory moats that delay competitive entry. For New Entrants and Emerging Players: India's PLI-subsidized biotechnology manufacturing zones offer underpenetrated contract manufacturing opportunities serving European pharmaceutical clients. Bangladeshi and Vietnamese textile processors present the most penetrable enzyme demand as hypochlorite elimination mandates drive biocatalytic adoption. A go-to-market angle anchored in regulatory fast-follower positioning—leveraging China's SAMR streamlined eighteen-month approval cycles—accelerates commercial traction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-fermentation platforms with demonstrated strain IP and contract manufacturing partnerships over capital-intensive asset builds. Long-term viability across a five-to-ten-year window hinges on regulatory classification clarity for cell-cultured proteins and bio-identical compounds. The signal to watch is EFSA novel food assessment throughput rates as an inflection indicator for mainstream retail adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Technology Deployment | Perfusion bioreactor installations in Heilongjiang compress batch downtime and virtualize scale economics. |
| Strain Documentation Infrastructure Investment | Whole-genome sequencing capabilities satisfy FDA GRAS requirements and limit competitive supplier pools. |
| Regulatory Fast-Track Partnership | SAMR streamlined approval cycles in China cut nucleotide registration timelines from thirty-six to eighteen months. |
| Backward Integration into Feedstock Supply | Captive molasses and corn steep liquor sourcing insulates margins from Brazilian sugarcane harvest volatility. |
| Precision Fermentation Platform Licensing | Technology licensing partnerships accelerate strain deployment timelines for bio-identical protein commercialization. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fermentation process engineers, regulatory affairs specialists at microbial culture suppliers, procurement directors at European industrial bakeries, and contract manufacturing officers at Indian pharmaceutical facilities; and secondary validation through SAMR food additive registration databases, EFSA novel food assessment records, US FDA GRAS notification filings, and customs trade data for amino acid and enzyme imports. Bottom-up triangulation across production capacity disclosures and top-down demand modeling across food, pharmaceutical, and industrial biotechnology verticals anchored volume and value estimates.
Forecast inputs considered metabolic function segmentation, regulatory pathway intensity, and scale-up complexity dimensions across the projection horizon. Product-type splits spanning yeast, enzymes, bacteria, and nutrients; application categories across food production, pharmaceutical, beverage manufacturing, and biofuel production; and end-user archetypes from commodity bulk buyers to precision-fermentation partners shaped the analytical framework. CAGRs were derived from segment-level growth rate synthesis applied to baseline capacity and demand estimates, with precision-fermentation protein adoption curves and clean-label ingredient penetration rates serving as key industry-specific forecast inputs.
Practitioners should monitor EFSA novel food assessment throughput, SAMR registration cycle times, and REACH engineered strain classification decisions for early signals of regulatory friction or acceleration. Forecasts reflect assumptions about continued carbon pricing mechanism expansion and precision-fermentation technology cost curves that industry-specific shocks could materially revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Cocoa Products Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
North America Whey Protein Ingredients Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Potato Fiber Market
Ingredients
Asia-Pacific Agar Market
Ingredients
Fish Peptones Market
Ingredients
Lime Seed Oils Market
Ingredients
Animal-Derived Ingredients Market
Ingredients
Europe Fats and Oil Market
Ingredients
Rennet Market
Ingredients
Cocoa Market
Ingredients
Coconut Flour Market
Ingredients
Chickpea Flour Market
Ingredients
Corn Gluten Meal Market