
 Mustard Oil Market | 2026-2036
Mustard Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Mustard Oil Market Foresight
Single-serve pouch packaging is realigning purchasing patterns among urban households and roadside eateries seeking portion control without storage burden. Cargill, Incorporated leverages its grain-oil infrastructure to secure feedstock cost advantages across South Asian supply chains. Dabur India Ltd. anchors its mustard oil portfolio within Ayurvedic positioning, competing against commodity-refined alternatives through brand heritage. Adani Wilmar Limited extends its pan-India distribution network to dominate modern trade shelf space for edible oils.
Mustard oil is a vegetable oil extracted from Brassica juncea seeds, containing approximately 60% monounsaturated fatty acids and characteristic allyl isothiocyanate compounds that impart pungency and preservative properties; it serves primarily as a cooking medium, flavoring agent, and traditional therapeutic base across South Asian cuisines and Ayurvedic formulations. Cold-pressed variants command premium positioning among health-conscious consumers seeking minimal thermal degradation, while refined grades occupy volume-driven institutional channels where smoke-point consistency matters more than organoleptic intensity. The food processing end-user segment concentrates margin pools, as contract manufacturers specify certified batches for pickle, snack, and ready-meal production.
India's FSSAI mandates fortification and transparent labeling for edible oils, directly influencing product formulation and packaging redesign across domestic manufacturers. Bangladesh's BSTI standards and Nepal's national quality specifications for mustard oil create layered compliance requirements for cross-border suppliers. Stakeholders must monitor evolving cold-chain logistics investments and e-commerce fulfillment capabilities, as these operational dimensions increasingly determine market access velocity in fragmented South Asian retail terrain.
Market Dynamics
India's FSSAI fortification mandates and Bangladesh's BSTI quality specifications are forcing simultaneous reformulation and packaging redesign across South Asian mustard oil supply chains, compressing margins for undifferentiated processors while rewarding certified cold-press operators.
Growth Catalysts
- Fortification mandates:India's FSSAI requires Vitamin A and D enrichment in edible oils, creating compliance-driven volume for certified mills equipped with injection systems.
- Food processing procurement:Contract manufacturers of pickles and ready-meals specify allyl isothiocyanate-rich cold-pressed grades for flavor consistency and natural preservation.
- E-commerce fulfillment infrastructure:Quick-commerce platforms in Dhaka and Kathmandu are building dedicated edible oil cold chains, expanding branded access beyond traditional kirana networks.
Market Restraints
- Seed price volatility:Brassica juncea procurement costs fluctuate with monsoon-dependent domestic harvests and competing biodiesel diversion in European markets.
- Refined palm oil substitution:Price-sensitive institutional buyers in Bangladesh switch to imported refined palm for high-heat applications, eroding mustard's volume position in food service.
- Smoke-point limitation:Cold-pressed mustard oil's lower thermal threshold restricts penetration into deep-frying segments dominated by chemically refined high-oleic alternatives.
Strategic Opportunities
- Nepal's branded consumption gap:Per capita mustard oil usage exceeds India but packaged penetration lags at under 35%, offering first-mover shelf space capture in Kathmandu's modern trade.
- Ayurvedic therapeutic positioning:External massage and nasal drop applications are integrating with wellness retail channels, commanding 3-4x cooking-grade price premiums.
- Single-serve pouch formats:Roadside eateries and urban nuclear households are adopting portion packs, reducing working capital burden and trial friction.
Industry Challenges
- Cold-chain capex intensity:Maintaining organoleptic integrity through last-mile distribution requires refrigerated warehousing investments that fragment regional players cannot absorb.
- Cross-border certification timelines:Bangladeshi exporters face 90-120 day BSTI batch testing queues when supplying Nepali distributors, constraining just-in-time replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mustard Oil Market |
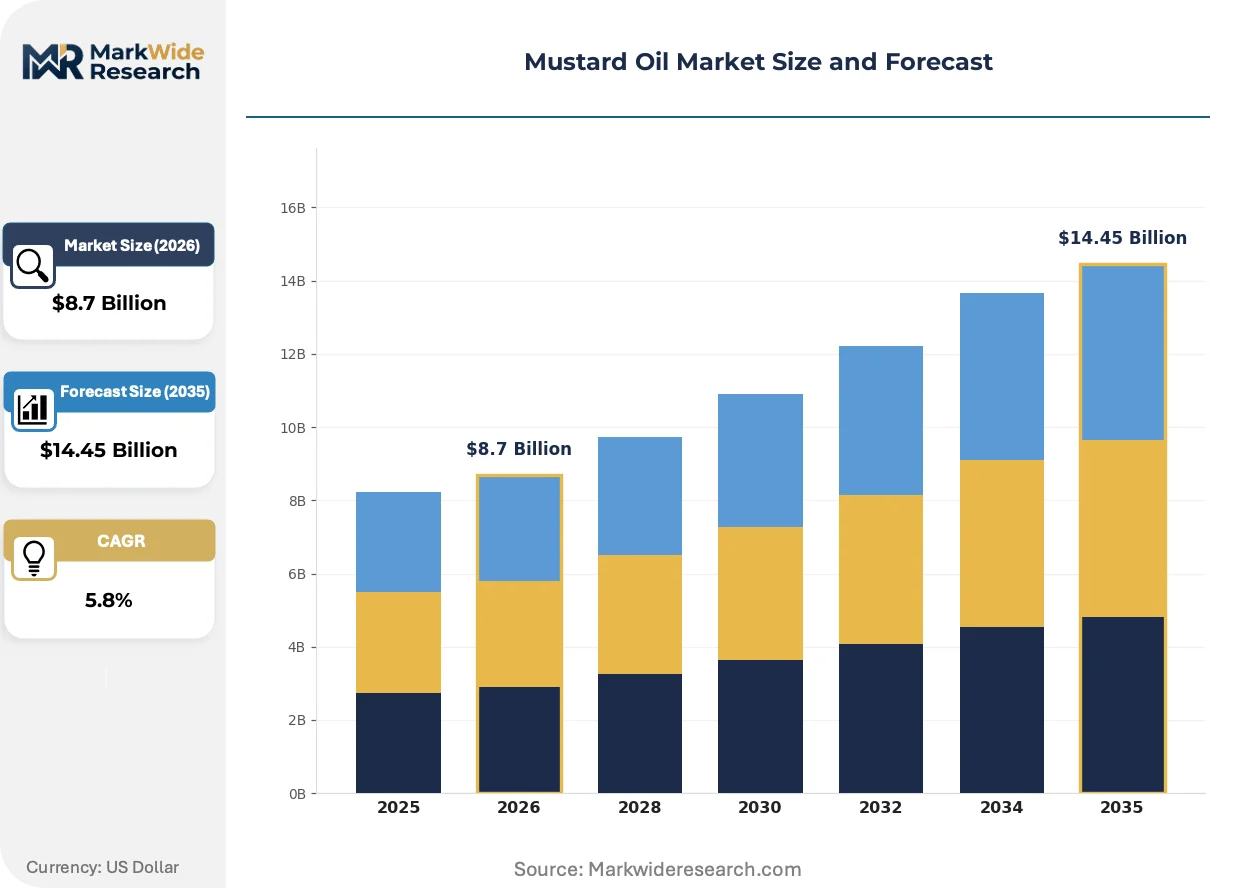
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-Pressed, Refined, Organic, Blended End User: Households, Restaurants, Food Processing, Industrial Packaging Type: Bottles, Cans, Pouches, Bulk Distribution Channel: Supermarkets, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | Cargill, Incorporated, Dabur India Ltd., Adani Wilmar Limited, Bansal Oil Mill Ltd., Puri Oil Mills Limited, Emami Agrotech Ltd., Marico, K. S. Oils Limited, Patanjali Ayurved, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mustard Oil Market Shifts & Advancements
Mechanical pressing technology and regulatory transparency requirements are converging to bifurcate the mustard oil market into premium cold-pressed wellness positioning and commodity-refined institutional supply, with packaging format innovation determining access velocity in fragmented retail terrain.
Supercritical CO2 extraction is integrating with traditional ghani pressing to preserve heat-sensitive bioactive compounds while achieving solvent-free certification. Ayurvedic product manufacturers and premium organic brands are adopting this hybrid approach at pilot scale. The technology is integrating quality assurance protocols that command shelf space in modern trade and export channels.
FSSAI's 2024 labeling amendments mandate QR-code traceability from crushing mill to retail pack, with batch-level fatty acid profiles and fortification verification. Domestic processors must redesign packaging lines and database infrastructure to comply. Small and medium mills in Bihar and West Bengal face the steepest compliance cost burden relative to revenue.
Urban households are consolidating edible oil purchases through quick-commerce platforms promising 10-minute delivery, displacing monthly kirana stock-up behavior. Swiggy Instamart and Blinkit in Delhi and Mumbai are building dedicated oil and ghee fulfillment nodes. This channel shift is most pronounced among dual-income nuclear families in India's top 15 metropolitan clusters.
Mustard Oil Market Segmentation
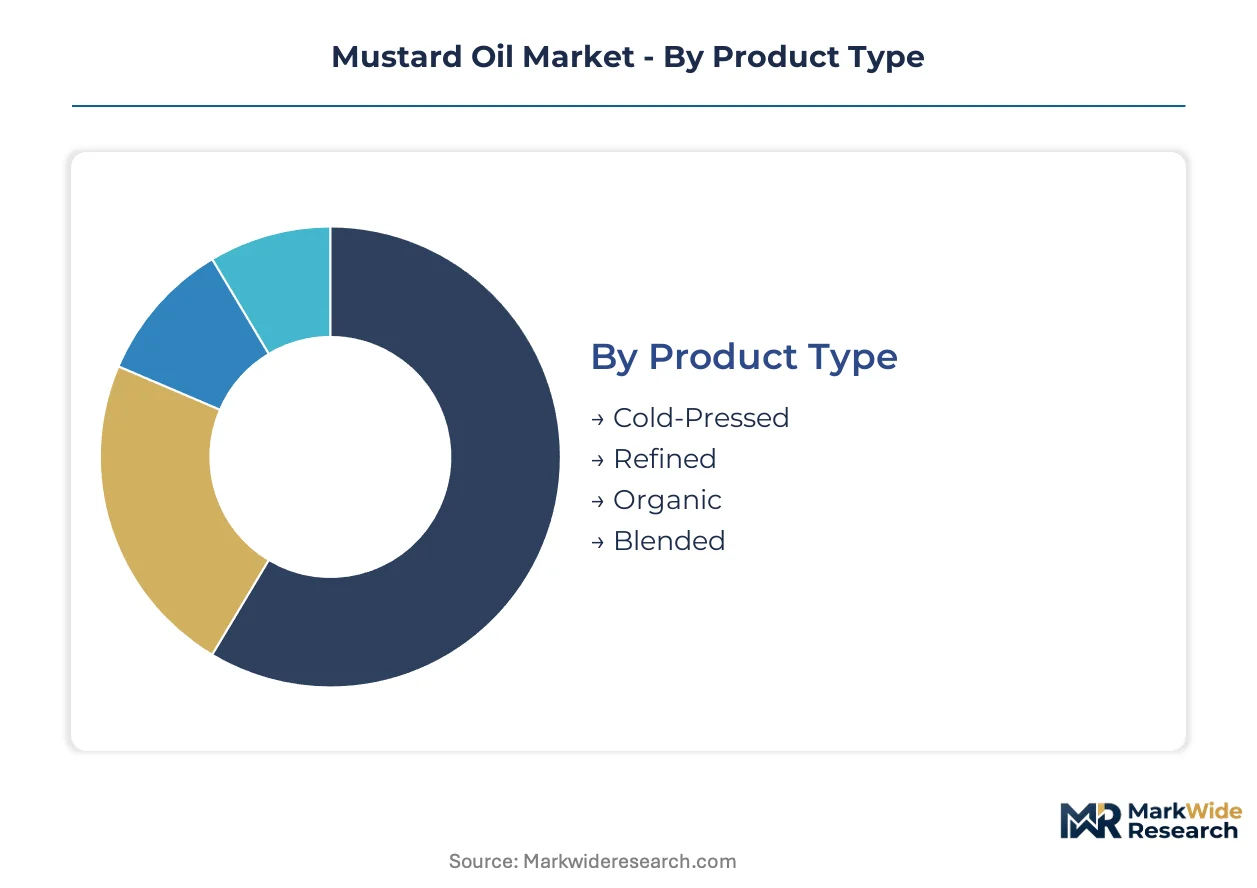
Mustard oil segmentation reflects divergent upgrade cycles across consumer tiers. Cold-pressed variants attract health-conscious households willing to pay premiums for minimal thermal degradation, while refined grades dominate institutional procurement where smoke-point consistency outweighs organoleptic intensity.
Product Type:
Replacement cycles accelerate as consumers trade up from commodity-refined to certified cold-pressed and organic grades, driven by FSSAI labeling transparency and wellness positioning.
- Cold-Pressed:Mechanical extraction below 40°C preserves allyl isothiocyanate compounds responsible for pungency and natural preservation. Urban households in Delhi and Mumbai concentrate demand here, compelled by Ayurvedic wellness narratives and minimal processing claims.
- Refined:Solvent-extracted and deodorized to neutral flavor profiles with elevated smoke points above 250°C. Bangladeshi food service operators and Indian institutional kitchens specify these batches for high-heat applications where thermal stability trumps taste intensity.
- Organic:Certified Brassica juncea cultivation without synthetic pesticides, commanding shelf space in modern trade organic aisles.
- Blended:Mustard-palm or mustard-soy combinations targeting price-sensitive volume segments in Nepal's traditional retail.
Refined sits at the top of the volume ranking, with Organic climbing the fastest.
End User:
Application-specific requirements split procurement patterns between flavor-driven and cost-driven buyers, with margin pools concentrating where batch certification matters most.
- Food Processing:Contract manufacturers of pickles, snacks, and ready-meals specify allyl isothiocyanate-rich cold-pressed grades for flavor consistency and extended shelf stability without synthetic preservatives. These buyers absorb premium pricing in exchange for certified traceability.
- Households:Nuclear families in Indian metropolitan clusters consolidate purchases through quick-commerce platforms, shifting from monthly kirana stock-ups to on-demand replenishment of 1-liter bottles and pouches.
- Restaurants:Roadside eateries and mid-tier dining establishments in Dhaka and Kathmandu adopt single-serve pouches to reduce working capital tied to inventory.
- Industrial:Biodiesel feedstock and lubricant base oil applications compete for seed supply with edible channels.
Households generate the largest absolute volume, though Food Processing delivers the steepest margin expansion.
Packaging Type:
Format innovation determines access velocity across fragmented South Asian retail terrain, with portion-controlled solutions gaining traction among cash-constrained buyers.
- Pouches:Single-serve and 200ml flexible packs reduce trial friction for urban nuclear households and roadside vendors lacking storage infrastructure. Swiggy Instamart and Blinkit fulfillment nodes prioritize these formats for 10-minute delivery promises.
- Bottles:PET and glass containers dominate modern trade shelf space, with FSSAI-mandated QR-code traceability requiring redesigned labeling infrastructure.
- Cans:Metal packaging preserves organoleptic integrity through extended distribution cycles in Nepal's mountain terrain.
- Bulk:15-liter tin containers serve institutional buyers and traditional wholesalers in Bangladesh's wet markets.
Bottles retain volume leadership, while Pouches expand most quickly through quick-commerce penetration.
Distribution Channel:
Channel concentration shapes pricing power and brand visibility, with modern trade and digital platforms extracting share from fragmented traditional networks.
- Supermarkets:Organized retail in Delhi, Mumbai, and Dhaka provides premium shelf positioning for certified cold-pressed and organic variants. Adani Wilmar and Dabur leverage pan-India networks to dominate facings in these controlled environments.
- Online Retail:Quick-commerce platforms build dedicated edible oil fulfillment nodes, displacing monthly stock-up behavior among dual-income metropolitan families.
- Wholesale:Traditional mandi networks and cash-and-carry operators serve price-sensitive bulk buyers in Bihar and West Bengal.
- Specialty Stores:Ayurvedic dispensaries and organic boutiques command 3-4x cooking-grade premiums for therapeutic-grade mustard oil positioned for external massage and nasal applications.
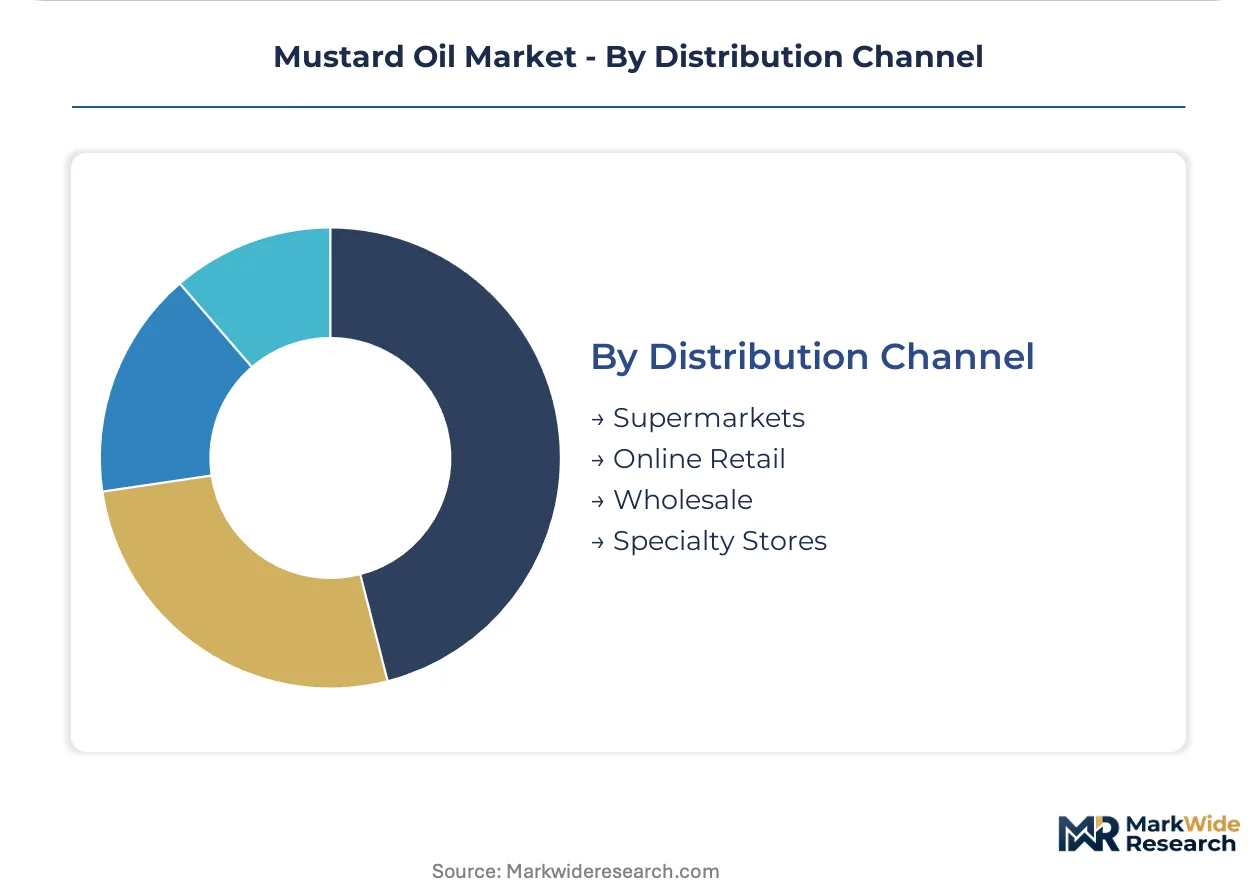
Wholesale maintains the widest reach by volume, yet Online Retail captures the steepest share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mustard oil production scaled through the Indo-Gangetic plain during the colonial era, with British-era processing infrastructure establishing the commercial foundation that persists across Bangladesh, Nepal, and eastern India today.
India
Domestic procurement of cold-pressed variants accelerates among Delhi and Mumbai households pursuing wellness positioning. FSSAI fortification mandates for Vitamin A and D injection systems force packaging line redesigns across Bihar and West Bengal processing clusters. Kolkata's traditional mill district modernizes mechanical pressing capacity to serve quick-commerce fulfillment nodes.
Bangladesh
Branded consumption concentrates in Dhaka's dual-income households adopting single-serve pouches for portion control. BSTI batch testing queues stretching 90-120 days constrain just-in-time replenishment for Nepali distributors. Chittagong's port infrastructure enables palm oil imports that erode mustard's position in food service channels.
Nepal
Per capita usage exceeds Indian levels yet packaged penetration lags below 35%, creating shelf space capture opportunities in Kathmandu's emerging modern trade. National quality specifications for edible oils layer compliance requirements atop BSTI and FSSAI standards for cross-border suppliers. Pokhara's mountain logistics favor metal can packaging preserving organoleptic integrity through extended distribution cycles.
Pakistan
Traditional consumption patterns persist in Punjab province households maintaining mustard oil as primary cooking medium. Provincial food safety authorities implement fortification guidelines tracking Indian regulatory evolution. Lahore's processing corridor expands solvent-extraction capacity serving institutional buyers prioritizing smoke-point consistency over pungency.
Sri Lanka
Ayurvedic therapeutic applications drive premium positioning among Colombo wellness retail channels commanding massage-grade price multiples. The country's national pharmaceutical regulator monitors heavy metal and aflatoxin thresholds for imported edible oils. Galle's spice processing cluster integrates mustard oil into traditional pickle manufacturing for export markets.
Mustard Oil Market Competitive Landscape
The competitive structure tilts toward diversified conglomerates with grain-oil infrastructure and Ayurvedic heritage brands. Tiered concentration persists: pan-India distributors dominate modern trade shelf space, regional millers serve traditional mandi networks, and wellness specialists extract premium multiples from therapeutic positioning. Dominant competitive moves include backward integration into seed procurement and packaging format innovation for quick-commerce channels.
Among diversified agribusiness conglomerates, Cargill, Incorporated anchors the infrastructure-heavy archetype through feedstock cost advantages across South Asian supply chains. Dabur India Ltd. and Adani Wilmar Limited occupy contrasting positions within the branded edible oil space—Dabur exemplifies Ayurvedic heritage positioning while Adani Wilmar represents scale-driven distribution dominance. These three entities collectively illustrate how grain-oil infrastructure, wellness narrative, and retail reach define competitive differentiation.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Dabur India Ltd. |
| Adani Wilmar Limited |
| Bansal Oil Mill Ltd. |
| Puri Oil Mills Limited |
| Emami Agrotech Ltd. |
| Marico |
| K. S. Oils Limited |
| Patanjali Ayurved |
| Others |
Supply & Pricing Matrix
Contract manufacturers of pickles and ready-meals anchor pricing power through certified batch specifications that absorb premium cold-pressed grades while price-sensitive institutional buyers in Bangladesh switch to refined palm oil for high-heat applications. This buyer-archete concentration splits the market into flavor-driven premium tiers and cost-driven commodity segments with divergent margin structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic cold-pressed variants from fortified refined grades and unbranded loose oil sold through traditional mandi networks. Price differentiation hinges on FSSAI certification status and allyl isothiocyanate content verification, with Ayurvedic therapeutic positioning commanding the steepest premiums for external massage applications. Cost compression in the refined institutional tier is intensifying because Chittagong's palm oil imports erode mustard's cost competitiveness for deep-frying. Food processing buyers demonstrate the least price sensitivity while Bangladeshi food service operators exhibit the highest.
Supply Chain Analysis
Single-source vulnerability sits with India's monsoon-dependent Brassica juncea harvests that feed processing clusters across Bihar and West Bengal before distribution to Bangladesh and Nepal. Raw material procurement draws from domestic seed cultivation, imported European biodiesel diversion streams, and competing industrial lubricant applications. Supply chain risk centers on tariff exposure at Bangladesh's Chittagong port where palm oil undercuts mustard positioning. Distribution runs through fragmented kirana networks in eastern India, quick-commerce fulfillment nodes in Delhi and Mumbai, and metal can logistics through Nepal's mountain terrain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mustard oil market functions as a stable compounder anchored by fortification mandates that create compliance-driven replacement demand across South Asian processing infrastructure.
For Market Incumbents: Cement defensible positioning through backward integration into seed procurement corridors across Bihar and West Bengal, securing feedstock cost advantages against European biodiesel diversion. Invest in FSSAI-mandated QR-code traceability infrastructure before smaller regional mills can absorb compliance costs, converting regulatory burden into shelf space capture at modern trade outlets. For New Entrants and Emerging Players: Begin with Nepal's branded consumption gap where packaged penetration lags below 35% despite per capita usage exceeding Indian levels, offering first-mover shelf space capture in Kathmandu's emerging modern trade. Target single-serve pouch formats for quick-commerce fulfillment nodes serving dual-income nuclear households in Dhaka and Kathmandu, reducing working capital burden for roadside vendors lacking storage infrastructure. For Investors and Strategic Acquirers: Diversified agribusiness conglomerates with grain-oil infrastructure represent the most active acquirer category in this space, seeking feedstock synergies across South Asian supply chains. Five-to-ten year viability rests on cold-chain logistics investments that determine last-mile access velocity. Watch for BSTI batch testing queue reductions as signal of cross-border replenishment acceleration enabling just-in-time supply to Nepali distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Procurement | Cargill's grain-oil infrastructure secures feedstock cost advantages across Bihar and West Bengal cultivation belts. |
| QR-Code Traceability Infrastructure | FSSAI-mandated batch labeling redesigns capture modern trade shelf space ahead of compliance-burdened regional mills. |
| Single-Serve Pouch Format Expansion | Swiggy Instamart and Blinkit fulfillment nodes prioritize portion packs for 10-minute delivery promises in metropolitan clusters. |
| Ayurvedic Therapeutic Positioning | Dabur's wellness narrative commands 3-4x cooking-grade premiums through external massage and nasal drop applications. |
| Cold-Chain Logistics Investment | Refrigerated warehousing preserves organoleptic integrity through Nepal's mountain distribution cycles and Dhaka's quick-commerce nodes. |
Research Methodology
Bottom-up household and food processing procurement modeling reconciled against top-down seed crushing capacity and trade flow tracking forms the analytical core of this study. Primary interviews with FSSAI compliance officers at Bihar and West Bengal processing clusters, procurement leads at Bangladeshi pickle manufacturers, category buyers at Delhi modern trade outlets, and cold-chain logistics operators in Kathmandu validate demand-side assumptions. Secondary sources include FSSAI fortification guidelines, BSTI batch testing disclosure records, Indian customs edible oil import data, and Nepal's national quality specification documents.
Historical trendline analysis of cold-pressed versus refined grade adoption patterns across Indian metropolitan clusters informs projection assumptions across the analysis window. Segmentation dimensions modeled include extraction method, end-user application, packaging format, and distribution channel complexity. CAGRs derive from fitted growth curves adjusted for regulatory mandate implementation timelines and quick-commerce penetration trajectories. Forecast inputs incorporate monsoon variability indices for Brassica juncea yield estimation and European biodiesel policy diversion coefficients.
Several conditions sit outside the modeled scope, including sudden FSSAI labeling amendment accelerations, Bangladeshi palm oil import tariff shocks, and Nepal's packaged penetration inflection timing. Forecasts reflect documented assumptions about compliance cost absorption capacity across regional mill tiers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Distillers Corn Oil Market
Ingredients
United States Gelatin Market
Ingredients
Global Gelatin Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
South America Feed Yeast Market
Ingredients
China Gelatin Market
Ingredients
Oat Ingredients Market
Ingredients
Soy Flour Market
Ingredients
Hexane-Free Protein Market
Ingredients
Bay Leaf Oil Market
Ingredients
Lipids Market
Ingredients
Olive Leaf Extract Market
Ingredients
Casein and Caseinates Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Lentils Flour Market
Ingredients
Smoke Ingredients for Food Market