
 L-Arabinose Market | 2026-2036
L-Arabinose Market Size, Share, and Industry Trends Forecast 2026-2036
L-Arabinose Market Outlook
Aftermarket formulation services is tilting margin pools away from commodity powder sales toward customized premix solutions for functional food brands. Healtang Biotech leverages its Shandong production base to dominate pharmaceutical-grade output. Roquette Frères anchors European supply through its plant-derived extraction expertise and established F&B channel relationships. CJ CheilJedang Corporation differentiates via integrated fermentation platforms that sustain cost advantages in crystalline L-arabinose production.
L-arabinose is a pentose sugar (C5H10O5) extracted from hemicellulose in plant biomass such as corn cobs, sugar beet pulp, and gum arabic, functioning primarily as a sucrose metabolism inhibitor that suppresses intestinal sucrase activity. Powder formulations occupy the largest volume share due to straightforward blending into bakery, confectionery, and beverage applications, though syrup and liquid concentrates are gaining traction in ready-to-drink functional beverages where solubility and dosing precision matter. The food and beverages segment leads absolute consumption, while dietary supplements represent the fastest-expanding application as metabolic health positioning drives new product development in North American and Asian markets.
China's SAMR and NMPA enforce GB standards for food additive purity and novel ingredient registration, directly shaping which suppliers gain domestic market access and influencing export certification requirements for international players. Japan's MHLW and FOSHU framework create a regulated pathway for L-arabinose health claims, conditioning product positioning and clinical substantiation investments for entrants targeting functional food status. Stakeholders must monitor evolving sucrase-inhibitor health claim pathways and fermentation technology cost curves to calibrate capacity commitments and geographic prioritization.
Market Dynamics
Precision fermentation capacity expansion in East Asia is compressing unit economics for crystalline L-arabinose, forcing extraction-based suppliers to defend position through pharmaceutical-grade certification and captive hemicellulose supply.
Growth Catalysts
- Metabolic health positioning:Functional food brands in Japan leverage MHLW's FOSHU framework to secure sucrase-inhibitor claims, accelerating formulation demand for validated L-arabinose grades.
- GB standard alignment:China's SAMR enforcement of tightened food additive purity specifications is filtering non-compliant imports and consolidating domestic supplier market access.
- Hemicellulose valorization:Corn wet millers and sugar beet processors are capturing pentose streams previously discarded, expanding feedstock availability for extraction-based production.
Market Restraints
- Feedstock cost volatility:Corn cob and sugar beet pulp pricing fluctuates with agricultural commodity cycles, squeezing margin stability for plant-derived extraction operations.
- Supplier concentration:Shandong province hosts disproportionate crystalline L-arabinose fermentation capacity, creating geographic risk exposure for buyers dependent on Chinese supply.
- Enzymatic substitution:Sucrase-inhibitor peptides and synthetic alternatives threaten L-arabinose's core functional positioning in glucose management applications.
Strategic Opportunities
- North American supplement penetration:FDA GRAS self-affirmation pathways remain underutilized for L-arabinose, offering first-mover positioning in metabolic health SKUs targeting prediabetic consumers.
- Precision fermentation scale-up:Integration of CRISPR-optimized yeast strains with continuous bioprocessing is collapsing production costs for food-grade crystalline output.
- Direct-to-brand premix services:Functional beverage startups seek turnkey sucrose-inhibition solutions, bypassing traditional ingredient distribution tiers.
Industry Challenges
- Analytical capability gaps:Commercial labs struggle with pentose stereoisomer differentiation, delaying certificate-of-analysis turnaround for pharmaceutical-grade shipments.
- Dual-use registration complexity:Suppliers seeking both food additive and API status face divergent NMPA and FDA documentation requirements, extending compliance timelines.
- Legacy equipment retrofit costs:Extraction facilities require crystallization train upgrades to meet evolving GB standards for heavy metal and microbial specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | L-Arabinose Market |
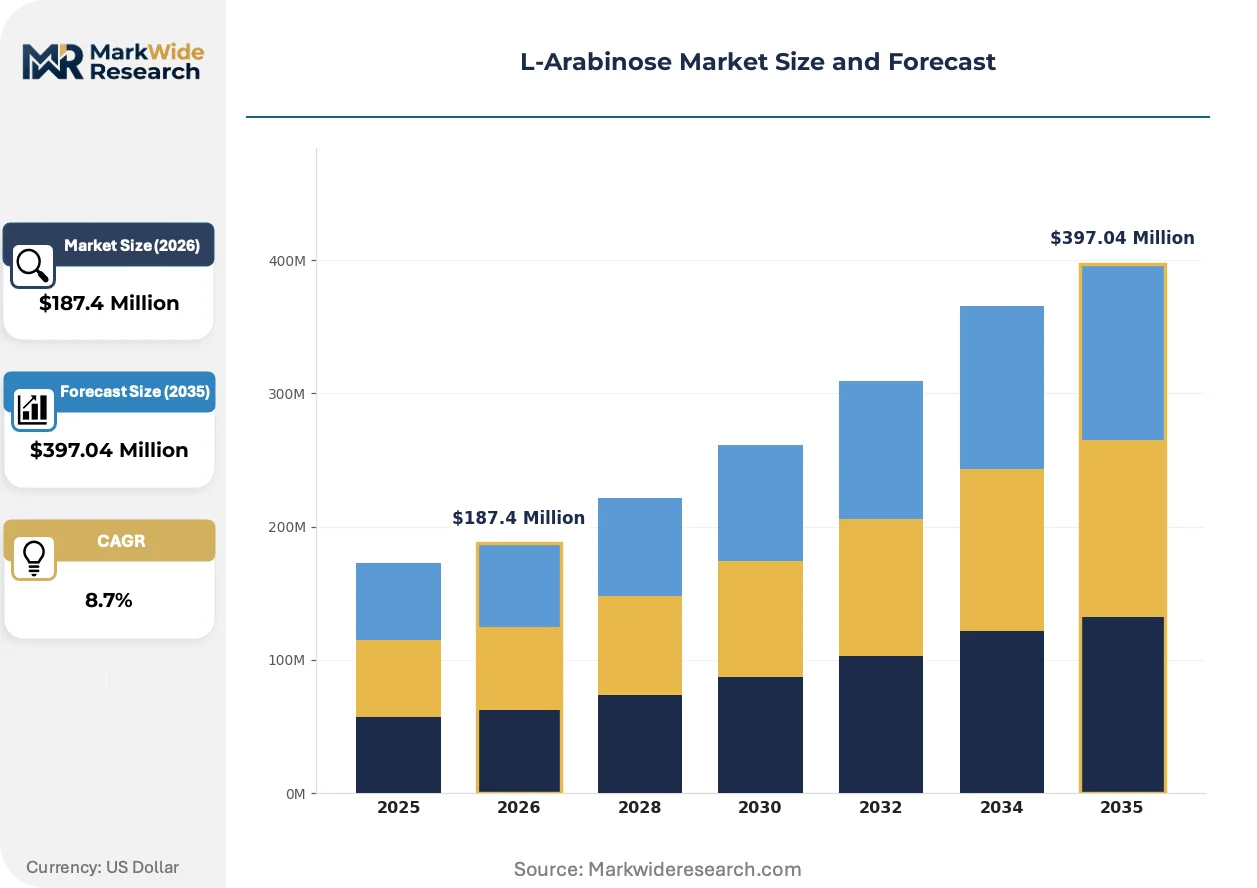
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Syrup, Tablets Application: Food & Beverages, Pharmaceuticals, Dietary Supplements, Cosmetics End User: Manufacturers, Distributors, Retailers, Research Institutions Form: Liquid, Solid, Concentrated, Crystalline |
| Companies Covered | Healtang Biotech, Shandong Longlive Bio-Technology, Danisco, Dalian Xindie Bio-Engineering, Yuwang Group, CJ CheilJedang Corporation, Futaste Pharmaceutical, Shandong Lujian Biological Technology, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
L-Arabinose Market Strategic Shifts
Bioprocess intensification and regulatory claim substantiation are converging to redefine competitive advantage, shifting value capture from commodity volume to certified functional positioning.
Continuous fermentation with cell retention is collapsing capital intensity for crystalline L-arabinose production. Biotech engineering firms in South Korea and China are deploying perfusion bioreactor designs that achieve pharmaceutical-grade titers at food-grade operating costs. This compression is enabling mid-scale entrants to challenge established extraction-based suppliers on specification parity.
EFSA's evolving guidance on carbohydrate metabolism health claims is tightening clinical substantiation requirements for European functional food applications. Manufacturers must now generate human intervention data demonstrating sucrase inhibition at realistic consumption doses. The dietary supplement segment faces the steepest compliance cost escalation, with several brands withdrawing unvalidated metabolic positioning.
Formulation houses are unbundling technical service from ingredient supply, selling sucrose-reduction consulting to bakery and confectionery brands. This service layer captures margin previously retained by finished product manufacturers. The shift is most visible in Japan, where FOSHU-approved L-arabinose formulations command premium positioning in aging-population convenience foods.
L-Arabinose Market Segmentation
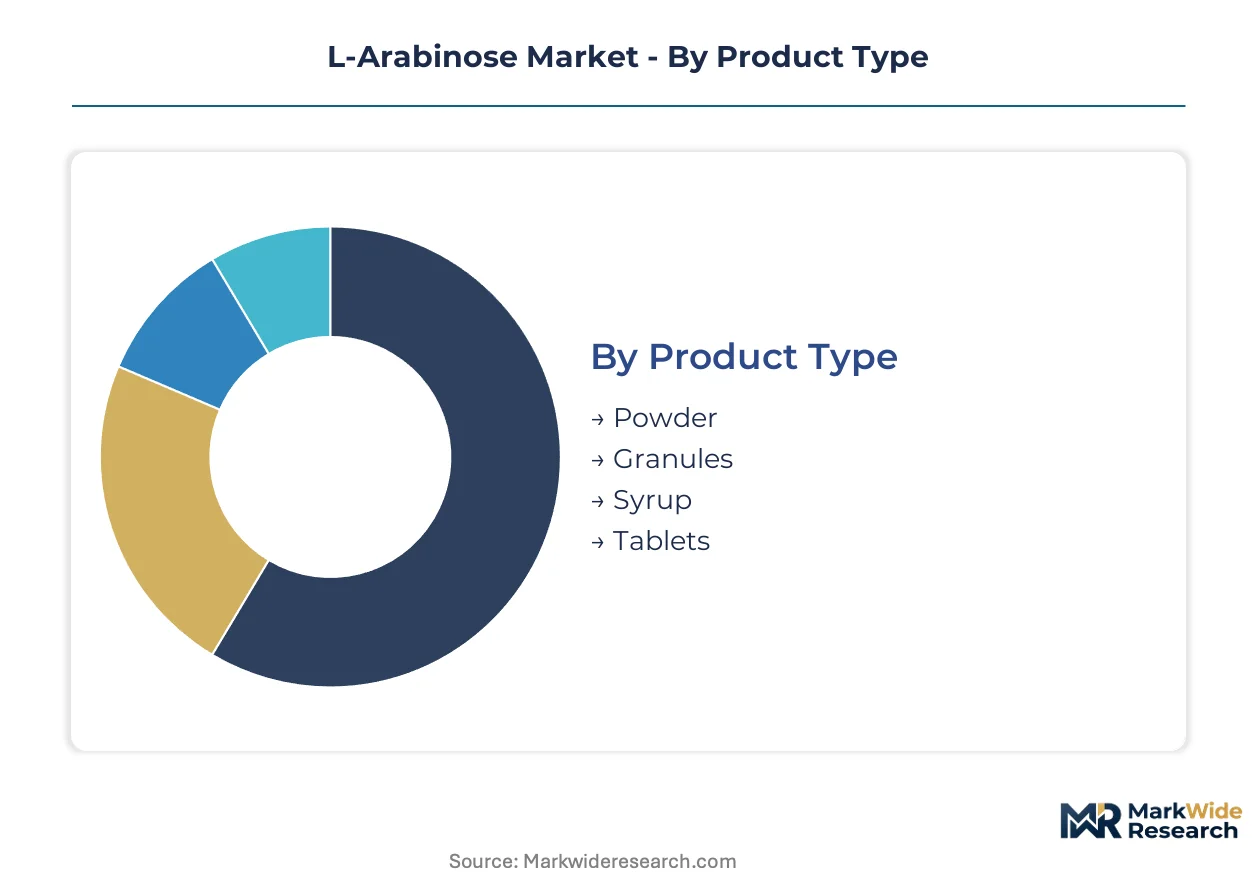
Segmentation in the L-arabinose market reveals divergent margin profiles and compliance burdens across physical forms and customer types. Powder and crystalline grades command pharmaceutical premiums, while syrup concentrates accelerate in ready-to-drink functional beverages where dosing precision matters.
Product Type:
Cycle times vary dramatically: powder formulations turn inventory weekly through bulk F&B channels, while tablet production runs align with quarterly pharmaceutical procurement cycles.
- Powder:Fine crystalline or spray-dried particles enable direct blending into bakery, confectionery, and beverage matrices. Demand concentrates in China's Shandong production corridor, where corn cob hemicellulose extraction feeds integrated powder-to-premix operations serving domestic functional food brands.
- Syrup:Aqueous solutions with standardized Brix levels facilitate precise pump dosing in continuous beverage manufacturing lines. Japanese FOSHU-approved functional drinks in Tokyo and Osaka metropolitan areas are the primary expansion vector, with MHLW claim substantiation requirements filtering supplier qualification.
- Granules:Agglomerated particles improve flowability for high-speed tableting operations.
- Tablets:Compressed unit doses target prediabetic consumer segments in North American supplement retail.
Powder dominates installed base. Syrup is where expansion concentrates.
Application:
Cost tier stratification separates commodity food additive grades from pharmaceutical API specifications requiring dual-use registration.
- Food & Beverages:Sucrose inhibition functionality drives incorporation into reduced-sugar bakery, confectionery, and carbonated drinks. China's SAMR enforces GB standards for additive purity, consolidating market access around NMPA-registered domestic suppliers and compliant importers.
- Dietary Supplements:Metabolic health positioning targets prediabetic populations through capsule, tablet, and powder delivery formats. FDA GRAS self-affirmation pathways in the United States remain underutilized, offering positioning advantages for first movers in glucose management SKUs.
- Pharmaceuticals:API-grade material requires certificate-of-analysis documentation for heavy metal and microbial specifications.
- Cosmetics:Humectant and prebiotic properties support skin microbiome formulations.
Food & Beverages anchors volume throughput. Dietary Supplements is climbing the fastest.
End User:
Customer type determines technical service intensity, with manufacturers demanding formulation support and retailers prioritizing turnkey private label solutions.
- Manufacturers:Integrated food, beverage, and pharmaceutical producers procure bulk crystalline grades for in-house formulation. Precision fermentation scale-up in South Korean biotech clusters is compressing unit economics, enabling qualified supply to mid-scale manufacturers previously dependent on Chinese extraction-based sources.
- Distributors:Inventory carrying and lot consolidation services bridge fragmented regional demand in Southeast Asian and Middle Eastern markets.
- Retailers:Private label functional food and supplement brands in Japanese convenience and drugstore channels.
- Research Institutions:Clinical and preclinical studies on sucrase inhibition mechanisms and metabolic outcomes.
Manufacturers command procurement scale. Research Institutions represent the steepest expansion trajectory for validated clinical-grade material.
Form:
Supply concentration in crystalline production creates specification premiums, while liquid concentrates enable geographic arbitrage through reduced shipping mass.
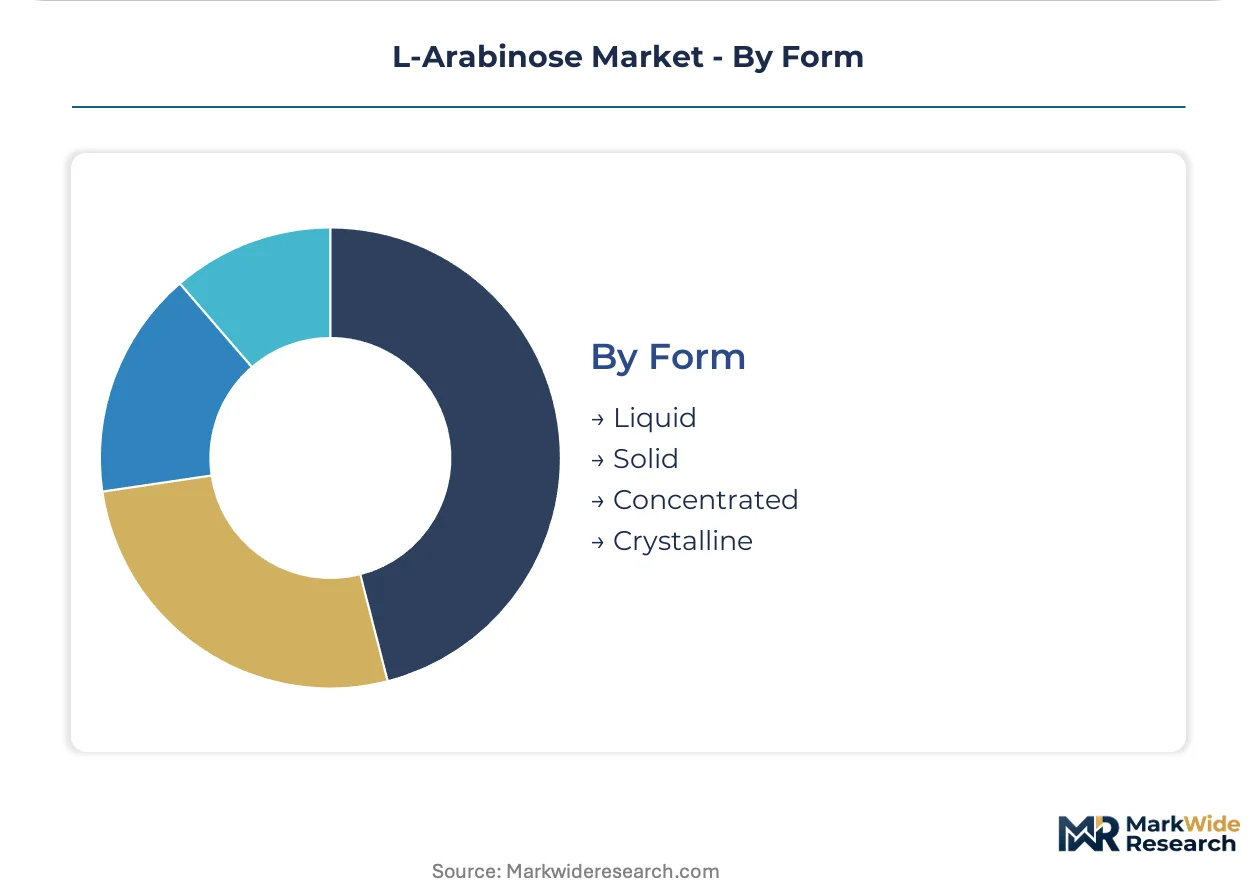
- Crystalline:High-purity solid with defined melting point and optical rotation specifications. Pharmaceutical-grade output from Healtang Biotech's Shandong fermentation trains supplies domestic API manufacturers and export markets requiring NMPA export certificates.
- Liquid:Aqueous or hydroalcoholic solutions with preserved bioactivity for beverage and cosmetic applications. European formulators in France and Germany leverage liquid concentrates to bypass crystallization energy costs and align with EU Green Deal decarbonization targets.
- Solid:Amorphous or semi-crystalline bulk for industrial processing.
- Concentrated:High-potency extracts for downstream dilution and standardization.
Crystalline dominates specification-sensitive segments. Liquid is gaining share fastest in sustainability-weighted procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan exhibit the lowest price elasticity, absorbing pharmaceutical-grade premiums for FOSHU-validated formulations, while Southeast Asian processors remain acutely sensitive to crystalline L-arabinose feedstock costs. China's domestic procurement anchors global volume throughput. European formulators prioritize sustainability credentials over unit economics.
China
Shandong province concentrates fermentation-based crystalline production, serving domestic functional food brands and API manufacturers. SAMR enforcement of tightened GB standards for food additive purity filters non-compliant imports and consolidates market access around NMPA-registered domestic suppliers. Corn wet millers in Jinan and Weifang capture pentose streams from hemicellulose extraction previously discarded as waste.
Japan
Tokyo and Osaka metropolitan areas drive FOSHU-approved functional beverage demand, with MHLW claim substantiation requirements conditioning supplier qualification. Aging-population convenience food brands absorb premium pricing for validated sucrase-inhibitor positioning. Precision fermentation scale-up in Kyushu biotech clusters challenges traditional extraction economics.
United States
Prediabetic consumer segments in California and Texas propel dietary supplement demand through capsule and tablet delivery formats. FDA GRAS self-affirmation pathways remain underutilized, offering first-mover positioning for metabolic health SKUs. Functional beverage startups in Colorado and Oregon seek turnkey sucrose-inhibition solutions bypassing traditional distribution tiers.
Germany
Roquette Frères anchors European supply through plant-derived extraction expertise and established F&B channel relationships. EFSA's evolving guidance on carbohydrate metabolism health claims tightens clinical substantiation requirements, escalating compliance costs for European functional food applications. Cologne and Hamburg formulation houses sell sucrose-reduction consulting to bakery and confectionery brands.
South Korea
Busan-Ulsan biotech engineering firms deploy perfusion bioreactor designs achieving pharmaceutical-grade titers at food-grade operating costs. CRISPR-optimized yeast strains integrated with continuous bioprocessing collapse production costs for crystalline output. Domestic manufacturers previously dependent on Chinese extraction-based sources now access qualified local supply.
L-Arabinose Market Competitive Environment
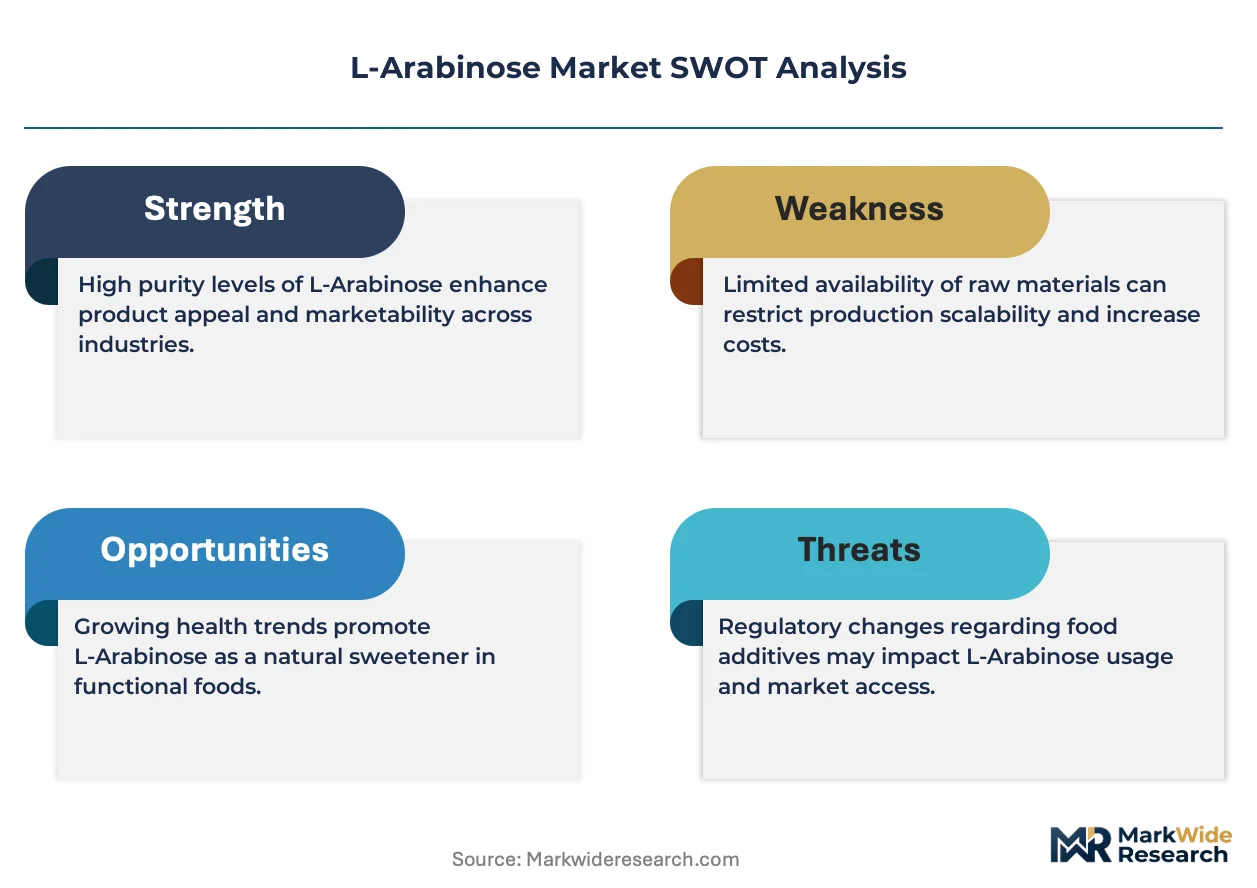
Precision fermentation specialists and plant-derived extraction houses split the market along specification-grade fault lines. The structure consolidates around three archetypes: integrated biotech platforms with captive fermentation capacity, agricultural processors valorizing hemicellulose waste streams, and formulation-forward ingredient houses unbundling technical services from commodity supply. Dominant competitive moves include capacity expansion in East Asian precision fermentation clusters and strategic partnerships between extraction-based suppliers and pharmaceutical-grade certification laboratories.
Within the integrated biotech tier, Healtang Biotech and CJ CheilJedang Corporation exemplify fermentation-based cost advantages, while Roquette Frères occupies a position representing European plant-extraction expertise. These three anchors illustrate the geographic and technological bifurcation shaping procurement decisions: Shandong-based fermentation trains supply domestic API manufacturers and export markets requiring NMPA export certificates, South Korean integrated platforms challenge on unit economics, and French extraction specialists defend through sustainability-weighted European procurement criteria.
| Leading Market Players |
|---|
| Healtang Biotech |
| Shandong Longlive Bio-Technology |
| Danisco |
| Dalian Xindie Bio-Engineering |
| Yuwang Group |
| CJ CheilJedang Corporation |
| Futaste Pharmaceutical |
| Shandong Lujian Biological Technology |
| Roquette Frères |
| Others |
Value Chain & Pricing Dynamics
Shandong province's fermentation corridor concentrates crystalline L-arabinose capacity, translating upstream scale into pricing leverage over downstream pharmaceutical-grade buyers. Corn wet millers in Jinan and Weifang valorize hemicellulose waste streams, compressing feedstock costs and enabling aggressive positioning against extraction-based European suppliers.
Pricing Analysis
Aftermarket formulation services and premix consulting now capture lifetime value exceeding commodity powder sales. Three-tier pricing structure across pharmaceutical-grade, food-additive, and feed-grade levels reflects NMPA registration status and certificate-of-analysis turnaround capabilities. Cost compression in food-grade crystalline output is intensifying because South Korean perfusion bioreactor deployments are collapsing unit economics. Pharmaceutical buyers in Japan exhibit the lowest price sensitivity, absorbing FOSHU-validation premiums, while Southeast Asian processors remain acutely responsive to feedstock cost fluctuations.
Supply Chain Analysis
Export-control scrutiny on CRISPR-optimized yeast strains and continuous bioprocessing equipment limits technology transfer to emerging fermentation hubs. Supply concentrates in China, South Korea, and France, with corn cob hemicellulose and sugar beet pulp anchoring extraction economics. Single-source vulnerability runs through Shandong's disproportionate share of global crystalline capacity. Distribution runs through NMPA-registered domestic suppliers and compliant importers serving food and beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The L-arabinose market reads as a service-attach opportunity where formulation consulting and turnkey premix solutions expand faster than commodity ingredient sales. Recurring revenue from FOSHU claim substantiation and customized sucrose-reduction consulting now outpaces hardware-like powder throughput growth.
For Market Incumbents: Pre-empt enzymatic substitution threats by locking pharmaceutical-grade certification capacity and securing captive hemicellulose supply from corn wet millers. Backward integration into Jinan and Weifang pentose streams defends margin position against South Korean fermentation scale-up. Channel control through direct-to-brand premix services captures margin previously retained by finished product manufacturers. For New Entrants and Emerging Players: Pursue FDA GRAS self-affirmation pathways for metabolic health positioning in North American dietary supplements, the most penetrable segment given underutilized regulatory routes. Target functional beverage startups in Colorado and Oregon seeking turnkey sucrose-inhibition solutions bypassing traditional distribution tiers. Go-to-market through formulation-forward technical service unbundling accelerates customer acquisition versus commodity supply pitches. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation platforms with CRISPR-optimized strain libraries and continuous bioprocessing capabilities over legacy extraction assets. Long-term viability hinges on regulatory claim substantiation infrastructure and dual-use registration expertise spanning NMPA and FDA pathways. Watch for EFSA guidance tightening on carbohydrate metabolism health claims as an inflection indicator for European compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | CRISPR-optimized yeast strains integrated with perfusion bioreactors collapse crystalline production costs. |
| FOSHU Claim Substantiation | MHLW-approved health claims in Japan command premium positioning for validated sucrase-inhibitor formulations. |
| Backward Integration into Hemicellulose | Corn wet millers capturing pentose streams expand feedstock security for extraction-based suppliers. |
| Direct-to-Brand Premix Services | Turnkey sucrose-reduction consulting captures margin from functional beverage startups bypassing distributors. |
| Dual-Use Registration Investment | Simultaneous NMPA food additive and API status extends addressable market for compliant suppliers. |
Study Parameters
The analysis maps precision fermentation platforms, plant-derived extraction operations, and formulation service providers, each validated through fermentation engineers, regulatory affairs specialists at NMPA and FDA, procurement managers at functional food brands, and technical directors at premix houses. Primary interviews triangulate against customs and trade data, NMPA registration filings, EFSA guidance documents, and FOSHU approval databases. Bottom-up capacity assessments and top-down demand modeling cross-validate volume and value outputs.
Assumptions hold precision fermentation cost curves on observed trajectories while allowing regulatory claim substantiation timelines to vary across geographies. Segmentation dimensions span physical form, application grade, end-user type, and production technology across the analysis window. CAGRs derive from installed capacity expansion, feedstock availability projections, and penetration assumptions for metabolic health positioning. Industry-specific inputs include sucrase-inhibitor clinical validation requirements and evolving GB standard enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by South Korean biotech engineering firms or sudden EFSA claim withdrawals would shift outcomes. Material shifts in NMPA dual-use registration requirements or CRISPR strain export control tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Caramel Ingredient Market
Ingredients
Quark Powder Market
Ingredients
Ground-Nut Oil Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Mirepoix Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Jojoba Oil Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
Desiccated Coconut Market
Ingredients
Konjac Flour Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Global Pregelatinized Starch Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Shortening Powder Market