
 Native Whey Protein Market | 2026-2036
Native Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Native Whey Protein Market Insights
Ingredient formulation services is reconfiguring margin distribution across the native whey protein value chain. Arla Foods leverages its Scandinavian dairy cooperative structure to secure raw milk supply for native whey extraction. Glanbia Nutritionals anchors its position through deep specialization in sports nutrition ingredient systems. Fonterra Co-operative Group dominates Oceania's grass-fed native whey output, competing on traceability credentials with European suppliers.
Native whey protein denotes the undenatured protein fraction extracted directly from fresh skim milk via cold microfiltration, preserving the native quaternary structure and bioactive peptide content with typical protein concentrations ranging from 80% to 95% depending on processing intensity. Its primary commercial purpose centers on delivering superior leucine bioavailability and intact immunoglobulins for muscle protein synthesis and immune modulation in performance nutrition. The isolate segment commands premium positioning due to higher protein purity and lower lactose burden, while hydrolysate variants are gaining traction in rapid-absorption applications for post-workout recovery. Sports nutrition remains the dominant application channel, though functional foods incorporation into fortified beverages and bakery matrices represents the fastest-expanding margin pool.
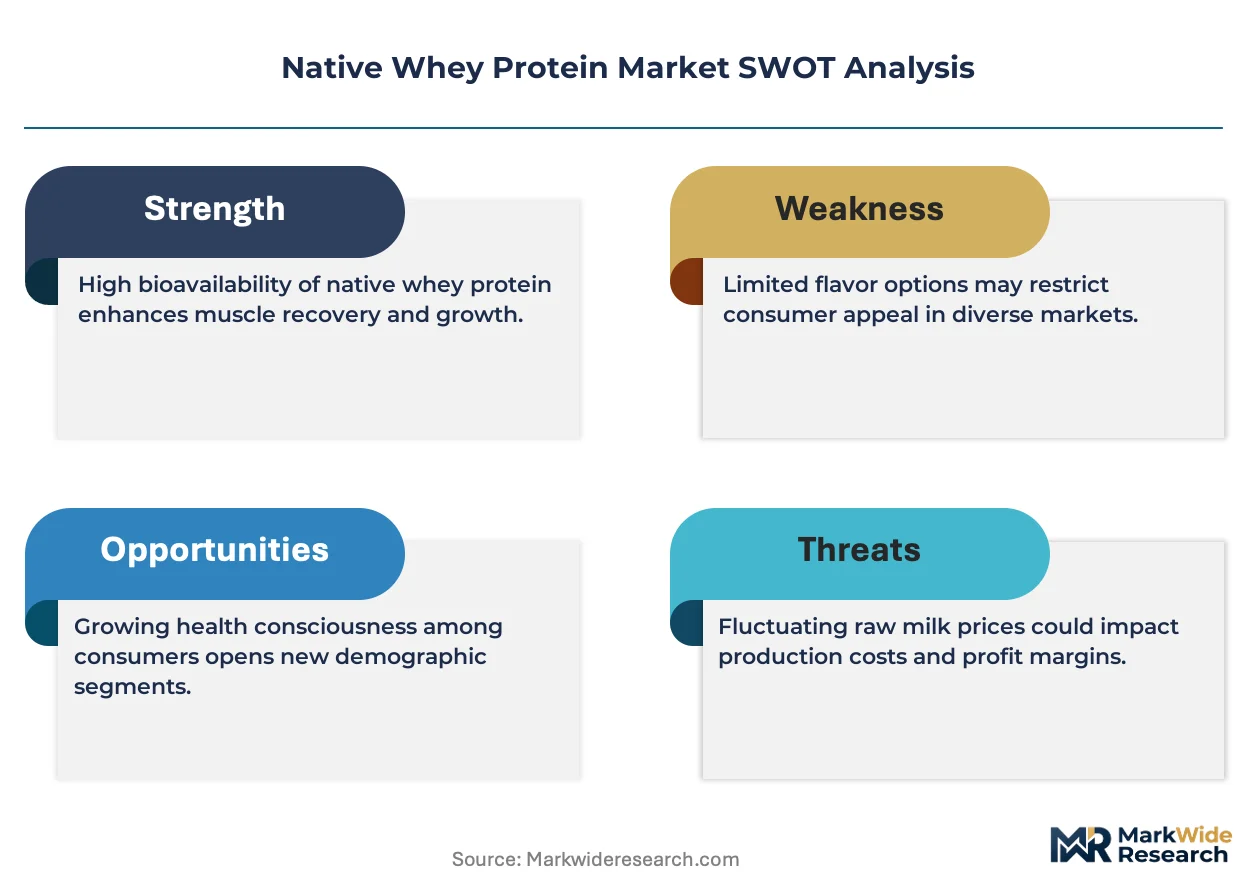
The U.S. FDA oversees protein content labeling and health claim substantiation, while the USDA regulates organic and grass-fed certification pathways that shape premium tier access. Europe's EFSA and EMA frameworks govern novel food approvals and nutritional health claims, with REACH compliance affecting processing aid chemicals used in membrane filtration systems. Stakeholders must monitor evolving protein content verification standards and clean-label certification requirements as regulatory scrutiny intensifies across both markets.
Market Dynamics
Cold microfiltration technology advances in Germany and New Zealand are compressing protein denaturation rates while expanding commercial scale, fundamentally restructuring how native whey isolates compete on bioactive retention credentials against commodity whey concentrates.
Growth Catalysts
- Sports nutrition demand:Athletes and fitness enthusiasts in the United States prioritize clean-label protein sources with intact immunoglobulin profiles, pulling volume toward undenatured isolate formats.
- REACH compliance evolution:Processing aid chemical restrictions under Europe's REACH framework are accelerating membrane filtration equipment upgrades that improve native protein yield rates.
- Grass-fed certification:USDA organic and grass-fed pathways in the United States create premium tier access for traceable native whey with verified pasture-based sourcing.
Market Restraints
- Fresh milk supply concentration:Scandinavian and Oceania dairy cooperative structures control raw input access, limiting independent processor entry.
- Technical yield ceiling:Cold filtration systems face protein retention limits near 95% purity before structural degradation occurs.
- Plant protein substitution:Pea and fava protein isolates compete on cost and sustainability positioning in functional food applications.
Strategic Opportunities
- Medical nutrition penetration:Specialized nutrition clinics in the United States represent underdeveloped channels for immunoglobulin-rich native whey in immune-modulation protocols.
- EFSA health claim pathway:Novel food approvals and substantiated muscle protein synthesis claims open premium positioning in European sports nutrition.
- Direct-to-consumer subscription:E-commerce platforms bypass traditional ingredient distribution, capturing margin from fitness enthusiasts seeking traceable sourcing.
Industry Challenges
- Membrane filtration expertise shortage:Skilled operators for cold microfiltration systems remain scarce in emerging production regions.
- Clean-label certification timelines:Third-party verification for non-GMO and grass-fed claims extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Native Whey Protein Market |
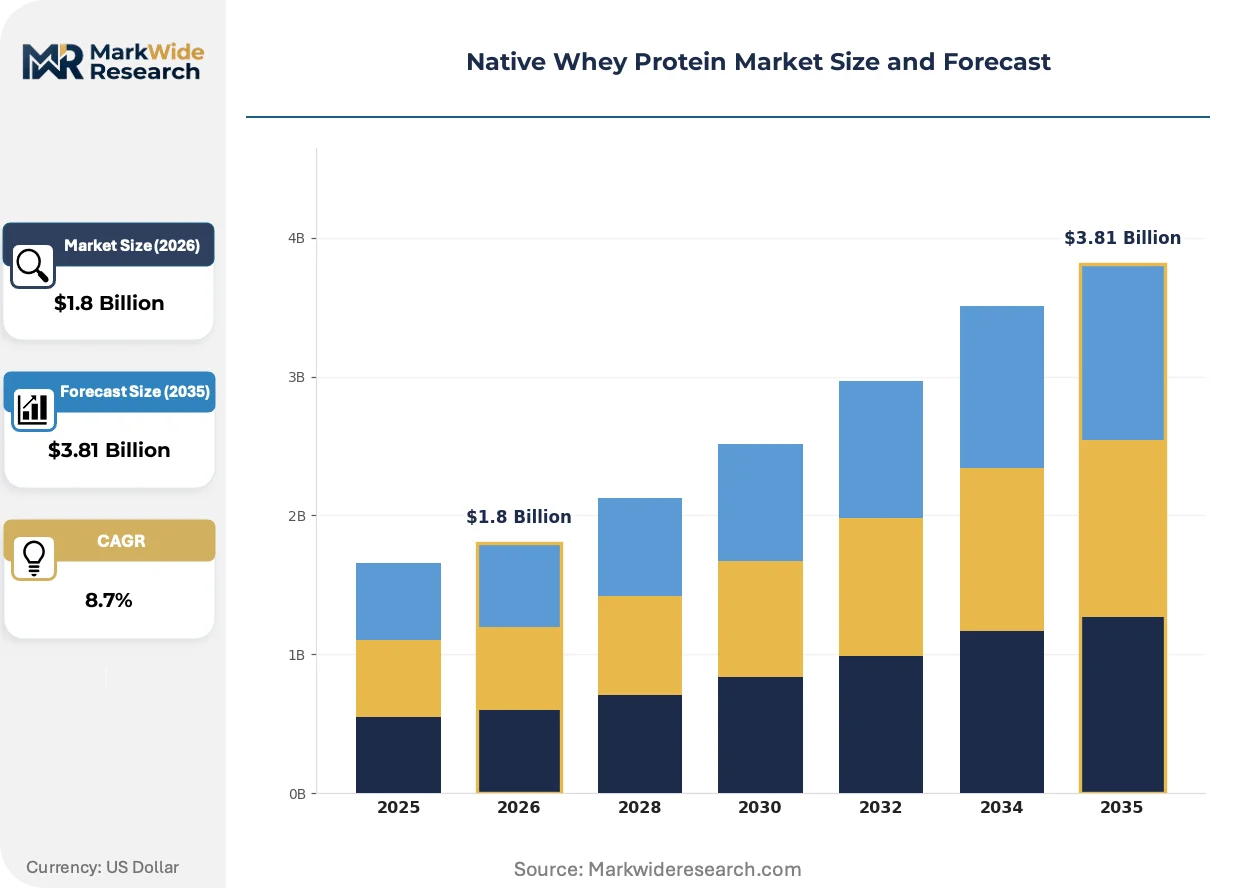
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolysate, Micellar Native Whey Application: Sports Nutrition, Functional Foods, Dietary Supplements, Weight Management End User: Athletes, Bodybuilders, Fitness Enthusiasts, Nutritional Clinics Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Arla Foods, Lactalis Ingredients, Ingredia SA, MILEI GmbH, Fonterra Co-operative Group, Glanbia Nutritionals, DMK Deutsches Milchkontor, Carbery Group, Hilmar Cheese Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Native Whey Protein Market Trends and Innovations
Digital process control and real-time protein structure monitoring are compressing quality variance in native whey production. Three developments are reshaping competitive positioning.
Inline spectroscopic monitoring is digitizing quality assurance workflows in cold filtration plants. German equipment manufacturers deploy near-infrared systems that track quaternary protein structure in real time. Sports nutrition ingredient buyers now demand batch-level bioactivity certificates, compressing tolerance for post-hoc testing failures.
EFSA's evolving framework for novel protein health claims is tightening substantiation requirements across European markets. Manufacturers must generate clinical trial data for muscle protein synthesis assertions. The isolate segment bears the heaviest compliance burden, with premium brands accelerating investment in proprietary peptide research.
Ingredient buyers are consolidating procurement around vertically integrated dairy cooperatives with captive native whey streams. Functional food manufacturers in the United States increasingly bypass traders, contracting directly with New Zealand and Scandinavian suppliers for multi-year volume commitments. This disintermediation concentrates pricing power with raw milk controllers.
Native Whey Protein Market Segmentation
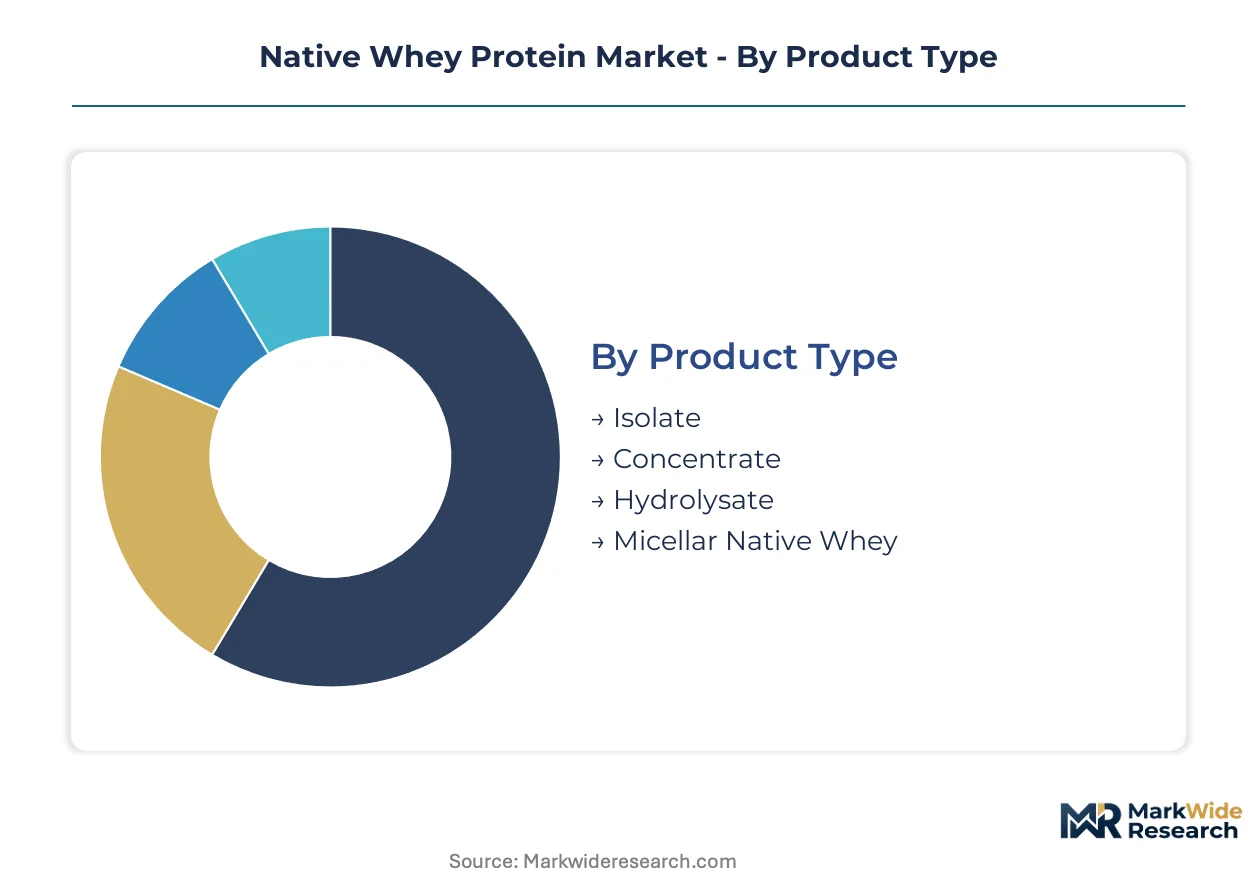
Native whey protein segmentation reflects divergent processing intensities and bioactive retention thresholds. Product format selection determines leucine bioavailability specifications and immunoglobulin preservation levels that end-users prioritize.
Product Type:
Isolate formats turn inventory fastest through sports nutrition procurement, while micellar variants move slowly due to specialized medical applications.
- Isolate:Cold microfiltration achieves 90-95% protein concentration with minimal lactose and intact quaternary structures. Demand concentrates in United States sports nutrition where athletes verify immunoglobulin retention certificates. FDA labeling requirements for protein content substantiation shape purity specifications.
- Hydrolysate:Enzymatic pre-digestion cleaves peptide bonds for rapid absorption kinetics. Post-workout recovery applications in German and New Zealand markets prioritize gastric emptying speed over bioactive preservation.
- Concentrate:Lower processing intensity yields 80% protein with higher lactose burden, serving cost-sensitive functional food fortification.
- Micellar Native Whey:Intact casein micelle structure requires specialized membrane configuration, limiting production to Scandinavian and Oceania cooperative facilities.
Isolate dominates installed base. Hydrolysate is where expansion concentrates.
Application:
Cost tier stratification separates premium clinical applications from mass-market functional food incorporation.
- Sports Nutrition:Protein bars, ready-to-drink formulations, and pre-workout systems specify undenatured isolate for leucine threshold activation. United States fitness enthusiasts drive volume through direct-to-subscription platforms.
- Functional Foods:Bakery matrices and fortified beverages absorb lower-purity concentrates. Pea protein substitution pressures margin in this tier.
- Dietary Supplements:Capsule and powder formats for general wellness consumers emphasize clean-label certification over bioactivity metrics.
- Weight Management:Meal replacement protocols in specialized nutrition clinics specify high-satiety micellar structures with documented gastric retention.
Sports Nutrition commands revenue concentration. Functional Foods is climbing the fastest.
End User:
Customer sophistication determines specification stringency and certification requirements across procurement channels.
- Athletes:Elite competitors in United States and German markets demand batch-level bioactivity certificates with quaternary structure verification.
- Bodybuilders:High-frequency training protocols prioritize leucine dosing precision and rapid absorption kinetics.
- Fitness Enthusiasts:Recreational users drive e-commerce volume with traceable sourcing preferences but lower technical specification awareness.
- Nutritional Clinics:Immune-modulation protocols specify immunoglobulin-rich native whey with USDA organic or grass-fed verification.
Fitness Enthusiasts represent volume base. Nutritional Clinics is where premium positioning concentrates.
Distribution Channel:
Margin capture varies with supply chain length and certification handling requirements.
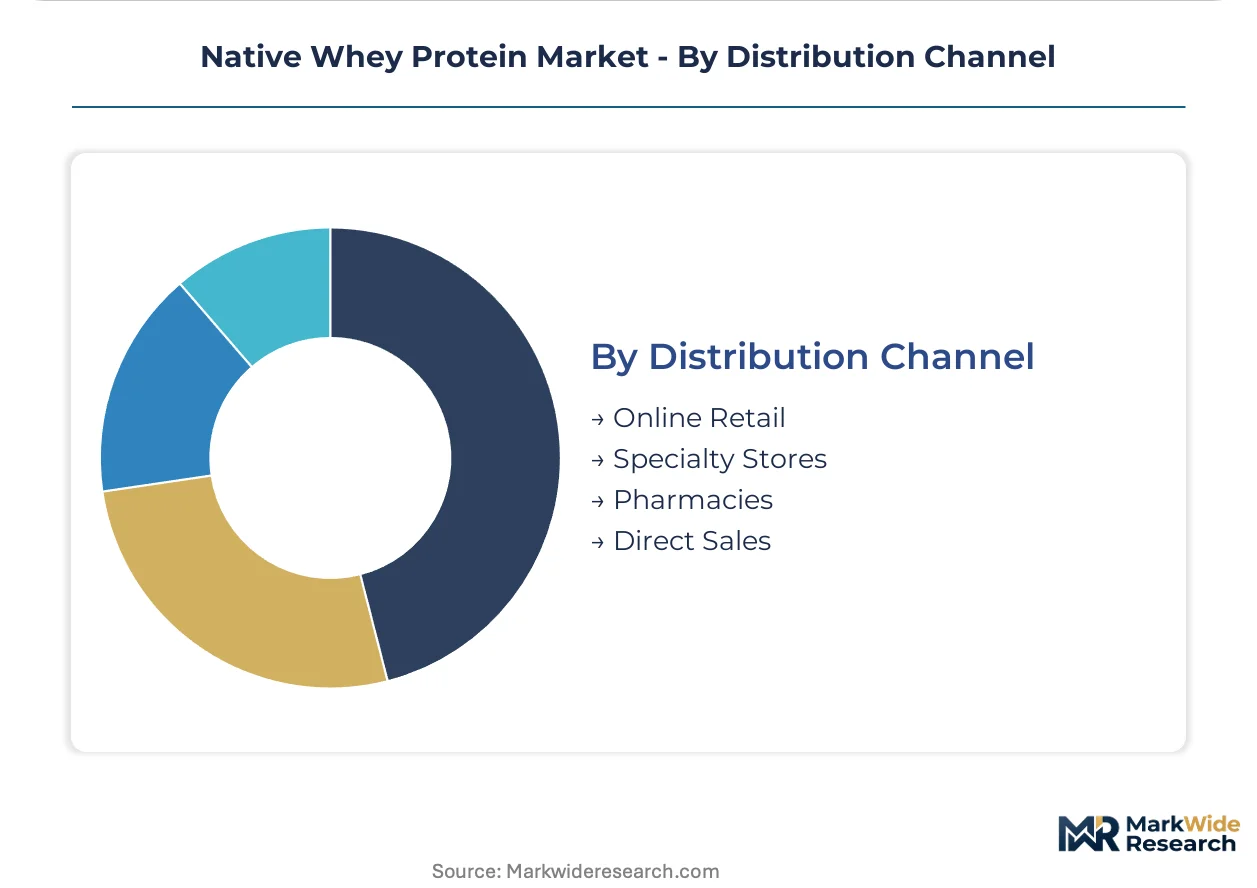
- Online Retail:Amazon and specialized fitness platforms bypass ingredient traders, capturing margin through subscription models with verified pasture-based sourcing claims.
- Specialty Stores:GNC and equivalent channels provide education-intensive environments for bioactive differentiation.
- Pharmacies:Clinical nutrition positioning requires EFSA health claim substantiation in European markets.
- Direct Sales:Multi-year volume commitments between functional food manufacturers and New Zealand or Scandinavian cooperatives eliminate intermediary margin.
Online Retail dominates transaction velocity. Direct Sales is where pricing power concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States buyers absorb premium pricing for grass-fed certification, while functional food manufacturers in emerging markets prioritize cost-competitive concentrate formats.
United States
Fitness enthusiasts and specialized nutrition clinics drive premium isolate uptake, with direct-to-consumer subscription models capturing margin from traceability-conscious buyers. FDA protein content labeling requirements and USDA organic certification pathways shape product launch timelines. California and Colorado host the densest cluster of sports nutrition formulators demanding batch-level bioactivity verification.
Germany
Cold microfiltration equipment manufacturers and enzymatic hydrolysate specialists serve post-workout recovery applications across German-speaking markets. REACH compliance evolution accelerates membrane filtration upgrades that improve native protein yield rates. Bavaria anchors production gravity with dairy cooperatives operating integrated native whey extraction facilities.
New Zealand
Grass-fed native whey output dominates Oceania supply, competing on traceability credentials with European suppliers. Fonterra's cooperative structure secures captive raw milk access for undenatured protein extraction. Canterbury and Waikato concentrate dairy processing infrastructure with membrane filtration expertise.
United Kingdom
Sports nutrition brands and functional food manufacturers source isolate and hydrolysate formats for leucine-optimized formulations. EFSA novel food approval frameworks and nutritional health claim substantiation requirements govern premium positioning. Greater London and the Midlands host ingredient distribution and formulation service clusters.
France
Medical nutrition and specialized clinical applications absorb immunoglobulin-rich micellar variants for immune-modulation protocols. ANSM pharmaceutical-grade manufacturing standards and EMA nutritional health claim pathways shape regulatory compliance. The Brittany dairy basin supplies raw material to Ingredia SA's native whey extraction operations.
Native Whey Protein Market Competitive Landscape
Scandinavian dairy cooperatives and Oceania grass-fed specialists split the market into supply-controlled and certification-differentiated segments. Three archetypes dominate: cooperative-integrated processors with captive milk supply, independent ingredient specialists with formulation expertise, and diversified nutrition conglomerates with sports nutrition channel control. Competitive moves concentrate on multi-year direct supply contracts with functional food manufacturers and membrane filtration technology licensing partnerships.
Among cooperative-integrated processors, Arla Foods and Fonterra Co-operative Group exemplify supply-side concentration through backward integration into raw milk control. Glanbia Nutritionals occupies a position within the formulation-specialist tier, anchoring sports nutrition ingredient system development. These three entities represent distinct strategic positions: Scandinavian cooperative structure, Oceania grass-fed traceability, and deep specialization in performance nutrition channels.
| Leading Market Players |
|---|
| Arla Foods |
| Lactalis Ingredients |
| Ingredia SA |
| MILEI GmbH |
| Fonterra Co-operative Group |
| Glanbia Nutritionals |
| DMK Deutsches Milchkontor |
| Carbery Group |
| Hilmar Cheese Company |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp dairy freight corridors transmit cold-chain cost volatility directly into native whey protein margin structures, amplifying pricing power for Scandinavian and Oceania cooperatives while forcing downstream tier separation between immunoglobulin-certified isolates and commodity concentrates.
Pricing Analysis
Ingredient formulation service contracts generate recurring revenue streams that exceed raw protein commodity margins by binding sports nutrition manufacturers to multi-year technical support agreements. Pricing stratifies across premium, standard, and economy tiers based on bioactive retention certificates and grass-fed verification status. Cost compression in functional food concentrates intensifies as pea protein isolates capture bakery and beverage fortification contracts. Nutritional clinics and elite athletes demonstrate lowest price sensitivity, prioritizing batch-level quaternary structure documentation over per-kilogram expenditure.
Supply Chain Analysis
Export-control restrictions on advanced membrane filtration equipment limit technology transfer to emerging production regions, concentrating native whey extraction expertise in Germany and New Zealand. Raw milk supply draws from Scandinavian cooperative structures and Oceania grass-fed dairy systems, with enzymatic hydrolysate processing inputs sourced from Bavarian specialty chemical producers. Single-source vulnerability permeates the micellar native whey tier, where intact casein micelle production remains captive to Arla Foods and Fonterra facilities. Distribution runs through direct long-term offtake agreements between functional food manufacturers and cooperative processors, bypassing traditional ingredient traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where regulatory entrenchment around EFSA health claim substantiation and FDA bioactivity labeling creates enduring barriers against commodity substitution.
For Market Incumbents: Insulate premium positioning by securing multi-year direct supply contracts with United States functional food manufacturers before membrane filtration technology licensing spreads. Accelerate proprietary peptide research investment to preempt EFSA clinical trial requirements for muscle protein synthesis claims. Plant protein substitution in bakery applications threatens concentrate-tier margins, demanding backward integration into grass-fed dairy sourcing to maintain traceability differentiation. For New Entrants and Emerging Players: Establish a beachhead in medical nutrition channels serving specialized nutrition clinics with immunoglobulin-rich micellar variants, where incumbent coverage remains sparse and USDA organic certification commands immediate price premiums. Target direct-to-consumer subscription platforms with verified pasture-based sourcing narratives, bypassing established sports nutrition distribution networks. Lead with batch-level bioactivity transparency as the primary go-to-market wedge against opaque commodity suppliers. For Investors and Strategic Acquirers: Formulation-specialist ingredient houses with captive sports nutrition channel relationships represent the highest-conviction acquisition archetype, offering immediate access to leucine-optimized product development expertise. Long-term viability hinges on clinical nutrition penetration rates and EFSA novel food approval velocity. Watch for membrane filtration equipment licensing deals into emerging production regions as the signal that supply-side concentration is eroding.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | German equipment manufacturers transfer cold microfiltration expertise to expand native protein yield rates in emerging dairy regions. |
| EFSA Health Claim Substantiation Investment | Isolate manufacturers fund clinical trials to secure novel food approvals for muscle protein synthesis positioning in European sports nutrition. |
| Direct-to-Consumer Subscription Launch | E-commerce platforms capture margin from traceability-conscious fitness enthusiasts through verified pasture-based sourcing claims. |
| Grass-Fed Certification Program Expansion | USDA organic pathway investment opens premium tier access for traceable native whey with documented pasture-based sourcing. |
| Medical Nutrition Channel Penetration | Specialized nutrition clinics absorb immunoglobulin-rich micellar variants for immune-modulation protocols beyond sports applications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA protein labeling guidance, EFSA novel food approval databases, and USDA organic certification records through structured interviews with membrane filtration equipment engineers, sports nutrition formulators, dairy cooperative procurement directors, and specialized nutrition clinic purchasing managers. Bottom-up volume estimates from cold microfiltration facility capacity data triangulate against top-down expenditure flows from functional food manufacturer ingredient procurement disclosures.
Forecast inputs span isolate versus concentrate versus hydrolysate product mix trajectories, grass-fed certification penetration rates across United States premium channels, and enzymatic hydrolysate adoption velocity in post-workout recovery applications. CAGRs derive from segment-level demand elasticity modeling against raw milk supply constraints and membrane filtration yield improvement curves. Cold-chain logistics cost indices and REACH compliance evolution timelines inform margin compression assumptions.
Sensitivities concentrate around EFSA health claim approval velocity, membrane filtration equipment technology transfer licensing decisions, and plant protein substitution rates in functional food fortification. Forecasts reflect documented assumptions regarding dairy cooperative supply concentration persistence and clean-label certification timeline stability. Material shifts in regulatory substantiation requirements or breakthroughs in alternative protein bioavailability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Prickly Pear Seed Oil Nutricosmetic Bases Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Fish Collagen Market
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
Middle East and Africa Feed Antioxidants Market
Nutritional Supplements
Australia Protein Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Vitamin D Supplements Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Global Beta Glucan Market