
 Brazil Corn Syrup Market | 2026-2036
Brazil Corn Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Corn Syrup Market Insights
Beverage producers is reorganizing procurement priorities toward high-fructose corn syrup for carbonated and juice applications. Cargill Agricola SA leverages its vertical integration from Brazilian corn origination to syrup refining, sustaining cost advantages across the value chain. Ingredion Incorporated specializes in modified starch and sweetener blends, competing on technical service for industrial bakery clients in Minas Gerais and Paraná.
Corn syrup comprises glucose polymers derived from corn starch hydrolysis, typically standardized by dextrose equivalent values ranging from 20 to 95 to control sweetness, viscosity, and browning behavior in food processing. Liquid corn syrup dominates volume flows into Brazilian confectionery operations, while high-fructose corn syrup captures expanding share in beverage applications where cost-efficient sweetness replacement drives formulation shifts. Corn sweeteners occupy a mature position in dairy applications, with margin pools concentrating in customized blends for food service channels.
ANVISA governs food additive safety and labeling requirements for corn-derived sweeteners sold in Brazil, while the Ministry of Agriculture enforces quality standards for domestic starch processing. FSSAI-equivalent alignment pressures are emerging as Brazilian exporters target Indian and Middle Eastern markets with certified syrup shipments. Stakeholders must monitor how ANVISA's pending purity rule revisions will reshape import access for non-integrated traders and redirect sourcing decisions toward domestic hydrolysis capacity.
Market Dynamics
ANVISA's pending purity rule revisions are compressing import access for non-integrated traders while redirecting sourcing decisions toward domestic hydrolysis capacity across Brazil's Southeast industrial corridor.
Growth Catalysts
- High-Fructose Corn Syrup Adoption:Beverage producers in São Paulo state are reorganizing procurement priorities toward HFCS for carbonated and juice applications, displacing cane sugar in cost-sensitive formulations.
- ANVISA Regulatory Alignment:Updated food additive regulations are tightening purity standards for sweetener imports, creating competitive advantage for domestic processors with certified hydrolysis operations.
- Confectionery Cluster Expansion:Liquid corn syrup volume flows concentrate in Minas Gerais and Paraná bakery clusters, where technical service requirements anchor regional consumption growth.
Market Restraints
- Feedstock Price Volatility:Brazilian corn origination costs fluctuate with seasonal harvest cycles and export parity pricing, compressing margin pools for non-integrated refiners.
- Import Dependency Concentration:Non-integrated traders face structural barriers as ANVISA certification timelines extend, limiting access to certified syrup shipments for small-scale distributors.
- Cane Sugar Substitution Threat:Brazil's sugarcane ethanol complex maintains residual sweetness capacity that competes with corn sweeteners in price-sensitive dairy and food service channels.
Strategic Opportunities
- Northeast Industrial Penetration:Bahia and Pernambuco confectionery operations remain underpenetrated by modified starch and sweetener blend technical service providers.
- Export Certification Pathways:FSSAI-equivalent alignment pressures are emerging as Brazilian exporters target Indian and Middle Eastern markets with certified syrup shipments.
- Food Service Channel Innovation:Customized blend development for institutional bakery clients creates white space beyond standardized dextrose equivalent commodity tiers.
Industry Challenges
- Hydrolysis Technical Talent Scarcity:Enzyme process engineering expertise concentrates at established processors, constraining capacity expansion timelines for new entrants.
- Legacy Equipment Integration:Retrofitting existing starch processing infrastructure for ANVISA-compliant purity standards demands capital-intensive filtration and monitoring system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Corn Syrup Market |
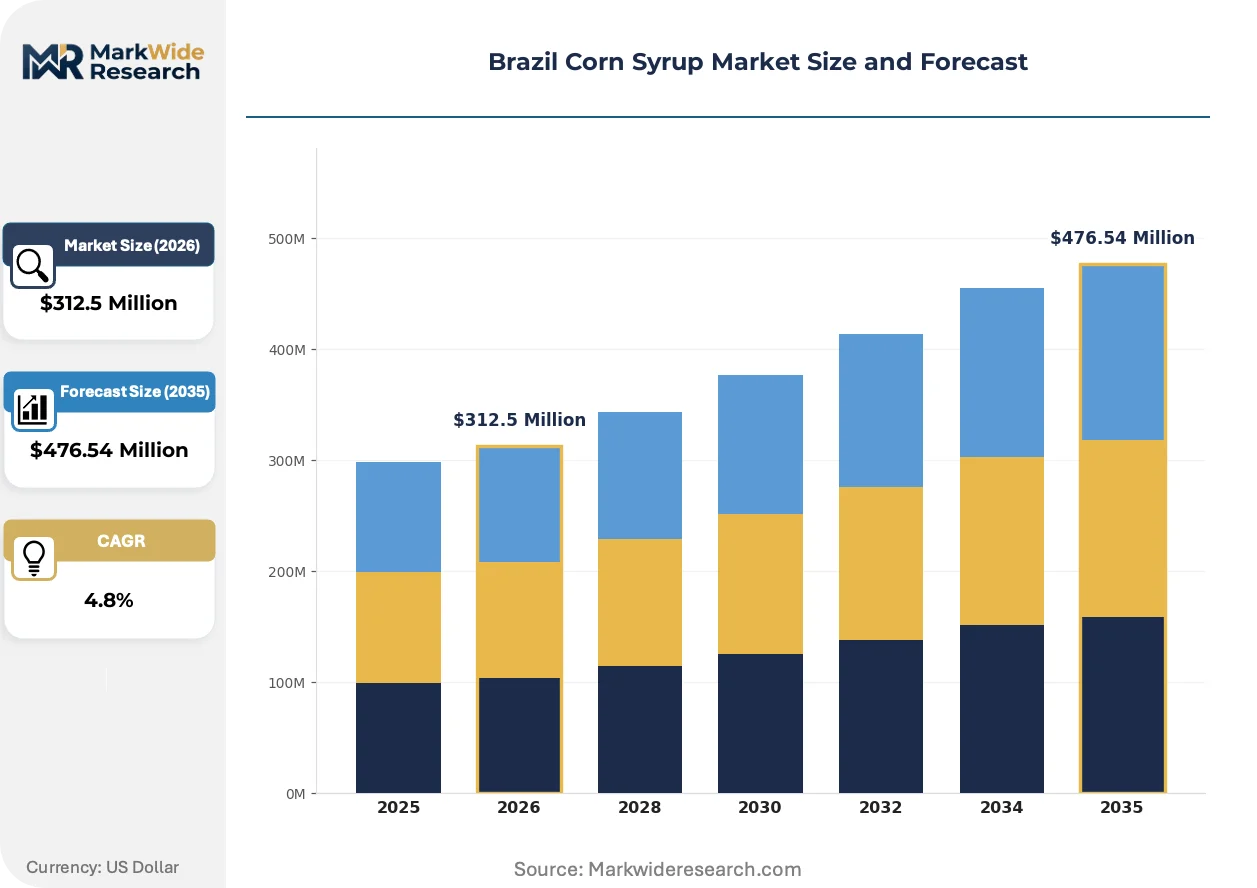
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Corn Syrup, High-Fructose Corn Syrup, Corn Sweeteners, Corn Starch Application: Beverages, Confectionery, Bakery, Dairy Products End User: Food Manufacturers, Beverage Producers, Retailers, Food Service Providers Distribution Channel: Direct Sales, Online Sales, Wholesalers, Supermarkets |
| Companies Covered | Tate & Lyle PLC, Cargill Agricola Sa, Tereos S.A., COFCO Rongshi Bio-technology Co., Ltd., Grain Processing Corporation, Cargill, Incorporated, Archer Daniels Midland Co., Global Sweeteners Holdings Limited, Ingredion Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Corn Syrup Market Trends and Innovations
Enzymatic hydrolysis process control and dextrose equivalent customization are actively reshaping competitive differentiation among Brazilian corn syrup processors serving industrial food manufacturers.
Continuous enzyme immobilization systems are bifurcating production economics between large-scale integrated processors and batch-dependent smaller refiners. Cargill Agricola SA and established domestic operators are deploying these systems to tighten dextrose equivalent variability below 0.5 points. The technology is compressing margin capture for non-integrated traders unable to justify capital deployment.
ANVISA's updated food additive regulations are mandating enhanced purity documentation for imported corn-derived sweeteners. Industrial buyers now require certificate-of-analysis packages exceeding prior disclosure thresholds. Beverage and confectionery segments in São Paulo state are responding by consolidating supplier panels toward domestic hydrolysis capacity with established regulatory relationships.
Technical service bundling is displacing commodity-only procurement relationships among Minas Gerais and Paraná bakery clusters. Industrial clients now expect formulation support alongside dextrose equivalent standardization. This behavioral shift concentrates purchasing authority at processors employing application-specific food scientists, compressing spot-market volumes for generic syrup grades.
Brazil Corn Syrup Market Segmentation
Segmentation in the Brazil corn syrup market reflects how ANVISA regulatory tiers, hydrolysis technology boundaries, and regional industrial clustering reshape procurement patterns. Buyers now sort suppliers by certification depth rather than commodity pricing alone.
Product Type:
ANVISA's pending purity revisions are bifurcating the product landscape between certified domestic hydrolysis output and import-restricted alternatives.
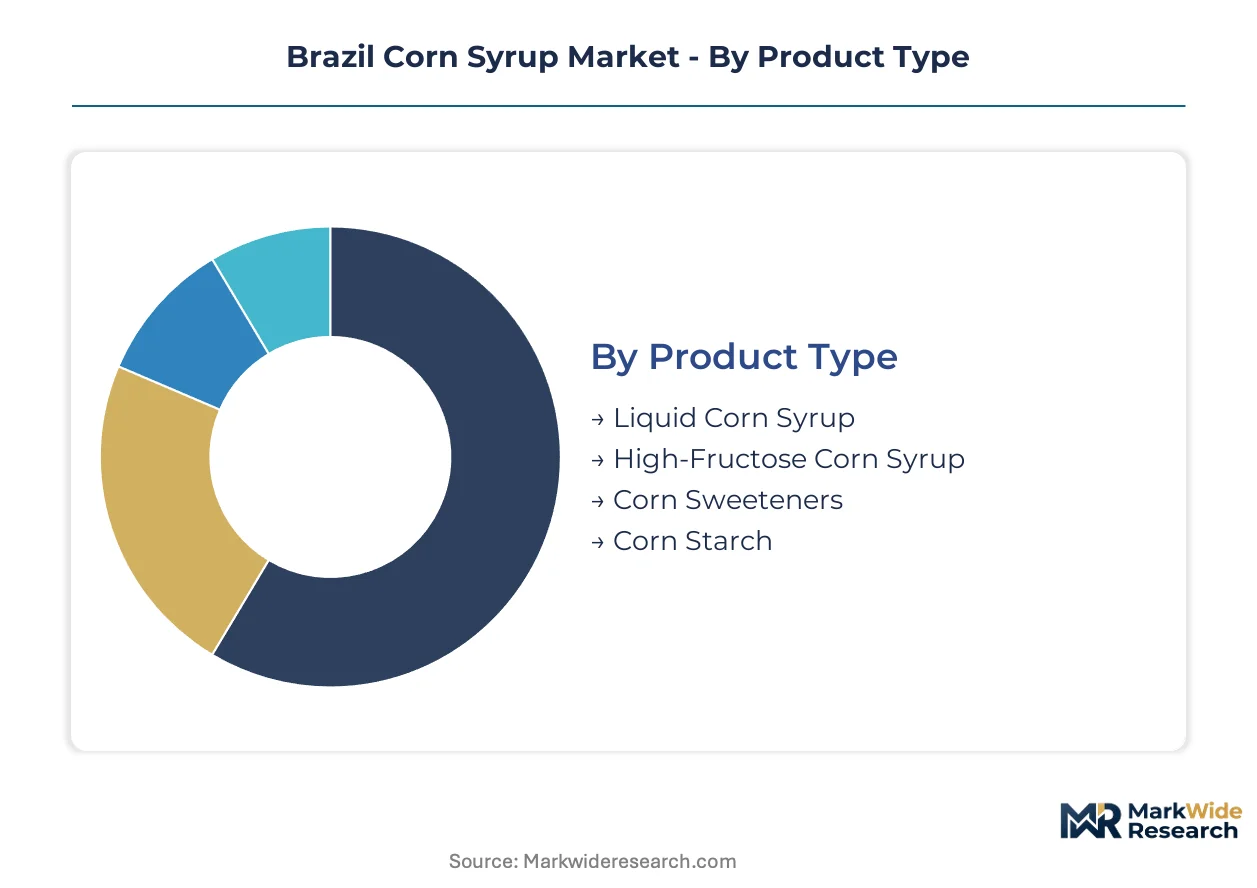
- Liquid Corn Syrup:Glucose polymer solutions standardized by dextrose equivalent values between 20 and 95, controlling viscosity and browning in thermal processing. São Paulo confectionery operations anchor volume demand as technical service requirements tighten supplier consolidation.
- High-Fructose Corn Syrup:Enzymatically isomerized syrup with elevated fructose content enabling cost-efficient sweetness replacement in beverage formulations. Carbonated and juice producers across the Southeast industrial corridor are reorganizing procurement priorities toward this grade.
- Corn Sweeteners:Dry and liquid glucose-fructose blends occupying mature positions in dairy applications.
- Corn Starch:Native and modified starches serving as hydrolysis feedstock and direct food ingredient.
Liquid corn syrup handles the majority of throughput; high-fructose corn syrup is gaining share fastest among reformulating beverage producers.
Application:
Cost tier differentiation separates commodity-grade syrup flows from customized technical service bundles.
- Beverages:Carbonated soft drinks and juice manufacturers in São Paulo state are displacing cane sugar with HFCS in cost-sensitive formulations. ANVISA-compliant certificate-of-analysis packages now dominate procurement specifications.
- Confectionery:Hard candies and chocolate coatings demand precise dextrose equivalent control for texture and shelf stability. Minas Gerais and Paraná clusters concentrate volume as bakery technical service requirements intensify.
- Bakery:Industrial bread and pastry operations utilizing liquid syrup for moisture retention and Maillard browning.
- Dairy Products:Ice cream and flavored milk applications where corn sweeteners compete with residual cane sugar capacity from Brazil's ethanol complex.
Beverages command the steepest expansion trajectory; confectionery retains the deepest volume base.
End User:
Customer type determines whether procurement flows through technical service relationships or spot-market transactions.
- Food Manufacturers:Integrated confectionery and bakery operations requiring formulation support alongside dextrose equivalent standardization. These clients are consolidating supplier panels toward domestic processors with established ANVISA relationships.
- Beverage Producers:Carbonated and juice bottlers reorganizing priorities toward HFCS with documented purity credentials.
- Retailers:Private-label and branded food product channels with indirect sweetener exposure through contract manufacturers.
- Food Service Providers:Institutional bakery and dairy clients creating white space for customized blend development.
Food manufacturers absorb the dominant procurement volume; beverage producers are shifting specifications most aggressively.
Distribution Channel:
Supply concentration in the Southeast corridor shapes how channels capture margin across integrated versus non-integrated value chains.
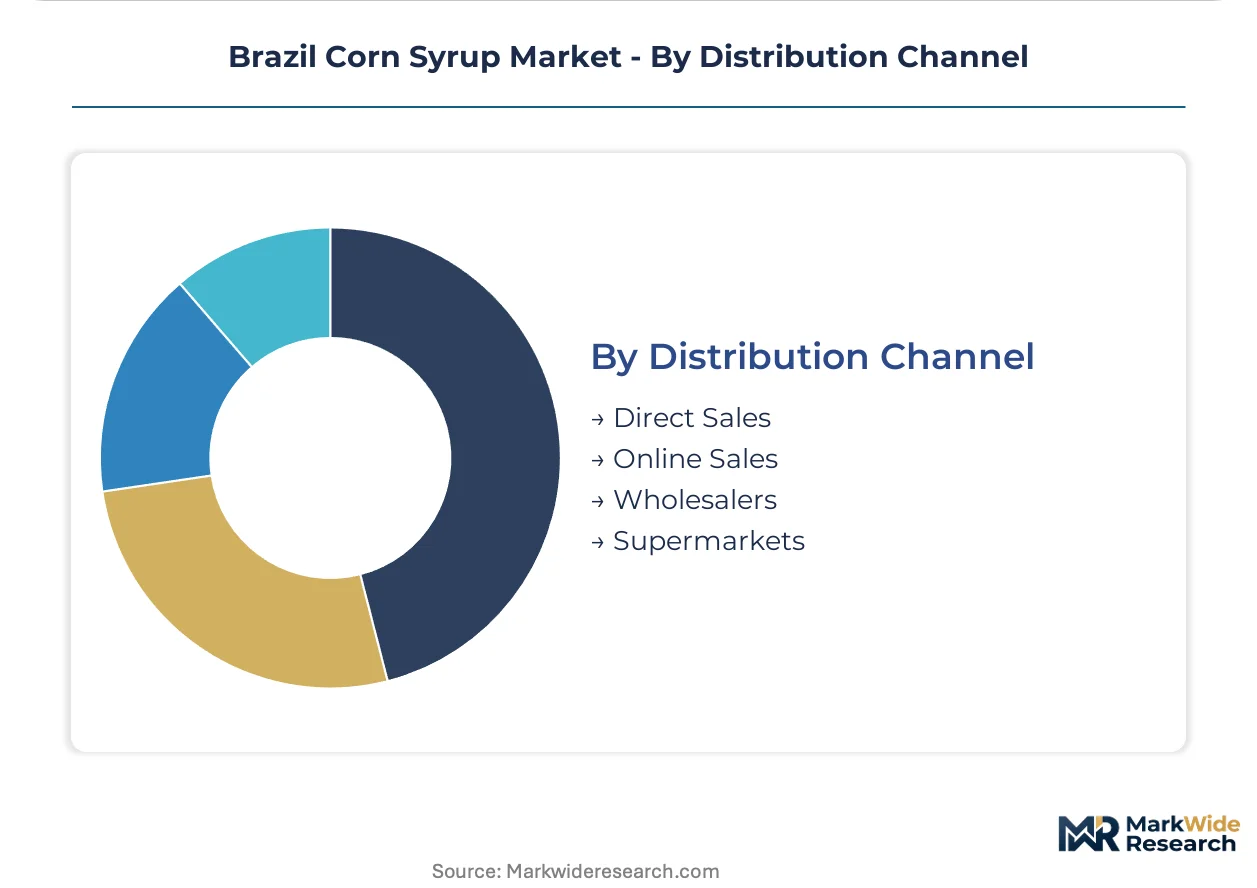
- Direct Sales:Processor-to-manufacturer relationships dominating large-volume beverage and confectionery accounts. Cargill Agricola SA leverages captive origination-to-refining infrastructure to sustain cost advantages in these channels.
- Wholesalers:Regional distributors serving Minas Gerais and Paraná bakery clusters with technical service bundling.
- Online Sales:Emerging procurement pathway for smaller food service accounts seeking certificate-of-analysis transparency.
- Supermarkets:Limited retail syrup presence concentrated in consumer-packaged corn sweetener formats.
Direct sales capture the bulk of industrial volume; online sales are climbing the fastest as smaller buyers seek regulatory documentation access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage and confectionery manufacturers cluster procurement authority in Brazil's Southeast industrial corridor, with São Paulo state anchoring the dominant buyer archetype for liquid corn syrup and high-fructose variants.
São Paulo
Carbonated soft drink and juice bottlers in São Paulo state are reorganizing formulation priorities toward high-fructose corn syrup, displacing cane sugar in cost-sensitive applications. ANVISA's updated food additive regulations are tightening purity documentation requirements for imported sweeteners. The state's industrial belt concentrates the nation's largest beverage production capacity, with procurement panels consolidating toward domestic hydrolysis operations holding established regulatory relationships.
Minas Gerais
Hard candy and chocolate coating manufacturers in Minas Gerais demand precise dextrose equivalent control for texture and shelf stability specifications. ANVISA certification timelines are extending for non-integrated traders, creating structural barriers to import access. The state's confectionery cluster anchors regional liquid corn syrup consumption, with technical service requirements intensifying supplier consolidation toward processors employing application-specific food scientists.
Paraná
Industrial bread and pastry operations in Paraná utilize liquid syrup for moisture retention and Maillard browning in thermal processing. The Ministry of Agriculture enforces quality standards for domestic starch processing that shape local sourcing decisions. Curitiba and surrounding industrial zones concentrate bakery technical service demand, with procurement patterns shifting from spot-market transactions toward bundled formulation support relationships.
Bahia
Confectionery operations in Bahia remain underpenetrated by modified starch and sweetener blend technical service providers, creating whitespace for domestic processor expansion. ANVISA's pending purity rule revisions are redirecting sourcing decisions toward certified domestic hydrolysis capacity. Salvador's industrial corridor shows emerging demand for customized syrup grades as regional food manufacturers seek alternatives to import-dependent supply chains.
Rio Grande do Sul
Dairy applications in Rio Grande do Sul present competitive tension between corn sweeteners and residual cane sugar capacity from Brazil's ethanol complex. State-level agricultural policy supports corn origination infrastructure that feeds regional starch processing. Porto Alegre's food manufacturing base sustains steady demand for standardized dextrose equivalent grades, though margin pools concentrate in customized blends for institutional food service channels.
Brazil Corn Syrup Market Competitive Landscape
Player mix skews toward integrated agribusiness conglomerates with captive corn origination and hydrolysis operations, compressing margin capture for non-integrated traders and spot-market participants. Structural concentration favors processors with backward integration into Brazilian corn supply chains and established ANVISA regulatory relationships. Three archetypes dominate: vertically integrated agribusiness operators, specialized starch and sweetener blend technologists, and regional distributors with technical service bundling capabilities. Competitive moves center on capacity expansion in the Southeast industrial corridor and strategic partnerships for enzyme process engineering expertise.
Among the integrated agribusiness tier, Cargill Agricola SA exemplifies the archetype of captive origination-to-refining infrastructure, sustaining cost advantages across procurement and hydrolysis stages. Ingredion Incorporated occupies a position representing specialized modified starch and sweetener blend capabilities, competing on technical service depth for industrial bakery clients. Archer Daniels Midland Co. sits within the scale-driven processor segment, leveraging established regulatory relationships and domestic hydrolysis capacity to capture volume flows from consolidating procurement panels.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Cargill Agricola Sa |
| Tereos S.A. |
| COFCO Rongshi Bio-technology Co., Ltd. |
| Grain Processing Corporation |
| Cargill, Incorporated |
| Archer Daniels Midland Co. |
| Global Sweeteners Holdings Limited |
| Ingredion Incorporated |
| Others |
Pricing and Supply Chain Analysis
ANVISA's pending purity rule revisions gate both supply qualification and price differentiation simultaneously, compressing import access for non-integrated traders while rewarding domestic hydrolysis operators with certified refining capacity. Beverage manufacturers in São Paulo state now require certificate-of-analysis packages that bifurcate procurement panels between premium-priced certified supply and restricted import alternatives.
Pricing Analysis
Continuous enzyme immobilization systems widen the pricing gap between current-generation integrated processors and prior-generation batch-dependent refiners. Three-tier pricing structure across premium, standard, and economy levels reflects dextrose equivalent precision, ANVISA certification depth, and technical service bundling intensity. Pricing pressure stems from feedstock origination cost volatility at Brazilian corn harvest cycles. Small-scale distributors exhibit highest price sensitivity; large beverage producers prioritize purity documentation over unit cost.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates inbound logistics costs for imported enzyme shipments and filtration equipment serving domestic hydrolysis expansion. Supply concentrates in Brazil's Southeast industrial corridor, with secondary nodes emerging in Rio Grande do Sul corn origination zones. Raw material dependencies center on Brazilian corn harvests, specialized enzyme formulations, and membrane filtration systems. Single-source vulnerability concentrates in enzyme process engineering expertise. Distribution runs through direct processor-to-manufacturer relationships for large accounts, with regional wholesalers serving Minas Gerais and Paraná bakery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service bundling expands faster than commodity syrup sales, as food manufacturers demand formulation support alongside dextrose equivalent standardization. This service-attach layer creates recurring revenue streams beyond transactional syrup procurement.
For Market Incumbents: Fortify ANVISA regulatory relationships and captive corn origination infrastructure against margin compression from enzyme process engineering talent scarcity. Expand hydrolysis capacity in São Paulo state's industrial belt to capture consolidating beverage procurement panels. Prioritize continuous enzyme immobilization deployment to tighten dextrose equivalent variability below competitor thresholds. For New Entrants and Emerging Players: Differentiate on application-specific food science capabilities for underpenetrated Northeast confectionery operations in Bahia and Pernambuco. Target white space in customized blend development for institutional food service channels. Pursue technical service partnerships with established enzyme suppliers to bypass hydrolysis engineering bottlenecks. For Investors and Strategic Acquirers: ANVISA's pending purity rule revisions reshape the acquisition landscape toward domestic hydrolysis capacity with established regulatory relationships. Long-term viability favors processors with backward integration into Brazilian corn supply chains. Monitor certificate-of-analysis disclosure thresholds as the inflection signal for import-dependent trader distress.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | São Paulo hydrolysis additions capture consolidating beverage procurement authority from cane sugar displacement. |
| Backward Integration | Corn origination control insulates margin pools from export parity pricing volatility at Brazilian harvest cycles. |
| Certification Investment | ANVISA-compliant purity documentation creates competitive moats against import-restricted non-integrated traders. |
| Technical Service Development | Application-specific food scientists anchor bundled relationships with Minas Gerais and Paraná bakery clusters. |
| Geographic Expansion | Northeast penetration into Bahia and Pernambuco captures underpenetrated confectionery technical service demand. |
Research Methodology
A spread of perspectives from starch processing plant managers, beverage procurement leads, confectionery technical directors, and ANVISA regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews across these stakeholder roles with secondary validation from ANVISA regulatory filings, Ministry of Agriculture quality standards, customs trade data on sweetener imports, and SEC disclosures from listed agribusiness operators. Bottom-up volume triangulation across hydrolysis capacity installations and top-down demand aggregation from end-use consumption patterns were reconciled to establish baseline estimates.
Segmentation dimensions modeled include product type tier, application category, end-user procurement archetype, and distribution channel structure across the analysis window. CAGRs were derived from regression analysis of historical consumption patterns projected against regulatory implementation timelines and industrial capacity expansion schedules. Forecast inputs incorporated enzyme process technology adoption curves and dextrose equivalent customization intensity by buyer segment.
Material uncertainties — ANVISA rule revision timing, Brazilian corn harvest yield variability, and enzyme supplier concentration risk — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance cost pass-through and industrial buyer consolidation behavior. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Konjac Root Fiber Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Potato Fiber Market
Ingredients
Black Seed Oil Market
Ingredients
Carob Protein Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Rose Extract Market
Ingredients
Lentils Flour Market
Ingredients
United States Corn Glucose Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Durian Powder Market
Ingredients
Lime Seed Oils Market