
 Global Waste to Fuel Technology Market | 2026-2036
Global Waste to Fuel Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waste to Fuel Technology Market Outlook
Modular plant design is expanding as the dominant configuration pattern for waste to fuel projects, allowing developers to scale capacity in increments matched to local feedstock availability. Veolia leverages its integrated waste collection infrastructure across France and Belgium to secure feedstock supply chains. Enerkem anchors North American project development with proprietary thermochemical ethanol production technology. Fulcrum BioEnergy differentiates through Fischer-Tropsch synthesis pathways targeting aviation fuel offtake agreements.
Waste to Fuel Technology encompasses thermochemical and biochemical processes that convert non-recyclable waste streams into liquid fuels, biogas, or hydrogen through controlled reaction systems operating at temperatures ranging from anaerobic mesophilic conditions to gasification above 700°C. Thermal conversion platforms dominate current installed capacity due to mature engineering and predictable output yields, while biological anaerobic digestion occupies mature margin pools in agricultural residue processing. Chemical gasification routes represent the fastest-growing technology segment as project developers target synthetic fuels and hydrogen for hard-to-abate transport applications.
The EU Green Deal and REACH frameworks mandate progressively stricter landfill diversion targets that directly expand addressable feedstock volumes for conversion facilities. EPA renewable fuel standards in the United States and Japan's METI hydrogen roadmap create parallel compliance-driven demand channels across three continents. Stakeholders must monitor feedstock certification schemes and carbon intensity scoring methodologies that will determine project economics and offtake pricing structures.
Market Dynamics
Modular thermochemical conversion units are fragmenting project development economics, allowing developers to match capacity increments precisely to municipal solid waste availability rather than committing to centralized mega-facilities with stranded feedstock risk.
Growth Catalysts
- EU Green Deal landfill diversion mandates:Binding renewable fuel targets for aviation and maritime transport expand addressable feedstock volumes across Germany, France, and the Netherlands.
- Synthetic aviation fuel specifications:Airlines under CORSIA carbon offset requirements are signing long-term offtake agreements for Fischer-Tropsch output from municipal solid waste gasification.
- Japan METI hydrogen roadmap:Government procurement guarantees for green hydrogen derived from waste streams accelerate commercial deployment of plasma gasification systems.
Market Restraints
- Feedstock heterogeneity:Inconsistent moisture content and contaminant loads in municipal solid waste increase preprocessing capital intensity by 15-25% versus design assumptions.
- Synthetic fuel certification lag:ASTM D7566 approval pathways for alcohol-to-jet and Fischer-Tropsch synthetic paraffinic kerosene extend project financing timelines by 18-24 months.
- Natural gas price volatility:Competing hydrogen production via steam methane reforming compresses green hydrogen margins when Henry Hub futures trade below $3.50/MMBtu.
Strategic Opportunities
- India waste-to-energy deficit:Only 4% of 62 million annual tonnes of urban municipal solid waste currently undergoes energy recovery, leaving substantial untapped feedstock for plasma gasification developers.
- Carbon intensity scoring methodologies:California LCFS and EU RED III certification premiums for negative-carbon fuels create pricing arbitrage for projects achieving sub-20 gCO2e/MJ lifecycle emissions.
- Biological-thermochemical hybrid systems:Integration of anaerobic digestion pre-processing with subsequent gasification of digestate residues improves carbon conversion efficiency and expands output slate to biogas, biochar, and hydrogen simultaneously.
Industry Challenges
- Process control engineering scarcity:Qualified operators capable of managing entrained-flow gasifier temperature profiles and syngas conditioning trains command 40% salary premiums over conventional refinery technicians.
- Front-end engineering design complexity:Each municipal solid waste stream requires customized feedstock handling, contaminant removal, and emissions control configurations that resist standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waste to Fuel Technology Market |
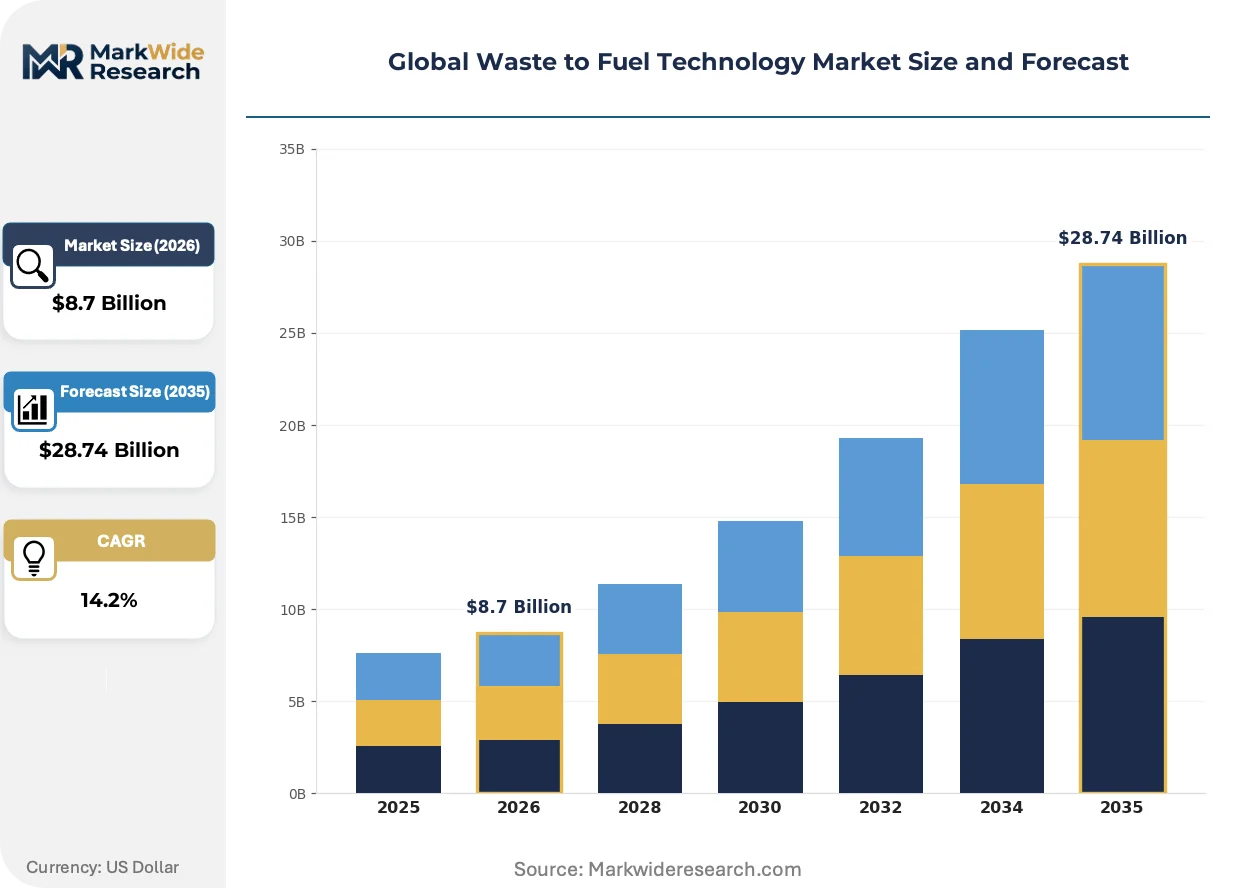
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thermal, Biological, Chemical, Gasification Feedstock Type: Municipal Solid Waste, Agricultural Residues, Industrial Waste, Forestry Biomass Application: Biofuels, Biogas, Synthetic Fuels, Hydrogen End User: Energy Utilities, Transport Sector, Industrial Clients, Government Entities |
| Companies Covered | China Everbright International Limited, Covanta Holding Corporation, Veolia, Suez, Waste Management, Inc., Abu Dhabi National Energy Company PJSC (Taqa), Enerkem, Fulcrum BioEnergy, Velocys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waste to Fuel Technology Market Strategic Shifts
Reaction engineering advances and digital twin deployment are compressing commissioning timelines while synthetic fuel certification pathways mature. Three developments are restructuring competitive positioning.
Containerized small-scale gasification units rated below 50 tonnes per day are decentralizing waste-to-fuel infrastructure deployment. Remote industrial facilities and island municipalities lacking landfill alternatives are adopting these systems to eliminate waste transport costs. Distributed generation architecture is compressing the addressable market for centralized mega-plants dependent on long-haul feedstock logistics.
REACH framework amendments tightening persistent organic pollutant thresholds in fuel products are forcing syngas cleanup technology upgrades. Project developers must install additional tar cracking and heavy metal removal stages to meet output specifications. Aviation fuel offtakers in Germany and the Netherlands are demanding third-party certification of contaminant levels prior to contract execution.
Airlines are consolidating procurement through direct equity participation in conversion facilities rather than arm's-length offtake agreements. Lufthansa, KLM, and British Airways parent IAG have established dedicated sustainable aviation fuel investment vehicles. This capital injection model is most visible in the Netherlands and United Kingdom, where airport hub operators coordinate feedstock aggregation across multiple municipal waste authorities.
Global Waste to Fuel Technology Market Segmentation
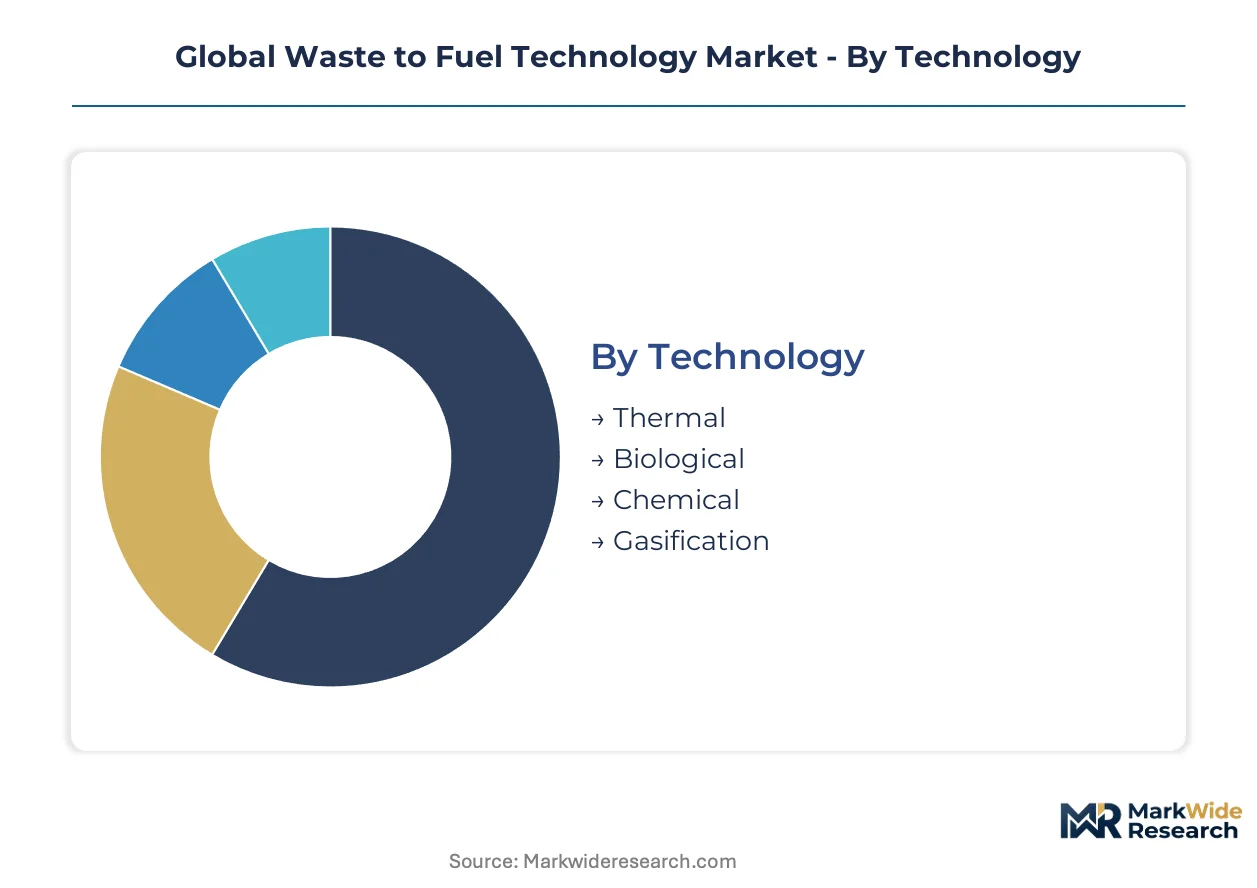
Waste to fuel technology segments around conversion chemistry, feedstock provenance, and output molecule. Each dimension carries distinct capital intensity profiles and offtake contract structures that determine project bankability.
Technology:
Supply concentration in thermal conversion platforms reflects decades of operational data and predictable syngas yields that de-risk project financing.
- Thermal:Combustion and pyrolysis systems operating above 400°C dominate installed capacity. Municipal waste incinerators in Germany and the Netherlands anchor demand for steam-cycle power generation from refuse-derived fuel.
- Biological:Anaerobic digestion of organic fractions produces biogas for grid injection or vehicle fuel. Agricultural residue processing in France and Belgium leverages existing farm infrastructure and established digestate markets.
- Chemical:Catalytic depolymerization and hydrothermal liquefaction convert wet organic streams without drying. Pilot deployments in Japan target food waste and sewage sludge for marine biofuel output.
- Gasification:Partial oxidation at 700-1000°C yields synthesis gas for Fischer-Tropsch fuel synthesis. Plasma gasification systems are gaining share fastest for hydrogen production under Japan METI procurement guarantees.
Today's leader: Thermal. Tomorrow's challenger: Gasification.
Feedstock Type:
Cost tiers stratify around collection infrastructure requirements and preprocessing complexity.
- Municipal Solid Waste:Heterogeneous streams with 40-60% moisture content require shredding, magnetic separation, and drying. Airlines in Germany and the Netherlands are locking long-term supply contracts for synthetic aviation fuel feedstock.
- Agricultural Residues:Seasonal availability and low bulk density challenge logistics. Straw and manure processing in France supplies biogas upgrading facilities with consistent organic loading rates.
- Industrial Waste:Manufacturing byproducts including spent solvents and plastic offcuts offer higher calorific value. Chemical sector clusters in Belgium provide concentrated feedstock flows with lower collection costs.
- Forestry Biomass:Wood chips and sawdust from sustainable harvesting carry certification premiums. Nordic combined heat and power plants integrate biomass gasification for district heating networks.
Lowest cost tier: Agricultural residues. Highest margin capture: Municipal solid waste.
Application:
End-use demand fragments across molecule types with divergent certification pathways and carbon intensity scoring methodologies.
- Biofuels:Ethanol and biodiesel for road transport blend mandates. Enerkem's thermochemical ethanol output serves California LCFS compliance markets with sub-30 gCO2e/MJ lifecycle emissions.
- Biogas:Methane-rich output from anaerobic digestion upgrades to pipeline-quality biomethane. Grid injection in France and Germany receives guaranteed feed-in tariffs under EU renewable gas targets.
- Synthetic Fuels:Fischer-Tropsch diesel and paraffinic kerosene for aviation and maritime. ASTM D7566 certification delays extend financing timelines for Fulcrum BioEnergy's municipal waste projects.
- Hydrogen:Syngas reforming and electrolysis integration targets industrial feedstock and fuel cell applications. Japan's METI hydrogen roadmap creates procurement guarantees for plasma gasification-derived output.
Mature volume pool: Biogas. Steepest expansion trajectory: Synthetic fuels.
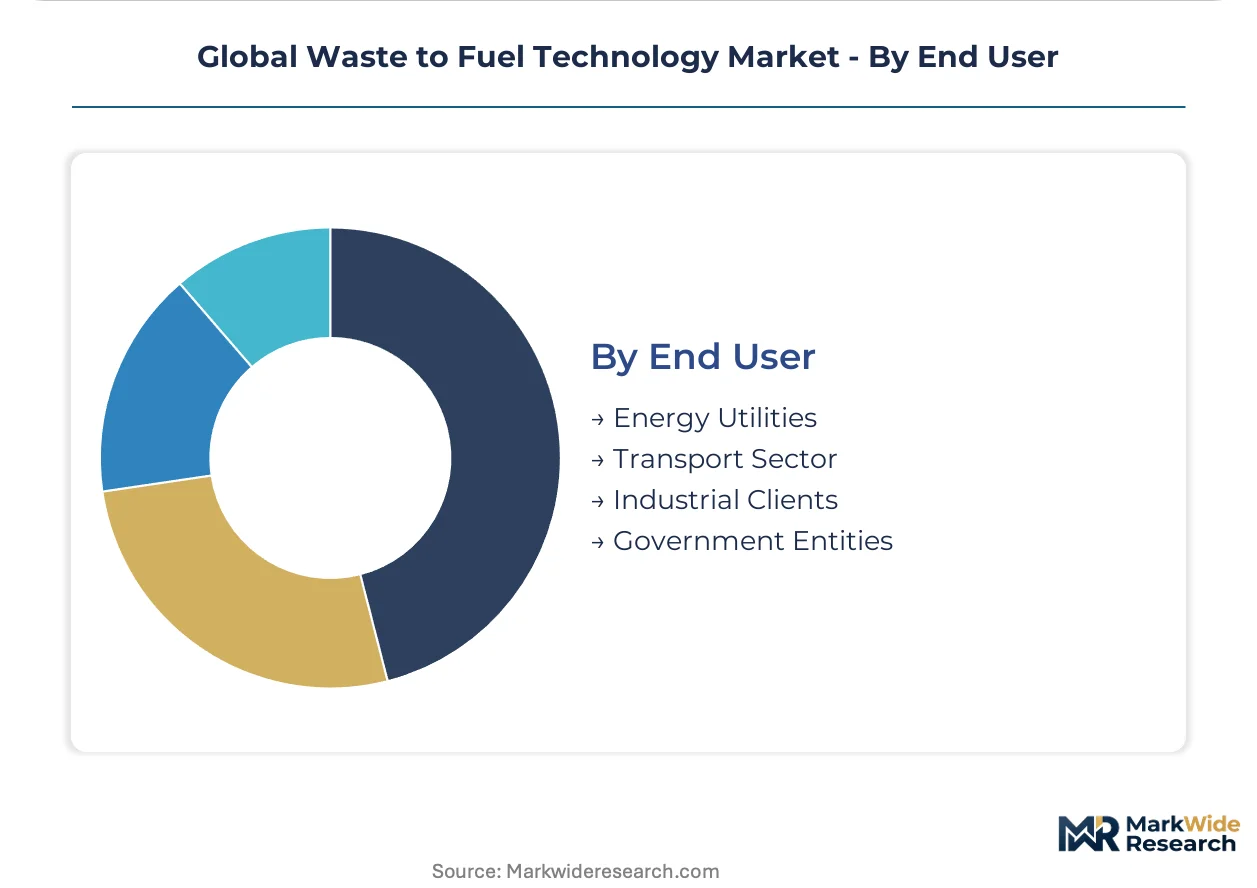
End User:
Customer type determines contract duration, price indexation, and technology performance guarantees.
- Energy Utilities:Baseload power purchase agreements and renewable gas offtake. French and Belgian utilities leverage Veolia's integrated waste collection for feedstock security.
- Transport Sector:Airlines under CORSIA carbon offset requirements and shipping operators facing IMO decarbonization targets. Direct equity participation is replacing arm's-length procurement.
- Industrial Clients:Chemical and steel producers seeking green hydrogen and syngas for process heat. German industrial clusters anchor demand for high-purity hydrogen from waste gasification.
- Government Entities:Municipal waste authorities procuring disposal capacity and central procurement agencies funding demonstration projects. EU Green Deal landfill diversion mandates expand addressable contract volumes.
Longest contract tenors: Energy utilities. Fastest procurement innovation: Transport sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial waste-to-fuel processing originated in Germany during the 1990s with integrated waste management districts combining incineration and district heating. The technology lineage spread through Northern Europe before reaching North American and Asian markets in the 2000s.
United States
Airlines under CORSIA carbon offset requirements are signing long-term offtake agreements for Fischer-Tropsch synthetic paraffinic kerosene derived from municipal solid waste. The EPA renewable fuel standard creates compliance-driven demand channels for thermochemical ethanol production. California's LCFS certification premiums attract project developers to the Central Valley and Los Angeles basin industrial corridors.
Germany
The EU Green Deal's binding renewable targets for aviation and maritime transport expand addressable feedstock volumes across municipal waste authorities. REACH framework amendments tightening persistent organic pollutant thresholds force syngas cleanup technology upgrades. The Rhine-Ruhr industrial cluster anchors commercial-scale thermochemical conversion facilities with integrated carbon capture.
Japan
Government procurement guarantees under the METI hydrogen roadmap accelerate commercial deployment of plasma gasification systems targeting industrial feedstock applications. Food waste and sewage sludge processing dominates pilot deployments for marine biofuel output. The Kanto region around Tokyo concentrates demonstration projects with direct utility offtake agreements.
India
Only 4% of 62 million annual tonnes of urban municipal solid waste currently undergoes energy recovery, leaving substantial untapped feedstock for plasma gasification developers. The country's national renewable energy mission provides capital subsidies for waste-to-energy projects above 5 MW capacity. Maharashtra and Gujarat state industrial zones attract foreign joint ventures targeting captive power generation.
Netherlands
Airport hub operators coordinate feedstock aggregation across multiple municipal waste authorities to secure synthetic aviation fuel supply chains. EU RED III certification premiums for negative-carbon fuels create pricing arbitrage for projects achieving sub-20 gCO2e/MJ lifecycle emissions. The Port of Rotterdam cluster integrates waste gasification with existing hydrogen infrastructure and chemical processing.
Global Waste to Fuel Technology Market Competitive Environment
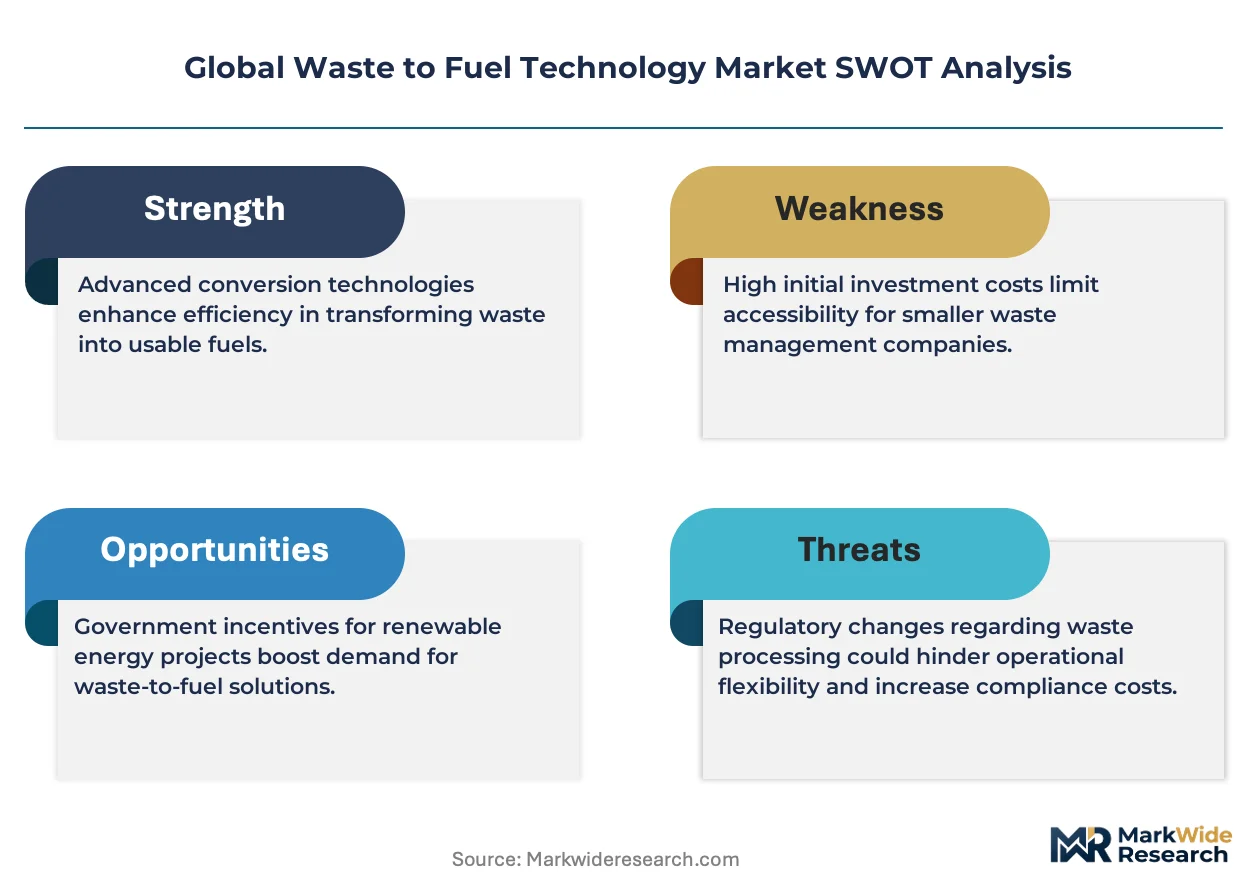
The competitive structure tilts toward integrated waste management conglomerates with captive feedstock infrastructure. Technology licensing specialists and pure-play conversion technology developers occupy secondary tiers with higher financing risk profiles. Two dominant competitive moves define current positioning: direct airline equity participation in conversion facilities replacing arm's-length procurement, and modular plant design standardization to reduce front-end engineering design complexity.
Among North American technology developers, Enerkem and Fulcrum BioEnergy exemplify the pure-play conversion archetype with proprietary thermochemical pathways. Veolia represents the integrated infrastructure model leveraging waste collection networks across France and Belgium to secure feedstock supply chains. These three companies occupy positions spanning technology licensing, project development, and vertical control over feedstock aggregation.
| Leading Market Players |
|---|
| China Everbright International Limited |
| Covanta Holding Corporation |
| Veolia |
| Suez |
| Waste Management, Inc. |
| Abu Dhabi National Energy Company PJSC (Taqa) |
| Enerkem |
| Fulcrum BioEnergy |
| Velocys |
| Others |
Value Chain & Pricing Dynamics
Airline procurement consolidation under CORSIA carbon offset requirements is forcing conversion technology suppliers toward standardized modular designs that compress engineering costs and stabilize long-term offtake pricing. This demand-side pressure cascades backward through equipment fabrication, tightening margins for non-specialized fabricators while rewarding process licensors with captive certification expertise.
Pricing Analysis
Long-term offtake contracting with price escalation clauses tied to carbon credit indexes dominates commercial arrangements. Price differentiation rests on ASTM D7566 certification status and feedstock guarantee security, with certified synthetic paraffinic kerosene commanding substantial premiums over unverified output. Pricing pressure stems from competing green hydrogen production via steam methane reforming when natural gas benchmarks soften. Municipal waste authorities exhibit highest price sensitivity due to constrained disposal budgets, while integrated airlines demonstrate lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Specialized welders and process control engineers capable of fabricating entrained-flow gasifier pressure vessels concentrate in Germany, Japan, and the United States. Equipment manufacturing draws from high-grade stainless steel alloys, ceramic refractory linings, and precision syngas analyzer instrumentation. Single-source vulnerability runs through plasma torch electrode suppliers concentrated in Japanese industrial clusters. Distribution runs through EPC contractors with established relationships to municipal waste authorities and airport hub operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as landfill diversion mandates across multiple jurisdictions guarantee feedstock availability for conversion facilities. Regulatory compliance requirements create durable demand floors that insulate project revenues from commodity volatility.
For Market Incumbents: Lock in feedstock supply exclusivity with municipal waste authorities in Germany and the Netherlands before competitor capacity enters operation. Prioritize backward integration into waste collection infrastructure to neutralize emerging pure-play technology developers lacking captive supply chains. Invest in ASTM D7566 certification acceleration to compress financing timelines and capture airline equity participation ahead of rival projects.
For New Entrants and Emerging Players: EU Green Deal landfill diversion mandates in France and Belgium open a window for modular gasification deployments serving district heating networks. Target agricultural residue processing in regions lacking incumbent anaerobic digestion capacity, where seasonal feedstock availability matches smaller-scale thermochemical units. Pursue joint development structures with industrial off-takers seeking captive hydrogen supply rather than competing head-to-head for airline offtake.
For Investors and Strategic Acquirers: Asymmetric upside sits with technology licensing specialists possessing proprietary thermochemical pathways but lacking project development balance sheets. The five-to-ten year viability window favors acquisition targets with demonstrated commercial operation at scale rather than pilot-stage platforms. Monitor ASTM D7566 certification timelines for Fulcrum BioEnergy and comparable developers as inflection indicators for bankable project finance availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Supply Exclusivity Agreements | Veolia's integrated waste collection in France and Belgium secures conversion facility input volumes. |
| ASTM D7566 Certification Acceleration | Fulcrum BioEnergy's synthetic paraffinic kerosene approval unlocks airline offtake contract execution. |
| Modular Plant Design Standardization | Enerkem's containerized units reduce front-end engineering complexity and match local municipal waste availability. |
| Direct Airline Equity Participation | Lufthansa and IAG investment vehicles replace arm's-length procurement with captive sustainable aviation fuel supply. |
| Plasma Gasification Scale-Up | Japan METI procurement guarantees accelerate commercial hydrogen production from food waste and sewage sludge. |
Study Parameters
Multiple input streams — executive interviews with gasification technology licensors, procurement discussions with airline sustainability officers, and regulatory filing analysis — were reconciled against secondary validation. Primary fieldwork engaged plant engineering directors at thermochemical conversion facilities, municipal waste authority contract managers, and EPC contractor project leads. Secondary sources included EPA renewable fuel standard compliance databases, EU ETS transaction registries, Japan METI hydrogen roadmap progress reports, and ASTM certification tracking systems. Bottom-up project pipeline aggregation and top-down addressable waste volume estimation were cross-referenced for triangulation.
Historical capacity deployment patterns were cross-referenced against expert panel assessments of feedstock availability and certification timeline probabilities. Segmentation modeling covered conversion chemistry, feedstock provenance, output molecule type, and end-user category across the projection horizon. CAGRs were derived from installed capacity growth trajectories weighted by regional policy enforcement likelihood. Industry-specific forecast inputs incorporated EU Green Deal landfill diversion target compliance schedules and CORSIA carbon offset phase-in requirements.
Revisions become necessary when synthetic fuel certification pathways extend beyond modeled timelines or natural gas price volatility compresses green hydrogen margins. Forecasts reflect assumptions regarding regulatory enforcement consistency and feedstock heterogeneity management capabilities. Material deviation in ASTM approval schedules or EU renewable target ambition levels warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Oil and Gas Waste Heat Recovery Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Energy Recovery Technologies Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
Drilling Waste Management Services Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market