
 Netherlands Waste to Energy Market | 2026-2036
Netherlands Waste to Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Waste to Energy Market Foresight
CE marking under the EU Waste Incineration Directive is redrawing competitive access for plant operators and technology suppliers. AEB Amsterdam leverages its vertically integrated Amsterdam operations to sustain high availability rates across multiple thermal lines. Attero BV anchors processing capacity in eastern Netherlands with dedicated feedstock contracts from German border regions. AVR competes aggressively on industrial steam supply contracts to Rotterdam's chemical cluster.
Netherlands waste to energy encompasses thermal and biological conversion systems that process municipal, industrial, and agricultural waste streams into electricity, heat, or synthetic fuels, typically operating at combustion temperatures between 850°C and 1,100°C with flue gas treatment trains to meet stringent emission limits. The primary purpose is simultaneous waste volume reduction and energy recovery for grid injection or industrial process heat. Incineration occupies the dominant share of installed capacity due to decades of operational track record and established residue handling infrastructure. Anaerobic digestion represents the fastest-expanding technology segment as organic waste separation mandates expand and biogas upgrading to biomethane improves project economics. Gasification retains niche positioning for specific industrial waste streams where syngas quality justifies higher capital intensity.
The Dutch Ministry of Infrastructure and Water Management enforces landfill diversion timelines through the National Waste Management Plan, while EU ETS carbon pricing and the CSRD sustainability disclosure rules reshape investment criteria for new capacity. The Netherlands' national emission authority coordinates with provincial environmental services to license stack emission limits that effectively mandate continuous emissions monitoring systems. Stakeholders must track how the EU Green Deal's revised waste hierarchy and emerging carbon capture integration mandates will reconfigure plant retrofit priorities and feedstock acceptance protocols.
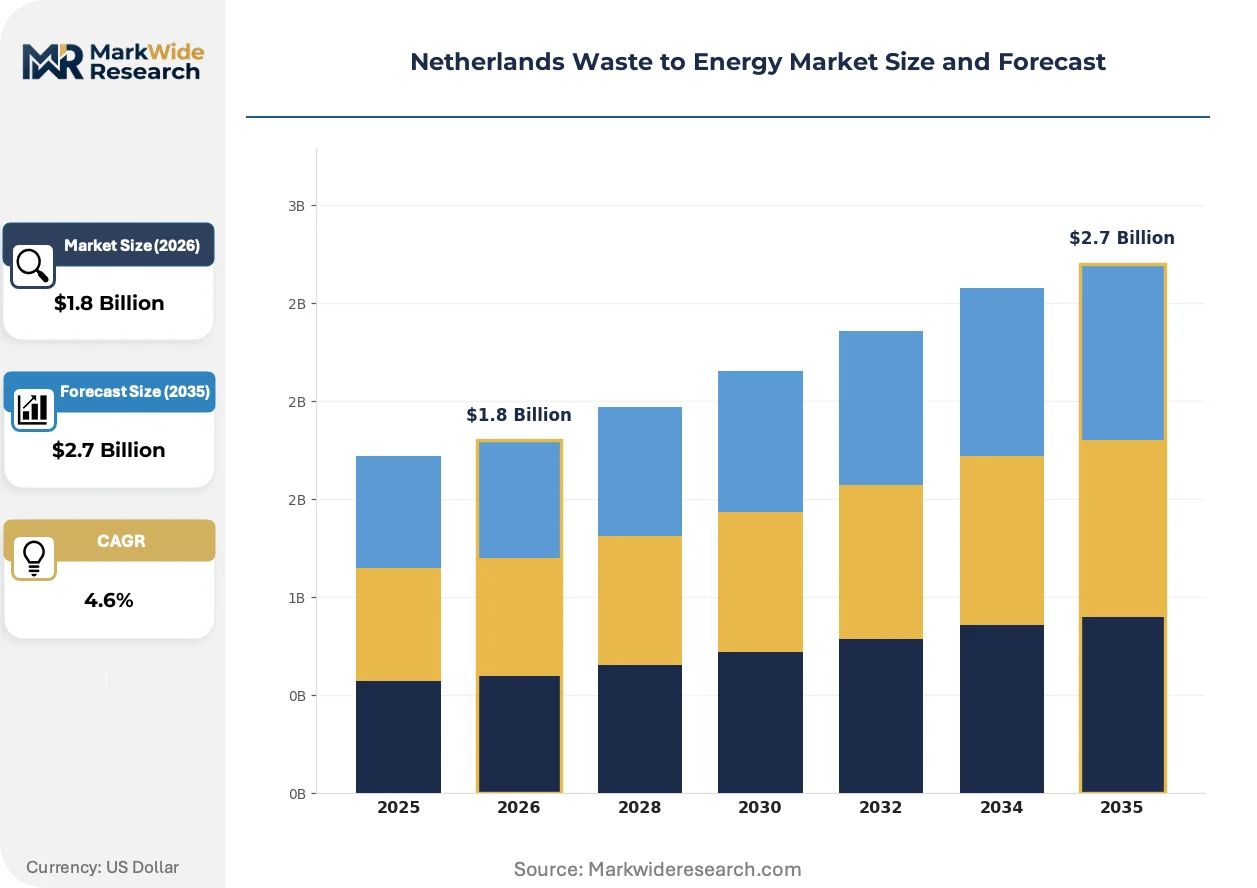
Market Dynamics
The Dutch waste-to-energy sector faces a structural squeeze between tightening landfill diversion mandates under the National Waste Management Plan and the rising cost of carbon compliance under EU ETS reforms. Plant operators must simultaneously upgrade emission control systems while securing long-term industrial heat offtake contracts to justify capital deployment.
Growth Catalysts
- EU ETS carbon pricing reforms:Rising carbon costs improve the relative economics of waste-derived energy versus fossil alternatives, accelerating technology upgrades across Randstad provinces.
- Industrial heat offtake agreements:Rotterdam's chemical cluster and Amsterdam port zones are contracting dedicated steam supply, creating revenue visibility for new capacity investments.
- Anaerobic digestion expansion:Organic waste separation mandates in North and South Holland are driving biogas upgrading infrastructure, with biomethane injection into the national grid improving project returns.
Market Restraints
- Residual ash disposal constraints:Limited domestic landfill capacity for bottom ash and fly ash treatment forces reliance on German and Belgian disposal facilities, raising logistics costs.
- Feedstock competition:Mechanical-biological treatment plants and recycling facilities compete for the same municipal waste streams, compressing gate fee margins in densely populated provinces.
- CE marking compliance costs:The EU Waste Incineration Directive's revised emission limits require continuous monitoring system upgrades, extending payback periods for smaller operators.
Strategic Opportunities
- Carbon capture integration:The EU Green Deal's emerging mandates for post-combustion CO2 capture at energy-from-waste plants position Dutch operators to supply negative-emission credits to industrial buyers.
- Eastern Netherlands feedstock access:Attero BV's processing corridors demonstrate the viability of cross-border waste contracts from German border regions, expanding addressable volume.
- Syngas-to-methanol pathways:Gasification technology convergence with electrolytic hydrogen production enables synthetic fuel output for maritime bunkering at Rotterdam terminals.
Industry Challenges
- Flue gas treatment specialist shortage:The Netherlands lacks sufficient certified technicians for continuous emissions monitoring system maintenance, constraining plant availability rates.
- Legacy grate combustion retrofit complexity:Integrating carbon capture readiness into existing thermal lines requires extended outage windows, disrupting steam supply contracts to industrial offtakers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Waste to Energy Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Incineration, Anaerobic Digestion, Gasification, Pyrolysis End User: Municipalities, Industrial Facilities, Power Plants, Waste Management Companies Feedstock Type: MSW, Industrial Waste, Agricultural Residues, Construction Waste Application: Energy Generation, Heat Recovery, Fuel Production, Carbon Capture |
| Companies Covered | AEB Bio-energiecentrale B.V., Attero BV, Indaver BV, Dutch Incinerators B.V., Axpo Holdings AG, Ingenia Consultants & Engineers BV, AEB Amsterdam, AVR, Mitsubishi Heavy Industries Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Waste to Energy Market Shifts & Advancements
Technology trajectories in Dutch waste-to-energy are diverging sharply between incumbent thermal upgrading and biological conversion scale-up. The sector's innovation frontier now centers on emission reduction integration and feedstock flexibility rather than pure energy yield optimization.
Advanced combustion control systems using artificial intelligence are fragmenting the traditional operations and maintenance vendor landscape. Rotterdam-based chemical cluster operators are piloting these platforms to optimize steam output consistency. The technology is compressing margins for conventional engineering service contracts by enabling predictive maintenance in-house.
CSRD sustainability disclosure rules are mandating granular Scope 3 emission reporting across EU waste value chains. Dutch provincial environmental services now require documented feedstock provenance for licensing renewals. North Holland municipalities are responding by contracting only processors with certified mass-balance tracking systems.
Long-term heat purchase agreements are displacing merchant power sales as the dominant revenue model. Amsterdam's district heating network operators are signing 15-year contracts with waste-to-energy plants, locking in baseload thermal supply. This shift is most visible in Randstad urban cores where building decarbonization targets outpace renewable heat alternatives.
Netherlands Waste to Energy Market Segmentation
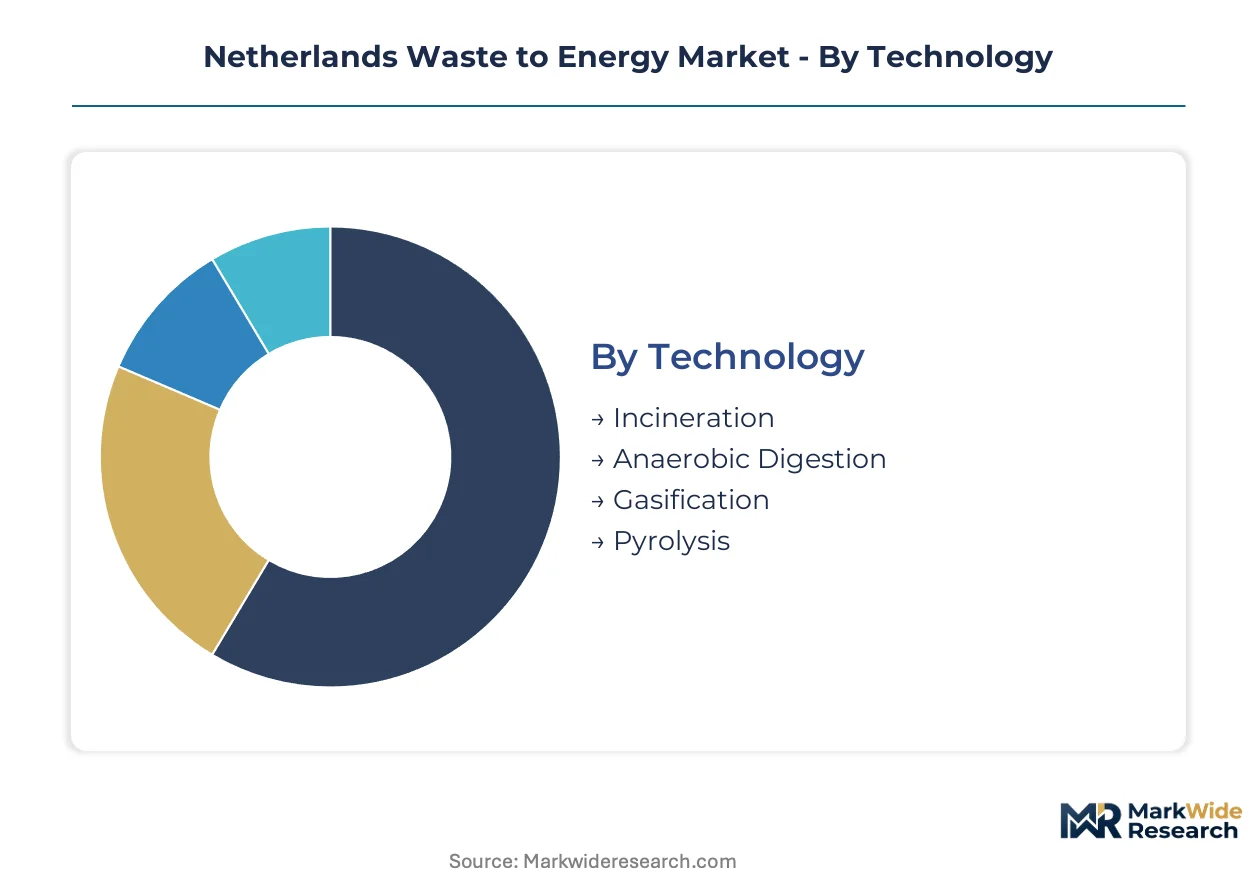
Segmentation in the Dutch waste-to-energy sector reveals how technology choices, feedstock access, and offtake contracting interlock to determine project viability. Each dimension carries distinct regulatory and commercial implications for operators navigating Randstad province licensing requirements.
Technology:
Technology selection channels capital deployment toward either proven thermal infrastructure or emerging biological conversion platforms, with financing terms and emission compliance trajectories diverging sharply between paths.
- Incineration:Grate combustion systems process mixed municipal and industrial waste streams at temperatures between 850°C and 1,100°C, with integrated flue gas treatment trains meeting EU Waste Incineration Directive limits. North Holland and South Holland municipalities contract these plants for baseload district heating supply to Amsterdam and Rotterdam urban cores, where long-term heat purchase agreements provide revenue certainty.
- Anaerobic Digestion:Wet fermentation systems break down source-separated organic waste to produce biogas for grid injection or vehicle fuel, operating at mesophilic or thermophilic temperature ranges. Organic waste separation mandates in Randstad provinces are accelerating biogas upgrading infrastructure, with biomethane certificates improving project economics for agricultural residue processors.
- Gasification:Partial oxidation at controlled oxygen levels yields syngas for methanol or hydrogen production, suited to specific industrial waste streams with consistent calorific value. Rotterdam port zone chemical clusters pilot these systems for maritime fuel synthesis.
- Pyrolysis:Thermal decomposition in oxygen-absent environments produces biochar, pyrolysis oil, and syngas from lignocellulosic feedstocks. Niche deployment targets agricultural residue valorization in eastern Netherlands biorefinery corridors.
Incineration dominates installed base. Anaerobic digestion is where expansion concentrates.
End User:
Customer type determines contracting structures, with public procurement rules governing municipal relationships while industrial offtakers negotiate bilateral steam supply agreements.
- Municipalities:Provincial governments and city authorities contract waste processing services under National Waste Management Plan diversion mandates, with gate fee mechanisms and residue disposal guarantees structuring long-term agreements. Randstad urban cores bundle collection, sorting, and energy recovery into integrated concession contracts.
- Industrial Facilities:Rotterdam chemical cluster operators and Amsterdam port zone refineries purchase process steam under dedicated supply contracts, with pressure and temperature specifications tailored to continuous manufacturing operations. These agreements anchor revenue for new capacity investments.
- Power Plants:Grid-connected operators procure waste-derived fuel for co-firing or dedicated biomass units, though merchant power exposure has declined relative to heat-focused business models.
- Waste Management Companies:Integrated collectors and processors operate intermediate sorting and preprocessing infrastructure, feeding prepared refuse-derived fuel to thermal conversion facilities under tolling arrangements.
Municipalities anchor feedstock security. Industrial facilities drive margin expansion.
Feedstock Type:
Input material characteristics dictate preprocessing requirements, emission profiles, and residue handling obligations under Dutch provincial environmental licensing.
- MSW:Mixed household and commercial waste streams with high moisture and variable composition require mechanical sorting and drying before thermal processing. North Holland source separation programs are reducing recoverable fractions, tightening supply for grate combustion plants.
- Industrial Waste:Manufacturing residues, packaging materials, and non-hazardous process waste offer higher calorific value and lower chlorine content than municipal streams. Rotterdam port zone chemical and logistics sectors generate concentrated volumes under long-term supply contracts.
- Agricultural Residues:Manure, crop waste, and food processing byproducts feed anaerobic digestion systems, with nutrient recovery obligations under Dutch manure policy creating co-product revenue streams.
- Construction Waste:Wood fractions, insulation materials, and demolition debris contribute to biomass fuel specifications, though contamination limits restrict acceptance at EU ETS-regulated facilities.
MSW commands the largest processing volumes. Industrial waste offers the highest gate fee realization.
Application:
Output configuration determines equipment investment, with combined heat and power systems commanding capital premiums over electricity-only units.
- Energy Generation:Steam turbine and generator sets convert thermal energy to grid electricity, with capacity factors constrained by seasonal heat demand patterns. Merchant power exposure has declined as operators prioritize contracted thermal offtake.
- Heat Recovery:District heating network supply and industrial process steam delivery capture higher value per unit of energy than power sales. Amsterdam and Rotterdam district heating operators sign 15-year baseload contracts with waste-to-energy plants.
- Fuel Production:Biomethane upgrading and synthetic fuel synthesis from syngas target transport sector decarbonization, with Rotterdam maritime bunkering terminals emerging as key demand anchors.
- Carbon Capture:Post-combustion amine scrubbing and oxy-fuel combustion configurations position plants for negative emission credit generation under emerging EU Green Deal mandates, though integration complexity extends retrofit timelines.
Heat recovery captures value most reliably. Carbon capture is climbing the fastest as a strategic priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Waste Management Plan's landfill diversion timelines and EU ETS carbon pricing reforms are redrawing investment geography across Dutch provinces. Provincial environmental services now license stack emission limits that mandate continuous monitoring systems, concentrating new capacity in industrial corridors with established heat offtake infrastructure.
North Holland
Amsterdam's district heating network operators contract 15-year baseload thermal supply from waste-to-energy plants serving the urban core. The provincial environmental service enforces documented feedstock provenance requirements under CSRD sustainability disclosure alignment. Amsterdam port zone chemical processors pilot advanced combustion control systems to optimize steam output consistency for continuous manufacturing operations.
South Holland
Rotterdam's chemical cluster purchases process steam under dedicated supply contracts with pressure and temperature specifications for manufacturing operations. The EU Waste Incineration Directive's revised emission limits drive continuous monitoring system upgrades across existing thermal lines. Rotterdam maritime bunkering terminals emerge as demand anchors for syngas-to-methanol pilot projects integrating electrolytic hydrogen production.
Brabant
Eindhoven Region's biorefinery corridors deploy pyrolysis systems targeting agricultural residue valorization from surrounding food processing sectors. Dutch manure policy creates nutrient recovery obligations that generate co-product revenue streams for anaerobic digestion operators. The province's organic waste separation mandates accelerate biogas upgrading infrastructure with biomethane injection into the national grid.
Northern Netherlands
Cross-border waste contracts from German border regions expand addressable feedstock volumes for processing facilities in Groningen and Drenthe provinces. The national emission authority coordinates licensing timelines with provincial environmental services to manage stack emission limit compliance across thermal conversion plants. Limited domestic landfill capacity for bottom ash and fly ash treatment forces reliance on German and Belgian disposal facilities, raising logistics costs for regional operators.
Netherlands Waste to Energy Market Competitive Landscape
Listed leaders compete with private specialists across feedstock contracting and industrial heat offtake dimensions. The market structure consolidates around vertically integrated operators with captive waste collection infrastructure and long-term municipal concession agreements. Three archetypes dominate: port-zone industrial steam suppliers, cross-border feedstock aggregators, and district heating baseload contractors. Competitive moves concentrate on securing 15-year heat purchase agreements and integrating carbon capture readiness into existing thermal lines.
Among Dutch-anchored operators, AEB Amsterdam and AVR occupy positions as district heating and industrial steam suppliers respectively, while Attero BV exemplifies the cross-border feedstock aggregation model. AEB Amsterdam represents the vertically integrated archetype with in-house waste collection and processing operations. AVR sits within the industrial cluster supply tier focused on Rotterdam chemical sector contracts. Attero BV anchors eastern Netherlands processing capacity with demonstrated viability of German border region feedstock access. Mitsubishi Heavy Industries Ltd. provides technology licensing and equipment supply to multiple Dutch operators without direct operational ownership.
| Leading Market Players |
|---|
| AEB Bio-energiecentrale B.V. |
| Attero BV |
| Indaver BV |
| Dutch Incinerators B.V. |
| Axpo Holdings AG |
| Ingenia Consultants & Engineers BV |
| AEB Amsterdam |
| AVR |
| Mitsubishi Heavy Industries Ltd. |
| Others |
Supply & Pricing Matrix
Ninety-day feedstock inventory buffers at Randstad thermal plants concentrate pricing power with vertically integrated operators who control waste collection infrastructure, while gate fee compression in North Holland feeds back into supplier selection favoring long-term municipal concession holders over merchant processors.
Pricing Analysis
CE marking tier creates the primary spread between premium and standard plant operators. Contract-based long-term offtake structures dominate, with 15-year heat purchase agreements locking in baseload revenue. Price differentiation hinges on certification level and geographic delivery cost to district heating networks. Municipalities exhibit highest price sensitivity due to public procurement rules, while Rotterdam chemical cluster buyers prioritize steam consistency over gate fees. Pricing pressure stems from feedstock competition with mechanical-biological treatment facilities.
Supply Chain Analysis
Port congestion at Rotterdam and Amsterdam terminals elevates inbound logistics costs for German and Belgian ash disposal shipments. Feedstock supply concentrates in Germany, Belgium, and domestic Randstad provinces. Raw material dependencies include municipal waste streams, industrial residues, and agricultural biomass. Single-source vulnerability runs through cross-border landfill capacity for bottom ash treatment. Distribution runs through provincial environmental licensing corridors with documented feedstock provenance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Rotterdam chemical cluster operators and Amsterdam district heating networks as these industrial offtakers consolidate steam procurement under fewer long-term agreements, squeezing merchant plant margins.
For Market Incumbents: Fortify feedstock security through backward integration into municipal collection concessions before mechanical-biological treatment facilities capture organic waste streams. Prioritize carbon capture readiness investments to position for EU Green Deal negative-emission credit markets. Lock in 15-year heat purchase agreements with Amsterdam and Rotterdam network operators to anchor revenue visibility against merchant power price volatility. For New Entrants and Emerging Players: CE marking fast-track pathways offer entry into South Holland industrial steam supply contracts where incumbent capacity constraints create white-space. Target anaerobic digestion scale-up in Brabant province where organic waste separation mandates outstrip biogas upgrading infrastructure. Lead with biomethane grid injection capabilities to differentiate from thermal-only competitors. For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because landfill diversion mandates and EU ETS carbon pricing create durable demand visibility for waste-derived energy assets. Acquisition candidates should display vertically integrated waste collection infrastructure and active carbon capture retrofit programs. Monitor EU Green Deal implementation timelines for post-combustion CO2 capture mandates as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | Positions Dutch operators for negative-emission credit sales under emerging EU Green Deal mandates. |
| Long-term Heat Purchase Agreement | Amsterdam district heating operators lock 15-year baseload supply, displacing merchant power exposure. |
| Cross-border Feedstock Contract | German border region waste volumes expand addressable supply for eastern Netherlands processing corridors. |
| Biogas Upgrading Infrastructure | Brabant province organic waste separation mandates drive biomethane injection into national grid. |
| Continuous Emissions Monitoring Upgrade | EU Waste Incineration Directive compliance extends operational licenses for Randstad thermal lines. |
Research Methodology
Operator-level perspectives from plant managers, provincial environmental licensing officers, municipal procurement leads, and industrial steam offtake coordinators anchored the qualitative base. Secondary validation drew from Dutch Ministry of Infrastructure and Water Management National Waste Management Plan filings, EU ETS carbon pricing registry data, provincial environmental service licensing records, and EU Waste Incineration Directive compliance databases. Bottom-up capacity and feedstock flow modeling triangulated against top-down investment tracking across the analysis window.
Sensitivity analysis tested forecast robustness across carbon price trajectories, landfill diversion timeline acceleration scenarios, and industrial heat demand elasticity assumptions. Segmentation dimensions modeled include technology type, feedstock source, end-user category, and application output configuration. CAGRs were derived from installed capacity expansion pipelines, technology-specific capital cost curves, and documented offtake contract tenors. Industry-specific inputs incorporated EU Green Deal carbon capture mandate implementation schedules and CSRD sustainability disclosure alignment timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained EU ETS carbon pricing and unchanged National Waste Management Plan diversion targets; material deviation would warrant model refresh. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory acceleration, feedstock import restriction, or carbon capture technology cost breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Energy Recovery Technologies Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Global Waste to Fuel Technology Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
Drilling Waste Management Services Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Brazil Waste to Energy Market