
 Agricultural Waste to Energy Market | 2026-2036
Agricultural Waste to Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Waste to Energy Market Analysis
Modular biogas digester bundling with combined heat and power units is realigning procurement patterns for mid-scale agricultural operations. Ameresco leverages its energy-as-a-service model to anchor long-term utility contracts in North American farm clusters. EnviTec Biogas specializes in standardized containerized digester systems that reduce installation lead times for European dairy cooperatives. Veolia competes through integrated waste collection-to-energy logistics that tighten feedstock security for French agricultural regions.
Agricultural waste to energy encompasses thermochemical and biochemical conversion processes that transform crop residues, animal manure, and food processing byproducts into usable energy carriers, with biogas systems typically operating at 35-55 degrees Celsius mesophilic conditions and producing methane concentrations of 50-70 percent. Biomass combustion and biogas anaerobic digestion occupy the dominant installed base, while gasification and pyrolysis represent faster-growing technology pools where capital efficiency improvements are concentrating investor attention. Corn stover and sugarcane bagasse command the largest feedstock volumes in existing capacity, though rice husk utilization is expanding fastest in South and Southeast Asian milling corridors where collection infrastructure now reaches economies of scale.
The EPA's Renewable Fuel Standard and the EU's Renewable Energy Directive shape feedstock qualification and carbon intensity scoring for market access in their respective jurisdictions, while India's MNRE biomass power policies and CEA grid connectivity mandates accelerate deployment timelines for agricultural residue projects. China's MEE enforcement of rural pollution control standards and dual carbon goals is redirecting provincial investment toward centralized biogas facilities. Stakeholders must track how evolving sustainability certification requirements for biomass traceability will reshape procurement protocols and project finance eligibility across major producing regions.
Market Dynamics
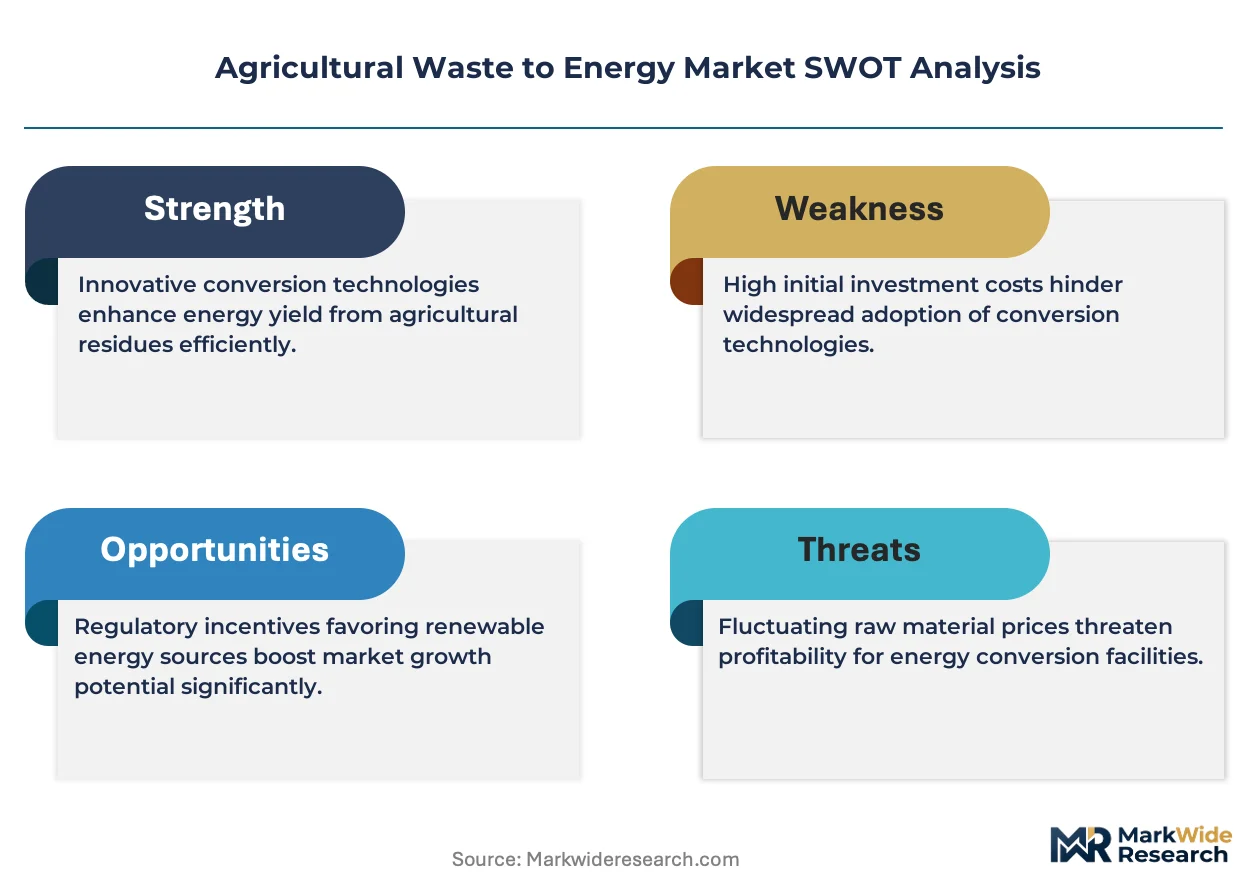
Feed-in-tariff expansion across Southeast Asian power utilities is compressing project payback periods and redirecting capital toward rice husk and bagasse installations in clustered milling zones.
Growth Catalysts
- EU Green Deal sustainability criteria:The revised Renewable Energy Directive tightens biomass traceability requirements, channeling investment toward certified agricultural residue supply chains in French and German farming regions.
- Mesophilic biogas digester adoption:Dairy cooperatives across Denmark and the Netherlands are deploying standardized containerized systems operating at 35-55 degrees Celsius, cutting installation lead times and methane leakage rates.
- Vietnam's Mekong Delta concentration:Multi-lateral development finance is pooling around rice husk-to-power projects where collection infrastructure has achieved economies of scale in An Giang and Kien Giang provinces.
Market Restraints
- Feedstock cost volatility:Corn stover and sugarcane bagasse pricing fluctuates with grain commodity cycles, squeezing project IRRs for independent power producers without long-term supply contracts.
- Grid interconnection bottlenecks:India's CEA mandates create procedural delays for agricultural residue projects seeking evacuation infrastructure in Bihar and Punjab states.
- Pyrolysis oil quality inconsistency:Thermochemical conversion yields remain variable across feedstock moisture profiles, limiting off-take agreements with refiners seeking standardized bio-crude specifications.
Strategic Opportunities
- Combined heat and power bundling:Modular biogas digesters paired with CHP units are opening mid-scale agricultural operations in Poland and Italy that previously lacked thermal offtake agreements.
- China's rural pollution enforcement:MEE standards under dual carbon goals are redirecting provincial investment toward centralized biogas facilities in Shandong and Henan livestock corridors.
- Carbon intensity scoring arbitrage:The EPA's Renewable Fuel Standard and EU RED carbon accounting divergence creates pathway optimization potential for feedstock suppliers qualifying for both jurisdictions.
Industry Challenges
- Anaerobic digestion microbiology expertise:The talent pool for optimizing mesophilic and thermophilic digester performance remains shallow across Eastern European project development teams.
- Gasification reactor materials science:High-temperature corrosion in biomass syngas environments drives unplanned maintenance cycles and replacement capex that strain operational budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Waste to Energy Market |
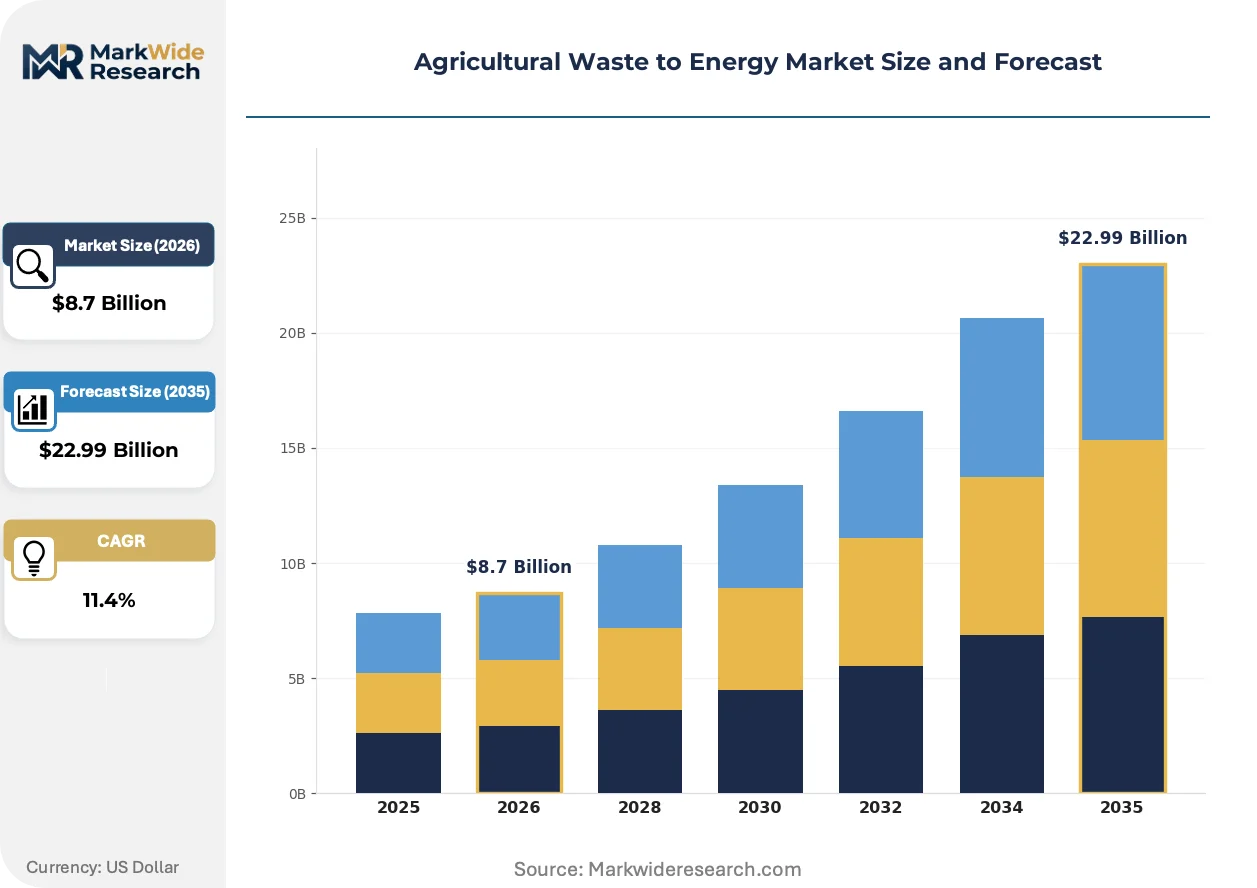
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biogas, Biomass, Gasification, Pyrolysis Feedstock Type: Corn Stover, Rice Husk, Sugarcane Bagasse, Wheat Straw End User: Agricultural Corporations, Energy Producers, Waste Management Companies, Government Agencies Application: Power Generation, Heat Production, Biofuels, Nutrient Recovery |
| Companies Covered | Ameresco, Veolia, Waste Management, SUEZ, Duke Energy, Bioenergy DevCo, Enel Green Power, EnviTec Biogas, A2A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Waste to Energy Market Emerging Trajectories
Technology convergence between thermochemical conversion and digital process control is compressing energy yield variance and enabling remote monitoring of distributed agricultural waste assets.
Pressurized oxygen-blown gasification is electrifying rural industrial microgrids by converting rice husk and corn stover into syngas suitable for reciprocating engines. Vietnamese milling cooperatives are deploying these systems at 2-5 MW scale to displace diesel backup generation. The technology is electrifying previously unviable project economics in feedstock-rich regions lacking transmission access.
The EU's revised Renewable Energy Directive tightens land-use change criteria and biomass traceability requirements for agricultural feedstocks entering the transport and heating sectors. Project developers must now deploy mass-balance certification systems and satellite monitoring to verify residue collection practices. French biogas clusters are responding fastest, integrating blockchain-based provenance tracking into digester operations to secure premium tariff eligibility.
Power purchase agreement structures are fragmenting as agricultural cooperatives bypass traditional utility intermediaries to contract directly with corporate offtakers seeking Scope 3 emission reductions. Danish biogas associations now aggregate output from 50+ farm-scale digesters into virtual power pools that transact with food manufacturers. This disintermediation is most visible in the Netherlands, where dairy processors are acquiring equity stakes in supplier digesters to secure biomethane offtake.
Agricultural Waste to Energy Market Segmentation
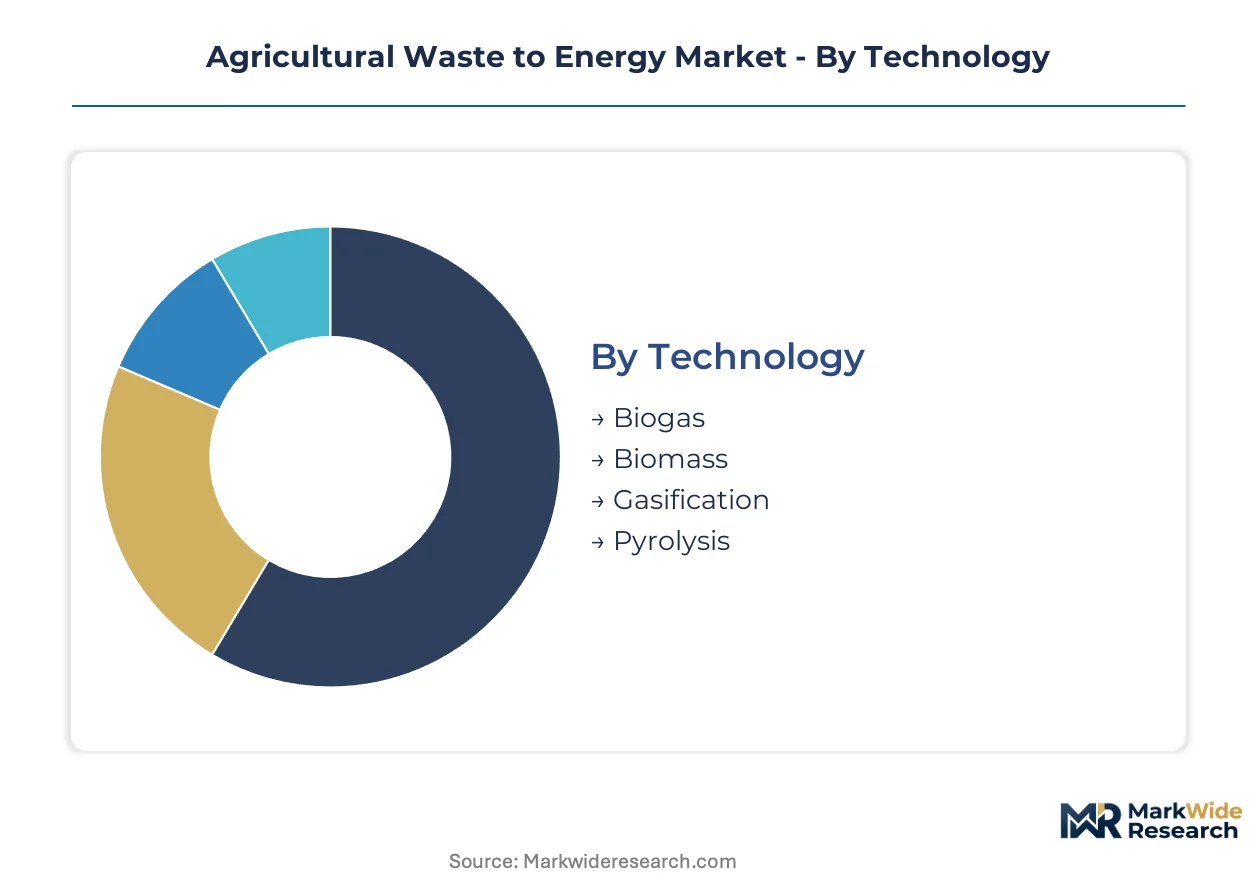
Technology pathways diverge sharply in capital requirements and feedstock flexibility, creating distinct investment profiles across project scales. Feedstock availability and end-user offtake security further stratify market entry barriers for developers.
Technology:
Capital intensity varies by an order of magnitude across conversion pathways, with thermochemical systems demanding substantially higher upfront engineering and materials investment than biochemical alternatives.
- Biogas:Anaerobic digestion operates at 35-55 degrees Celsius mesophilic conditions, producing methane concentrations of 50-70 percent. Danish dairy cooperatives and Vietnamese rice milling clusters deploy standardized containerized digesters to cut installation lead times and secure feed-in-tariff contracts.
- Biomass:Direct combustion of crop residues and animal manure requires lower technology risk but demands consistent feedstock preprocessing. French agricultural regions and North American farm clusters anchor long-term utility contracts through integrated waste collection logistics.
- Gasification:Pressurized oxygen-blown systems convert rice husk and corn stover into syngas for reciprocating engines at 2-5 MW scale.
- Pyrolysis:Thermochemical conversion yields bio-crude with variable quality across moisture profiles, limiting refiner offtake agreements.
Biomass combustion absorbs the bulk of installed capacity; gasification is expanding most quickly in feedstock-rich regions lacking transmission access.
Feedstock Type:
Collection infrastructure maturity and commodity price linkage determine project finance eligibility and long-term supply contract viability.
- Corn Stover:The largest feedstock volume in existing capacity, though pricing fluctuates with grain commodity cycles. Independent power producers in the US Midwest face squeezed IRRs without long-term supply contracts.
- Rice Husk:Utilization is climbing fastest in South and Southeast Asian milling corridors where collection infrastructure achieves economies of scale. Vietnam's Mekong Delta provinces draw multi-lateral development finance for husk-to-power installations.
- Sugarcane Bagasse:Brazilian and Indian sugar cooperatives integrate bagasse cogeneration into existing milling operations.
- Wheat Straw:European biogas clusters in Poland and Italy deploy wheat straw in combined heat and power configurations for mid-scale agricultural operations.
Corn stover dominates current feedstock throughput; rice husk is gaining share fastest as Asian collection networks mature.
End User:
Customer type dictates project scale, offtake structure, and regulatory compliance burden across development timelines.
- Agricultural Corporations:Integrated farming operations deploy captive biogas facilities to manage manure liabilities and secure thermal offtake. Dutch dairy processors acquire equity stakes in supplier digesters to lock in biomethane supply.
- Energy Producers:Power utilities across Southeast Asia expand feed-in-tariff contracts for agricultural residue projects, compressing payback periods in clustered milling zones.
- Waste Management Companies:Veolia and competitors tighten feedstock security through integrated collection-to-energy logistics in French regions.
- Government Agencies:China's MEE redirects provincial investment toward centralized biogas facilities under rural pollution enforcement and dual carbon goals.
Energy producers command the largest project pipeline; agricultural corporations are driving the steepest expansion trajectory through vertical integration.
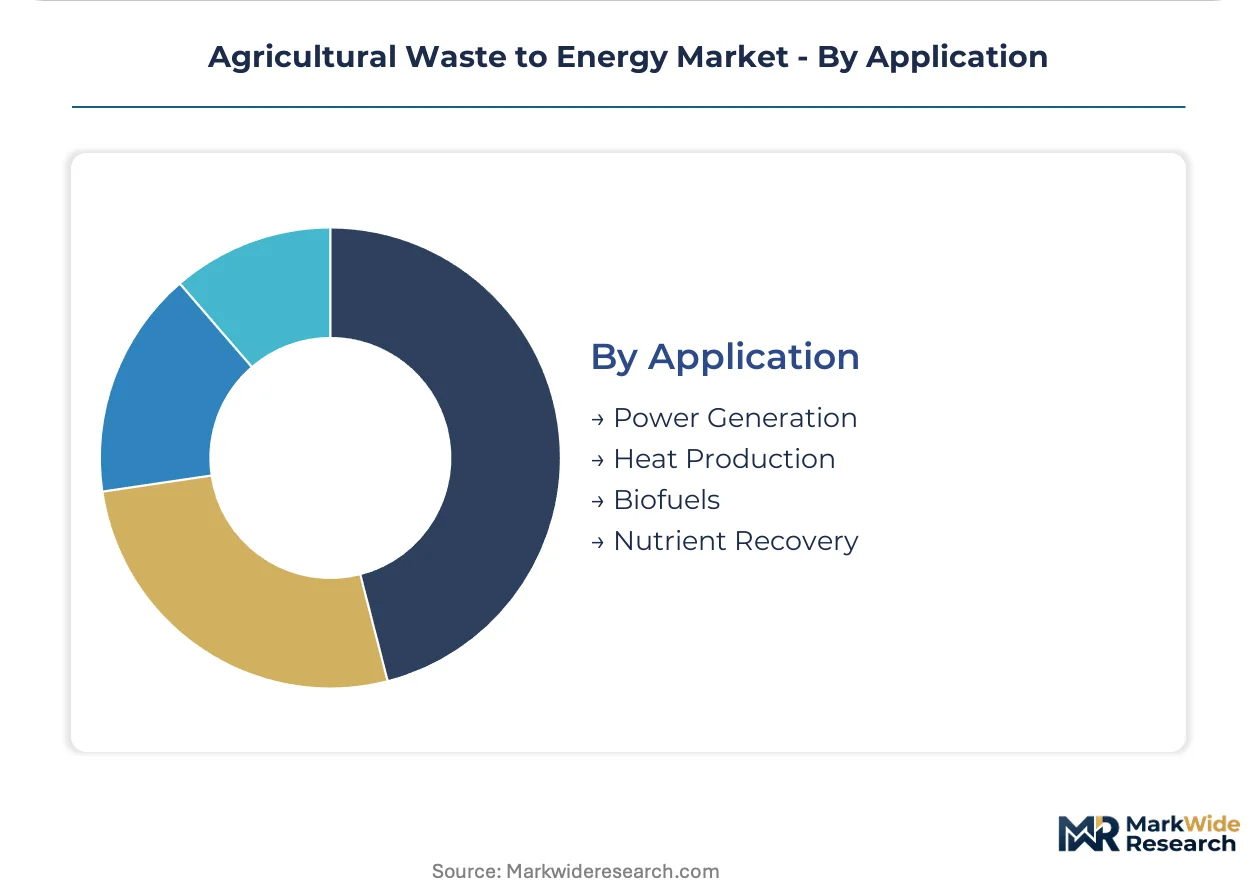
Application:
Revenue model stability and carbon credit eligibility vary by energy carrier output and end-market regulatory treatment.
- Power Generation:Grid-connected agricultural residue projects face interconnection bottlenecks under India's CEA mandates, creating procedural delays in Bihar and Punjab states. Vietnamese pressurized gasification systems electrify rural industrial microgrids.
- Heat Production:Combined heat and power bundling opens mid-scale operations in Poland and Italy previously lacking thermal offtake agreements. Modular digesters paired with CHP units realign procurement patterns.
- Biofuels:EPA Renewable Fuel Standard and EU Renewable Energy Directive carbon accounting divergence creates pathway optimization potential for feedstock suppliers qualifying for both jurisdictions.
- Nutrient Recovery:Digestate output from mesophilic systems returns phosphorus and nitrogen to agricultural soils, closing nutrient loops in Danish and Netherlands dairy corridors.
Power generation retains the dominant revenue share; biofuels are climbing fastest as transport sector carbon intensity requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of agricultural residue energy concentrates in feedstock-rich farming belts, while consumption demand clusters around industrial zones seeking thermal and power offtake. Vietnam's Mekong Delta and India's northern grain states anchor installed capacity expansion. European biogas corridors and North American farm clusters complete the geographic footprint.
United States
Corn stover collection networks in Iowa and Illinois supply independent power producers facing squeezed IRRs without long-term supply contracts. The EPA's Renewable Fuel Standard shapes feedstock qualification and carbon intensity scoring for biofuel pathway access. Midwest farm clusters anchor Ameresco's energy-as-a-service utility contracts through modular digester bundling.
Germany
Dairy cooperatives in Lower Saxony and Bavaria deploy standardized containerized digesters operating at mesophilic conditions to cut methane leakage rates. The EU Green Deal's revised Renewable Energy Directive tightens biomass traceability requirements, channeling investment toward certified residue supply chains. EnviTec Biogas specializes in these systems for European agricultural operations.
China
Livestock corridors in Shandong and Henan provinces redirect provincial investment toward centralized biogas facilities under MEE rural pollution enforcement and dual carbon goals. The country's national environmental regulator enforces standards that accelerate deployment timelines for agricultural residue projects. Provincial governments pool capital around manure-to-energy installations in these eastern farming belts.
Vietnam
Rice husk-to-power projects in An Giang and Kien Giang provinces draw multi-lateral development finance where collection infrastructure achieves economies of scale. Feed-in-tariff expansion across national power utilities compresses project payback periods in clustered milling zones. Pressurized oxygen-blown gasification systems electrify rural industrial microgrids at 2-5 MW scale.
India
Sugarcane bagasse cogeneration integrates into existing milling operations in Maharashtra and Uttar Pradesh sugar cooperatives. The CEA grid connectivity mandates create procedural delays for agricultural residue projects seeking evacuation infrastructure in Bihar and Punjab states. MNRE biomass power policies accelerate deployment timelines for residue-to-power installations in these northern grain states.
Agricultural Waste to Energy Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology pathways and geographic footprints. The vendor base stratifies into three tiers: integrated waste-to-energy conglomerates with collection logistics, technology licensors with standardized digester platforms, and regional project developers with captive feedstock relationships. Dominant competitive moves include strategic partnerships with agricultural cooperatives and capacity expansion into clustered milling zones where collection infrastructure achieves scale.
Among North American energy service providers, Ameresco and Waste Management exemplify divergent strategic archetypes. Ameresco occupies a position within the long-term utility contracting tier, while Waste Management sits within the integrated collection-to-energy logistics segment. Veolia anchors the European conglomerate tier with French agricultural region coverage. EnviTec Biogas represents the standardized technology platform specialist archetype for dairy cooperative deployments.
| Leading Market Players |
|---|
| Ameresco |
| Veolia |
| Waste Management |
| SUEZ |
| Duke Energy |
| Bioenergy DevCo |
| Enel Green Power |
| EnviTec Biogas |
| A2A |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EU RED-compliant biomass and uncertified residue streams manifests in both feedstock procurement premiums and supply chain segregation. French biogas clusters now pay traceability premiums for satellite-verified corn stover while Vietnamese rice mills source unverified husk through informal broker networks at substantial discounts.
Pricing Analysis
Margin tightening in standardized digester systems reflects steel and membrane cost escalation plus installation labor shortages. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-certified EU feedstock from mass-balance verified Asian supply and uncertified spot market material. Cost-down pressure on containerized biogas units accelerates because dairy cooperatives in Denmark and the Netherlands consolidate procurement through purchasing alliances. Agricultural corporations show lowest price sensitivity given captive manure liabilities, while independent power producers in India's northern states face acute budget constraints under CEA-mandated grid upgrade obligations.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for digester component logistics. Manufacturing concentration rests on Germany for precision-engineered agitators, China for steel vessels and electrical housings, and Denmark for membrane and sensor packages. Raw material dependencies include specialty stainless alloys for corrosion resistance, polymer membranes for gas separation, and rare-earth elements for process control instrumentation. Single-source vulnerability from Chinese electrical component suppliers creates procurement risk during trade policy shifts. Distribution runs through EPC contractor networks with localized assembly partnerships in Vietnam and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's revised Renewable Energy Directive erects a compliance moat that rewards early certification investment while excluding late adopters from premium tariff eligibility.
For Market Incumbents: Lock in long-term feedstock supply contracts in Vietnam's Mekong Delta and India's Punjab corridor before collection infrastructure achieves full economies of scale. Acquire specialized microbiology talent pools in Eastern Europe where anaerobic digestion expertise remains scarce. Defend against pyrolysis technology disruptors by embedding CHP bundling into existing utility relationships. For New Entrants and Emerging Players: Agricultural cooperatives in Poland and Italy represent the most penetrable channel partner type for modular digester deployments lacking thermal offtake history. Target mid-scale livestock operations in Shandong province where MEE enforcement creates urgent manure liability pressure. White-space exists in blockchain-based provenance tracking systems for French biogas clusters seeking RED compliance. Go-to-market leverage centers on energy-as-a-service contracting that eliminates upfront capital barriers. For Investors and Strategic Acquirers: Re-rating potential sits with technology licensors possessing standardized containerized platforms given the acceleration of dairy cooperative procurement consolidation. Long-term viability favors specialists with demonstrated installation lead time compression and methane leakage rate certification. Acquisition target archetype includes regional project developers with captive feedstock relationships in clustered milling zones. Watch for EPA-EU carbon accounting convergence as the signal indicating feedstock supplier pathway optimization premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Supply Contracting | Long-term offtake agreements with Vietnamese rice milling cooperatives secure collection infrastructure access ahead of competitor lock-up. |
| Blockchain Provenance Integration | Mass-balance certification systems with satellite monitoring satisfy EU RED traceability requirements for premium tariff eligibility. |
| Microbiology Talent Acquisition | Specialized anaerobic digestion expertise addresses capability scarcity constraining Eastern European project development timelines. |
| CHP Bundling Expansion | Combined heat and power pairing opens mid-scale Polish and Italian agricultural operations previously lacking thermal revenue streams. |
| Containerized Platform Standardization | Reduced installation lead times accelerate feed-in-tariff capture in competitive Danish and Dutch dairy cooperative procurement cycles. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and feedstock supply specialists combined with EIA project databases, IEA renewable energy reports, FERC interconnection filings, and MNRE biomass policy circulars. Bottom-up installation capacity tallies triangulated against top-down energy output estimates across the analysis window.
Data-stream reconciliation between feedstock availability assessments and technology deployment tracking informed the analytical framework. Segmentation dimensions modeled include conversion pathway, feedstock type, project capacity tier, regulatory framework cluster, and regional grid connectivity status. CAGRs derived from capacity expansion pipelines and feed-in-tariff contract volumes. Forecast inputs incorporated MEE enforcement intensity projections and EU RED implementation timelines.
Several conditions sit outside the modeled scope, including breakthrough thermochemical conversion efficiency gains, abrupt feed-in-tariff policy suspensions, and unanticipated agricultural commodity price shocks. Forecasts reflect documented assumptions regarding collection infrastructure buildout rates and interconnection queue clearance timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
United States Waste to Energy Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
Brazil Waste to Energy Market
Waste to Energy Systems
North America Waste to Energy Market