
 Energy Recovery Technologies Market | 2026-2036
Energy Recovery Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Recovery Technologies Market Foresight
Aftermarket service revenue for energy recovery systems is fragmenting across third-party refurbishment networks and original equipment service arms. Bosch leverages its thermal technology portfolio to anchor premium heat exchanger maintenance contracts in European automotive plants. Denso Corporation competes through in-house production of compact turbine assemblies for vehicle waste heat recovery. BorgWarner Inc. specializes in pressure exchanger retrofits for industrial process lines, sustaining margin pools outside new equipment sales.
Energy recovery technologies capture and convert otherwise dissipated thermal, mechanical, or chemical energy into reusable power or process inputs, typically operating across temperature differentials from 60°C to 400°C depending on heat source grade. These systems serve primarily to reduce primary energy consumption and lower operational carbon intensity in continuous-process industries. Heat exchangers dominate installed base value due to decades of proven deployment in petrochemical and food processing facilities. Mechanical technologies including pressure exchangers and turbines represent the fastest-expanding segment as seawater reverse osmosis desalination capacity expands in water-stressed regions. Electrical systems remain comparatively nascent, with margin pools concentrated in R&D-stage thermoelectric materials rather than commercial deployments.
The EPA enforces emissions thresholds that compel US manufacturing facilities to install certified waste heat recovery equipment or face penalties under Clean Air Act enforcement. In Europe, the EU Green Deal and F-Gas Regulation together restrict high-global-warming-potential refrigerants in thermal systems, redirecting procurement toward compliant heat pump and exchanger designs. China's MEE administers dual carbon goals that mandate energy intensity reductions for designated industrial consumers, effectively conditioning market access on recovery technology adoption. Stakeholders must monitor how divergent efficiency certification timelines across these jurisdictions reshape equipment interoperability requirements and service localization strategies.
Market Dynamics
Data center thermal loads are forcing operators to treat waste heat as a recoverable asset rather than a disposal cost, compressing payback periods for heat-to-power installations and rewriting procurement specifications across colocation and hyperscale facilities.
Growth Catalysts
- EU Ecodesign Directive:Tightening efficiency thresholds for industrial motors and thermal equipment are compelling automotive and food processing plants across Germany, France, and Italy to accelerate heat exchanger replacement cycles.
- Seawater reverse osmosis expansion:Pressure exchanger demand concentrates in water-stressed coastal zones of Saudi Arabia, Israel, and Australia as desalination capacity scales to offset municipal supply deficits.
- China's MEE dual carbon enforcement:State-mandated energy intensity audits for designated industrial consumers in Jiangsu and Guangdong provinces are conditioning operating licenses on verified waste heat recovery deployment.
Market Restraints
- High-grade alloy supply concentration:Superalloy procurement for turbine blades and heat exchanger cores depends on a concentrated supplier base in Germany and Japan, exposing lead times to geopolitical friction.
- Heat source intermittency:Batch-process industries in specialty chemicals and pharmaceuticals generate thermal gradients below the 60°C threshold for viable organic Rankine cycle operation, constraining addressable application scope.
- Legacy refrigerant phase-out costs:The EU F-Gas Regulation imposes escalating quotas on high-global-warming-potential working fluids, forcing retrofits of existing heat pump installations before end-of-life.
Strategic Opportunities
- Industrial cluster heat networks:District heating integration in Rotterdam, Eindhoven, and Gothenburg creates anchor demand for centralized waste heat aggregation from colocated process plants.
- Vehicle waste heat recovery:Compact turbine assemblies for heavy-duty trucking and marine propulsion remain underpenetrated relative to passenger car applications, with METI efficiency incentives accelerating Japanese OEM evaluation.
- AI-driven predictive maintenance:Sensor-embedded heat exchanger systems enable outcome-based service contracts that displace scheduled overhaul models in petrochemical complexes.
Industry Challenges
- Thermofluids engineering scarcity:Design of compact heat exchangers and turbine blade geometries requires specialized computational fluid dynamics expertise concentrated in aerospace and power generation sectors, limiting vendor scaling.
- Legacy control system integration:Brownfield process lines in North American refineries and chemical plants operate on proprietary DCS architectures that resist open-protocol heat recovery equipment interfacing without costly middleware.
- ASME and PED certification timelines:Pressure equipment safety approvals for high-temperature heat recovery systems extend 14-22 months, compressing project delivery windows for EPC contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Recovery Technologies Market |
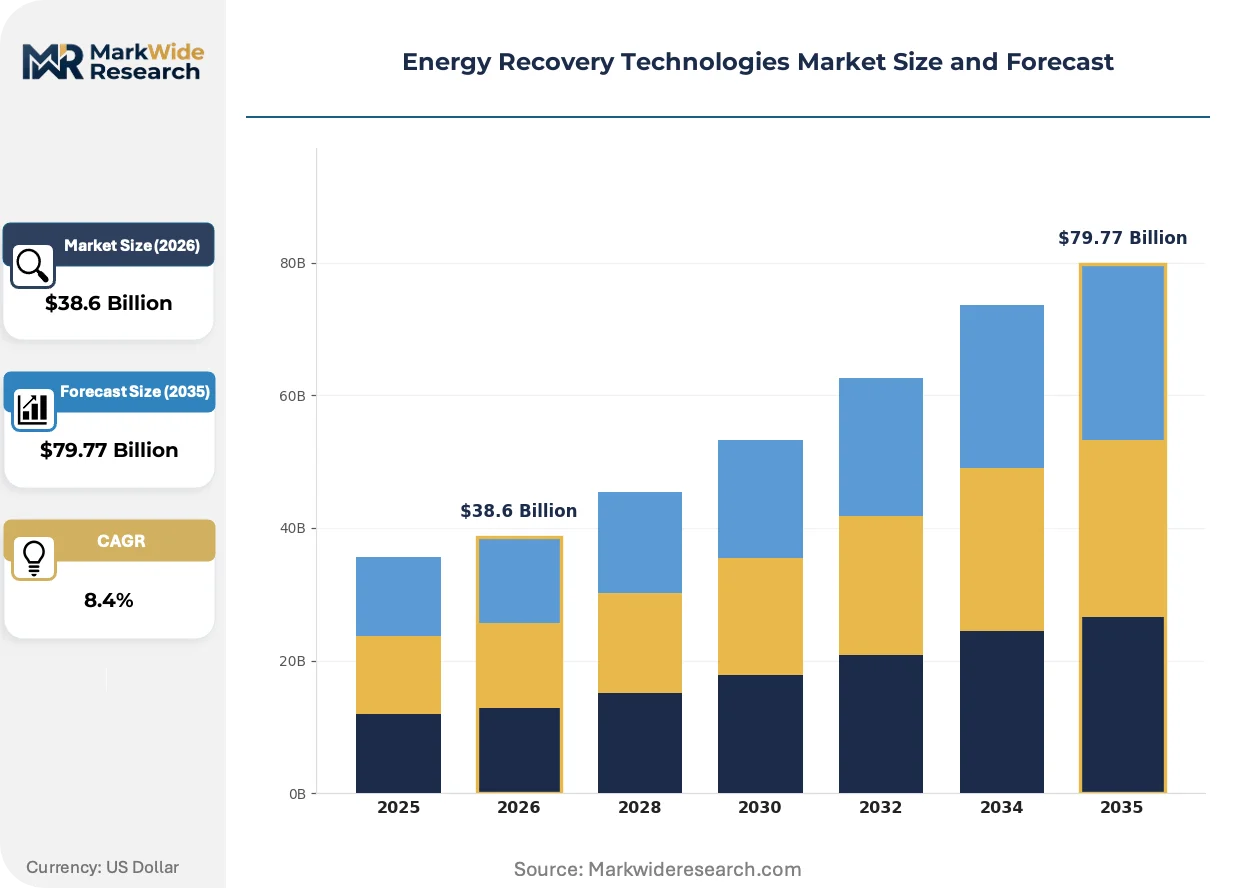
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Exchangers, Pressure Exchangers, Turbines, Compressors Application: Waste Heat Recovery, Water Treatment, Desalination, Industrial Processes Technology: Thermal Technologies, Mechanical Technologies, Chemical Processes, Electrical Systems End User: Manufacturing, Utilities, Oil & Gas, Food & Beverage |
| Companies Covered | Robert Bosch GmbH, Continental AG, Toyota Motor Corporation, BorgWarner Inc., ZF Friedrichshafen AG, General Motors Company, Denso Corporation, Cummins Inc., BMW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Recovery Technologies Market Shifts & Advancements
Digital twin architectures are displacing physical prototyping in thermal system design, compressing development cycles while enabling real-time optimization of heat recovery performance across distributed industrial assets.
Advanced ceramic matrix composites for heat exchanger cores withstand temperature differentials exceeding 800°C in steel and cement kiln applications. European refractory specialists are adopting these materials for retrofit installations in Rotterdam and Duisburg industrial clusters. The technology is virtualizing traditional metal-alloy supply chains by reducing dependence on nickel and cobalt feedstocks.
The EPA Clean Air Act enforcement framework mandates continuous emissions monitoring and verified waste heat recovery installation for major source manufacturing facilities. Penalty exposure and enforcement discretion are redirecting capital allocation toward certified equipment procurement. Petrochemical complexes along the US Gulf Coast are prioritizing EPA-compliant pressure exchanger retrofits to avoid consent decree exposure.
Aftermarket service unbundling is fragmenting maintenance revenue across third-party refurbishment networks and OEM service arms. Data center operators in Frankfurt, Amsterdam, and Singapore are negotiating performance-guaranteed heat recovery service contracts that separate equipment ownership from thermal output responsibility. This reconfiguration concentrates margin pressure on original equipment vendors while elevating specialized thermal service providers.
Energy Recovery Technologies Market Segmentation
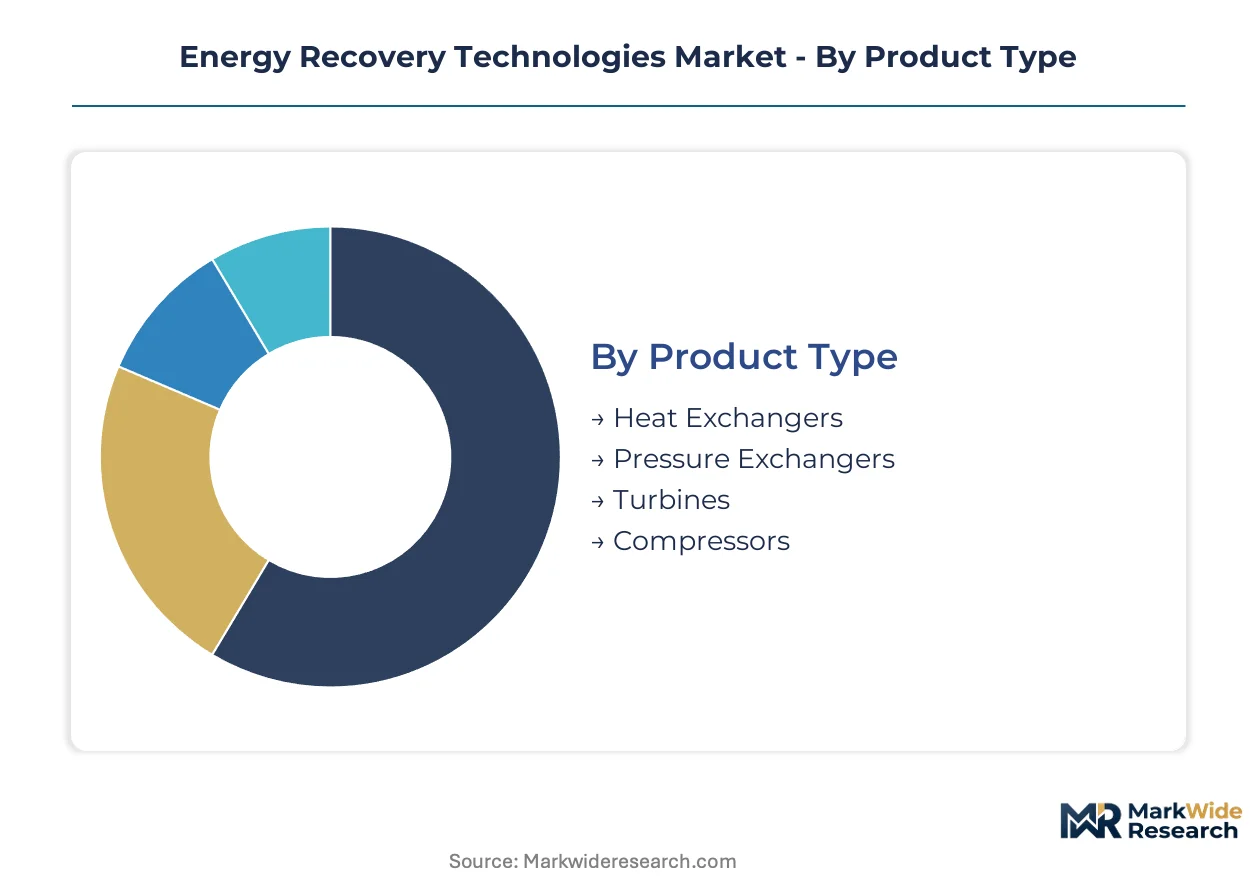
Energy recovery technologies span divergent thermal grades and process intensities, requiring precise matching of equipment specifications to source characteristics. Segmentation reveals how technology maturity and regulatory pressure concentrate margin pools across distinct product architectures and end-use applications.
Product Type:
Use-case spectrum stretches from continuous-process heat transfer to intermittent mechanical energy conversion, with each product category serving distinct temperature bands and maintenance regimes.
- Heat Exchangers:Plate-and-frame and shell-and-tube configurations dominate petrochemical and food processing baseload operations. European automotive plants in Germany and France are accelerating replacement cycles under EU Ecodesign Directive efficiency thresholds, compressing procurement timelines for certified units.
- Pressure Exchangers:Isobaric chambers transfer energy between high-pressure brine and incoming seawater in reverse osmosis trains. Demand concentrates in Saudi Arabia, Israel, and Australia's coastal desalination corridors as municipal supply deficits drive capacity expansion.
- Turbines:Organic Rankine cycle and steam expanders convert thermal gradients above 150°C into shaft power. Compact assemblies for heavy-duty trucking applications remain underpenetrated relative to stationary industrial deployments.
- Compressors:Intercooled screw and centrifugal units recover pressure energy in natural gas processing and air separation trains. Refinery operators along the US Gulf Coast prioritize EPA-compliant configurations to avoid Clean Air Act enforcement exposure.
Established volume favors heat exchangers; emerging adoption favors pressure exchangers.
Application:
Cost tier stratification separates mature efficiency retrofits from capital-intensive greenfield installations, with payback period sensitivity driving procurement authority placement.
- Waste Heat Recovery:Systems capture thermal energy from exhaust streams, furnace off-gases, and cooling circuits across 60°C to 400°C source grades. China's MEE dual carbon enforcement in Jiangsu and Guangdong provinces mandates verified deployment for designated industrial consumers, conditioning operating licenses on recovery technology adoption.
- Water Treatment:Energy recovery devices reduce pumping loads in municipal and industrial filtration networks. Pressure exchanger integration in Singapore and Rotterdam water reclamation facilities demonstrates lowest lifecycle cost for high-pressure membrane operations.
- Desalination:Seawater reverse osmosis plants deploy isobaric energy recovery to slash specific energy consumption below 3 kWh per cubic meter. Capacity scaling in water-stressed coastal zones of the Middle East and Australia anchors equipment demand.
- Industrial Processes:Cement kilns, steel furnaces, and chemical reactors generate recoverable thermal loads through continuous high-temperature operation. Advanced ceramic matrix composites are penetrating retrofit installations in Rotterdam and Duisburg industrial clusters, withstanding temperature differentials exceeding 800°C.
Procurement authority for waste heat recovery sits with plant engineering; desalination decisions concentrate with municipal water authorities and EPC contractors.
Technology:
Customer type divergence separates process-industry engineers specifying proven thermal systems from R&D-stage buyers evaluating novel electrical conversion architectures.
- Thermal Technologies:Heat exchangers, regenerators, and recuperators transfer energy across temperature gradients with decades of operational validation. Food and beverage processors in Italy and Spain specify hygienic-design plate exchangers under EU food safety frameworks.
- Mechanical Technologies:Pressure exchangers, turbines, and expanders convert fluid pressure and kinetic energy into reusable shaft power. This segment is climbing the fastest as seawater reverse osmosis capacity expands across water-stressed regions.
- Chemical Processes:Absorption heat pumps and thermochemical storage systems leverage reversible reactions for temperature upgrading. Deployment remains concentrated in district heating integration projects in Eindhoven and Gothenburg industrial clusters.
- Electrical Systems:Thermoelectric generators and piezoelectric harvesters convert thermal and vibrational energy directly to electricity. Margin pools concentrate in R&D-stage materials rather than commercial deployments, with commercialization timelines extending beyond current forecast windows.
Process engineers favor thermal and mechanical technologies; sustainability officers and research consortia pilot electrical system prototypes.
End User:
Supply concentration for superalloy components and specialized engineering services shapes vendor accessibility across end-user categories with divergent technical sophistication.
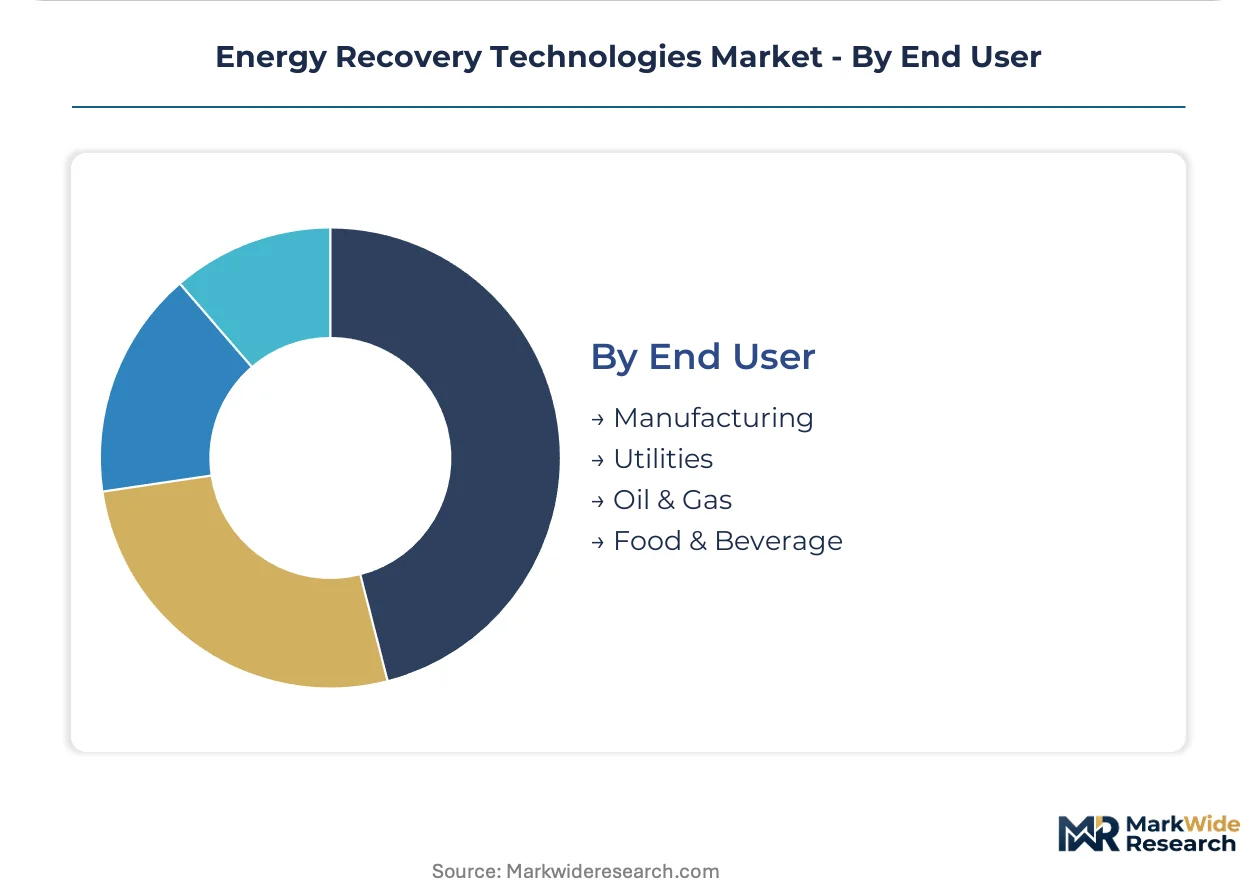
- Manufacturing:Automotive, electronics, and discrete goods producers deploy heat recovery for compressed air systems, paint curing ovens, and process cooling loops. German automotive plants anchor premium maintenance contract demand for OEM service arms.
- Utilities:Power generators and district heating operators aggregate waste heat from colocated industrial sources. Rotterdam's port industrial cluster demonstrates centralized thermal network architecture, creating anchor demand for large-scale heat exchanger installations.
- Oil & Gas:Upstream production, refining, and petrochemical complexes generate substantial recoverable thermal and pressure energy. US Gulf Coast refineries face EPA Clean Air Act enforcement pressure, redirecting capital toward certified pressure exchanger retrofits.
- Food & Beverage:Pasteurization, evaporation, and drying operations present continuous low-grade heat sources. Hygienic-design requirements and EU food safety regulations constrain vendor qualification to specialists with proven cleanability validation.
Volume concentration favors manufacturing and oil & gas; policy-driven retrofit urgency favors utilities facing decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Superalloy procurement for turbine blades and heat exchanger cores concentrates manufacturing dependencies in Germany and Japan, exposing lead times to geopolitical friction while China's coastal provinces enforce the strictest retrofit timelines.
United States
Petrochemical complexes along the US Gulf Coast generate substantial recoverable thermal and pressure energy from continuous high-temperature operations. EPA Clean Air Act enforcement mandates continuous emissions monitoring and verified waste heat recovery installation for major source manufacturing facilities. Refinery operators in Texas and Louisiana prioritize certified pressure exchanger retrofits to avoid consent decree exposure and penalty risk.
Germany
Automotive plants across Baden-Württemberg and Bavaria anchor premium maintenance contract demand for thermal technology service arms. EU Ecodesign Directive tightening efficiency thresholds for industrial motors and thermal equipment compels accelerated heat exchanger replacement cycles. Industrial clusters in Duisburg and the Ruhr region demonstrate centralized waste heat aggregation architectures for district heating integration.
China
State-backed efficiency mandates apply strictest retrofit timelines in Jiangsu and Guangdong coastal manufacturing provinces. MEE dual carbon goals mandate energy intensity reductions for designated industrial consumers, conditioning operating licenses on verified waste heat recovery deployment. Yangtze River Delta process plants face compressed procurement timelines for certified heat recovery equipment.
Saudi Arabia
Seawater reverse osmosis capacity expansion in water-stressed coastal zones drives pressure exchanger demand for municipal supply deficit offset. Desalination corridor development concentrates equipment procurement authority with EPC contractors and municipal water authorities. Red Sea coastal installations deploy isobaric energy recovery to slash specific energy consumption below threshold levels.
Japan
Compact turbine assemblies for heavy-duty trucking and marine propulsion applications remain underpenetrated relative to passenger car deployments. METI efficiency incentives accelerate OEM evaluation of vehicle waste heat recovery systems. Nagoya-area automotive suppliers leverage in-house production capabilities for thermal component fabrication.
Energy Recovery Technologies Market Competitive Landscape
Diversified industrial conglomerates and specialized thermal technology providers split the market across distinct value capture models. Tier-one automotive suppliers leverage captive production of compact turbine assemblies to anchor service contracts. Industrial process specialists concentrate margin pools in pressure exchanger retrofits for brownfield installations. Dominant competitive moves include backward integration into superalloy component fabrication and geographic expansion through EPC contractor partnerships in water-stressed regions.
Within the diversified industrial tier, Robert Bosch GmbH and Continental AG exemplify archetypes leveraging broad thermal technology portfolios to secure premium maintenance contracts. Denso Corporation occupies a position representing specialized compact turbine production for vehicle applications. BorgWarner Inc. anchors the industrial process specialist segment, with ZF Friedrichshafen AG sitting within the scale-driven automotive supplier category. These entities collectively illustrate how vendor strategies diverge between equipment ownership models and outcome-based thermal service configurations.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Toyota Motor Corporation |
| BorgWarner Inc. |
| ZF Friedrichshafen AG |
| General Motors Company |
| Denso Corporation |
| Cummins Inc. |
| BMW Group |
| Others |
Supply & Pricing Matrix
German and Japanese superalloy suppliers for turbine blades and heat exchanger cores anchor upstream margin capture, forcing downstream equipment vendors to absorb volatility or push price adjustments through long-term service contracts. Aftermarket service unbundling fragments pricing power across third-party refurbishment networks and OEM service arms, compressing realized margins on new equipment sales while elevating lifetime value extraction through maintenance tiers.
Pricing Analysis
Aftermarket parts and extended service contracts generate the dominant share of lifetime customer value, displacing upfront equipment margins as the primary revenue anchor. Three-tier pricing structure across premium, standard, and economy levels stratifies according to ASME/PED certification grade and geographic delivery scope. Cost compression in standard-tier heat exchanger retrofits intensifies because of third-party refurbishment network expansion. Municipal water authorities in desalination corridors exhibit highest price sensitivity due to capex scrutiny, while data center operators demonstrate lowest sensitivity given compressed payback periods on heat-to-power installations.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day extended payment terms have become standard for EPC contractors managing desalination project cash cycles. Superalloy feedstocks draw from concentrated supplier bases in Germany, Japan, and the United States. Nickel, cobalt, and advanced ceramic matrix composites constitute critical input dependencies. Single-source vulnerability for high-grade alloy procurement exposes lead times to geopolitical friction. Distribution runs through EPC contractor partnerships in water-stressed regions and direct OEM service arms in European automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from electrical system architectures should thermoelectric materials advance beyond current R&D-stage limitations, threatening the thermal-mechanical technology base that anchors current margin pools.
For Market Incumbents: Pre-empt electrical system substitution by accelerating R-stage thermoelectric partnerships before commercialization windows open. Secure captive supply of German and Japanese superalloy components to defend against third-party refurbishment network encroachment on aftermarket revenue. Backward integration into ceramic matrix composite fabrication anchors margin control as metal-alloy supply chains face feedstock pressure. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point given minimal incumbent service infrastructure and rising cooling load intensity. Vehicle waste heat recovery for heavy-duty trucking applications remains underpenetrated relative to passenger car deployments, with METI efficiency incentives accelerating Japanese OEM evaluation. Partner with EPC contractors in Saudi Arabian and Australian desalination corridors to bypass established OEM direct sales channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial process specialists holding pressure exchanger retrofit expertise in brownfield installations. Five-to-ten year viability hinges on regulatory enforcement durability across EU Ecodesign Directive and China's MEE dual carbon mandates. Watch for EPA Clean Air Act enforcement discretion tightening as the signal indicating accelerated capital redirection toward certified equipment procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Components | Captive supply of German and Japanese turbine blade materials reduces geopolitical lead time exposure. |
| AI-Driven Predictive Maintenance Platform | Sensor-embedded heat exchanger systems enable outcome-based service contracts displacing scheduled overhaul models. |
| Ceramic Matrix Composite Manufacturing Scale-Up | Advanced materials withstand 800°C+ differentials in Rotterdam and Duisburg cement and steel retrofit installations. |
| EPC Contractor Partnership Expansion | Desalination corridor development in Saudi Arabia and Australia anchors pressure exchanger demand through project finance structures. |
| District Heating Network Integration | Rotterdam, Eindhoven, and Gothenburg industrial clusters create anchor demand for centralized waste heat aggregation systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and EPC contractor project databases across the analysis window. Plant engineers, aftermarket service directors, and procurement leads at petrochemical complexes provided operational validation. EIA energy intensity data, EU Ecodesign Directive implementation reports, and China's MEE enforcement disclosures furnished secondary triangulation. Bottom-up equipment shipment tracking and top-down industrial energy consumption modeling converged on segment-level estimates.
Forecast inputs span technology type, application intensity, end-user category, and regional regulatory enforcement phase across the projection horizon. Organic Rankine cycle adoption curves, pressure exchanger deployment in desalination capacity builds, and heat exchanger replacement cycles under EU efficiency mandates shaped growth trajectories. CAGRs derive from regression against verified installation data and policy-mandated retrofit timelines.
Macroeconomic conditions sit as an overlay; deviation in industrial capex cycles, superalloy commodity prices, or carbon credit valuations would shift the trajectory. Forecasts embed assumptions regarding regulatory enforcement continuity and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Southeast Asia Waste-To-Energy Market
Waste to Energy Systems
United States Waste to Energy Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
Drilling Waste Management Services Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Brazil Waste to Energy Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Waste to Energy (WTE) Market