
 Big Rig Trucks Market | 2026-2036
Big Rig Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Big Rig Trucks Market Analytics
Multi-source procurement among fleet operators is broadening supplier engagement across the heavy-duty segment. Freightliner leverages captive manufacturing scale to dominate North American dealership networks. PACCAR sustains premium positioning through Kenworth and Peterbilt dual-brand architecture. Volvo Trucks competes on integrated powertrain and safety system bundling.
Big rig trucks denote Class 8 commercial vehicles exceeding 33,000 pounds gross vehicle weight rating, engineered with ladder-frame chassis, diesel or electric drivetrains, and sleeper or day cab configurations for freight hauling, construction, and resource extraction. Tractor trailers command the largest revenue pool due to interstate commerce dependency and fleet standardization. Electric engine types attract capital fastest as charging infrastructure deploys along freight corridors and total cost of ownership models shift. Heavy duty load capacity segments retain margin concentration given specialized axle, suspension, and braking requirements that limit supplier commoditization.
NHTSA governs Federal Motor Vehicle Safety Standards for braking, stability control, and underride protection, while EPA Phase 3 rules constrain CO2 emissions per ton-mile and force engine redesign cycles. The Department of Transportation's INVEST Act infrastructure funding indirectly stimulates construction-oriented dump truck and flatbed demand through highway and bridge project awards. Stakeholders must weigh powertrain portfolio bets against residual value uncertainty as regulatory compliance timelines compress and alternative fuel infrastructure remains geographically uneven.
Market Dynamics
EPA Phase 3 greenhouse gas standards are compressing engine redesign cycles while electric powertrain development absorbs disproportionate R&D capital, forcing fleet operators to place simultaneous bets on diesel efficiency and zero-emission alternatives.
Growth Catalysts
- Interstate freight volume expansion:Port-to-warehouse drayage and cross-country routes sustain replacement cycles for heavy-duty tractor trailers. Fleet standardization concentrates procurement in the United States.
- Charging infrastructure deployment:Capital allocation along freight corridors is accelerating total cost of ownership recalibration. Electric engine types attract capital fastest as corridor coverage expands.
- INVEST Act infrastructure funding:Highway and bridge project awards indirectly stimulate construction-oriented dump truck and flatbed demand through federal transportation spending.
Market Restraints
- Battery cell supply concentration:Cathode material processing and cell manufacturing cluster in specific Asian supply basins, creating geographic vulnerability for North American electric truck assembly.
- Residual value uncertainty:Regulatory compliance timelines compress faster than secondary market pricing mechanisms can adapt, distorting fleet financing models.
- Alternative fuel infrastructure gaps:Hydrogen and megawatt charging networks remain geographically uneven, limiting route flexibility for early zero-emission adopters.
Strategic Opportunities
- Integrated powertrain-safety bundling:Volvo Trucks and competitors are compressing procurement complexity by combining drivetrain and active safety systems into single-vendor contracts.
- Sleeper cab electrification:Auxiliary power unit replacement with battery-electric hotel loads opens margin expansion in long-haul segments previously resistant to full powertrain conversion.
- Construction sector fleet turnover:Federal infrastructure awards in the United States are accelerating replacement cycles for vocational trucks in dump and flatbed configurations.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments lack sufficient trained personnel for megawatt charging infrastructure and battery pack diagnostics.
- Dual powertrain inventory complexity:Dealerships must stock diesel and electric parts simultaneously, compressing working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Rig Trucks Market |
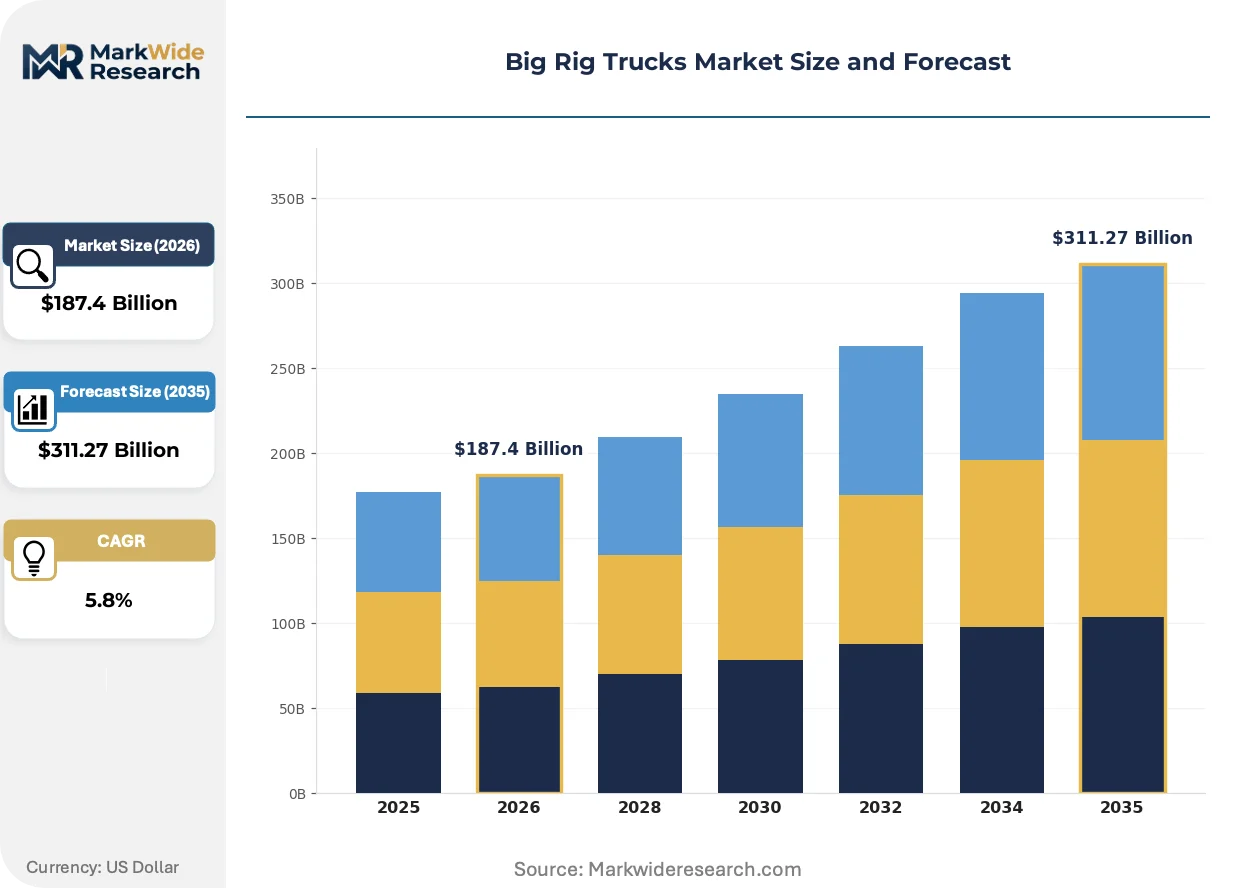
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Tractor Trailers, Dump Trucks, Flatbed Trucks, Tanker Trucks Engine Type: Diesel, Electric, Hybrid, Gasoline Load Capacity: Lightweight, Medium Duty, Heavy Duty, Super Duty End User: Logistics, Construction, Agriculture, Mining |
| Companies Covered | Freightliner, Peterbilt, Kenworth, International, Volvo Trucks, Mack Trucks, Western Star, PACCAR, Daimler Truck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Rig Trucks Market Evolving Landscape
Powertrain electrification is fragmenting traditional supplier relationships while EPA enforcement timelines compress product development cycles. Three forces currently reshape competitive positioning.
Battery-electric drivetrain architecture is decentralizing maintenance networks away from established engine rebuild corridors. Regional fleet operators in California and Texas are adopting electric tractors faster than national averages projected. This technology is decentralizing service revenue from centralized remanufacturing hubs toward distributed high-voltage technician pools.
NHTSA underride protection mandates are forcing chassis redesign investments across all sleeper and day cab configurations. Trailer rear-impact guard standards tighten crashworthiness requirements that cascade into tractor fifth-wheel height specifications. Vocational dump truck segments face the steepest compliance cost escalation due to variable bed configurations.
Fleet operators are consolidating vendor relationships to reduce procurement transaction costs across mixed diesel-electric portfolios. Large logistics buyers now demand unified telematics platforms spanning legacy and zero-emission assets. This consolidation concentrates most visibly among United States-based interstate carriers with standardized tractor specifications.
Big Rig Trucks Market Segmentation
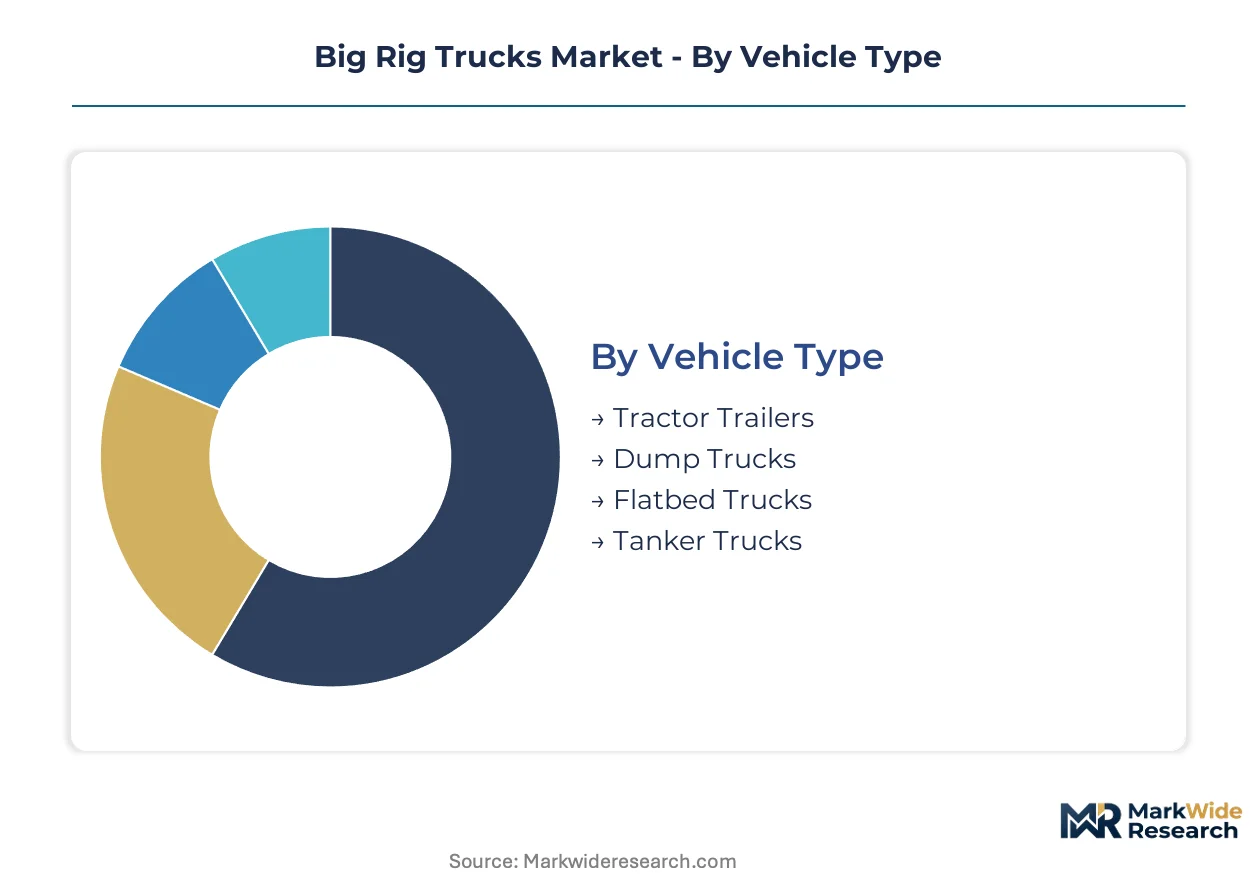
Big rig truck segmentation reveals how powertrain technology and duty cycle requirements fragment procurement patterns across fleet operators. Vehicle configuration choices cascade through financing terms, maintenance networks, and residual value calculations.
Vehicle Type:
Standalone long-haul platforms dominate revenue concentration, while embedded vocational configurations serve project-specific demand cycles.
- Tractor Trailers:Sleeper and day cab configurations engineered for interstate commerce with ladder-frame chassis and fifth-wheel coupling systems. Port-to-warehouse drayage in California and cross-country routes sustain replacement cycles as freight volumes climb along United States interstate corridors.
- Dump Trucks:Hydraulic lift mechanisms integrated with reinforced chassis for aggregate and construction material transport. Federal highway and bridge project awards through the Department of Transportation's INVEST Act accelerate fleet turnover in United States construction markets.
- Flatbed Trucks:Open-deck designs with stake-side or removable rail options for oversized freight and equipment hauling.
- Tanker Trucks:Cylindrical vessel integration for liquid and dry bulk commodities with specialized pumping and venting systems.
Tractor trailers lead volumes today; dump trucks are gaining share fastest through infrastructure stimulus deployment.
Engine Type:
Powertrain cost tiers stratify around total cost of ownership models, with premium electric configurations requiring capital reallocation against established diesel service networks.
- Diesel:Compression-ignition engines with aftertreatment systems for EPA Phase 3 compliance. Established remanufacturing corridors in Indiana and Tennessee sustain secondary market liquidity despite tightening emissions mandates.
- Electric:Battery-electric drivetrains with megawatt charging capability for depot and corridor refueling. California fleet operators adopt these tractors faster than national averages as charging infrastructure deploys along freight corridors.
- Hybrid:Dual powertrain architectures combining diesel range extension with electric torque supplementation.
- Gasoline:Spark-ignition engines limited to light vocational applications with lower duty cycle requirements.
Diesel retains the largest installed base; electric powertrains are climbing the fastest as corridor coverage expands.
Load Capacity:
Application intensity and axle configuration requirements determine margin distribution across weight class specifications.
- Heavy Duty:Exceeding 33,000 pounds GVWR with specialized axle, suspension, and braking systems for sustained interstate operation. These configurations retain margin concentration given engineering complexity that limits supplier commoditization.
- Super Duty:Extreme load ratings for mining and resource extraction with reinforced frames and multiple drive axles. Permian Basin operations in Texas and Wyoming coal fields sustain procurement for these specialized platforms.
- Medium Duty:Regional distribution and urban freight applications with simplified maintenance requirements.
- Lightweight:Last-mile and local delivery configurations with reduced fuel consumption profiles.
Heavy duty specifications dominate revenue today; super duty segments show steepest expansion trajectory through resource extraction investment.
End User:
Customer procurement maturity varies from standardized fleet replacement cycles to project-driven spot acquisition patterns.
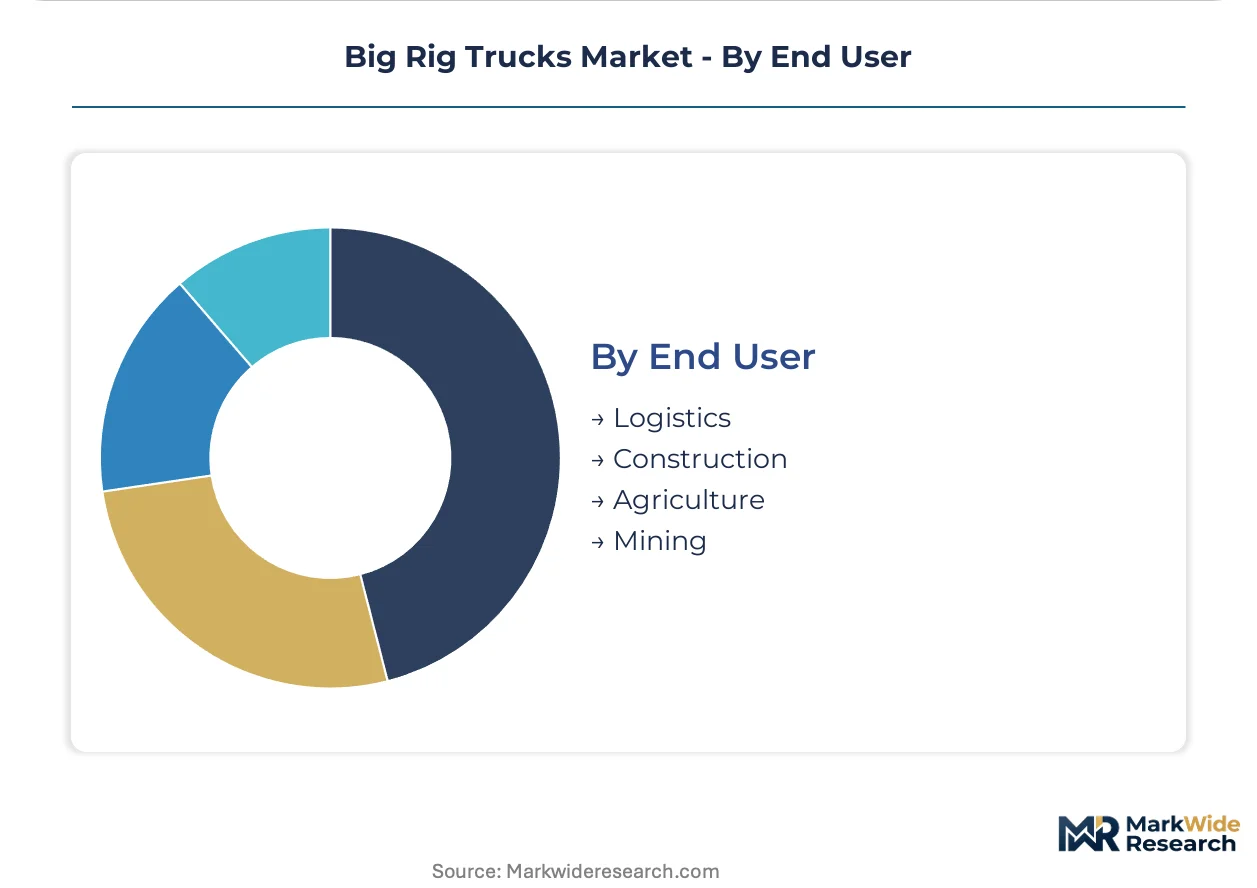
- Logistics:Asset-light and asset-heavy carriers with standardized tractor specifications for interstate commerce. Large United States-based carriers now demand unified telematics platforms spanning legacy and zero-emission assets.
- Construction:Project-dependent fleet operators with vocational truck requirements tied to federal infrastructure awards. Highway and bridge spending through the INVEST Act indirectly stimulates dump truck and flatbed demand.
- Agriculture:Seasonal grain transport and equipment hauling with variable duty cycle intensity.
- Mining:Resource extraction operations with extreme environment durability requirements and captive maintenance facilities.
Logistics commands the largest procurement volumes; construction end use is expanding most quickly through federal transportation spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes manufacturing corridor anchors North American heavy-duty truck assembly, with Detroit-to-Chicago industrial density supporting engine foundries, axle plants, and sleeper cab fabrication facilities that feed interstate logistics networks.
United States
Port-to-warehouse drayage in California and cross-country freight corridors sustain replacement cycles for Class 8 tractors. NHTSA underride protection mandates and EPA Phase 3 emissions standards force chassis redesign investments. Indiana and Tennessee host established engine remanufacturing corridors that sustain secondary market liquidity despite tightening regulatory compliance timelines.
Germany
Integrated powertrain engineering clusters in Munich and Stuttgart advance autonomous braking and electric drivetrain bundling for premium export markets. KBA type-approval processes enforce EU heavy-duty CO2 standards that accelerate zero-emission development cycles. The Baden-Württemberg automotive belt concentrates supplier networks for axle and suspension systems serving both domestic and North American OEM contracts.
China
Domestic freight volume expansion along Belt and Road corridors stimulates heavy-duty procurement for resource extraction and construction logistics. MIIT fuel consumption standards and dual carbon goals compress engine efficiency redesign timelines. Shandong Province manufacturing bases export chassis components and cab assemblies to Southeast Asian and African markets under competitive cost structures.
Japan
Precision manufacturing of transmission and braking systems supplies global heavy-duty OEMs through just-in-time delivery networks. METI carbon neutrality roadmaps redirect R&D capital toward hydrogen combustion and battery-electric architectures. The Nagoya-Chubu industrial zone specializes in high-torque axle differentials and automated manual transmissions for long-haul applications.
Canada
Cross-border trade density along the Windsor-Detroit corridor and prairie grain transport sustain Class 8 tractor demand tied to US freight networks. Transport Canada harmonizes vehicle safety standards with NHTSA regulations while enforcing distinct emissions compliance pathways. Ontario manufacturing plants assemble cabs and chassis for integrated North American supply chains serving Detroit Three OEM requirements.
Big Rig Trucks Market Competitive Landscape
Global majors compete with regional champions across powertrain technology and fleet service networks. The market structure concentrates around integrated OEMs with captive engine manufacturing and multi-brand dealership architectures. Three archetypes dominate: scale-driven volume producers with dense service coverage, premium-positioned dual-brand operators, and integrated safety-powertrain bundlers. Competitive moves center on electric powertrain R&D partnerships and telematics platform consolidation to reduce fleet procurement transaction costs.
Among North American volume manufacturers, Freightliner anchors the scale-driven tier with extensive dealership density across interstate corridors. PACCAR occupies the premium-positioned segment through its dual-brand Kenworth and Peterbilt architecture. Volvo Trucks exemplifies the integrated bundling approach, combining drivetrain and active safety systems into unified fleet contracts. These three structures represent the dominant competitive configurations reshaping supplier relationships and service revenue models.
| Leading Market Players |
|---|
| Freightliner |
| Peterbilt |
| Kenworth |
| International |
| Volvo Trucks |
| Mack Trucks |
| Western Star |
| PACCAR |
| Daimler Truck |
| Others |
Value Network & Pricing Analysis
Interstate logistics fleet operators with standardized procurement specifications command the dominant pricing leverage in heavy-duty tractor trailer markets, compressing margins through multi-source bidding while EPA Phase 3 compliance costs cascade into chassis and powertrain pricing tiers.
Pricing Analysis
Input-cost pass-through from battery cell materials and specialized axle components drives contract renegotiation cycles across diesel-electric mixed fleets. Three-tier pricing structure across premium integrated-safety bundles, standard drivetrain configurations, and economy day cab specifications reflects brand positioning and after-sales service attachment. Pricing pressure stems from fleet consolidation of vendor relationships and unified telematics demands. Asset-light regional carriers exhibit highest price sensitivity; mining and resource extraction operators with captive maintenance facilities show lowest.
Supply Chain Analysis
Reverse-logistics flows through Indiana and Tennessee engine remanufacturing corridors sustain secondary market liquidity for diesel powertrains while battery pack refurbishment networks remain geographically sparse. Manufacturing concentration centers on the Great Lakes corridor in the United States, Ontario in Canada, and Shandong Province in China for chassis and cab assemblies. Critical inputs include high-strength steel for ladder-frame construction, lithium-ion cells for electric drivetrains, and specialized braking system components. Single-source vulnerability in cathode material processing creates geographic exposure for North American electric truck assembly. Distribution runs through captive OEM dealership networks with parts depots positioned along interstate freight corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by logistics fleet migration toward integrated powertrain-safety bundles that command premium positioning despite higher upfront capital requirements.
For Market Incumbents: Extend service network coverage into high-voltage technician training and megawatt charging infrastructure deployment to capture maintenance revenue migrating from centralized engine rebuild hubs. Consolidate telematics platform offerings across diesel-electric mixed fleets to reduce procurement transaction costs for large United States-based carriers. Battery cell supply concentration in Asian processing basins presents substitution risk requiring dual-source qualification programs. For New Entrants and Emerging Players: Direct fleet procurement platforms offer the lowest friction entry path for electric powertrain specialists seeking bypass of established dealership networks. Sleeper cab electrification with battery-electric auxiliary power units represents the most penetrable white-space segment previously resistant to full powertrain conversion. Target California port-to-warehouse drayage operators with corridor charging infrastructure partnerships as anchor customer acquisition strategy. For Investors and Strategic Acquirers: Electric vehicle charging network operators are the most active acquirer in this space, seeking captive fleet demand to anchor infrastructure utilization. Long-term viability favors integrated powertrain-safety bundlers with established high-voltage service networks over pure-play drivetrain assemblers. Acquisition target archetype: regional electric truck assemblers with California Air Resources Board certification and corridor charging partnerships. Monitor EPA enforcement timeline acceleration and NHTSA underride protection mandate implementation as inflection indicators for chassis redesign investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Powertrain-Safety Bundling | Volvo Trucks and competitors compress procurement complexity into single-vendor contracts spanning drivetrain and active safety systems. |
| Megawatt Charging Infrastructure Partnership | Charging network operators anchor utilization through exclusive fleet service agreements along California and Texas freight corridors. |
| High-Voltage Technician Certification Programs | Fleet maintenance departments address scarcity through OEM-sponsored training pipelines at regional technical institutes. |
| Telematics Platform Consolidation | Large logistics buyers demand unified data layers spanning legacy diesel and zero-emission assets in mixed fleets. |
| Engine Remanufacturing Network Expansion | Indiana and Tennessee facilities sustain secondary market liquidity despite tightening EPA Phase 3 compliance timelines. |
Research Methodology
Multiple input streams — fleet procurement director interviews, OEM platform engineering consultations, and charging infrastructure operator surveys — were reconciled against vehicle production databases, EPA certification filings, and interstate freight volume statistics. Primary fieldwork engaged fleet maintenance supervisors, dealership parts managers, high-voltage technician training coordinators, and federal transportation grant administrators. Secondary validation drew from NHTSA safety standard dockets, Department of Transportation INVEST Act award disclosures, and state-level zero-emission vehicle registration data. Bottom-up unit economics and top-down freight demand models were cross-referenced for triangulation.
Historical production volumes were cross-referenced against panel input from procurement executives at asset-heavy carriers and asset-light logistics operators across the analysis window. Segmentation dimensions modeled include vehicle configuration, powertrain architecture, load capacity tier, and end-use application intensity. CAGRs were derived from freight demand elasticity, replacement cycle compression, and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs incorporated EPA Phase 3 implementation pacing and corridor charging infrastructure deployment schedules.
Battery cell supply disruption, EPA enforcement acceleration, and hydrogen infrastructure abandonment are the dominant revision risks that could compress electric powertrain adoption trajectories or extend diesel dominance. Forecasts reflect assumptions about charging network geographic coverage and fleet financing model adaptation to residual value uncertainty. Practitioners should monitor cathode material processing capacity expansion, NHTSA rulemaking dockets, and megawatt charging standard finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Heavy-Duty Truck Fleet Control Unit Architectures Market
Heavy-Duty Trucks
Digger Derrick Truck Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Malaysia Fire Truck Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market
Heavy-Duty Trucks
Fire Trucks Market