
 United States Refrigerated Trucking Market | 2026-2036
United States Refrigerated Trucking Market Size, Share, and Industry Trends Forecast 2026-2036
United States Refrigerated Trucking Market Analytics
Pharmaceutical cold chain logistics is realigning carrier priorities as biologics and vaccine distribution demand stricter temperature protocols. Knight-Swift Transportation Company leverages its national terminal network to sustain temperature integrity across long-haul lanes. J.B. Hunt anchors dedicated contract relationships with major food retailers, while C.H. Robinson Worldwide competes through digital freight-matching platforms that optimize refrigerated asset utilization.
Refrigerated trucking encompasses tractor-trailer combinations equipped with mechanical refrigeration units capable of maintaining cargo temperatures between minus 20 degrees Fahrenheit and 55 degrees Fahrenheit depending on product requirements. These vehicles transport perishable commodities through insulated van bodies with continuous temperature monitoring and data logging systems. The single temp segment dominates volume due to standardized frozen food distribution, though multi temp equipment captures premium pricing by enabling simultaneous transport of frozen and fresh goods in compartmentalized trailers. The food and beverage end user category occupies the largest share of payload capacity, while contract logistics services generate superior margin stability compared to volatile spot freight arrangements.
The Federal Motor Carrier Safety Administration enforces hours-of-service regulations that directly constrain refrigerated fleet utilization rates and driver availability. The Environmental Protection Agency's Phase 2 greenhouse gas standards compel refrigeration unit manufacturers to improve diesel-powered transport refrigeration unit efficiency and accelerate electric auxiliary power unit adoption. Fleet operators must monitor California Air Resources Board rulemaking, as the state's Advanced Clean Trucks regulation frequently precedes federal mandates and reshapes equipment procurement timelines nationwide.
Market Dynamics
Carrier economics hinge on California Air Resources Board rulemaking, where Advanced Clean Trucks mandates cascade eastward and compress equipment replacement cycles. Fleet operators face simultaneous pressure from EPA Phase 2 greenhouse gas standards and FDA Sanitary Transportation rules, forcing parallel compliance investments.
Growth Catalysts
- Biologics cold chain expansion:Temperature-sensitive pharmaceutical shipments now require continuous monitoring from manufacturing to final mile, pulling dedicated refrigerated capacity into healthcare distribution networks.
- FDA Sanitary Transportation rule:Mandated temperature logging and driver training protocols create barriers to entry that protect incumbent carriers with established compliance infrastructure.
- Midwest protein processing clusters:Iowa, Nebraska, and Kansas meatpacking corridors generate concentrated outbound refrigerated demand that supports dedicated lane economics.
Market Restraints
- Diesel transport refrigeration unit cost volatility:Fuel price swings compress margins on long-haul lanes where refrigeration units consume auxiliary diesel independent of tractor fuel.
- Driver availability constraints:Federal Motor Carrier Safety Administration hours-of-service regulations cap fleet utilization rates below dry van benchmarks.
- California regulatory preemption:CARB zero-emission mandates force premature equipment retirement in a state that anchors West Coast freight corridors.
Strategic Opportunities
- Electric auxiliary power unit adoption:Battery-electric refrigeration units at distribution centers enable overnight staging without diesel idling, qualifying operators for IRA clean vehicle tax credits.
- Multi-temperature trailer penetration:Compartmentalized equipment captures premium pricing from food retailers consolidating frozen and fresh procurement.
- Southeast pharmaceutical corridor:North Carolina and Georgia biomanufacturing clusters generate underpenetrated demand for validated cold chain services.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems require costly retrofitting to interface with real-time temperature monitoring platforms mandated by shipper contracts.
- Refrigeration technician scarcity:Specialized mechanical training for transport refrigeration unit maintenance outpaces vocational program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Refrigerated Trucking Market |
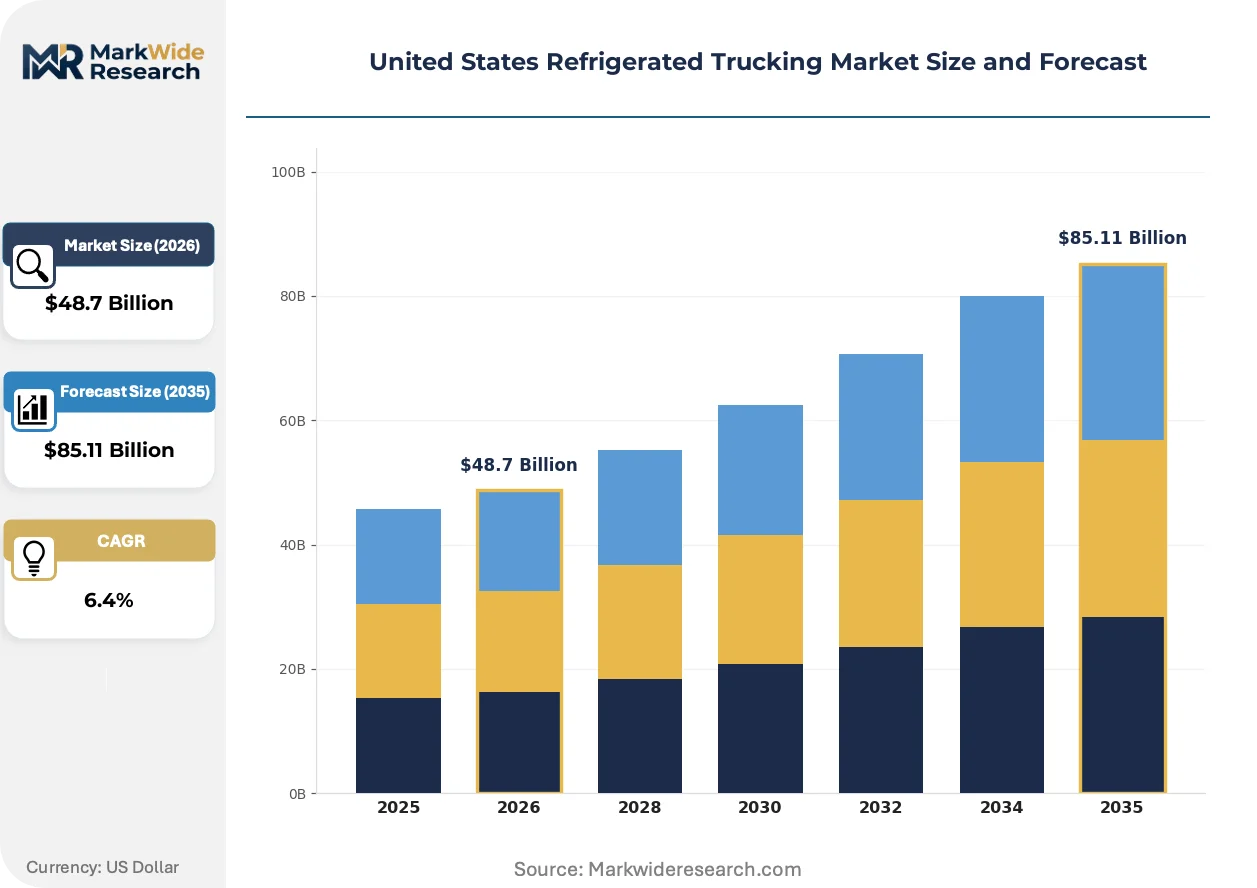
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Truck Type: Single Temp, Multi Temp, Constant Temp, Refrigerated Van Payload Capacity: Less than 5 Tons, 5-10 Tons, 10-15 Tons, Above 15 Tons End User: Food & Beverage, Pharmaceuticals, Agriculture, Healthcare Service Type: Dedicated Freight, Spot Freight, Contract Logistics, Temperature-Controlled |
| Companies Covered | Knight-Swift Transportation Company, J.B. Hunt, C.H. Robinson Worldwide, Prime Inc., C.R. England, Marten Transport, Covenant Logistics Group, ATS (Anderson Trucking Service), Ryder System, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Refrigerated Trucking Market Evolving Landscape
Digital freight platforms are compressing spot market opacity while sensor networks transform cargo visibility from a cost center into a competitive differentiator. Equipment electrification and autonomous temperature management now define carrier capability hierarchies.
Telematics-enabled cargo monitoring is consolidating control over temperature excursions across multi-stop routes. Food retailers and pharmaceutical distributors now mandate continuous data logging as a contract precondition. This capability compression is squeezing smaller operators lacking capital for sensor infrastructure and cloud-based analytics platforms.
EPA Phase 2 greenhouse gas standards are tightening transport refrigeration unit efficiency benchmarks and accelerating electric auxiliary power unit adoption. Manufacturers must redesign diesel-powered units or pivot to battery-electric architectures. Refrigerated fleets operating California lanes face the steepest compliance curves as CARB rules typically precede federal implementation by two to four years.
Shippers are unbundling temperature validation from transportation contracts and awarding certification work to specialized third-party logistics providers. Pharmaceutical manufacturers now separate lane qualification from freight procurement, creating dual-vendor structures. This disintermediation is most advanced in the Northeast corridor connecting New Jersey distribution hubs to Boston and Philadelphia metro areas.
United States Refrigerated Trucking Market Segmentation
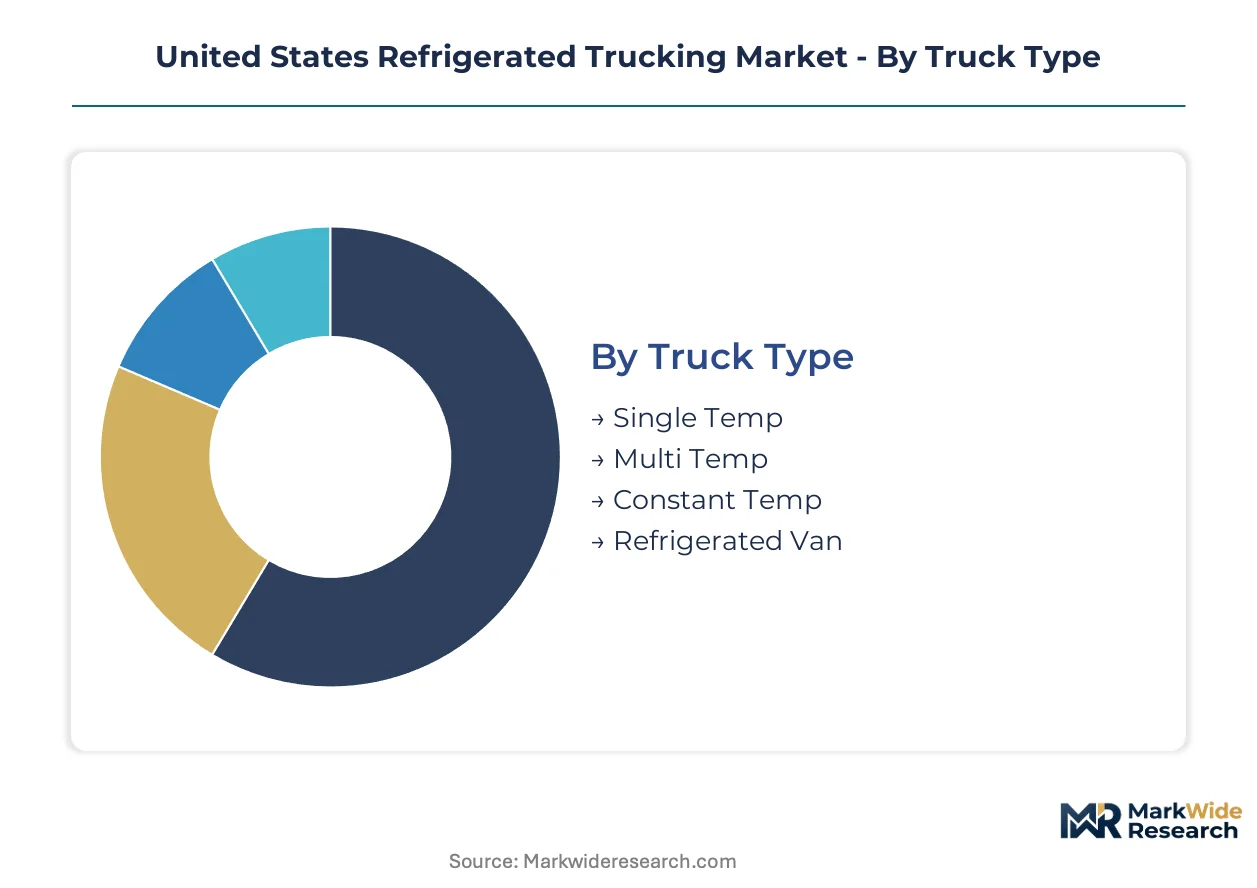
Refrigerated trucking segmentation reveals how equipment specialization and service models align with cargo sensitivity and shipper procurement patterns. Carrier fleet composition and contract structures vary sharply across these dimensions, creating distinct competitive arenas.
Truck Type:
Volume concentration favors standardized single-temperature units, while premium capture concentrates in compartmentalized equipment serving consolidated procurement.
- Single Temp:Maintains uniform temperature throughout the cargo area via integrated mechanical refrigeration units. Midwest meatpacking corridors in Iowa and Nebraska generate concentrated demand for frozen protein distribution, where standardized protocols minimize per-mile operating complexity.
- Multi Temp:Compartmentalized trailers with independent climate zones enable simultaneous transport of frozen and fresh goods. Food retailers operating Southeast distribution networks from North Carolina and Georgia procurement hubs drive adoption, as consolidated loads reduce empty backhaul miles.
- Constant Temp:Precision-controlled environments maintain narrower temperature bands for high-sensitivity cargo. Pharmaceutical distributors in the Northeast corridor between New Jersey and Boston mandate validated constant temperature protocols for biologics shipments.
- Refrigerated Van:Smaller-capacity urban delivery vehicles with direct-drive refrigeration systems. Final-mile grocery delivery networks in dense metropolitan areas deploy these units for store replenishment and direct-to-consumer cold chain completion.
Mature deployment sits with Single Temp. Newer deployment is concentrated in Multi Temp.
Payload Capacity:
Mid-range tonnage categories anchor food retail distribution, while extreme capacity brackets serve distinct procurement patterns in protein processing and pharmaceutical consolidation.
- 5-10 Tons:Versatile capacity bracket dominating regional grocery distribution and foodservice supply chains. California Central Valley agricultural shippers deploy these units for produce consolidation before long-haul handoff to larger equipment.
- 10-15 Tons:Heavy-duty configurations serving meatpacking plant output and dairy processing volumes. Nebraska and Kansas protein processing clusters generate dedicated lane demand requiring this capacity tier for full-load economics.
- Less than 5 Tons:Light-duty urban delivery platforms for pharmaceutical samples and specialty food distribution. Metropolitan hospital networks and independent grocers in Northeast corridor cities utilize this segment for high-frequency, low-volume replenishment.
- Above 15 Tons:Maximum-capacity units for bulk frozen commodity movement and export container drayage. West Coast port complexes handling refrigerated container transfers to inland distribution centers deploy this equipment for density optimization.
Established fleet composition centers on 5-10 Tons. Capacity expansion is accelerating fastest in 10-15 Tons.
End User:
Food sector procurement generates baseline volume, while healthcare and pharmaceutical segments command premium rate structures through compliance requirements.
- Food & Beverage:Dominant demand source spanning frozen packaged goods, fresh produce, dairy, and protein categories. FDA Sanitary Transportation rule compliance investments create carrier selection criteria favoring established temperature logging infrastructure.
- Pharmaceuticals:Temperature-validated distribution of vaccines, biologics, and temperature-sensitive therapeutics. Continuous monitoring requirements from manufacturing through final mile pull dedicated refrigerated capacity into healthcare networks.
- Agriculture:Seasonal harvest movements and nursery stock transport requiring controlled atmosphere capabilities. California produce shippers and Florida citrus exporters drive peak seasonal demand concentration.
- Healthcare:Hospital supply chains, blood product distribution, and clinical specimen transport. Metropolitan medical center clusters in Boston, Philadelphia, and Chicago generate recurring lane requirements with strict chain-of-custody documentation.
Contract maturity is deepest in Food & Beverage. Validation complexity is expanding most quickly in Pharmaceuticals.
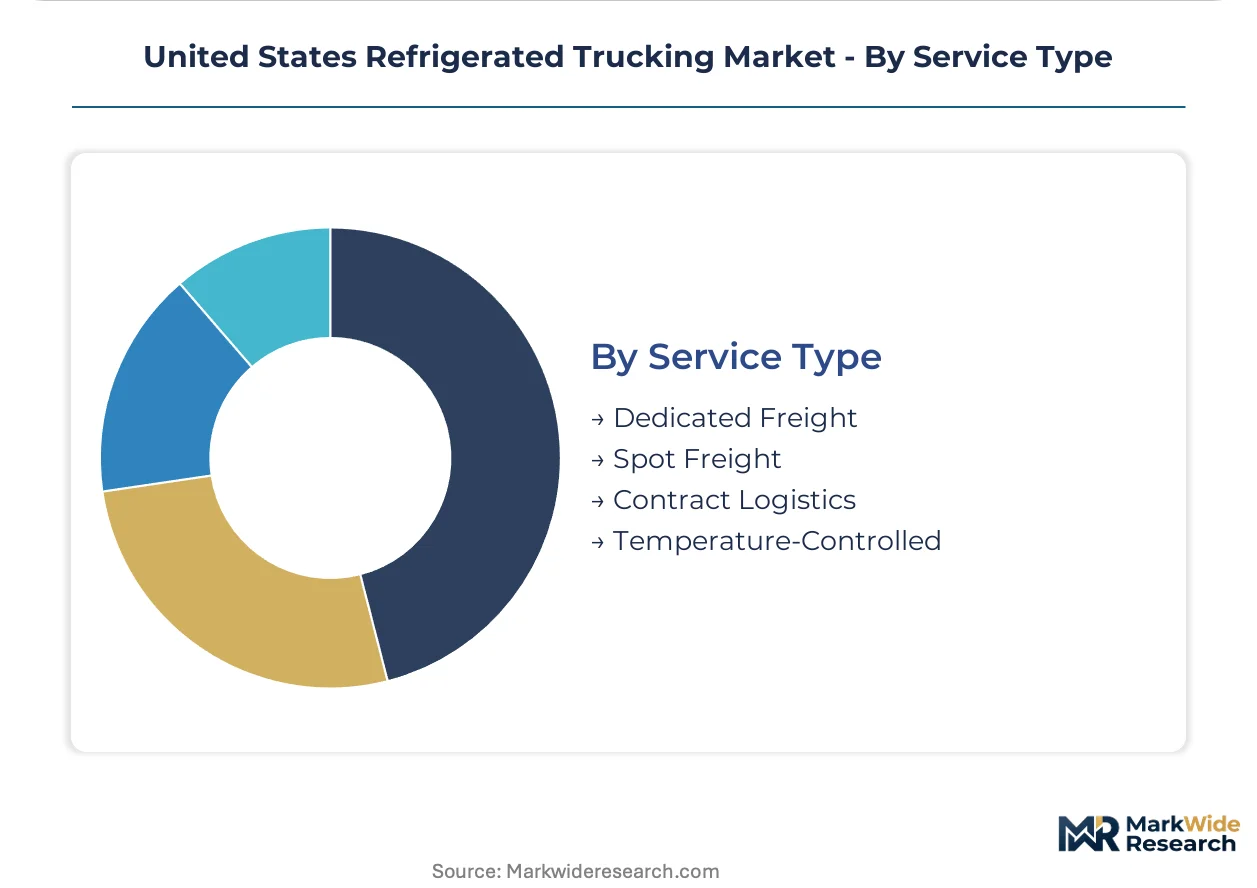
Service Type:
Procurement structure determines margin stability, with dedicated arrangements insulating carriers from spot market volatility.
- Contract Logistics:Multi-year agreements with guaranteed volume commitments and integrated warehousing services. National food retailers anchor these relationships, providing fleet utilization predictability that supports equipment financing.
- Dedicated Freight:Exclusive capacity allocation for single shipper networks with dedicated tractor-trailer assignments. Midwest protein processors maintain dedicated fleets for plant-to-distribution center movements.
- Temperature-Controlled:Service tier emphasizing validated cold chain integrity with continuous monitoring documentation. Pharmaceutical manufacturers require this specification for regulatory compliance across distribution networks.
- Spot Freight:Transactional procurement through digital freight platforms for surge capacity and backhaul optimization. Agricultural harvest peaks and seasonal produce movements generate spot demand concentration.
Revenue stability concentrates in Contract Logistics. Platform-mediated volume is climbing fastest in Spot Freight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and federal tax incentives are concentrating refrigerated fleet investment in designated distressed census tracts near major distribution corridors. These geographic preferences reshape carrier terminal placement and cold storage co-location strategies.
California
Central Valley produce shippers generate seasonal surge demand requiring flexible refrigerated capacity. The California Air Resources Board enforces Advanced Clean Trucks mandates that accelerate zero-emission refrigeration unit adoption ahead of federal timelines. Los Angeles-Long Beach port complexes anchor West Coast import cold chains handling temperature-sensitive Asian food products.
Texas
Cross-border trade with Mexico drives dedicated refrigerated lanes for fresh produce and protein shipments. The Texas Department of Transportation prioritizes freight corridor investments along Interstate 35 connecting Laredo to Dallas-Fort Worth distribution hubs. Houston's petrochemical complex supports cold storage infrastructure for pharmaceutical manufacturing inputs.
Midwest Agricultural Corridor
Iowa, Nebraska, and Kansas meatpacking clusters generate concentrated outbound refrigerated demand with dedicated contract economics. The FDA's Sanitary Transportation rule compliance investments favor established carriers with temperature logging infrastructure. Chicago anchors regional distribution with intermodal cold chain handoffs between rail and truck.
Southeast
North Carolina and Georgia biomanufacturing clusters generate underpenetrated demand for validated pharmaceutical cold chain services. The Inflation Reduction Act clean vehicle tax credits accelerate electric auxiliary power unit adoption at Atlanta and Charlotte distribution centers. Florida's citrus export season creates predictable spot freight peaks.
Northeast Corridor
New Jersey distribution hubs connect to Boston and Philadelphia metro areas through pharmaceutical-validated lanes. The FDA mandates continuous temperature monitoring for biologics shipments originating from New Jersey manufacturing sites. New York City's final-mile grocery delivery networks deploy refrigerated vans for store replenishment.
United States Refrigerated Trucking Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with asset-heavy carriers commanding dedicated freight relationships while brokers capture spot market volatility. The vendor base organizes around three archetypes: national integrated carriers with terminal networks, regional dedicated specialists, and digital freight platforms. Consolidation pressure favors scale players with compliance infrastructure investments. M&A activity targets regional refrigerated fleets with established food retail contracts.
Among national integrated carriers, Knight-Swift Transportation Company anchors temperature integrity across long-haul lanes through terminal network density. J.B. Hunt occupies a position within dedicated contract logistics, securing multi-year agreements with major food retailers. C.H. Robinson Worldwide exemplifies the digital freight-matching archetype, optimizing refrigerated asset utilization through platform-mediated procurement.
| Leading Market Players |
|---|
| Knight-Swift Transportation Company |
| J.B. Hunt |
| C.H. Robinson Worldwide |
| Prime Inc. |
| C.R. England |
| Marten Transport |
| Covenant Logistics Group |
| ATS (Anderson Trucking Service) |
| Ryder System |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between pharmaceutical-validated lanes and commodity food corridors manifests in both rate premiums and equipment procurement patterns. FDA Sanitary Transportation rule compliance creates a pricing ladder where constant-temperature biologics shipments command substantial premiums over single-temp frozen protein moves, while carriers with established temperature logging infrastructure capture dedicated contract economics that smaller operators cannot match.
Pricing Analysis
Expedited lead-time premiums dominate pharmaceutical corridors where biologics manufacturers pay substantial rate differentials for validated cold chain capacity with sub-24-hour positioning. Three-tier pricing structure across premium, standard, and economy levels reflects equipment sophistication and compliance infrastructure depth. Pricing pressure stems from diesel transport refrigeration unit fuel volatility compressing margins on long-haul lanes. Food retailers exhibit highest price sensitivity through consolidated procurement tenders, while pharmaceutical distributors prioritize temperature integrity over rate minimization.
Supply Chain Analysis
Dual-sourcing mandates from major food retailers and pharmaceutical distributors require carriers to maintain redundant equipment pools and backup driver networks across key corridors. Manufacturing concentration for transport refrigeration units centers on the United States, Germany, and Japan, with diesel engine and compressor assemblies drawing from these production hubs. Specialized aluminum alloys for insulated van bodies and refrigerant chemicals represent critical input dependencies. Single-source vulnerability exists in electric auxiliary power unit battery supply chains. Distribution runs through terminal networks anchored at major protein processing clusters and pharmaceutical manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States refrigerated trucking market sits in a technology-transition phase as battery-electric refrigeration units displace diesel-powered transport refrigeration unit architectures. This equipment replacement cycle creates divergent winners based on capital access and compliance infrastructure depth.
For Market Incumbents: Deepen terminal network density in the Midwest agricultural corridor to defend dedicated contract relationships against digital freight platform encroachment. Invest in electric auxiliary power unit retrofitting at California distribution centers to capture IRA clean vehicle tax credits ahead of CARB zero-emission mandates. Vertical integration into temperature monitoring software protects margin position as shippers unbundle validation from transportation contracts.
For New Entrants and Emerging Players: Begin with Southeast pharmaceutical corridor penetration targeting North Carolina and Georgia biomanufacturing clusters where validated cold chain services remain underpenetrated. Multi-temperature trailer specialization offers a defensible entry point against established single-temp fleets. Direct sales to regional food retailers bypasses national contract logistics incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-size regional fleets with established FDA Sanitary Transportation compliance infrastructure given consolidation pressure from scale players. Long-term viability favors asset-heavy operators with dedicated contract economics over spot-market-dependent brokers. Monitor CARB rulemaking acceleration as the inflection signal for equipment replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Auxiliary Power Unit Adoption | Qualifies operators for IRA clean vehicle tax credits while eliminating diesel idling at distribution centers. |
| Multi-Temperature Trailer Fleet Expansion | Captures premium pricing from food retailers consolidating frozen and fresh procurement loads. |
| Telematics Platform Integration | Meets pharmaceutical shipper mandates for continuous temperature logging and excursion alerts. |
| Terminal Network Densification | Sustains temperature integrity across long-haul lanes through strategic Midwest and Southeast placement. |
| Driver Training Certification Programs | Creates FDA Sanitary Transportation rule compliance barriers that protect incumbent market position. |
Research Methodology
Document review covered refrigerated carrier SEC filings, FMCSA enforcement data, and CARB regulatory dockets, complemented by interviews with fleet operations directors, shipper procurement managers, and transport refrigeration unit manufacturers. Primary fieldwork included discussions with food retail distribution executives and pharmaceutical logistics specialists. Secondary validation drew from EPA Phase 2 greenhouse gas standard technical documentation, FDA Sanitary Transportation rule guidance, and refrigerated equipment trade association publications. Bottom-up carrier capacity modeling and top-down freight demand estimation were triangulated against customs trade flow data.
Cross-referencing historical fleet deployment patterns against industry panel input informed the analytical framework across the projection horizon. Segmentation dimensions modeled include truck type specialization, payload capacity tier, end-use industry vertical, and service procurement structure. CAGRs were derived through equipment replacement cycle analysis and freight demand elasticity estimation. Forecast inputs incorporated CARB regulatory preemption timelines and pharmaceutical cold chain expansion trajectories.
Underlying measurement precision varies by segment; pharmaceutical and contract logistics categories carry tighter precision than spot freight and agricultural movements. Forecasts reflect assumptions regarding regulatory implementation schedules and equipment cost curves. Deviation in EPA Phase 3 greenhouse gas standard timing or diesel price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Saudi Arabia Refrigerated Truck Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Truck Headache Rack Market