
 Bucket Trucks Market | 2026-2036
Bucket Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Bucket Trucks Market Analysis
Telematics-enabled fleet management is decoupling hardware sales from recurring service revenue in the bucket truck sector. Altec Industries leverages vertical integration across boom fabrication and chassis modification to sustain margin control. Versalift competes through specialized insulated designs for live-line electrical work.
Bucket trucks are hydraulically operated aerial work platforms mounted on commercial chassis, typically offering working heights from 30 to 200 feet with payload capacities exceeding 1,000 pounds for personnel and equipment. Their primary purpose spans electrical utility maintenance, telecommunications infrastructure installation, and vegetation management. Insulated configurations command premium positioning due to live-line work requirements, while electric fuel types represent the fastest-expanding segment as fleet operators phase out diesel procurement. Telescopic booms occupy mature demand pools in standard utility applications, whereas articulating designs capture margin concentration in complex-access construction and emergency response scenarios.
OSHA standards govern fall protection and boom stability testing, while EPA regulations drive powertrain emissions compliance across diesel and gasoline variants. The Federal Aviation Administration coordinates with utility operators near airport approach zones, restricting boom heights and operational windows. Fleet managers must monitor electrification readiness against charging infrastructure gaps and evolving battery weight trade-offs that alter chassis load distributions.
Market Dynamics
Telematics integration is decoupling hardware revenue from recurring service streams, compelling manufacturers to restructure pricing around uptime guarantees rather than unit sales alone.
Growth Catalysts
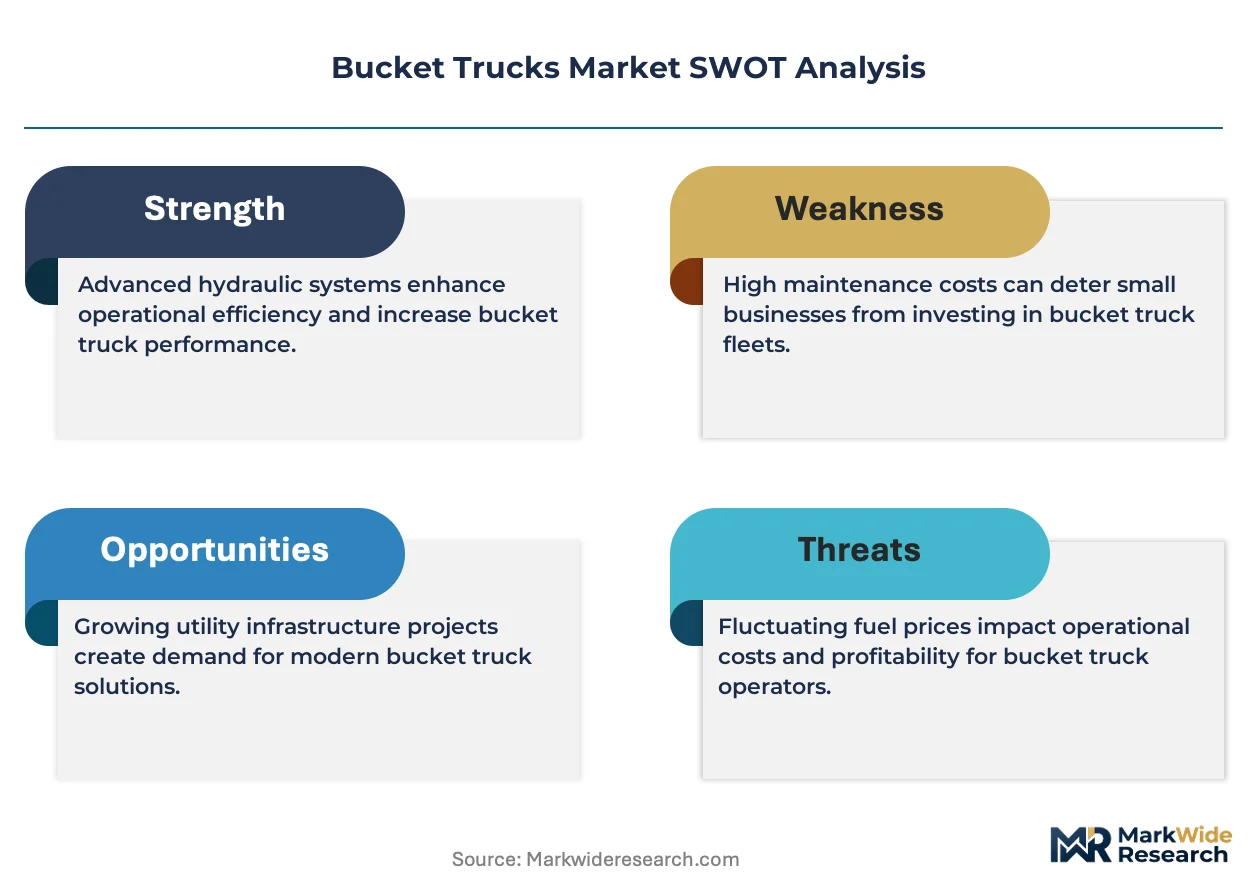
- Storm-response infrastructure mandates:Southeastern US states are accelerating fleet procurement for vegetation management and emergency restoration, creating sustained order pipelines for insulated aerial platforms.
- OSHA boom safety certification tightening:Enhanced fall protection and stability testing requirements are forcing fleet replacement cycles, particularly among municipal electric cooperatives operating aging equipment.
- Live-line electrical work expansion:Insulated boom configurations are capturing premium positioning as utilities minimize service interruptions through energized maintenance protocols.
Market Restraints
- Steel and aluminum input volatility:Chassis fabrication and boom construction face margin compression from commodity price swings, particularly affecting smaller regional body builders lacking forward contracts.
- Specialized hydraulic component concentration:Precision valve and cylinder manufacturing clusters in Germany and Japan, creating lead time vulnerability for North American assemblers.
- Battery weight trade-offs:Electric powertrain adoption stalls where battery mass exceeds chassis payload ratings, limiting deployment in high-reach configurations above 150 feet.
Strategic Opportunities
- India transmission grid modernization:State electricity boards are expanding aerial fleet procurement under central government rural electrification programs, opening import channels for insulated platform suppliers.
- Telecommunications 5G small cell deployment:Fiber optic and antenna installation is generating demand for compact articulating booms in urban right-of-way constraints.
- EPA emissions compliance retrofit incentives:Diesel engine repower programs are creating aftermarket revenue streams for engine integration specialists serving legacy fleet operators.
Industry Challenges
- Certified aerial equipment technician scarcity:Hydraulic system diagnostics and insulated boom testing require specialized training pipelines that vocational programs have not scaled to match fleet expansion rates.
- Telematics-legacy fleet integration complexity:Retrofitting connectivity modules onto pre-2015 chassis involves proprietary CAN bus protocols that fragment software standardization efforts across OEM silos.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bucket Trucks Market |
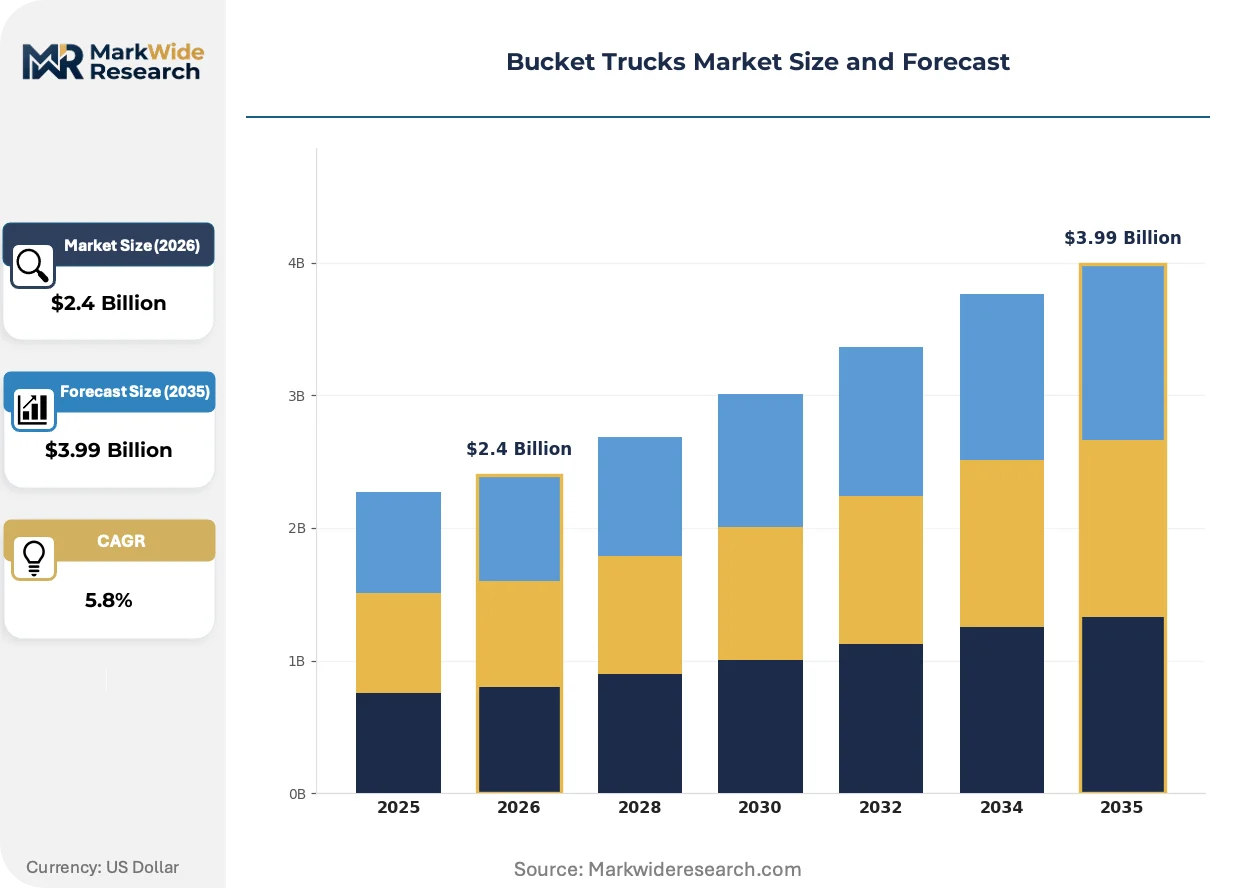
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
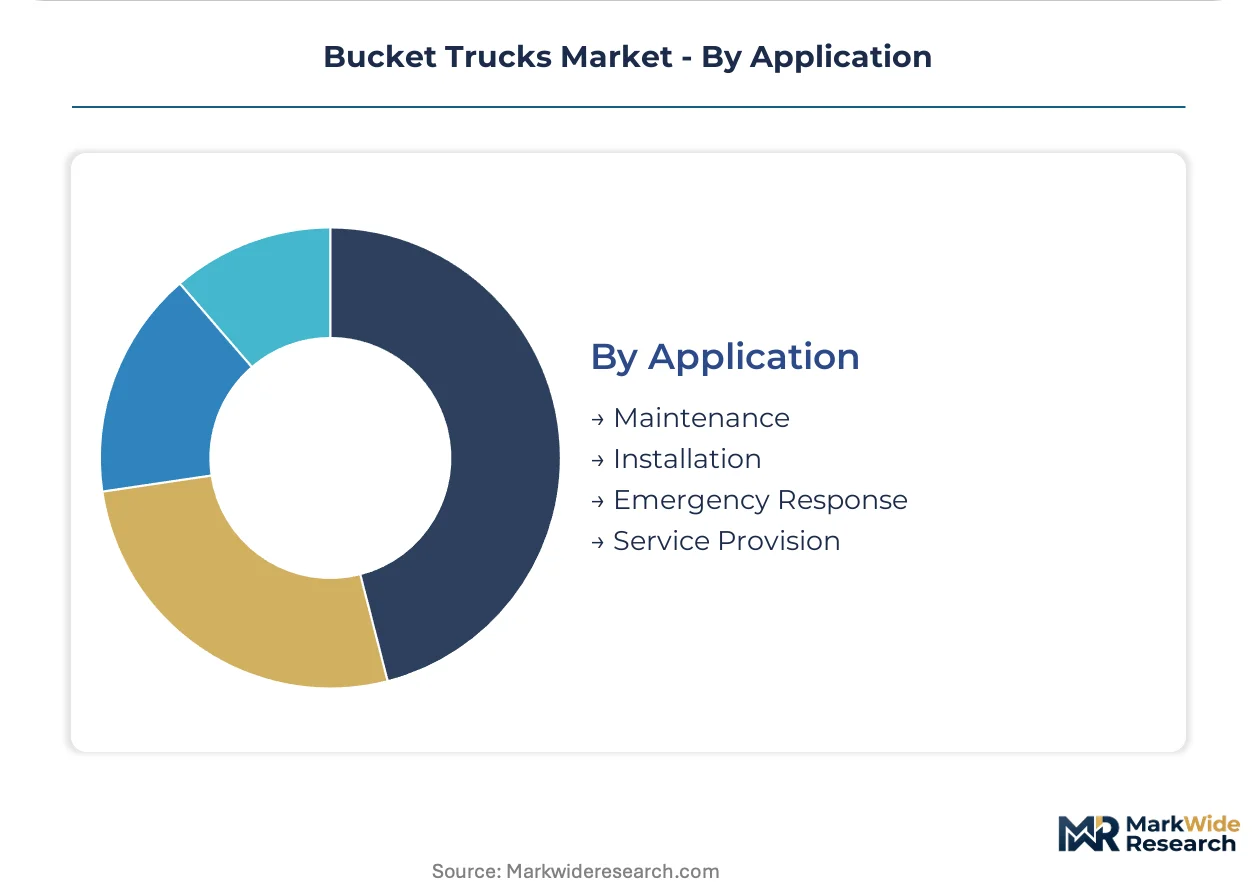
| Segmentation | Product Type: Articulating, Telescopic, Insulated, Non-insulated End User: Utilities, Construction, Telecommunications, Tree Care Fuel Type: Diesel, Electric, Hybrid, Gasoline Application: Maintenance, Installation, Emergency Response, Service Provision |
| Companies Covered | Altec Industries, Terex Corporation, Versalift, Palfinger AG, Aichi Corporation, Elliott Equipment Company, Tadano Ltd., CTE Group SPA, Dur-A-Lift, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bucket Trucks Market Emerging Trajectories
Electrification, connectivity, and modular platform design are converging to transform how fleet operators specify, deploy, and monetize aerial work equipment across utility and contractor segments.
Lithium-ion battery systems with integrated thermal management are decentralizing fleet energy infrastructure by enabling depot-based charging without utility transformer upgrades. Municipal operators in California and New York are piloting these configurations to bypass diesel procurement restrictions. The technology is decentralizing maintenance scheduling by allowing overnight charging that eliminates mid-shift refueling downtime.
EPA Tier 4 Final and upcoming Tier 5 standards are compressing diesel engine supplier consolidation, with remaining certified powertrain providers commanding premium positioning for non-electric configurations. Equipment purchasers in Texas and Florida are accelerating order timing to lock in pre-standard pricing. Insulated boom fabricators face recertification costs that favor vertically integrated chassis-boom assemblers over independent body builders.
Subscription-based uptime contracts are displacing traditional equipment ownership models among mid-sized vegetation management contractors. Fleet management companies are capturing maintenance and telematics bundling revenue that manufacturers previously retained. The shift is most visible in the southeastern United States where storm-response reliability requirements make downtime penalties commercially viable.
Bucket Trucks Market Segmentation
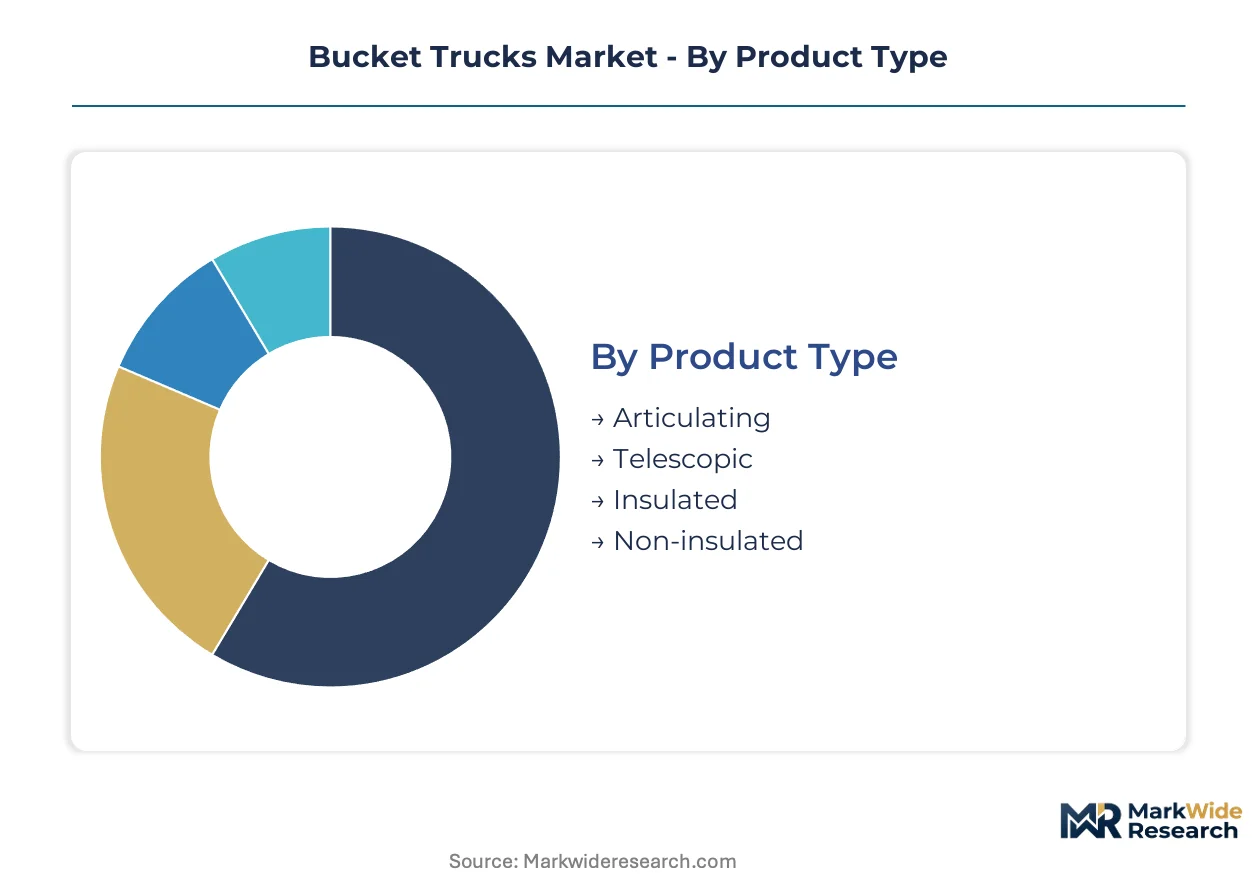
Bucket truck procurement patterns diverge sharply across technical specifications and operational contexts. Fleet managers weight boom configuration against fuel infrastructure, while regulatory pressure reshapes category priorities.
Product Type:
Buyers in this category prioritize reach complexity against capital outlay and maintenance burden.
- Articulating:Knuckle-boom designs with multiple pivot points enable positioning around obstacles like building facades and dense tree canopies. Demand concentrates among urban vegetation management contractors in Atlanta and Houston where right-of-way constraints limit straight-line access.
- Telescopic:Straight-boom configurations extend vertically through nested hydraulic cylinders, offering simpler maintenance and lower acquisition cost. Utilities in Florida and Georgia standardize on these for routine distribution line work where unobstructed vertical reach dominates operational requirements.
- Insulated:Dielectric boom materials enable energized line work without service interruption, commanding premium positioning from electric cooperatives facing live-line maintenance mandates.
- Non-insulated:Standard steel or aluminum booms serve de-energized applications and general construction, capturing volume in price-sensitive municipal fleets.
Volume sits with Telescopic configurations; growth tilts toward Articulating designs in constrained urban corridors.
End User:
Operational intensity and uptime requirements separate procurement behavior across customer types.
- Utilities:Investor-owned and municipal electric operators run the highest utilization rates, often exceeding 2,000 annual hours per unit. Southeastern cooperatives are replacing aging fleets ahead of OSHA recertification deadlines.
- Construction:General contractors and specialty trades demand flexible rental arrangements rather than ownership, favoring mid-reach articulating units for commercial building envelope work.
- Telecommunications:5G fiber and small cell deployment is accelerating orders for compact booms under 50 feet, particularly among contractors serving Verizon and AT&T infrastructure programs in Texas and California.
- Tree Care:Independent arborists and municipal forestry departments prioritize chipper-truck compatibility and ground-level controls for single-operator efficiency.
Utilities dominate absolute unit demand; telecommunications infrastructure spending is climbing fastest among end-user categories.
Fuel Type:
Payload capacity constraints and charging infrastructure availability fragment fleet electrification timelines.
- Electric:Battery-electric powertrains eliminate tailpipe emissions and reduce noise complaints in residential zones. California municipal operators are piloting these for sub-100-foot configurations where battery weight preserves chassis ratings.
- Diesel:Compression-ignition engines retain dominance in high-reach applications above 150 feet where battery mass would exceed gross vehicle weight limits. Texas and Florida utilities are accelerating pre-Tier 5 procurement.
- Hybrid:Diesel-electric architectures allow engine-off boom operation, cutting fuel consumption and emissions during stationary work. These are gaining traction among California contractors facing CARB fleet rules.
- Gasoline:Spark-ignition variants serve light-duty applications under 50 feet, primarily in residential tree care and small telecommunications contractors.
Diesel retains volume leadership; electric configurations are expanding most quickly in states with zero-emission fleet mandates.
Application:
Revenue model stability and crew specialization requirements shape equipment specification.
- Maintenance:Scheduled inspection and repair of existing infrastructure generates predictable utilization and favors standardized fleet configurations. Electric utilities in the Carolinas and Georgia run dedicated maintenance divisions with uniform boom specifications.
- Installation:New infrastructure deployment demands flexible reach capabilities for varying site conditions. Telecommunications contractors serving 5G rollout programs require rapid deployment across dispersed locations.
- Emergency Response:Storm restoration crews prioritize reliability and parts commonality over feature sophistication. Southeastern mutual aid agreements standardize on specific boom configurations to enable interoperability.
- Service Provision:Rental and contracted aerial services monetize equipment through hourly or daily rates, favoring versatile units that span multiple end-user requirements.
Maintenance commands the installed base; emergency response procurement is gaining share fastest as climate resilience spending accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in the United States and Germany, while demand clusters in storm-prone regions and emerging electrification markets. Consumption patterns diverge sharply between mature replacement cycles and first-time fleet procurement.
United States
Southeastern utilities in Florida and Georgia are accelerating fleet replacement ahead of OSHA recertification deadlines for aging insulated booms. EPA Tier 4 Final and upcoming Tier 5 standards are compressing diesel engine procurement timelines in Texas. The Atlanta-Houston corridor anchors vegetation management contractor demand for articulating configurations in constrained urban right-of-ways.
Germany
Precision hydraulic component manufacturing clusters around Stuttgart and Munich, supplying valve and cylinder systems to North American assemblers. REACH chemical regulations and EU Green Deal decarbonization targets are pressuring chassis powertrain electrification timelines. Bavarian fabricators face margin compression from steel input volatility and extended lead times for specialized subsystems.
India
State electricity boards under the central government's rural electrification programs are expanding aerial fleet procurement for transmission grid modernization. Central Electricity Authority safety mandates are tightening insulated platform certification requirements for live-line work. Maharashtra and Gujarat host emerging assembly partnerships between domestic chassis modifiers and international boom technology licensors.
Japan
Specialized hydraulic component production concentrates in Nagoya and Osaka industrial zones, creating supply vulnerability for North American bucket truck assemblers. METI carbon neutrality roadmaps are accelerating electric powertrain pilot programs in municipal utility fleets. Japanese manufacturers occupy premium positioning in high-reach telescopic configurations for export markets.
China
Domestic utility fleet expansion and Belt and Road infrastructure exports are driving chassis modification demand in the Yangtze River Delta. GB standards for aerial work platform safety are converging with ISO specifications, easing export certification for indigenous manufacturers. Shandong Province hosts volume production of non-insulated configurations for construction and telecommunications applications.
Bucket Trucks Market Vendor Landscape
Capital-heavy chassis modifiers compete with asset-light boom technology licensors across distinct margin tiers. The vendor base separates between vertically integrated assemblers controlling boom fabrication through final delivery, and regional body builders sourcing hydraulic subsystems from specialized component suppliers. Three archetypes dominate: integrated chassis-boom manufacturers, independent aerial platform specialists, and rental fleet operators capturing recurring service revenue. Competitive moves center on telematics-enabled uptime guarantees and backward integration into hydraulic component supply.
Within the integrated manufacturer tier, Altec Industries and Versalift exemplify vertical control over boom fabrication and chassis modification. Terex Corporation occupies a position spanning multiple aerial work equipment categories. Palfinger AG anchors European hydraulic lifting technology application. These archetypes represent alternative paths to margin defense against commodity input volatility and service revenue capture.
| Leading Market Players |
|---|
| Altec Industries |
| Terex Corporation |
| Versalift |
| Palfinger AG |
| Aichi Corporation |
| Elliott Equipment Company |
| Tadano Ltd. |
| CTE Group SPA |
| Dur-A-Lift |
| Others |
Supply Flow & Price Mechanics
OSHA recertification deadlines for aging insulated booms are compressing replacement timelines and forcing fleet managers toward pre-certified configurations, compelling suppliers to absorb dielectric testing costs upfront and compressing margins on non-integrated body builders.
Pricing Analysis
Margin tightening in standard non-insulated configurations traces to municipal procurement consolidation and volume-based contracting. Three-tier pricing structure across premium insulated, standard telescopic, and economy non-insulated levels dominates fleet transactions. Price differentiation hinges on dielectric certification grade and after-sales service bundling. Cost compression accelerates in the economy tier as regional body builders compete on chassis acquisition cost. Utilities show lowest price sensitivity due to uptime penalty clauses; independent arborists exhibit highest sensitivity with rental preference over ownership.
Supply Chain Analysis
Direct-to-OEM channels handle fleet-scale utility demand while independent distributors serve contractor spot purchases. Manufacturing gravity centers on the United States, Germany, and Japan for precision hydraulic components. Boom fabrication draws from specialized steel and aluminum alloys, dielectric composite materials, and precision valve systems. Single-source vulnerability concentrates in German and Japanese hydraulic subsystem suppliers. Distribution runs through manufacturer-direct fleet contracts and regional equipment dealers with service bay networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric powertrain technology is displacing diesel dominance in sub-100-foot configurations, creating fleet procurement bifurcation between legacy infrastructure and zero-emission mandates.
For Market Incumbents: Extend telematics-enabled uptime guarantee offerings to capture recurring service revenue from hardware commoditization. Deepen backward integration into hydraulic component supply to defend against lead time volatility from German and Japanese precision manufacturers. Altec Industries and Versalift demonstrate margin control through captive boom fabrication capacity. For New Entrants and Emerging Players: Municipal electric cooperatives with aging pre-2015 fleets represent the most penetrable buyer archetype as OSHA recertification deadlines force replacement cycles. Target compact articulating configurations for 5G telecommunications contractors in Texas and California urban corridors. Pursue telematics retrofit partnerships with legacy fleet operators as a service-led entry vector. For Investors and Strategic Acquirers: The window for entry favors vertically integrated chassis-boom assemblers with EPA certification pipelines and established utility fleet relationships. Long-term viability rests on electrification readiness and telematics platform development rather than manufacturing scale alone. Monitor EPA Tier 5 implementation timing as the inflection indicator for diesel engine supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables subscription-based uptime contracts that decouple revenue from unit sales. |
| Backward Integration into Hydraulics | Reduces lead time vulnerability from German and Japanese precision component suppliers. |
| Electric Powertrain Certification | Qualifies manufacturers for California and New York zero-emission fleet procurement mandates. |
| Insulated Boom Recertification Investment | Captures replacement demand from municipal cooperatives facing OSHA deadline pressure. |
| Regional Service Network Expansion | Supports storm-response reliability requirements in southeastern US mutual aid agreements. |
Methodological Framework
Multi-period observation of fleet procurement patterns, OSHA certification timelines, and EPA regulatory phases anchored the trend analysis, supplemented by interviews with utility fleet managers, municipal procurement officers, aerial equipment technicians, and hydraulic component suppliers. Secondary validation drew from EPA regulatory filings, OSHA safety standard updates, utility cooperative annual reports, and aerial work equipment trade association data. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across segments.
Segment-weighting applied product type, fuel configuration, end-user category, and application intensity dimensions across the projection horizon. CAGRs derived from fitted growth curves against historical replacement cycle data and regulatory compliance deadlines. Industry-specific inputs included storm-response infrastructure spending trajectories and electrification readiness assessments by utility service territory.
Revisions become necessary when EPA Tier 5 implementation timing shifts, battery weight-to-payload ratios cross critical chassis thresholds, or OSHA extends recertification deadlines. Forecasts reflect documented assumptions regarding fleet electrification pace and commodity input stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Heavy-Duty Truck Dashboard Switch Panel Systems Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Heavy-Duty Truck Fleet Control Unit Architectures Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market