
 Telehealth and Telemedicine Market | 2026-2036
Telehealth and Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
Telehealth and Telemedicine Market Outlook
Employer-sponsored health plans are bifurcating demand away from traditional fee-for-service channels toward subscription-based virtual care models. Teladoc Health, Inc. leverages its chronic care portfolio to anchor recurring revenue streams across diabetes and hypertension management. Amwell sustains platform stickiness through deep EHR integrations with major hospital systems. MDLIVE competes on speed-to-appointment metrics in the urgent care segment, where consumer expectations for sub-15-minute wait times now dominate purchase decisions.
Telehealth and telemedicine encompass real-time clinical services, asynchronous store-and-forward diagnostics, and remote patient monitoring delivered through digital infrastructure rather than physical co-location. Core technical specifications include HIPAA-compliant encryption protocols, 99.9% uptime SLAs for acute care triage, and FDA 510(k) clearance pathways for algorithm-driven diagnostic software. Software Solutions now captures the dominant margin pool as health systems prioritize white-label platform licensing over hardware procurement. AI Diagnostics within the Technology dimension is displacing rule-based symptom checkers as large-language models achieve clinical-grade triage accuracy in peer-reviewed validation studies.
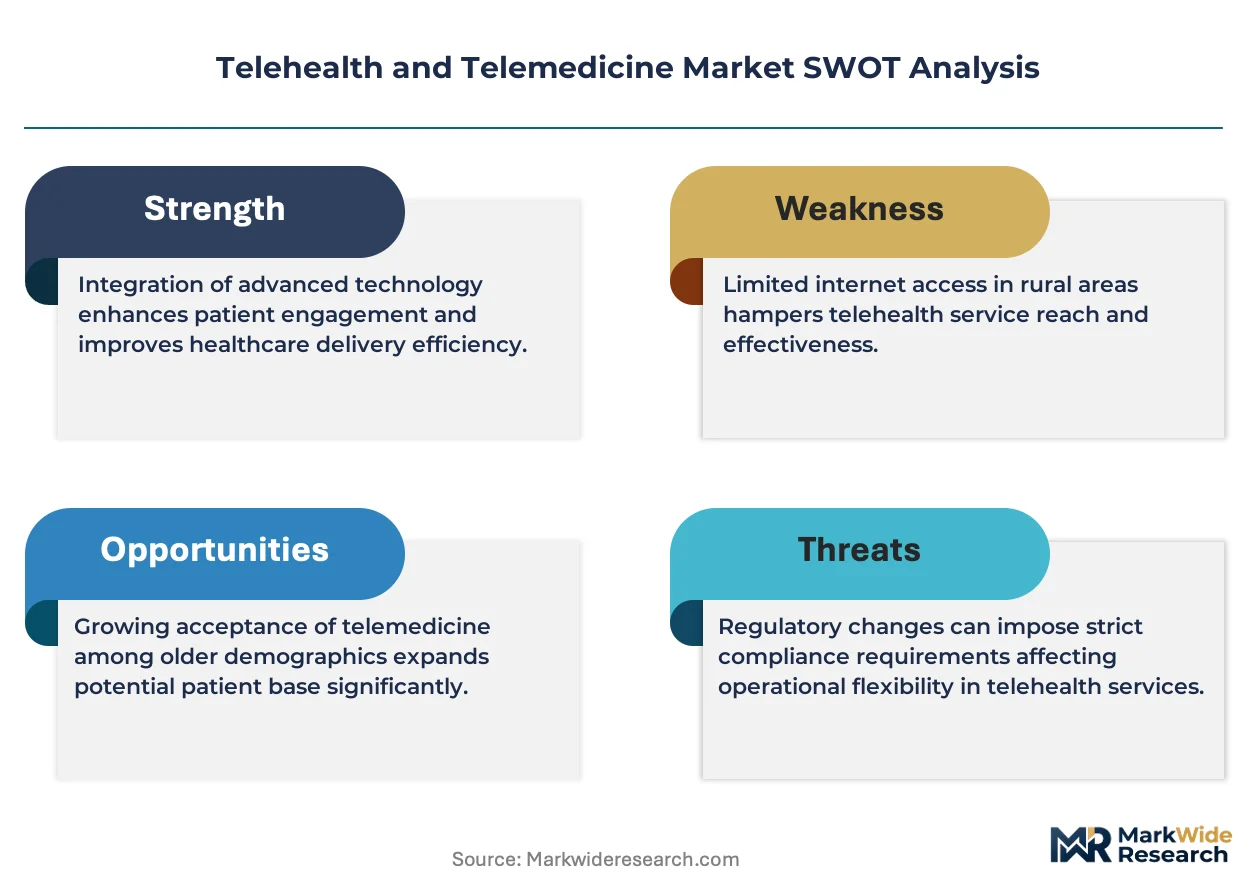
FDA oversight of software-as-medical-device platforms intersects with CMS reimbursement rulings to determine which modalities achieve sustainable payment parity. The EU AI Act imposes risk-classification requirements on diagnostic algorithms entering European markets, creating divergent compliance burdens for multi-territory deployments. Stakeholders must monitor evolving state-level telehealth licensing compacts that determine whether clinicians can practice across jurisdictional boundaries without redundant credentialing.
Market Dynamics
Reimbursement parity laws across U.S. states have permanently shifted payment infrastructure toward virtual care channels, erasing the historical fee-for-service advantage of physical encounters and forcing capital reallocation into platform licensing models.
Growth Catalysts
- CMS reimbursement rulings:Federal payment parity mandates now cover synchronous video visits and remote patient monitoring, expanding addressable patient populations for virtual-first providers.
- Chronic disease management:Employer-sponsored plans and Medicare Advantage are directing new budgets toward subscription-based diabetes and hypertension programs that require continuous digital engagement.
- FDA 510(k) clearance pathways:Streamlined software-as-medical-device approvals for algorithm-driven diagnostic tools are accelerating commercialization timelines for AI triage platforms.
Market Restraints
- State-level licensing compacts:Incomplete interstate credentialing agreements create redundant compliance burdens for clinicians practicing across U.S. state lines.
- EU AI Act risk classification:European diagnostic algorithm requirements impose divergent validation standards that fragment product development roadmaps for multi-territory deployments.
- Cloud infrastructure concentration:Reliance on three dominant hyperscale providers for HIPAA-compliant hosting creates single-point-of-failure exposure for acute care triage systems.
Strategic Opportunities
- Rural health system penetration:Underserved U.S. counties with physician shortages present captive demand for asynchronous store-and-forward diagnostic networks.
- Behavioral health integration:Virtual psychiatric consultations and digital therapeutic programs remain underpenetrated relative to physical medicine offerings.
- Large-language model convergence:Clinical-grade NLP is enabling automated documentation and real-time decision support that reduces clinician administrative burden.
Industry Challenges
- EHR integration complexity:Health systems demand bidirectional data flows with legacy Cerner and Epic installations that require custom API development and extended implementation timelines.
- Clinician workflow retraining:Virtual-first care protocols demand new competencies in digital rapport-building and remote physical examination techniques that medical education curricula have not standardized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telehealth and Telemedicine Market |
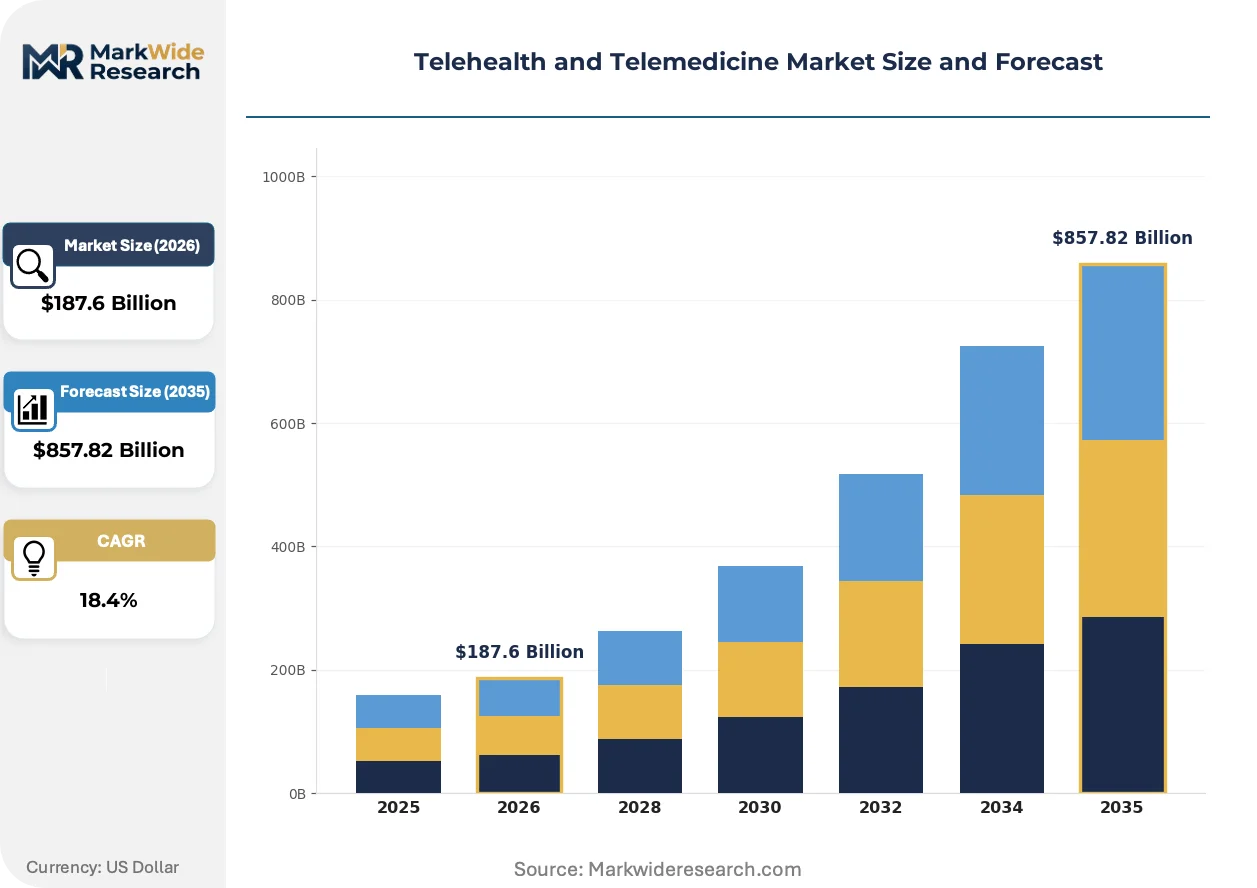
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $857.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Remote Monitoring Devices, Mobile Health Apps, Consultation Platforms Technology: Video Conferencing, Wearable Devices, Cloud Solutions, AI Diagnostics Delivery Mode: Mobile Access, Desktop Access, SMS Services, Virtual Platforms End User: Patients, Healthcare Providers, Insurance Companies, Enterprises |
| Companies Covered | Teladoc Health, Inc., Amwell, MDLIVE, Doctor on Demand, Inc., Doximity, Inc., Koninklijke Philips N.V., Medtronic, GE Healthcare, Epic Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telehealth and Telemedicine Market Strategic Shifts
Large-language models trained on clinical corpora are compressing diagnostic timelines and forcing incumbents to rebuild core platform architectures around conversational AI rather than rule-based logic trees.
Multimodal diagnostic algorithms that synthesize voice biomarkers, facial analysis, and patient-reported symptoms are displacing single-input symptom checkers in urgent care triage workflows. Health systems in the United States are piloting these tools for sub-15-minute intake protocols. The structural consequence is margin compression for legacy questionnaire-based platforms that cannot retrofit real-time sensor fusion.
The EU AI Act's risk-classification framework for medical algorithms is fragmenting compliance roadmaps for software developers seeking European market entry. High-risk diagnostic applications now require notified body review and post-market surveillance systems that add months to commercialization timelines. Developers are responding by sequencing U.S. FDA 510(k) clearance ahead of European submissions to preserve cash runway.
Employer-sponsored health plans are unbundling urgent care from comprehensive primary care relationships, creating spot-market purchasing for on-demand virtual visits. This procurement pattern favors speed-to-appointment metrics over longitudinal patient records. The shift is most visible in technology sector employee populations where consumer-grade service expectations have transferred to clinical service delivery.
Telehealth and Telemedicine Market Segmentation
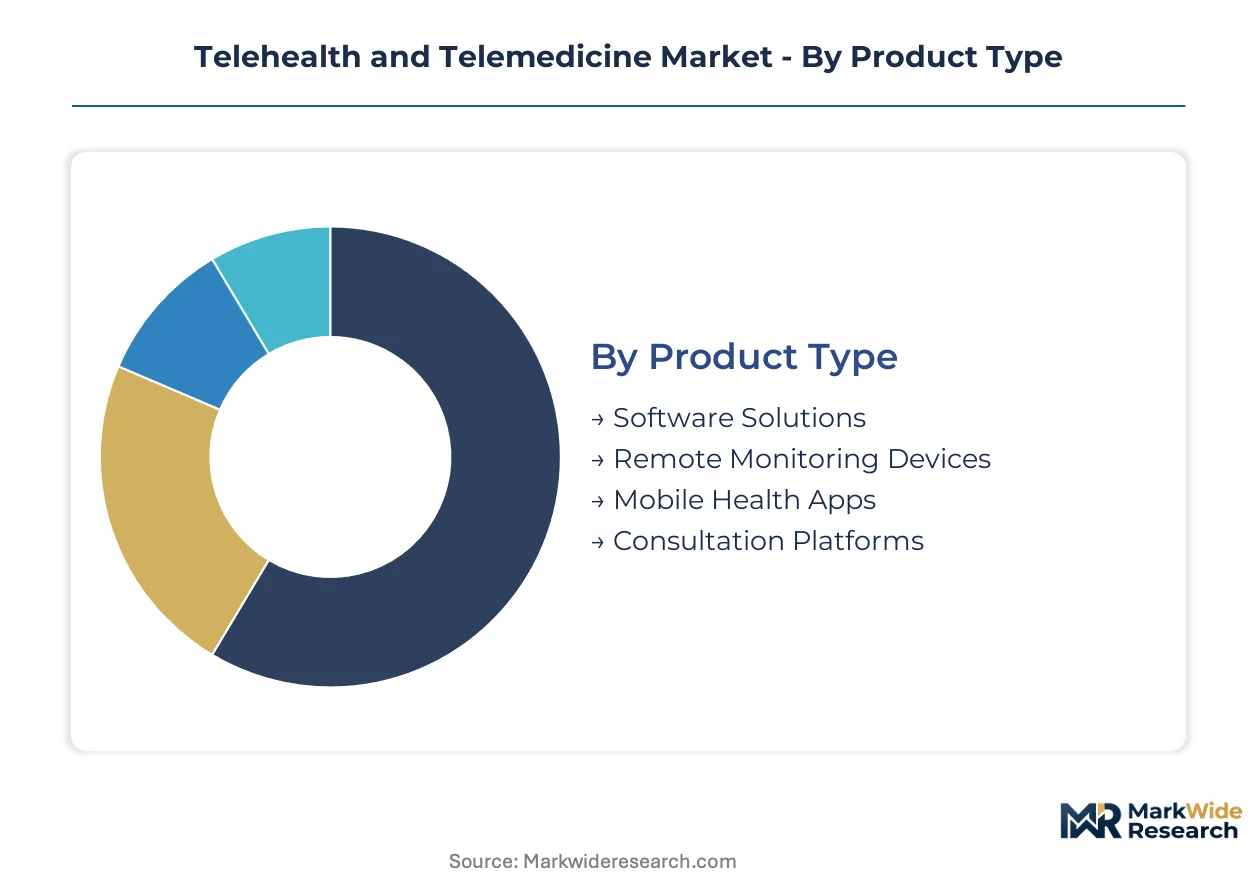
Telehealth and telemedicine segmentation reflects divergent regulatory pathways across FDA 510(k) software classifications, HIPAA infrastructure requirements, and CMS reimbursement tiers. Each segment carries distinct compliance burdens and margin profiles that reshape vendor competitive positioning.
Product Type:
FDA clearance pathways differentiate software platforms from hardware peripherals, creating tiered validation timelines that favor asset-light delivery models.
- Software Solutions:Cloud-native platforms with HIPAA-compliant encryption protocols and 99.9% uptime SLAs. Health systems in the United States prioritize white-label licensing over proprietary development, concentrating demand among integrated delivery networks seeking EHR interoperability. CMS reimbursement parity for synchronous video visits accelerates procurement cycles for virtual-first providers.
- Remote Monitoring Devices:FDA-cleared biosensors and software-as-medical-device peripherals transmitting continuous physiologic data. Medicare Advantage chronic disease management programs in the United States drive subscription revenue for diabetes and hypertension monitoring kits. The 2023 FDA guidance lowered clinical trial barriers, compressing commercialization timelines for algorithm-driven diagnostic tools.
- Mobile Health Apps:Consumer-facing symptom checkers and wellness trackers operating below medical device thresholds. Direct-to-employer sales channels bypass traditional payer infrastructure.
- Consultation Platforms:Real-time clinical encounter systems with integrated scheduling and documentation workflows. Rural health systems leverage these for specialist access without redundant credentialing.
Software Solutions handles the majority of throughput; Remote Monitoring Devices is expanding most quickly on share.
Technology:
Technical specifications determine whether platforms qualify for acute care triage versus routine wellness applications, with AI Diagnostics commanding premium licensing fees.
- AI Diagnostics:Large-language models trained on clinical corpora achieving peer-reviewed triage accuracy. These systems displace rule-based symptom checkers in urgent care workflows where sub-15-minute intake protocols dominate procurement decisions. FDA 510(k) clearance for algorithm-driven software creates defensible moats against commodity diagnostic tools.
- Video Conferencing:Real-time audiovisual infrastructure with end-to-end encryption and bandwidth adaptation for low-connectivity environments. Rural United States counties with physician shortages deploy these for asynchronous specialist consultations, though reimbursement parity varies by state Medicaid programs.
- Wearable Devices:Continuous biosensors transmitting heart rate, glucose, and activity metrics to clinical dashboards. Employer-sponsored wellness programs subsidize device costs to reduce downstream claims.
- Cloud Solutions:Hyperscale-hosted infrastructure with HIPAA Business Associate Agreements and geographic data residency controls. Concentration among three dominant providers creates single-point-of-failure exposure for acute care systems.
Video Conferencing retains the largest installed base; AI Diagnostics is climbing the fastest on revenue contribution.
Delivery Mode:
Patient access preferences bifurcate between synchronous real-time encounters and asynchronous store-and-forward modalities, with mobile-first designs capturing younger demographics.
- Mobile Access:Smartphone-native applications with biometric authentication and push-notification triage alerts. Technology sector employee populations in the United States drive demand for consumer-grade service expectations in clinical delivery.
- Desktop Access:Browser-based platforms optimized for complex documentation and multi-screen clinical workflows. Healthcare providers prefer these for longitudinal primary care relationships requiring detailed EHR integration.
- SMS Services:Text-based appointment reminders, medication adherence prompts, and simple symptom surveys. Low-bandwidth requirements penetrate elderly populations with limited digital literacy.
- Virtual Platforms:Immersive environments incorporating augmented reality for remote physical examination guidance. Pilot deployments focus on orthopedic and dermatology assessments.
Mobile Access serves the highest patient volume; Virtual Platforms is gaining share fastest among pilot health systems.
End User:
Procurement authority and reimbursement mechanisms differ sharply between direct patient purchasers, institutional providers, and risk-bearing payers.
- Healthcare Providers:Hospitals and physician groups licensing platforms for virtual-first care delivery. Deep EHR integrations with Cerner and Epic installations require custom API development and extended implementation timelines. United States health systems prioritize bidirectional data flows to maintain longitudinal patient records.
- Insurance Companies:Payers designing narrow networks and prior authorization workflows around telehealth cost savings. Medicare Advantage plans direct new budgets toward subscription-based chronic disease management programs.
- Patients:Direct-pay consumers seeking on-demand urgent care outside traditional primary care relationships. Speed-to-appointment metrics dominate purchase decisions in this spot-market segment.
- Enterprises:Self-insured employers unbundling virtual care from comprehensive health benefits. Procurement favors speed over continuity, compressing margins for longitudinal care models.
Healthcare Providers account for the dominant procurement volume; Insurance Companies is the fastest mover on policy-driven adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based telehealth platforms export virtual care infrastructure to Canada, the United Kingdom, and Australia, where reimbursement frameworks increasingly mirror U.S. payment parity models. This trade-flow corridor concentrates technology licensing revenue among HIPAA-compliant platform developers seeking multi-territory deployment.
United States
Employer-sponsored plans and Medicare Advantage drive subscription demand for chronic disease management platforms across diabetes and hypertension programs. CMS reimbursement rulings now mandate payment parity for synchronous video visits and remote patient monitoring in most states. The Boston-Cambridge corridor hosts concentrated AI diagnostic development, where clinical-grade large-language models achieve peer-reviewed triage accuracy.
Germany
Statutory health insurance funds are expanding digital health app prescriptions under the DiGA fast-track approval pathway. The EU AI Act imposes risk-classification requirements on diagnostic algorithms entering European markets, creating divergent compliance burdens for multi-territory deployments. Berlin's health technology cluster attracts U.S. platform providers seeking European market entry through notified body partnerships.
United Kingdom
NHS England's virtual ward programs deploy remote patient monitoring for post-acute care transitions, reducing hospital readmission rates. The Medicines and Healthcare products Regulatory Agency aligns software-as-medical-device oversight with FDA 510(k) precedents to accelerate market access. London's digital health ecosystem concentrates telehealth startups targeting NHS procurement frameworks.
Japan
Aging demographics and rural physician shortages accelerate adoption of asynchronous store-and-forward diagnostic networks. The Ministry of Economy, Trade and Industry promotes regulatory harmonization with FDA digital health guidance to streamline cross-border platform licensing. Tokyo-Osaka metropolitan corridors host pilot deployments of multimodal diagnostic algorithms integrating voice biomarkers and facial analysis.
India
Direct-to-consumer telehealth platforms penetrate tier-2 and tier-3 cities where specialist density remains critically low. The Central Drugs Standard Control Organization is developing software-as-medical-device classification rules aligned with FDA and EU precedents. Bangalore and Hyderabad clusters concentrate health technology development centers serving domestic and export markets.
Telehealth and Telemedicine Market Competitive Environment
Player mix skews toward integrated virtual care platforms with chronic disease management capabilities, creating tiered competitive dynamics between comprehensive providers and point-solution specialists. Market structure concentrates procurement authority among health systems prioritizing EHR interoperability over standalone functionality. Two strategic archetypes dominate: platform licensors seeking white-label deployments and urgent-care specialists competing on speed-to-appointment metrics. Competitive moves center on EHR integration partnerships and AI diagnostic capability acquisitions.
Within the integrated platform tier, Teladoc Health, Inc. and Amwell occupy positions exemplifying chronic care portfolio anchoring and deep health system embedding respectively. MDLIVE represents the speed-optimized archetype competing in spot-market urgent care procurement. These three entities illustrate divergent strategic postures across subscription-based longitudinal care and on-demand transactional models.
| Leading Market Players |
|---|
| Teladoc Health, Inc. |
| Amwell |
| MDLIVE |
| Doctor on Demand, Inc. |
| Doximity, Inc. |
| Koninklijke Philips N.V. |
| Medtronic |
| GE Healthcare |
| Epic Systems Corporation |
| Others |
Value Chain & Pricing Dynamics
Per-patient subscription contracts lock in multi-year revenue visibility for virtual care platforms while insulating health systems from utilization volatility. These arrangements concentrate procurement leverage among integrated delivery networks that can guarantee minimum enrollment thresholds, compressing margins for standalone point-solution vendors competing on transactional pricing.
Pricing Analysis
Next-generation AI diagnostic platforms command licensing premiums over legacy rule-based symptom checkers that cannot retrofit conversational interfaces. Three-tier pricing structure across enterprise, mid-market, and direct-to-consumer levels separates health system deployments from employer-sponsored plans and individual urgent care purchases. Cost compression in the urgent care tier is intensifying because speed-to-appointment metrics dominate spot-market procurement. Employer-sponsored plans exhibit highest price sensitivity due to unbundled benefit designs that treat virtual visits as commodity transactions.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound costs for FDA-cleared biosensors manufactured in Taiwan and South Korea. Cloud infrastructure draws from hyperscale data centers concentrated in the United States, Ireland, and Singapore, with software development anchored in Bangalore and Tel Aviv clusters. Single-source vulnerability concentrates in three dominant cloud providers hosting HIPAA-compliant workloads for acute care triage systems. Distribution runs through health system GPO contracts and direct-to-employer sales channels that bypass traditional pharmaceutical distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across behavioral health integration and rural specialist access where incumbent platforms under-invest. Employer unbundling of urgent care from primary care relationships creates niche openings for purpose-built solutions.
For Market Incumbents: Secure chronic disease management revenue through exclusive Medicare Advantage partnerships before regulatory shifts alter risk-adjustment calculations. Deepen EHR integration moats with Epic and Cerner to raise switching costs for health system customers facing clinician workflow retraining investments. Vertical integration into remote monitoring device manufacturing reduces supplier concentration exposure for hardware-dependent service lines.
For New Entrants and Emerging Players: Asynchronous store-and-forward diagnostic networks for rural counties with physician shortages represent the most penetrable white-space target. Behavioral health virtual consultations remain under-served relative to physical medicine offerings, with reimbursement parity expanding faster than platform supply. Target direct-to-employer sales channels that bypass health system procurement complexity and prioritize speed over longitudinal care continuity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among chronic care platforms with Medicare Advantage risk contracts that embed multi-year patient relationships. Long-term viability across the projection horizon hinges on FDA 510(k) clearance portfolios that create regulatory moats against commodity diagnostic tools. Acquisition targets should demonstrate interoperable EHR connectivity and post-clearance commercial traction. The signal to watch is CMS reimbursement ruling expansions that validate new virtual care modalities beyond synchronous video.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Algorithm-driven diagnostic software achieves regulatory validation ahead of EU AI Act compliance timelines. |
| Hospital System Partnership | Deep EHR integrations with Epic and Cerner installations create platform stickiness through bidirectional data flows. |
| Reimbursement Strategy | CMS payment parity mandates for remote patient monitoring expand addressable populations for virtual-first providers. |
| Software Companion Development | Large-language models trained on clinical corpora displace rule-based symptom checkers in urgent care triage workflows. |
| CE Marking Pathway | European notified body review requirements fragment product roadmaps for multi-territory diagnostic algorithm deployments. |
Study Parameters
The analysis maps synchronous video platforms, asynchronous diagnostics, remote patient monitoring, and AI triage systems, each validated through health system CIOs, Medicare Advantage plan directors, FDA regulatory consultants, and biomedical engineers. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, CMS reimbursement rulings, hospital procurement databases, and GPO contract disclosures. Bottom-up enrollment and utilization data triangulates against top-down payer budget allocation estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models deployment mode, end-user procurement authority, technology generation, and regional regulatory cluster dimensions. CAGRs derive from segmented enrollment trajectories and per-patient revenue assumptions, with chronic disease management program expansion and AI diagnostic adoption curves serving as primary forecast inputs.
Underlying assumptions cover CMS reimbursement parity persistence, FDA software-as-medical-device clearance timelines, and state-level licensing compact evolution, with deviation risk concentrated in EU AI Act implementation delays and hyperscale cloud infrastructure concentration. Recalibration cycles align with material shifts in federal payment policy and diagnostic algorithm regulatory precedents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telemedicine Technologies Market
Telemedicine
Tele-ICU Services Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
US Virtual Visits Market
Telemedicine
Europe Telemedicine Market
Telemedicine
Telehealth Kiosk Market
Telemedicine
Telehealth Software Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Global Telemedicine Market
Telemedicine
Global Virtual Care Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
India Telemedicine Market
Telemedicine
US Telehealth Market