
 Europe Veterinary Vaccine Market | 2026-2036
Europe Veterinary Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Veterinary Vaccine Market Foresight
Companion animal practice is broadening its share of vaccine consumption across European veterinary channels. Zoetis leverages its transatlantic manufacturing footprint to supply both livestock and pet segments. Boehringer Ingelheim International GmbH anchors its position through R&D intensity in porcine respiratory vaccines. Virbac SA specializes in fish health immunologicals for Mediterranean aquaculture operations.
Europe veterinary vaccines comprise antigen preparations derived from attenuated, inactivated, or recombinant pathogens, formulated with adjuvants to stimulate protective immunity in food-producing and companion animals, with stability requirements typically demanding cold-chain maintenance at two to eight degrees Celsius. Live Attenuated products dominate volume due to cost efficiency in poultry and cattle programs, while DNA vaccines represent the fastest-expanding category as nucleic acid manufacturing scales reduce per-dose costs. Intramuscular delivery leads administration routes for large-animal applications, though intranasal formats gain traction in respiratory disease control where mucosal immunity proves decisive.
The European Medicines Agency oversees centralized marketing authorization for veterinary immunologicals, while national regulators such as Germany's Federal Office for Consumer Protection and Food Safety execute batch-release testing that shapes time-to-market timelines. The EU Veterinary Medicines Regulation mandates environmental risk assessments for novel products, directing R&D investment toward biodegradable adjuvant systems and reduced-antigen formulations. Stakeholders must monitor regulatory divergence between EMA centralized procedures and member-state flexibility clauses as product development strategies calibrate to evolving compliance thresholds.
Market Dynamics
The EU Veterinary Medicines Regulation is compressing development timelines while elevating environmental compliance thresholds, forcing manufacturers to reconfigure formulation chemistry and cold-chain logistics simultaneously.
Growth Catalysts
- EMA Centralized Authorization:The streamlined marketing authorization procedure accelerates cross-border product launches, reducing redundant national filings for novel immunologicals.
- Companion Animal Channel Expansion:Small-animal clinics in France and Italy are extending vaccine protocols beyond core antigens to lifestyle and travel-related indications.
- DNA Vaccine Manufacturing Scale-Up:Nucleic acid production platforms are achieving cost parity with conventional attenuated products, opening price-accessible entry points for aquaculture operators.
Market Restraints
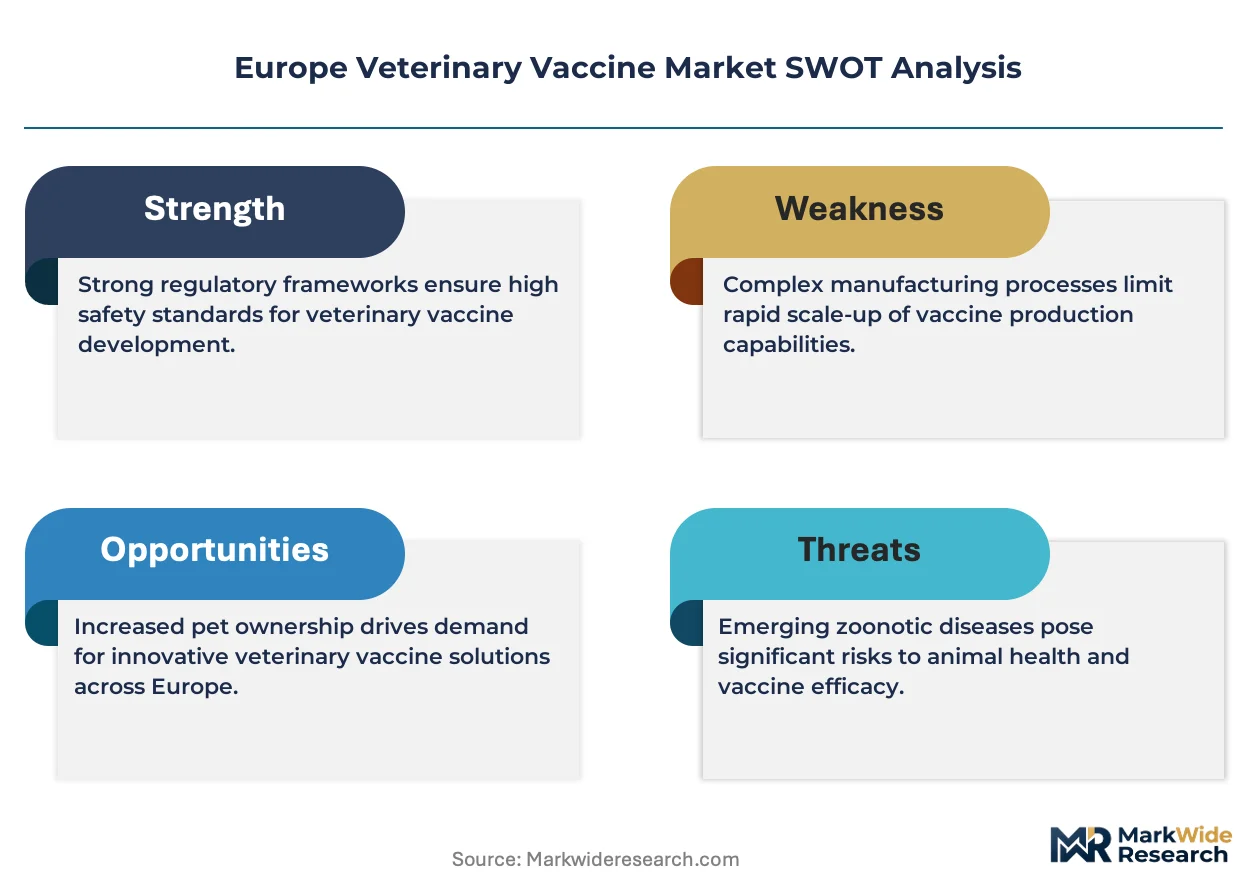
- Adjuvant Input Concentration:Squalene and alum supply chains concentrate in a limited number of specialty chemical producers, exposing formulators to raw material volatility.
- Cold-Chain Infrastructure Gaps:Two-to-eight-degree Celsius stability requirements strain distribution networks in Eastern European markets with fragmented veterinary service coverage.
- Batch-Release Testing Bottlenecks:Germany's Federal Office for Consumer Protection and Food Safety maintains rigorous release protocols that extend time-to-market for imported products.
Strategic Opportunities
- Spanish Aquaculture Undersupply:Mediterranean fish farming operations lack specialized immunological coverage for emerging bacterial pathogens in sea bass and sea bream production.
- Biodegradable Adjuvant Systems:The EU Green Deal's environmental risk assessment mandates are creating first-mover advantages for formulations with reduced ecological persistence.
- Intranasal Delivery Convergence:Mucosal immunity platforms combining live-vector and subunit technologies are opening respiratory disease segments previously dominated by parenteral products.
Industry Challenges
- Regulatory Affairs Talent Scarcity:The intersection of immunology and environmental toxicology expertise required for EMA dossier preparation exceeds current workforce supply.
- Legacy System Integration:Cold-chain monitoring platforms must interface with national traceability databases that lack standardized data exchange protocols.
- Antigen Matching Complexity:Field strain evolution in porcine respiratory diseases outpaces reference strain updates in licensed products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Veterinary Vaccine Market |
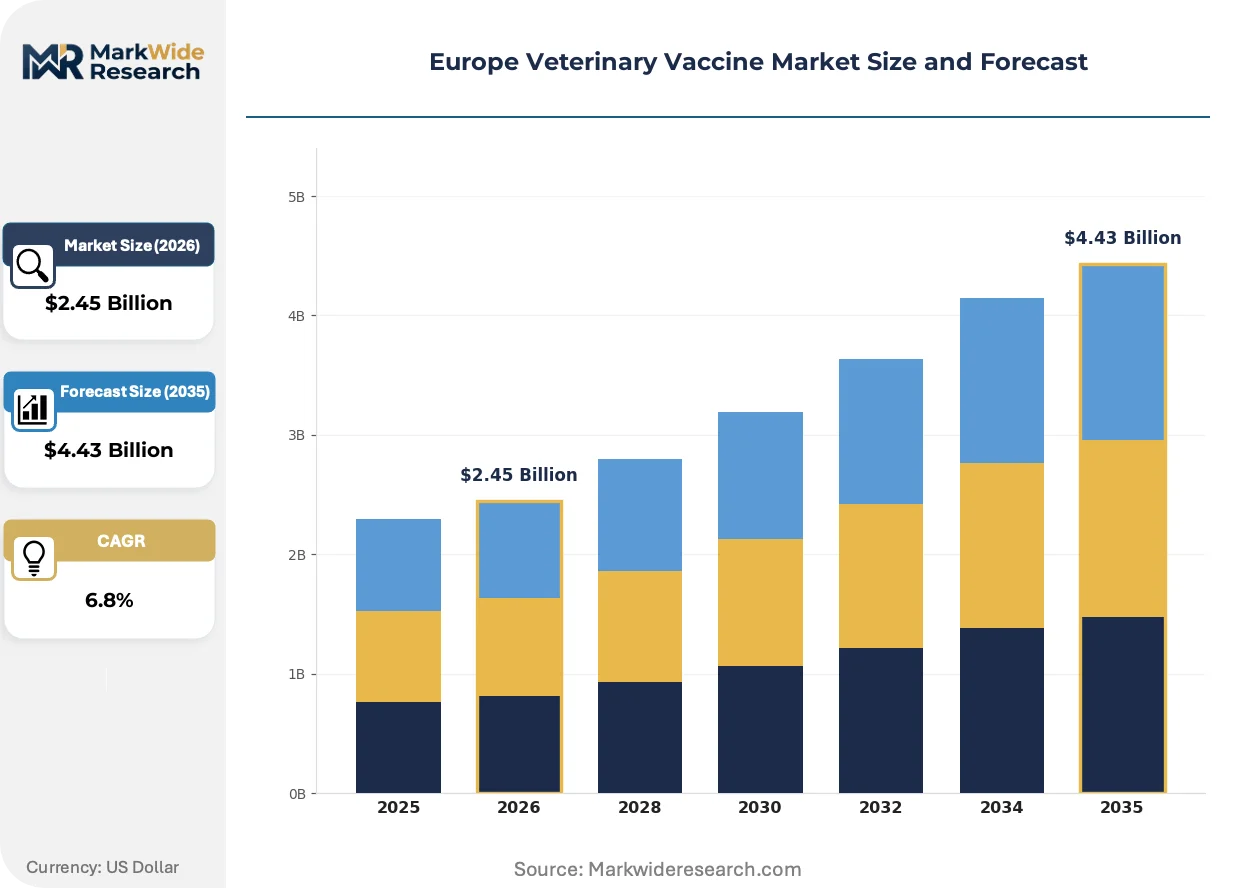
| Market Size in 2026 | $2.45 Billion |
| Market Size in 2035 | $4.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Subunit, DNA Animal Type: Cattle, Poultry, Swine, Aquaculture Route of Administration: Subcutaneous, Intranasal, Intramuscular, Oral Distribution Channel: Veterinary Clinics, Pharmacies, Online Retail, Distributors |
| Companies Covered | Zoetis, Merck & Co., Boehringer Ingelheim International GmbH, Virbac SA, Elanco Animal Health, Ceva Santé Animale, HIPRA, Phibro Animal Health Corporation, Neogen Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Veterinary Vaccine Market Shifts & Advancements
Formulation science and delivery mechanisms are converging to reduce dose volumes while expanding mucosal protection, reshaping how veterinary practices administer preventive care across species.
DNA vaccine platforms are decentralizing manufacturing economics by enabling cell-free production at reduced biosafety containment levels. Regional veterinary pharmaceutical facilities in the Netherlands and Denmark are adopting modular nucleic acid synthesis equipment to produce autogenous vaccines for local livestock populations. This distributed production model is compressing lead times for emergency outbreak response while reducing transcontinental cold-chain dependency.
REACH regulation amendments are tightening scrutiny of persistent organic pollutants in adjuvant systems, compelling reformulation investments across the industry. Manufacturers must now submit comprehensive environmental fate data for novel immunological excipients before EMA centralized authorization. Livestock vaccine portfolios face the steepest compliance burden, as large-animal dose volumes amplify environmental exposure calculations.
Subscription-based preventive health programs are displacing transaction-by-transaction vaccine purchasing in companion animal practices. German and UK veterinary groups are bundling core immunizations with wellness monitoring services, locking in multi-year patient relationships. This model concentrates purchasing authority at corporate practice level, squeezing margin flexibility for traditional distribution intermediaries.
Europe Veterinary Vaccine Market Segmentation
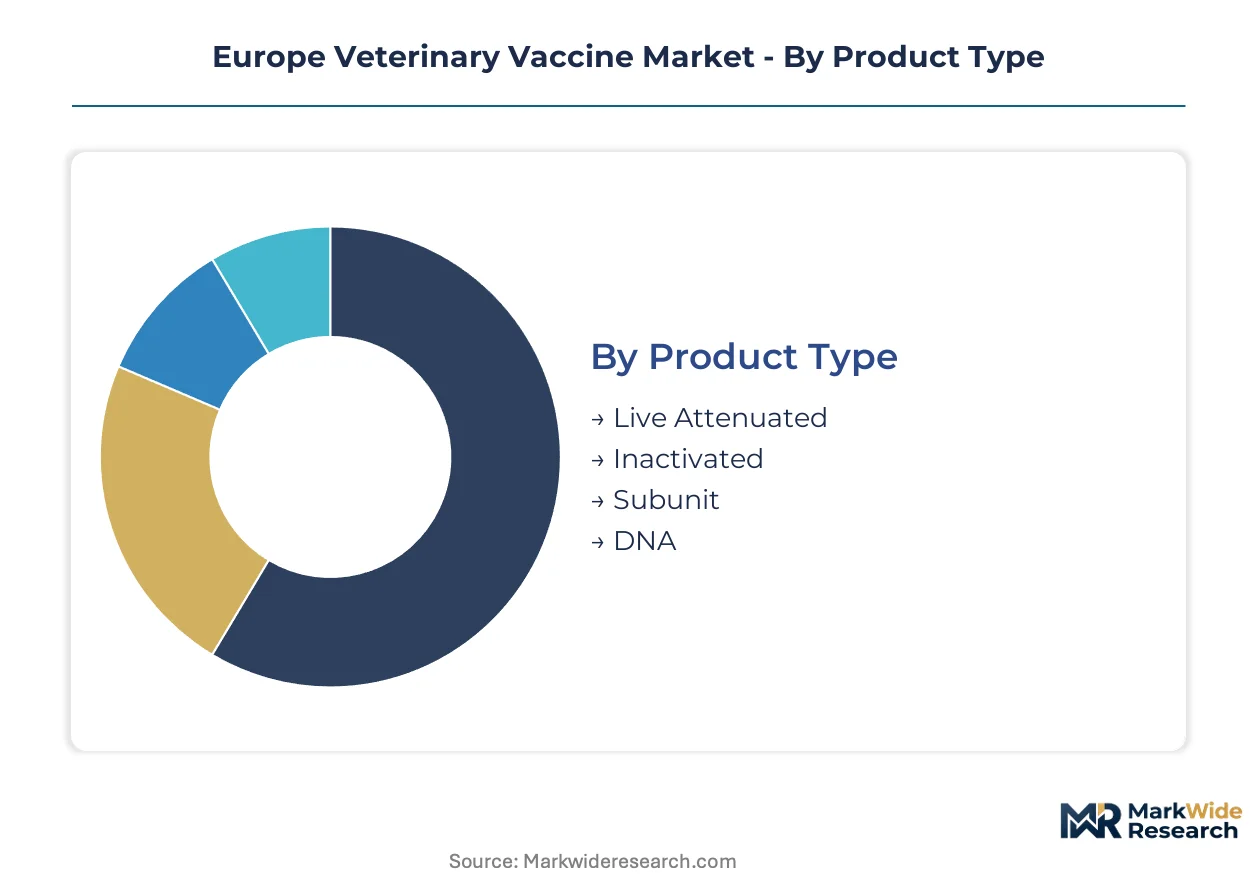
Veterinary vaccine segmentation reveals divergent capital requirements across manufacturing modalities. Live attenuated production demands biosafety level containment infrastructure. DNA platforms require nucleic acid synthesis equipment but lower cleanroom classifications.
Product Type:
Live Attenuated vaccines absorb the heaviest upfront capital allocation for viral seed stock banking and egg-based or cell culture production suites.
- Live Attenuated:Formulations contain weakened pathogen strains capable of limited replication to stimulate cellular immunity. German cattle operations and Dutch poultry integrators anchor demand for thermostable modified-live preparations against bovine respiratory disease and Newcastle disease. Cold-chain dependency at minus 15 to minus 50 degrees Celsius for master seed stocks elevates storage infrastructure costs.
- Inactivated:Killed pathogen preparations combined with mineral oil or aluminum hydroxide adjuvants generate humoral antibody responses without replication risk. French and Italian swine producers favor these formulations for breeding stock protocols where vaccine shedding must be eliminated. Batch consistency requirements drive quality control expenditure.
- Subunit:Purified protein antigens produced via recombinant expression systems reduce reactogenicity profiles.
- DNA:Plasmid vectors encoding pathogen antigens enable rapid reformulation against emerging strains.
Most installed capacity flows through Live Attenuated. Expansion is steepest in DNA.
Animal Type:
Volume concentration varies sharply by species biology and farm structure across European production geographies.
- Cattle:Large-animal dose volumes and extended immunization schedules in dairy and beef operations sustain bulk manufacturing economics. Bavarian and Lower Saxony dairy cooperatives drive demand for multivalent clostridial and respiratory combination vaccines. Individual animal identification mandates in Germany and France enable precise herd health tracking that supports premium vaccine uptake.
- Poultry:Mass administration via hatchery spray or drinking water delivery achieves lowest per-dose costs at industrial scale. Spanish and Polish broiler integrators deploy in ovo vaccination technology to reduce labor and stress-related losses. Short production cycles compress feedback loops for vaccine efficacy assessment.
- Swine:Porcine reproductive and respiratory syndrome virus complexity sustains autogenous vaccine demand.
- Aquaculture:Mediterranean sea bass and sea bream farming in Greece and Spain generates specialized bacterial vaccine requirements.
Poultry channels process the highest absolute doses. Aquaculture is climbing the fastest.
Route of Administration:
Delivery technology selection hinges on mucosal versus systemic immunity requirements and field labor constraints.
- Intramuscular:Deep tissue deposition ensures reliable antigen presentation for large-animal applications. German veterinary practitioners prefer 2-5 milliliter injectable formats for cattle respiratory and clostridial programs. Needle-free injection systems are penetrating high-throughput feedlot operations to reduce carcass blemish and handler injury.
- Intranasal:Mucosal delivery generates secretory IgA at respiratory entry points for airborne pathogens. UK and Scandinavian pig producers are adopting live-vector intranasal platforms against influenza and Mycoplasma hyopneumoniae. Reduced needle handling aligns with farm biosecurity protocols.
- Subcutaneous:Dermal deposition suits smaller companion animal doses and certain livestock applications.
- Oral:Drinking water and feed incorporation enables mass medication without individual handling.
Intramuscular remains the default for cattle. Intranasal is gaining share fastest in swine respiratory segments.
Distribution Channel:
Channel economics reflect prescriptive authority concentration and cold-chain integrity requirements.
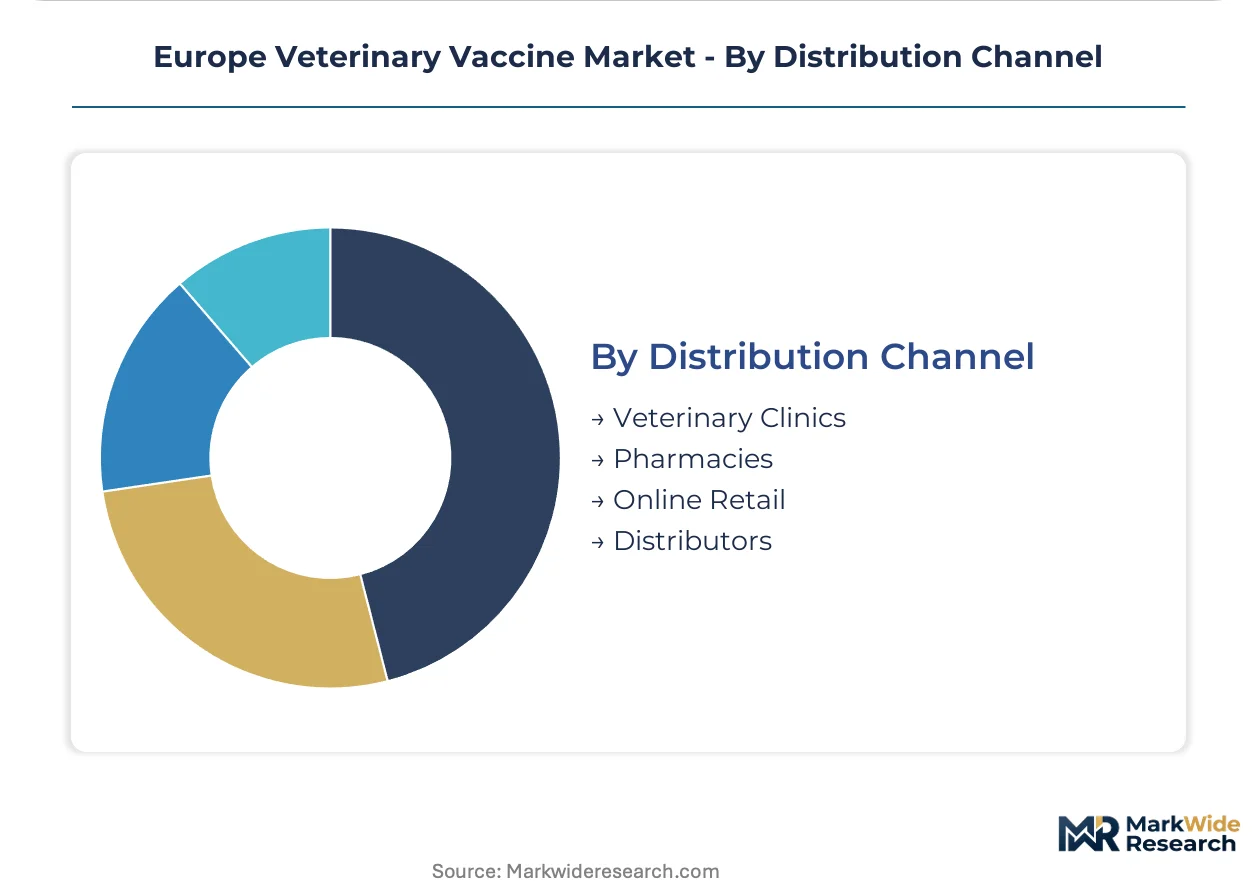
- Veterinary Clinics:Companion animal vaccine protocols concentrate purchasing power in corporate practice groups. German and UK clinic chains are consolidating procurement through centralized formulary committees that negotiate direct manufacturer contracts. Wellness program bundling locks in multi-year patient relationships and reduces price elasticity.
- Distributors:Full-line veterinary wholesalers maintain temperature-controlled warehousing and field sales forces serving fragmented rural practices. French and Italian agricultural cooperatives rely on distributor credit terms and inventory management for seasonal livestock vaccination campaigns. Route density determines per-dose logistics costs.
- Pharmacies:Human retail channels capture limited companion animal vaccine sales where regulatory frameworks permit.
- Online Retail:Direct-to-consumer platforms are penetrating prescription-required markets through telemedicine partnerships.
Distributors handle the greatest tonnage. Veterinary clinics are expanding share fastest in companion animal value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with streamlined environmental compliance pathways. The EU Veterinary Medicines Regulation's batch-release harmonization reduces cross-border friction, yet national implementation variance creates localized cost-of-compliance gaps that shape facility siting decisions.
Germany
Bavarian dairy cooperatives and Lower Saxony poultry integrators sustain the continent's densest veterinary service utilization. Germany's Federal Office for Consumer Protection and Food Safety enforces rigorous batch-release testing that extends time-to-market for imported products. The Hanover region anchors Boehringer Ingelheim's porcine respiratory vaccine R&D operations.
France
French companion animal clinics in Lyon and Paris are extending vaccine protocols to lifestyle and travel-related indications. ANSM oversight of veterinary immunologicals aligns with EMA centralized procedures while maintaining national flexibility for autogenous vaccine frameworks. The Lyon biocluster supports Virbac SA's specialized operations in Mediterranean aquaculture health.
Spain
Mediterranean sea bass and sea bream farming in Murcia and Catalonia generates undersupplied demand for bacterial vaccines against emerging pathogens. Spanish agricultural cooperatives rely on distributor credit terms for seasonal livestock vaccination campaigns. The Valencia region concentrates aquaculture vaccine distribution infrastructure serving Greek and Italian farming operations.
Netherlands
Dutch poultry integrators deploy in ovo vaccination technology to reduce labor and stress-related losses in high-throughput hatcheries. REACH regulation amendments are tightening scrutiny of persistent organic pollutants in adjuvant systems manufactured at Rotterdam chemical hubs. Wageningen University research clusters are pioneering modular nucleic acid synthesis for distributed autogenous vaccine production.
United Kingdom
UK veterinary groups are bundling core immunizations with wellness monitoring services, locking in multi-year patient relationships. The Veterinary Medicines Directorate maintains post-Brexit regulatory divergence from EMA centralized procedures that complicates cross-border product launches. Cambridge and Oxford research corridors are advancing intranasal delivery platforms for respiratory disease control.
Europe Veterinary Vaccine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with livestock channels favoring scale-driven integrated suppliers while companion animal practices concentrate purchasing authority in corporate formulary committees. The vendor base organizes around three archetypes: transatlantic diversified pharmaceutical conglomerates, European-focused R&D-intensive specialists, and regional autogenous vaccine fabricators. Competitive positioning hinges on M&A-driven portfolio breadth expansion and strategic partnerships for nucleic acid manufacturing scale-up.
Among transatlantic pharmaceutical conglomerates, Zoetis and Merck & Co. occupy positions leveraging manufacturing footprint breadth across both livestock and pet segments. Boehringer Ingelheim International GmbH exemplifies the R&D-intensive specialist archetype through its German-anchored porcine respiratory vaccine operations. Virbac SA represents Mediterranean-focused specialization in aquaculture health immunologicals.
| Leading Market Players |
|---|
| Zoetis |
| Merck & Co. |
| Boehringer Ingelheim International GmbH |
| Virbac SA |
| Elanco Animal Health |
| Ceva Santé Animale |
| HIPRA |
| Phibro Animal Health Corporation |
| Neogen Corporation |
| Others |
Supply & Pricing Matrix
Specialized formulation chemists and cold-chain logistics engineers in the Netherlands and Germany command wage premiums that compress margin spreads between premium mRNA-adjuvant platforms and economy-grade mineral oil formulations. Labor-cost differentials across these northern European manufacturing clusters translate directly into pricing-tier spreads, with Bavarian facilities absorbing higher per-dose overhead than Polish contract manufacturing organizations.
Pricing Analysis
Distributor margins in the veterinary channel typically absorb 15-25% of ex-manufacturer price before clinic-level markups. Three-tier pricing structure across premium, standard, and economy levels separates thermostable modified-live vaccines with extended shelf-life claims from basic inactivated formulations. Cost compression in the economy tier is intensifying because Spanish and Italian agricultural cooperatives negotiate consolidated procurement volumes. Small companion animal practices in France exhibit the least price sensitivity due to wellness program bundling, while Polish broiler integrators drive hardest bargain on poultry mass-administration products.
Supply Chain Analysis
Squalene and alum adjuvant inputs rest on specialty chemical producers concentrated in Belgium, Germany, and the Netherlands. Nucleic acid synthesis equipment and viral seed stock banking infrastructure draw from these same Benelux-Rhine manufacturing corridors. Single-source vulnerability in thermostable excipient supply creates exposure when REACH amendments trigger reformulation requirements. Distribution runs through temperature-controlled veterinary wholesalers with route density determining per-dose logistics costs across fragmented Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European veterinary vaccines hinges on biodegradable adjuvant premiumization and distributed DNA manufacturing economics that collapse cold-chain overhead. The shift toward subscription-based companion animal wellness programs concentrates purchasing authority at corporate practice level, enabling price discipline.
For Market Incumbents: Acquire nucleic acid synthesis platform capabilities to secure autonomous production of autogenous vaccine plasmids against porcine respiratory strain evolution. Consolidate distributor relationships in Spain and Greece where aquaculture vaccine undersupply creates channel control opportunities. EMA environmental risk assessment mandates threaten legacy mineral oil formulations; accelerate biodegradable adjuvant R&D to defend premium positioning.
For New Entrants and Emerging Players: Capture the Spanish sea bass and sea bream bacterial vaccine segment where Mediterranean farming operations lack specialized immunological coverage. Target modular manufacturing partnerships with Wageningen University research clusters for distributed autogenous production. Intranasal delivery convergence in UK and Scandinavian swine respiratory markets offers regulatory-fast-track entry with mucosal immunity platform differentiation.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional autogenous vaccine fabricators with cell-free production capabilities and established veterinary clinic relationships. Five-to-ten-year viability favors specialists with nucleic acid manufacturing scale-up partnerships over legacy attenuated vaccine dependent portfolios. Watch EMA centralized authorization timeline compression as inflection indicator for first-mover premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Adjuvant Reformulation | REACH amendments in Rotterdam chemical hubs force environmental fate compliance investment. |
| Modular Nucleic Acid Manufacturing Scale-Up | Wageningen research clusters enable distributed autogenous vaccine production for emergency outbreak response. |
| Intranasal Delivery Platform Development | Cambridge and Oxford corridors advance mucosal immunity for respiratory disease control in UK swine herds. |
| Corporate Practice Direct Procurement Contracts | German clinic chains bundle wellness programs, locking multi-year patient relationships and squeezing distributor margins. |
| Aquaculture Vaccine Distribution Infrastructure | Valencia region concentration serves undersupplied Greek and Italian sea bass farming operations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with veterinary pharmaceutical R&D directors, regulatory affairs specialists at EMA and national competent authorities, corporate practice procurement committees, and agricultural cooperative livestock managers with secondary validation against EMA centralized procedure filings, EU Veterinary Medicines Regulation implementation guidance, REACH amendment documentation, and trade data on adjuvant chemical imports. Bottom-up dose-volume modeling across species segments triangulated against top-down manufacturer revenue disclosures.
Historical reference periods anchored volume and value projections across the modeling period, with analytical frameworks segmenting by product type, animal species, route of administration, and distribution channel. CAGRs derived from segmented growth rate reconciliation against macro veterinary service utilization trends. Industry-specific forecast inputs incorporated cold-chain infrastructure development trajectories in Eastern European markets and EMA batch-release harmonization timeline assumptions.
Regulatory implementation variance, adjuvant input price volatility, and field strain evolution outpacing reference strain updates are the dominant revision risks to projection assumptions. Forecasts reflect documented assumptions about EMA centralized procedure efficiency gains and REACH environmental compliance cost pass-through. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
CBD Pet Market
Veterinary
Global Porcine Vaccine Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Bovine Mastitis Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Veterinary in Vitro Fertilization Market
Veterinary
Veterinary Progesterone Testing Market
Veterinary
Global Veterinary Care Market
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
Global Veterinary Electrosurgery Market
Veterinary
ASEAN Poultry Vaccines Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Global Veterinary Holters Market
Veterinary
Veterinary Hospitals Market
Veterinary
Global Cattle Vaccines Market
Veterinary
Clonorchiasis Market