
 Asia-Pacific Veterinary Healthcare Market | 2026-2036
Asia-Pacific Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Veterinary Healthcare Market Outlook
Biologics is shifting from traditional chemically synthesized pharmaceuticals toward recombinant and vector-based vaccines across Asia-Pacific product portfolios. Zoetis leverages its mammalian cell culture platforms to anchor premium vaccine supply in Japan and Australia. Boehringer Ingelheim sustains R&D intensity across its Asian operations, competing on respiratory disease portfolios for swine and poultry. Virbac specializes in parasiticide formulations, dominating channel access through veterinary clinic networks in Thailand and Indonesia.
Asia-Pacific veterinary healthcare encompasses the prevention, diagnosis, and treatment of disease in companion animals, livestock, and aquatic species through pharmaceutical, biological, and diagnostic modalities. Injectable vaccines require cold chain maintenance at two to eight degrees Celsius, while oral nutraceuticals incorporate omega fatty acids and probiotic cultures for gastrointestinal and dermatological conditions. Pharmaceuticals command the largest revenue pool among product types due to chronic disease management in aging companion animal populations, though diagnostics registers the fastest structural expansion as point-of-care imaging and molecular testing displace referral-lab dependency. Companion animals concentrate margin pools in urban Japan, South Korea, and Australia, while livestock applications sustain volume throughput across China's pig-rearing provinces and India's dairy belts.
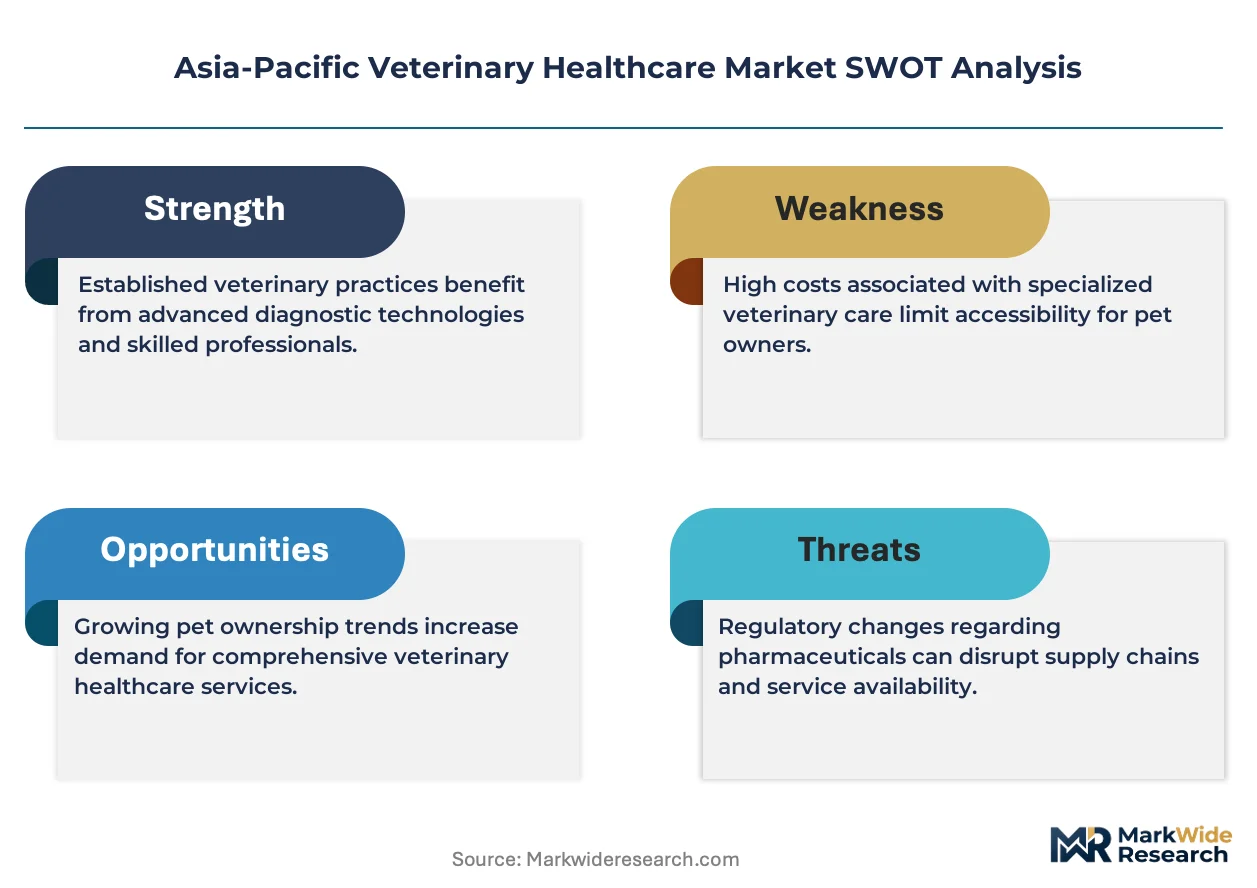
India's CDSCO mandates veterinary drug registration under the Drugs and Cosmetics Act, while China's NMPA enforces Good Manufacturing Practice certification for all biological products entering clinical distribution. Australia's TGA harmonizes with APVMA standards for agricultural and veterinary chemical access, creating multi-layered compliance burdens for multinational suppliers. Japan's PMDA maintains separate approval pathways for novel biologics, extending time-to-market for recombinant vaccines relative to conventional platforms. Stakeholders must monitor regulatory divergence on gene-edited therapeutics and environmental risk assessments for aquaculture pharmaceuticals across these jurisdictions.
Market Dynamics
Companion animal aging across Japan, South Korea, and Australia's metropolitan corridors is compressing diagnostic-to-treatment cycles while China's NMPA accelerates biologics approval timelines for recombinant vaccines.
Growth Catalysts
- CDSCO registration mandates:India's Drugs and Cosmetics Act enforcement compels formal veterinary drug documentation, expanding addressable market for registered pharmaceutical suppliers.
- Livestock respiratory disease pressure:Swine and poultry producers across China's Henan and Shandong provinces drive preventive vaccine procurement at commercial scale.
- Point-of-care molecular testing:CRISPR-based pathogen detection platforms reduce referral-lab dependency in Thailand's veterinary clinic networks.
Market Restraints
- Cold chain infrastructure gaps:Two-to-eight-degree Celsius vaccine storage requirements strain distribution reach in Indonesia's outer island veterinary posts.
- PMDA biologics pathway duration:Japan's separate approval track for novel recombinant vaccines extends commercialization timelines versus conventional platforms.
- Gene-edited therapeutic uncertainty:Divergent national positions on environmental risk assessment for aquaculture pharmaceuticals create regulatory arbitrage costs.
Strategic Opportunities
- Vietnam's underpenetrated companion segment:Rising urban pet ownership in Ho Chi Minh City and Hanoi corridors lacks specialized oncology and dermatology service infrastructure.
- PLI scheme manufacturing incentives:India's production-linked incentive framework for pharmaceutical active ingredients attracts contract manufacturing investment for veterinary APIs.
- Telemedicine-diagnostics convergence:Remote consultation platforms paired with at-home sample collection kits reshape first-contact veterinary access in Australia's rural territories.
Industry Challenges
- Veterinary specialist workforce scarcity:Board-certified pathologists and imaging specialists concentrate in Tokyo, Seoul, and Sydney, leaving tier-two cities underserved.
- Multi-jurisdiction compliance synchronization:Australia's TGA-APVMA harmonization creates documentation redundancy for suppliers accessing both human and agricultural chemical pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Veterinary Healthcare Market |
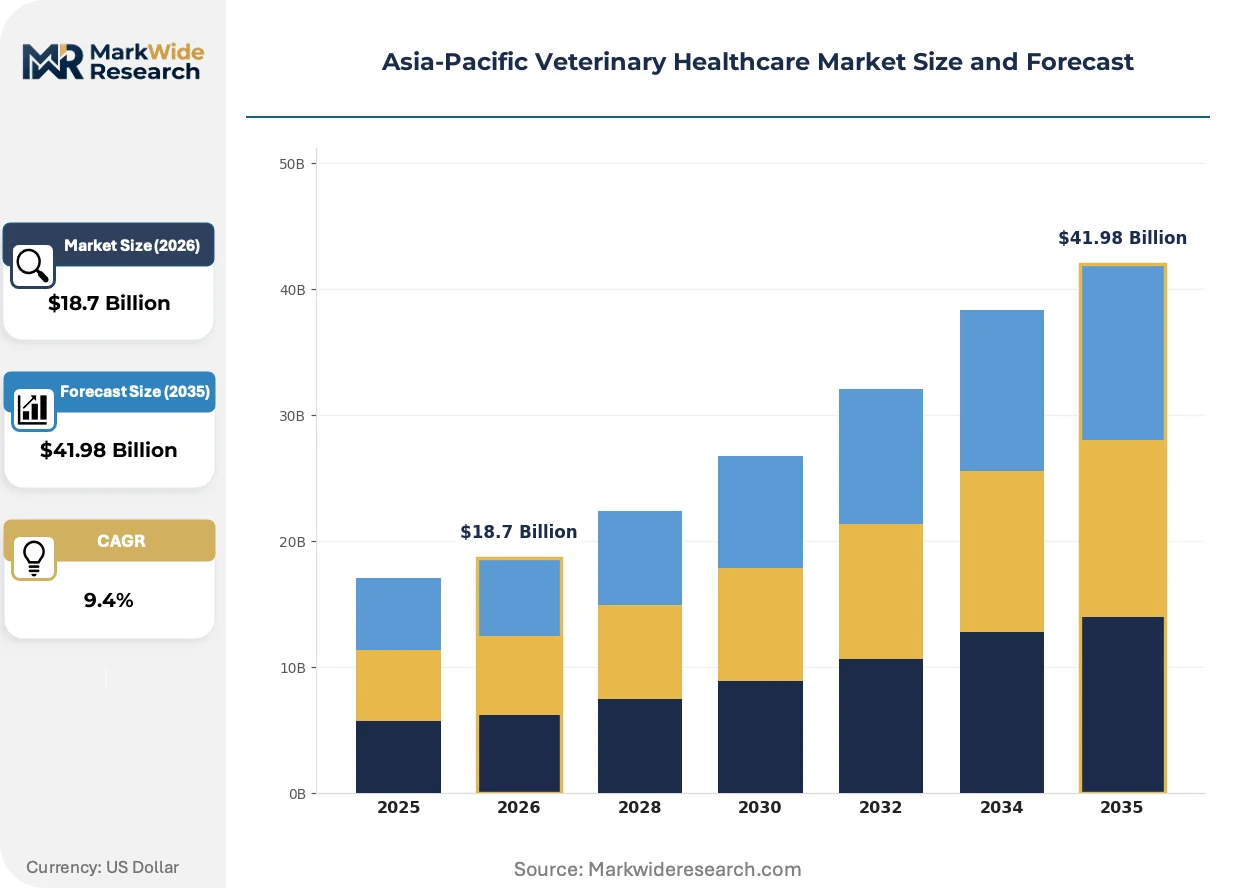
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Pharmaceuticals, Nutraceuticals, Diagnostics Delivery Mode: Injectable, Oral, Topical, Inhalation Animal Type: Companion Animals, Livestock, Aquatic Animals, Exotic Pets End User: Veterinary Hospitals, Clinics, Research Laboratories, Pet Owners |
| Companies Covered | Merck Animal Health, Vetoquinol, Zoetis, IDEXX Laboratories, Virbac, Boehringer Ingelheim, Ceva Santé Animale, Phibro Animal Health, Elanco, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Veterinary Healthcare Market Strategic Shifts
Digital pathology and artificial intelligence are compressing diagnostic turnaround times while regulatory convergence pressures reshape product development roadmaps across the region's fragmented approval landscape.
CRISPR-based pathogen detection platforms is rewriting the economics of veterinary diagnostics by enabling same-day infectious disease identification without centralized laboratory infrastructure. Small-animal practitioners in Japan's Kanto region adopt these systems at accelerating rates. The technology is rewriting referral patterns by capturing cases previously routed to university teaching hospitals.
China's NMPA Good Manufacturing Practice certification requirements for all biological products entering clinical distribution tighten quality benchmarks for imported vaccines. Domestic manufacturers in Suzhou and Hangzhou biotech clusters upgrade mammalian cell culture capabilities to meet these standards. Swine vaccine suppliers face compressed margins as compliance costs rise while price ceilings persist in provincial procurement tenders.
Subscription-based preventive care packages displace episodic treatment billing in South Korea's Seoul metropolitan veterinary market. Pet insurance penetration above forty percent in this corridor enables predictable revenue streams for clinic networks. Bangkok and Singapore practitioners pilot similar models as middle-class pet owners seek cost predictability for chronic disease management in aging companion animals.
Asia-Pacific Veterinary Healthcare Market Segmentation
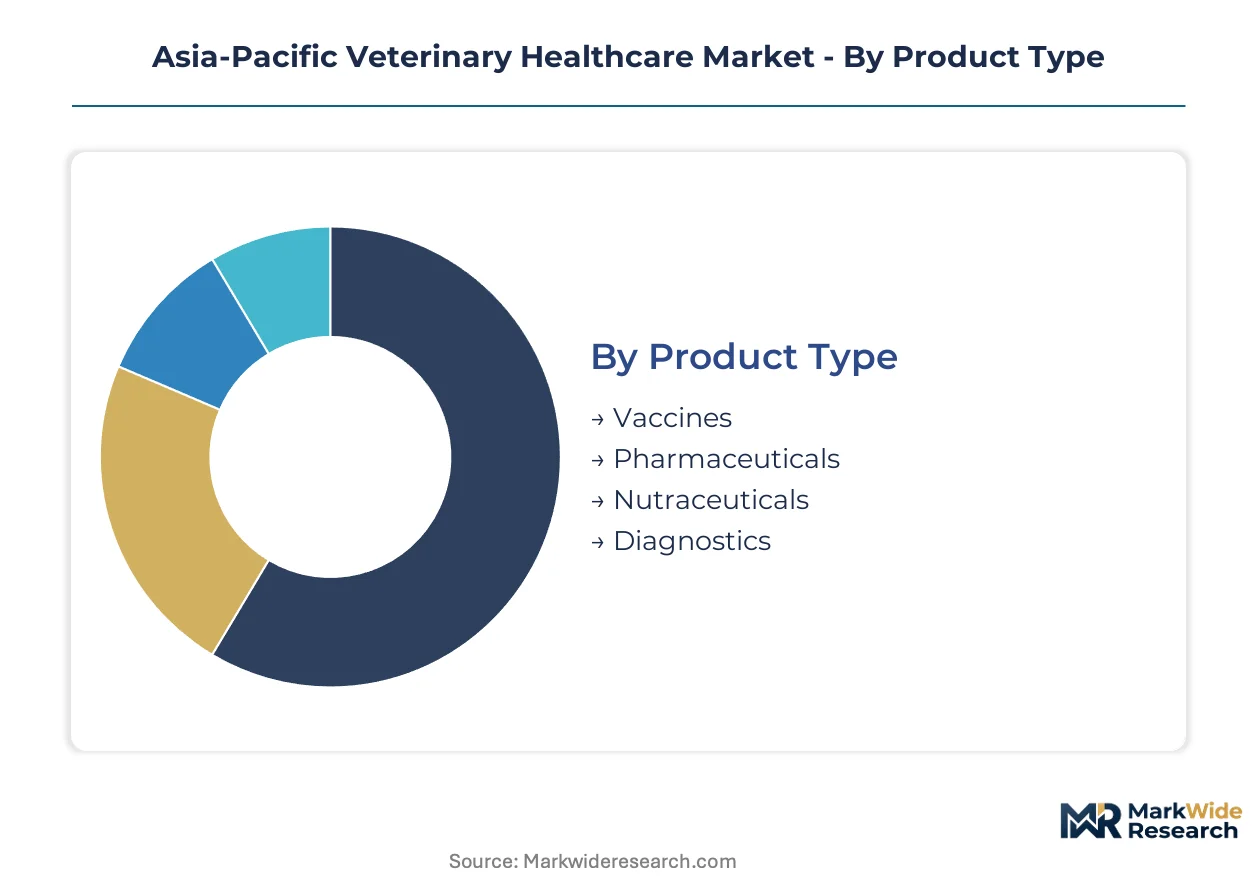
Segmentation in Asia-Pacific veterinary healthcare reveals how regulatory pathways, cold chain requirements, and species-specific disease burdens fragment procurement decisions across national markets. Product type and animal category determine which CDSCO, NMPA, or PMDA certifications suppliers must secure before commercial entry.
Product Type:
Vaccines demand NMPA Good Manufacturing Practice certification for all biological products entering clinical distribution in China, while pharmaceuticals face CDSCO registration mandates under India's Drugs and Cosmetics Act. Recombinant platforms trigger PMDA's separate approval pathway in Japan, extending timelines versus conventional formulations.
- Vaccines:Recombinant and vector-based platforms require mammalian cell culture infrastructure and sustained cold chain maintenance at two to eight degrees Celsius. Demand concentrates in China's Henan and Shandong swine-rearing provinces, where commercial producers procure respiratory disease prevention at scale.
- Pharmaceuticals:Chemically synthesized therapeutics for chronic disease management in aging companion animal populations command the largest revenue pool among product types. Metropolitan veterinary corridors in Tokyo, Seoul, and Sydney drive prescription volumes for dermatological and gastrointestinal conditions.
- Nutraceuticals:Omega fatty acid and probiotic formulations for skin and gut health bypass stringent biologics pathways, accelerating time-to-market in Thailand and Indonesia.
- Diagnostics:Point-of-care imaging and molecular testing platforms displace referral-lab dependency in Japan's Kanto region and Australia's rural territories.
Leading the category by volume: Pharmaceuticals. Growing fastest: Diagnostics.
Delivery Mode:
Route of administration determines distribution infrastructure investments, with temperature-controlled logistics favoring stable formulations over fragile biologicals in Indonesia's outer island veterinary posts.
- Injectable:Parenteral vaccines and therapeutics dominate livestock applications, requiring syringe-needle compliance with national veterinary drug administration standards.
- Oral:Nutraceuticals and antiparasitic formulations suit companion animal compliance, with chewable tablets penetrating Bangkok and Singapore clinic networks.
- Topical:Dermatological parasiticides from Virbac's portfolio sustain channel dominance through veterinary clinic networks in Thailand and Indonesia.
- Inhalation:Respiratory therapeutics for swine and poultry operations in China's commercial farming belts utilize nebulization systems.
Highest margin concentration: Injectable. Steepest expansion trajectory: Oral.
Animal Type:
Species classification splits procurement between urban companion animal service infrastructure and rural livestock volume contracts, with aquaculture pharmaceuticals facing divergent environmental risk assessments across jurisdictions.
- Companion Animals:Aging dog and cat populations in Japan, South Korea, and Australia's metropolitan corridors compress diagnostic-to-treatment cycles while driving oncology and dermatology service demand.
- Livestock:Swine and poultry producers across China's pig-rearing provinces and India's dairy belts sustain preventive vaccine procurement at commercial scale.
- Aquatic Animals:Shrimp and finfish therapeutics encounter regulatory uncertainty on gene-edited environmental risk assessment, fragmenting approval pathways.
- Exotic Pets:Specialized reptile and avian therapeutics concentrate in Singapore and Australia's urban exotic veterinary practices.
Revenue concentration: Companion Animals. Volume throughput: Livestock.
End User:
Customer type determines pricing power and purchasing frequency, with institutional procurement in veterinary hospitals contrasting subscription-based preventive packages emerging in South Korea's clinic networks.
- Veterinary Hospitals:Tertiary referral centers in Tokyo, Seoul, and Sydney concentrate board-certified pathologists and imaging specialists, capturing complex surgical and oncology cases.
- Clinics:Primary care networks in Ho Chi Minh City and Hanoi lack specialized service infrastructure despite rising urban pet ownership.
- Research Laboratories:Contract research organizations in Suzhou and Hangzhou biotech clusters support domestic vaccine manufacturers upgrading mammalian cell culture capabilities.
- Pet Owners:Direct-to-consumer at-home sample collection kits paired with telemedicine platforms reshape first-contact access in Australia's rural territories.
Procurement scale leader: Veterinary Hospitals. Gaining share fastest: Pet Owners through telemedicine convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Companion animal expenditure concentrates in Japan's metropolitan corridors and Australia's coastal cities, while livestock vaccine procurement dominates China's interior provinces and India's dairy belts. This bifurcation shapes divergent regulatory priorities and distribution infrastructure investments across the region.
China
Swine respiratory disease pressure across Henan and Shandong provinces drives commercial-scale vaccine procurement from domestic biotech clusters. NMPA's Good Manufacturing Practice certification requirements for all biological products entering clinical distribution force Suzhou and Hangzhou manufacturers to upgrade mammalian cell culture capabilities. Provincial procurement tenders in these pig-rearing corridors compress margins while enforcing volume commitments.
Japan
Aging dog and cat populations in Tokyo and Osaka metropolitan areas compress diagnostic-to-treatment cycles for oncology and dermatology services. PMDA maintains separate approval pathways for novel recombinant vaccines, extending commercialization timelines relative to conventional platforms. Kanto region veterinarians adopt CRISPR-based pathogen detection at accelerating rates, capturing cases previously routed to university teaching hospitals.
India
Dairy belt operations across Maharashtra and Gujarat sustain preventive therapeutics procurement for livestock productivity. CDSCO mandates veterinary drug registration under the Drugs and Cosmetics Act, compelling formal documentation that expands addressable markets for registered pharmaceutical suppliers. The PLI scheme for pharmaceutical manufacturing attracts contract manufacturing investment for veterinary active ingredients in these western states.
Australia
Telemedicine-diagnostics convergence reshapes first-contact veterinary access across rural territories and outer metropolitan rings. TGA harmonization with APVMA standards creates multi-layered compliance burdens for suppliers accessing both human and agricultural chemical pathways. Sydney and Melbourne concentrate board-certified pathologists and imaging specialists, leaving tier-two cities underserved for complex surgical referrals.
South Korea
Subscription-based preventive care packages displace episodic treatment billing in Seoul's metropolitan veterinary market where pet insurance penetration exceeds forty percent. MFDS regulatory frameworks align with international standards for biological product approval, though domestic manufacturers prioritize companion animal therapeutics over livestock applications. Busan-Ulsan corridor clinics pilot similar subscription models as middle-class pet owners seek cost predictability.
Asia-Pacific Veterinary Healthcare Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers respond to NMPA certification requirements and CDSCO registration mandates. The vendor base consolidates around three tiers: multinational pharmaceutical conglomerates with mammalian cell culture platforms, mid-scale regional specialists in parasiticide formulations, and domestic biotech clusters upgrading fermentation capabilities. Strategic archetypes include premium vaccine suppliers competing on cold chain reliability, formulation specialists dominating channel access through clinic networks, and API manufacturers leveraging India's PLI incentives. M&A activity and geographic licensing agreements represent the dominant competitive moves as firms secure distribution reach across Indonesia's outer islands and Vietnam's underpenetrated urban corridors.
Among mammalian cell culture platform operators, Zoetis anchors premium vaccine supply in Japan and Australia, while Boehringer Ingelheim occupies a position competing on respiratory disease portfolios for swine and poultry. Virbac exemplifies the formulation specialist archetype, sustaining channel dominance through veterinary clinic networks in Thailand and Indonesia where topical parasiticides penetrate at scale.
| Leading Market Players |
|---|
| Merck Animal Health |
| Vetoquinol |
| Zoetis |
| IDEXX Laboratories |
| Virbac |
| Boehringer Ingelheim |
| Ceva Santé Animale |
| Phibro Animal Health |
| Elanco |
| Others |
Value Chain & Pricing Dynamics
NMPA certification tiers versus provincial tender floors bifurcate vaccine economics across China's pig-rearing corridors, compressing margins for domestic manufacturers while rewarding cold-chain reliability premiums in Japan and Australia. This tier divergence manifests in supply chain configurations: Suzhou biotech clusters absorb compliance upgrade costs while Indonesian outer island posts abandon temperature-sensitive biologicals for stable oral formulations.
Pricing Analysis
Volume-throughput livestock contracts in Henan and Shandong provinces trade at razor margins against premium companion animal therapeutics in Tokyo and Seoul metropolitan corridors. Pricing stratifies across NMPA-certified biologics, CDSCO-registered pharmaceuticals, and nutraceuticals bypassing stringent pathways. Provincial procurement tenders in China compress vaccine pricing as compliance costs rise. Smallholder dairy producers across India's Gujarat belt exhibit acute price sensitivity, while insured pet owners in South Korea's Seoul corridor absorb subscription-based preventive packages with minimal friction.
Supply Chain Analysis
Mammalian cell culture specialists cluster in Suzhou and Hangzhou biotech corridors where fermentation engineering talent pools anchor recombinant vaccine production. Active pharmaceutical ingredients for veterinary applications draw from India's Maharashtra and Gujarat manufacturing belts under PLI scheme incentives. Cold chain infrastructure gaps across Indonesia's outer islands create single-source vulnerability for temperature-controlled biologicals. Distribution runs through veterinary hospital networks in tier-one cities, with direct-to-consumer sample collection kits penetrating Australia's rural territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into mammalian cell culture capabilities is reshaping competitive positioning as NMPA certification requirements and PMDA biologics pathways force control over upstream biological production.
For Market Incumbents: Hedge against margin compression in China's provincial tender systems by securing CDSCO registration for Indian API sourcing and deepening cold chain partnerships in Southeast Asia. Channel control through veterinary clinic networks in Thailand and Indonesia defends parasiticide formulation share against generic entrants. Certification investment in NMPA Good Manufacturing Practice upgrades sustains access to Henan and Shandong livestock volume contracts. For New Entrants and Emerging Players: CRISPR-based pathogen detection platforms offer technology-first entry into Japan's Kanto region where same-day diagnostics capture cases from university teaching hospitals. Vietnam's Ho Chi Minh City and Hanoi corridors present white-space opportunity in specialized oncology and dermatology service infrastructure for aging companion animals. Telemedicine-at-home sample collection convergence in Australia's rural territories enables direct-to-consumer go-to-market bypassing established clinic networks. For Investors and Strategic Acquirers: Re-rating potential sits with domestic biotech clusters possessing mammalian cell culture capabilities given NMPA's tightening certification requirements for biological products. Acquisition targets include Suzhou and Hangzhou manufacturers upgrading fermentation infrastructure to meet Good Manufacturing Practice standards. Watch provincial procurement tender participation rates as inflection indicator for sustainable margin recovery in China's swine vaccine segment.| Strategic Initiative | Industry Significance |
|---|---|
| Mammalian Cell Culture Scale-Up | NMPA certification compliance anchors market access for recombinant vaccine suppliers in China. |
| CDSCO Registration Investment | Formal documentation under India's Drugs and Cosmetics Act expands addressable pharmaceutical markets. |
| Cold Chain Partnership Expansion | Two-to-eight-degree Celsius logistics penetration reaches Indonesia's outer island veterinary posts. |
| Telemedicine Platform Integration | Remote consultation paired with at-home sampling reshapes first-contact access in Australia's rural territories. |
| Subscription Preventive Care Launch | Cost predictability models displace episodic billing in South Korea's insured pet owner corridors. |
Study Parameters
Regulatory filing databases, veterinary pharmaceutical trade publications, and CDSCO registration records formed the secondary backbone, cross-referenced against primary interviews with drug development executives, regulatory affairs leads at multinational animal health firms, veterinary clinic network procurement managers, and dairy cooperative therapeutics buyers. Bottom-up and top-down triangulation validated segment-level estimates across product type, animal category, and national regulatory clusters.
Bottom-up modeling aggregated species-specific disease burden data, treatment penetration rates, and pricing benchmarks by certification tier, while top-down approaches cross-checked against national veterinary expenditure surveys and pharmaceutical production statistics. Segmentation dimensions included product type, delivery mode, animal category, and end-user channel structure across the analysis window. CAGRs derived from regression analysis of historical procurement patterns and regulatory timeline acceleration effects.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt NMPA certification enforcement shifts or PMDA pathway duration extensions. Assumptions reflect current regulatory trajectories for gene-edited therapeutics and environmental risk assessments. Material deviation in provincial tender participation rates or cold chain infrastructure investment flows warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
Veterinary Thermography Market
Veterinary
Vet Software Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Global Animal Vaccine Market
Veterinary
CBD Pet Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Global Cattle Vaccines Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Mastitis Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Veterinary Wound Sprays Market