
 Germany Veterinary Healthcare Market | 2026-2036
Germany Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Veterinary Healthcare Market Foresight
Market Dynamics
Veterinary specialist labor availability is collapsing across rural German districts, forcing clinics to consolidate and automate diagnostic workflows. Boehringer Ingelheim leverages its Mannheim manufacturing base to sustain vaccine output for bovine and porcine segments. Zoetis dominates companion animal therapeutics through direct veterinary channel partnerships. Merck competes in diagnostic equipment through its alliance with regional laboratory networks.
Segment Structure
Veterinary healthcare encompasses preventive, curative, and diagnostic services and products administered to livestock, companion animals, and exotic species, with biologics requiring cold-chain distribution at two-to-eight degrees Celsius to preserve efficacy. The sector serves agricultural productivity, food safety assurance, and pet longevity objectives across German federal states. Vaccines command the largest product-type revenue pool given mandatory livestock immunization schedules, while nutritional supplements represent the fastest-expanding category as pet owners shift toward preventive wellness. Diagnostic equipment concentrates margin in university-adjacent equine centers and large dairy operations that justify capital investment in imaging and laboratory systems.
Regulatory Environment
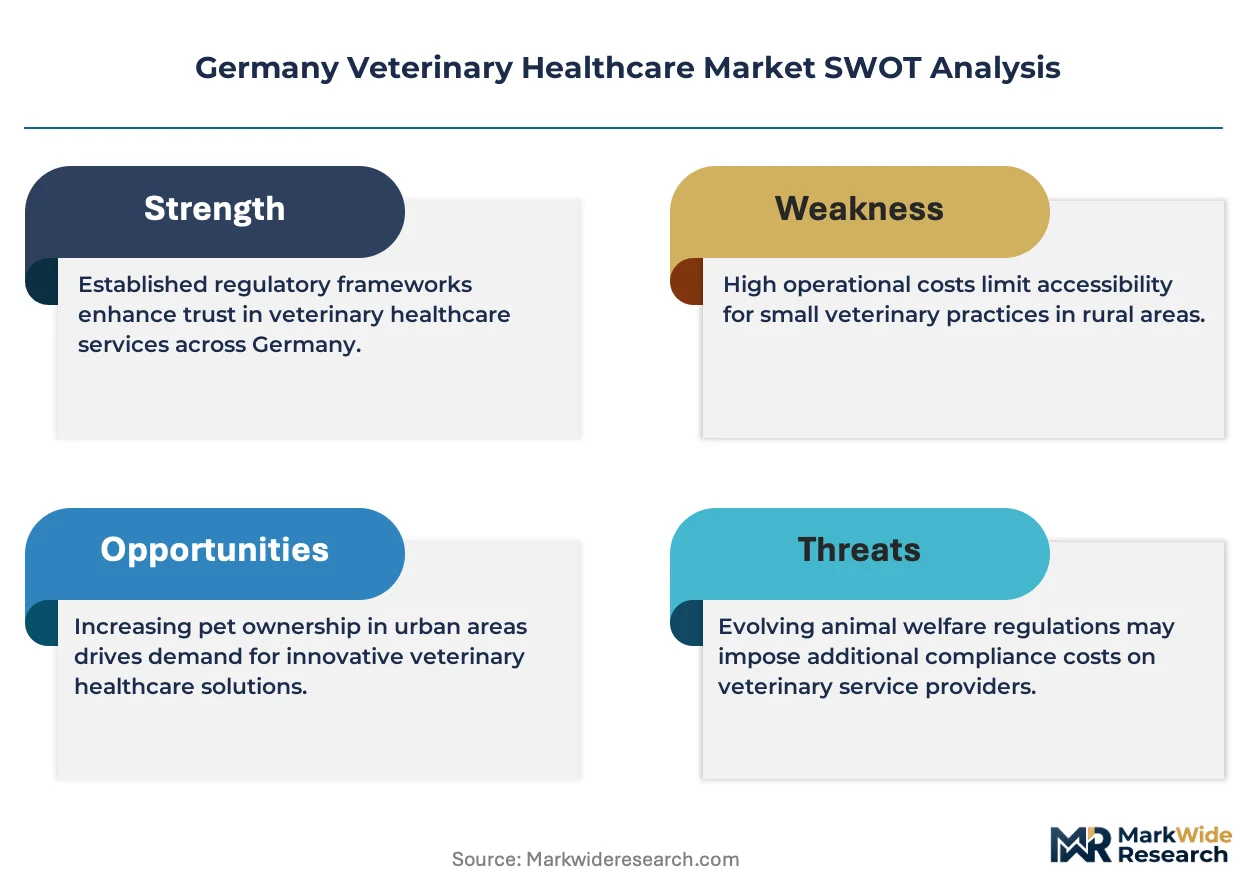
The EU Veterinary Medicines Regulation and Germany's Federal Ministry of Food and Agriculture enforce antimicrobial stewardship standards that restrict antibiotic prophylaxis and elevate vaccine demand. KBA-adjacent state veterinary offices in Bavaria and Lower Saxony conduct residue monitoring that shapes product registration and clinic procurement compliance. Stakeholders must monitor implementation timelines for the EU Green Deal's farm-to-fork targets, which will tighten animal welfare benchmarks and redirect investment toward precision livestock monitoring technologies.
Market Dynamics
EU Veterinary Medicines Regulation enforcement is compressing antibiotic prophylaxis across German livestock operations while accelerating cold-chain vaccine infrastructure investment in Bavaria and Lower Saxony dairy clusters.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Tightening animal welfare benchmarks in Germany redirect capital toward precision livestock monitoring systems and automated health tracking.
- Companion animal longevity demand:Pet owners in urban centers like Munich and Hamburg prioritize preventive wellness services and nutritional supplementation over reactive treatment.
- Mandatory livestock immunization schedules:KBA-adjacent state veterinary offices sustain recurring vaccine procurement volumes across North Rhine-Westphalia's dense cattle operations.
Market Restraints
- Veterinary specialist labor scarcity:Rural districts in eastern Germany face collapsing clinician availability, forcing clinic consolidation and service rationing.
- Cold-chain distribution cost concentration:Biologics requiring two-to-eight degrees Celsius preservation elevate logistics expenditure for peripheral veterinary networks.
- Antimicrobial residue monitoring intensity:KBA state veterinary offices impose compliance burdens that slow product registration timelines for novel therapeutics.
Strategic Opportunities
- Diagnostic equipment penetration in equine centers:University-adjacent facilities in Lower Saxony justify capital investment in imaging and laboratory automation.
- Veterinary channel direct partnerships:Companion animal therapeutics distribution bypasses wholesale intermediaries through clinic-exclusive supply agreements.
- EU AI Act veterinary application frameworks:Regulatory clarity on algorithmic diagnostic tools creates white space for machine-learning-enabled pathology systems.
Industry Challenges
- Diagnostic workflow automation integration:Consolidating rural clinics struggle to harmonize legacy record systems with new laboratory information management platforms.
- Biologics handling certification timelines:Cold-chain competency requirements delay staff deployment and constrain service expansion in understaffed regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Veterinary Healthcare Market |
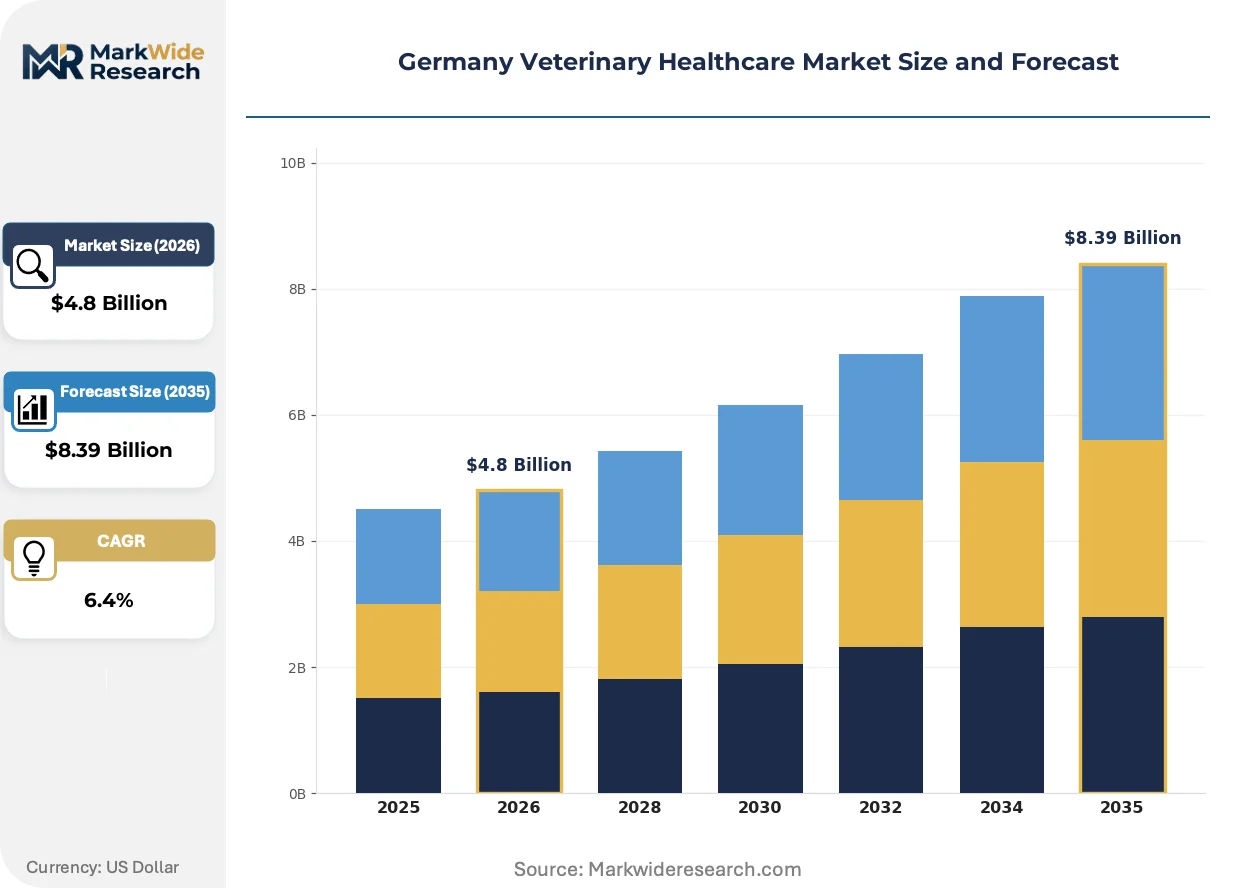
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Nutritional Supplements, Diagnostic Equipment, Surgical Instruments Therapy Area: Infectious Diseases, Parasitic Infestations, Reproductive Disorders, Musculoskeletal Conditions, Dermatological Issues End User: Veterinary Clinics, Animal Shelters, Research Facilities, Equine Centers, Zoos Distribution Channel: Veterinary Pharmacies, Online Retailers, Direct Sales, Agricultural Cooperatives, Specialty Distributors |
| Companies Covered | Merck, IDEXX Laboratories, Zoetis, Virbac, Vetoquinol, Boehringer Ingelheim, Ceva, Phibro Animal Health, Elanco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Veterinary Healthcare Market Shifts & Advancements
Digital pathology and remote monitoring systems are restructuring how German veterinary practices deliver preventive care, compressing diagnostic turnaround times while redistributing expertise across fragmented geographic networks.
Point-of-care molecular diagnostics is displacing centralized laboratory referral for bovine respiratory pathogen detection. Large dairy cooperatives in Bavaria deploy portable PCR systems directly at farm sites. This decentralization is displacing traditional veterinary clinic revenue models built on sample transport and external lab markups.
The EU Veterinary Medicines Regulation's antimicrobial stewardship mandates force German livestock producers to document treatment justification through prescription registries. KBA state offices audit compliance through residue surveillance programs. Vaccine substitution protocols now dominate procurement conversations in North Rhine-Westphalia's pig and cattle sectors.
Pet owner subscription models for preventive wellness are restructuring companion animal service delivery in Berlin and Frankfurt metropolitan areas. Traditional fee-for-service billing loses share to monthly health plans bundling vaccinations, dental cleaning, and nutritional counseling. Urban veterinary groups capture recurring revenue streams while locking in client retention against independent clinic competition.
Germany Veterinary Healthcare Market Segmentation
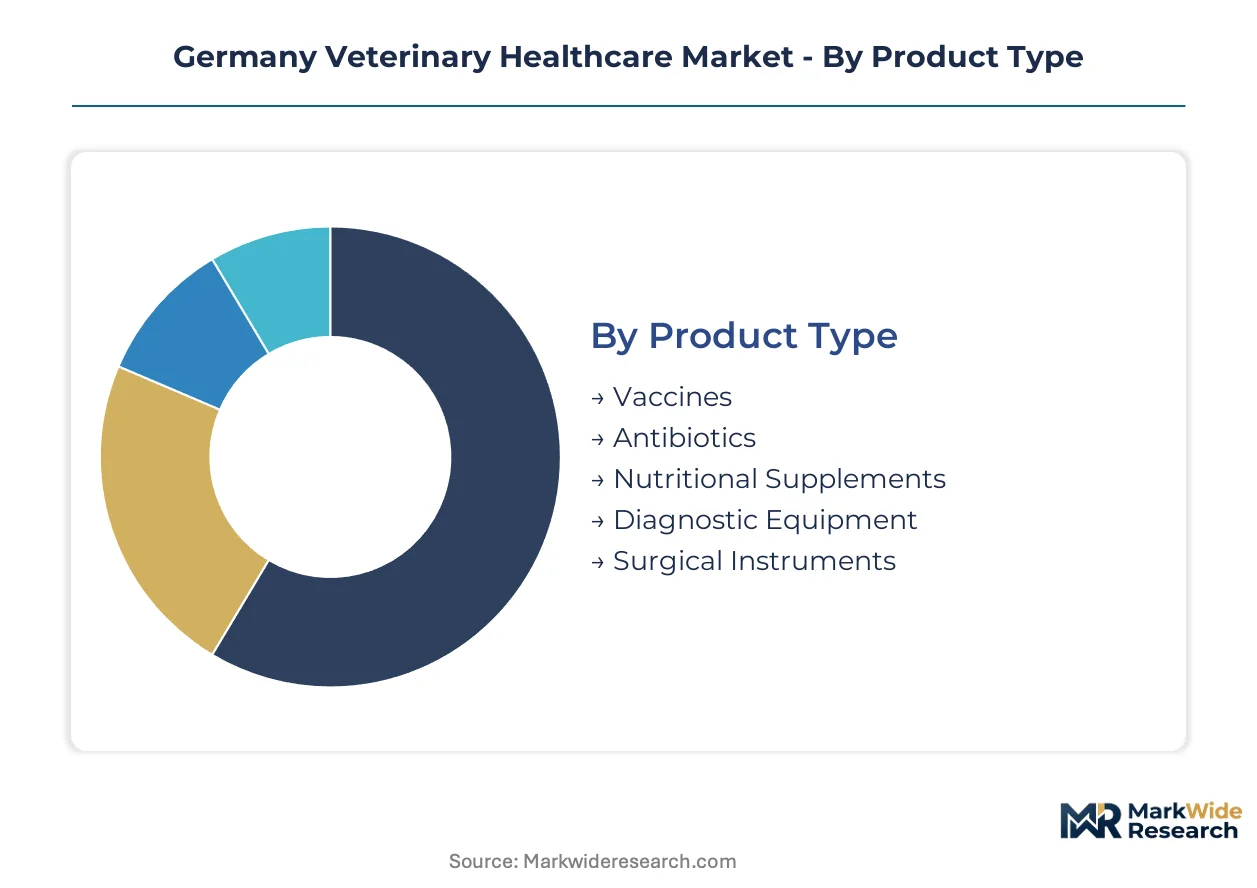
Veterinary healthcare procurement patterns in Germany diverge sharply across product categories and end-use settings. Livestock operations prioritize bulk vaccine contracts and residue-compliant therapeutics, while companion animal clinics concentrate spending on diagnostic equipment and preventive wellness services.
Product Type:
Margin pools concentrate in cold-chain biologics and capital-intensive diagnostic systems, where regulatory compliance barriers protect pricing power.
- Vaccines:Live-attenuated and inactivated formulations for bovine, porcine, and companion animal indications require continuous two-to-eight degrees Celsius distribution. Bavarian dairy cooperatives and North Rhine-Westphalia pig producers sustain procurement volumes through mandatory immunization schedules enforced by KBA-adjacent state veterinary offices.
- Diagnostic Equipment:Imaging systems, portable PCR platforms, and laboratory automation tools command premium pricing in university-adjacent equine centers and large dairy operations. Lower Saxony veterinary networks justify capital investment through high-throughput sample processing and reduced external laboratory dependency.
- Antibiotics:Therapeutic use restrictions under EU Veterinary Medicines Regulation compress prophylactic prescribing, shifting demand toward narrow-spectrum alternatives with documented treatment justification.
- Nutritional Supplements:Preventive wellness positioning captures urban pet owner spending in Munich and Hamburg metropolitan markets, with subscription bundling replacing transactional purchasing.
- Surgical Instruments:Specialty consumables and sterilization equipment serve clinic consolidation trends, with procurement centralizing through group purchasing organizations in dense veterinary networks.
The dominant share belongs to Vaccines, while Nutritional Supplements is closing the gap fastest.
Therapy Area:
Volume concentration tracks livestock epidemiology in northern federal states and companion animal demographics in urban centers.
- Infectious Diseases:Bovine respiratory pathogens and porcine viral infections drive systematic vaccination protocols. Residue monitoring intensity from KBA state offices shapes therapeutic decision-making across North Rhine-Westphalia's dense cattle operations.
- Parasitic Infestations:Endoparasite control in grazing livestock and ectoparasite management in companion animals sustain recurring pharmaceutical demand, with resistance surveillance guiding product rotation.
- Reproductive Disorders:Dairy herd fertility management and equine breeding programs concentrate specialized veterinary labor in Lower Saxony and Bavaria.
- Musculoskeletal Conditions:Equine performance medicine and canine orthopedic surgery generate procedural revenue in university-adjacent referral hospitals.
- Dermatological Issues:Allergy testing and chronic skin condition management support diagnostic laboratory throughput in Berlin and Frankfurt urban clinics.
Infectious Diseases retains the largest addressable base, though Musculoskeletal Conditions is expanding most quickly through specialty referral centralization.
End User:
Customer-type differentiation separates high-volume agricultural procurement from premium companion animal service delivery.
- Veterinary Clinics:Mixed-animal practices in rural eastern Germany face consolidation pressure from labor scarcity, while urban small-animal hospitals in Munich capture preventive wellness subscription revenue.
- Equine Centers:University-adjacent facilities in Lower Saxony justify imaging capital expenditure through referral networks and performance horse clientele.
- Animal Shelters:Municipal and nonprofit operations concentrate sterilization and basic immunization demand, with procurement constrained by public budget cycles.
- Research Facilities:Pharmaceutical development and toxicology studies sustain specialized pathogen-free animal supply and diagnostic service contracts.
- Zoos:Exotic species veterinary requirements drive niche pharmaceutical procurement and specialist consultation arrangements.
Veterinary Clinics command the dominant procurement volume, with Equine Centers showing the steepest expansion trajectory through capital investment in diagnostic capabilities.
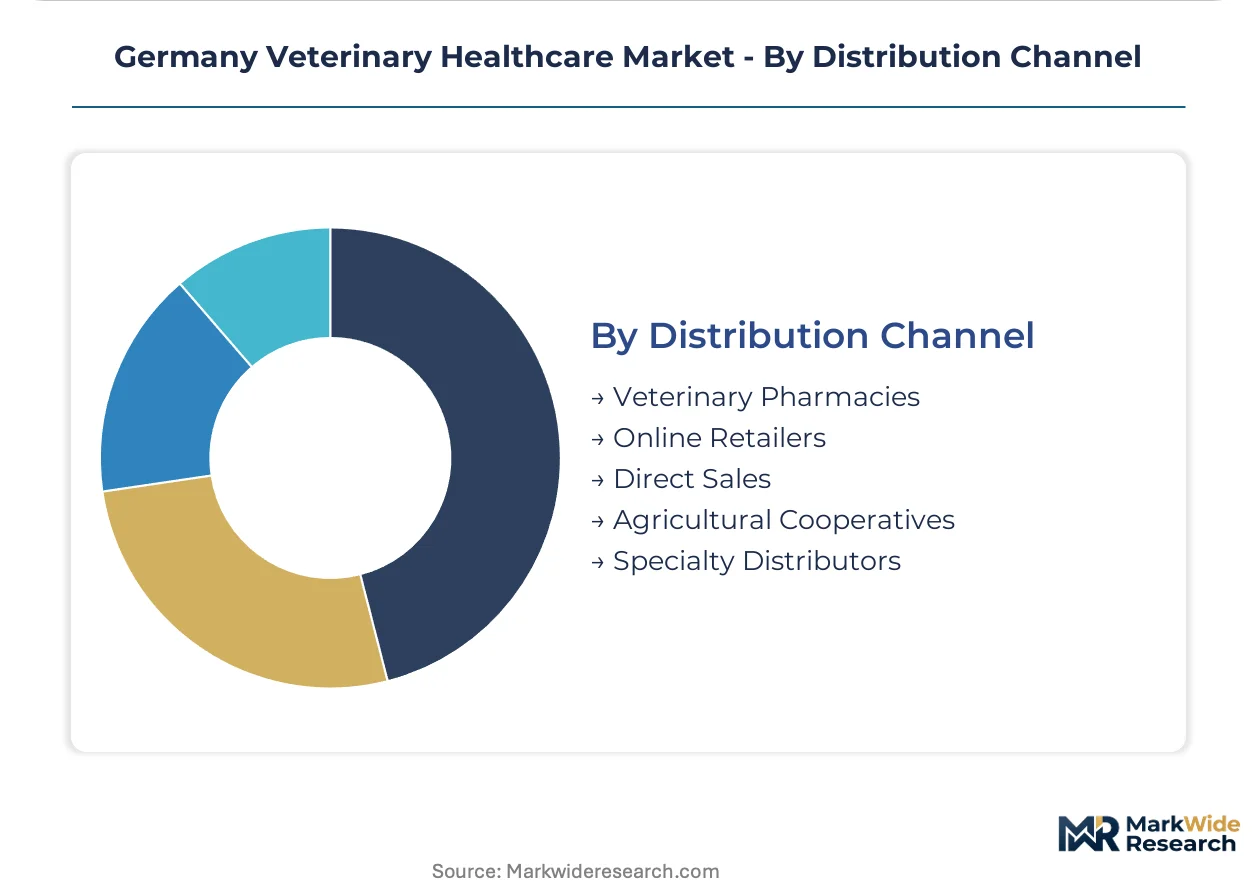
Distribution Channel:
Channel economics reflect cold-chain handling requirements and customer relationship intensity across livestock and companion animal segments.
- Veterinary Pharmacies:Federally licensed dispensaries adjacent to clinic operations capture prescription fulfillment and nutritional supplement sales with regulatory compliance integration.
- Direct Sales:Manufacturer-to-clinic arrangements for vaccines and therapeutics bypass wholesale markups, with Boehringer Ingelheim leveraging Mannheim manufacturing proximity for Bavarian dairy network supply.
- Online Retailers:Nutritional supplements and non-prescription wellness products face channel conflict with clinic-exclusive distribution agreements.
- Agricultural Cooperatives:Bulk vaccine procurement and herd health program administration concentrate purchasing power for North Rhine-Westphalia and Lower Saxony livestock producers.
- Specialty Distributors:Cold-chain logistics providers serve peripheral veterinary networks with biologics handling certification and temperature-validated delivery infrastructure.
Veterinary Pharmacies hold the largest channel share, though Direct Sales is gaining ground fastest through manufacturer consolidation of clinic relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA-adjacent state veterinary offices in Bavaria and Lower Saxony anchor procurement compliance frameworks that cascade through federal veterinary networks. Procurement volumes concentrate where dairy herd density intersects with diagnostic infrastructure investment.
Bavaria
Dairy cooperatives sustain bulk vaccine procurement through mandatory bovine immunization schedules enforced by Munich-adjacent state veterinary offices. The EU Veterinary Medicines Regulation's antimicrobial stewardship standards redirect investment toward cold-chain biologics distribution. Mannheim manufacturing proximity supports just-in-time vaccine delivery to Upper Bavaria's dense cattle operations.
North Rhine-Westphalia
Pig and cattle producers face compressed antibiotic prophylaxis windows under tightened residue monitoring protocols. KBA state offices audit treatment justification through prescription registries that shape therapeutic decision-making. The Ruhr veterinary clinic network consolidates procurement through group purchasing organizations serving mixed-animal practices.
Lower Saxony
University-adjacent equine centers justify capital expenditure in imaging systems and laboratory automation tools. The Hannover veterinary school anchors referral networks that concentrate specialized reproductive disorder treatment. Precision livestock monitoring technologies penetrate dairy operations around Oldenburg through EU Green Deal farm-to-fork implementation funding.
Baden-Württemberg
Stuttgart metropolitan pet owners drive preventive wellness subscription models that displace traditional fee-for-service billing. Nutritional supplement demand concentrates in urban small-animal hospitals capturing recurring revenue streams. The state's pharmaceutical manufacturing base supports regional diagnostic equipment supply chains.
Berlin-Brandenburg
Municipal animal shelters concentrate sterilization and basic immunization demand constrained by public budget cycles. Research facilities sustain specialized pathogen-free animal supply contracts for pharmaceutical development. The capital's veterinary labor pool attracts diagnostic workflow automation vendors targeting clinic consolidation trends.
Germany Veterinary Healthcare Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with manufacturer-to-clinic direct sales displacing wholesale intermediaries in vaccine and therapeutic distribution. Boehringer Ingelheim leverages captive manufacturing proximity to Bavarian dairy networks, while Zoetis anchors companion animal channel partnerships. Three archetypes dominate: vertically integrated biologics manufacturers, diagnostic equipment specialists, and veterinary pharmacy consolidators. Competitive moves concentrate on clinic-exclusive supply agreements and cold-chain logistics certification to capture peripheral network penetration.
Within the integrated biologics tier, Boehringer Ingelheim represents the manufacturing-proximity archetype through its Mannheim base serving southern German livestock clusters. Zoetis occupies the companion animal therapeutics position through direct veterinary channel relationships. Merck sits within the diagnostic equipment specialist archetype via regional laboratory network alliances. IDEXX Laboratories exemplifies the point-of-care molecular diagnostics trajectory displacing centralized laboratory referral. These anchors illustrate how procurement centralization and cold-chain competency requirements reshape competitive positioning across federal veterinary networks.
| Leading Market Players |
|---|
| Merck |
| IDEXX Laboratories |
| Zoetis |
| Virbac |
| Vetoquinol |
| Boehringer Ingelheim |
| Ceva |
| Phibro Animal Health |
| Elanco |
| Others |
Supply & Pricing Matrix
Long-term vaccine procurement contracts with KBA-adjacent state veterinary offices lock in supply access and price visibility for Bavarian dairy cooperatives and North Rhine-Westphalia livestock producers. These multi-year agreements insulate bulk buyers from spot-market volatility in cold-chain biologics while compressing margins for peripheral veterinary networks lacking procurement scale.
Pricing Analysis
Bavaria commands premium pricing for diagnostic equipment compared to eastern German rural districts where clinic consolidation forces fee compression. Pricing stratifies across premium, standard, and economy tiers based on cold-chain certification grade and after-sales service bundling. Cost compression in the antibiotics segment is intensifying because EU Veterinary Medicines Regulation restrictions eliminate prophylactic prescribing revenue. Small-animal urban clinics show least price sensitivity due to preventive wellness subscription models, while municipal animal shelters face acute budget constraints.
Supply Chain Analysis
Just-in-time vaccine delivery dominates Bavarian dairy procurement through Mannheim manufacturing proximity, while strategic stockpiling persists for exotic species therapeutics serving zoos and research facilities. Domestic German production anchors cold-chain biologics supply, with supplemental inputs drawn from Netherlands-based pharmaceutical packaging and Danish veterinary diagnostic component manufacturing. Single-source vulnerability concentrates in mRNA vaccine substrate supply. Distribution runs through federally licensed veterinary pharmacies integrated with clinic operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vaccine substitution protocols under EU antimicrobial stewardship mandates threaten incumbent antibiotic portfolios, requiring defensive repositioning toward preventive biologics and precision livestock monitoring systems.
For Market Incumbents: Secure cold-chain logistics certification for peripheral network penetration before regional competitors consolidate clinic relationships. Anchor backward integration into diagnostic equipment manufacturing to capture margin pools shifting from therapeutics toward imaging and laboratory automation. Defend against point-of-care molecular diagnostics displacement by embedding subscription service models in large dairy cooperative contracts. For New Entrants and Emerging Players: Differentiate on AI-enabled pathology algorithms awaiting EU AI Act veterinary application clarity. Target eastern German rural districts where veterinary specialist labor scarcity has forced service rationing and created white-space for remote diagnostic platforms. Enter through agricultural cooperative channel partnerships rather than clinic-direct sales to bypass entrenched manufacturer relationships. For Investors and Strategic Acquirers: Capital is best deployed toward diagnostic equipment specialists with university-adjacent equine center installed bases and laboratory automation capabilities. Long-term viability hinges on precision livestock monitoring technology adoption curves across northern federal states. Watch KBA state office procurement compliance enforcement intensity as the inflection signal for vaccine contract renewal velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Logistics Certification | KBA-compliant temperature-validated distribution unlocks peripheral veterinary network access in understaffed eastern districts. |
| Diagnostic Equipment Manufacturing Scale-Up | Portable PCR platform production captures point-of-care molecular diagnostics demand displacing centralized laboratory referral. |
| Preventive Wellness Subscription Launch | Monthly health plan bundling locks client retention against independent clinic competition in Berlin and Frankfurt metropolitan areas. |
| Precision Livestock Monitoring Partnership | EU Green Deal farm-to-fork implementation funding accelerates automated health tracking adoption in Lower Saxony dairy operations. |
| Veterinary Channel Direct Consolidation | Manufacturer-to-clinic exclusive supply agreements bypass wholesale intermediaries and capture vaccine procurement centralization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with veterinary clinic directors, agricultural cooperative procurement managers, KBA state veterinary office compliance officers, and pharmaceutical regulatory affairs leads; and secondary validation through EU Veterinary Medicines Regulation implementation timelines, German Federal Ministry of Food and Agriculture policy documents, and livestock herd health program databases. Bottom-up clinic procurement pattern analysis triangulated against top-down federal state veterinary network capacity assessments.
Across the analysis window, forecasts model product type segmentation by cold-chain handling requirements, therapy area concentration by livestock epidemiology patterns, end user differentiation between agricultural and companion animal settings, and distribution channel evolution by regulatory compliance integration depth. CAGRs derive from procurement volume trajectories in mandatory immunization schedules and diagnostic equipment replacement cycles calibrated against veterinary labor availability constraints.
The analysis sits within stated boundaries; outcomes outside EU Green Deal farm-to-fork target adherence or KBA residue monitoring protocol stability would require recalibration. Forecasts reflect assumptions about antimicrobial stewardship enforcement continuity and cold-chain infrastructure investment flows. Revision becomes warranted when veterinary specialist labor scarcity crosses thresholds that trigger clinic consolidation acceleration beyond modeled rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Canine Atopic Dermatitis Market
Veterinary
Companion Animal Vaccines Market
Veterinary
Global Veterinary Point of Care Market
Veterinary
Veterinary Disinfectants Market
Veterinary
Global Swine Vaccines Market
Veterinary
Global Veterinary Electrosurgery Market
Veterinary
Global Pet Obesity Management Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Veterinary Anesthesia Drugs Market
Veterinary
Veterinary Progesterone Testing Market
Veterinary
Veterinary Scales Market
Veterinary
Global Veterinary MRI Market
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market