
 North America and Europe Veterinary Telehealth Market | 2026-2036
North America and Europe Veterinary Telehealth Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Veterinary Telehealth Market Intelligence
Subscription-based leasing of telehealth infrastructure is fragmenting competitive barriers, allowing smaller veterinary groups to deploy digital consultation tools without capital-intensive IT buildouts. Vetster leverages a marketplace model that connects independent veterinarians directly to pet owners, sustaining low fixed-cost expansion across North American metro corridors. FirstVet anchors its position through partnerships with major pet insurers, embedding telehealth access within policy benefits. Airvet differentiates by targeting employer wellness programs, offering corporate pet benefits as a channel into high-volume user acquisition.
Veterinary telehealth encompasses remote delivery of animal health services through synchronous video, asynchronous messaging, and connected diagnostic peripherals, with platforms typically requiring minimum bandwidth thresholds of 1.5 Mbps for real-time dermoscopy and otoscopy feeds. The primary commercial purpose centers on triaging presenting complaints, extending the reach of credentialed veterinarians beyond physical clinic boundaries, and reducing non-emergency caseload burdens on brick-and-mortar practices. Consultation services currently dominate transaction volumes while remote monitoring via wearable biometrics represents the fastest-growing technology segment as continuous glucose monitors and activity trackers for companion animals achieve greater accuracy. Mobile platforms capture disproportionate user engagement compared to web portals, reflecting pet owner preference for on-demand, appointment-free interactions.
Telehealth prescribing rules from the FDA and state veterinary medical boards in the United States create a patchwork compliance environment that platforms must navigate to enable prescription fulfillment, while the EU's Veterinary Medicines Regulation and national telemedicine frameworks across France, Germany, and the United Kingdom establish divergent standards for remote diagnosis and treatment authorization. The European Medicines Agency's ongoing harmonization efforts could streamline cross-border platform operations but remain incomplete. Stakeholders must monitor regulatory divergence between American state-level veterinary practice acts and emerging EU-wide digital health credentials, as compliance architecture will determine which platforms can scale across jurisdictions without operational fragmentation.
Market Dynamics
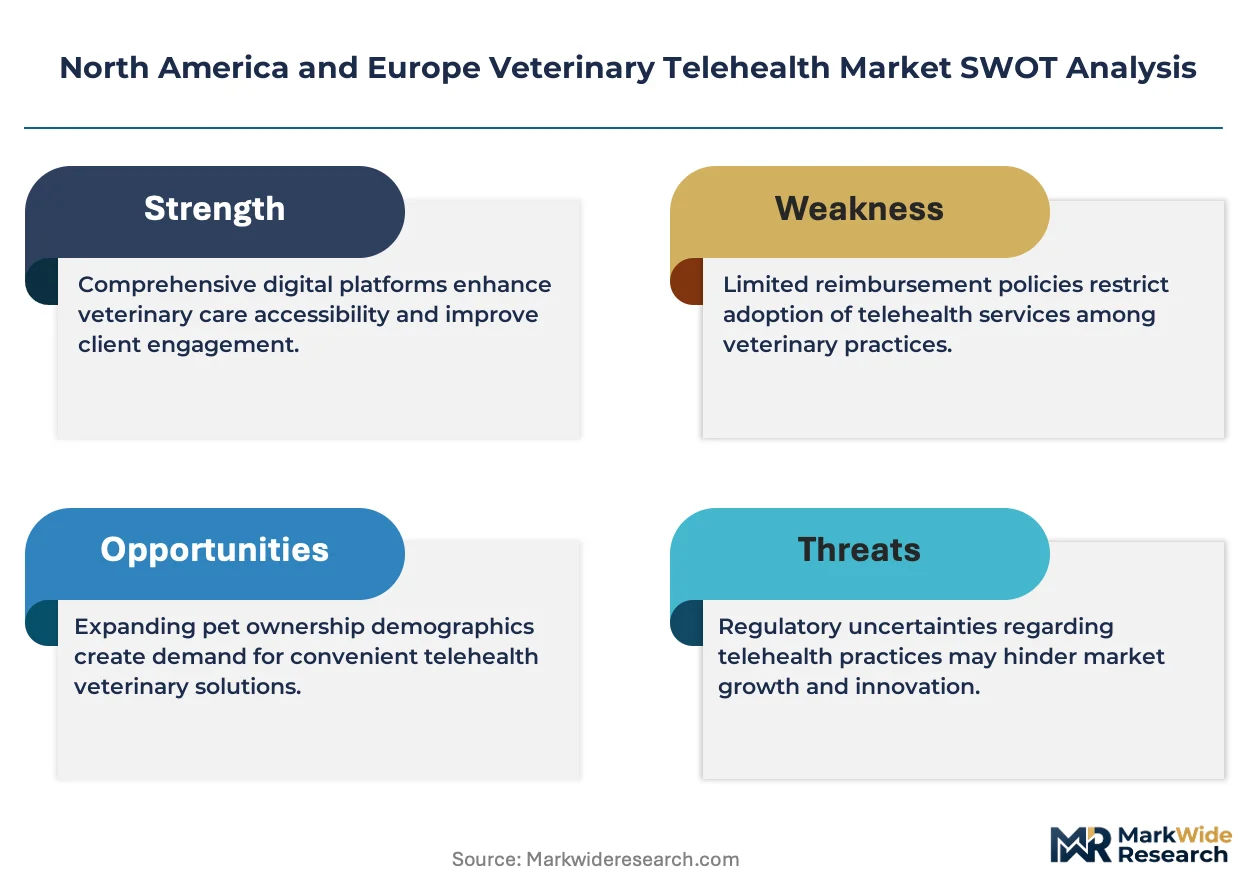
The FDA's loosening guidance on veterinary telemedicine prescribing authority is restructuring competitive access rules across the United States, while workforce shortages in the United Kingdom compress platform adoption timelines. These regulatory and labor dynamics are redistributing market power toward infrastructure-light service models.
Growth Catalysts
- Subscription-based infrastructure leasing:Smaller veterinary groups deploy digital consultation tools without capital-intensive IT buildouts, fragmenting competitive barriers across suburban and rural communities.
- EMA harmonization efforts:The European Medicines Agency's ongoing work could streamline cross-border platform operations, reducing operational fragmentation for multi-jurisdictional providers.
- Wearable biometrics accuracy gains:Continuous glucose monitors and activity trackers for companion animals achieve greater diagnostic reliability, accelerating remote monitoring adoption.
Market Restraints
- State-level veterinary practice act fragmentation:The patchwork of FDA and state veterinary medical board telehealth prescribing rules creates compliance complexity that limits prescription fulfillment capabilities.
- Minimum bandwidth thresholds:Real-time dermoscopy and otoscopy feeds require 1.5 Mbps connectivity, excluding underserved rural areas with poor telecommunications infrastructure.
- Divergent EU national frameworks:France, Germany, and the United Kingdom maintain separate standards for remote diagnosis and treatment authorization, complicating platform scaling.
Strategic Opportunities
- Employer wellness program channel:Corporate pet benefits represent an underpenetrated acquisition vector into high-volume user pools within North American metropolitan corridors.
- Pet insurer partnership embedding:Telehealth access integration within policy benefits creates sticky distribution relationships and reduces customer acquisition costs.
- Mobile-first platform optimization:Pet owner preference for on-demand, appointment-free interactions via mobile devices exceeds current web portal engagement, signaling interface investment priorities.
Industry Challenges
- Credentialed veterinarian supply constraints:United Kingdom veterinary workforce shortages limit platform capacity expansion despite accelerating demand concentration.
- Cross-jurisdiction compliance architecture:Platforms must build separate operational frameworks for American state-level veterinary practice acts versus emerging EU-wide digital health credentials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Veterinary Telehealth Market |
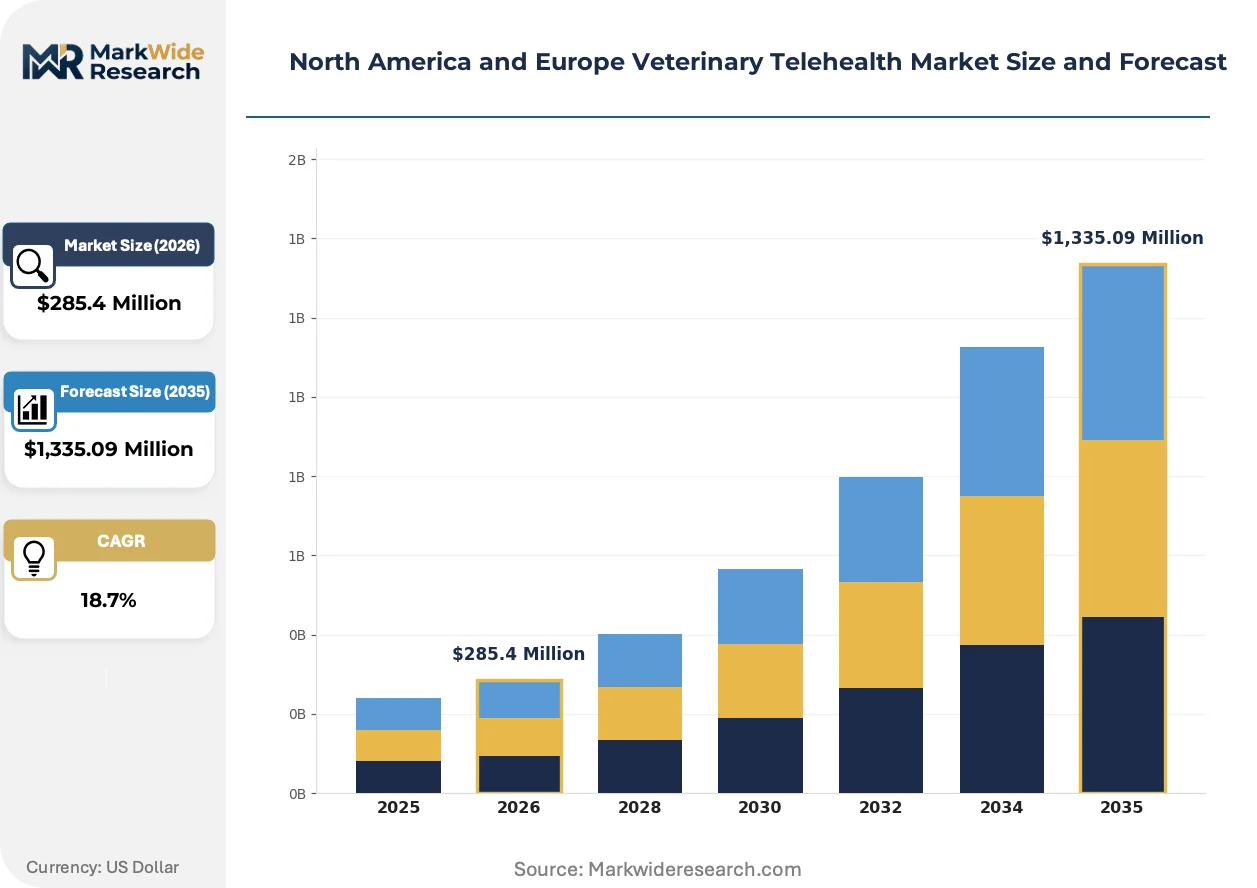
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,335.09 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation, Diagnosis, Follow-Up, Prevention End User: Pet Owners, Veterinary Clinics, Animal Hospitals, Shelters Technology: Video Conferencing, Chat Applications, Remote Monitoring, Mobile Platforms Delivery Mode: Online Platforms, Mobile Apps, Call Centers, Web Portals |
| Companies Covered | Petzam, BabelBark, FirstVet, Vetster, Airvet, PawSquad, Whiskers Worldwide, TeleVet, Vets Now, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Veterinary Telehealth Market Strategic Shifts & Innovations
Platform architecture is pivoting toward asynchronous messaging and connected diagnostic peripherals, compressing the traditional synchronous video consultation model. This technological reconfiguration is redistributing value toward infrastructure providers and away from appointment-based service delivery.
Connected diagnostic peripherals for remote dermoscopy and otoscopy are collapsing the distance between suburban pet owners and specialist-level visual assessment. Rural and ex-urban veterinarians adopt these tools fastest, recognizing their capacity to retain cases that previously required metropolitan referral. The technology is collapsing the geographic monopoly of specialty practices on complex dermatological and otological evaluations.
The FDA's evolving guidance on telemedicine prescribing authority is loosening operational constraints for asynchronous consultation platforms across the United States. State veterinary medical boards retain divergent standards, creating compliance complexity that favors platforms with regulatory affairs capabilities. California, Texas, and Florida veterinary boards are responding with accelerated rulemaking timelines to capture federal permissiveness.
Pet owners in suburban and rural communities are abandoning appointment-scheduled clinic visits for on-demand digital triage of presenting complaints. Mobile platforms capture disproportionate engagement compared to web portals, reflecting generational preference shifts among millennial and Gen Z pet owners. This behavioral rotation is most visible in the United Kingdom, where veterinary workforce shortages amplify convenience-seeking substitution patterns.
North America and Europe Veterinary Telehealth Market Segmentation
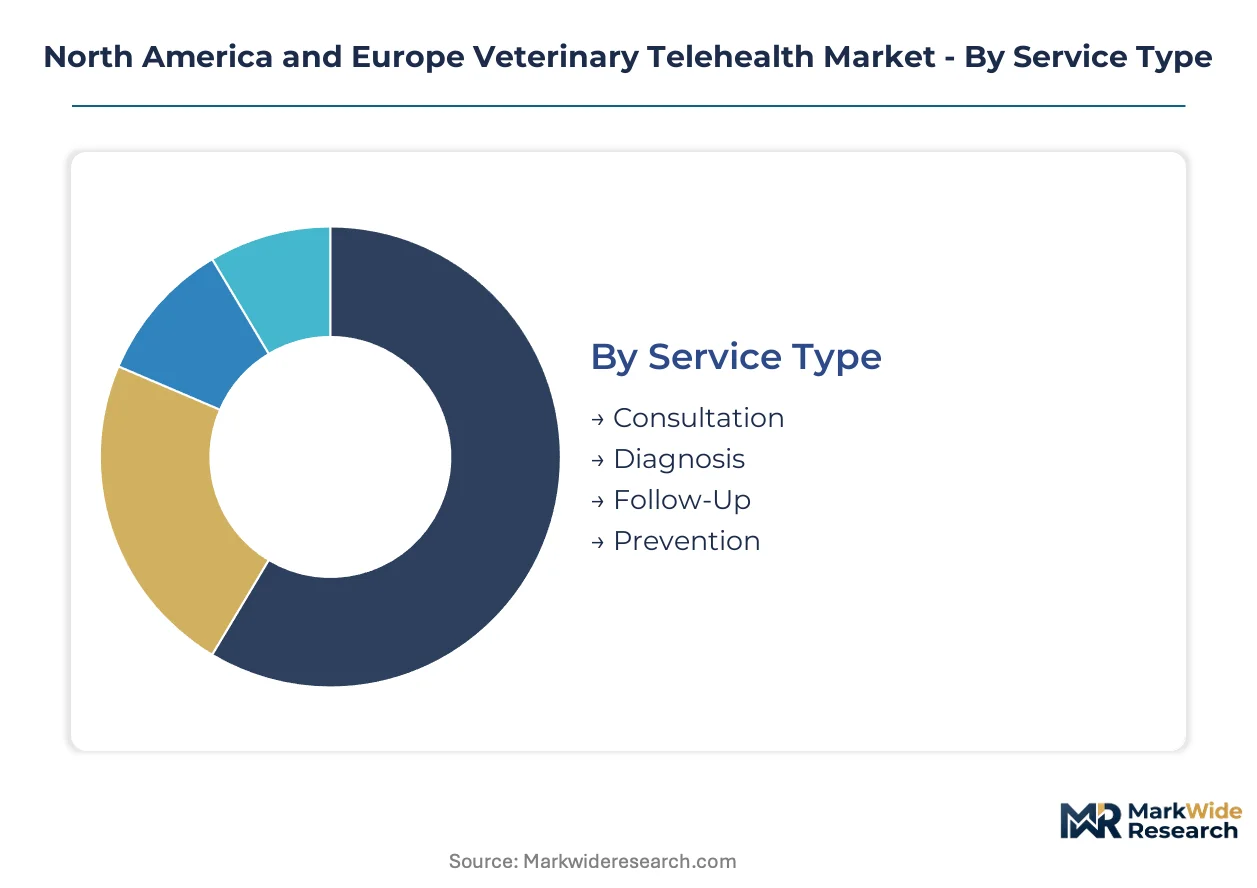
Telehealth service architecture fragments across multiple operational dimensions, each governing distinct revenue pools and compliance requirements. Understanding these segment boundaries clarifies where platform investments concentrate and which user acquisition channels offer sustainable competitive moats.
Service Type:
Mature consultation services anchor revenue stability while emerging prevention modules reshape lifetime customer value calculations.
- Consultation:Synchronous video and asynchronous messaging platforms triage presenting complaints, with demand concentrating in suburban United States communities where clinic travel burdens drive substitution. The FDA's loosening prescribing guidance expands prescription fulfillment capabilities for these encounters.
- Diagnosis:Remote dermoscopy and otoscopy feeds requiring 1.5 Mbps minimum bandwidth enable specialist-level visual assessment, with United Kingdom veterinary workforce shortages accelerating platform adoption for case escalation. Continuous glucose monitors and activity trackers enhance diagnostic reliability for chronic conditions.
- Follow-Up:Post-treatment monitoring via mobile platforms captures disproportionate engagement among millennial and Gen Z pet owners seeking appointment-free interactions.
- Prevention:Wellness planning and vaccination scheduling modules embedded within pet insurer policy benefits create sticky distribution relationships across North American metropolitan corridors.
Consultation handles the majority of throughput; prevention is the fastest mover on share.
End User:
Customer type determines pricing power and platform interface requirements, with direct-to-consumer models diverging sharply from institutional procurement patterns.
- Pet Owners:Individual subscribers in rural and ex-urban communities represent the fastest-expanding user base, abandoning appointment-scheduled clinic visits for on-demand digital triage. Mobile-first platform optimization exceeds current web portal engagement.
- Veterinary Clinics:Smaller groups leverage subscription-based infrastructure leasing to deploy digital consultation tools without capital-intensive IT buildouts, fragmenting competitive barriers across suburban markets.
- Animal Hospitals:Large institutional adopters integrate telehealth platforms to reduce non-emergency caseload burdens on brick-and-mortar specialty practices.
- Shelters:Non-profit and municipal facilities utilize asynchronous messaging for triage of intake populations, with cost constraints favoring lower-bandwidth communication modes.
Pet owners dominate transaction volumes; veterinary clinics are expanding most quickly as platform penetration deepens.
Technology:
Interface modality governs diagnostic capability ceilings and user retention economics, with hardware-enabled monitoring displacing pure software plays.
- Video Conferencing:Real-time synchronous consultation remains the default for complex presenting complaints, though bandwidth thresholds exclude underserved rural areas with poor telecommunications infrastructure.
- Chat Applications:Asynchronous messaging platforms compress operational costs while maintaining triage throughput, with the FDA's evolving guidance loosening constraints for these modalities.
- Remote Monitoring:Wearable biometrics including continuous glucose monitors and activity trackers achieve greater diagnostic reliability, representing the steepest expansion trajectory as accuracy gains accelerate adoption.
- Mobile Platforms:Smartphone-native interfaces capture disproportionate user engagement compared to web portals, reflecting generational preference shifts and on-demand service expectations.
Video conferencing retains the largest installed base; remote monitoring is climbing the fastest on technology investment.
Delivery Mode:
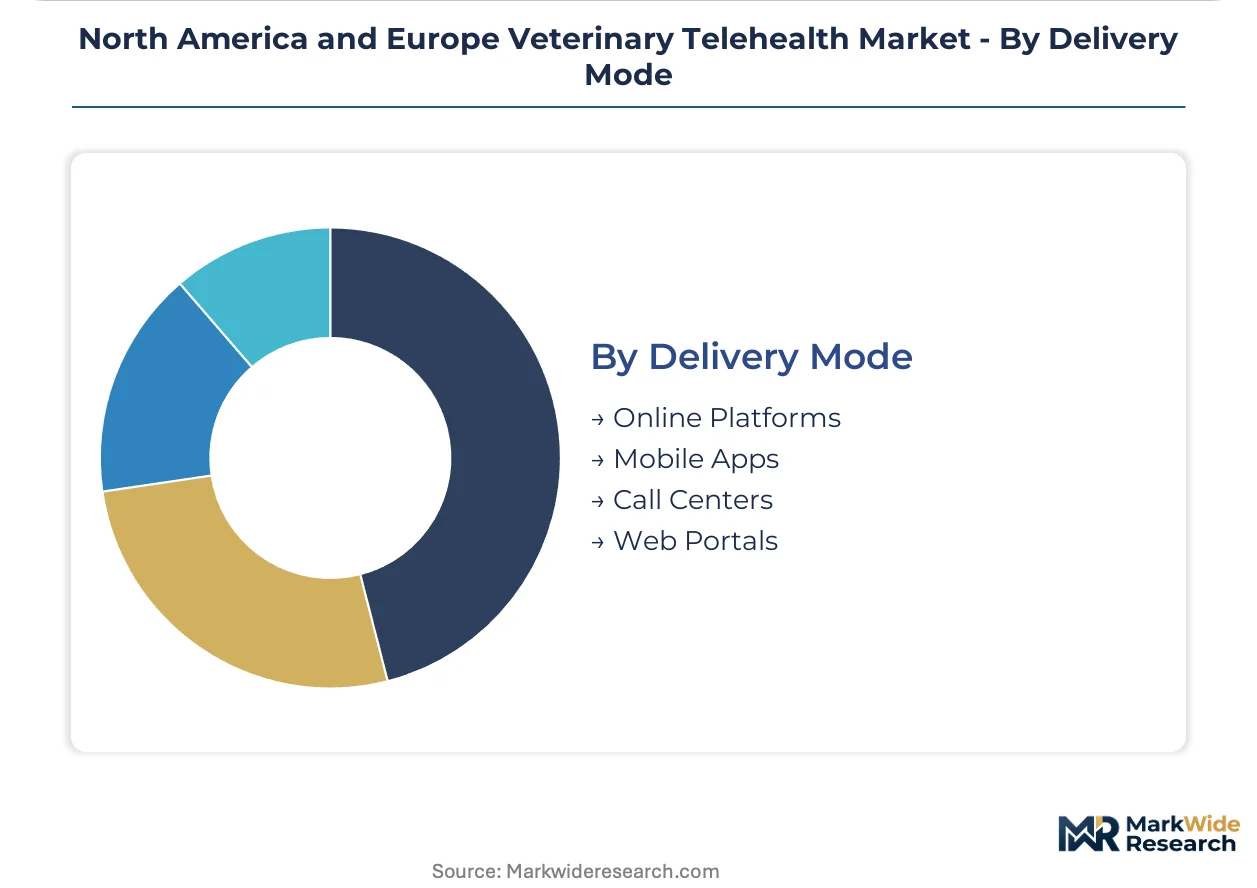
Distribution channel selection shapes customer acquisition cost structures and regulatory compliance architecture across jurisdictions.
- Online Platforms:Browser-based access points serve institutional adopters and older demographic segments less inclined toward app-based interactions.
- Mobile Apps:Native smartphone applications dominate millennial and Gen Z engagement, with employer wellness program channels driving corporate pet benefits adoption in North American metro corridors.
- Call Centers:Voice-only consultation modes persist in rural United States markets with intermittent broadband coverage, though diagnostic capability remains limited.
- Web Portals:Desktop-optimized interfaces retain utility for multi-pet households and complex case documentation, despite lower overall engagement metrics.
Mobile apps command the highest user engagement; call centers are gaining share fastest in connectivity-constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's evolving guidance on veterinary telemedicine prescribing authority is loosening operational constraints across the United States, while the European Medicines Agency's harmonization efforts aim to streamline cross-border platform operations. These policy shifts are redistributing market power toward infrastructure-light service models and accelerating adoption timelines in workforce-constrained markets.
United States
Suburban and rural pet owners represent the fastest-expanding user base as they seek alternatives to clinic travel. State veterinary medical boards in California, Texas, and Florida are responding with accelerated rulemaking timelines to capture federal permissiveness. The Southeast corridor from Atlanta to Miami exhibits concentrated platform penetration as employer wellness programs drive corporate pet benefits adoption.
United Kingdom
Veterinary workforce shortages and high pet ownership rates are accelerating platform adoption faster than any other European market. The UK's national telemedicine framework establishes distinct standards for remote diagnosis authorization that diverge from continental EU approaches. London and the Southeast anchor demand concentration, with Manchester and Birmingham emerging as secondary hubs for telehealth infrastructure deployment.
Germany
The EU's Veterinary Medicines Regulation intersects with national telemedicine frameworks to create compliance complexity for platform operators. German veterinary chambers maintain stringent requirements for remote prescription fulfillment that exceed EMA baseline guidance. The Rhine-Ruhr metropolitan region and Munich cluster host the densest concentrations of platform-veterinary practice partnerships.
Canada
Health Canada and provincial veterinary regulators are observing FDA developments while maintaining conservative stances on remote prescribing authority. Telecommunications infrastructure gaps in northern and rural provinces exclude significant addressable populations from real-time diagnostic services. Toronto, Vancouver, and Calgary concentrate platform investment as urban pet ownership rates align with mobile-first service preferences.
France
ANSM and national veterinary order regulations establish separate standards for remote diagnosis that complicate platform scaling across EU borders. The country's centralized healthcare administration tradition creates friction with asynchronous consultation models. The Paris Île-de-France region dominates transaction volumes, with Lyon and Marseille representing emerging adoption corridors for connected diagnostic peripherals.
North America and Europe Veterinary Telehealth Market Key Industry Players
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single entity commands decisive market share. Subscription-based infrastructure leasing has lowered entry barriers for smaller veterinary groups, multiplying the number of active platform operators. Two strategic archetypes dominate: marketplace connectors linking independent veterinarians directly to pet owners, and insurer-embedded platforms distributing telehealth access through policy benefits. Competitive moves concentrate on pet insurer partnership formation and employer wellness program channel penetration.
Among marketplace-model operators, Vetster and Airvet occupy distinct positioning vectors, with the former exemplifying low fixed-cost expansion across metropolitan corridors and the latter anchoring corporate pet benefits distribution. FirstVet represents the insurer-embedded archetype through partnerships with major pet insurers. These three entities illustrate how channel control and partnership depth, rather than proprietary technology alone, determine competitive standing in this market.
| Leading Market Players |
|---|
| Petzam |
| BabelBark |
| FirstVet |
| Vetster |
| Airvet |
| PawSquad |
| Whiskers Worldwide |
| TeleVet |
| Vets Now |
| Others |
Cost & Logistics Intelligence
United States-based cloud infrastructure providers anchor the upstream cost stack for veterinary telehealth platforms, concentrating margin capture in data center operations and API middleware layers rather than end-user consultation fees. This concentration forces downstream platform operators to compete on service-layer differentiation rather than infrastructure ownership.
Pricing Analysis
Certification level creates the primary spread between platform tiers, with FDA 510(k)-cleared diagnostic peripherals commanding premium positioning against uncertified consumer-grade alternatives. Subscription-based SaaS tiers dominate revenue models, though per-consultation transactional pricing persists in marketplace-model platforms. Price differentiation hinges on integration depth with practice management systems and after-hours coverage guarantees. Cost compression in the independent veterinarian marketplace segment is intensifying because subscription-based infrastructure leasing fragments barriers to entry. Small veterinary groups exhibit highest price sensitivity, while large animal hospital systems prioritize interoperability over unit cost.
Supply Chain Analysis
Upstream hardware feedstocks for connected diagnostic peripherals draw from Taiwan and South Korea for imaging sensors, with Chinese manufacturers supplying consumer-grade wearable biometrics. Software development centers on India and Poland for engineering talent, while customer-facing operations concentrate in the United States and United Kingdom. Single-source vulnerability in specialized veterinary-grade camera modules creates procurement risk for dermoscopy and otoscopy device vendors. Distribution runs through direct-to-practice sales teams for institutional adopters, with app store marketplaces handling consumer-facing mobile platform delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary telehealth functions as a service-attach play where recurring consultation subscriptions and insurer-embedded benefits expand faster than one-time hardware sales of diagnostic peripherals. Prevention-module revenue per user now outpaces initial platform licensing fees.
For Market Incumbents: Insulate core insurer partnerships through exclusive data-sharing arrangements that lock in policy-embedded telehealth access. Deepen backward integration into proprietary wearable biometrics development to reduce dependency on third-party glucose monitor suppliers. The emerging threat of employer wellness program channels bypassing traditional veterinary relationships demands defensive positioning in corporate benefits administration.
For New Entrants and Emerging Players: Build out asynchronous messaging infrastructure for shelter and municipal intake triage, the most penetrable segment given cost constraints and lower bandwidth requirements. Target rural United States communities excluded by real-time video bandwidth thresholds. A veterinary chamber certification-first go-to-market angle accelerates credibility with state regulatory bodies.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marketplace platforms that have scaled user acquisition without achieving insurer-channel dominance. Long-term viability in this market hinges on recurring revenue attachment rates rather than transactional consultation volumes. The signal to watch is FDA rulemaking velocity on asynchronous prescribing authority, which would inflect platform economics toward lower-cost service models.
| Strategic Initiative | Industry Significance |
|---|---|
| Pet Insurer Partnership Formation | Embedding telehealth access within policy benefits reduces customer acquisition costs for platform operators. |
| Employer Wellness Program Channel | Corporate pet benefits penetration in North American metro corridors unlocks high-volume user pools. |
| Mobile-First Platform Optimization | Smartphone-native interfaces align with millennial and Gen Z pet owner preference for on-demand interactions. |
| Connected Diagnostic Peripheral Launch | FDA-cleared dermoscopy and otoscopy devices collapse geographic distance to specialist-level visual assessment. |
| Regulatory Affairs Capability Buildout | State veterinary medical board compliance expertise enables prescription fulfillment across fragmented US jurisdictions. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with veterinary practice owners, telehealth platform product managers, pet insurer benefits directors, and state veterinary medical board administrators; and secondary validation through FDA guidance documents, EMA harmonization working papers, SEC filings of publicly traded pet care companies, and veterinary workforce statistics from national professional associations. Bottom-up modeling of platform transaction volumes and top-down triangulation against pet ownership demographics and insurance penetration rates anchored market sizing.
Forecast inputs considered service type segmentation, technology modality splits, and delivery mode channel economics across the projection horizon. Modeled dimensions included consultation versus prevention service mix, synchronous video versus asynchronous messaging adoption curves, and mobile app versus web portal engagement patterns. CAGRs were derived from regression analysis of historical platform adoption against veterinary workforce density and telecommunications infrastructure coverage. Specific inputs incorporated FDA rulemaking timelines and EMA cross-border harmonization progress.
Practitioners should monitor FDA prescribing authority guidance revisions and state veterinary medical board rulemaking accelerations for early signals of regulatory inflection. Cross-checking against national pet insurance policy attachment rates and veterinary school graduation statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Tables Market
Veterinary
OTC Cat Medicines Market
Veterinary
Companion Animal Drugs Market
Veterinary
Veterinary Healthcare Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Mastitis Market
Veterinary
Compression Veterinary Bandages Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Veterinary Parasiticides Market
Veterinary
Veterinary Excipients Market
Veterinary
Veterinary Thermography Market
Veterinary
Veterinary Vaccines Market
Veterinary
Animal Drug Compounding Market