
 Veterinary Excipients Market | 2026-2036
Veterinary Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Excipients Market Analytics
Continuous manufacturing is tilting pharmaceutical processing toward excipient blends engineered for direct compression and hot-melt extrusion. BASF SE leverages its superdisintegrant portfolio to anchor supply relationships with veterinary tablet producers across North America and Europe. Evonik Industries AG sustains R&D intensity in functional polymers for controlled-release antiparasitic formulations. Croda International Plc specializes in lipid-based delivery systems that improve bioavailability of poorly soluble veterinary actives.
Veterinary excipients are pharmacologically inactive substances formulated alongside active pharmaceutical ingredients to ensure stability, manufacturability, and targeted release in animal drug products. These materials must meet species-specific tolerability thresholds, with particle size distribution and moisture content specifications critical for uniform blending in high-speed tablet presses. Binders and coatings represent the most mature product categories, where margin pools have compressed due to commoditization of standard cellulose grades. Disintegrants in fast-dissolving oral formats for companion animals represent the fastest-growing product type as pet owners demand palatable, easy-to-administer medications.
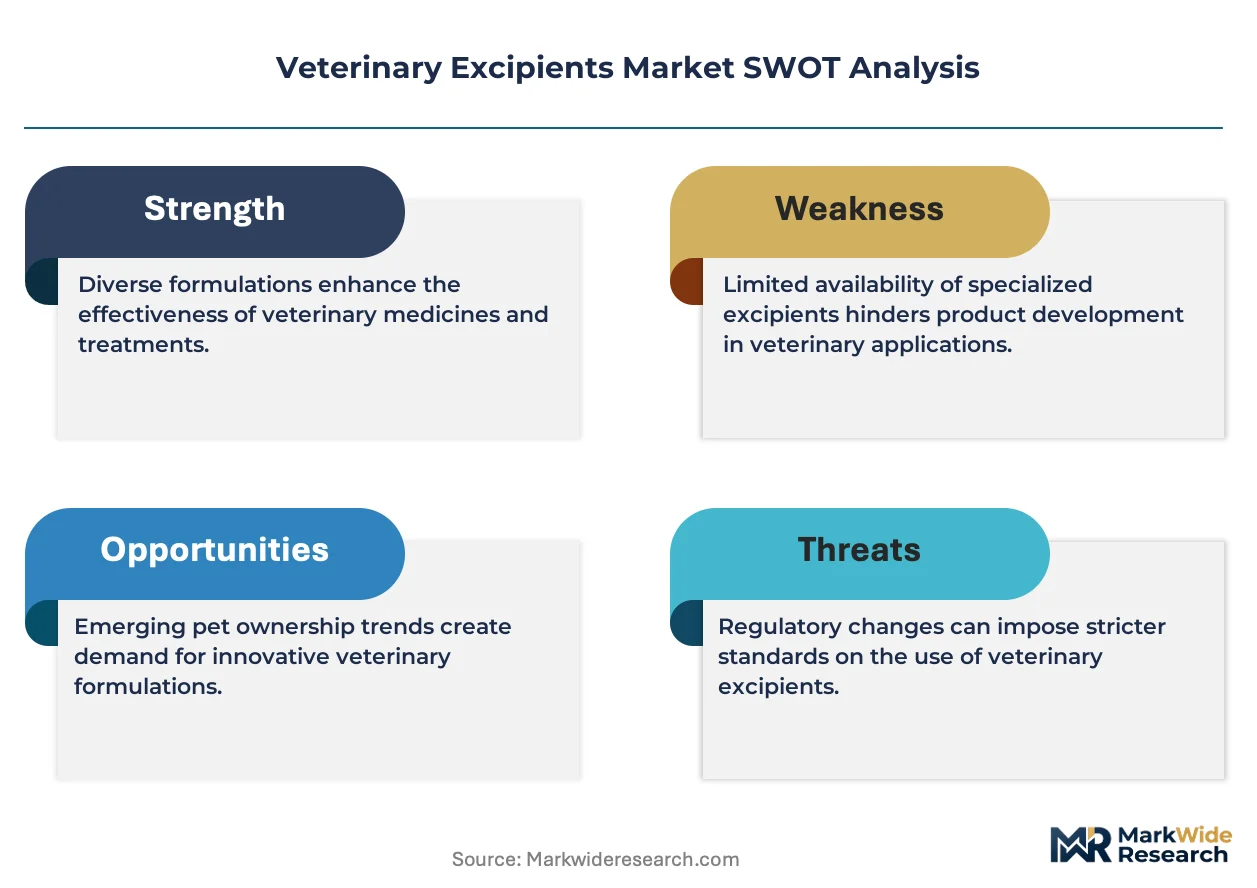
FDA Center for Veterinary Medicine enforces Current Good Manufacturing Practice regulations that dictate excipient qualification and supplier auditing protocols for animal drug sponsors. EMA's Committee for Medicinal Products for Veterinary Use coordinates European pharmacopoeial standards that harmonize excipient purity specifications across member states. India's CDSCO and China's NMPA maintain national formularies that increasingly reference ICH Q3D elemental impurity guidelines, narrowing the regulatory gap with Western markets. Stakeholders must monitor how pharmacopoeial modernization and tightening impurity thresholds reshape supplier qualification burdens and reformulation costs.
Market Dynamics
Continuous processing adoption in pharmaceutical manufacturing is compressing batch-to-batch variability tolerances and forcing excipient suppliers to engineer pre-blended, functionally optimized grades that integrate seamlessly into direct compression and hot-melt extrusion lines.
Growth Catalysts
- Livestock vaccine expansion:Mass immunization programs for cattle and poultry in Brazil and India are consuming record volumes of stabilizer excipients formulated for thermostable cold-chain alternatives.
- FDA bioequivalence pathways:Abbreviated new animal drug application (ANADA) approvals for generic veterinary medicines mandate excipient performance parity, locking suppliers into long-term qualification relationships with sponsors.
- Cellulose ether functionalization:Modified HPMC grades with tailored viscosity profiles are displacing gelatin in companion animal soft-chew matrices, opening formulation flexibility for moisture-sensitive actives.
Market Restraints
- API-excipient incompatibility screening costs:Accelerated stability testing protocols for novel excipient-API combinations add twelve to eighteen months to development timelines and strain mid-tier formulator budgets.
- Pharma-grade cellulose supply concentration:Three specialized pulp processors control over seventy percent of veterinary-grade microcrystalline cellulose feedstock, creating single-source vulnerability for tablet binder supply.
- Propylene glycol substitution pressure:Glycerin and sorbitol solutions are gaining traction in oral liquid formulations as pet owners and veterinarians scrutinize solvent safety profiles in chronic administration settings.
Strategic Opportunities
- Oral fast-dissolve films for feline medication:Thin-film excipient platforms that adhere to mucosal surfaces address the persistent compliance gap in cat owners who struggle with pilling.
- China NMPA veterinary excipient monograph expansion:Domestic manufacturers can capture share from imports by pre-qualifying grades against newly harmonized ICH Q3D elemental impurity standards ahead of Western competitors.
- Precision fermentation-derived polymers:Biosynthesized polysaccharides with batch-to-batch molecular consistency are converging with CRISPR-edited probiotic delivery systems for gut-targeted veterinary therapeutics.
Industry Challenges
- Excipient master file management:Veterinary sponsors must maintain Type II drug master files across FDA, EMA, and NMPA jurisdictions simultaneously, multiplying documentation overhead and audit frequency.
- Continuous manufacturing retrofit capex:Excipient producers face eight-figure capital outlays to install real-time release testing infrastructure and powder flow characterization suites demanded by pharmaceutical contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Excipients Market |
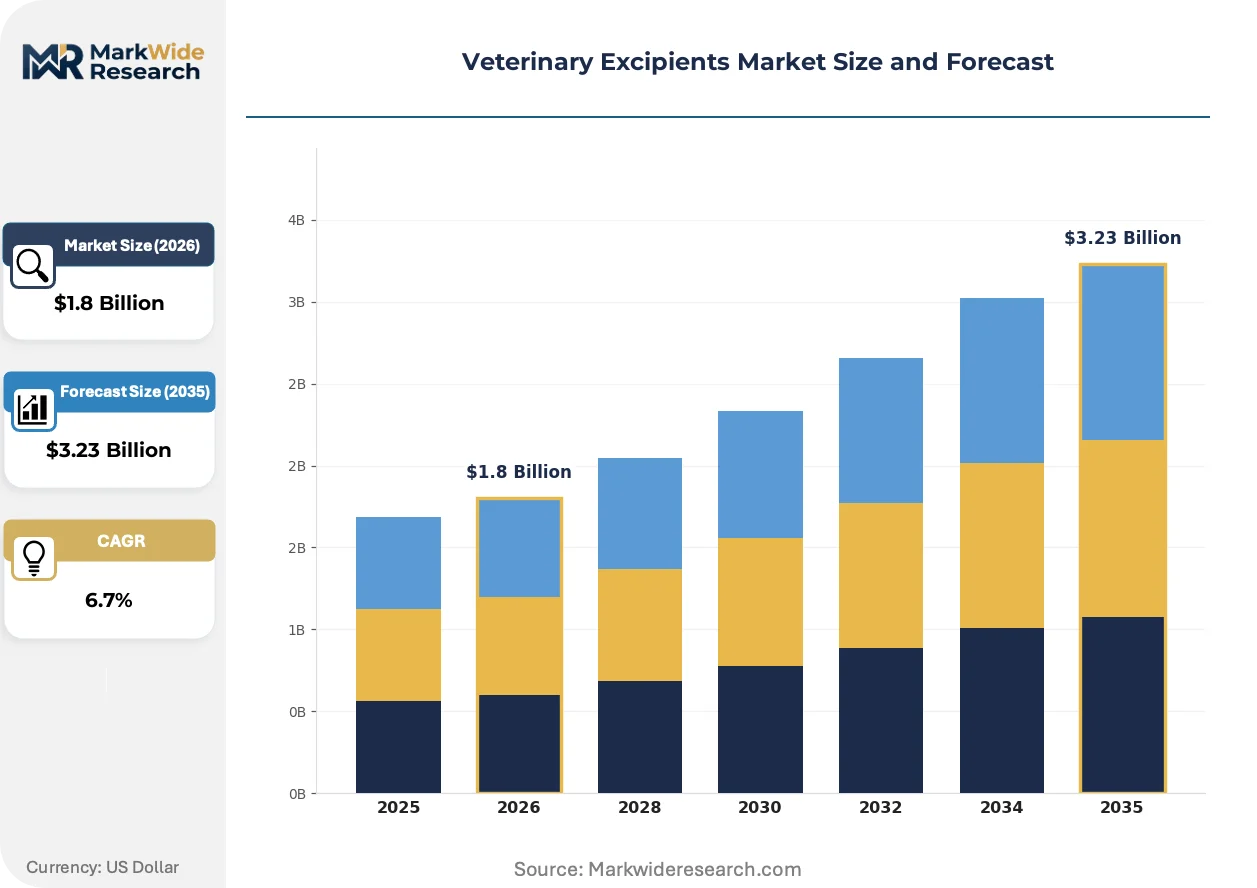
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binders, Fillers, Disintegrants, Coatings Application: Vaccines, Antiparasitics, Antibiotics, Nutraceuticals End User: Veterinary Clinics, Pharmaceuticals, Research Laboratories, Animal Feed Manufacturers Form: Powder, Granules, Liquid, Tablets |
| Companies Covered | JRS PHARMA GmbH & Co. KG, Evonik Industries AG, BASF SE, DuPont de Nemours Inc., Archer Daniels Midland Company, Croda International Plc, Clariant AG, Lubrizol Corporation, Ashland Global Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Excipients Market Evolving Landscape
Formulation science is migrating from commodity excipient supply toward engineered material platforms that compress development risk and accelerate regulatory filing readiness for novel veterinary dosage forms.
Multifunctional co-processed excipients are hybridizing traditional binder-disintegrant-lubricant roles into single-granule systems that eliminate blending steps and reduce powder segregation risk in high-speed tablet presses. North American contract manufacturers serving companion animal pharmaceutical innovators are adopting these grades fastest, with three of the five largest veterinary CDMOs now specifying co-processed platforms in their standard formulation templates. This hybridizing architecture is compressing the competitive position of standalone excipient suppliers who lack co-processing capabilities.
EMA's updated veterinary good manufacturing practice guidelines now mandate formal excipient risk assessment documentation that traces supply chain provenance through tier-three raw material sources. European formulators must re-qualify existing suppliers or absorb the cost of redundant auditing across multiple member state competent authorities. The controlled-release implant segment faces the steepest compliance burden, as these long-acting delivery systems require excipient stability data spanning the full duration of therapeutic effect.
Companion animal owners are consolidating medication purchases through veterinary clinic dispensing channels and direct-to-consumer subscription platforms, disintermediating traditional pharmacy distribution. This channel compression is forcing excipient suppliers to certify grades for smaller batch sizes and more frequent changeovers that match the inventory velocity of clinic-centric supply chains. The United States exhibits this pattern most acutely, where corporate veterinary group purchasing organizations now negotiate excipient-inclusive finished product contracts that bypass independent distributor networks entirely.
Veterinary Excipients Market Segmentation
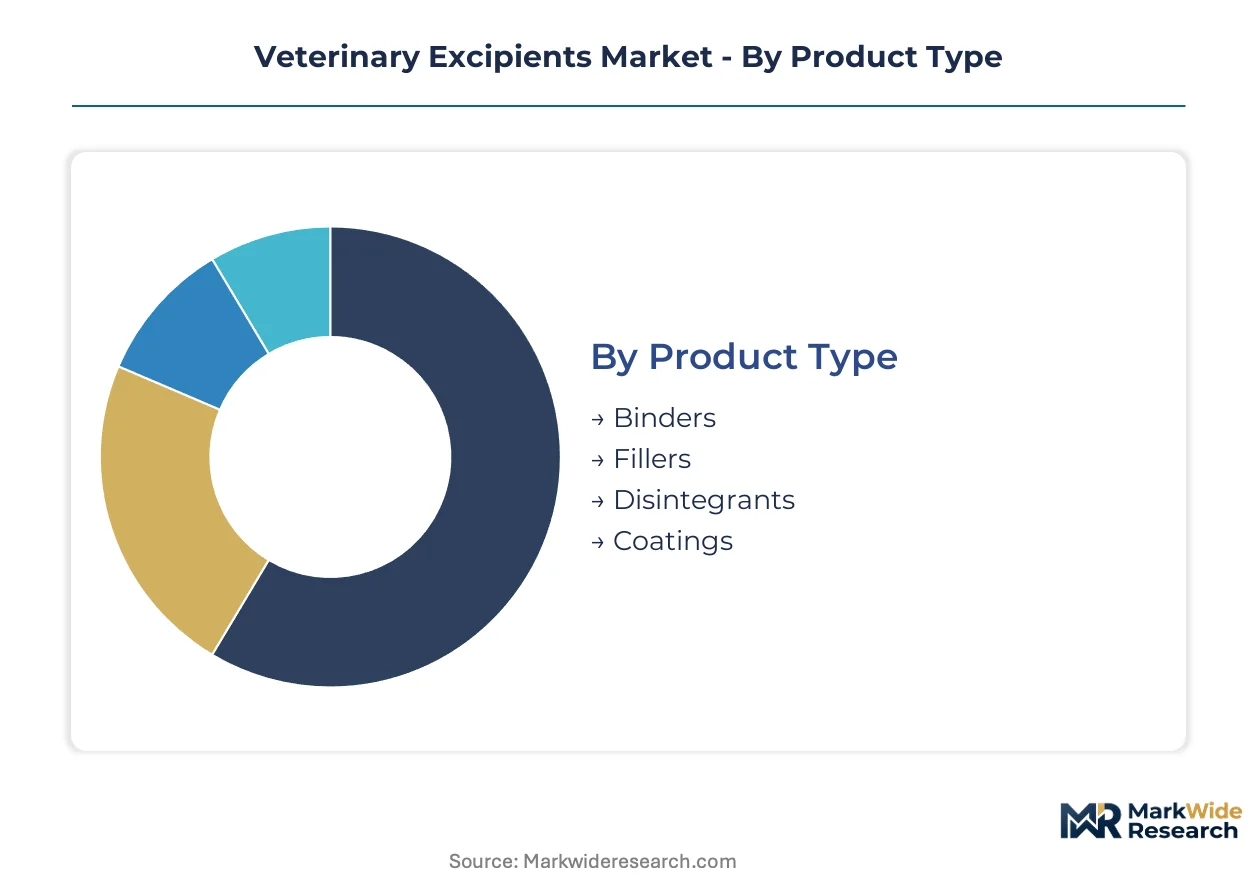
Veterinary excipient suppliers configure product portfolios around formulation physics and regulatory filing pathways. Segment-specific qualification requirements create distinct margin profiles and customer lock-in dynamics across dosage form categories.
Product Type:
Cost tier determines specification intensity and supplier consolidation patterns across functional excipient categories.
- Binders:Cellulose ethers and polyvinylpyrrolidone grades provide tablet structural integrity through plastic deformation under compression. Demand concentrates in high-volume livestock antibiotic manufacturing across the United States and Germany, where FDA bioequivalence standards mandate performance consistency across generic sponsors.
- Disintegrants:Superdisintegrants like croscarmellose sodium and sodium starch glycolate accelerate API release through rapid fluid uptake and swelling. Fast-dissolving oral formats for companion animals in North American veterinary clinics are rotating this segment up the growth rankings as pet compliance becomes a formulary priority.
- Fillers:Lactose and microcrystalline cellulose grades bulk tablet matrices to achieve target dosage weights.
- Coatings:Enteric and film-coating polymers protect acid-labile actives and mask bitter tastes in palatable formulations.
Binders hold installed capacity across legacy pharmaceutical manufacturing sites. Disintegrants are rotating up the share rankings.
Application:
Application scope dictates stability specification stringency and cold-chain infrastructure requirements.
- Vaccines:Stabilizer excipients including trehalose, sucrose, and hydrolyzed gelatin protect antigen integrity during lyophilization and thermal stress. Mass immunization programs for cattle in Brazil and poultry in India are consuming record volumes of thermostable excipient formulations designed for cold-chain alternatives.
- Antiparasitics:Controlled-release polymers enable sustained therapeutic plasma levels against endoparasites and ectoparasites. Long-acting injectable and implant formats for cattle operations in Australia and Argentina depend on PLGA and lipid matrix excipients with degradation profiles matched to parasite life cycles.
- Antibiotics:Solubilizing excipients and taste-masking coatings address palatability challenges in water-medication and feed-additive administration.
- Nutraceuticals:Bioavailability-enhancing lipid systems and protective encapsulants support omega fatty acid and probiotic stability in companion animal supplements.
Antiparasitics hold installed capacity. Vaccines are rotating up the share rankings.
End User:
Customer type determines batch size requirements, technical service intensity, and procurement contract structures.
- Pharmaceuticals:Integrated animal health divisions and contract manufacturing organizations drive specification-grade volume with formal supplier qualification protocols. CDMO networks in the United States, Germany, and China anchor demand for pre-blended, functionally optimized excipient grades compatible with continuous manufacturing lines.
- Veterinary Clinics:Corporate group purchasing organizations and direct-to-consumer subscription platforms are compressing order quantities while increasing changeover frequency. Smaller batch sizes and rapid inventory velocity characterize excipient sourcing for clinic-dispensed companion animal medications.
- Research Laboratories:Preclinical and clinical trial material supply demands high-purity, low-volume excipient grades with extensive documentation packages.
- Animal Feed Manufacturers:Premix and medicated feed additive production utilizes excipient carriers for uniform API distribution in bulk rations.
Pharmaceuticals hold installed capacity. Veterinary clinics are rotating up the share rankings.
Form:
Physical state governs powder flow engineering, moisture sensitivity, and packaging configuration requirements.
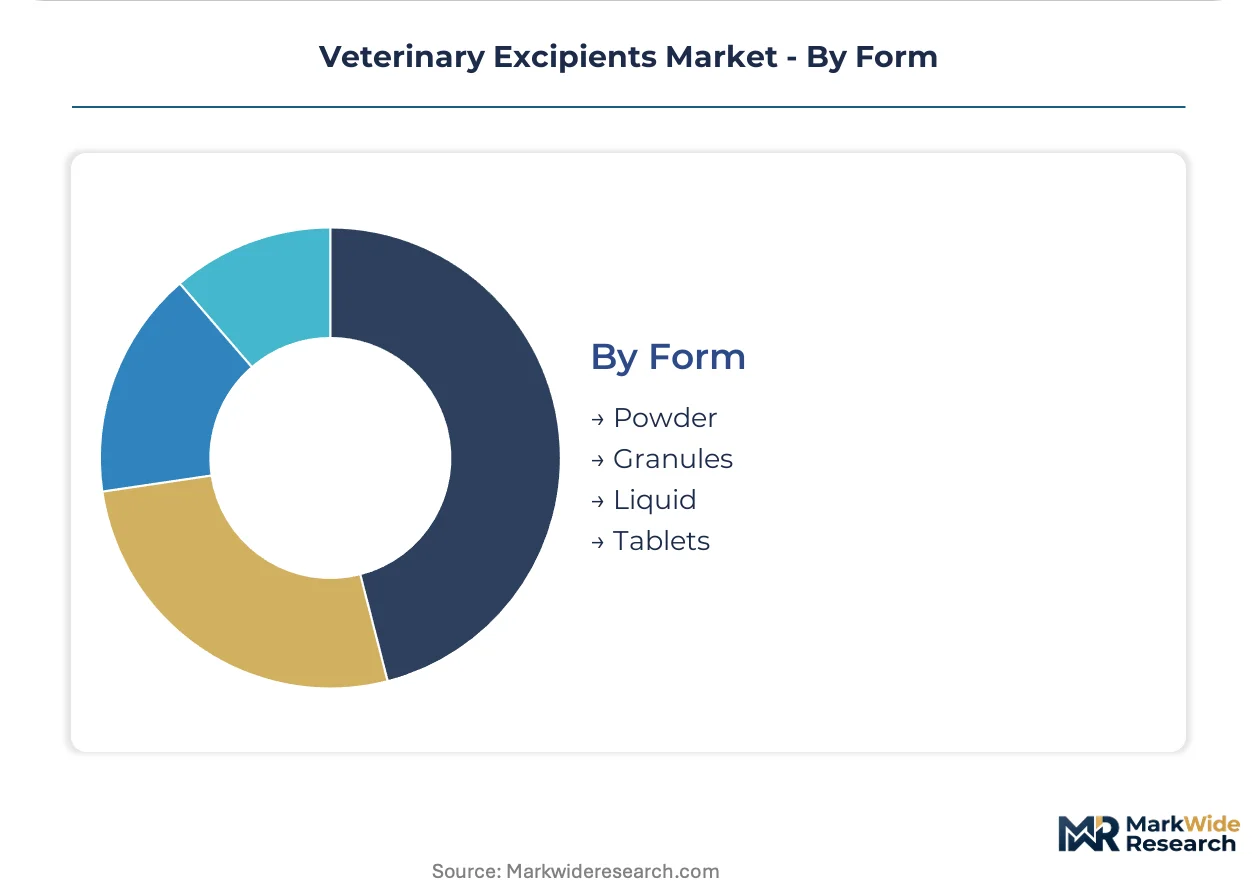
- Tablets:Direct-compression and granulation-grade excipients must meet precise particle size distribution and flowability specifications for high-speed rotary presses. Companion animal palatability demands in the United States are expanding specifications for chewable matrix binders and flavor-masking coatings.
- Liquid:Solubilizers, co-solvents, and viscosity modifiers enable oral drench, injectable, and pour-on formulations. Glycerin and sorbitol solutions are gaining formulation share against propylene glycol in chronic administration settings as veterinarians scrutinize solvent safety profiles.
- Powder:Micronized grades for suspension and soluble powder reconstitution require controlled agglomeration and dispersibility characteristics.
- Granules:Intermediate processing forms and direct-fed premix carriers demand uniform particle size for blending efficiency and segregation resistance.
Tablets hold installed capacity. Liquid formulations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized cellulose ether grades to veterinary pharmaceutical manufacturers across North America and Western Europe, anchoring transatlantic excipient trade flows. This corridor supplies critical binder and controlled-release polymer feedstock for companion animal tablet production.
United States
Corporate veterinary group purchasing organizations in Texas and Florida consolidate excipient procurement for clinic-dispensed medications. FDA Center for Veterinary Medicine enforces Current Good Manufacturing Practice regulations that dictate supplier auditing protocols. The Research Triangle Park cluster in North Carolina hosts contract manufacturing organizations specifying pre-blended grades for continuous tablet presses.
Germany
Livestock vaccine producers in Lower Saxony consume stabilizer excipients for thermostable cold-chain alternatives. EMA's Committee for Medicinal Products for Veterinary Use coordinates pharmacopoeial standards harmonizing purity specifications across member states. The Frankfurt-Rhine-Main metropolitan region anchors superdisintegrant R&D for fast-dissolving companion animal formats.
China
Domestic manufacturers in Jiangsu and Zhejiang provinces scale cellulose ether production for generic veterinary drug sponsors. NMPA maintains national formularies referencing ICH Q3D elemental impurity guidelines. The Yangtze River Delta cluster concentrates precision fermentation-derived polymer development for gut-targeted therapeutics.
Brazil
Mass cattle immunization programs in Mato Grosso and São Paulo states drive record stabilizer excipient consumption. ANVISA aligns veterinary drug registration requirements with international bioequivalence standards. The Campinas technology corridor attracts contract manufacturers serving Latin American antiparasitic formulation demand.
India
Poultry vaccine production in Telangana and Haryana states accelerates uptake of lyoprotectant excipients. CDSCO increasingly references ICH Q3D guidelines in national formularies. The Hyderabad-Visakhapatnam industrial belt specializes in cost-competitive microcrystalline cellulose for export to African and Southeast Asian markets.
Veterinary Excipients Market Competitive Landscape
On the supply side, the industry is consolidating around functional polymer specialists with captive R&D infrastructure and long-qualification relationships with veterinary drug sponsors. Three strategic archetypes dominate: diversified chemical conglomerates with pharmaceutical-grade cellulose portfolios, mid-cap excipient pure-plays focused on co-processed platforms, and fermentation-derived polymer innovators. Competitive intensity centers on M&A activity targeting regional distribution networks and strategic partnerships with contract manufacturing organizations.
Within the diversified chemical tier, BASF SE and Evonik Industries AG occupy positions as anchor suppliers across North American and European veterinary markets. Croda International Plc exemplifies the lipid-based delivery specialist archetype, with its portfolio weighted toward bioavailability enhancement for poorly soluble actives. These three entities represent contrasting strategic postures—scale-driven polymer breadth, functional polymer R&D intensity, and formulation-science specialization—without any single approach commanding definitive market control.
| Leading Market Players |
|---|
| JRS PHARMA GmbH & Co. KG |
| Evonik Industries AG |
| BASF SE |
| DuPont de Nemours Inc. |
| Archer Daniels Midland Company |
| Croda International Plc |
| Clariant AG |
| Lubrizol Corporation |
| Ashland Global Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Three specialized pulp processors in Germany and the United States control over seventy percent of veterinary-grade microcrystalline cellulose feedstock, anchoring margin capture at the binder-disintegrant interface while downstream tablet manufacturers absorb reformulation costs from single-source vulnerability.
Pricing Analysis
Prior-generation standard cellulose grades trade at commodity compression, current-generation functionalized HPMC and co-processed platforms command formulation-science premiums, and next-generation precision fermentation-derived polymers carry biosynthesis cost structures that limit immediate scale. Three-tier pricing structure across pharmaceutical-grade certification, technical-grade volume contracts, and feed-grade commodity separates veterinary sponsors by qualification burden. Cost compression in standard cellulose ethers runs through Brazilian and Indian generic manufacturers expanding capacity. Corporate veterinary group purchasing organizations in the United States exhibit highest price sensitivity due to inventory velocity demands, while long-acting implant specialists in Australia and Argentina show lowest sensitivity given therapeutic value capture.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for cellulose ether and superdisintegrant procurement, forcing dual-sourcing investments that inflate working capital requirements. Supply concentrates in Germany for specialized polymer R&D, China for fermentation-derived platform scale, and India for cost-competitive microcrystalline cellulose export. Feedstock dependencies span pharmaceutical-grade wood pulp, refined petrochemical derivatives for synthetic polymers, and fermentation feedstocks for biosynthesized grades. Single-source vulnerability at the pulp processor tier creates chokepoint risk for tablet binder supply. Distribution runs through contract manufacturing organization networks in the United States, Germany, and China that specify pre-blended grades for continuous manufacturing lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through corporate veterinary group purchasing organizations in the United States and direct-to-consumer subscription platforms, fragmenting order quantities while intensifying price negotiation leverage against excipient suppliers.
For Market Incumbents: Harden qualification-relationship durability with FDA Center for Veterinary Medicine sponsors facing abbreviated new animal drug application deadlines by embedding technical service teams at sponsor R&D sites. Deepen backward integration into pharmaceutical-grade pulp processing to neutralize single-source feedstock vulnerability. Prioritize co-processing capability investments that compress blending steps for contract manufacturing organizations adopting continuous tablet presses. For New Entrants and Emerging Players: Oral fast-dissolve film platforms for feline medication in North American veterinary clinics represent the most penetrable entry point, addressing persistent compliance gaps that established suppliers have underdeveloped. China's NMPA veterinary excipient monograph expansion offers regulatory-first-mover positioning against Western import dependence. Precision fermentation-derived polymer supply to gut-targeted probiotic delivery developers provides a technical differentiation angle that sidesteps commodity cellulose competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mid-cap excipient pure-plays possessing co-processing platforms but lacking global distribution reach. Five-to-ten year viability hinges on continuous manufacturing retrofit completion and regulatory qualification relationship depth rather than commodity scale. Monitor FDA Type II drug master file submission velocity from Chinese domestic manufacturers as inflection indicator for import substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Processed Platform Scale-Up | Eliminates blending steps for CDMOs specifying continuous tablet press compatibility. |
| Precision Fermentation Capacity Buildout | Biosynthesized polysaccharides match CRISPR-edited probiotic delivery degradation profiles. |
| Regulatory Qualification Relationship Investment | Locks long-term supply agreements with sponsors facing ANADA bioequivalence deadlines. |
| Backward Integration into Pulp Processing | Neutralizes single-source vulnerability from three specialized pharmaceutical-grade processors. |
| Fast-Dissolve Film Platform Launch | Addresses feline medication compliance gap in corporate veterinary clinic dispensing channels. |
Research Methodology
A standing panel of veterinary pharmaceutical formulation scientists, contract manufacturing organization procurement directors, regulatory affairs specialists at animal health sponsors, and excipient supplier technical service managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA Center for Veterinary Medicine drug master file databases, EMA Committee for Medicinal Products for Veterinary Use guidance documents, NMPA veterinary excipient monograph publications, and customs trade flow records for pharmaceutical-grade cellulose derivatives. Bottom-up volume estimates by dosage form category triangulated against top-down market sizing from identified supplier capacity disclosures.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated continuous manufacturing adoption pathways throughout the forecast period. Segmentation dimensions modeled encompassed product type functional hierarchy, application stability specification stringency, end-user batch size and technical service intensity, and physical form powder flow engineering requirements. CAGRs derived from segment-level volume build-ups applied to value-per-unit estimates reflecting tiered pricing structures. Industry-specific inputs included veterinary clinic dispensing channel inventory velocity data and livestock vaccine program expansion schedules from Brazil and India national agricultural ministries.
Practitioners should monitor pharmacopoeial modernization timelines and tightening ICH Q3D elemental impurity threshold implementations for early signals of reformulation cost inflation. Forecasts reflect assumptions about regulatory harmonization pace and continuous manufacturing adoption curves that could revise materially if sponsor qualification protocols lengthen or CDMO capex commitments stall. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Ultrasound Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Spay and Neuter Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Companion Animal Vaccines Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Global Orthopedic Veterinary Implants Market
Veterinary
Global Veterinary Care Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Veterinary Endodontics Market