
 Global Swine Vaccines Market | 2026-2036
Global Swine Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Swine Vaccines Market Foresight
GMP certification for veterinary biologicals is bifurcating the competitive landscape between multinational manufacturers and regional suppliers. Zoetis leverages integrated manufacturing platforms to sustain supply security across multiple continents. Boehringer Ingelheim GmbH anchors its position through deep specialization in respiratory disease portfolios. Merck & Co., Inc. competes by controlling distribution networks that reach fragmented farm operations in emerging markets.
Swine vaccines are biological preparations containing attenuated, inactivated, or recombinant antigenic material designed to stimulate protective immunity against specific porcine pathogens, with formulations requiring cold-chain maintenance between 2°C and 8°C to preserve efficacy. Their primary commercial purpose is to reduce morbidity, mortality, and production losses in intensive pork production systems. Live attenuated platforms still occupy the largest revenue pool due to established efficacy and farmer familiarity, though mRNA and DNA categories are attracting development capital as manufacturers navigate regulatory pathways for novel delivery systems. Porcine Reproductive & Respiratory Syndrome vaccines dominate target disease segments because the virus inflicts persistent economic damage across breeding and growing operations.
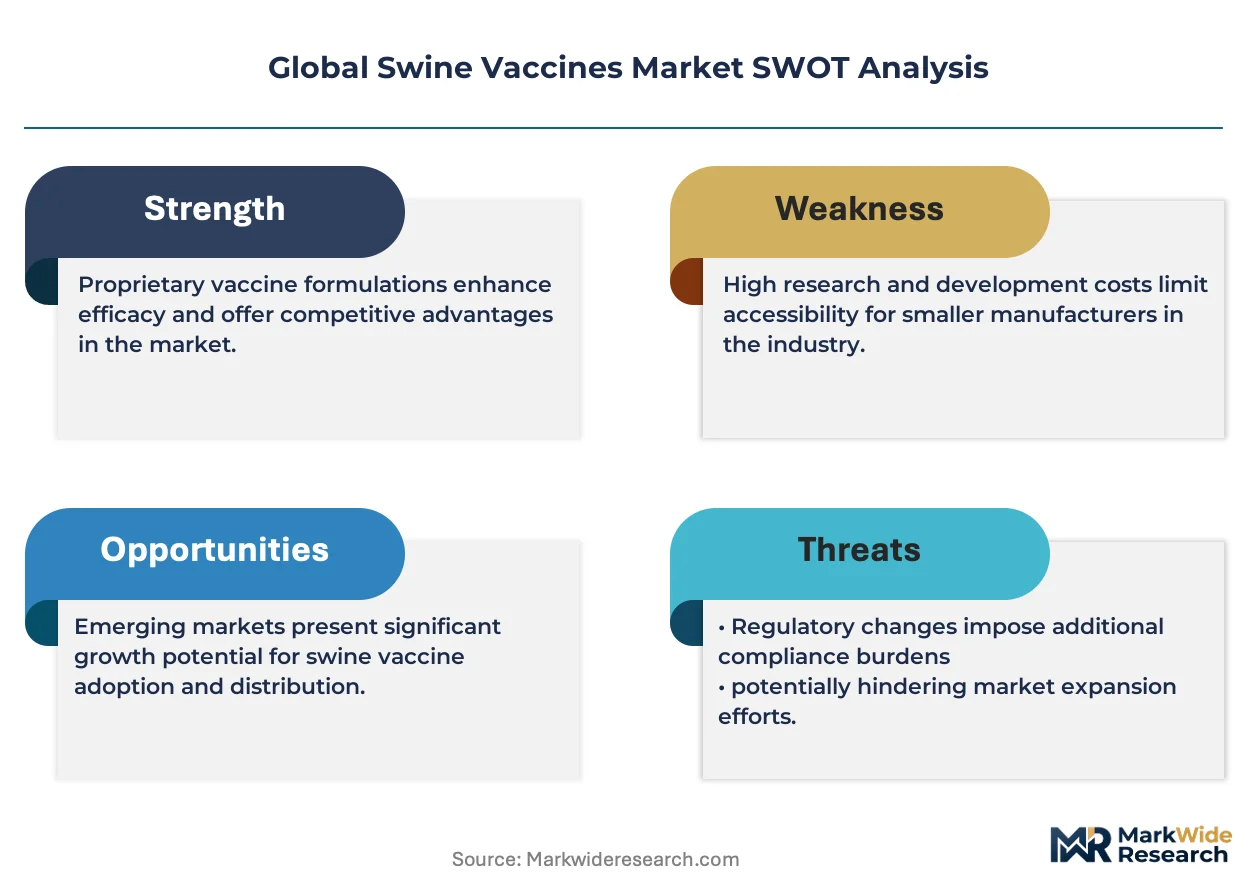
FDA Center for Veterinary Medicine, EMA, and China's NMPA each enforce distinct potency testing and batch release protocols that shape formulation requirements and registration timelines for market entry. The EU F-Gas Regulation and REACH frameworks additionally constrain adjuvant chemistry choices and cold-chain refrigerant selections. Stakeholders must monitor how divergent regulatory timelines for platform technologies will influence portfolio allocation between proven inactivated formats and emerging nucleic acid approaches.
Market Dynamics
The swine vaccines sector is experiencing a platform transition as nucleic acid delivery systems challenge established attenuated formulations, forcing manufacturers to split R&D budgets between proven efficacy pathways and novel regulatory submissions.
Growth Catalysts
- African swine fever containment mandates:China's recurring outbreaks sustain elevated preventive vaccination programs across breeding and finishing operations.
- EU F-Gas Regulation:Cold-chain refrigerant phase-downs accelerate investment in thermostable formulation technologies that reduce distribution infrastructure costs.
- Antibiotic reduction protocols:Veterinary biologicals are displacing prophylactic antimicrobial use in intensive pork production systems.
Market Restraints
- Adjuvant chemistry constraints:REACH frameworks limit aluminum-based and oil-in-water adjuvant options, compressing formulation flexibility for inactivated platforms.
- Batch release bottlenecks:Divergent potency testing protocols between FDA Center for Veterinary Medicine, EMA, and China's NMPA extend registration timelines for novel candidates.
- Live vaccine stability limitations:Attenuated platforms require uninterrupted cold-chain maintenance between 2°C and 8°C, restricting distribution reach to remote production regions.
Strategic Opportunities
- Vietnam and Philippines expansion:Underpenetrated commercial farm sectors in Southeast Asia present white space for respiratory disease portfolio penetration.
- DNA-mRNA convergence:Nucleic acid platform advances enable rapid strain-matched vaccine development against emerging porcine pathogens.
- Direct-to-farm digital channels:Veterinary service platforms are compressing traditional distributor layers in fragmented farm operations.
Industry Challenges
- Regulatory science talent scarcity:Shortage of professionals experienced in novel platform submissions to multiple veterinary medicine agencies slows pipeline advancement.
- Legacy system integration friction:Farm management software incompatibility with digital vaccination tracking tools complicates compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Swine Vaccines Market |
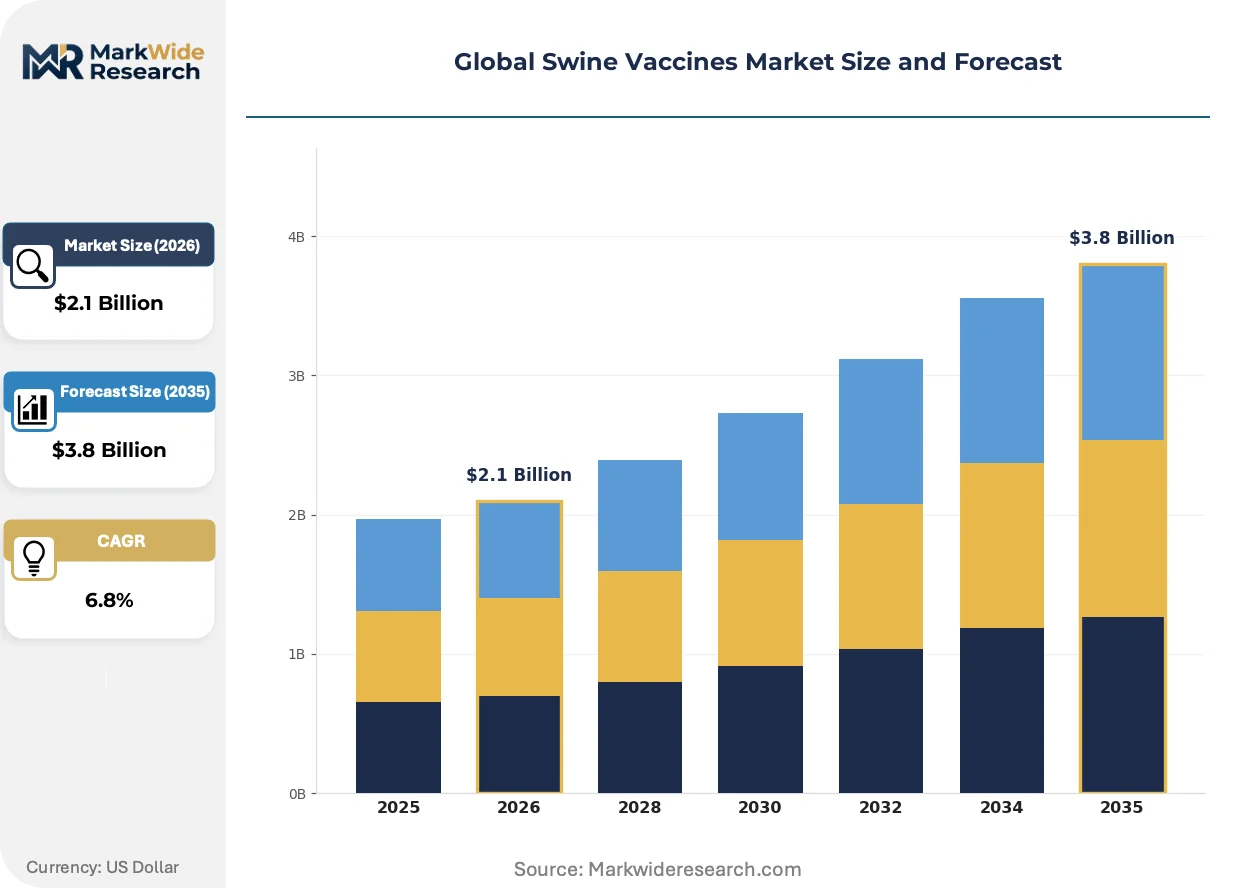
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, mRNA, DNA Target Disease: Porcine Reproductive & Respiratory Syndrome, Classical Swine Fever, Aujeszky’s Disease, Porcine Circovirus, Swine Influenza End User: Commercial Farms, Breeding Facilities, Research Institutions, Veterinary Clinics Distribution Channel: Direct Sales, Veterinary Pharmacies, Online Platforms, Agro-Distributors, Cooperative Societies |
| Companies Covered | Zoetis, Merck & Co., Inc., Boehringer Ingelheim GmbH, Ceva, Elanco, Phibro Animal Health, HIPRA, Virbac, Biogénesis Bagó, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Swine Vaccines Market Shifts & Advancements
Novel delivery platforms and tightening environmental frameworks are restructuring how biologicals are formulated, approved, and distributed across pork production systems worldwide.
mRNA vaccine platforms are displacing conventional attenuated approaches in development pipelines. Large-scale commercial farms in North America and Western Europe are piloting nucleic acid candidates for porcine reproductive and respiratory syndrome. Thermostable formulation advances are compressing cold-chain dependency and enabling direct-to-farm distribution models previously unreachable.
China's NMPA has streamlined emergency use authorization pathways for African swine fever candidates, compressing traditional multi-year review cycles. Domestic manufacturers are accelerating strain-matched vaccine development against evolving viral lineages. This regulatory velocity is attracting development capital toward Chinese market-specific portfolios while multinational firms navigate parallel submission tracks.
Consolidated procurement contracts now dominate commercial farm purchasing decisions. Integrated pork producers in Brazil and Spain are unbundling veterinary service contracts from product supply, selecting biologicals through outcome-based performance metrics rather than historical supplier relationships. This purchasing evolution is compressing margins for distributors lacking technical service capabilities.
Global Swine Vaccines Market Segmentation
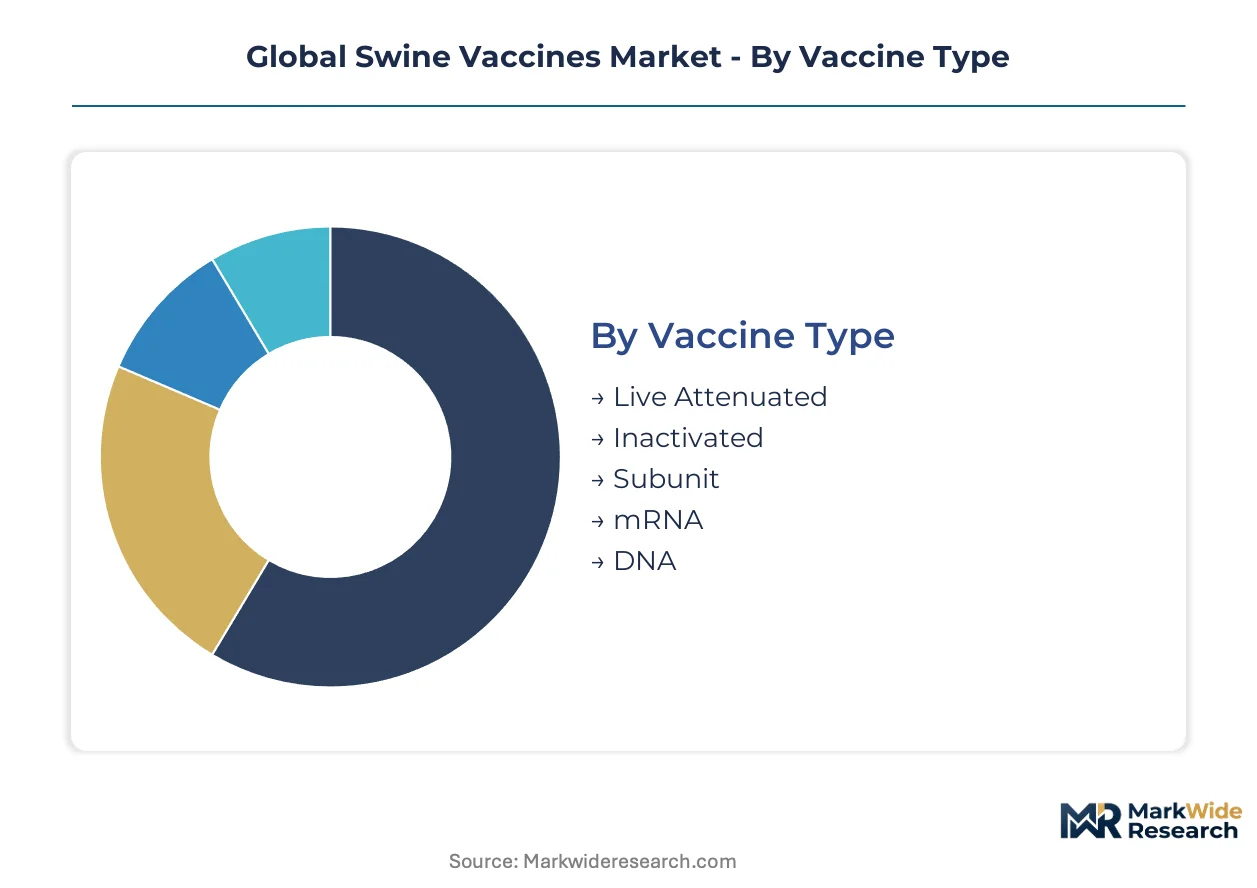
Segmentation in swine vaccines reveals how platform technology, disease pressure, and procurement channel evolution are fragmenting margin pools across the value chain. Manufacturers must align R&D allocation and distribution investments with the specific cost structures and regulatory requirements of each segment cluster.
Vaccine Type:
Margin concentration sits with platforms that balance manufacturing scale against cold-chain infrastructure requirements, with novel nucleic acid formats commanding premium positioning despite regulatory uncertainty.
- Live Attenuated:These formulations contain weakened pathogenic organisms that replicate minimally in the host to stimulate cellular immunity without causing disease. Demand concentrates in China's commercial breeding operations where African swine fever containment mandates sustain high-volume preventive programs. The established efficacy profile and farmer familiarity protect revenue pools despite cold-chain dependency.
- mRNA:Synthetic nucleotide sequences encoding viral antigens trigger rapid, strain-matched immune responses without biological cultivation. North American and Western European large-scale producers are piloting these candidates for porcine reproductive and respiratory syndrome, attracted by accelerated development timelines against evolving viral lineages.
- Inactivated:Whole pathogen preparations destroyed by chemical or thermal treatment retain immunogenicity while eliminating replication risk. These formulations serve regulatory-conservative markets requiring extensive safety documentation.
- Subunit:Purified protein or polysaccharide antigens eliminate extraneous pathogenic material, reducing adverse reaction profiles in high-value breeding stock.
- DNA:Plasmid-based genetic vaccines offer thermostable alternatives to mRNA with simpler storage requirements, gaining development attention for remote distribution scenarios.
The dominant share belongs to Live Attenuated, while mRNA is closing the gap fastest.
Target Disease:
Volume distribution follows the economic damage inflicted across breeding and growing operations, with respiratory and systemic diseases capturing procurement priority in intensive production systems.
- Porcine Reproductive & Respiratory Syndrome:This viral infection causes persistent reproductive failure in sows and respiratory distress in growing pigs, inflicting continuous economic damage across integrated operations. Demand clusters in Vietnam and the Philippines where expanding commercial farm sectors lack historical exposure management protocols.
- African Swine Fever:The highly contagious hemorrhagic virus triggers near-total mortality in affected herds, driving emergency authorization pathways and strain-matched development in China. Recurring outbreaks sustain elevated preventive vaccination consumption across breeding and finishing operations.
- Classical Swine Fever:Endemic in specific regional pockets, this pestivirus necessitates eradication-focused vaccination programs aligned with international trade certification requirements.
- Aujeszky's Disease:Pseudorabies virus control programs concentrate in regions maintaining negative herd status for export market access.
- Porcine Circovirus:Subclinical infection undermines immune competence and growth performance, driving inclusion in combination protocols for finishing operations.
- Swine Influenza:Zoonotic potential and human pandemic risk elevate regulatory attention beyond pure production economics.
Porcine Reproductive & Respiratory Syndrome retains the largest addressable base, though African Swine Fever commands the steepest expansion trajectory.
End User:
Procurement sophistication varies sharply across customer types, with integrated operations leveraging outcome-based contracting while fragmented holdings depend on distributor relationships.
- Commercial Farms:Large-scale integrated pork producers in Brazil and Spain are unbundling veterinary service contracts from product supply, selecting biologicals through performance metrics rather than historical supplier relationships. This purchasing evolution compresses margins for distributors lacking technical service capabilities.
- Breeding Facilities:Genetic multiplier operations prioritize disease-free certification and vertical transmission blocking, accepting premium pricing for validated efficacy documentation.
- Research Institutions:Academic and government veterinary laboratories procure experimental formulations and reference materials for regulatory science and field trial programs.
- Veterinary Clinics:Smallholder-facing practitioners serve fragmented farm operations through traditional distributor layers, though digital veterinary service platforms are compressing these intermediaries.
Commercial Farms absorb the dominant procurement volume, while Research Institutions are expanding fastest through novel platform development partnerships.
Distribution Channel:
Channel selection determines working capital intensity and technical service requirements, with direct models capturing consolidated accounts and cooperative structures penetrating fragmented production geographies.
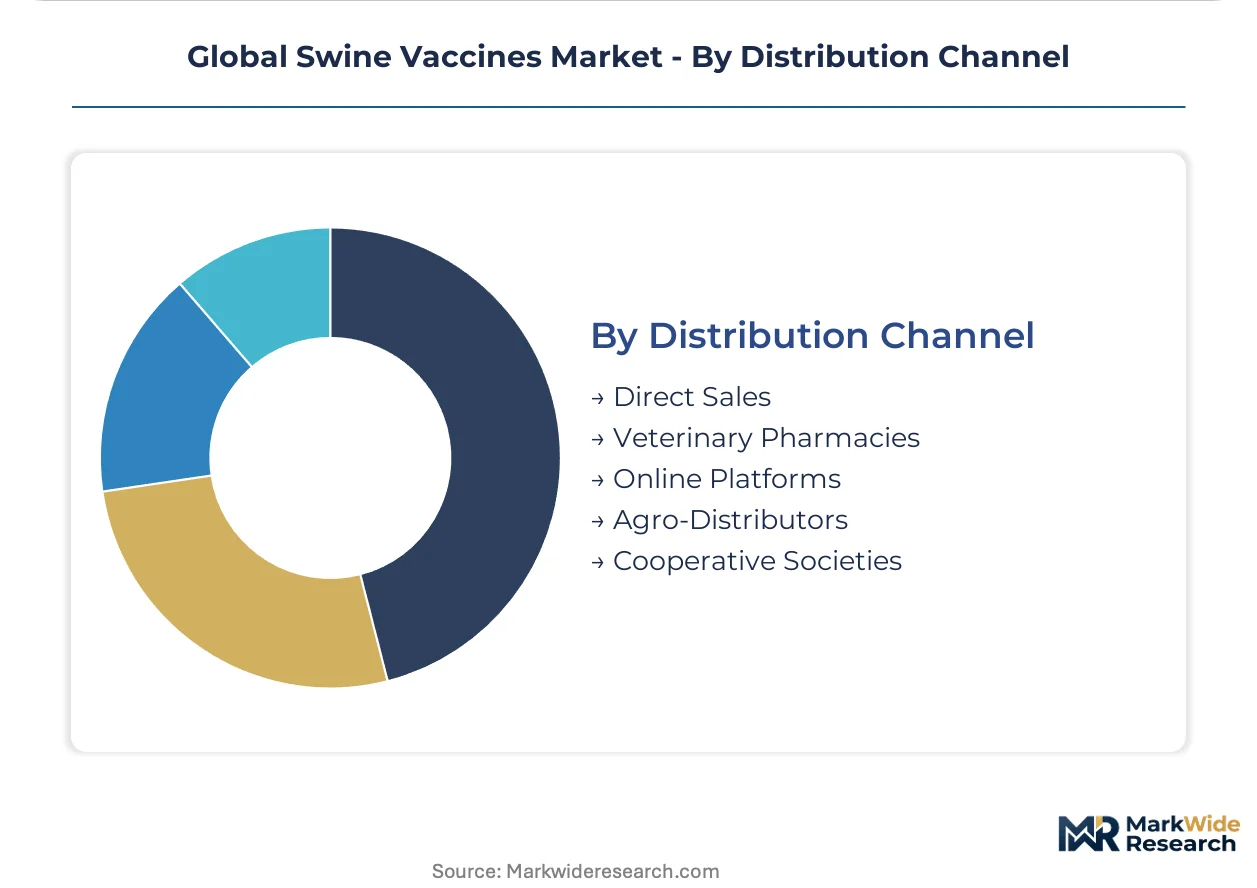
- Direct Sales:Manufacturer-to-farm relationships eliminate distributor margins and enable outcome-based contracting for integrated producers with sufficient procurement scale.
- Veterinary Pharmacies:Licensed dispensaries provide regulatory-compliant access for smaller operations requiring prescription oversight and cold-chain assurance.
- Online Platforms:Direct-to-farm digital channels are compressing traditional distributor layers, though cold-chain integrity verification remains a adoption constraint.
- Agro-Distributors:Multi-product agricultural suppliers leverage existing farm relationships to bundle biologicals with feed and equipment procurement.
- Cooperative Societies:Producer-owned purchasing organizations aggregate fragmented demand to negotiate volume pricing and shared technical services.
Agro-Distributors maintain the broadest geographic footprint, while Online Platforms are gaining share fastest through consolidated procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's cold-chain container throughput underwrites China's dominance in veterinary biologicals distribution, connecting domestic manufacturers to Southeast Asian pork production clusters.
China
Recurring African swine fever outbreaks sustain elevated preventive vaccination across breeding and finishing operations. NMPA streamlined emergency use authorization pathways, compressing traditional multi-year review cycles for novel candidates. Domestic manufacturers in Guangdong Province accelerate strain-matched vaccine development against evolving viral lineages.
United States
Large-scale commercial farms pilot nucleic acid platforms for porcine reproductive and respiratory syndrome. FDA Center for Veterinary Medicine enforces distinct potency testing protocols that shape formulation requirements. Integrated pork producers in Iowa and North Carolina unbundle veterinary service contracts from product supply.
Germany
Regulatory-conservative procurement prioritizes inactivated formulations with extensive safety documentation. EMA batch release protocols extend registration timelines for novel candidates. Bavarian veterinary pharmaceutical clusters specialize in respiratory disease portfolio development.
Brazil
Expanding commercial farm sectors drive demand for combination protocols in finishing operations. ANVISA governs import licensing and manufacturing standards for biologicals. São Paulo-based integrated producers leverage outcome-based performance metrics for biological selection.
Vietnam
Underpenetrated commercial farm sectors present white space for respiratory disease portfolio penetration. The country's national pharmaceutical regulator aligns with ASEAN harmonization initiatives for veterinary medicine approval. Mekong Delta pork production clusters lack historical exposure management protocols.
Global Swine Vaccines Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and regulatory science capabilities. The vendor base fragments between multinational manufacturers with integrated platforms and regional suppliers lacking GMP certification. Three archetypes dominate: vertically integrated biologicals conglomerates, respiratory disease portfolio specialists, and emerging nucleic acid platform developers. Competitive moves concentrate on thermostable formulation advances and direct-to-farm digital channel expansion.
Within the vertically integrated tier, Zoetis and Merck & Co., Inc. occupy positions that exemplify supply security across multiple continents. Boehringer Ingelheim GmbH anchors the specialization archetype through deep focus on respiratory disease portfolios. These three entities represent distinct strategic postures—manufacturing breadth, distribution network control, and therapeutic area depth—that shape competitive dynamics.
| Leading Market Players |
|---|
| Zoetis |
| Merck & Co., Inc. |
| Boehringer Ingelheim GmbH |
| Ceva |
| Elanco |
| Phibro Animal Health |
| HIPRA |
| Virbac |
| Biogénesis Bagó |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between integrated pork producers and biologicals manufacturers lock in multi-year supply security while anchoring price visibility against raw material volatility in adjuvant chemistry markets. These arrangements concentrate procurement power among Brazil's São Paulo-based integrators and Spain's Aragón Valley operations, compressing spot-market liquidity for smaller holdings.
Pricing Analysis
Volume-discount tiering structures stratify across premium GMP-certified, standard regional-manufacturer, and economy unbranded generic levels. Price differentiation hinges on cold-chain assurance certification and technical service bundling, with integrated operations commanding steepest discounts through consolidated procurement. Pricing pressure stems from outcome-based contracting adoption in Brazil and Spain, where performance metrics displace historical supplier premiums. Fragmented farm operations in Vietnam and the Philippines exhibit highest price sensitivity, while genetic multiplier breeding facilities accept premium positioning for validated efficacy documentation.
Supply Chain Analysis
Inventory cycles for live attenuated platforms stretch lead times because uninterrupted 2°C to 8°C cold-chain requirements constrain geographic reach. Manufacturing concentrates in the United States, Germany, and China, with Guangdong Province domestic suppliers gaining share through NMPA-fast-tracked African swine fever candidates. Formulation draws from aluminum-based adjuvant feedstocks and specialized cell culture media, exposing producers to REACH framework chemistry restrictions. Single-source vulnerability clusters around thermostable formulation patents held by select developers. Distribution runs through agro-distributor networks for fragmented operations, while direct-to-farm channels capture consolidated accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation between established attenuated formats and emerging nucleic acid approaches creates specialist niches as procurement digitization and outcome-based contracting reward technical service capabilities over pure manufacturing scale.
For Market Incumbents: Fortify respiratory disease portfolio depth against mRNA platform displacement by accelerating thermostable formulation R&D and securing GMP certification for novel adjuvant chemistries under REACH compliance. Backward integration into plasmid DNA production secures supply continuity for nucleic acid pipeline candidates. Channel control through direct-to-farm digital platforms defends margin position against distributor disintermediation in Brazil and Spain. For New Entrants and Emerging Players: Anchor in Vietnam and Philippines commercial farm sectors where respiratory disease management protocols remain underdeveloped and distributor relationships lack technical service depth. Strain-matched African swine fever vaccine development for NMPA emergency use authorization offers fastest regulatory pathway to revenue. Digital veterinary service platforms provide go-to-market angle that compresses traditional procurement layers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among nucleic acid platform developers with thermostable formulation portfolios and Chinese regulatory submission capabilities. Long-term viability over the analysis window favors acquisition targets combining manufacturing scale with direct-to-farm channel infrastructure. Watch for NMPA approval velocity as inflection indicator distinguishing domestic Chinese manufacturers from multinational parallel-track submissions.| Strategic Initiative | Industry Significance |
|---|---|
| Thermostable Formulation Development | Eliminates cold-chain dependency, enabling distribution to remote Mekong Delta and Brazilian interior production regions. |
| NMPA Emergency Use Authorization Submission | Compresses multi-year review cycles for African swine fever candidates, accelerating market entry timelines. |
| Direct-to-Farm Digital Channel Buildout | Disintermediates agro-distributor layers, capturing margin from outcome-based contracting with integrated producers. |
| Respiratory Disease Portfolio Expansion | Targets PRRS management gaps in Vietnam and Philippines commercial farm sectors lacking exposure protocols. |
| Plasmid DNA Manufacturing Scale-Up | Secures captive supply for nucleic acid platforms as mRNA and DNA categories attract development capital. |
Research Methodology
The analysis maps live attenuated, mRNA, inactivated, subunit, and DNA vaccine platforms, each validated through regulatory affairs directors at veterinary pharmaceutical manufacturers, procurement leads at integrated pork producers, cold-chain logistics operators, and EMA batch release specialists. Primary interviews combined with secondary validation against FDA Center for Veterinary Medicine filings, NMPA emergency use authorization records, EMA veterinary medicines registers, and customs trade data for biologicals imports. Bottom-up segment sizing triangulated against top-down market envelope checks.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled vaccine type, target disease, end user procurement sophistication, and distribution channel structure as segmentation dimensions. CAGRs derived from regression analysis of historical biologicals consumption against pork production intensity metrics, veterinary service digitization indices, and regulatory approval velocity differentials by agency.
Material uncertainties — African swine fever lineage evolution, REACH adjuvant chemistry restriction expansion, thermostable formulation patent litigation — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway convergence and procurement digitization adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Global Veterinary Holters Market
Veterinary
Veterinary and Animal Healthcare Logistics Market
Veterinary
Pet DNA Testing Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market
Veterinary
Veterinary Supplements Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
Global Veterinary Rapid Test Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market
Veterinary
Veterinary Hospitals Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Veterinary Excipients Market
Veterinary
Isoxazoline Market
Veterinary
Global Veterinary MRI Market
Veterinary
Pet Veterinary Diet Market