
 Europe Veterinarians Market | 2026-2036
Europe Veterinarians Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Veterinarians Market Insights
Specialty-grade veterinary services is reorganizing how European clinics allocate capital and talent. Zoetis leverages its diagnostics portfolio to anchor premium service workflows in France and Germany. Boehringer Ingelheim competes through vaccine specialization across large-animal corridors in Spain and Italy. Ceva Santé Animale sustains geographic dominance in poultry health, extending its reach into Eastern European veterinary networks.
Veterinarians are medically trained professionals licensed to diagnose, treat, and prevent disease in animals, employing pharmaceutical interventions, surgical procedures, and diagnostic imaging with equipment typically operating at 50-150 kV for radiography and 1.5-3 Tesla for MRI in companion species. Their commercial purpose centers on maintaining animal health for food security, companion welfare, and zoonotic disease containment. Diagnostics and surgery command the deepest margin pools among service types, while emergency care specialty posts the fastest growth trajectory. Solo practice remains the dominant practice size configuration across Southern Europe, though referral centers accumulate the highest revenue per veterinarian in the United Kingdom and Benelux.
EMA veterinary product guidelines, the EU Veterinary Medicines Regulation, and national licensing boards such as France's ANSM and Germany's BVL shape antimicrobial prescribing limits and biologic approval pathways, directly constraining clinic formularies and supplier contracts. REACH chemical standards further govern disinfectant and pharmaceutical ingredient compositions used in practice settings. Stakeholders must monitor how evolving EU Green Deal sustainability criteria will reshape procurement rules for veterinary pharmaceuticals and single-use diagnostic consumables.
Market Dynamics
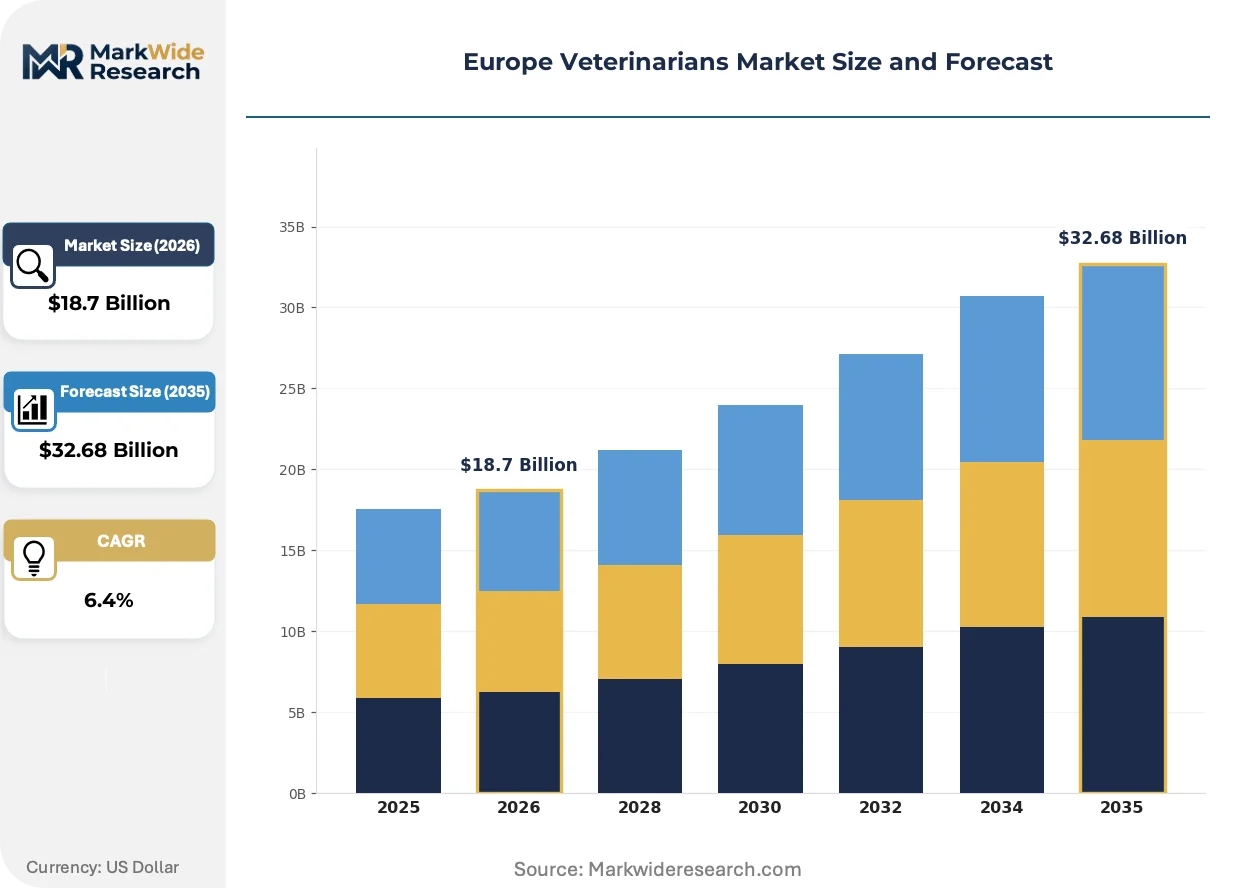
The EU Veterinary Medicines Regulation is compressing antimicrobial prescribing autonomy while pet insurance penetration in Germany and France pulls capital toward diagnostic-intensive workflows.
Growth Catalysts
- Pet insurance density:France and Germany post the deepest companion animal coverage rates in Europe, funneling owners toward specialty referral centers and advanced imaging services.
- EMA streamlined biologics pathways:Accelerated veterinary immunotherapy approvals are expanding clinic formularies for oncology and atopy management.
- Urban corridor concentration:Benelux and UK metropolitan clusters concentrate affluent pet-owning households within 30-minute referral radiuses.
Market Restraints
- Veterinary workforce maldistribution:Eastern European member states face persistent clinician shortages relative to livestock density, capping service throughput.
- Antimicrobial stewardship compliance costs:The EU Veterinary Medicines Regulation mandates enhanced record-keeping infrastructure that squeezes solo practice margins.
- Specialty equipment import dependency:MRI and CT systems for companion species rely on non-EU component supply chains exposed to tariff volatility.
Strategic Opportunities
- Poland and Romania livestock modernization:Cattle and swine productivity initiatives in these accession-era markets are generating demand for production animal veterinary services.
- Telemedicine-triage convergence:Remote consultation platforms paired with point-of-care diagnostics are opening subscription revenue streams for multi-site practice groups.
- EU Green Deal procurement criteria:Sustainability-linked pharmaceutical tenders will favor suppliers with circular packaging and reduced carbon footprint credentials.
Industry Challenges
- Specialist certification pipelines:European College of Veterinary Specialties residency positions remain bottlenecked relative to referral center expansion plans.
- Legacy practice management system integration:Solo practitioners in Southern Europe face technical debt migrating paper records to cloud-based platforms required for EMA pharmacovigilance reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Veterinarians Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultations, Surgeries, Vaccinations, Diagnostics Animal Type: Dogs, Cats, Birds, Reptiles Practice Size: Solo Practice, Small Clinic, Large Clinic, Referral Center Specialty: Emergency Care, Dentistry, Surgery, Internal Medicine |
| Companies Covered | Boehringer Ingelheim, Zoetis, Ceva Santé Animale, Virbac, Elanco, IDEXX Laboratories, MSD Animal Health, Vetoquinol, Dechra Pharmaceuticals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Veterinarians Market Trends and Innovations
Artificial intelligence diagnostic tools and point-of-care testing platforms are compressing the traditional laboratory-referral model while regulatory pressure on antimicrobial use reshapes prescribing software.
AI-powered radiograph interpretation software is displacing film-based second-opinion workflows in UK and German companion animal hospitals. Tier-one referral centers in London and Munich deploy these tools for thoracic and orthopedic screening, reducing specialist veterinarian reading time by half. The technology is displacing traditional teleradiology arrangements and compressing the value capture of standalone imaging interpretation services.
REACH chemical standards revision is tightening excipient disclosure requirements for topical veterinary pharmaceuticals. Manufacturers must reformulate dermatology and otology products to exclude newly restricted solvent classes, extending reformulation timelines by 12-18 months. French and German national regulators are accelerating pre-approval dialogue to prevent market withdrawal disruptions.
Subscription-based wellness plans are replacing episodic fee-for-service billing in Netherlands and Scandinavian urban practices. Younger pet owners in Amsterdam and Copenhagen favor predictable monthly outlays covering preventive care, diagnostics, and tele-triage access. Channel intermediaries including pet retail chains are capturing plan enrollment through co-branded veterinary partnerships.
Europe Veterinarians Market Segmentation
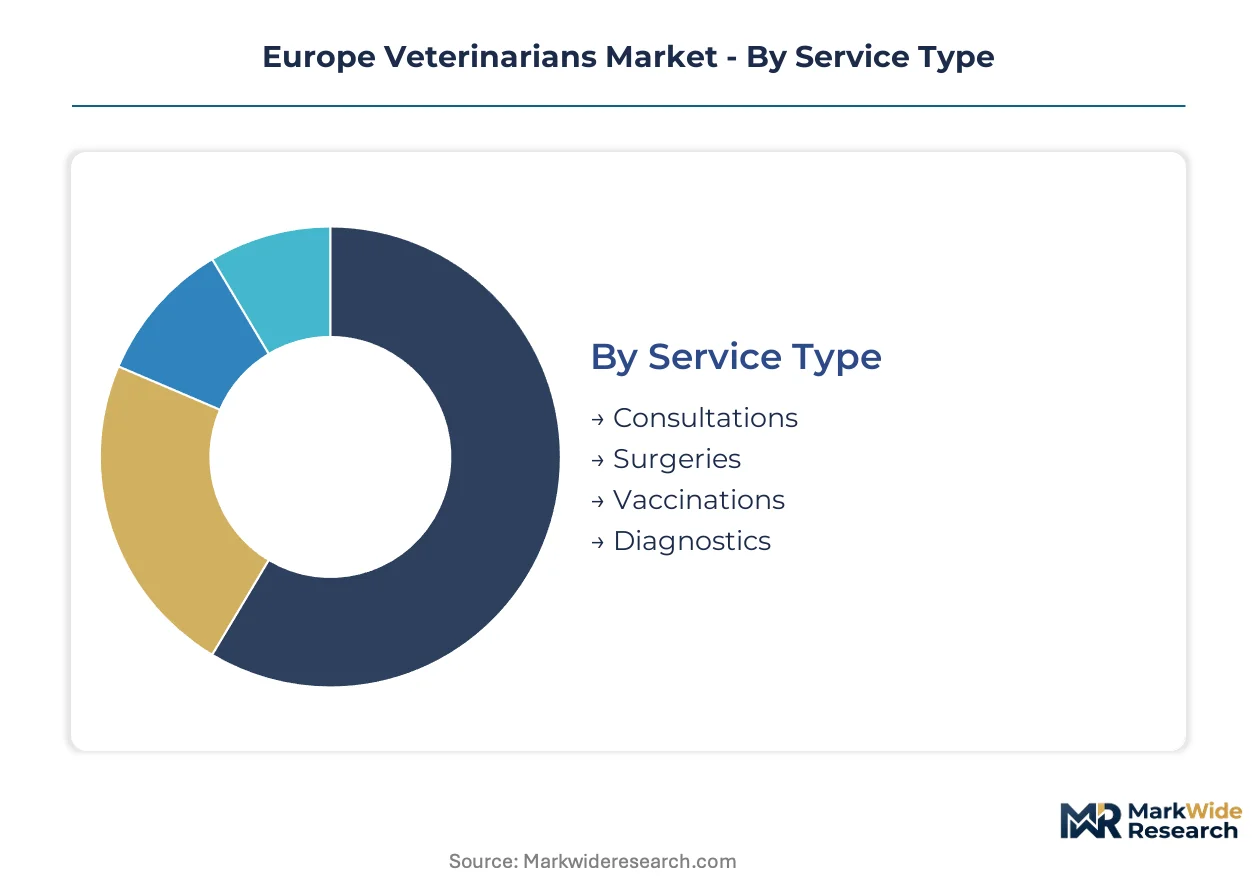
Veterinary service delivery across Europe fragments along clinical capability, animal species concentration, and practice scale economics. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that shape capital allocation decisions.
Service Type:
Domestic demand concentrates in consultative and preventive services across France and Germany, while diagnostic and surgical workflows increasingly cross-border as referral networks consolidate.
- Consultations:Routine examinations and preventive health assessments constitute the volume foundation of European general practice. French and German pet insurance density pulls owners toward scheduled wellness visits rather than reactive episodic care.
- Surgeries:Orthopedic and soft-tissue procedures command premium pricing in UK and Benelux referral centers. Specialist certification bottlenecks constrain throughput despite climbing demand for cruciate repair and oncologic resection.
- Vaccinations:Core immunization protocols anchor client retention in solo practices across Southern Europe. EMA streamlined biologics pathways are expanding clinic formularies for emerging companion animal diseases.
- Diagnostics:Imaging and laboratory services concentrate revenue in urban corridor practices with capital-intensive equipment. AI-powered radiograph interpretation is compressing traditional teleradiology arrangements in London and Munich hospitals.
Consultations command the established base. The steepest expansion runs through diagnostics.
Animal Type:
Cost tier stratification separates species with insurance-backed diagnostic intensity from those reliant on out-of-pocket spending.
- Dogs:Large-breed orthopedic demand and oncology specialization drive capital investment in German and UK referral centers. Subscription wellness plans in Netherlands and Scandinavian markets prioritize canine preventive care packages.
- Cats:Feline internal medicine and dentistry represent underserved capacity relative to population density. French practitioners report rising demand for chronic renal disease management and hyperthyroid treatment protocols.
- Birds:Avian veterinary access concentrates in metropolitan practices with exotic certification. Italian and Spanish urban corridors sustain limited but high-margin specialist services for companion psittacines.
- Reptiles:Herpetological medicine remains a niche specialty with geographic concentration in UK and German academic centers. Herpetofauna import regulations under REACH chemical standards constrain pharmaceutical formulation availability.
Dogs anchor revenue concentration. Cats are gaining share fastest as feline-specific pharmaceutical development accelerates.
Practice Size:
Volume distribution favors small-scale configurations in Southern Europe against consolidated multi-site models in Northern markets.
- Solo Practice:Single-veterinarian operations dominate Spain, Italy, and Portugal, constrained by antimicrobial stewardship compliance costs and legacy record-keeping infrastructure. These configurations face technical debt migrating to cloud-based EMA pharmacovigilance platforms.
- Small Clinic:Two-to-four veterinarian practices balance autonomy with limited diagnostic equipment investment. Polish and Romanian livestock corridors are seeing small clinic formation around cattle and swine productivity initiatives.
- Large Clinic:Multi-veterinarian facilities with in-house imaging capture urban companion animal density in Benelux metropolitan clusters. Telemedicine-triage convergence is opening subscription revenue streams for this tier.
- Referral Center:Tier-one specialty hospitals in London, Munich, and Amsterdam accumulate highest revenue per veterinarian. European College of Veterinary Specialties residency bottlenecks limit specialist supply against expansion plans.
Solo practice holds the installed base. Referral centers climb the fastest as insurance penetration deepens.
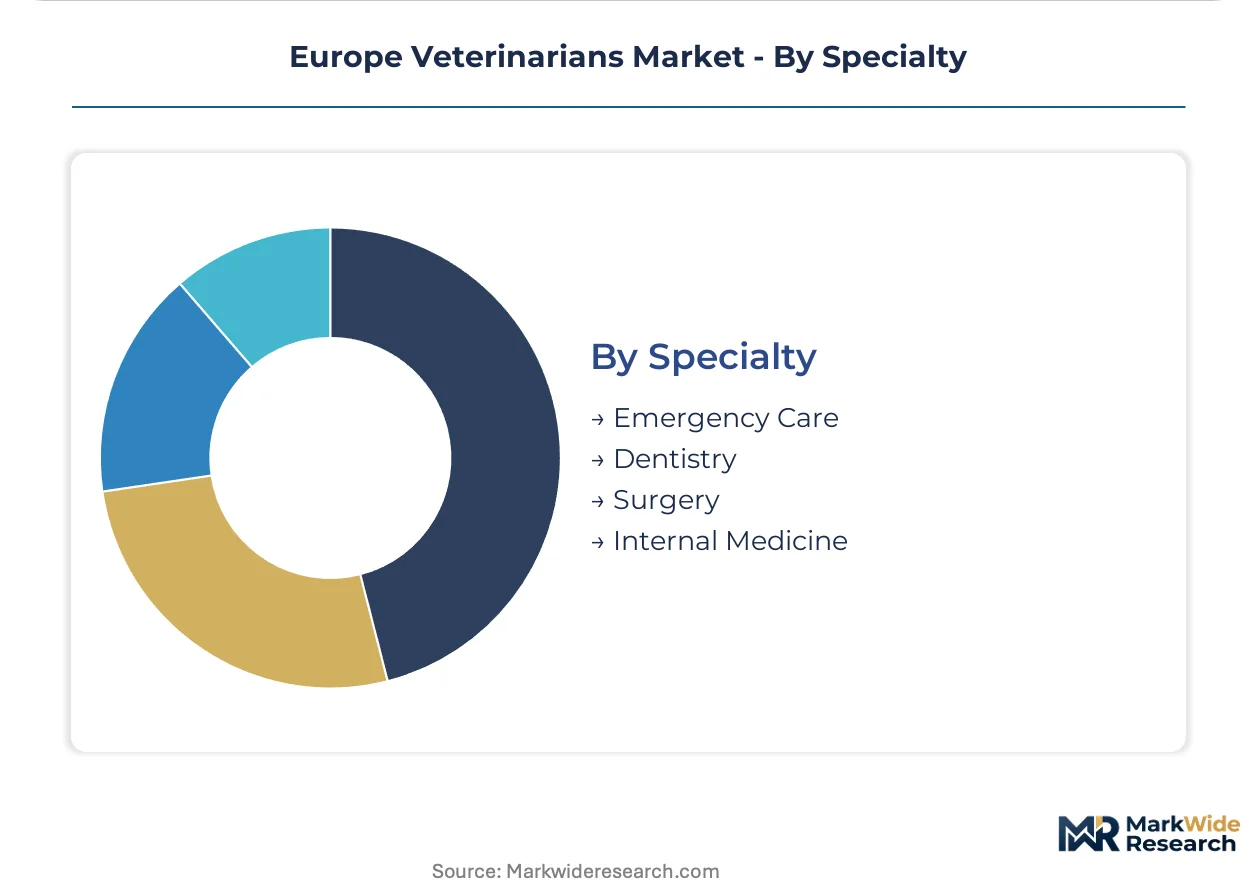
Specialty:
Application intensity separates emergency and surgical disciplines with 24-hour staffing requirements from scheduled appointment-based services.
- Emergency Care:After-hours critical services post the steepest growth trajectory across UK and German urban markets. Workforce shortages constrain overnight coverage expansion despite premium fee structures.
- Dentistry:Periodontal disease treatment and oral surgery represent underpenetrated capacity relative to clinical need. REACH chemical standards revision is tightening excipient requirements for topical dental pharmaceuticals.
- Surgery:Soft-tissue and orthopedic specialization concentrates in academic-affiliated referral centers. Equipment import dependency for MRI and CT systems exposes margin volatility to tariff fluctuations.
- Internal Medicine:Chronic disease management and diagnostic workup sustain recurring revenue in insured companion animal populations. EMA oncology and atopy immunotherapy approvals are expanding therapeutic arsenals.
Internal medicine commands the established specialty base. Emergency care represents the fastest-climbing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary service capacity concentrates in Western European urban corridors where pet insurance density and specialty referral infrastructure co-locate. Eastern accession markets face persistent clinician shortages relative to livestock density.
Germany
Large-breed orthopedic demand and oncology specialization drive capital investment in Munich and Berlin referral centers. BVL antimicrobial stewardship mandates compress solo practice margins while pulling capital toward diagnostic-intensive workflows. The Bavarian metropolitan cluster sustains the deepest specialist veterinarian density in continental Europe.
United Kingdom
Tier-one specialty hospitals in London accumulate highest revenue per veterinarian through 24-hour emergency coverage and advanced imaging services. The RCVS specialist certification pipeline remains bottlenecked against referral center expansion plans. Greater Manchester and West Midlands urban corridors concentrate multi-site practice group consolidation.
France
Companion animal insurance penetration funnels owners toward scheduled wellness visits and preventive care protocols. ANSM pre-approval dialogue accelerates reformulation timelines for topical pharmaceuticals facing REACH chemical standards revision. The Île-de-France region anchors premium service workflows through Parisian academic-affiliated centers.
Netherlands
Subscription-based wellness plans replace episodic fee-for-service billing in Amsterdam and Rotterdam urban practices. Younger pet owners favor predictable monthly outlays covering tele-triage access. Randstad metropolitan clusters concentrate affluent households within 30-minute referral radiuses of large diagnostic-equipped facilities.
Poland
Cattle and swine productivity initiatives generate demand for production animal veterinary services across rural corridors. EU accession-era livestock modernization programs expand small clinic formation around dairy and pork value chains. Warsaw and Kraków metropolitan areas sustain limited companion animal specialty capacity against rising urban pet ownership.
Europe Veterinarians Market Competitive Landscape
Concentration sits with diversified animal health conglomerates commanding integrated pharmaceutical-diagnostics portfolios. Mid-tier European specialists compete through vaccine and parasiticide specialization in production animal corridors. The competitive arena splits between premium-tier referral service networks and volume-driven pharmaceutical suppliers. M&A activity targets point-of-care diagnostics platforms, while strategic partnerships lock in exclusive vaccine distribution across national veterinary networks.
Within the diversified pharmaceutical tier, Boehringer Ingelheim and Zoetis exemplify archetypes anchoring premium service workflows through diagnostics-pharmaceutical integration. Ceva Santé Animale occupies a position representing geographic dominance in poultry health extension. These three entities sit within distinct competitive vectors: vaccine specialization, diagnostics anchoring, and production animal network penetration respectively.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Zoetis |
| Ceva Santé Animale |
| Virbac |
| Elanco |
| IDEXX Laboratories |
| MSD Animal Health |
| Vetoquinol |
| Dechra Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
AI-powered radiograph interpretation displaces traditional teleradiology arrangements while simultaneously pulling procurement decisions toward German and UK metropolitan clusters and compressing margins for standalone imaging services across Southern European solo practices.
Pricing Analysis
The EU Veterinary Medicines Regulation dictates the pricing tier structure across European veterinary services, mandating enhanced record-keeping infrastructure that squeezes solo practice margins while funneling capital toward diagnostic-intensive workflows in insured markets. Three-tier pricing structure across premium, standard, and economy levels separates referral center specialty care from small clinic general practice and solo practitioner episodic services, with premium tiers anchored by specialist certification and equipment density. Cost compression in the standard tier is intensifying because antimicrobial stewardship compliance burdens disproportionately burden smaller configurations. Out-of-pocket spending in Eastern European livestock corridors exhibits highest price sensitivity, while insured companion animal owners in Benelux metropolitan clusters demonstrate lowest elasticity.
Supply Chain Analysis
Extended lead times for MRI and CT systems constrain capital deployment timelines across UK and German referral centers expanding specialty capacity. Equipment manufacturing concentrates in the United States, Japan, and Germany, with component sourcing drawing from Taiwanese semiconductor foundries and South Korean display panel producers. Supply chain risk centers on single-source vulnerability for superconducting magnet assemblies and gradient coil subsystems. Distribution runs through manufacturer-direct sales teams for tier-one hospitals alongside regional veterinary distributors serving small clinic and solo practice configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across practice size configurations and geographic veterinary workforce distribution creates multiple entry niches for differentiated service models, as pet insurance penetration pulls demand toward diagnostic-intensive workflows faster than specialist certification pipelines can supply qualified clinicians.
For Market Incumbents: Shield referral center margins by securing exclusive European College of Veterinary Specialties residency pipeline agreements before competitor expansion accelerates specialist wage inflation. Consolidate cloud-based practice management platform offerings to capture antimicrobial stewardship compliance spend from Southern European solo practitioners facing technical debt migration costs. For New Entrants and Emerging Players: EMA streamlined biologics certification fast-tracks offer entry into oncology and atopy immunotherapy service lines where formulary expansion outpaces specialist veterinarian supply. Target Polish and Romanian livestock corridors for production animal service formation around EU accession-era productivity initiatives. Deploy telemedicine-triage subscription models to capture younger pet owner preference for predictable monthly outlays in Netherlands and Scandinavian urban practices. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors multi-site practice groups with diagnostic equipment density and cloud-based platform infrastructure. Long-term viability over the projection horizon rests on exposure to insured companion animal corridors with deepening specialty referral penetration. Acquisition focus should center on point-of-care diagnostics platforms and telemedicine-enabled practice networks. Monitor European College of Veterinary Specialties residency position expansion rates as inflection indicator for specialist supply constraint relief.| Strategic Initiative | Industry Significance |
|---|---|
| Specialist Certification Pipeline Lock-in | Exclusive residency agreements with European College of Veterinary Specialties secure scarce clinician supply against competitor expansion in UK and German corridors. |
| Cloud Practice Management Platform Migration | Antimicrobial stewardship compliance requirements under EU Veterinary Medicines Regulation create captive demand from Southern European solo practitioners. |
| Point-of-Care Diagnostics Integration | AI-powered radiograph interpretation and laboratory platforms compress traditional referral models while capturing premium workflow value. |
| Telemedicine-Triage Subscription Launch | Predictive monthly billing models align with younger pet owner preferences in Amsterdam and Copenhagen metropolitan clusters. |
| Production Animal Corridor Expansion | Polish and Romanian livestock modernization initiatives generate demand for veterinary services around dairy and pork value chains. |
Research Methodology
Initial hypotheses were tested against primary input from veterinary practice owners, pharmaceutical regulatory affairs leads, pet insurance underwriting executives, and diagnostic equipment procurement managers and refined through secondary validation against EMA veterinary product guidelines, EU Veterinary Medicines Regulation implementation documents, national licensing board formularies from France's ANSM and Germany's BVL, and REACH chemical standards revision notices. Bottom-up service volume estimates triangulated with top-down pharmaceutical and diagnostics revenue allocations.
Variance decomposition across service type, animal species, practice size configuration, and specialty discipline shaped the analytical framework over the projection horizon. CAGRs derived from segmented demand modeling incorporating pet insurance penetration trajectories, antimicrobial stewardship compliance cost curves, and specialist veterinarian supply constraints. Forecast inputs included European College of Veterinary Specialties residency position counts and AI diagnostic platform adoption curves across UK and German referral networks.
Decision-makers should treat outputs as directional under assumptions of steady EU regulatory enforcement and stable pet insurance coverage expansion; material deviation in antimicrobial stewardship stringency or macroeconomic pressure on discretionary companion animal spending would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Swine Respiratory Diseases Treatment Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Veterinary Hospitals Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market
Veterinary
Animal Antibiotics Market
Veterinary
Global Veterinary Infusion Pumps Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Spay and Neuter Market
Veterinary
Global Canine Atopic Dermatitis Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Canine Parvovirus Market
Veterinary
Pet Cancer Therapeutics Market