
 South Africa Spinal Surgery Devices Market | 2026-2036
South Africa Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Spinal Surgery Devices Market Analytics
Modular implant configurations is shifting how procurement teams evaluate spinal systems across South African hospital groups. Medtronic PLC leverages its broad fusion portfolio to anchor long-term supply contracts with private hospital networks. Stryker Corporation competes through specialized navigation and power tool ecosystems that integrate with its implant lines. DePuy Synthes (Johnson & Johnson) sustains market presence via extensive distributor relationships that reach secondary cities beyond the major metros.
South Africa spinal surgery devices encompass instruments, implants, and biologics designed to stabilize, decompress, or correct spinal pathologies through open or minimally invasive approaches; titanium alloy and polyetheretherketone (PEEK) constructions dominate load-bearing applications due to biocompatibility and radiolucency requirements. Fusion devices occupy the largest revenue pool as degenerative disc disease and spondylolisthesis cases drive anterior and posterior lumbar interbody fusion demand. Minimally invasive surgery represents the fastest-expanding procedure category, fueled by reduced hospitalization costs and faster recovery trajectories that appeal to cost-sensitive medical schemes.
SAHPRA governs medical device registration and post-market surveillance, while the South African Bureau of Standards (SABS) enforces quality management system certifications that foreign manufacturers must obtain for market entry. The National Health Insurance (NHI) white paper signals future procurement centralization, creating uncertainty for premium-priced robotic and navigation-assisted systems. Stakeholders must monitor NHI implementation timelines and SAHPRA registration backlogs to align product portfolios with evolving reimbursement and access pathways.
Market Dynamics
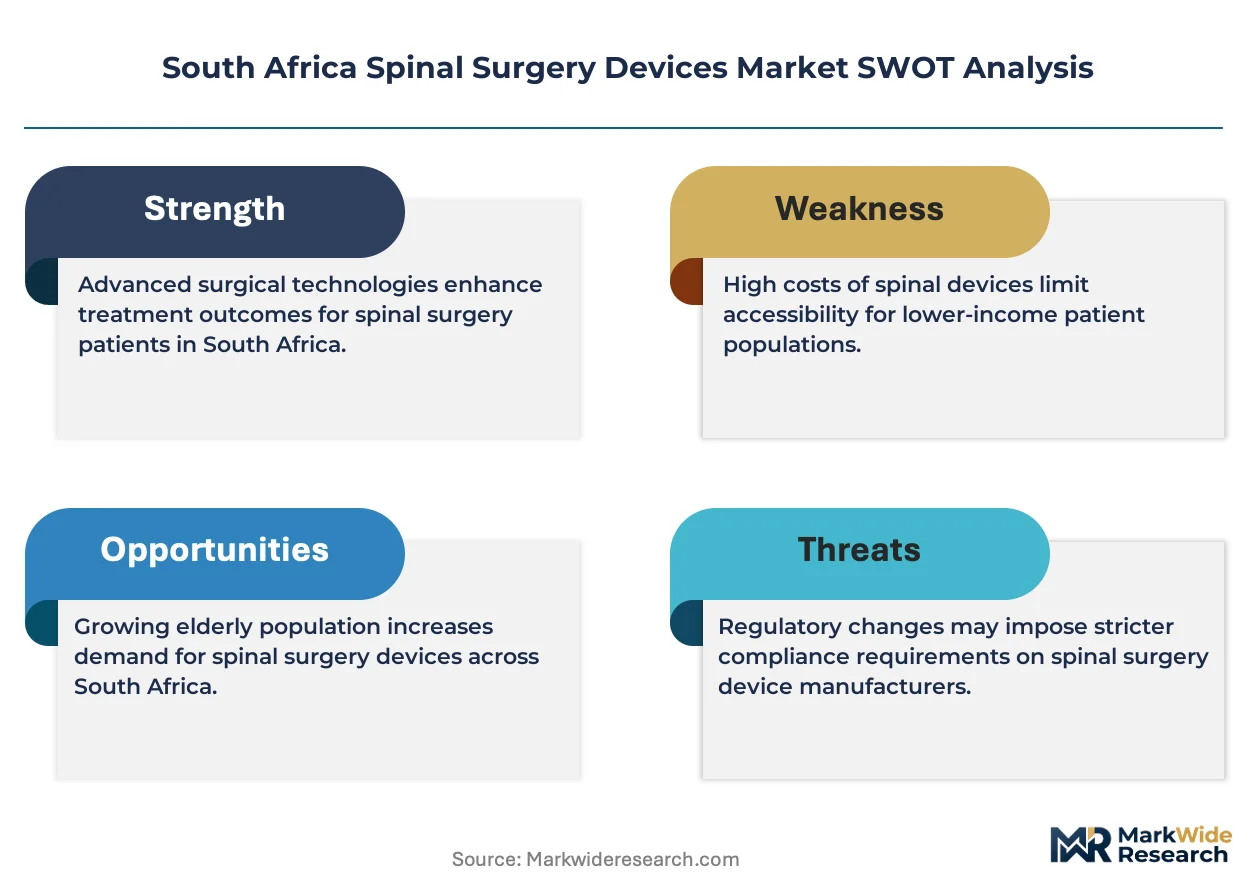
SAHPRA's tightened implant registration requirements are compressing distributor networks toward certified supply chains, concentrating procurement authority within Gauteng and Western Cape hospital groups while marginalizing uncertified intermediaries.
Growth Catalysts
- Minimally Invasive Surgery (MIS) adoption:Private hospital networks in Johannesburg and Cape Town are expanding MIS procedure volumes as medical schemes favor reduced hospitalization costs and faster patient recovery trajectories.
- SAHPRA registration enforcement:The regulatory body's stricter post-market surveillance requirements are pushing distributors toward transparent supply chains, improving product traceability and patient safety outcomes.
- Titanium alloy and PEEK material advances:Biocompatibility and radiolucency improvements in load-bearing constructions are expanding surgical indications for complex spinal interventions across tertiary referral networks.
Market Restraints
- Import dependency for precision-machined implants:South Africa lacks domestic titanium forging capacity, exposing procurement teams to currency volatility and extended lead times from European and Asian suppliers.
- SAHPRA registration backlog:Extended approval timelines for novel navigation and robotic systems delay market entry for advanced surgical technologies, compressing effective patent windows.
- Specialized surgeon scarcity:Complex spinal procedures require fellowship-trained orthopaedic and neurosurgical specialists concentrated in Johannesburg, Cape Town, and Durban, limiting procedure volume expansion into secondary cities.
Strategic Opportunities
- KwaZulu-Natal expansion:Durban's tertiary hospital infrastructure remains underutilized relative to population density, creating white space for distributor partnerships and surgeon training programs.
- NHI procurement centralization:The National Health Insurance white paper signals future bulk purchasing authority, positioning early movers to secure long-term supply contracts with public sector anchor institutions.
- Biologics integration with fusion hardware:Convergence of synthetic bone graft substitutes with interbody cages offers premium positioning opportunities as private schemes expand coverage for advanced fusion constructs.
Industry Challenges
- SAHPRA compliance timeline compression:Foreign manufacturers face parallel-track requirements for quality management certification through SABS and product registration, stretching regulatory affairs resources.
- Legacy inventory reconciliation:Distributors must clear pre-2020 implant stocks that lack updated SAHPRA registration documentation, creating working capital strain and obsolescence risk.
- Surgeon training infrastructure gaps:Cadaveric lab access and proctoring networks for navigation-assisted techniques remain concentrated in metropolitan academic centers, slowing adoption curve flattening.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Spinal Surgery Devices Market |
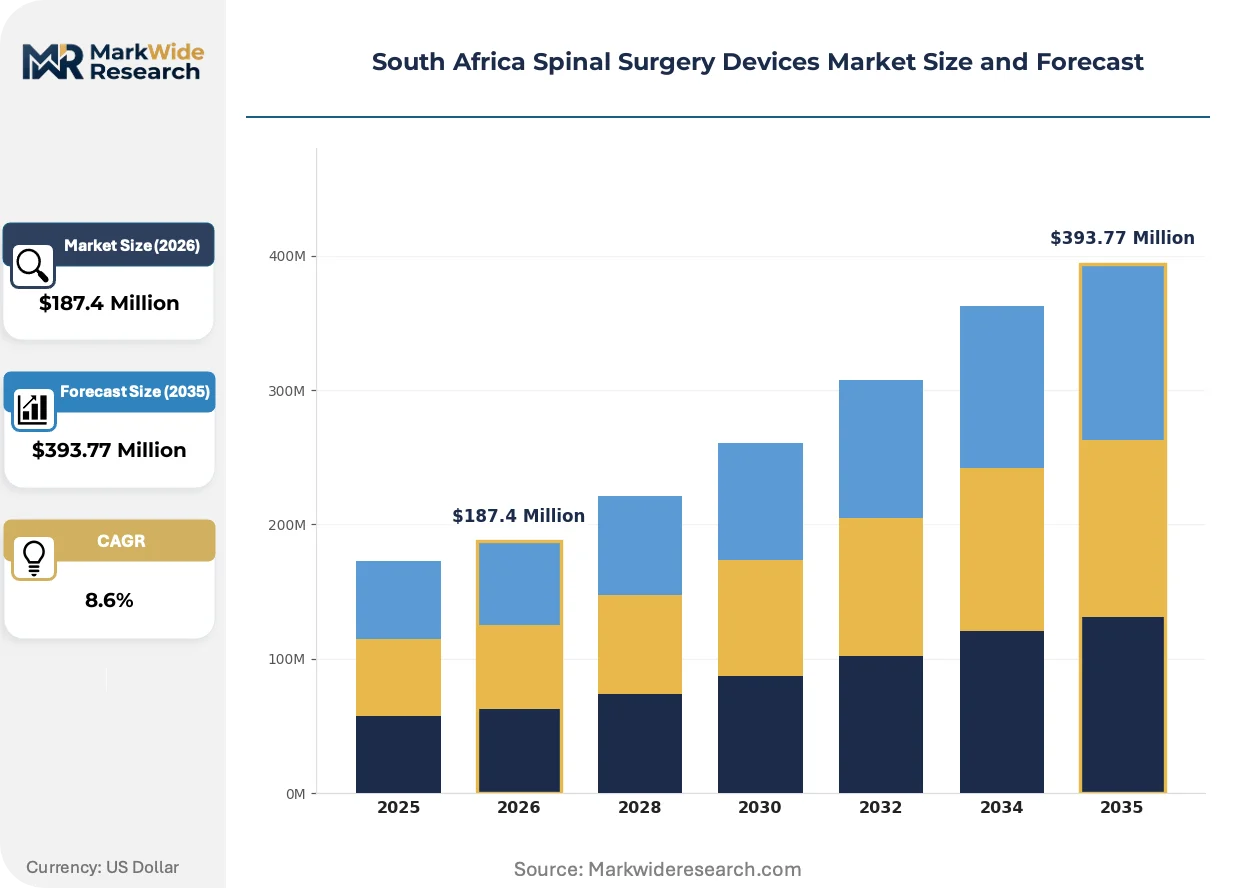
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Fusion Devices, Non-fusion Devices, Implants, Bone Grafts End User: Hospitals, Outpatient Surgical Centers, Specialty Clinics, Rehabilitation Centers Procedure Type: Open Surgery, Minimally Invasive Surgery, Robotic Surgery, Revision Surgery Material: Metal, Polymer, Ceramic, Composite |
| Companies Covered | Medtronic PLC, Stryker Corporation, DePuy Synthes (Johnson & Johnson), Globus Medical Inc., Zimmer Biomet Holdings Inc., NuVasive Inc., Alphatec Spine Inc., Orthofix Medical Inc., B. Braun Melsungen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Spinal Surgery Devices Market Evolving Landscape
Navigation-assisted and robotic surgical platforms are penetrating South African private hospital networks, compressing the learning curve for complex deformity correction while reshaping capital equipment procurement cycles and service contract structures.
Robotic navigation systems are integrating preoperative planning software with intraoperative guidance to reduce screw malposition rates in posterior spinal fusion. Private hospital groups in Gauteng are deploying these platforms at select flagship facilities to differentiate their orthopaedic service lines. This technology is integrating surgical training programs with real-time feedback loops, accelerating competency development among fellowship-trained spine surgeons.
SAHPRA's alignment with International Medical Device Regulators Forum (IMDRF) principles is harmonizing South African registration requirements with FDA and EMA standards. Foreign manufacturers now face streamlined documentation pathways for products already approved in major jurisdictions. High-value navigation and robotic systems are most affected, with vendors accelerating SAHPRA submissions to secure first-mover positioning ahead of NHI procurement centralization.
Medical scheme administrators are unbundling device reimbursement from surgical professional fees, creating direct price transparency between implant vendors and funders. This restructuring concentrates purchasing leverage within scheme-managed preferred provider networks in Johannesburg and Cape Town. The Eastern Cape and Limpopo provinces lag in this transition, retaining traditional fee-for-service models that obscure true device costs.
South Africa Spinal Surgery Devices Market Segmentation
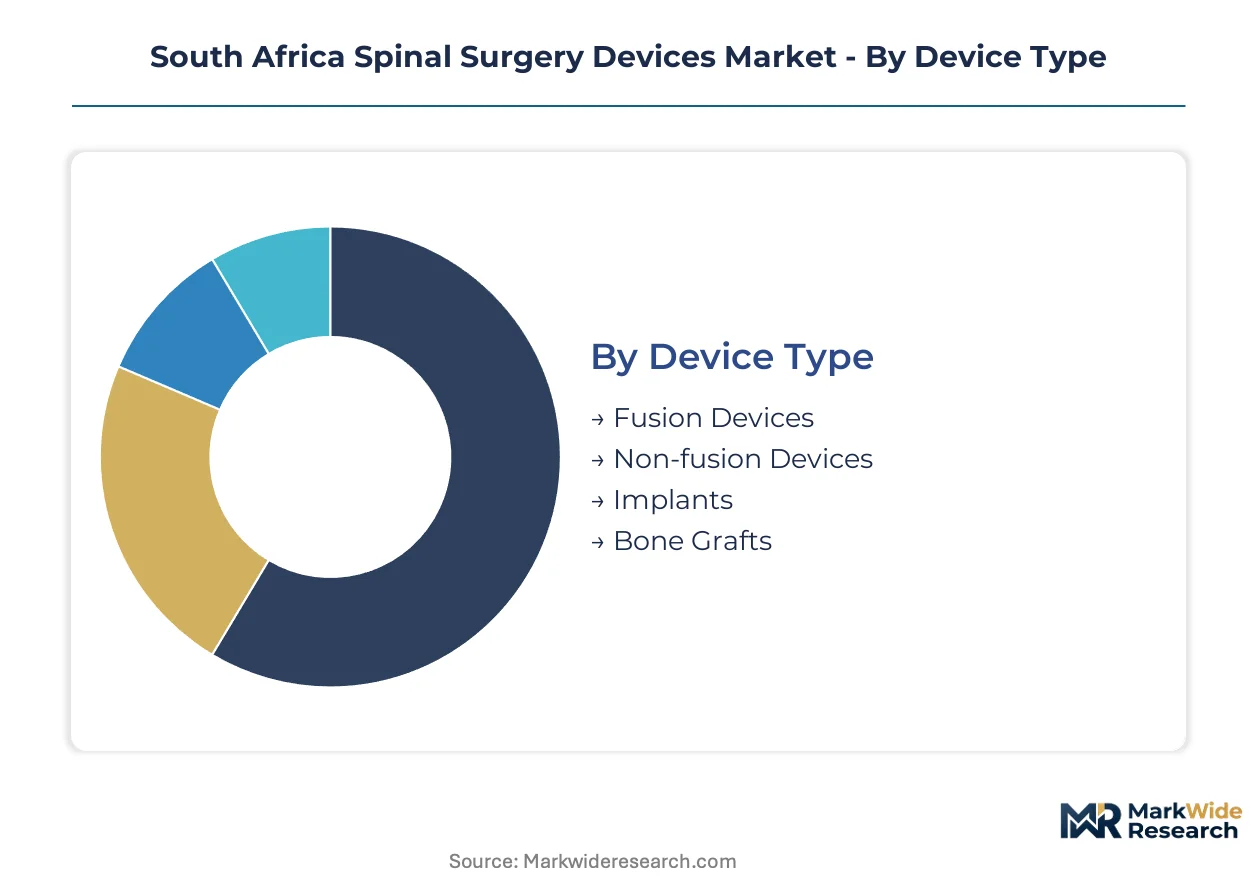
Device categorization in South Africa spinal surgery devices reveals distinct procurement patterns across private hospital networks and public sector channels. Each segment carries unique SAHPRA registration requirements and reimbursement pathways that shape vendor positioning.
Device Type:
Procurement teams differentiate spinal systems by surgical indication and long-term implant durability requirements.
- Fusion Devices:Interbody cages and pedicle screw systems fabricated from titanium alloy or PEEK polymer dominate anterior and posterior lumbar fusion procedures. Johannesburg and Cape Town tertiary hospitals anchor demand as degenerative disc disease caseloads concentrate in Gauteng and Western Cape referral networks.
- Non-fusion Devices:Dynamic stabilization systems and artificial disc replacements preserve motion segment biomechanics. Private medical schemes in Durban and Pretoria are selectively expanding coverage for these alternatives as durability data from European registries influences local policy.
- Implants:Bone screws, rods, and plates for fracture fixation and deformity correction.
- Bone Grafts:Autograft harvest systems and synthetic bone void fillers for fusion augmentation.
Volume sits with fusion hardware; growth tilts toward non-fusion alternatives.
End User:
Facility infrastructure determines capital equipment compatibility and surgeon training investment levels.
- Hospitals:Tertiary academic centers and private hospital groups in Johannesburg, Cape Town, and Durban perform complex deformity correction and multi-level fusion. These institutions command procurement leverage through high-volume contracts with Medtronic, Stryker, and DePuy Synthes.
- Outpatient Surgical Centers:Ambulatory facilities in Gauteng suburbs are expanding single-level microdiscectomy and decompression volumes. Reduced overhead costs and faster patient throughput attract medical scheme preferred provider network designation.
- Specialty Clinics:Orthopaedic and neurosurgical practices with limited procedure rooms.
- Rehabilitation Centers:Postoperative care facilities coordinating device-related physical therapy protocols.
Procedure concentration favors hospital-based surgery; ambulatory expansion is climbing fastest.
Procedure Type:
Surgical approach selection drives instrument tray configuration and capital equipment procurement cycles.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw placement reduce tissue disruption and hospitalization duration. Private hospital groups in the Western Cape are prioritizing MIS training to differentiate orthopaedic service lines and capture medical scheme volume incentives.
- Robotic Surgery:Navigation-assisted platforms integrate preoperative planning with intraoperative guidance for screw trajectory optimization. SAHPRA registration timelines for these systems lag FDA and EMA approvals, compressing effective commercialization windows.
- Open Surgery:Traditional posterior approaches for complex deformity and trauma.
- Revision Surgery:Hardware removal and revision fusion for pseudarthrosis or adjacent segment disease.
Open procedures retain case volume; robotic systems are gaining share fastest.
Material:
Biocompatibility certification and radiolucency requirements filter supplier qualification for SAHPRA registration.
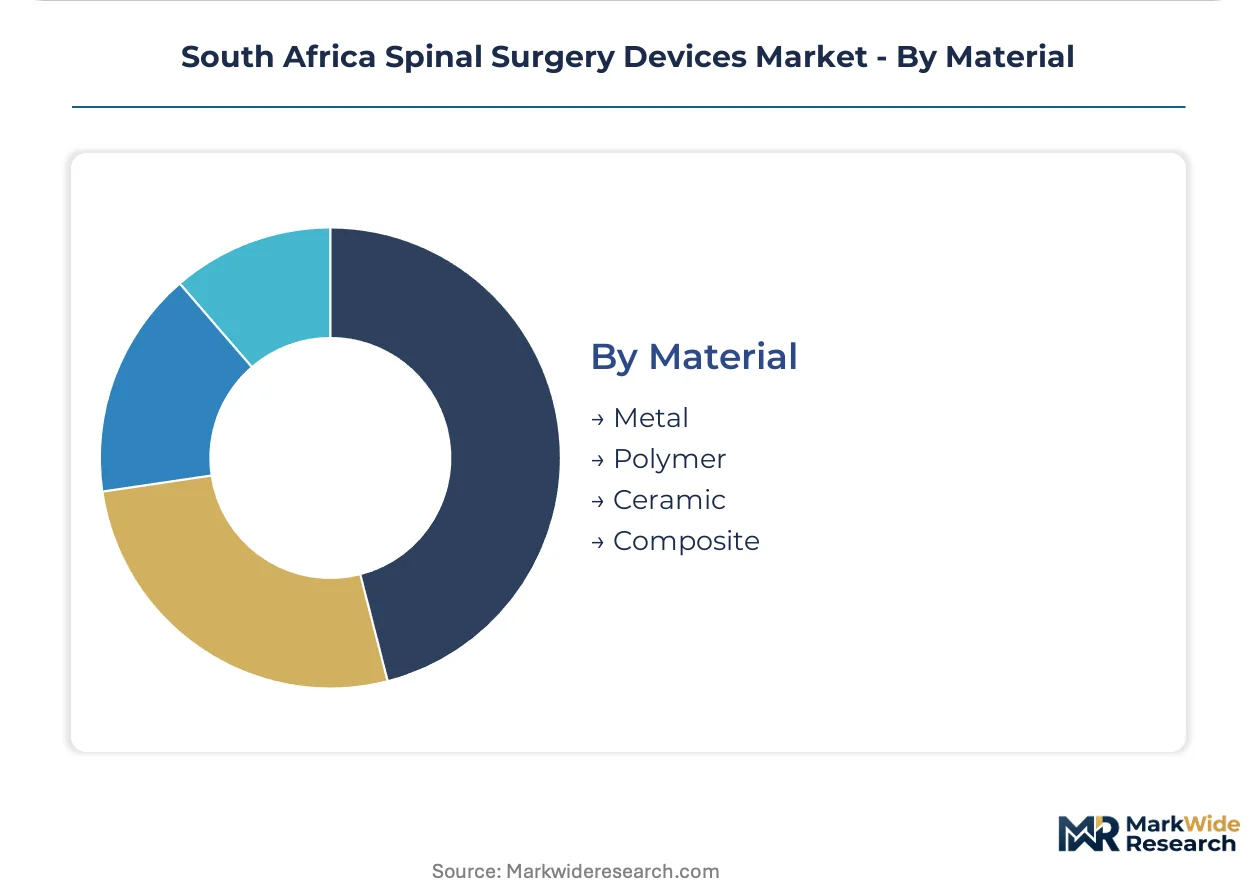
- Metal:Titanium alloy constructs dominate load-bearing applications due to strength-to-weight ratio and osseointegration properties. European and Asian forging suppliers control raw material sourcing, exposing South African distributors to currency volatility and extended lead times.
- Polymer:PEEK interbody cages offer radiolucency for postoperative imaging assessment. Demand concentrates in private hospital networks where advanced imaging protocols justify premium material costs.
- Ceramic:Alumina and zirconia components for bearing surfaces in motion-preserving devices.
- Composite:Carbon fiber reinforced polymers for radiolucent instrumentation.
Metal systems anchor procurement volume; polymer adoption shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa produces no precision-machined titanium spinal implants domestically, forcing complete reliance on imported European and Asian supply chains. Gauteng, Western Cape, and KwaZulu-Natal provinces concentrate procedure demand and procurement authority.
Gauteng
Johannesburg's tertiary hospital networks anchor the highest spinal fusion volumes nationwide. SAHPRA registration requirements filter distributor access, concentrating certified supply chains within private hospital groups. Pretoria's academic medical centers train fellowship surgeons who disperse to secondary cities.
Western Cape
Cape Town private hospital chains are expanding minimally invasive surgery capacity to capture medical scheme volume incentives. The province's medical device distributors maintain direct relationships with European forging suppliers. Stellenbosch University's surgical training programs feed specialist talent into regional referral networks.
KwaZulu-Natal
Durban's tertiary infrastructure remains underutilized relative to population density, creating expansion white space. Private schemes here are selectively expanding coverage for motion-preserving alternatives as durability data accumulates. Distributor partnerships and surgeon training programs are penetrating this gap.
Eastern Cape
Port Elizabeth and East London retain traditional fee-for-service reimbursement models that obscure true device costs. Public sector procurement through Eastern Cape Health lags private scheme unbundling trends. Specialist surgeon scarcity limits complex procedure expansion beyond Gqeberha's academic center.
Free State
Bloemfontein's Universitas Academic Hospital anchors regional spinal trauma referrals from rural hinterlands. The province depends on Gauteng-based distributors for implant logistics, extending lead times. Public sector budget constraints favor basic fusion hardware over navigation-assisted platforms.
South Africa Spinal Surgery Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South Africa's spinal surgery devices market. Tier-one multinational medical technology corporations anchor procurement contracts through broad fusion portfolios and integrated navigation ecosystems. Mid-tier distributors battle regulatory compliance costs as SAHPRA tightens registration enforcement. Competitive moves concentrate on securing long-term supply agreements with expanding private hospital networks and navigating NHI procurement centralization timelines.
Among the diversified multinational tier, Medtronic PLC, Stryker Corporation, and DePuy Synthes occupy positions defined by comprehensive implant portfolios and established distributor relationships. Medtronic exemplifies the broad fusion portfolio archetype anchoring hospital group contracts. Stryker represents the navigation-integrated ecosystem approach. DePuy Synthes sits within the extensive geographic reach archetype penetrating secondary cities beyond major metros.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker Corporation |
| DePuy Synthes (Johnson & Johnson) |
| Globus Medical Inc. |
| Zimmer Biomet Holdings Inc. |
| NuVasive Inc. |
| Alphatec Spine Inc. |
| Orthofix Medical Inc. |
| B. Braun Melsungen AG |
| Others |
Value Network & Pricing Analysis
Fellowship-trained spinal surgeon concentration in Johannesburg, Cape Town, and Durban creates labor-cost differentials that widen pricing-tier spreads between metropolitan tertiary centers and secondary-city facilities.
Pricing Analysis
Cost-down pressure on standard fusion hardware accelerates because medical scheme administrators are unbundling device reimbursement from surgical professional fees. Three-tier pricing structure across premium navigation-assisted systems, standard titanium-PEEK constructs, and economy-grade basic fusion hardware dominates procurement. SAHPRA certification grade and volume scale drive price differentiation. Private hospital groups in Gauteng and the Western Cape exhibit lowest price sensitivity due to medical scheme preferred provider network incentives; Eastern Cape public sector procurement shows highest sensitivity amid budget constraints.
Supply Chain Analysis
Titanium alloy forging capacity rests on German, Swiss, and South Korean precision-machining suppliers. Raw material dependencies span titanium sponge from Ukrainian and Russian sources, PEEK polymer from Victrex and Solvay facilities in the UK and Belgium, and navigation system electronics from Taiwanese semiconductor foundries. Single-source vulnerability concentrates in European forging houses for complex interbody cage geometries. Distribution runs through Gauteng-based certified distributors with direct hospital group contracts, bypassing legacy uncertified intermediaries marginalized by SAHPRA enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa spinal surgery devices functions as a consolidation play where SAHPRA registration compliance costs are forcing sub-scale distributors and uncertified intermediaries toward exit or acquisition.
For Market Incumbents: To counter emerging pure-play navigation specialists, anchor long-term supply contracts with expanding private hospital networks in KwaZulu-Natal and secure SABS quality management certification ahead of NHI procurement centralization timelines. Deepen backward integration into biologics-synthetic bone graft combinations to capture premium positioning as medical schemes expand advanced fusion construct coverage.
For New Entrants and Emerging Players: Enter via Durban's underutilized tertiary infrastructure where population density exceeds current procedure volume, targeting motion-preserving non-fusion alternatives as private schemes selectively expand coverage based on European registry durability data. Partner with Stellenbosch University surgical training programs to accelerate surgeon competency development and differentiate against established navigation-integrated ecosystems.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier distributors possessing SAHPRA-certified supply chains and direct Gauteng hospital group relationships given NHI procurement centralization will favor consolidated, compliant vendors. Watch SAHPRA registration backlog resolution velocity as the inflection indicator for advanced robotic and navigation system market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Acceleration | First-mover positioning in navigation-assisted platforms ahead of NHI procurement centralization secures premium hospital group contracts. |
| Hospital System Partnership | Direct supply agreements with Netcare and Life Healthcare groups in Gauteng anchor volume against distributor consolidation. |
| Surgeon Training Program Expansion | Proctoring networks at Stellenbosch and University of Cape Town accelerate MIS adoption curve flattening beyond metropolitan centers. |
| Biologics Integration Development | Synthetic bone graft-interbody cage combinations capture medical scheme premium reimbursement as fusion construct coverage expands. |
| KwaZulu-Natal Distribution Buildout | Durban infrastructure partnerships address population-procedure volume mismatch in highest-density underserved province. |
Research Methodology
SAHPRA registration databases, hospital procurement contract disclosures, and medical scheme reimbursement policy documents formed the secondary backbone. Primary interviews with spinal surgeons, hospital purchasing committee members, biomedical engineers at tertiary centers, and GPO contracts managers validated demand assumptions. Customs import records for titanium implants and PEEK constructs provided supply-side triangulation against bottom-up procedure volume estimates.
Bottom-up modeling anchored forecast outputs, with top-down macro health expenditure trends serving as boundary checks. Segmentation dimensions spanned device type, procedure approach, material composition, and end-user facility tier across the projection horizon. CAGRs derived from procedure volume trajectories, medical scheme coverage expansion rates, and capital equipment replacement cycles. SAHPRA approval timelines and NHI implementation milestones fed scenario-weighted outcomes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged registration backlogs or accelerated NHI procurement centralization. Assumptions reflect current reimbursement unbundling trends and distributor certification status. Currency volatility against the euro and yen, surgeon training pipeline constraints, and public sector budget reallocations warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Veterinary Orthopedic Drills Market