
 Global Veterinary Electrosurgery Market | 2026-2036
Global Veterinary Electrosurgery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Electrosurgery Market Foresight
Veterinary surgical technician training capacity is reorganizing how quickly clinics adopt advanced electrosurgical platforms. Medtronic leverages its human-electrosurgery R&D intensity to transfer bipolar vessel-sealing technology into veterinary suites. Covetrus sustains broad channel control across North American and European distribution networks for capital equipment. KARL STORZ dominates rigid endoscopy-electrosurgery integration, a sub-area where few competitors match optical-surgical convergence.
Veterinary electrosurgery employs radio-frequency alternating current, typically 300 kHz to 3 MHz, to cut, coagulate, or desiccate tissue through resistive heating with controlled thermal spread. Electrosurgical generators constitute the core capital segment, while smoke evacuators represent the fastest-growing attachment category as occupational safety standards for surgical plume harden. Soft tissue surgery anchors procedure volume, though orthopedic applications gain traction as TPLO and other bone-oriented techniques migrate from specialty to general practice.
The FDA Center for Veterinary Medicine and EU MDR frame device clearance pathways, while ISO 13485 quality management and IEC 60601 electrical safety standards govern design verification and international market access. Japan's PMDA and METI impose additional electromagnetic compatibility testing that filters which manufacturers enter Asia-Pacific's second-largest market. Stakeholders must monitor how regional notified-body capacity bottlenecks and evolving veterinary-specific biocompatibility requirements reshape competitive entry timelines.
Market Dynamics
Veterinary electrosurgery is bifurcating between high-frequency bipolar platforms and legacy monopolar systems as specialist hospitals prioritize vessel-sealing precision over cost-driven procurement. This technological divergence is compressing mid-tier equipment margins while elevating service-contract profitability for integrated suite vendors.
Growth Catalysts
- Bipolar Vessel-Sealing Technology:Advanced radio-frequency platforms reduce thermal spread to sub-millimeter zones, enabling safer soft-tissue resections in companion animal oncology. Specialist veterinary hospitals in the United States are retrofitting surgical suites with these systems to match human-grade outcomes.
- EU MDR Biocompatibility Mandates:Stricter electrical safety and material testing requirements for active implantable devices are filtering out non-compliant manufacturers. This regulatory elevation is consolidating procurement toward ISO 13485-certified suppliers with validated quality management systems.
- Smoke Evacuator Attachment Demand:Occupational health standards for surgical plume exposure are hardening across Germany and Japan. Clinics are bundling evacuator systems with generator purchases to meet workplace safety inspector requirements.
Market Restraints
- Copper and Semiconductor Input Volatility:Electrosurgical generator manufacturing depends on precision-wound transformers and RF power modules. Supply concentration for these components in East Asian foundries creates margin pressure during commodity price spikes.
- Notified-Body Capacity Bottlenecks:EU MDR conformity assessment timelines for active surgical devices now exceed eighteen months in some member states. Small manufacturers face working capital strain during extended clearance periods.
- Laser Surgery Substitution:Carbon dioxide and diode laser platforms compete for soft-tissue procedures in equine and exotic animal practices. These alternatives eliminate grounding pad requirements and reduce collateral thermal damage in delicate anatomical regions.
Strategic Opportunities
- Brazilian Specialist Hospital Expansion:São Paulo and Rio de Janeiro are adding dedicated veterinary oncology and orthopedic centers. ANVISA regulatory harmonization with ISO standards is shortening market entry timelines for foreign device manufacturers.
- Rigid Endoscopy-Electrosurgery Convergence:Integrated visualization-cautery platforms enable minimally invasive procedures previously limited to open surgery. This technology pairing is migrating from academic referral hospitals to high-volume general practices.
- India's PLI Scheme for Medical Devices:Production-linked incentives for domestic manufacturing of active surgical equipment are attracting component suppliers to Gujarat and Karnataka clusters. This policy tailwind supports cost-competitive export positioning.
Industry Challenges
- Veterinary Surgical Technician Training Capacity:Advanced bipolar and vessel-sealing platforms require hands-on credentialing beyond standard electrosurgery certification. North American veterinary technology programs are struggling to update curricula at the pace of equipment evolution.
- Legacy Generator Integration Complexity:Clinics with substantial capital invested in monopolar systems face workflow disruption when adopting bipolar platforms. Footswitch compatibility and grounding pad standardization issues complicate mixed-fleet operating room configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Electrosurgery Market |
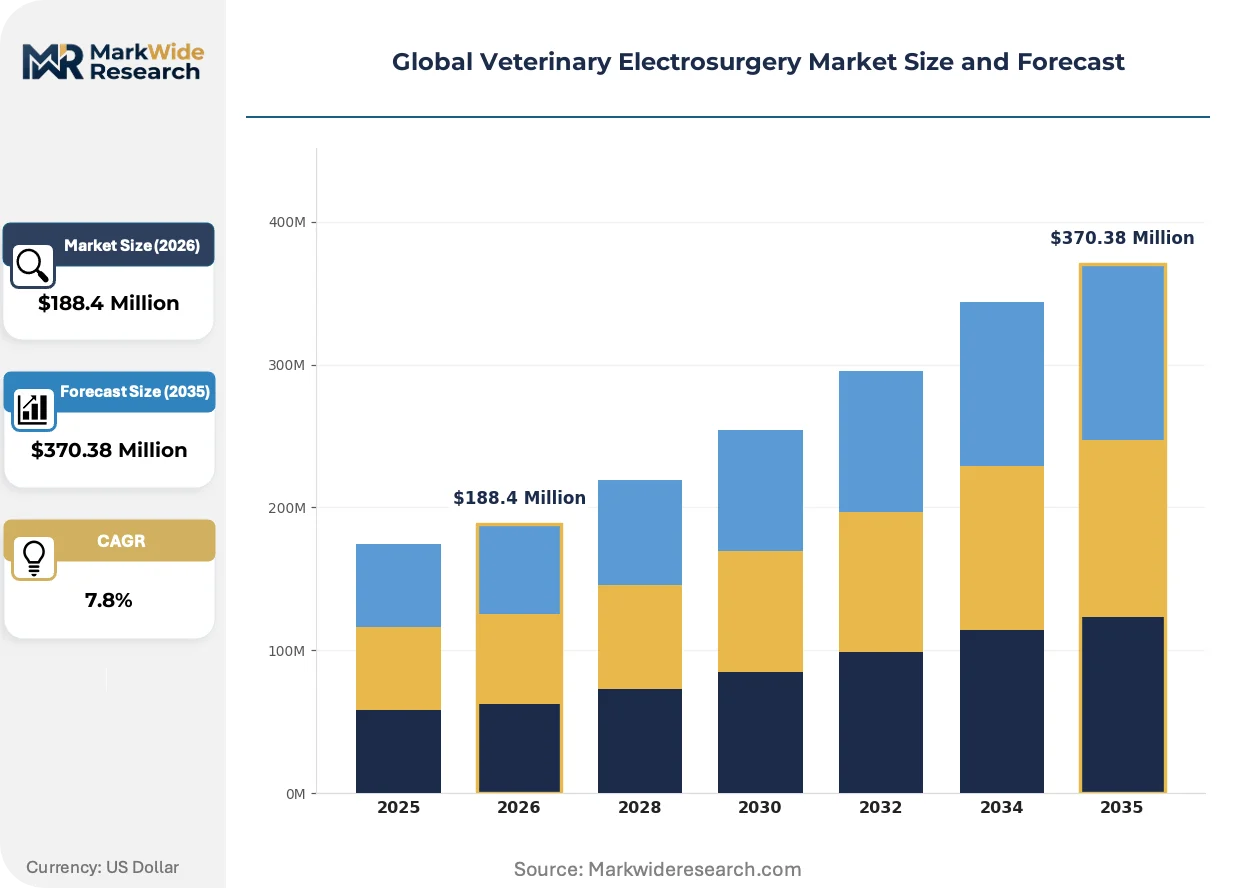
| Market Size in 2026 | $188.4 Million |
| Market Size in 2035 | $370.38 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrosurgical Generators, Electrosurgical Instruments, Smoke Evacuators, Disposables Application: Soft Tissue Surgery, Orthopedic Surgery, Dermatology Procedures, Gynecological Operations, Ophthalmic Surgery End User: Veterinary Clinics, Animal Research Centers, Mobile Veterinary Services, Equine Hospitals, Zoos Deployment: Fixed Installation, Portable Units, Battery Operated Devices, Integrated Surgical Suites |
| Companies Covered | Medtronic, Covetrus, Symmetry Surgical, B. Braun, Integra LifeSciences, Avante Animal Health, KARL STORZ, Eickemeyer, Burtons Medical Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Electrosurgery Market Shifts & Advancements
Radio-frequency energy delivery is fragmenting across multiple technological paradigms as manufacturers compete on thermal precision, smoke management, and connectivity integration. This diversification is reshaping R&D allocation and partnership strategies across the supplier base.
Adaptive impedance-sensing generators are bifurcating the equipment market by automatically adjusting power output based on real-time tissue resistance feedback. Specialist veterinary hospitals in Germany and Japan are prioritizing these systems for oncologic resections where margin control is critical. This capability is compressing demand for fixed-output generators while elevating service revenue from calibration-dependent platforms.
Japan's PMDA and METI electromagnetic compatibility testing requirements are filtering which manufacturers access the Asia-Pacific's second-largest veterinary device market. These standards exceed baseline IEC 60601 provisions for conducted emissions and harmonic distortion. European and North American suppliers are establishing dedicated Tokyo testing partnerships to avoid multi-month regulatory delays.
Leasing and subscription-based equipment access are displacing outright capital purchases among independent companion animal clinics in the United States. Distributors are unbundling preventive maintenance from capital contracts to capture recurring revenue streams. This financing shift is most visible in California and Texas metropolitan markets where clinic consolidation has concentrated buying power among multi-site operators.
Global Veterinary Electrosurgery Market Segmentation
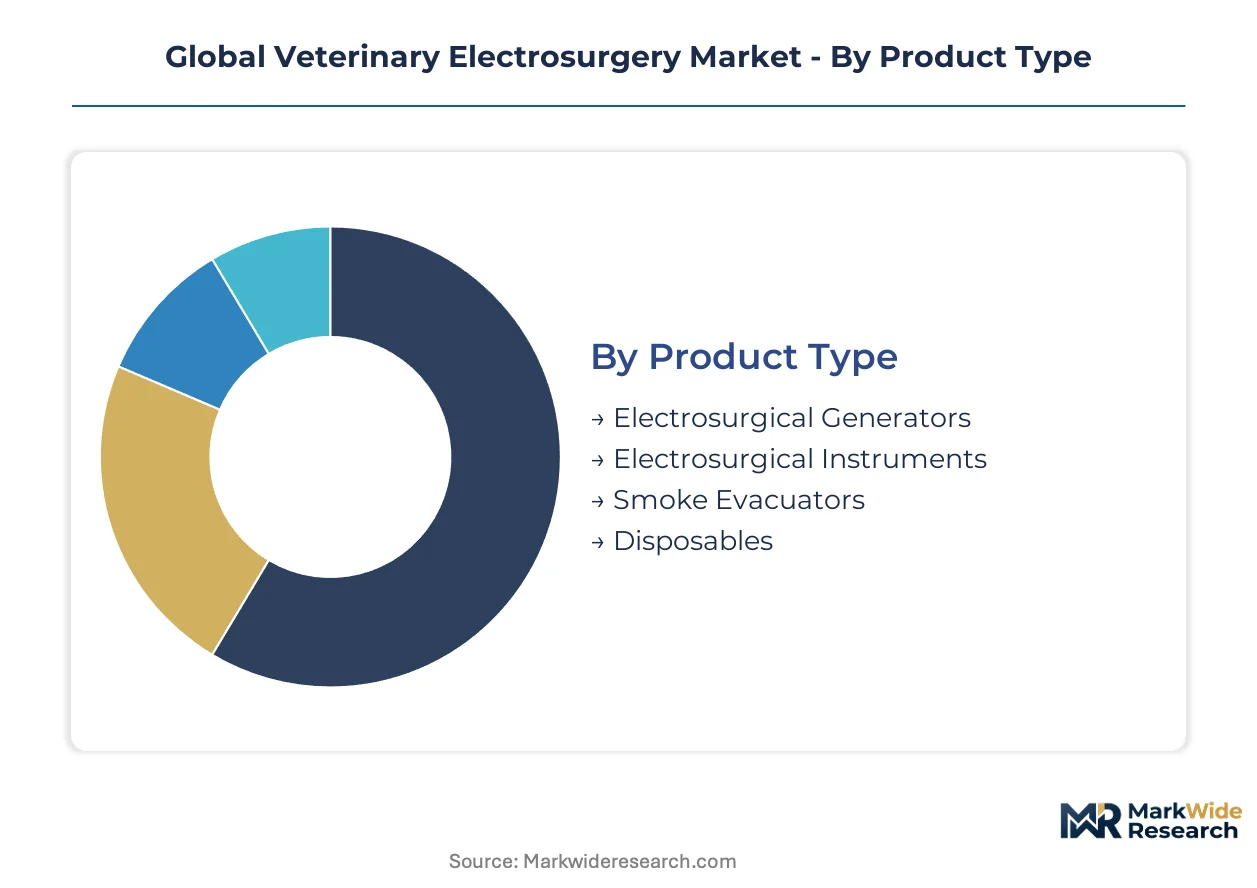
Veterinary electrosurgery segments diverge sharply by capital intensity and procedure specialization. Product type determines margin structure, while end-user configuration shapes purchasing authority and service contract terms across companion and production animal settings.
Product Type:
Smoke evacuators face the most acute substitution pressure from standalone filtration systems and laser surgery platforms that eliminate plume generation entirely.
- Electrosurgical Generators:Radio-frequency power units deliver 300 kHz to 3 MHz current for cutting and coagulation. Specialist veterinary hospitals in Germany prioritize adaptive impedance-sensing models for oncologic margin control.
- Smoke Evacuators:High-flow suction systems with ULPA filtration capture surgical plume at the source. Workplace safety inspector mandates across Japan and Germany are bundling these with generator purchases.
- Electrosurgical Instruments:Handpieces, electrodes, and forceps interface with generator outputs. Reusable instrument demand concentrates in high-volume United States metropolitan practices.
- Disposables:Single-use grounding pads, tips, and drapes reduce cross-contamination risk. Procurement is shifting toward bulk contracts among multi-site clinic operators in Texas and California.
Electrosurgical generators anchor the volume base while smoke evacuators gain share at the steepest rate.
Application:
Cost tier stratification separates high-complexity oncologic resections from routine soft-tissue procedures performed in general practice.
- Soft Tissue Surgery:Abdominal and thoracic procedures constitute the procedural backbone. General companion animal clinics in the United States perform these at volume, though margin pressure from laser alternatives is intensifying.
- Orthopedic Surgery:TPLO and other bone-oriented techniques require precision thermal control. Specialist hospitals in Japan are retrofitting suites with bipolar vessel-sealing platforms for these applications.
- Dermatology Procedures:Mass removals and cosmetic interventions leverage fine-tip electrodes. Mobile veterinary services in Brazil favor portable generators for field-based dermatology.
- Gynecological Operations:Spays and reproductive surgeries drive disposables consumption. High-volume sterilization programs in Indian veterinary clinics create recurring revenue attachment opportunities.
- Ophthalmic Surgery:Delicate adnexal procedures demand minimal thermal spread. Equine hospitals in Germany invest in microbipolar instruments for eyelid tumor resections.
Soft tissue surgery commands the highest procedure count while orthopedic applications expand most quickly as techniques migrate from specialty to general practice.
End User:
Customer type determines financing structure, with consolidated multi-site operators extracting preferential leasing terms unavailable to independent operators.
- Veterinary Clinics:Companion animal general practices generate the majority of unit demand. California and Texas metropolitan markets show concentrated buying power among consolidated operators.
- Equine Hospitals:Large-animal specialists require higher-output generators for thicker tissue planes. São Paulo's expanding specialist centers are upgrading electrosurgical capabilities for equine oncology.
- Animal Research Centers:Controlled study environments prioritize traceable calibration and documentation. ISO 13485-certified suppliers dominate this compliance-intensive segment.
- Mobile Veterinary Services:Field-based practitioners depend on battery-operated or generator-compatible portable units. Brazilian rural veterinary networks are expanding mobile surgical outreach.
- Zoos:Exotic species procedures require adaptable instrument configurations. Specialist veterinary contractors serving European zoological parks source customizable electrode sets.
Veterinary clinics provide the installed base foundation while equine hospitals are climbing the fastest as specialist infrastructure expands in Brazil and Germany.
Deployment:
Supply concentration in RF power module manufacturing favors integrated suite vendors with captive component sourcing over standalone portable device assemblers.
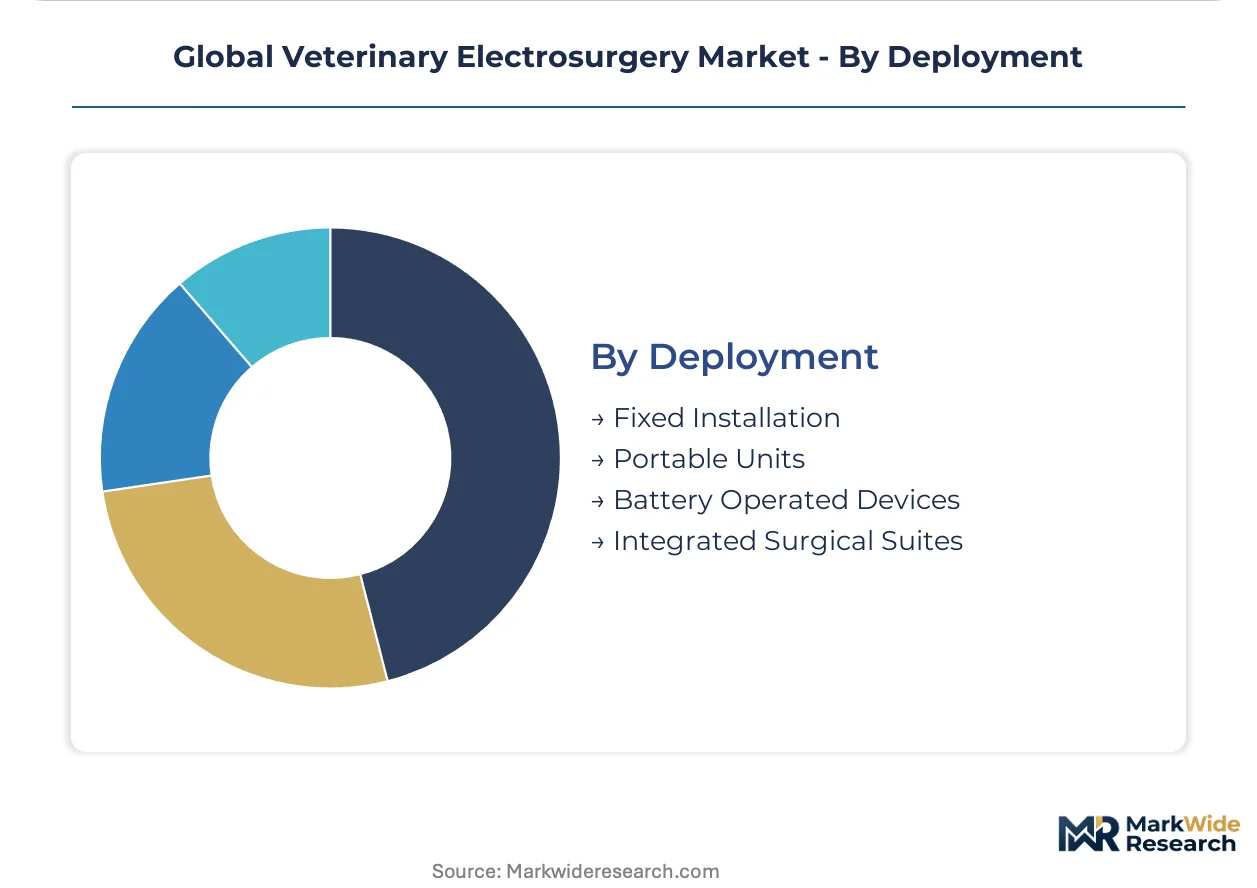
- Fixed Installation:Hardwired generator systems anchor dedicated surgical suites. United States specialist hospitals favor these for bipolar vessel-sealing retrofit programs.
- Integrated Surgical Suites:Converged visualization-cautery platforms enable minimally invasive procedures. German academic referral hospitals are migrating this technology to high-volume general practices.
- Portable Units:Mobile generator systems serve field and emergency applications. Japanese regulatory electromagnetic compatibility requirements filter which manufacturers enter this segment.
- Battery Operated Devices:Cordless operation eliminates grounding pad requirements for select procedures. Equine field practitioners in rural United States markets value this configuration.
Fixed installation systems retain the largest installed base while integrated surgical suites show the steepest expansion trajectory as endoscopy-electrosurgery convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys bipolar vessel-sealing platforms at specialist density unmatched elsewhere, while Germany and Japan filter market entry through electromagnetic compatibility regimes that exclude marginal suppliers. Brazil and India represent alternative growth vectors where regulatory harmonization and production incentives reshape competitive access.
United States
Companion animal oncology drives retrofit demand across metropolitan specialist hospitals. The FDA Center for Veterinary Medicine maintains electrical safety clearance pathways parallel to human device frameworks. California and Texas multi-site clinic operators extract preferential leasing terms through consolidated procurement power.
Germany
Workplace safety inspector mandates harden surgical plume exposure standards in academic referral centers. EU MDR biocompatibility requirements filter active surgical device suppliers toward ISO 13485-certified manufacturers. Bavarian veterinary technology programs struggle to match curriculum updates against equipment evolution pace.
Japan
PMDA and METI electromagnetic compatibility testing exceeds baseline IEC 60601 provisions for conducted emissions. Specialist hospitals in Tokyo and Osaka prioritize adaptive impedance-sensing generators for margin-critical oncologic resections. Kanto region academic centers drive rigid endoscopy-electrosurgery convergence into general practice migration.
Brazil
São Paulo and Rio de Janeiro specialist hospital expansion creates dedicated oncology and orthopedic center demand. ANVISA regulatory harmonization with ISO standards compresses foreign device manufacturer entry timelines. Mobile veterinary services in rural networks expand surgical outreach using portable generator configurations.
India
High-volume sterilization programs in Gujarat and Karnataka veterinary clinics generate recurring disposables revenue attachment. PLI scheme production-linked incentives attract active surgical equipment component suppliers to domestic manufacturing clusters. Maharashtra specialist infrastructure investment lags companion animal demand growth.
Global Veterinary Electrosurgery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling endoscopy-electrosurgery convergence and distribution channel density. Mid-tier equipment margins compress as technological divergence between bipolar and monopolar platforms accelerates. Two archetypes dominate: integrated surgical suite vendors with captive RF power module sourcing, and pure-play distributors leveraging broad North American and European network control. Competitive moves concentrate on strategic partnerships for regulatory testing access and service-contract unbundling to capture recurring revenue.
Within the integrated technology tier, Medtronic and KARL STORZ occupy positions shaped by human-device R&D transfer and optical-surgical convergence respectively. Covetrus exemplifies the distribution-centric archetype, anchoring channel control across capital equipment procurement networks. These three represent distinct competitive vectors: technology integration, visualization platform dominance, and procurement consolidation leverage.
| Leading Market Players |
|---|
| Medtronic |
| Covetrus |
| Symmetry Surgical |
| B. Braun |
| Integra LifeSciences |
| Avante Animal Health |
| KARL STORZ |
| Eickemeyer |
| Burtons Medical Equipment |
| Others |
Supply & Pricing Matrix
Scale economies in RF power module manufacturing concentrate procurement leverage among integrated suite vendors, compressing price floors for standalone generator assemblers while elevating service-contract premiums for adaptive impedance-sensing platforms. This concentration dynamic feeds back into supply chain configuration, as captive component sourcing becomes the primary margin defense against copper and semiconductor input volatility.
Pricing Analysis
Contract structures bifurcate between long-term equipment leases bundled with preventive maintenance and spot procurement of disposables and replacement instruments. Three-tier pricing structure across premium adaptive-sensing, standard bipolar, and economy monopolar levels separates specialist hospitals from general practices. Cost compression in mid-tier equipment is intensifying because technological divergence between vessel-sealing precision and legacy thermal spread erodes interchangeable procurement. Consolidated multi-site operators in California and Texas demonstrate lowest price sensitivity, while independent rural clinics in Brazil and India face acute budget constraints.
Supply Chain Analysis
Inbound logistics costs from East Asian foundries through congested Pacific trade lanes amplify working capital strain for precision-wound transformer and RF semiconductor sourcing. Manufacturing concentration in China, South Korea, and Japan feeds from copper concentrate and rare-earth magnet dependencies. Single-source vulnerability in high-frequency power module fabrication creates procurement risk during geopolitical trade restrictions. Distribution runs through Covetrus-controlled North American networks and KARL STORZ-direct European channels for capital equipment, with regional distributors handling disposables replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bipolar vessel-sealing disruption is accelerating competitive repositioning as EU MDR biocompatibility mandates filter supplier bases and specialist hospitals demand human-grade precision. This regulatory-technological inflection compresses timelines for capability acquisition across all stakeholder archetypes.
For Market Incumbents: Secure captive RF power module sourcing through backward integration into East Asian component partnerships or exclusive offtake agreements, insulating margin structures against semiconductor foundry concentration. Lock ISO 13485-certified quality management systems ahead of notified-body capacity bottlenecks that threaten clearance timelines for next-generation adaptive generators. Channel control through veterinary technology program partnerships defends installed base against emerging portable-device entrants targeting mobile services. For New Entrants and Emerging Players: Anchor in Brazilian specialist hospital expansion corridors where ANVISA harmonization shortens regulatory entry timelines and oncology center buildouts outpace incumbent coverage. Target India's PLI scheme manufacturing clusters for cost-competitive export positioning into price-sensitive Southeast Asian markets. Go-to-market through leasing-subscription financing partnerships with multi-site clinic operators extracts recurring revenue without capital purchase friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated surgical suite vendors with unbundled service contracts and calibration-dependent platform dependencies. Five-to-ten year viability favors acquisition targets with validated electromagnetic compatibility testing for Japan's PMDA-METI regime and established Tokyo partnerships. Watch smoke evacuator attachment bundling rates as the inflection signal for workplace safety standard hardening velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | ISO 13485 quality system validation accelerates notified-body clearance timelines for active surgical devices. |
| Tokyo Testing Partnership Establishment | PMDA electromagnetic compatibility pre-qualification filters market entry into Asia-Pacific's second-largest veterinary device market. |
| Leasing-Subscription Model Launch | Unbundled preventive maintenance contracts capture recurring revenue from California and Texas multi-site clinic consolidation. |
| Veterinary Technology Program Alliance | Hands-on credentialing partnerships address surgical technician training capacity gaps constraining bipolar platform adoption. |
| Rigid Endoscopy Convergence Development | Visualization-cautery integration enables minimally invasive procedure migration from academic referral hospitals to general practice. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with veterinary surgical technicians, hospital procurement managers, biomedical engineers, and GPO contracts directors; and secondary validation against FDA Center for Veterinary Medicine filings, EU MDR notified-body clearance databases, PMDA electromagnetic compatibility test summaries, and ANVISA regulatory harmonization records. Bottom-up procedure volume modeling and top-down capital equipment shipment triangulation anchored market size estimation.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, application specialty, end-user configuration, and deployment mode. CAGRs derived from equipment replacement cycle analysis, procedure volume elasticity to specialist hospital expansion, and regulatory clearance timeline impacts. Forecast inputs incorporated veterinary technology program graduation rates and workplace safety inspector mandate adoption curves for smoke evacuator bundling.
Underlying assumptions cover stable copper and semiconductor pricing, intact East Asian foundry access, and linear EU MDR notified-body capacity recovery, with deviation risk concentrated in geopolitical trade restrictions and electromagnetic compatibility standard escalation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Ultrasound Market
Veterinary
Bovine Collagen Market
Veterinary
Animal Antibiotics Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Canine Parvovirus Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Animal Microchip Implant Market
Veterinary
Global Dog Vaccines Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
Mastitis Market
Veterinary
ASEAN Poultry Vaccines Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Pet Cremation Market