
 Mastitis Market | 2026-2036
Mastitis Market Size, Share, and Industry Trends Forecast 2026-2036
Mastitis Market Outlook
Combination therapy bundling is repositioning buyer choice in the mastitis treatment landscape, as producers seek integrated kits pairing antibiotics with analgesics rather than standalone products. Zoetis leverages its diagnostic-to-treatment pipeline to anchor premium positioning across veterinary channels. Boehringer Ingelheim competes through manufacturing scale in intramammary formulations. Merck & Co., Inc. differentiates via R&D intensity in vaccine adjuvant platforms for subclinical mastitis prevention.
Mastitis denotes inflammation of the mammary gland and udder tissue, typically triggered by bacterial pathogens such as Staphylococcus aureus, Streptococcus uberis, or Escherichia coli, with diagnosis relying on somatic cell count thresholds and microbial culture identification. Its primary commercial purpose centers on restoring milk production capacity and preventing culling losses in dairy operations. Antibiotics occupy the largest revenue pool due to established veterinary protocols, while vaccines represent the fastest-expanding segment as producers shift toward preventive economics. Diagnostic imaging and genomic sequencing technologies are capturing margin pools by enabling pathogen-specific treatment selection that reduces blanket antibiotic use.
The FDA's Veterinary Feed Directive and EMA's guidelines on prudent antimicrobial use jointly constrain prophylactic antibiotic deployment, compelling manufacturers to reformulate toward narrower-spectrum or non-antibiotic alternatives. ISO standards for veterinary medicinal products and national residue monitoring programs shape product registration timelines and market access conditions across producing regions. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating R&D portfolios toward diagnostics-enabled precision therapy.
Market Dynamics
The FDA's Veterinary Feed Directive and parallel EMA antimicrobial stewardship programs are forcing a structural pivot from blanket antibiotic therapy toward diagnostics-enabled precision treatment protocols across commercial dairy operations.
Growth Catalysts
- Regulatory pressure on residue limits:The FDA's updated withdrawal period guidelines for intramammary antibiotics are compelling producers toward rapid diagnostic adoption to avoid milk discard penalties.
- Genomic pathogen identification:Commercial sequencing platforms now deliver same-day speciation of Staphylococcus aureus versus Streptococcus uberis, enabling targeted therapy selection that preserves milk production.
- Large-scale cooperative consolidation:United States dairy cooperatives exceeding 10,000 head are centralizing procurement decisions around preventive health bundles that combine vaccines with diagnostic subscriptions.
Market Restraints
- Veterinarian supply concentration:Rural veterinary service deserts in the Upper Midwest and Pacific Northwest limit on-farm diagnostic deployment for subclinical mastitis screening.
- Antibiotic pipeline attrition:Narrower-spectrum development programs face extended FDA Center for Veterinary Medicine review timelines compared to legacy broad-spectrum formulations.
- Input cost volatility:Bovine colostrum-derived immunoglobulin prices fluctuate with feed grain markets, compressing margins for biological mastitis preventives.
Strategic Opportunities
- Underpenetrated precision diagnostics:Brazil's expanding commercial dairy sector lacks pathogen-specific culture capacity, creating white space for portable PCR platforms.
- Preventive vaccine adjuvants:Novel toll-like receptor agonist formulations are reducing subclinical infection rates below somatic cell count thresholds in trial herds.
- Subscription-based health monitoring:Dairy management software integrations are enabling recurring-revenue models that bundle somatic cell count telemetry with treatment recommendations.
Industry Challenges
- Diagnostic technician training gaps:On-farm milk culture interpretation requires microbiology competency that exceeds standard herd manager certification programs.
- Legacy parlor infrastructure:Retrofitting older herringbone milking systems with automated mastitis detection sensors demands capital expenditure that smaller operations defer.
- Cross-border residue standard harmonization:Divergent maximum residue limits between Codex Alimentarius, FDA, and EMA complicate export-oriented herd health protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mastitis Market |
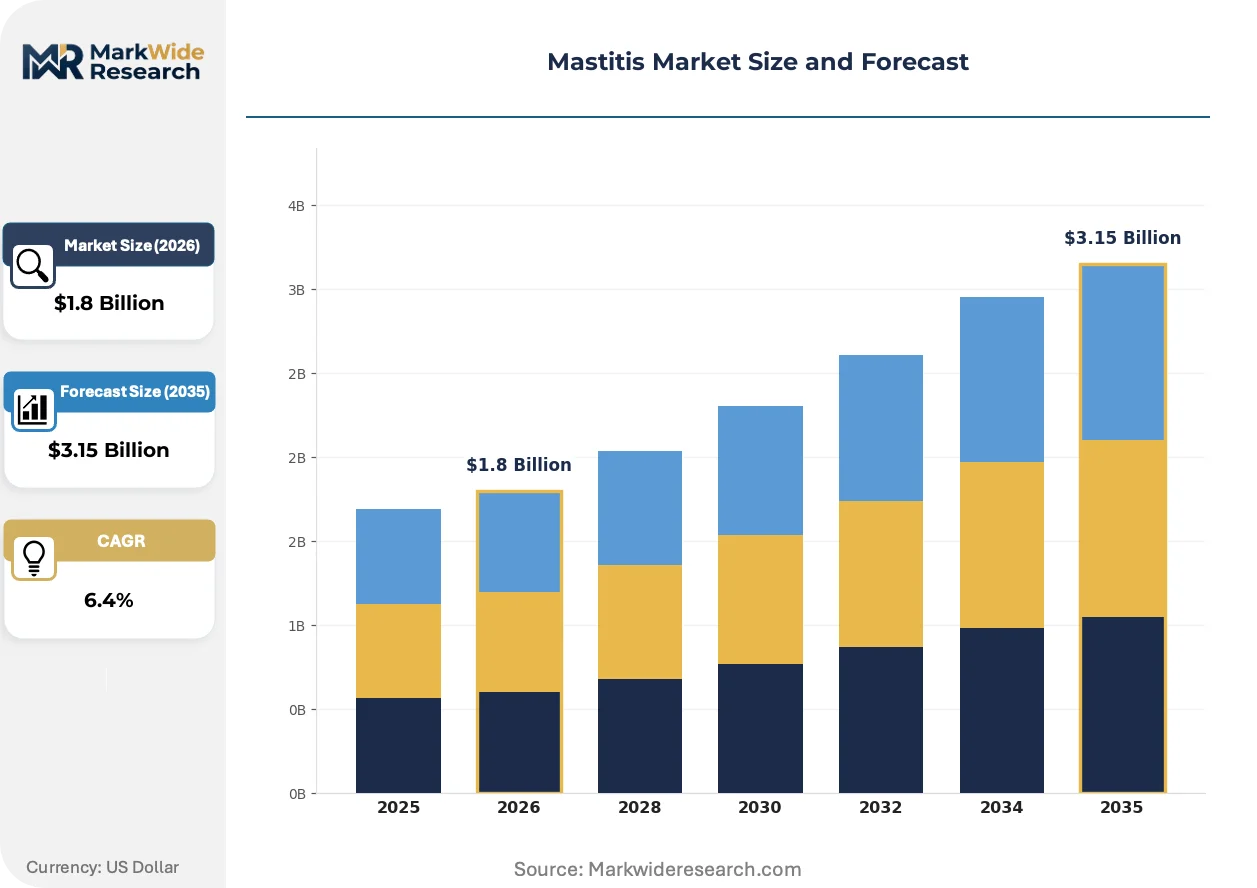
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Analgesics, Vaccines, Intramammary Therapy Treatment Approach: Conservative Management, Surgical Intervention, Medical Therapy, Holistic Therapy End User: Dairy Farmers, Veterinary Clinics, Research Institutions, Livestock Producers Technology: Diagnostic Imaging, Microbiological Testing, Genomic Sequencing, Immunotherapy |
| Companies Covered | Elanco Animal Health, Virbac, Zoetis, ImmuCell Corporation, HIPRA, Merck & Co., Inc., Ceva Santé Animale, Phibro Animal Health Corporation, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mastitis Market Strategic Shifts
Diagnostics-to-treatment integration is compressing decision cycles from days to hours, while biological alternatives and data-driven prevention protocols are displacing conventional antibiotic-centric workflows across commercial operations.
Automated inline somatic cell count sensors using Fourier-transform infrared spectroscopy are modularizing mastitis detection into continuous monitoring rather than periodic testing. Large-scale operations in Wisconsin and California are retrofitting parlor systems with these platforms to trigger immediate segregation protocols. This technology is modularizing the traditional veterinary visit into real-time alerts that bypass labor-intensive manual screening.
The EMA's revised guidelines on prudent use of antimicrobials in veterinary medicine now mandate culture-based susceptibility testing before third-generation cephalosporin deployment. This policy is extending treatment timelines and elevating diagnostic service revenues as a percentage of total mastitis expenditure. European producers are responding by consolidating veterinary contracts with diagnostic-equipped practices that can deliver 24-hour culture turnaround.
Cooperative procurement offices are consolidating vendor relationships around integrated health packages that combine vaccines, diagnostics, and treatment protocols under single-source agreements. This buying-pattern shift is marginalizing standalone antibiotic suppliers that lack adjacent diagnostic or preventive portfolios. The concentration is most visible in the Upper Midwest, where four cooperatives now control antibiotic purchasing for over 40 percent of regional dairy cows.
Mastitis Market Segmentation
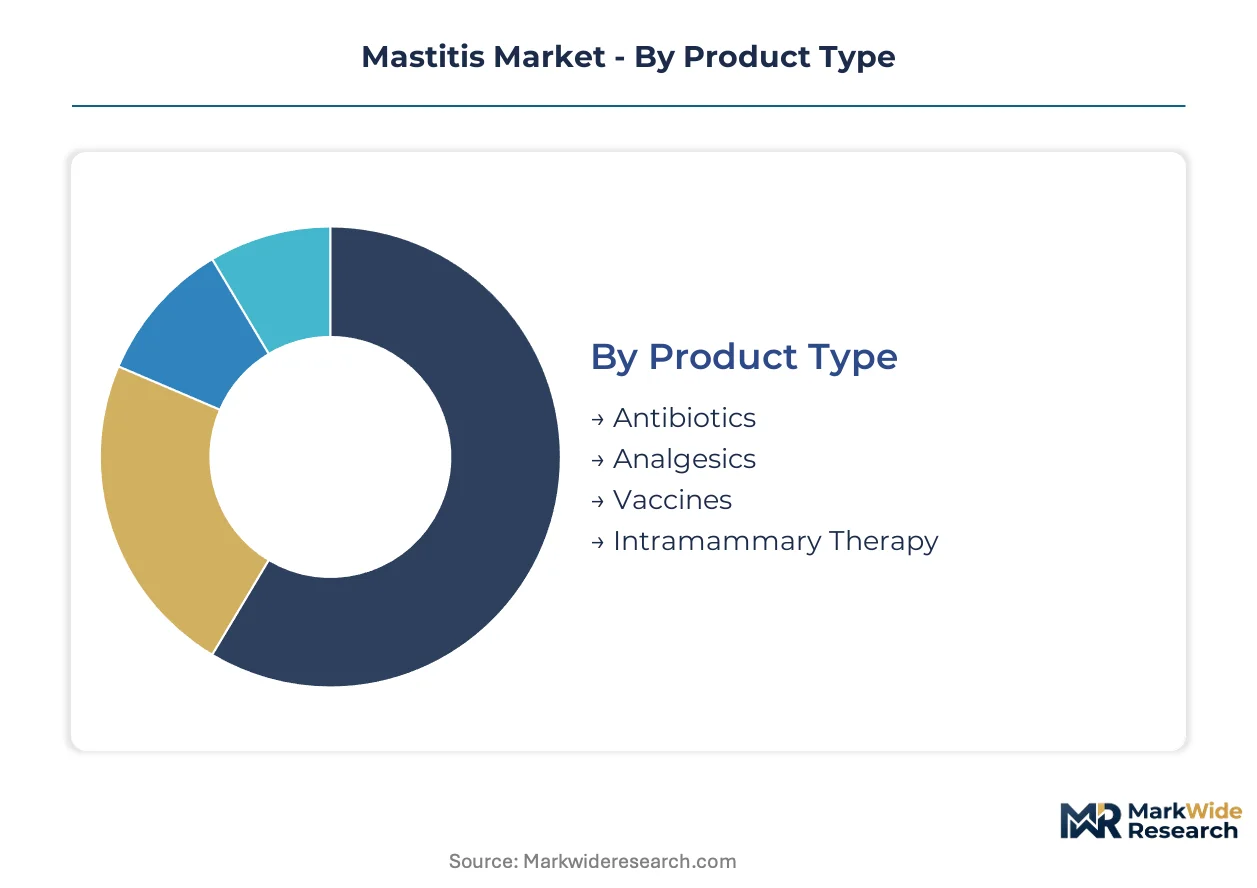
Mastitis treatment procurement splits sharply between preventive and curative modalities, with buyer economics dictating whether operations prioritize upfront biological investment or reactive pharmaceutical intervention. Dairy cooperatives centralizing herd health decisions are compressing these segment boundaries into bundled service contracts.
Product Type:
Cost tier determines procurement priority, with premium biologicals commanding capital allocation ahead of commodity antibiotics in operations exceeding 1,000 head.
- Antibiotics:Intramammary formulations containing beta-lactams or cephalosporins remain the default first-line intervention for clinical cases. Demand concentrates in large-scale Wisconsin and California operations where FDA withdrawal period compliance drives rapid-turnaround purchasing from veterinary distributors.
- Vaccines:Subunit and whole-cell formulations targeting Staphylococcus aureus and E. coli are gaining procurement share in preventive protocols. Trials with toll-like receptor agonist adjuvants in Upper Midwest herds are pushing somatic cell counts below regulatory thresholds without antibiotic use.
- Analgesics:NSAID formulations for pain management accompany antibiotic therapy in welfare-certified operations.
- Intramammary Therapy:Dry cow formulations and lactating cow tubes represent the procedural standard in parlor-based treatment workflows.
Volume sits with antibiotics; growth tilts toward vaccines.
Treatment Approach:
Application severity drives protocol selection, with subclinical cases increasingly diverted from pharmaceutical intervention toward non-antibiotic management.
- Medical Therapy:Pharmaceutical protocols combining systemic and intramammary antibiotics address acute clinical presentations. European adoption concentrates in Germany and Netherlands where EMA susceptibility testing mandates extend treatment timelines and elevate diagnostic service bundling.
- Conservative Management:Milk culture-based withholding and supportive care without antibiotics targets subclinical grades. California dairies facing state antibiotic use reporting requirements are expanding non-pharmaceutical protocols to preserve market access.
- Holistic Therapy:Botanical and homeopathic alternatives occupy niche positioning in organic-certified operations.
- Surgical Intervention:Teat amputation and mastectomy address chronic refractory cases in high-value breeding stock.
Medical therapy captures the revenue base; conservative management is expanding most quickly.
End User:
Customer scale determines purchasing modality, with consolidated cooperatives displacing individual farm procurement through centralized veterinary contracts.
- Dairy Farmers:Commercial operations exceeding 500 head drive bulk antibiotic procurement and preventive health subscription adoption. Four Upper Midwest cooperatives now control purchasing for over 40 percent of regional cow inventory.
- Veterinary Clinics:Mixed-animal practices in rural service areas provide on-farm diagnostics and treatment administration. Technician capacity constraints in Pacific Northwest veterinary deserts limit diagnostic deployment for subclinical screening.
- Livestock Producers:Beef and small-ruminant operations require sporadic mastitis intervention for breeding stock.
- Research Institutions:University veterinary schools and agricultural extension services validate novel treatment protocols and adjuvant formulations.
Dairy farmers anchor procurement volume; veterinary clinics are gaining share fastest through diagnostic service bundling.
Technology:
Margin capture concentrates in platforms enabling pathogen-specific treatment selection, displacing blanket antibiotic protocols.
- Genomic Sequencing:Portable PCR and whole-genome platforms deliver same-day Staphylococcus aureus versus Streptococcus uberis speciation. Brazil's expanding commercial dairy sector lacks culture capacity, creating white space for field-deployable systems.
- Diagnostic Imaging:Ultrasonography and thermography support severity grading and treatment response monitoring. Inline Fourier-transform infrared sensors in Wisconsin parlors enable real-time somatic cell count monitoring that triggers immediate segregation protocols.
- Microbiological Testing:Conventional culture and sensitivity testing remains the regulatory baseline for EMA cephalosporin use authorization.
- Immunotherapy:Monoclonal antibody and cytokine therapies represent experimental alternatives to antibiotic intervention.
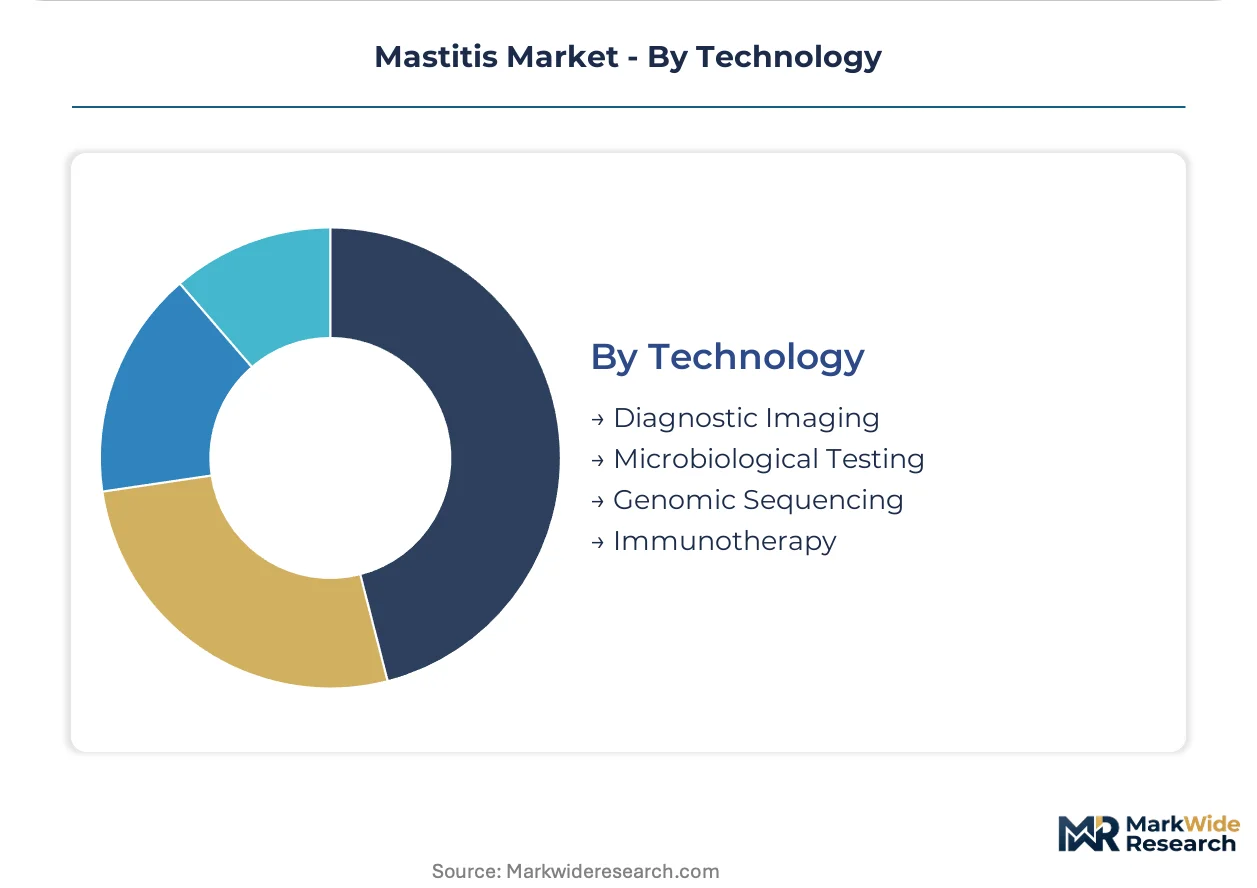
Microbiological testing holds installed base; genomic sequencing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in North American and European dairy belts where large-scale operations drive veterinary pharmaceutical consumption, while emerging commercial sectors in Brazil and India are expanding diagnostic and preventive protocol adoption.
United States
Wisconsin and California dairy cooperatives exceeding 10,000 head centralize procurement of intramammary therapies and diagnostic subscriptions. The FDA's Veterinary Feed Directive constrains prophylactic antibiotic use, compelling investment in rapid pathogen identification platforms. Four Upper Midwest cooperatives now control antibiotic purchasing for over 40 percent of regional cow inventory.
Germany
Large-scale operations in Lower Saxony and Bavaria drive demand for precision diagnostics that preserve milk production capacity. EMA guidelines mandate culture-based susceptibility testing before third-generation cephalosporin deployment, extending treatment timelines. Veterinary practices in the Münsterland dairy cluster are consolidating around 24-hour culture turnaround capabilities to capture service revenues.
Brazil
Expanding commercial herds in São Paulo and Minas Gerais states lack pathogen-specific culture capacity, creating white space for portable PCR platform deployment. ANVISA registration pathways for veterinary biologicals shape market entry timelines for foreign manufacturers. The southern Paraná dairy belt is retrofitting parlors with automated somatic cell count sensors to meet export residue standards.
Netherlands
Intensive operations in Friesland and Overijssel prioritize somatic cell count telemetry integration with herd management software. EU Green Deal sustainability metrics and national antibiotic reduction targets are accelerating vaccine adjuvant adoption. The Wageningen agricultural research corridor validates novel toll-like receptor formulations for subclinical infection prevention.
India
Cooperative dairy networks in Gujarat and Maharashtra are expanding from commodity procurement toward preventive health service bundling. FSSAI residue monitoring programs and state-level veterinary infrastructure gaps limit diagnostic deployment for subclinical screening. The Anand milk cooperative cluster is piloting genomic sequencing platforms to reduce blanket antibiotic use in crossbred herds.
Mastitis Market Competitive Environment
The competitive structure tilts toward diversified animal health conglomerates with integrated diagnostic-to-treatment pipelines. Market concentration remains moderate, with revenue pools fragmenting across pharmaceutical manufacturers, diagnostic platform developers, and biological specialists. Three archetypes dominate: full-service veterinary health conglomerates with vaccine-adjuvant R&D intensity, precision diagnostics platform specialists, and regional intramammary formulation manufacturers competing on manufacturing scale. Competitive moves center on diagnostic service bundling with treatment protocols and cooperative procurement consolidation through single-source health package agreements.
Within the full-service conglomerate tier, Zoetis anchors premium positioning across veterinary channels through its diagnostic-to-treatment pipeline integration, while Merck & Co., Inc. occupies a position emphasizing vaccine adjuvant platform development for subclinical mastitis prevention. Boehringer Ingelheim exemplifies the manufacturing-scale archetype in intramammary formulations. Among biological specialists, ImmuCell Corporation represents the narrower-focus segment developing alternatives to antibiotic intervention. These players collectively illustrate the strategic divergence between preventive biological investment and reactive pharmaceutical supply.
| Leading Market Players |
|---|
| Elanco Animal Health |
| Virbac |
| Zoetis |
| ImmuCell Corporation |
| HIPRA |
| Merck & Co., Inc. |
| Ceva Santé Animale |
| Phibro Animal Health Corporation |
| Boehringer Ingelheim |
| Others |
Value Chain & Pricing Dynamics
Bovine colostrum-derived immunoglobulin feed grain price volatility flows through biological mastitis preventives into three-tier pricing structure across premium, standard, and economy levels, with large-scale dairy cooperatives leveraging volume scale to compress supplier margins while smaller operations absorb input cost pass-through.
Pricing Analysis
Margin tightening in intramammary antibiotic tiers reflects FDA withdrawal period compliance costs and diagnostic service bundling requirements. Three-tier pricing structure across premium, standard, and economy levels separates pathogen-specific PCR-enabled protocols from commodity beta-lactam tubes. Cost compression in economy antibiotic segments accelerates because cooperative procurement offices consolidate purchasing power. Smallholder dairy farmers in veterinary service deserts exhibit highest price sensitivity; large Wisconsin and California cooperatives above 10,000 head demonstrate lowest sensitivity due to preventive health subscription models.
Supply Chain Analysis
Regional distribution centers in Iowa and California's Central Valley operate hub-and-spoke patterns reaching Upper Midwest and Pacific Northwest dairy belts. Active pharmaceutical ingredient production concentrates in India, China, and Ireland for beta-lactam and cephalosporin precursors. Finished intramammary formulation draws from bovine colostrum suppliers in New Zealand, Argentina, and the United States. Single-source vulnerability in toll-like receptor agonist adjuvant feedstock creates supply risk for vaccine manufacturers. Distribution runs through veterinary distributor networks with cooperative direct purchasing increasingly bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mastitis treatment landscape is consolidating around integrated diagnostic-to-treatment pipelines, with FDA antimicrobial stewardship mandates and cooperative procurement centralization forcing standalone antibiotic suppliers toward acquisition or exit.
For Market Incumbents: Anchor market position through backward integration into rapid diagnostic platform development and captive vaccine adjuvant manufacturing capacity. Acquire regional veterinary practices in Pacific Northwest service deserts to secure distribution control against emerging precision diagnostics specialists. Invest in toll-like receptor agonist R&D to substitute antibiotic revenue pools as EMA and FDA restrictions tighten. For New Entrants and Emerging Players: Mid-scale Brazilian dairy operations in São Paulo and Minas Gerais states lacking pathogen-specific culture capacity represent the most penetrable buyer archetype. Portable PCR platform deployment with Portuguese-language technical support captures white space before incumbent diagnostic conglomerates establish ANVISA-registered distribution. Telematics-integrated somatic cell count subscription models offer differentiated go-to-market positioning against transactional antibiotic vendors. For Investors and Strategic Acquirers: Cooperative procurement office consolidation beyond 40 percent regional cow inventory control is the leading indicator that standalone intramammary formulation manufacturers face margin compression requiring strategic exit. Five-to-ten year viability favors diversified animal health conglomerates with diagnostic service revenue streams over commodity antibiotic pure-plays. Monitor ANVISA registration pathway acceleration for foreign veterinary biological manufacturers as Brazil's commercial dairy sector expands.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Platform Integration | PCR-enabled pathogen speciation preserves milk production capacity while reducing blanket antibiotic use penalties. |
| Vaccine Adjuvant Manufacturing Scale-Up | Toll-like receptor agonist production capacity captures preventive protocol shift in EMA-regulated European markets. |
| Veterinary Practice Acquisition | Control of 24-hour culture turnaround capabilities secures service revenue bundling in Germany's Münsterland dairy cluster. |
| Cooperative Procurement Partnership | Single-source health package agreements with Upper Midwest consolidates lock in antibiotic and diagnostic volume commitments. |
| ANVISA Registration Pathway Investment | Brazilian regulatory approval for field-deployable diagnostics opens São Paulo commercial dairy sector penetration. |
Study Parameters
Document review covered FDA Veterinary Feed Directive implementation records, EMA antimicrobial stewardship guidelines, ANVISA veterinary biological registration databases, and ISO veterinary medicinal product standards, complemented by interviews with dairy cooperative procurement directors, large-animal veterinary practitioners, intramammary formulation plant managers, and precision diagnostics platform engineers. Secondary validation drew from USDA National Animal Health Monitoring System reports, university extension mastitis control program evaluations, and trade customs data for veterinary pharmaceutical imports. Bottom-up cow-level treatment frequency modeling triangulated against top-down manufacturer revenue segmentation.
Segmented outputs across product type, treatment approach, end user scale, and technology platform dimensions were generated over the projection horizon. CAGRs were derived from regression analysis against somatic cell count telemetry adoption curves, cooperative consolidation rates, and regulatory compliance cost trajectories. Forecast inputs incorporated veterinary service desert geographic expansion, bovine colostrum immunoglobulin price elasticity, and pathogen-specific culture capacity installation rates.
Revisions become necessary when FDA cephalosporin withdrawal period guidelines extend further, EMA mandates additional susceptibility testing tiers, or Brazilian commercial dairy herd growth accelerates beyond veterinary infrastructure capacity. Forecasts reflect documented assumptions regarding cooperative procurement centralization velocity and diagnostic platform cost reduction curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Vet Software Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Veterinary Endodontics Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Veterinary Supplements Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market
Veterinary
Otc Pet Medication Market
Veterinary
Veterinary Hospitals Market
Veterinary
Veterinary Scales Market
Veterinary
Veterinary Antibiotics Market