
 Global Dog Vaccines Market | 2026-2036
Global Dog Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dog Vaccines Market Foresight
Multivalent core specification upgrades is unwinding legacy single-antigen production economics across developed and emerging markets alike. Zoetis leverages its vertically integrated biologics platform to sustain cost leadership in recombinant vector manufacturing. Boehringer Ingelheim International GmbH anchors European supply through specialized cold-chain distribution networks. Merck & Co., Inc. competes on R&D intensity with novel adjuvant platforms targeting duration-of-immunity extension.
Dog vaccines are attenuated, inactivated, or recombinant antigen preparations administered to canines to induce protective immunity against viral and bacterial pathogens, with formulations typically stabilized via lyophilization or liquid suspension in buffered saline containing proprietary adjuvant systems. Their primary commercial purpose is to prevent morbidity and mortality in domestic dog populations while satisfying public health mandates for rabies control. Rabies and parvovirus formulations dominate volume due to universal legal requirements and high clinical efficacy thresholds, while intranasal bordetella segments capture premium positioning through reduced administration stress and faster mucosal onset. Subcutaneous delivery remains the standard route for core multivalent products, though oral rabies baits for wildlife interface management represent a growing technical specialization with distinct margin profiles.
USDA Center for Veterinary Biologics enforces batch purity and potency testing that shapes product development timelines and manufacturing compliance costs for US-market entrants. EMA veterinary product standards and WHO rabies elimination frameworks collectively elevate quality benchmarks and harmonize export requirements across OECD jurisdictions. Stakeholders must monitor evolving duration-of-immunity label claims and vector platform patent expiries as determinants of portfolio restructuring decisions.
Market Dynamics
Multivalent core specification upgrades are unwinding legacy single-antigen production economics across developed and emerging markets alike, forcing manufacturers to reconfigure biologics platforms around duration-of-immunity extension claims.
Growth Catalysts
- EMA Veterinary Product Standards:Harmonized quality benchmarks across OECD jurisdictions reduce export compliance burdens for European manufacturers. This accelerates cross-border product registrations.
- Shelter Intake Protocols:Veterinary clinics are expanding vaccination programs for municipal animal control facilities. These bulk procurement contracts drive volume concentration in the institutional channel.
- Recombinant Vector Platforms:Novel antigen delivery systems enable differentiated duration-of-immunity labeling. Manufacturers capture premium positioning through technical differentiation.
Market Restraints
- Cold-Chain Distribution Costs:Specialized temperature-controlled logistics for lyophilized and liquid suspension formulations inflate delivered product costs. Last-mile infrastructure gaps in tropical climates compound spoilage risk.
- USDA Batch Purity Testing:Center for Veterinary Biologics enforcement of potency verification extends product development timelines. Compliance costs disproportionately burden smaller market entrants.
- Oral Rabies Bait Substitution:Wildlife interface management programs are shifting toward bait-delivery systems for vector control. This displaces traditional parenteral vaccine demand in certain public health applications.
Strategic Opportunities
- Brazil Municipal Rabies Initiatives:Expanding compulsory vaccination mandates in Latin America's largest canine population create volume anchors. State-level procurement consolidation favors scale-efficient suppliers.
- Intranasal Bordetella Delivery:Mucosal administration routes reduce veterinary staff time and animal stress. Premium positioning in the companion animal segment rewards formulation innovation.
- ISO Harmonization Frameworks:International standards convergence for veterinary biologics testing protocols streamlines multi-market registrations. Early adopters of unified quality systems capture first-mover regulatory advantages.
Industry Challenges
- Adjuvant Platform Patent Complexity:Proprietary immunostimulant formulations face overlapping intellectual property claims. Licensing negotiations delay product pipeline advancement.
- Lyophilization Equipment Scarcity:Freeze-drying capacity constraints limit formulation flexibility for thermostable products. Capital equipment lead times extend manufacturing scale-up schedules.
- WHO Rabies Elimination Alignment:Divergent national implementation timelines for international eradication frameworks create demand forecasting uncertainty. Manufacturers must balance inventory against policy volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dog Vaccines Market |
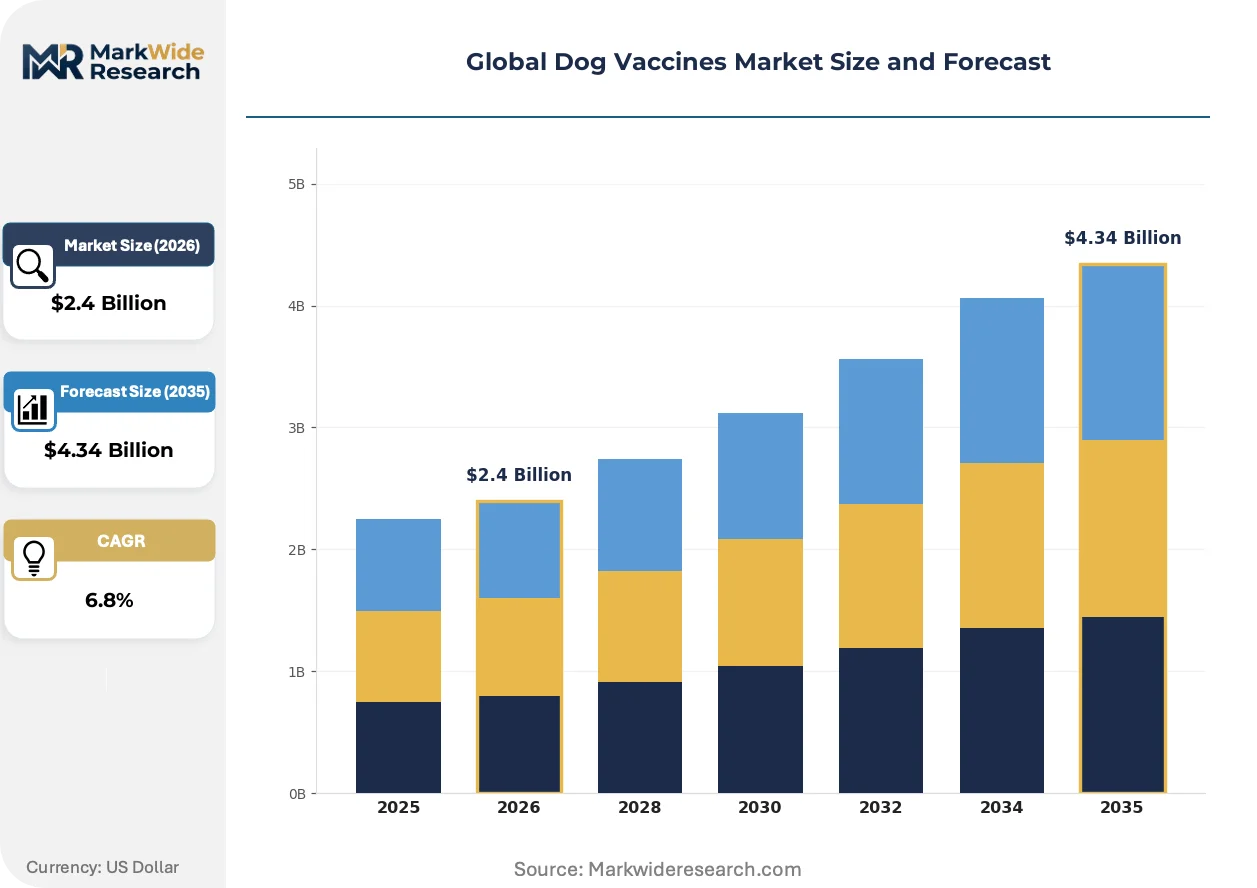
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Rabies, Parvovirus, Distemper, Leptospirosis, Bordetella, Lyme Administration Route: Subcutaneous, Intramuscular, Oral, Intranasal End User: Veterinary Clinics, Animal Shelters, Diagnostic Labs, Mobile Vet Services Distribution Channel: Veterinary Hospitals, Online Retailers, Pharmacies, Pet Specialty Stores |
| Companies Covered | Zoetis, Boehringer Ingelheim International GmbH, Merck & Co., Inc., Elanco, Virbac, Bioveta a.s, Hester Biosciences Limited, Ceva, HIPRA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dog Vaccines Market Shifts & Advancements
Recombinant vector manufacturing is fragmenting competitive positions across the dog vaccines landscape, as technical differentiation in antigen delivery systems becomes the primary axis of rivalry rather than scale economies alone.
DNA platform technologies are fragmenting traditional attenuated virus production methods. Large veterinary clinic chains and municipal procurement bodies are adopting these platforms for customizable multivalent formulations. The shift compresses legacy single-antigen product margins while rewarding biologics specialists with captive vector development capabilities.
USDA Center for Veterinary Biologics has tightened duration-of-immunity label claim evidentiary requirements. Manufacturers must now conduct extended field trials to support extended revaccination intervals. Core multivalent products face reformulation pressure, with subcutaneous delivery segments investing in novel adjuvant systems to meet elevated efficacy thresholds.
Veterinary clinic consolidation is altering procurement patterns across North America and Western Europe. Independent practices are losing purchasing leverage to corporate-owned hospital networks. Brazil and Mexico exhibit the most visible concentration, where national chains negotiate direct supply agreements that bypass traditional distributor markups.
Global Dog Vaccines Market Segmentation
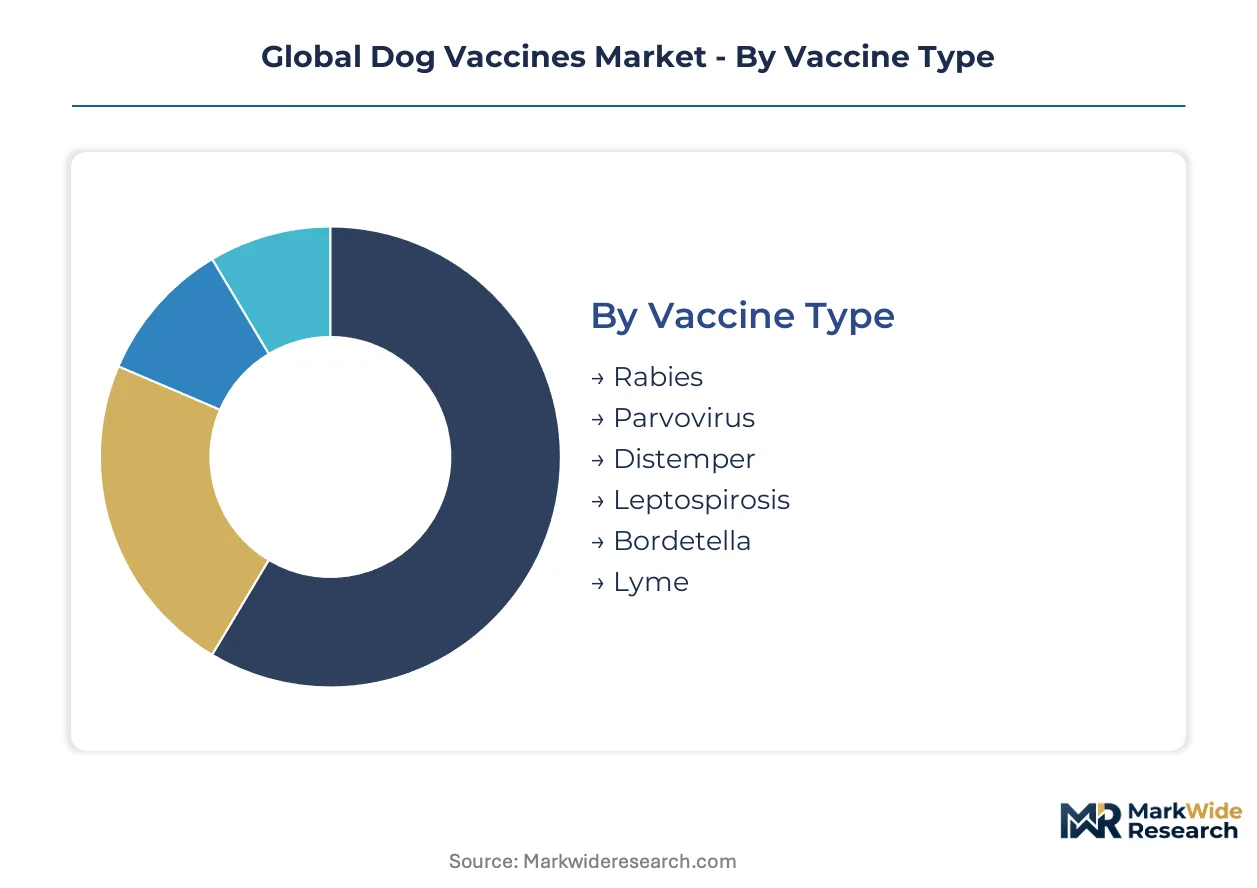
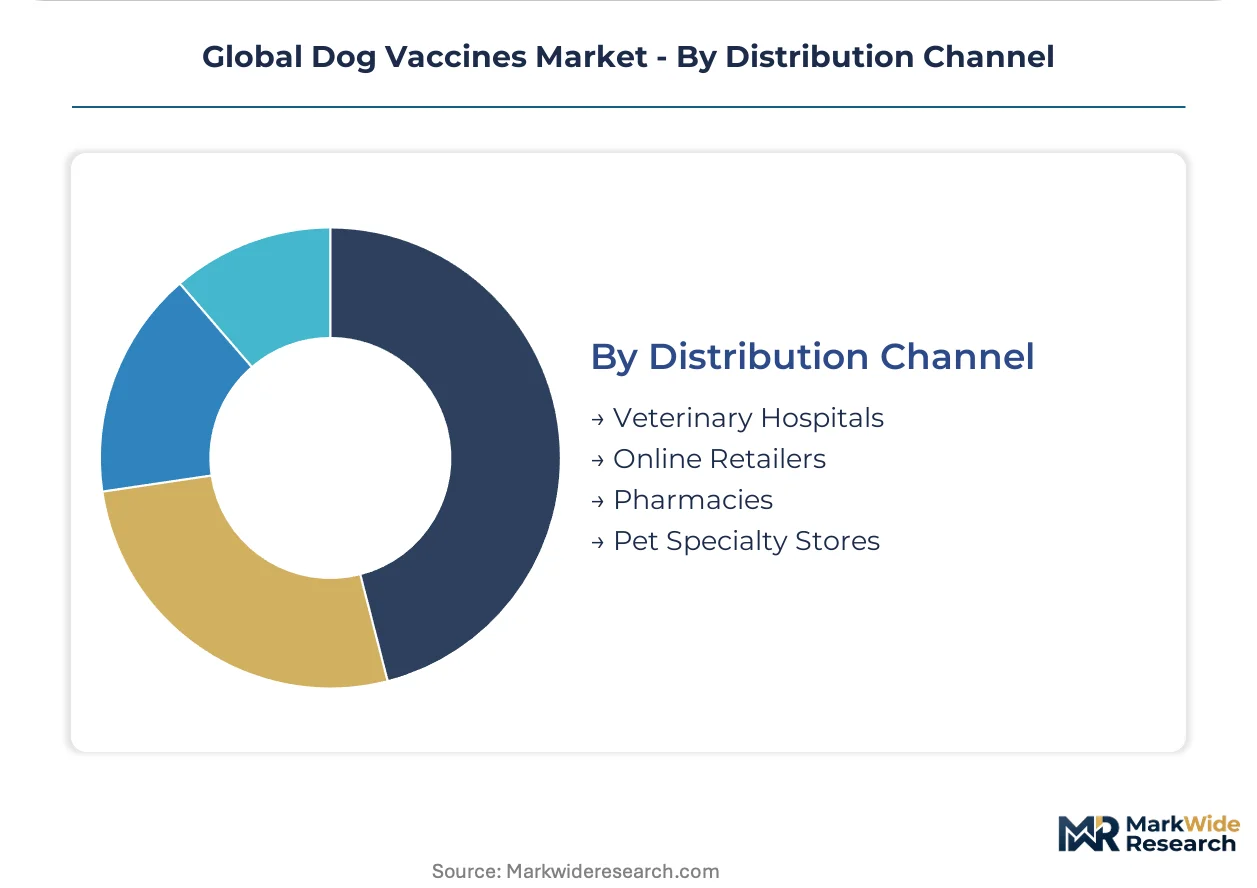
Vaccine type and administration route configurations determine manufacturing platform investments and cold-chain infrastructure requirements across national markets. Distribution channel selection directly shapes margin capture and regulatory compliance burdens for biologics suppliers.
Vaccine Type:
Rabies and parvovirus formulations anchor domestic procurement volumes in Brazil and India through compulsory municipal mandates, while leptospirosis and Lyme segments concentrate in export-oriented North American and European specialty markets.
- Rabies:Attenuated and inactivated viral preparations stabilized via lyophilization for extended thermostability. Brazil's municipal control programs and India's street dog sterilization initiatives concentrate bulk institutional demand, with WHO elimination frameworks driving standardization requirements.
- Parvovirus:High-titer modified live virus formulations requiring precise cold-chain maintenance from production through administration. North American veterinary clinic consolidation and European shelter intake protocols anchor volume, where duration-of-immunity labeling determines premium positioning.
- Distemper:Core multivalent component with established production economics across OECD manufacturing bases.
- Leptospirosis:Bacterial subunit vaccines capturing specialty positioning in temperate climate veterinary markets.
- Bordetella:Intranasal and parenteral formulations differentiated by mucosal onset speed claims.
- Lyme:Region-specific demand concentrated in northeastern United States and Central European tick-endemic zones.
Rabies commands the established base. The steepest expansion runs through Bordetella intranasal delivery formats.
Administration Route:
Cost tier differentiation separates capital-intensive subcutaneous multivalent production from premium intranasal formulation development, with oral delivery systems occupying distinct wildlife management margin structures.
- Subcutaneous:Standard delivery for core multivalent products requiring sterile needle-syringe administration. North American corporate veterinary networks and European clinic chains drive volume concentration, where batch consistency and adjuvant safety profiles determine supplier selection.
- Intranasal:Mucosal administration of modified live bordetella and parainfluenza antigens eliminating injection stress. Premium companion animal clinics in the United States and United Kingdom reward reduced staff time and improved patient compliance with price premiums.
- Intramuscular:Alternative parenteral route for specific adjuvant formulations and large-breed administration.
- Oral:Bait-delivery systems for wildlife rabies vector control with distinct USDA regulatory pathways and public procurement structures.
Subcutaneous delivery maintains volume dominance. Intranasal administration gains share fastest through veterinary clinic efficiency demands.
End User:
Customer type fragmentation splits between high-volume institutional tenders and premium companion animal service providers, with mobile platforms emerging as a distinct logistics segment.
- Veterinary Clinics:Primary administration sites for core multivalent protocols and annual revaccination schedules. Corporate chain consolidation in the United States and Brazil redirects procurement through direct manufacturer agreements, compressing distributor margins.
- Animal Shelters:High-turnover municipal and private facilities requiring rapid intake vaccination protocols. Brazilian state-level procurement consolidation and Indian municipal corporation tenders concentrate volume in price-sensitive institutional channels.
- Diagnostic Labs:Reference laboratories supporting titer testing and vaccine response validation services.
- Mobile Vet Services:Emerging channel addressing rural access gaps and home-based companion animal care in dispersed geographies.
Veterinary clinics anchor revenue concentration. Animal shelters represent the fastest volume expansion through municipal program scaling.
Distribution Channel:
Supply concentration patterns separate regulated biologics distribution through licensed veterinary facilities from emerging direct-to-consumer pressures in retail and digital channels.
- Veterinary Hospitals:Licensed dispensing of prescription biologics with cold-chain integrity guarantees. European specialized distribution networks and North American clinic-based inventory models maintain channel dominance through regulatory compliance requirements.
- Online Retailers:Digital platforms capturing OTC supplement and parasite control adjacencies, with vaccine sales restricted by national biologics licensing frameworks.
- Pharmacies:Limited vaccine access in jurisdictions with expanded pharmacist administration authority.
- Pet Specialty Stores:Wellness product retail without core vaccine distribution due to temperature control and prescription status limitations.
Veterinary hospitals control regulated biologics flow. Online retailers expand fastest in adjacent wellness categories despite vaccine restrictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian municipal procurement exhibits extreme price elasticity under compulsory rabies mandates, while premium intranasal formats in the United Kingdom and United States command minimal volume sensitivity. This divergence shapes manufacturer portfolio allocation across geographies.
United States
Corporate veterinary chain consolidation redirects procurement through direct manufacturer agreements, bypassing traditional distributor networks. USDA Center for Veterinary Biologics enforces stringent duration-of-immunity label claim requirements through extended field trial mandates. Greater Boston and Pacific Northwest clusters concentrate specialty companion animal clinic networks investing in premium mucosal delivery formats.
Brazil
State-level municipal rabies control programs generate institutional tender volumes at compressed margins. ANVISA harmonizes veterinary biologics registration pathways with Mercosur technical standards to accelerate cross-border approvals. São Paulo and Rio de Janeiro metropolitan regions anchor procurement consolidation through unified state health secretariat purchasing.
Germany
Specialized cold-chain distribution networks serve premium companion animal segments with minimal price sensitivity. EMA veterinary product standards elevate quality benchmarks that filter export-capable manufacturers from price-competitive entrants. Baden-Württemberg and Bavaria host concentrated biologics manufacturing infrastructure serving OECD export markets.
India
Street dog sterilization and rabies elimination initiatives generate high-volume institutional demand at government-negotiated price ceilings. CDSCO regulates veterinary vaccine import licensing and local manufacturing facility inspections under harmonized WHO prequalification alignment. Maharashtra and Gujarat clusters concentrate contract manufacturing capacity for thermostable lyophilized formulations.
United Kingdom
Premium companion animal clinics reward intranasal bordetella delivery with price premiums for reduced staff time and improved patient compliance. Veterinary Medicines Directorate enforces batch release testing that extends product registration timelines for non-EU sourced biologics. London and Southeast England concentrate corporate veterinary network headquarters directing national procurement standardization.
Global Dog Vaccines Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the dog vaccines landscape. Vertically integrated biologics specialists with captive recombinant vector platforms command premium positioning through duration-of-immunity differentiation, while regional manufacturers with freeze-drying capacity access compete on municipal tender economics. Three archetypes dominate: multinational animal health conglomerates with full-spectrum portfolios, mid-scale regional biologics specialists with cold-chain infrastructure, and contract manufacturing organizations serving price-sensitive institutional channels. Competitive moves concentrate on strategic partnerships for adjuvant platform access and geographic expansion through distributor acquisition.
Among the integrated animal health conglomerates, Zoetis and Boehringer Ingelheim International GmbH exemplify archetypes with biologics manufacturing depth and regulatory scale. Merck & Co., Inc. occupies a position representing R&D-intensive competition through novel formulation platforms. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim International GmbH |
| Merck & Co., Inc. |
| Elanco |
| Virbac |
| Bioveta a.s |
| Hester Biosciences Limited |
| Ceva |
| HIPRA |
| Others |
Supply & Pricing Matrix
Freeze-drying capacity utilization rates above 80% in OECD manufacturing clusters compress marginal cost curves for thermostable formulations while elevating price floors for new entrants lacking captive lyophilization infrastructure. This scale dynamic concentrates supply-side pricing power among incumbent biologics specialists with multi-decade equipment amortization, forcing municipal tender competitors to absorb margin erosion through volume commitments.
Pricing Analysis
USDA Center for Veterinary Biologics dictates the pricing tier structure through duration-of-immunity label claim evidentiary requirements that stratify products across premium, standard, and economy levels. Certification grade and cold-chain reliability serve as primary price differentiation drivers, with WHO-prequalified formulations commanding 15-30% premiums over non-harmonized alternatives. Pricing pressure stems from Brazilian state-level procurement consolidation that aggregates municipal rabies control volumes into single-tender awards. Animal shelters and municipal control programs exhibit extreme price sensitivity, while premium companion animal clinics in the United States and United Kingdom demonstrate minimal elasticity for intranasal delivery formats.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient and bacterial substrate production for attenuated virus formulations, while Germany and the United States concentrate recombinant vector platform manufacturing. Supply chains draw from embryonated egg supplies, cell culture media, and proprietary adjuvant chemistries as critical inputs. Single-source vulnerability in lyophilization equipment—where three European OEMs control 70% of global freeze-dryer installation—creates capacity allocation risk during demand surges. Distribution runs through specialized cold-chain logistics providers with 2-8°C validated packaging, bypassing general pharmaceutical wholesalers due to potency preservation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary clinic consolidation across North America and Brazil has shifted buyer power toward corporate procurement offices, fragmenting pricing leverage for independent practices and compressing distributor margins in institutional channels.
For Market Incumbents: Secure adjuvant platform patent positions through licensing negotiations or captive R&D investment to defend against recombinant vector substitution threats. Add freeze-drying capacity in India or Brazil to capture municipal tender economics while maintaining premium positioning in OECD markets through duration-of-immunity extension claims. Channel control through direct supply agreements with corporate veterinary chains eliminates distributor markups and locks in volume commitments. For New Entrants and Emerging Players: Differentiate on thermostable formulation development for tropical climate distribution, where cold-chain infrastructure gaps create spoilage risk for incumbent liquid suspension products. Target Indian municipal corporation tenders and Brazilian state health secretariat procurement as the most penetrable institutional segments, leveraging contract manufacturing relationships with established CDSCO or ANVISA-registered facilities. A go-to-market angle emphasizing oral rabies bait co-development with wildlife management agencies opens distinct regulatory pathways with reduced competitive density. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among recombinant vector platform specialists with captive manufacturing and multi-year municipal supply contracts. Long-term viability over a 5-10 year horizon favors biologics manufacturers with backward integration into adjuvant chemistry and forward integration into cold-chain distribution. The acquisition target archetype comprises mid-scale regional specialists with ANVISA or CDSCO registration and underutilized lyophilization capacity. The signal to watch is duration-of-immunity label claim approvals, which trigger portfolio restructuring and create distressed asset opportunities among single-antigen producers.| Strategic Initiative | Industry Significance |
|---|---|
| Adjuvant Platform Licensing Agreement | Secures proprietary immunostimulant access for differentiated duration-of-immunity claims against USDA evidentiary standards. |
| Freeze-Drying Capacity Expansion | Captures municipal tender economics in Brazil and India through thermostable formulation cost leadership. |
| Direct Supply Agreement with Corporate Chains | Bypasses distributor markups in United States and Brazilian veterinary clinic consolidation. |
| Oral Rabies Bait Co-Development | Opens wildlife vector control procurement channels with distinct USDA regulatory pathways. |
| ISO Harmonization Certification Investment | Streamlines multi-market registrations across OECD jurisdictions through unified quality system adoption. |
Research Methodology
The analysis maps vaccine type segments, administration route configurations, and distribution channel structures, each validated through veterinary clinic procurement managers, municipal animal control officers, and biologics regulatory affairs specialists. Primary interviews with cold-chain logistics providers and freeze-drying equipment manufacturers combined with secondary validation from USDA Center for Veterinary Biologics guidance documents, EMA veterinary product standards, and ANVISA registration databases. Bottom-up volume modeling across national markets triangulates against top-down value estimates derived from manufacturer revenue disclosures and institutional tender award records.
Consistency checks against WHO rabies elimination framework implementation timelines and OECD veterinary biologics trade flows validated projection outputs across the analysis window. Segmentation dimensions modeled include vaccine type, administration route, end user category, and distribution channel, with regional regulatory cluster differentiation for USDA, EMA, and ANVISA jurisdictions. CAGRs were derived from historical volume trajectories and policy-mandated vaccination schedule changes, incorporating lyophilization capacity expansion announcements and municipal procurement consolidation patterns as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain infrastructure investment, stable regulatory evidentiary requirements, and continued municipal funding for rabies control programs would require recalibration. Forecasts reflect assumptions regarding WHO elimination framework alignment, patent expiry schedules for proprietary adjuvant platforms, and freeze-drying equipment lead time normalization. Recalibration cycles align with material shifts in USDA label claim requirements, EMA veterinary product standard revisions, and municipal procurement consolidation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Tables Market
Veterinary
Europe Dog Dewormers Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
USA Animal Model Market
Veterinary
Global Veterinary Telemetry Systems Market
Veterinary
Veterinary Supplements Market
Veterinary
Milking Salve Market
Veterinary
Global Veterinary Rapid Test Market
Veterinary
OTC Cat Medicines Market
Veterinary
Europe Veterinarians Market
Veterinary
Global Animal Sedative Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Global Animal Model Market
Veterinary
Global Swine Vaccines Market
Veterinary
Europe Veterinary Antibiotics Market