
 Canine Parvovirus Market | 2026-2036
Canine Parvovirus Market Size, Share, and Industry Trends Forecast 2026-2036
Canine Parvovirus Market Analytics
Modified-live vaccine potency standards are reorganizing competitive dynamics among canine parvovirus suppliers. Zoetis leverages its USDA-licensed manufacturing network to sustain domestic supply security for veterinary distributors. Boehringer Ingelheim anchors European supply through its German production complex, while Merck Animal Health differentiates via recombinant vector platforms for multivalent canine vaccines.
Canine parvovirus refers to a non-enveloped, single-stranded DNA virus of the Parvoviridae family that targets rapidly dividing intestinal crypt cells and bone marrow progenitors in domestic dogs, with commercial products engineered to minimum infectious dose titers of 10^7.0 TCID50 per dose to ensure seroconversion. Vaccines command the largest revenue pool due to mandatory puppy protocols and revaccination schedules, while diagnostic kits represent the fastest-expanding segment as point-of-care antigen tests displace centralized laboratory workflows. Treatment medications concentrate margin in hospital-grade formulations, with intravenous delivery modes dominating severe clinical presentations.
USDA Center for Veterinary Biologics governs batch release and potency testing for canine parvovirus vaccines sold in the United States, while EMA veterinary product standards shape market access across European member states and ISO 17025 accreditation requirements drive diagnostic kit manufacturer qualification. Stakeholders must monitor evolving USDA guidance on duration-of-immunity labeling claims and EMA trends toward reduced animal testing in vaccine batch release.
Market Dynamics
USDA potency benchmarks for modified-live canine parvovirus vaccines are compressing supplier margins while veterinary clinics consolidate purchasing power through distributor networks. This regulatory tightening favors manufacturers with captive biologics production infrastructure.
Growth Catalysts
- Puppy vaccination protocols:Mandatory primary series and revaccination schedules create recurring demand cycles across veterinary clinics and animal shelters.
- EMA batch-release harmonization:Streamlined veterinary product standards accelerate cross-border vaccine distribution among European member states.
- Point-of-care antigen testing:Rapid diagnostic kits displace centralized laboratory workflows, expanding access in rural veterinary settings.
Market Restraints
- Cold-chain infrastructure gaps:Temperature-sensitive modified-live vaccines face distribution constraints in regions with unreliable veterinary logistics networks.
- USDA licensing timelines:Extended potency verification and safety testing protocols delay new entrant market access by 18-36 months.
- Recombinant vector substitution:Novel platform technologies threaten conventional modified-live vaccine market positioning in premium veterinary segments.
Strategic Opportunities
- Brazilian veterinary network expansion:Underpenetrated companion animal clinics in São Paulo and Rio de Janeiro states present volume growth potential.
- Duration-of-immunity labeling:Extended revaccination interval claims offer differentiation against commodity vaccine positioning.
- Telemedicine-integrated diagnostics:Remote veterinary consultation platforms create new channels for at-home parvovirus test kit distribution.
Industry Challenges
- Veterinary virology expertise scarcity:Specialized talent for vaccine potency assay development concentrates at USDA-licensed manufacturing sites.
- Biocontainment facility capex:Modified-live vaccine production requires Biosafety Level 2 infrastructure investments exceeding $50 million per facility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canine Parvovirus Market |
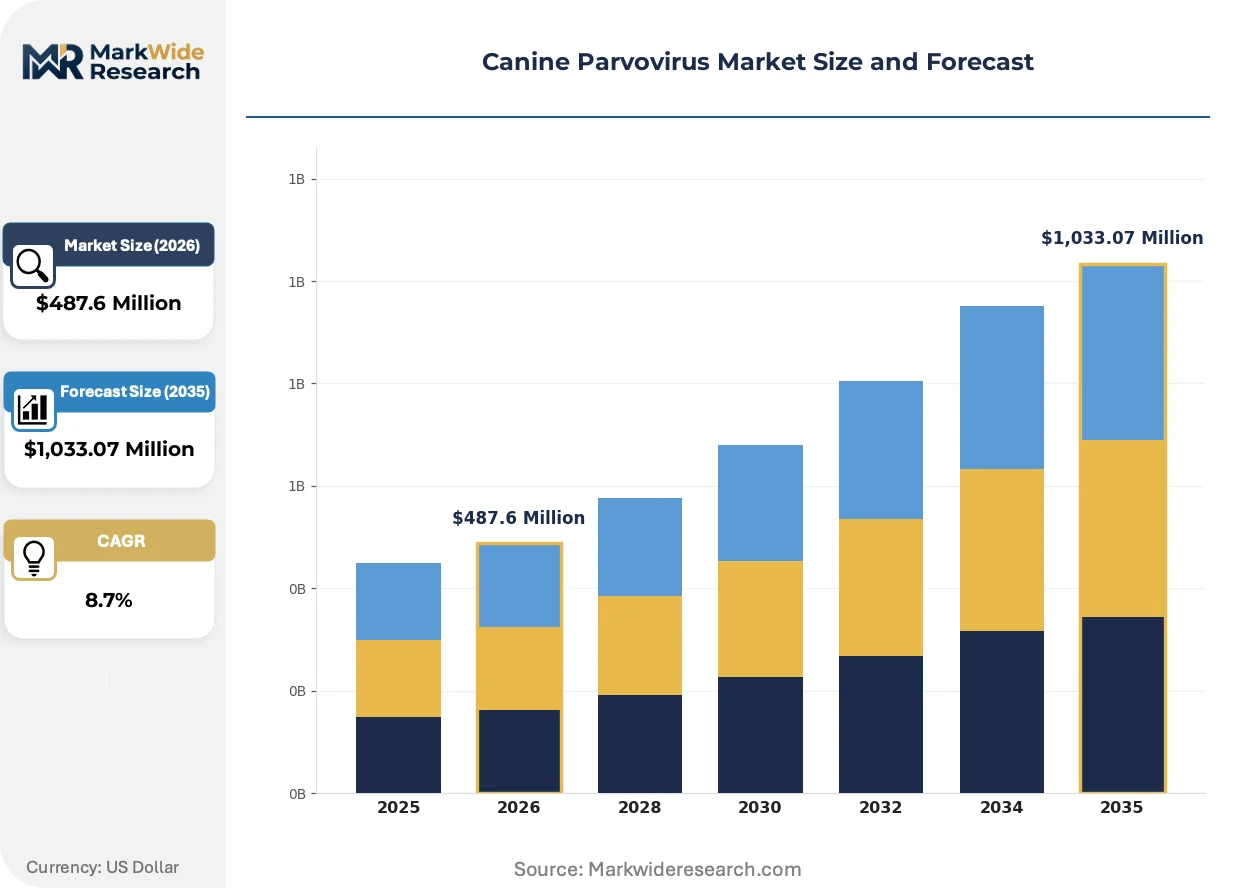
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Diagnostic Kits, Treatment Medications, Support Care Products End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Pet Care Centers Delivery Mode: Injection, Oral, Intravenous, Topical Formulation: Liquid, Powder, Suspension, Gel |
| Companies Covered | Zoetis, Elanco Animal Health, Boehringer Ingelheim, Merck Animal Health, Virbac, Ceva Santé Animale, IDEXX Laboratories, Vetoquinol, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canine Parvovirus Market Evolving Landscape
Recombinant vector platforms and point-of-care diagnostics are fragmenting the traditional vaccine-diagnostic value chain. These shifts compress testing turnaround times while raising the technical bar for new manufacturing entrants.
Messenger RNA vaccine technology is decomposing the dominance of conventional modified-live platforms in canine infectious disease prevention. Major veterinary teaching hospitals are piloting mRNA parvovirus candidates in controlled challenge studies. This platform transition threatens to obsolete legacy adjuvant formulations and reshape supplier R&D allocation across the sector.
USDA Center for Veterinary Biologics guidance on reduced animal testing for vaccine batch release is tightening compliance pathways for domestic manufacturers. The agency's 3Rs initiative (replacement, reduction, refinement) mandates in vitro potency assay validation. European suppliers exporting to the United States must now harmonize with these USDA standards or face extended import review cycles.
Subscription-based preventive care plans are consolidating vaccine procurement decisions at the corporate veterinary group level rather than individual clinic discretion. Mars Veterinary Health and Vetcor are negotiating enterprise pricing directly with manufacturers. This concentration is most visible in the United States, where corporate practice ownership now exceeds 25 percent of companion animal hospitals.
Canine Parvovirus Market Segmentation
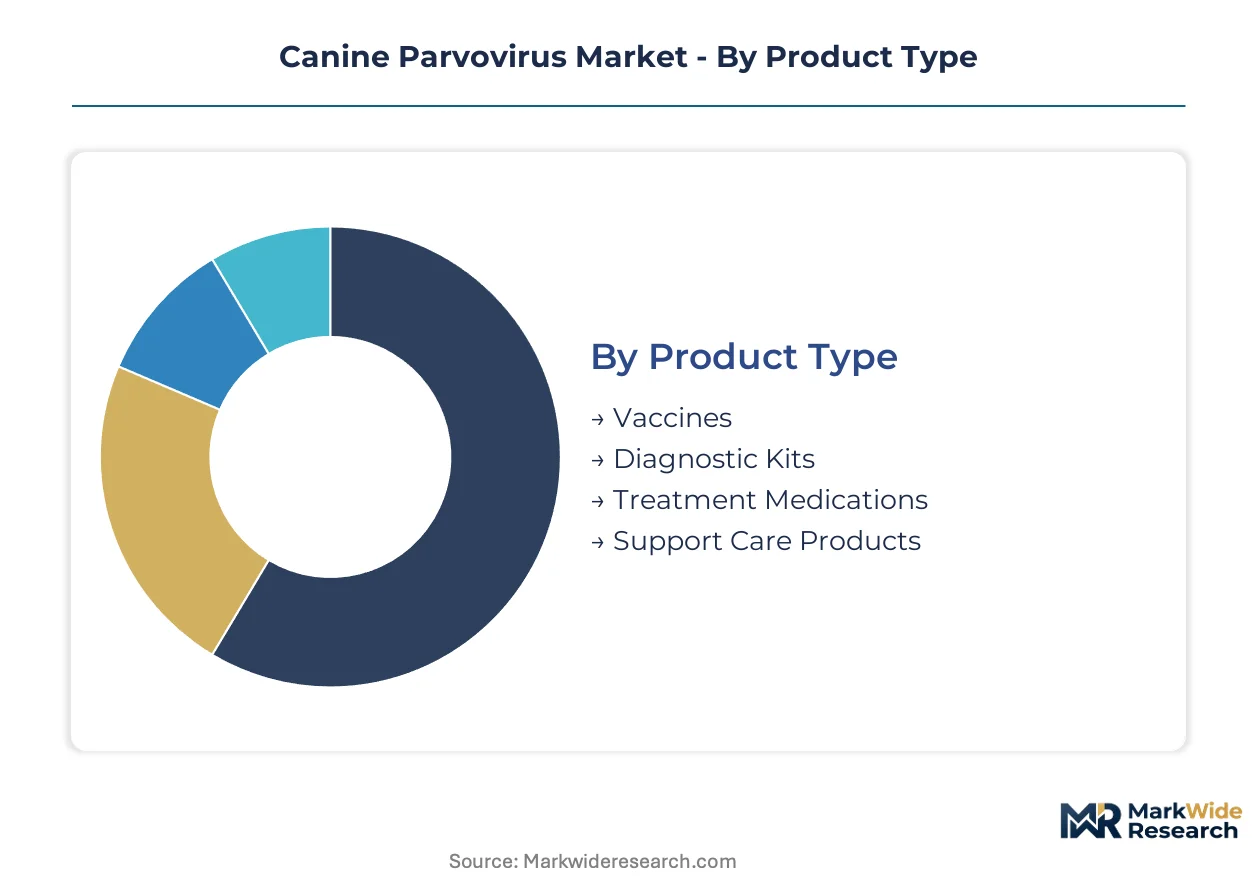
Canine parvovirus market segmentation reveals distinct procurement patterns across veterinary settings. Product type distribution tracks directly to regulatory approval pathways, while end-user concentration reflects corporate consolidation in companion animal care.
Product Type:
Domestic supply security concentrates in modified-live vaccines manufactured under USDA Center for Veterinary Biologics licensing, while diagnostic kit sourcing increasingly draws from ISO 17025-accredited facilities across multiple geographies.
- Vaccines:Modified-live and recombinant vector formulations engineered to minimum infectious dose titers of 10^7.0 TCID50 per dose. Demand clusters in United States veterinary clinics executing mandatory puppy protocols, constrained by cold-chain infrastructure requirements for temperature-sensitive biologics.
- Diagnostic Kits:Point-of-care antigen detection platforms displacing centralized laboratory workflows. Growth concentrates in rural veterinary settings across Brazil and Germany, driven by telemedicine-integrated consultation models requiring rapid turnaround.
- Treatment Medications:Hospital-grade formulations for severe clinical presentations.
- Support Care Products:Adjunctive therapies managing dehydration and secondary complications.
Vaccines command the established base. The steepest expansion runs through diagnostic kits.
End User:
Procurement authority is shifting from individual clinic discretion to corporate veterinary group headquarters, with subscription-based preventive care plans consolidating purchasing decisions at the enterprise level.
- Veterinary Clinics:Primary care settings administering routine vaccination protocols and initial diagnostic screening. Volume concentrates in corporate-owned networks across the United States, where Mars Veterinary Health and Vetcor negotiate direct manufacturer pricing.
- Animal Hospitals:Emergency and referral centers managing severe parvovirus presentations requiring intravenous fluid therapy and isolation protocols. Demand clusters in metropolitan areas with established specialty referral networks.
- Research Laboratories:Academic and contract facilities conducting vaccine efficacy trials.
- Pet Care Centers:Boarding and daycare facilities implementing preventive health screening.
Veterinary clinics command the established base. The steepest expansion runs through animal hospitals.
Delivery Mode:
Route selection tracks to clinical severity, with parenteral methods dominating hospital-grade applications and oral formulations limited to prophylactic or maintenance contexts.
- Injection:Subcutaneous and intramuscular routes for vaccine administration and depot formulations. Demand concentrates in United States and German veterinary clinics executing standardized puppy protocols, constrained by practitioner training requirements for proper technique.
- Intravenous:Direct vascular access for fluid resuscitation and critical care medications. Growth clusters in animal hospitals managing severe enteric presentations, driven by inpatient mortality reduction protocols.
- Oral:Enteral administration for maintenance hydration and nutritional support.
- Topical:Dermal applications for adjunctive symptomatic management.
Injection commands the established base. The steepest expansion runs through intravenous delivery.
Formulation:
Physical state selection reflects stability requirements, distribution logistics, and reconstitution protocols at the point of use.
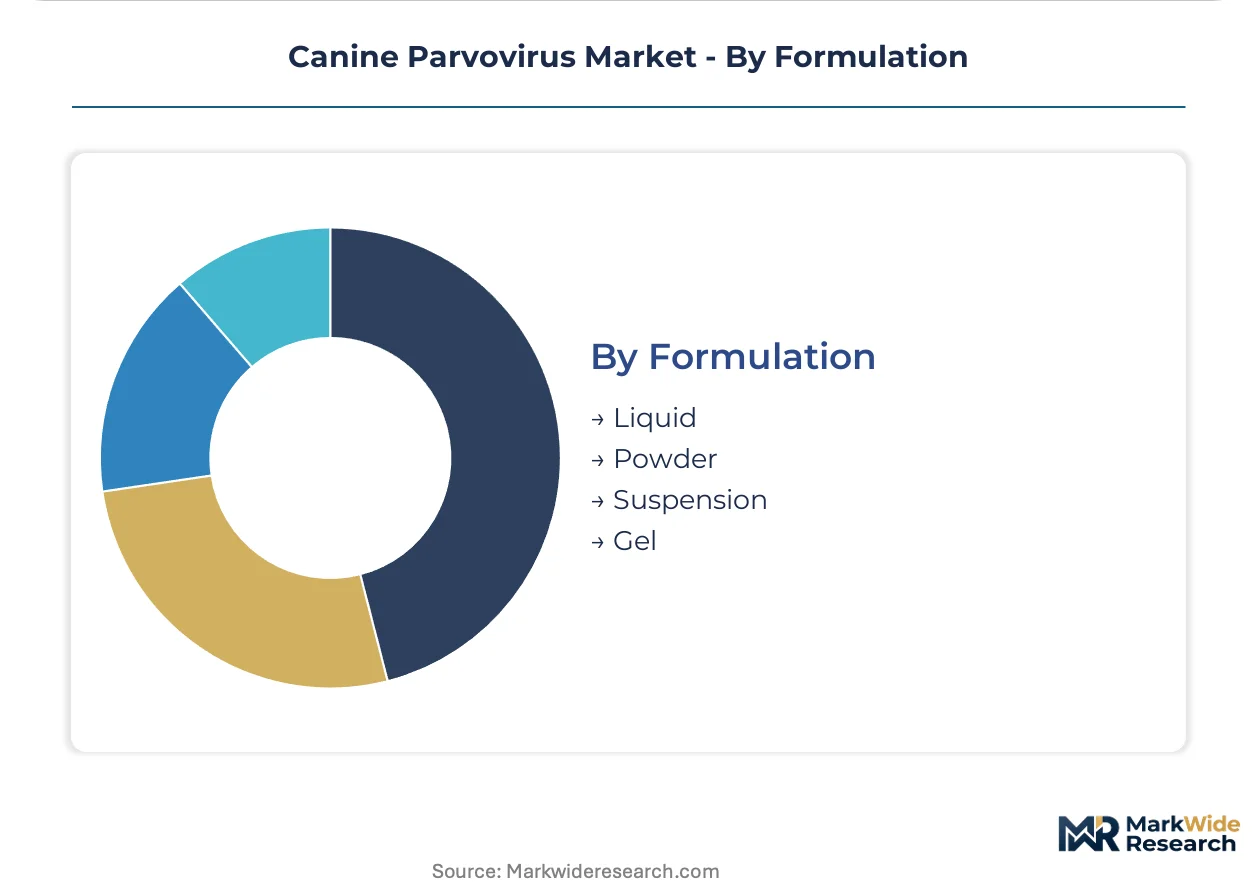
- Liquid:Ready-to-use solutions for immediate administration in clinical settings. Demand concentrates in high-throughput United States veterinary clinics prioritizing workflow efficiency, constrained by shorter shelf life and cold-chain dependency.
- Powder:Lyophilized formats requiring reconstitution prior to use, common in modified-live vaccines. Growth clusters in export markets where ambient temperature stability extends distribution reach.
- Suspension:Colloidal dispersions for depot-effect formulations.
- Gel:Viscous preparations for topical or mucosal application.
Liquid formulations command the established base. The steepest expansion runs through powder formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary clinics in the United States absorb price premiums for USDA-licensed vaccines with minimal elasticity, while Brazilian distributors face acute price sensitivity due to fragmented purchasing networks and cold-chain cost burdens.
United States
Corporate veterinary groups Mars Veterinary Health and Vetcor consolidate procurement decisions across over 25 percent of companion animal hospitals. USDA Center for Veterinary Biologics licensing requirements tighten potency verification timelines, compressing supplier margins. Manufacturing infrastructure clusters in Kansas and Iowa, where Zoetis and Merck Animal Health operate captive biologics facilities serving domestic distributor networks.
Brazil
São Paulo and Rio de Janeiro states present underpenetrated clinic density relative to canine population scale, driving volume expansion targets. ANVISA veterinary product registration harmonizes with USDA standards for imported modified-live vaccines, though extended review cycles delay new entrant access. Cold-chain infrastructure gaps in northern states constrain temperature-sensitive biologics distribution beyond major metropolitan corridors.
Germany
Boehringer Ingelheim anchors European supply through its Ingelheim production complex, serving EMA-regulated markets with batch-release harmonization accelerating cross-border distribution. EMA veterinary product standards on reduced animal testing mandate in vitro potency assay validation, raising technical barriers for diagnostic kit manufacturers. The Baden-Württemberg corridor concentrates research laboratory demand for vaccine efficacy trials.
China
NMPA veterinary biologics registration requirements diverge from USDA and EMA standards, creating separate compliance pathways for domestic and imported vaccines. The Yangtze River Delta hosts contract manufacturing organizations developing point-of-care diagnostic platforms for export markets. Local canine vaccination protocols remain less standardized than Western markets, limiting premium vaccine penetration.
Australia
TGA veterinary product standards align closely with USDA benchmarks, facilitating streamlined import pathways for US-manufactured modified-live vaccines. The Sydney-Melbourne corridor dominates specialty animal hospital demand for intravenous treatment medications. Rural veterinary networks in Queensland and Western Australia drive point-of-care antigen testing adoption to offset centralized laboratory distance.
Canine Parvovirus Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with recombinant vector platform developers commanding premium positioning while established modified-live manufacturers defend volume through scale economies. The supplier base concentrates among USDA-licensed biologics producers with captive manufacturing infrastructure, creating tiered access barriers for new entrants. Three archetypes dominate: integrated pharmaceutical conglomerates with veterinary divisions, specialized animal health pure-plays, and diagnostic-focused technology developers. Competitive dynamics center on duration-of-immunity labeling differentiation and corporate veterinary group enterprise pricing negotiations.
Among integrated pharmaceutical conglomerates, Zoetis and Boehringer Ingelheim exemplify the scale-driven archetype with captive biologics production networks spanning multiple regulatory jurisdictions. Merck Animal Health occupies a position within the technology-differentiated tier, representing recombinant vector platform development priorities. These three companies anchor the competitive structure through distinct strategic postures rather than overlapping market pursuit.
| Leading Market Players |
|---|
| Zoetis |
| Elanco Animal Health |
| Boehringer Ingelheim |
| Merck Animal Health |
| Virbac |
| Ceva Santé Animale |
| IDEXX Laboratories |
| Vetoquinol |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
USDA Center for Veterinary Biologics licensing requirements simultaneously gate supplier qualification and stratify pricing tiers across the canine parvovirus market, with modified-live vaccine manufacturers commanding premium positioning unavailable to diagnostic kit producers lacking captive biologics infrastructure. This regulatory architecture concentrates margin capture among USDA-licensed facilities while compressing returns for distributors facing extended potency verification timelines.
Pricing Analysis
After-sales service contracts for revaccination scheduling and telemedicine-integrated diagnostic support now drive lifetime value beyond initial product transactions. Three-tier pricing structure across premium USDA-licensed vaccines, standard EMA-registered imports, and economy unbranded alternatives reflects certification grade and cold-chain reliability. Cost compression in the economy tier intensifies because Brazilian distributors absorb ambient stability premiums for lyophilized formats. Corporate veterinary groups exhibit lowest price sensitivity due to enterprise pricing negotiations, while independent rural clinics in northern Brazil face acute cost constraints.
Supply Chain Analysis
Strategic stockpiling of modified-live vaccines dominates procurement behavior due to temperature sensitivity and batch-release uncertainty, contrasting with just-in-time preferences for point-of-care diagnostic kits. Manufacturing concentrates in the United States, Germany, and Brazil, with captive biologics facilities in Kansas and Iowa anchoring North American supply. Production draws from embryonated egg substrates, cell culture media, and sterile filtration systems. Single-source vulnerability runs through German recombinant vector platform suppliers. Distribution runs through veterinary distributor networks consolidating purchasing decisions at corporate headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diagnostic kit subscriptions and telemedicine-integrated consultation platforms represent the fastest-expanding recurring-revenue layer, outpacing vaccine hardware sales as corporate veterinary groups consolidate procurement around preventive care plans.
For Market Incumbents: Consolidate manufacturing footprint through backward integration into Biosafety Level 2 biologics facilities, defending against mRNA platform substitution by securing USDA duration-of-immunity labeling extensions. Channel control through direct corporate group negotiations anchors volume retention against emerging recombinant vector competitors. For New Entrants and Emerging Players: Anchor in São Paulo and Rio de Janeiro veterinary networks, where clinic density lags canine population scale and ANVISA registration pathways favor agile diagnostic kit developers over vaccine manufacturers. Telemedicine-integrated antigen testing platforms offer the most penetrable entry angle for capital-constrained entrants. For Investors and Strategic Acquirers: EMA reduced animal testing mandates reshape the acquisition landscape toward diagnostic kit manufacturers with validated in vitro potency assays. The five-to-ten year viability window favors platform-agnostic players with ISO 17025 accreditation spanning multiple regulatory jurisdictions. Watch USDA guidance on mRNA veterinary vaccine approval timelines as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Duration-of-Immunity Labeling Extension | USDA approval for extended revaccination intervals differentiates premium vaccines from commodity alternatives in corporate procurement. |
| Telemedicine Platform Partnership | Integration with Mars Veterinary Health and Vetcor remote consultation systems opens at-home diagnostic kit distribution channels. |
| Lyophilized Format Scale-Up | Ambient temperature stability extends distribution reach into Brazilian northern states lacking reliable cold-chain infrastructure. |
| In Vitro Potency Assay Validation | EMA and USDA 3Rs compliance eliminates animal testing bottlenecks while raising technical barriers for diagnostic kit competitors. |
| Corporate Group Enterprise Pricing | Direct negotiation with consolidated purchasing departments secures volume commitments exceeding twenty-five percent of companion animal hospitals. |
Research Methodology
A spread of perspectives from veterinary biologics manufacturing directors, USDA regulatory affairs specialists, corporate veterinary group procurement officers, and point-of-care diagnostic platform engineers converged on the working assumptions shaping this analysis. Primary field engagement combined with secondary validation from FDA Center for Veterinary Biologics guidance documents, EMA veterinary product standards, ANVISA registration databases, and ISO 17025 accreditation records. Bottom-up clinic-level demand estimation triangulated against top-down manufacturer shipment data.
Segmentation dimensions modeled include product type, end-user category, delivery mode, and formulation state across the projection horizon. CAGRs derived from historical growth pattern analysis applied to regulatory pipeline visibility and corporate consolidation trajectories. Forecast inputs incorporated puppy vaccination protocol adherence rates and cold-chain infrastructure development curves by metropolitan corridor.
Decision-makers should treat outputs as directional under sustained USDA potency benchmark tightening and EMA batch-release harmonization; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as mRNA platform efficacy data and corporate veterinary group M&A activity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Companion Animal Arthritis Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Companion Animal Drugs Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Veterinary Excipients Market
Veterinary
France Veterinary Healthcare Market
Veterinary
Global Animal Vaccine Market
Veterinary
Swine Respiratory Diseases Treatment Market
Veterinary
Global Cattle Vaccines Market
Veterinary
Global Veterinary Point of Care Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
ASEAN Poultry Vaccines Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market
Veterinary
US Surgical Pet Collar Market