
 Bovine Collagen Market | 2026-2036
Bovine Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Bovine Collagen Market Analytics
Contracted collagen peptide subscriptions for monthly wellness regimens is consolidating recurring revenue streams away from one-time ingredient sales. Gelita leverages its vertical integration across rendering to finished peptide to sustain margin control in hydrolyzed grades. Rousselot anchors European pharmaceutical certification with specialized native collagen for hemostatic applications. PB Leiner competes on scale in South American bovine hide sourcing.
Bovine collagen denotes the fibrous structural protein extracted from cow hides, bones, and connective tissues through acid or alkaline hydrolysis, yielding gelatin at partial cleavage or bioactive peptides at complete enzymatic breakdown; it functions as a gelling agent, emulsifier, and tissue scaffold across food, medical, and cosmetic systems. Hydrolyzed collagen and collagen peptides command premium positioning in dietary supplements and functional beverages where solubility and amino acid bioavailability determine formulation value. Gelatin retains mature, volume-driven demand in confectionery and capsule shells, while native collagen occupies narrow but high-margin niches in wound care matrices and regenerative medicine.
The FDA enforces BSE-related sourcing restrictions through 21 CFR regulations, while EFSA mandates species identification and geographical traceability under feed and food safety frameworks; REACH and EU MDR further govern collagen use in medical devices and cosmetics, elevating compliance costs for non-certified suppliers. China's NMPA and GB standards impose additional veterinary health documentation on imported bovine materials. Stakeholders must monitor evolving ESG disclosure requirements from the EU Green Deal and CSRD, as supply chain transparency becomes inseparable from market access in premium segments.
Market Dynamics
Clean-label formulation mandates from nutraceutical buyers are compressing supply chains toward documented, single-species sourcing. This pressure forces rendering facilities to invest in DNA authentication and blockchain traceability systems.
Growth Catalysts
- EFSA species-identification mandates:European food and supplement manufacturers now require certified bovine-only collagen, eliminating porcine cross-contamination risks and opening premium pricing tiers for verified suppliers.
- Enzymatic hydrolysis advancement:Improved protease specificity yields collagen peptides below 3,000 Daltons with enhanced bioavailability, accelerating adoption in sports nutrition and functional beverage formulations.
- Brazilian hide processing concentration:Integrated tannery-to-peptide facilities in São Paulo state capture economies of scale, lowering input costs for global nutraceutical contract manufacturers.
Market Restraints
- BSE-related 21 CFR restrictions:FDA sourcing prohibitions on specified risk materials from certain geographies limit raw material pools and elevate compliance documentation burdens.
- Gelatin substitution by plant-based hydrocolloids:Pectin, carrageenan, and modified starch alternatives displace bovine gelatin in conventional confectionery and soft capsule applications.
- Argentine hide supply volatility:Currency instability and export quota fluctuations in Argentina's cattle sector create input price unpredictability for peptide manufacturers.
Strategic Opportunities
- India's PLI scheme for active pharmaceutical ingredients:Domestic collagen production incentives could reduce import dependency for medical device and hemostat manufacturers in Mumbai and Hyderabad clusters.
- Personalized nutrition subscription models:Direct-to-consumer peptide regimens bypass traditional ingredient distribution, capturing margin from end-user relationships.
- EU Green Deal ESG disclosure requirements:Early compliance with CSRD supply chain transparency standards secures preferential access to premium cosmetic and pharmaceutical accounts.
Industry Challenges
- EU MDR technical documentation timelines:Medical device collagen suppliers face 12-18 month certification cycles for hemostatic and wound care applications, delaying revenue recognition.
- Peptide-to-gelatin process switching complexity:Multi-product facilities struggle to balance enzymatic hydrolysis capacity against gelatin extraction demand swings without yield degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bovine Collagen Market |
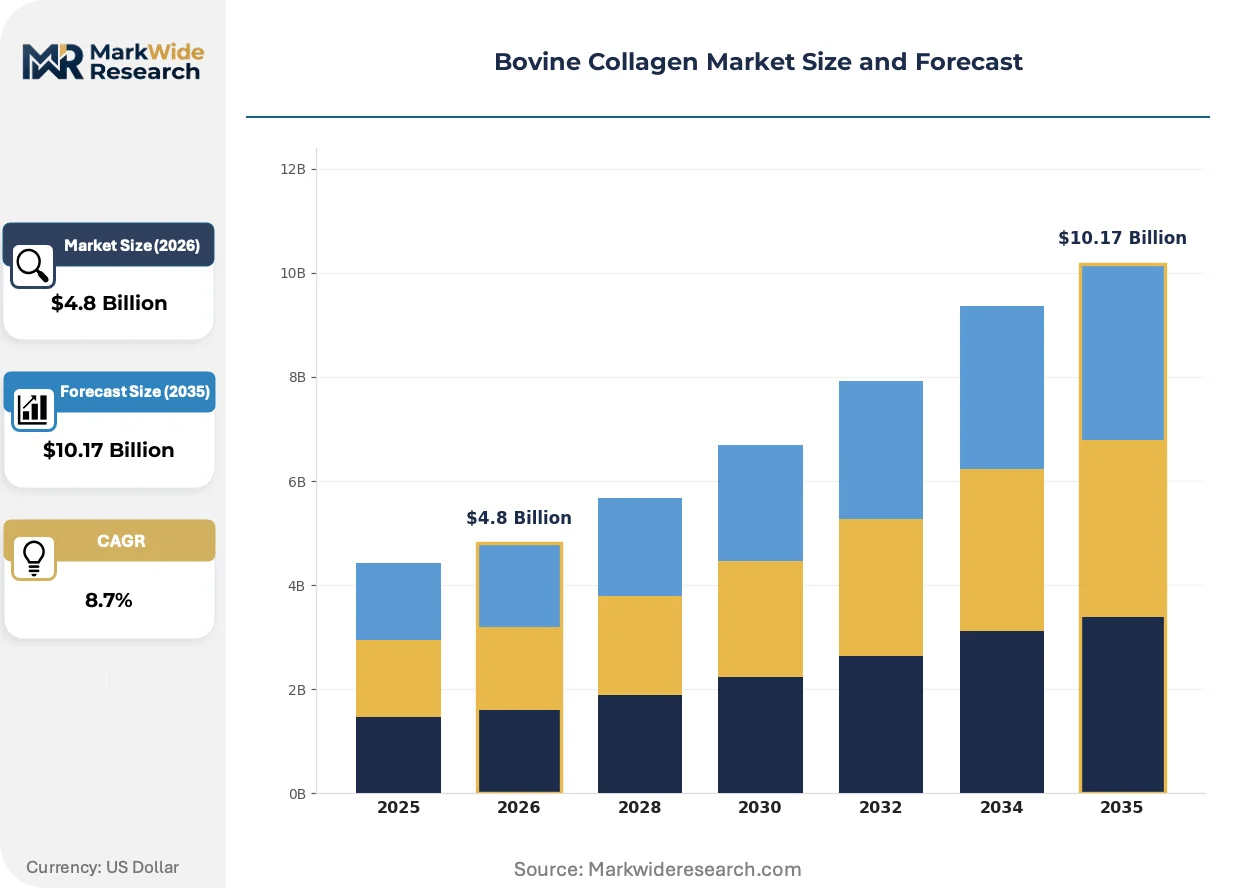
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Native Collagen Application: Cosmetics, Dietary Supplements, Food and Beverages, Pharmaceuticals Form: Powder, Liquid, Capsule, Granules End User: Healthcare Providers, Cosmetic Manufacturers, Nutraceutical Companies, Food Industry |
| Companies Covered | Gelita, Nitta Gelatin, Rousselot, Weishardt, Collagen Matrix, PB Leiner, Vital Proteins, Lapi Gelatine, Vinh Hoan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bovine Collagen Market Evolving Landscape
Biotechnology and digital traceability systems are restructuring how collagen moves from abattoir to finished formulation. These shifts compress traditional intermediaries while elevating verification requirements.
Precision fermentation of recombinant collagen proteins is decentralizing raw material sourcing away from conventional rendering operations. Startups in California and the Netherlands now produce bio-identical triple-helix structures without cattle inputs. Cosmetic formulators in South Korea and Japan are piloting these materials for vegan positioning. This technology is decentralizing geographic supply risk but intensifying R&D competition between biotech entrants and established hide processors.
REACH registration requirements for collagen derivatives used in medical devices are tightening substance documentation obligations. ECHA deadlines now demand full toxicological profiles for peptide fractions above one ton annual volume. German and Swiss device manufacturers are consolidating supplier bases to reduce compliance fragmentation. Native collagen for regenerative medicine faces the steepest documentation burden, pushing smaller peptide suppliers toward hydrolyzed grades with simpler dossiers.
Subscription-based wellness regimens are displacing bulk ingredient procurement in premium nutraceutical channels. Direct-to-consumer brands in the United States and United Kingdom now contract quarterly peptide deliveries rather than spot purchasing. This model concentrates buyer power with platform operators while squeezing traditional distributors. Contract manufacturers in Utah and Oregon are reconfiguring production schedules to match recurring shipment cadences rather than batch-scale optimization.
Bovine Collagen Market Segmentation
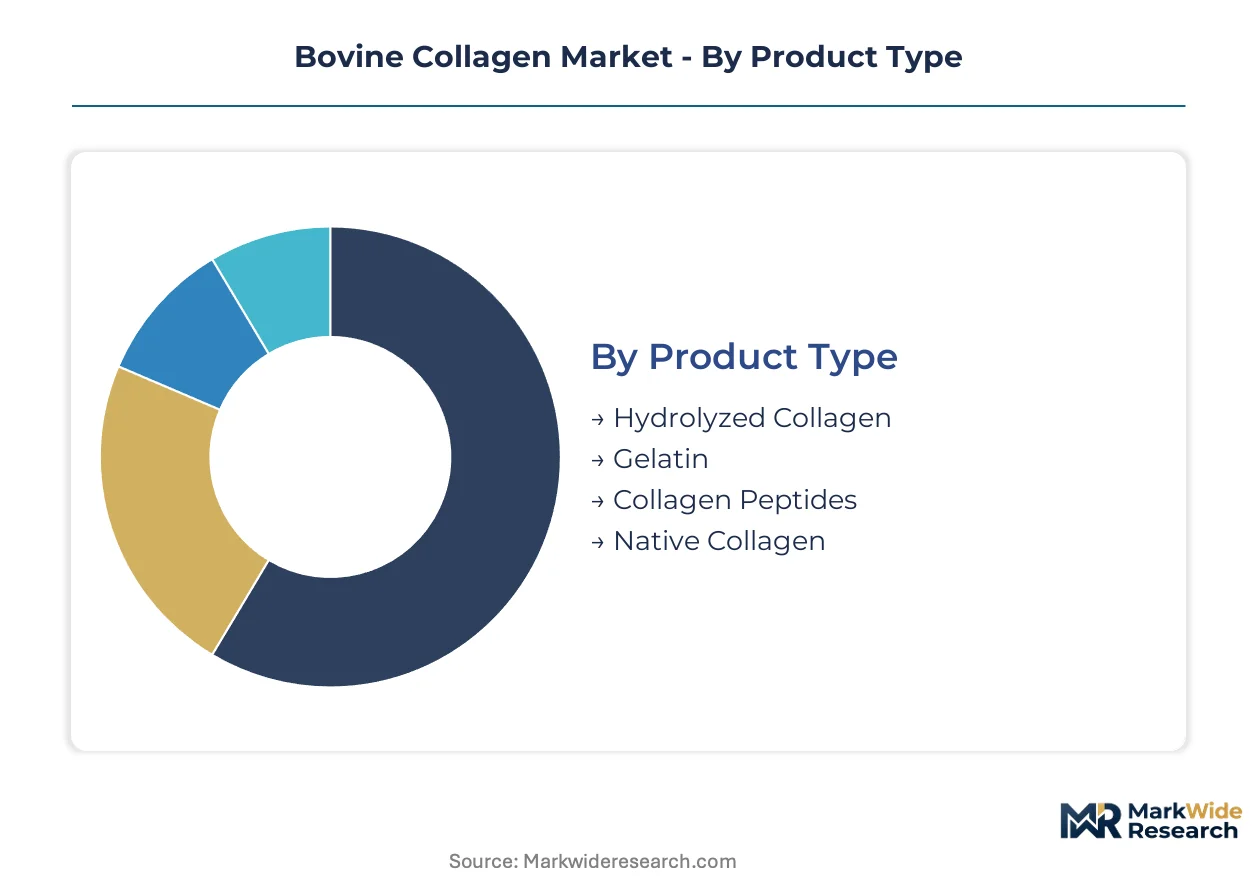
Segmentation in bovine collagen markets separates margin pools by certification burden and functional specification. Hydrolyzed grades command pharmaceutical premiums where FDA 21 CFR and EU MDR documentation gates access, while gelatin volumes flow through less regulated food channels.
Product Type:
FDA BSE sourcing restrictions and EU MDR technical documentation requirements concentrate compliance costs unevenly across product categories, with native collagen facing the steepest certification barriers.
- Hydrolyzed Collagen:Enzymatically cleaved to peptide fractions below 3,000 Daltons for enhanced bioavailability. Sports nutrition formulators in Germany and the United States specify this grade for rapid dissolution in functional beverages, though EFSA species-identification mandates now require DNA-verified bovine-only sourcing documentation.
- Collagen Peptides:Further refined hydrolysates with standardized molecular weight distributions for clinical nutrition applications. Japanese cosmetic manufacturers and South Korean nutricosmetic brands drive procurement of odorless, low-molecular-weight grades for premium positioning in ingestible beauty products.
- Gelatin:Partially hydrolyzed collagen retaining gelling functionality for confectionery and capsule shells. Brazilian integrated processors supply bulk volumes to global pharmaceutical contract manufacturers under less stringent documentation requirements than medical-grade peptides.
- Native Collagen:Intact triple-helix structures preserved through non-denaturing extraction for hemostatic sponges and wound matrices. REACH registration and EU MDR certification cycles of 12-18 months restrict supplier pools to vertically integrated specialists with dedicated regulatory affairs capacity.
Gelatin sits at the top of the volume ranking, with collagen peptides climbing the fastest.
Application:
End-use segmentation tracks diverging margin structures, with pharmaceutical and cosmetic channels rewarding certification investment while food applications compete on scale economies.
- Dietary Supplements:Powder and liquid formulations dominate direct-to-consumer subscription models in the United States and United Kingdom. Contract manufacturers in Utah and Oregon reconfigure production schedules to match quarterly peptide delivery cadences rather than batch-scale optimization.
- Pharmaceuticals:Hemostats, wound care matrices, and regenerative medicine scaffolds require native collagen with full toxicological dossiers under REACH and EU MDR. German and Swiss device manufacturers consolidate supplier bases to reduce compliance fragmentation.
- Cosmetics:South Korean and Japanese formulators pilot precision-fermented recombinant collagen for vegan positioning, though bovine-derived peptides retain cost advantages in mass-market topical applications.
- Food and Beverages:Gelatin retains mature demand in confectionery, though pectin and modified starch alternatives displace bovine sources in conventional gummy and soft candy applications.
Food and beverages sits at the top of the volume ranking, with pharmaceuticals expanding most quickly.
Form:
Physical format determines supply chain configuration, with powder and liquid concentrates enabling bulk ingredient economics while capsules and granules serve finished goods channels.
- Powder:Bulk hydrolysates shipped in industrial drums to contract manufacturers and blenders. Brazilian São Paulo state facilities capture economies of scale in spray-dried peptide production for global nutraceutical brands.
- Liquid:Ready-to-drink collagen shots and beverage premixes concentrate value in South Korean and Japanese beauty-from-within markets. Shelf-stability requirements favor lower-molecular-weight peptides with reduced viscosity.
- Capsule:Hard and soft gelatin shells retain demand in pharmaceutical and supplement applications, though plant-based alternatives gain share in clean-label positioning.
- Granules:Instant-dissolving formats for functional foods and clinical nutrition, with Argentine processors supplying Latin American markets despite currency-driven price volatility.
Powder sits at the top of the volume ranking, with liquid gaining share fastest.
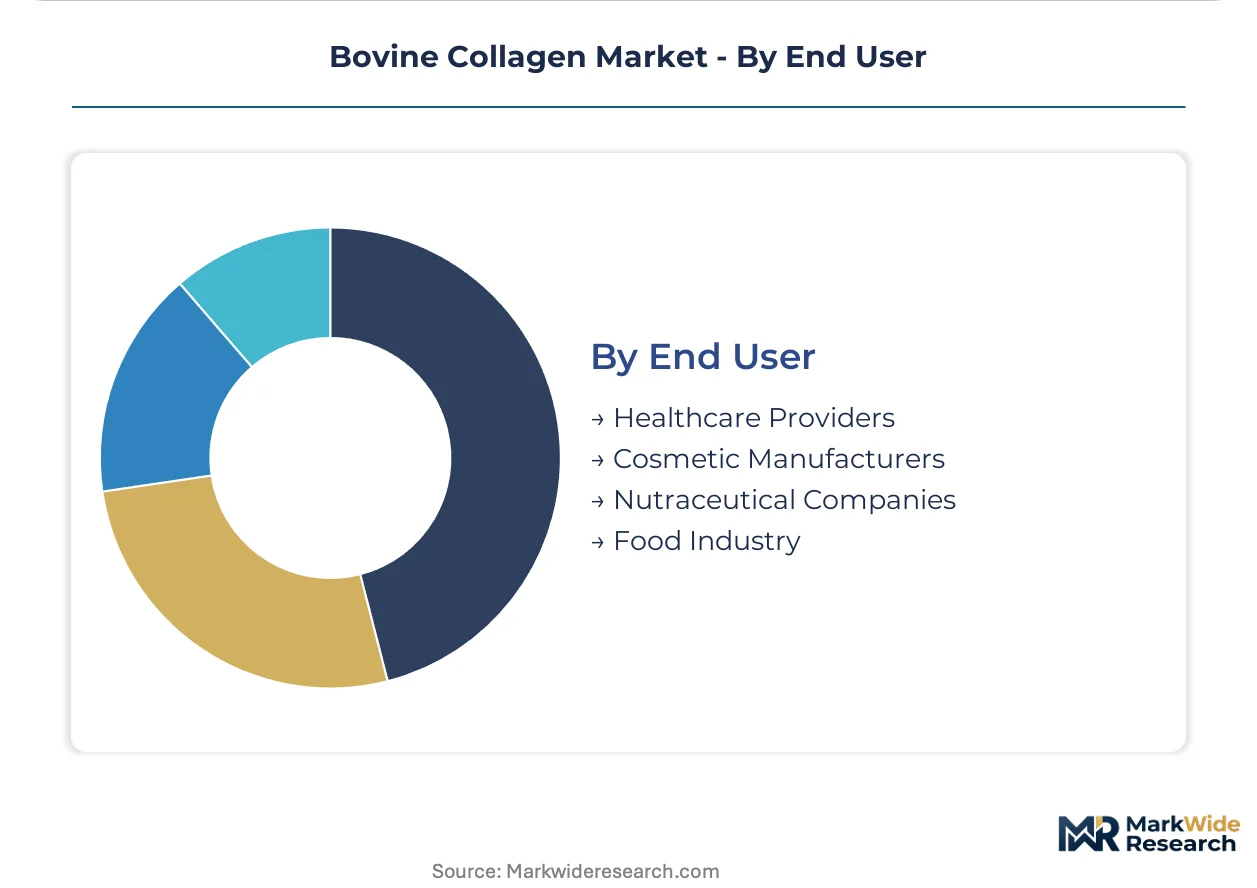
End User:
Customer type segmentation reveals procurement pattern divergence between bulk ingredient buyers and finished formulation specialists.
- Nutraceutical Companies:Drive bulk peptide procurement as clean-label formulations gain priority, with subscription-based wellness regimens consolidating recurring revenue streams away from spot purchasing.
- Cosmetic Manufacturers:South Korean and Japanese formulators specify low-odor, low-molecular-weight grades for premium nutricosmetic positioning, with ESG disclosure requirements under EU CSRD influencing supplier selection.
- Healthcare Providers:Hospital systems and surgical centers source hemostatic and wound care products through group purchasing organizations, with EU MDR certification gating market access for collagen device suppliers.
- Food Industry:Confectionery and dairy processors specify gelatin by Bloom strength and viscosity, with integrated tannery-to-peptide facilities in Brazil capturing cost advantages in high-volume contracts.
Food industry sits at the top of the volume ranking, with nutraceutical companies climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA documentation requirements for veterinary health certificates contrast sharply with Brazil's integrated tannery-to-peptide facilities that bypass import friction entirely. Argentina's currency-driven supply volatility disrupts pricing predictability for peptide manufacturers dependent on hide exports. India's PLI scheme for active pharmaceutical ingredients is redirecting medical-grade collagen investment toward domestic production clusters.
United States
Direct-to-consumer subscription models concentrate buyer power with Utah and Oregon contract manufacturers reconfiguring production for quarterly delivery cadences. FDA 21 CFR BSE sourcing restrictions limit raw material pools to documented, single-species supply chains. Greater Boston and Research Triangle medical device clusters demand native collagen with full toxicological dossiers for hemostatic applications.
Germany
Sports nutrition formulators in Bavaria specify enzymatically hydrolyzed peptides below 3,000 Daltons for rapid dissolution in functional beverages. EFSA species-identification mandates eliminate porcine cross-contamination risks and open premium pricing tiers for verified bovine-only suppliers. The Rhine-Ruhr industrial corridor hosts vertically integrated rendering specialists with dedicated regulatory affairs capacity for REACH documentation.
China
Nutricosmetic brands in Shanghai and Guangzhou drive procurement of odorless, low-molecular-weight grades for premium ingestible beauty positioning. NMPA GB standards impose veterinary health documentation on imported bovine materials, elevating compliance costs for foreign suppliers. Yangtze River Delta peptide processors are consolidating backward integration into rendering operations to circumvent import friction.
Brazil
Integrated tannery-to-peptide facilities in São Paulo state capture economies of scale, lowering input costs for global nutraceutical contract manufacturers. ANVISA alignment with international BSE protocols maintains export access to pharmaceutical markets demanding species-verified sourcing. The Campinas industrial cluster anchors South American hide processing concentration with spray-dried peptide production for bulk industrial drum shipments.
Japan
Cosmetic formulators in Osaka and Tokyo pilot precision-fermented recombinant collagen for vegan positioning, though bovine-derived peptides retain cost advantages in mass-market applications. METI standards for functional food ingredients create documentation gates that favor established suppliers with existing dossier libraries. The Kansai region's nutricosmetic manufacturers specify low-odor grades for premium positioning in beauty-from-within markets.
Bovine Collagen Market Competitive Landscape
Top-tier vendors anchor pharmaceutical certification tiers, while mid-scale processors compete on South American hide sourcing economies and enzymatic hydrolysis yield optimization. The vendor base stratifies across three strategic archetypes: vertically integrated rendering-to-peptide specialists with captive tannery relationships, regional gelatin processors serving confectionery and capsule shell demand, and biotechnology entrants pursuing precision-fermented recombinant alternatives. Dominant competitive moves include backward integration into rendering operations to secure documented single-species supply chains, and portfolio diversification toward medical-grade native collagen to capture hemostatic and wound care premiums.
Among European-based specialists, Rousselot and PB Leiner occupy positions within the certification-intensive pharmaceutical tier, while Gelita exemplifies the vertically integrated archetype with control spanning rendering through finished peptide production. These three entities represent the structural poles around which mid-scale competitors and biotechnology entrants position for access to premium nutraceutical and medical device accounts.
| Leading Market Players |
|---|
| Gelita |
| Nitta Gelatin |
| Rousselot |
| Weishardt |
| Collagen Matrix |
| PB Leiner |
| Vital Proteins |
| Lapi Gelatine |
| Vinh Hoan |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap renderers in Argentina and Brazil anchor supply-side discipline, converting hide availability into pricing leverage through captive tannery relationships. Their financing structures prioritize steady-state cash flows over aggressive capacity expansion, compressing price volatility for hydrolyzed grades while concentrating premium-tier power with vertically integrated European specialists.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for standard-grade collagen peptides, forcing São Paulo processors to compete on volume against established European suppliers. Three-tier pricing structure across pharmaceutical-certified, food-grade, and industrial gelatin levels separates margin pools by documentation burden. Cost compression in food-grade gelatin intensifies because plant-based hydrocolloids displace bovine sources in confectionery applications. Nutraceutical contract manufacturers exhibit highest price sensitivity, while German medical device clusters accept premiums for REACH-registered native collagen.
Supply Chain Analysis
EU MDR certification gates concentrate supplier pools, restricting medical-grade native collagen to vertically integrated specialists with dedicated regulatory affairs capacity. Raw material flows draw from Brazilian tannery clusters, Argentine hide exporters, and Chinese rendering operations. Supply chain risk centers on Argentine currency volatility disrupting hide export pricing predictability. Distribution runs through bulk industrial drum shipments to contract manufacturers, with direct-to-consumer subscription models bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bovine collagen functions as a stable compounder, with recurring revenue from subscription wellness regimens dampening cyclicality inherent in spot ingredient markets.
For Market Incumbents: Deepen backward integration into rendering operations to secure DNA-verified single-species supply chains against precision-fermented recombinant substitutes. Invest in dedicated EU MDR regulatory affairs capacity to defend pharmaceutical certification tiers from mid-scale competitors. Capture margin from end-user relationships by acquiring direct-to-consumer peptide subscription platforms. For New Entrants and Emerging Players: The gap between premium pharmaceutical-certified peptides and economy food-grade gelatin creates entry space for mid-tier sports nutrition specialists. Target German and United States functional beverage formulators seeking rapid-dissolution hydrolysates below 3,000 Daltons. Pursue white-label manufacturing partnerships with Utah and Oregon contract manufacturers reconfiguring production schedules for quarterly delivery cadences. For Investors and Strategic Acquirers: Valuations sit cheapest among South American integrated tannery-to-peptide processors with ANVISA-aligned export protocols. Long-term viability hinges on defensible sourcing documentation rather than commodity scale. Watch EFSA species-identification mandate enforcement as the inflection signal separating verified suppliers from cross-contaminated inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering | Captures documented single-species supply chains required by FDA 21 CFR sourcing restrictions. |
| EU MDR Certification Investment | Opens 12-18 month revenue cycles for hemostatic and wound care native collagen applications. |
| Enzymatic Hydrolysis Yield Optimization | Lowers production costs for peptide fractions below 3,000 Daltons in Brazilian São Paulo facilities. |
| Direct-to-Consumer Subscription Launch | Bypasses traditional distributors by capturing recurring revenue from quarterly peptide delivery regimens. |
| Precision Fermentation R&D Partnership | Positions cosmetic formulators for vegan collagen alternatives piloted in South Korean and Japanese markets. |
Research Methodology
Multiple input streams — primary interviews with rendering facility managers, peptide procurement leads at nutraceutical contract manufacturers, and regulatory affairs directors at medical device firms; secondary validation through FDA 21 CFR filings, EFSA species-identification guidance documents, ANVISA export protocols, and Brazilian customs trade data — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, application, form, and end-user segmentation dimensions produced volume and value outputs over the projection horizon. CAGRs were derived from modeled adoption curves for enzymatic hydrolysis advancement and subscription-based wellness regimen penetration, cross-checked against hide processing capacity expansion in São Paulo state and Yangtze River Delta consolidation trends.
Caveats apply where EFSA enforcement intensity, Argentine currency instability, or precision-fermented recombinant collagen cost curves could materially shift the outlook. Forecasts reflect assumptions about regulatory documentation timelines and clean-label formulation priority persistence. A model refresh is warranted upon material change in EU MDR certification cycle duration or Brazilian tannery integration economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Orthopedic Dog Bed Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market
Veterinary
ASEAN Poultry Vaccines Market
Veterinary
Global Swine Vaccines Market
Veterinary
North America and Europe Veterinary Telehealth Market
Veterinary
Veterinary Ultrasound Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Veterinary Hospitals Market
Veterinary
Spay and Neuter Market
Veterinary
Canine Separation Anxiety Treatment Market