
 Pet Cremation Market | 2026-2036
Pet Cremation Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Cremation Market Insights
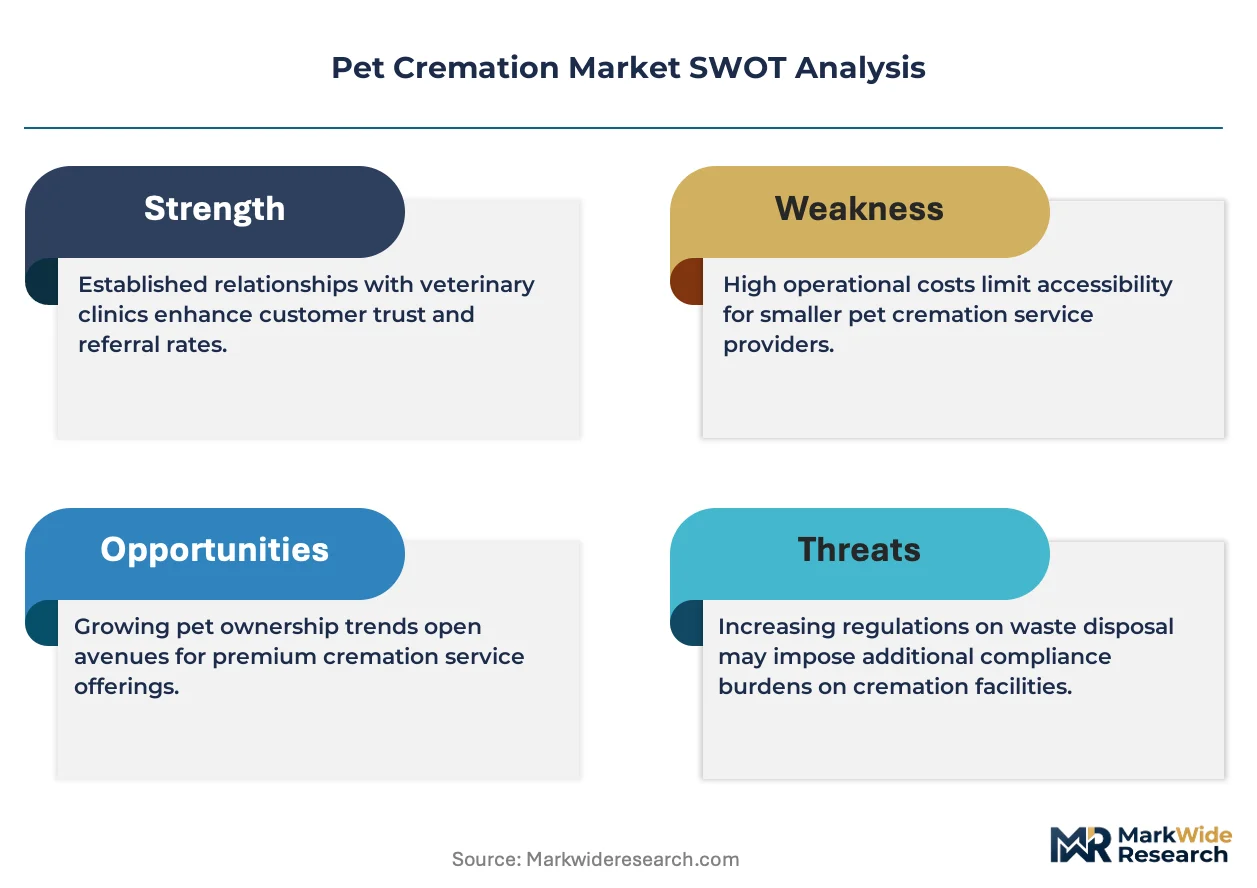
Asset-light franchising is reshaping competitive dynamics in pet cremation, lowering capital barriers for regional entrants. Pet Passages, Inc. leverages a franchise model to extend brand presence without direct facility ownership. Inciner8 Limited anchors its position through manufacturing scale in thermal processing equipment. American Crematory Equipment Company differentiates via specialized product lines for companion animal applications.
Pet cremation encompasses the thermal or alkaline hydrolysis reduction of deceased companion animals to ash and bone fragments, with modern systems operating at temperatures between 760°C and 980°C for complete combustion. The process serves pet owners seeking sanitary, dignified disposition alternatives to burial, while generating memorial products for home retention or scattering. Individual cremation commands premium pricing due to guaranteed single-pet processing and certificate-of-cremation documentation. Aquamation is gaining traction as veterinary channels promote its lower energy profile and absence of airborne emissions. Memorial services and urn customization capture outsized margins compared to standard package offerings.
EPA regulations under the Clean Air Act govern crematory emissions, while OSHA standards address operator exposure to heat and particulate matter in facility environments. State-level veterinary board rules in California, Texas, and Florida govern the handling and transport of deceased pets, creating compliance complexity for multi-state operators. Stakeholders must monitor evolving alkaline hydrolysis permitting frameworks as municipalities reassess wastewater discharge classifications for this emerging technology.
Market Dynamics
EPA emissions standards under the Clean Air Act are forcing crematory operators toward cleaner combustion architectures, while pet humanization trends elevate service expectations beyond basic disposition.
Growth Catalysts
- Alkaline hydrolysis permitting expansion:Municipal wastewater discharge reclassifications in select US jurisdictions are enabling aquamation facility licensing. This technology attracts environmentally conscious pet owners seeking lower-carbon alternatives.
- Veterinary clinic service integration:Primary care and specialty veterinary practices are embedding memorial counseling and cremation coordination into end-of-life care protocols. This channel consolidation streamlines owner decision-making at emotional inflection points.
- California-Texas-Florida demand concentration:Elevated pet ownership rates combined with above-median household disposable income in these three states support premium service uptake and memorial product attachment.
Market Restraints
- Natural gas price volatility:Thermal cremation systems depend on consistent fuel input costs. Price spikes compress operator margins and deter facility expansion in marginal markets.
- Equipment supplier concentration:Crematory incinerator manufacturing clusters among a limited set of specialized foundries. Supply disruptions propagate quickly through installation backlogs.
- Substitute competition from home burial:Rural and suburban property owners with sufficient land area retain legal access to private pet interment. This zero-cost alternative caps pricing power in exurban service territories.
Strategic Opportunities
- Direct-to-consumer digital scheduling platforms:Mobile-enabled cremation arrangement tools bypass veterinary channel intermediaries. This disintermediation captures margin and accelerates booking velocity.
- Biometric memorialization products:DNA preservation and paw-print casting services attach to cremation packages. These high-margin add-ons transform transactional disposition into commemorative experiences.
- OSHA compliance automation:Workforce safety management software tailored to crematory heat and particulate exposure reduces insurance premiums. Early adopters gain cost structure advantages in multi-facility operations.
Industry Challenges
- Certified crematory operator scarcity:Technical training programs for thermal system operation and emissions monitoring remain limited. Talent gaps constrain facility throughput and expansion timelines.
- Legacy facility retrofit complexity:Older crematories face structural constraints when installing secondary combustion chambers and filtration stacks. Physical plant limitations delay EPA compliance upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Cremation Market |
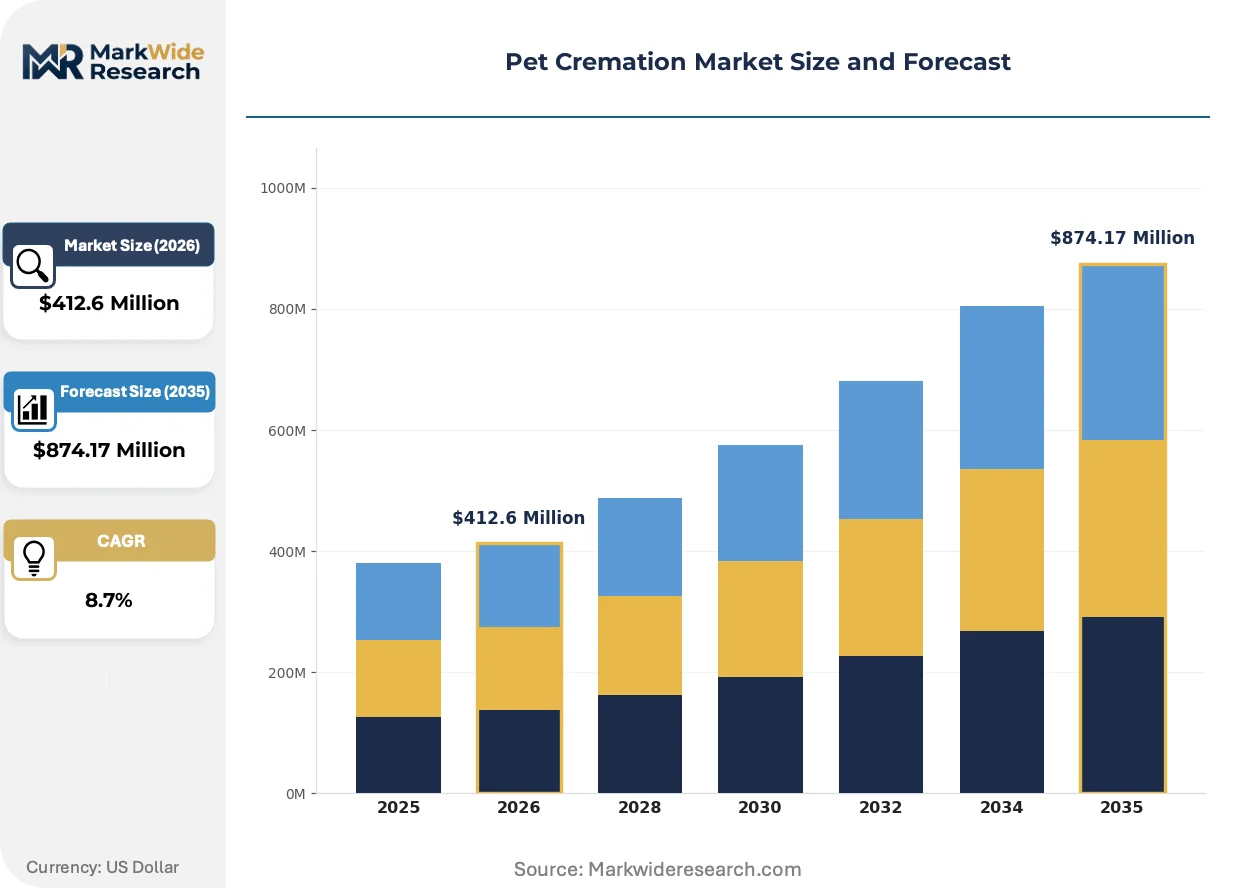
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cremation Type: Individual, Communal, Wholesale, Aquamation Service Offering: Standard Package, Premium Package, Memorial Services, Urn Customization Distribution Channel: Veterinary Clinics, Pet Hospitals, Online Platforms, Funeral Homes Pet Type: Dogs, Cats, Rabbits, Other Small Animals |
| Companies Covered | Addfield Environmental Systems Ltd, B&L Cremation Systems, Inc., Pet Passages, Inc., Inciner8 Limited, Firelake Manufacturing, Gateway Services Inc., American Crematory Equipment Company, Facultatieve Technologies LIMITED, ACS, INC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Cremation Market Trends and Innovations
Equipment manufacturers and service operators are converging on hybrid thermal processing architectures that reconcile emissions compliance with operational flexibility. This technical pivot redefines competitive capability requirements.
Flameless cremation technology is hybridizing conventional incineration with alkaline hydrolysis process controls. Veterinary specialty hospitals in metropolitan markets are piloting these systems to offer dual-modality service menus. The technology is hybridizing capital deployment decisions by enabling single-facility operators to serve both traditional and environmentally motivated customer segments without redundant infrastructure.
EPA Region-specific enforcement variance under the Clean Air Act is creating compliance complexity for multi-state operators. Stringent interpretation in coastal jurisdictions accelerates equipment replacement cycles. California-based service chains are responding by consolidating processing capacity in Nevada and Arizona border zones where regulatory interpretation permits extended legacy system operation.
Pet owners are fragmenting across memorial service intensity preferences, with demand bifurcating between unattended cremation and full-ceremony disposition. Veterinary clinics are unbundling aftercare coordination from medical services, referring owners to specialized pet funeral directors. This channel specialization is most visible in Florida's retirement corridor, where aging pet populations and established funeral service infrastructure overlap.
Pet Cremation Market Segmentation
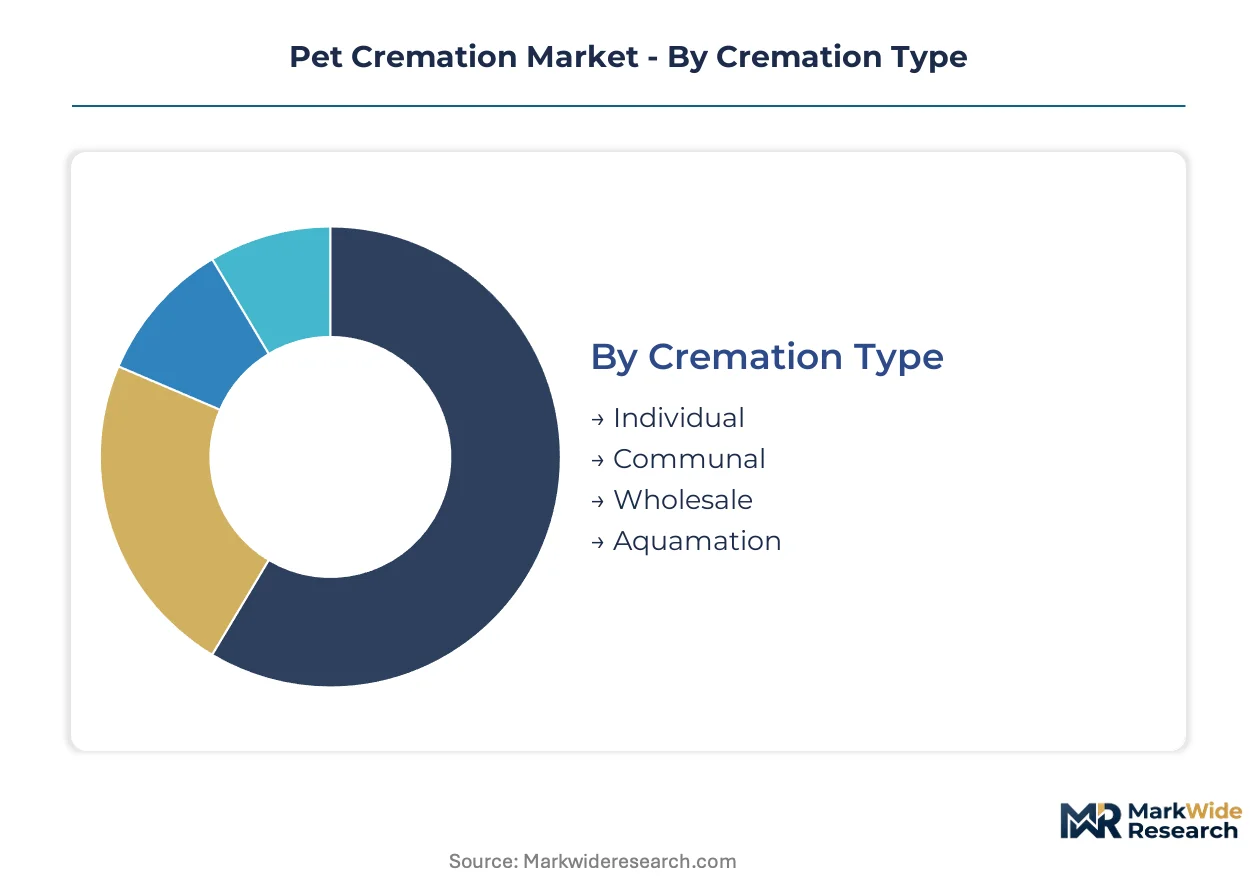
Segmentation in pet cremation reveals how service intensity, channel access, and species-specific handling requirements create distinct operational economics. Operators configure capacity and staffing around these divides to optimize throughput and margin capture.
Cremation Type:
Cycle times vary dramatically across modalities, with thermal systems completing combustion in 45-90 minutes while aquamation requires 18-20 hours per cycle.
- Individual:Single-pet processing with guaranteed ash return and certificate documentation commands the highest price point. California, Texas, and Florida veterinary clinics drive concentration as pet humanization elevates demand for verified identity preservation.
- Aquamation:Alkaline hydrolysis uses water-based dissolution at elevated temperature and pressure, eliminating stack emissions entirely. Municipal wastewater permitting in select US jurisdictions is unlocking facility licensing for this lower-carbon alternative.
- Communal:Multiple pets processed simultaneously with no ash return offers entry-level pricing for cost-conscious owners.
- Wholesale:Bulk disposition contracts with municipal shelters and veterinary teaching hospitals generate volume throughput with minimal service overhead.
Individual cremation anchors the volume base while aquamation gains share at the steepest rate.
Service Offering:
Margin structures diverge sharply between commoditized disposition and experiential add-ons that transform transactional encounters into memorial events.
- Memorial Services:Ceremony coordination, viewing rooms, and grief counseling extend facility utilization beyond processing equipment. Florida's retirement corridor shows particular concentration where aging pet populations overlap with established funeral service infrastructure.
- Urn Customization:Material selection, engraving, and biometric integration (paw prints, DNA preservation) capture outsized margins. These attach to cremation packages through veterinary clinic referral networks at emotional decision points.
- Premium Package:Bundled individual cremation with priority scheduling and upgraded urn selection targets above-median household income segments.
- Standard Package:Basic individual or communal cremation with minimal memorial product attachment serves price-sensitive demand.
Standard packages generate the highest absolute transaction volume while memorial services expand most quickly as veterinary channels unbundle aftercare coordination.
Distribution Channel:
Channel control determines customer acquisition economics and pricing power, with intermediaries capturing 30-50% of end-consumer spend in traditional veterinary referral models.
- Veterinary Clinics:Primary care and specialty practices embed cremation coordination into end-of-life protocols, streamlining owner decisions at emotional inflection points. California-based chains are consolidating processing capacity in Nevada and Arizona border zones to manage EPA compliance costs.
- Online Platforms:Direct-to-consumer scheduling tools bypass veterinary intermediaries, capturing margin and accelerating booking velocity through mobile-enabled arrangement interfaces.
- Pet Hospitals:Emergency and specialty facilities handle complex euthanasia cases requiring immediate disposition coordination.
- Funeral Homes:Human funeral service operators in metropolitan markets are adding pet-specific capacity to leverage existing crematory infrastructure.
Veterinary clinics dominate transaction origination while online platforms climb the fastest as digital-native pet owners seek disintermediated purchasing paths.
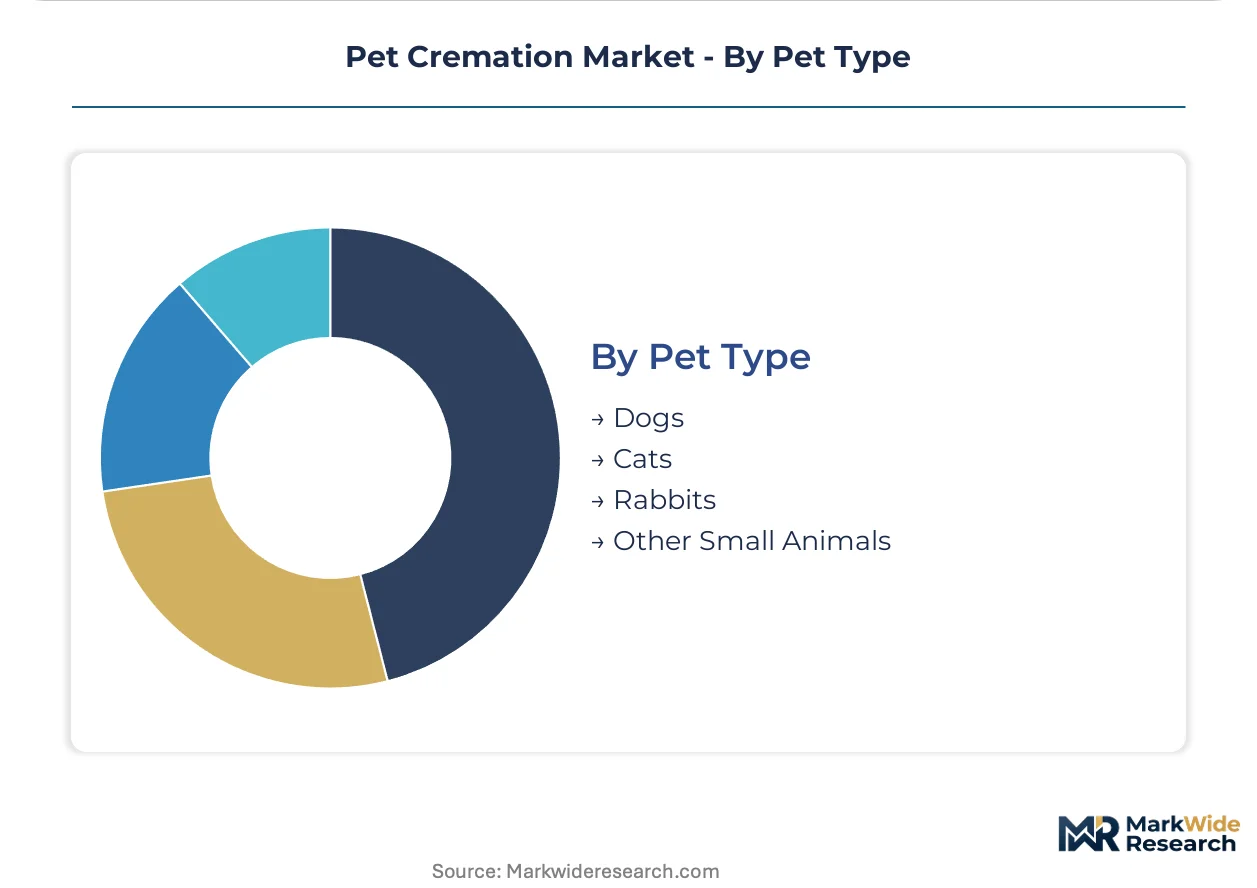
Pet Type:
Species-specific handling protocols and equipment sizing requirements create operational segmentation that influences facility capital allocation and staffing specialization.
- Dogs:Large-breed cremation requires higher-capacity retort systems and extended cycle times. Demand concentrates in suburban and exurban service territories where property ownership enables home burial alternatives that cap pricing power.
- Cats:Smaller retort compatibility and higher urban ownership rates align with clinic-based service models in dense metropolitan markets.
- Rabbits:Exotic pet handling protocols and specialized veterinary referral networks serve niche demand with premium service expectations.
- Other Small Animals:Birds, reptiles, and pocket pets require modified processing approaches and limited dedicated capacity.
Dogs anchor the volume base while rabbits and exotic species expand most quickly as veterinary specialty channels deepen service penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions enforcement under the Clean Air Act is accelerating equipment replacement cycles across key markets, while municipal wastewater discharge reclassifications in select jurisdictions are unlocking alkaline hydrolysis facility licensing.
United States
California, Texas, and Florida concentrate demand through elevated pet ownership rates and above-median household disposable income. EPA Region-specific enforcement variance creates compliance complexity, with stringent coastal interpretations accelerating replacement cycles. California-based service chains are consolidating processing capacity in Nevada and Arizona border zones where regulatory interpretation permits extended legacy system operation.
United Kingdom
Urban pet density in Greater London and Southeast England supports premium service uptake for individual cremation with guaranteed ash return. The Environment Agency regulates crematory emissions through environmental permitting regulations, with municipal authorities governing wastewater discharge for aquamation facilities. Crematorium operators in Manchester and Birmingham are piloting hybrid thermal processing architectures to reconcile emissions compliance with operational flexibility.
Germany
High pet ownership rates in North Rhine-Westphalia and Bavaria combine with stringent environmental standards to drive demand for cleaner combustion technologies. The Federal Immission Control Act (BImSchG) governs crematory emissions, while state-level veterinary boards regulate deceased animal handling protocols. Equipment manufacturers in Baden-Württemberg are developing secondary combustion chamber designs for export markets.
Japan
Metropolitan Tokyo and Osaka anchor demand through high-density pet ownership and limited burial space availability. METI energy efficiency standards influence equipment procurement decisions for thermal processing systems. Crematory operators in Kansai are integrating memorial service coordination with veterinary specialty hospitals to capture margin from experiential add-ons.
Australia
New South Wales and Victoria lead national demand through urban pet ownership concentration and established veterinary service infrastructure. State-level environmental protection agencies regulate crematory stack emissions, with local councils assessing aquamation wastewater discharge applications. Sydney-based operators are expanding direct-to-consumer digital scheduling platforms to bypass traditional veterinary channel intermediaries.
Pet Cremation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented market tiers. Veterinary clinic networks and online platforms capture customer acquisition economics, while equipment manufacturers anchor supply-side concentration. Three archetypes dominate: asset-light franchise operators, integrated service providers, and specialized equipment fabricators. Competitive moves center on geographic consolidation through multi-facility rollups and technology licensing agreements for alkaline hydrolysis systems.
Among franchise-model operators, Pet Passages, Inc. exemplifies asset-light expansion without direct facility ownership. Equipment specialists include UK-based Inciner8 Limited and American Crematory Equipment Company, which occupy positions in thermal processing manufacturing. These three companies represent distinct strategic archetypes—franchise scaling, manufacturing scale, and specialized product lines—illustrating how competitive positioning fragments across service and supply functions.
| Leading Market Players |
|---|
| Addfield Environmental Systems Ltd |
| B&L Cremation Systems, Inc. |
| Pet Passages, Inc. |
| Inciner8 Limited |
| Firelake Manufacturing |
| Gateway Services Inc. |
| American Crematory Equipment Company |
| Facultatieve Technologies LIMITED |
| ACS, INC |
| Others |
Pricing and Supply Chain Analysis
EPA emissions enforcement variance across US jurisdictions functions as a regulatory chokepoint that compresses margin spreads between premium individual cremation and economy communal tiers while forcing supply chain reconfiguration toward Nevada and Arizona border zones.
Pricing Analysis
Certification level (EPA-compliant secondary combustion vs. legacy single-chamber systems) creates the primary spread between thermal cremation tiers. Three-tier pricing structure across premium individual, standard partitioned, and economy communal levels dominates service menus. Pricing pressure stems from natural gas volatility and veterinary channel intermediaries capturing 30-50% of end-consumer spend. Rural property owners with home burial access exhibit highest price sensitivity, while urban pet owners in California-Texas-Florida corridors show lowest.
Supply Chain Analysis
Export-control restrictions on high-temperature refractory materials and emissions monitoring systems limit equipment flows from UK and German manufacturers to US operators. Crematory incinerator fabrication concentrates in the United Kingdom, Germany, and select US foundries. Retort chambers, filtration stacks, and control systems feed from specialized metalworking and instrumentation suppliers. Single-source vulnerability runs through limited certified operator training programs. Distribution runs through veterinary clinic networks, direct-to-consumer platforms, and funeral home partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical talent scarcity for certified crematory operation and emissions compliance represents the binding constraint on facility throughput expansion, creating acquisition premiums for operators with trained workforces.
For Market Incumbents: Insulate margin position by consolidating processing capacity in Nevada and Arizona border zones where EPA interpretation permits extended legacy system operation. Acquire alkaline hydrolysis permitting expertise ahead of municipal wastewater reclassifications. Channel control through veterinary clinic exclusivity agreements remains the critical defensive lever against direct-to-consumer platform disintermediation.
For New Entrants and Emerging Players: Establish a beachhead in aquamation services within California coastal jurisdictions where emissions enforcement is most stringent. Target Florida's retirement corridor for memorial service unbundling opportunities. Deploy mobile-enabled scheduling platforms to bypass veterinary intermediaries and capture margin directly from digital-native pet owners.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors multi-facility rollups with regulatory arbitrage capabilities. Long-term viability hinges on hybrid thermal processing architectures serving both traditional and environmentally motivated segments. Watch municipal wastewater discharge reclassifications as the signal indicating inflection toward alkaline hydrolysis infrastructure investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Alkaline Hydrolysis Permitting | Municipal wastewater reclassifications in California unlock licensing for lower-emission aquamation facilities. |
| Multi-Facility Rollup | Consolidation across Nevada-Arizona border zones captures EPA compliance arbitrage opportunities. |
| Direct-to-Consumer Platform Launch | Mobile scheduling tools bypass veterinary intermediaries and accelerate booking velocity. |
| Certified Operator Training Program | Technical workforce development alleviates throughput constraints and reduces insurance premiums. |
| Hybrid Thermal System Investment | Dual-modality equipment serves both traditional cremation and aquamation demand without redundant infrastructure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement records, state veterinary board filings, and municipal wastewater discharge permits. Primary interviews engaged crematory operators, veterinary practice managers, equipment manufacturers, and regulatory compliance officers. Secondary sources included Clean Air Act implementation guidance, OSHA technical manuals, and trade association capacity surveys. Bottom-up facility capacity estimates triangulated against top-down pet ownership and mortality rate projections.
Forecast inputs incorporate cremation type segmentation, service offering tiers, distribution channel mix, and pet species handling requirements across the analysis window. Modeled dimensions span individual-communal-aquamation modalities, veterinary clinic versus direct-to-consumer origination, and dog-cat-exotic species splits. CAGRs derived from elasticity-adjusted demand curves and capacity expansion timelines. Natural gas price trajectories and EPA enforcement intensity assumptions shaped scenario boundaries.
Sensitivities concentrate around municipal permitting velocity for alkaline hydrolysis and veterinary channel consolidation patterns. Forecasts reflect documented assumptions regarding pet humanization trends and emissions compliance costs. Material shifts in EPA regional enforcement interpretation or natural gas supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Canine Atopic Dermatitis Market
Veterinary
Pet Light Therapy Devices Market
Veterinary
Spay and Neuter Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Canine Flu Therapeutics Market
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
Pet DNA Testing Market
Veterinary
Veterinary in Vitro Fertilization Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Veterinary Disinfectants Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Europe Dog Dewormers Market