
 South Korea Computed Tomography Market | 2026-2036
South Korea Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Computed Tomography Market Analytics
Modular service bundling is repositioning how South Korean hospitals procure CT systems, shifting capital expenditure into managed equipment service contracts with predictable lifecycle costs. GE Healthcare leverages its installed base in Seoul metropolitan hospitals to sustain long-term service revenue streams. Siemens Healthineers anchors its competitive stance through R&D intensity in photon-counting detector architectures. Samsung Electronics differentiates by controlling domestic manufacturing scale and channel proximity to regional health networks.
Computed tomography denotes X-ray-based cross-sectional imaging systems utilizing rotating gantry assemblies, detector arrays, and reconstruction algorithms to generate volumetric anatomical datasets with spatial resolution typically below one millimeter. These systems serve primary diagnostic functions across oncology staging, trauma assessment, and interventional planning in South Korean clinical settings. Multi-slice CT dominates current procurement volumes due to established reimbursement codes and workflow integration, while spectral CT captures expanding margin pools as hospitals seek material decomposition capabilities for lesion characterization. Digital CT technology leads replacement demand, though dual energy CT installations are accelerating in academic institutes pursuing research-tier imaging protocols.
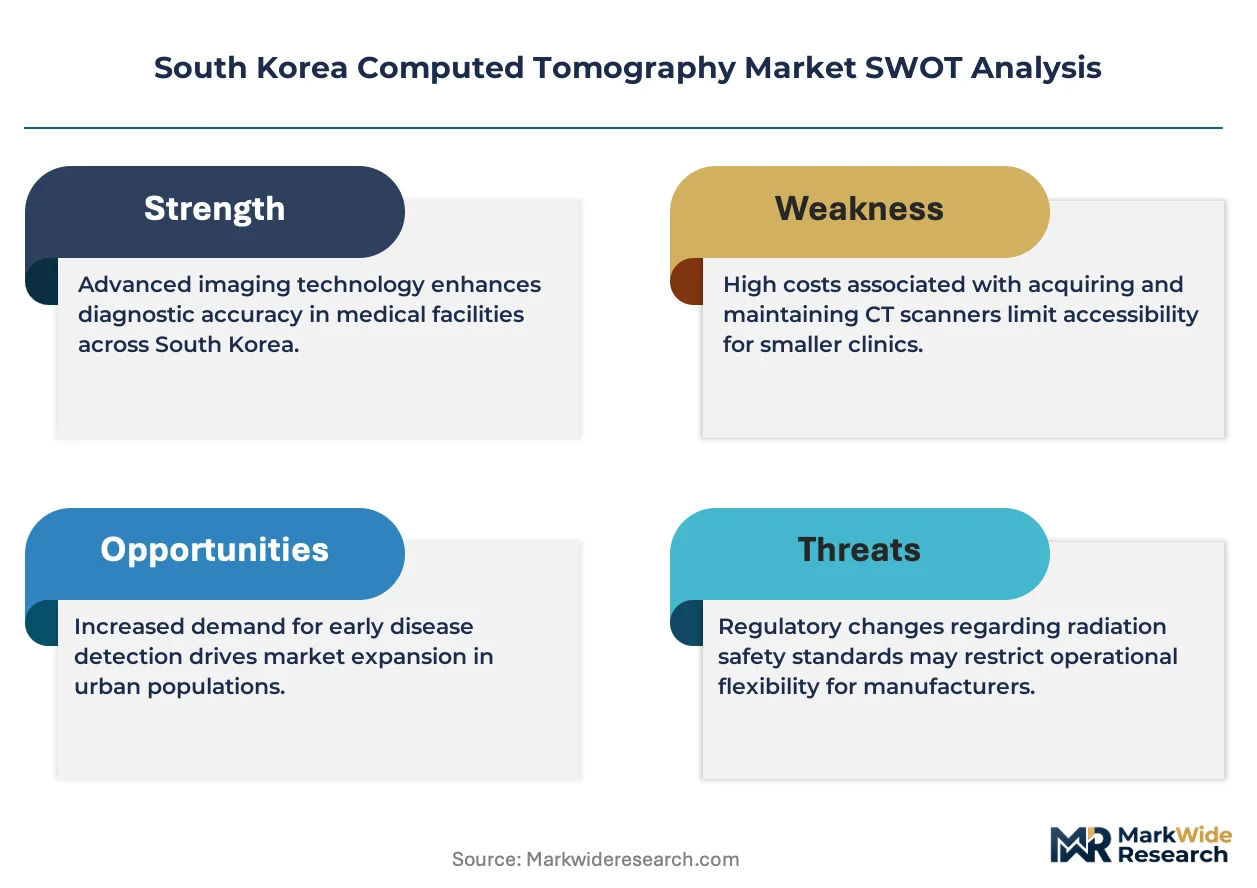
MFSD regulates device safety and clinical performance standards under the Medical Device Act, while MFDS alignment with MDR-equivalent quality management systems shapes import requirements for multinational suppliers. KFDA historical frameworks and MFDS current good manufacturing practice inspections determine market access timelines and post-market surveillance obligations for domestic and foreign manufacturers. Stakeholders must monitor reimbursement rate negotiations between the Health Insurance Review and Assessment Service and hospital consortia, as these settlements directly influence upgrade cycles and technology adoption thresholds.
Market Dynamics
Managed equipment service contracts are compressing capital expenditure cycles across South Korean hospital networks, converting scanner procurement from asset purchases into multi-year operational agreements with bundled maintenance and upgrade provisions.
Growth Catalysts
- Spectral CT material decomposition:Tertiary oncology centers in Seoul are prioritizing lesion characterization capabilities for staging protocols, pulling replacement demand from conventional multi-slice systems.
- MFDS reimbursement alignment:The Health Insurance Review and Assessment Service is expanding diagnostic imaging coverage codes, shortening payback periods for high-end scanner investments.
- Regional health network consolidation:Hospital clusters in Busan and Daegu are centralizing procurement authority, creating volume aggregation effects that favor fleet standardization.
Market Restraints
- Detector array supply concentration:Domestic manufacturers rely on imported photon-counting sensor substrates, exposing procurement timelines to concentrated Asian semiconductor foundry capacity.
- Capital intensity barriers:Mid-tier regional hospitals face compressed operating margins that delay scanner replacement beyond technical obsolescence thresholds.
- Technical interoperability limits:Legacy PACS infrastructure in established Seoul metropolitan facilities creates data format friction when integrating next-generation reconstruction algorithms.
Strategic Opportunities
- Underserved provincial networks:Secondary hospitals in Gwangju and Daejeon operate aging single-slice systems, creating replacement white space for mid-range digital CT platforms.
- MFDS streamlined approval pathways:The regulator's equivalence recognition for MDR-certified devices accelerates market entry timelines for European manufacturers.
- AI reconstruction convergence:Deep learning-based noise reduction is converging with low-dose protocols, enabling new clinical applications in pediatric and repeat-scan populations.
Industry Challenges
- Specialized service engineering scarcity:Photon-counting detector calibration requires field technicians with semiconductor physics training, creating recruitment bottlenecks for equipment vendors.
- Legacy system integration complexity:Hospital IT departments must bridge DICOM format gaps between 15-year-old archive systems and modern iterative reconstruction workstations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Computed Tomography Market |
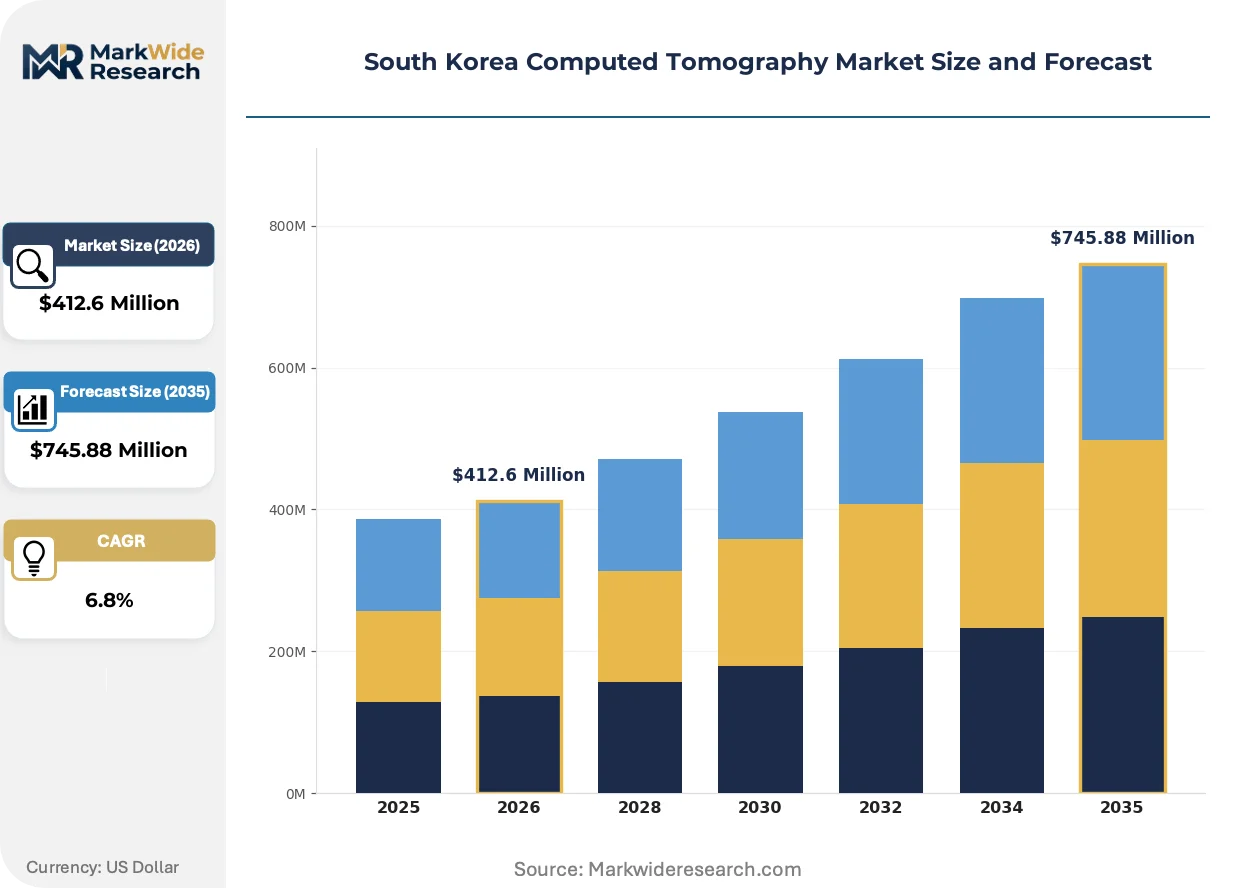
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Slice CT, Cone Beam CT, Positron Emission Tomography, Standalone CT End User: Hospitals, Radiology Centers, Diagnostic Imaging Centers, Academic Institutes Technology: Analog CT, Digital CT, Dual Energy CT, Spectral CT Application: Oncology, Neurology, Cardiology, Orthopedics |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, United Imaging Healthcare, Carestream Health, Samsung Electronics, Planmeca Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Computed Tomography Market Evolving Landscape
Photon-counting detector architectures are redefining spatial resolution benchmarks, while reimbursement reforms and procurement centralization are compressing decision timelines across South Korean provider networks.
Deep learning reconstruction algorithms are converging with low-dose acquisition protocols to maintain diagnostic confidence at reduced radiation exposure. Tertiary oncology departments in Seoul are adopting these systems for repeat-scan monitoring workflows. The technology is converging with spectral imaging to enable material-specific quantification that conventional energy-integrating detectors cannot achieve.
MFDS alignment with EU MDR equivalence standards is compressing approval timelines for imported CT systems. The regulator now accepts notified body certifications from European authorities, eliminating redundant clinical trial requirements. Multinational suppliers are responding by prioritizing Seoul metropolitan hospital networks for initial photon-counting installations.
Centralized procurement consortia are displacing individual hospital purchasing authority across South Korean regional health networks. Hospital clusters in Busan and Daegu now negotiate fleet-wide service agreements rather than single-unit acquisitions. This consolidation is most visible in tertiary centers seeking standardized maintenance protocols across multiple facilities.
South Korea Computed Tomography Market Segmentation
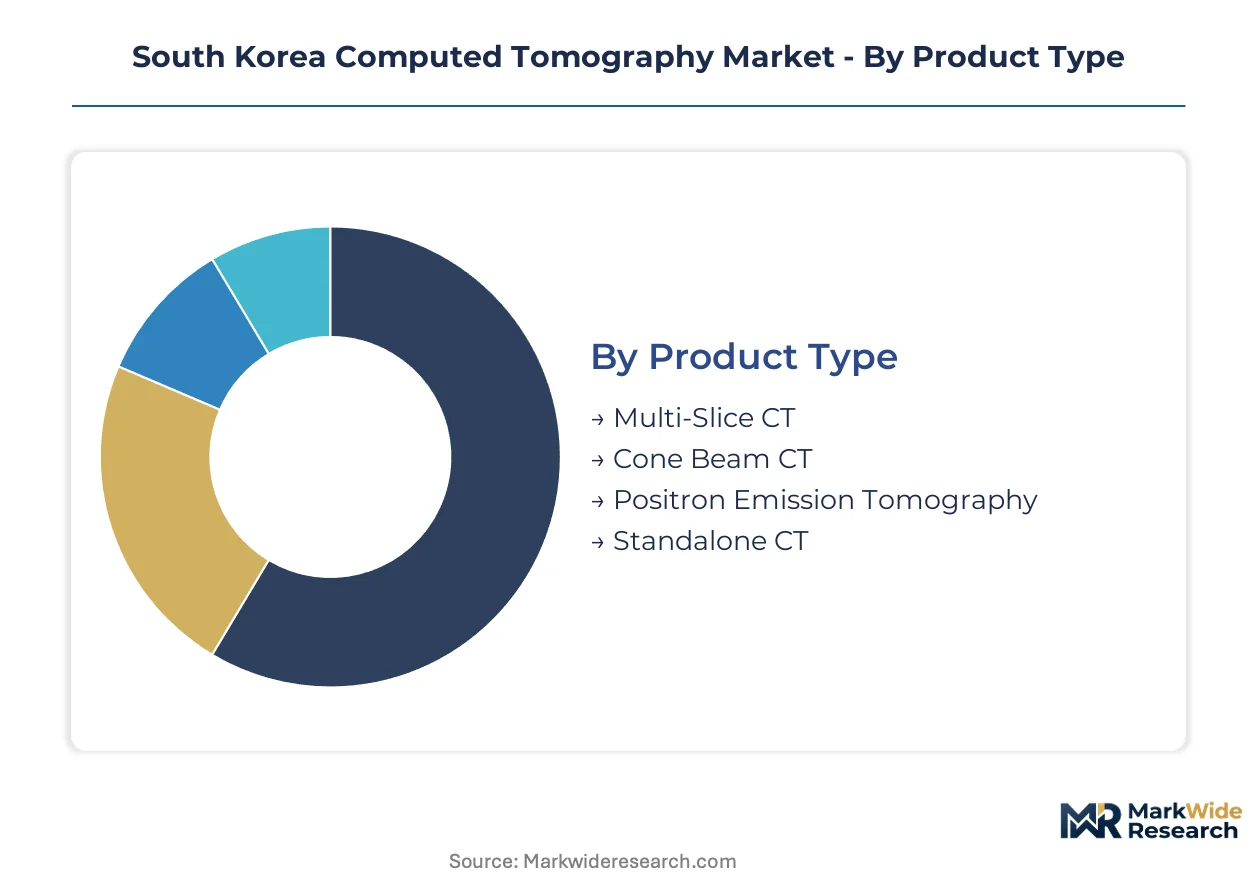
CT system procurement in South Korea stratifies sharply across technical specifications, clinical workflows, and institutional scale. Understanding these divides reveals where replacement cycles concentrate and which technology tiers command premium positioning.
Product Type:
Scanner architectures differentiate by slice count, gantry geometry, and detector configuration, with each format serving distinct throughput and resolution requirements.
- Multi-Slice CT:Systems with 64 to 320 detector rows dominate installed base volumes across Seoul metropolitan hospitals. Tertiary centers in Gangnam and Jongno districts prioritize these platforms for high-throughput emergency and oncology workflows where rapid volumetric acquisition compresses examination times.
- Spectral CT:Dual-layer and rapid kV-switching architectures enable material decomposition for lesion characterization. Demand concentrates in Samsung Medical Center and Asan Medical Center staging protocols, where iodine quantification drives reimbursement-advantaged diagnostic pathways.
- Cone Beam CT:Compact C-arm mounted systems serve interventional suites and dental-maxillofacial applications with sub-millimeter isotropic resolution.
- Positron Emission Tomography:Hybrid PET-CT configurations integrate metabolic and anatomical imaging for radiation therapy planning in proton therapy centers.
- Standalone CT:Single-slice and quad-slice legacy systems persist in secondary hospitals across Gwangju and Daejeon where capital constraints delay fleet modernization.
Mature deployment sits with Multi-Slice CT across established Seoul networks. Newer deployment is concentrated in Spectral CT at academic institutes pursuing research-tier imaging protocols.
End User:
Institutional purchasing authority determines contract structure, with consolidated networks extracting fleet-scale pricing unavailable to independent operators.
- Hospitals:Tertiary medical centers in Seoul and Busan anchor procurement volumes through multi-year managed equipment service agreements. These institutions integrate spectral CT into oncology pathways where material decomposition capabilities justify premium capital allocation.
- Academic Institutes:Seoul National University Hospital and Yonsei University Health System drive photon-counting detector adoption for clinical research protocols. Their purchasing decisions prioritize reconstruction algorithm flexibility and dose reduction credentials over throughput metrics.
- Radiology Centers:Independent imaging facilities in Daegu and Incheon concentrate on high-margin outpatient procedures with rapid turnaround requirements.
- Diagnostic Imaging Centers:Specialized clinics in Suwon and Ulsan focus on occupational health screening and pre-operative assessment markets.
Procurement consolidation favors hospital networks with centralized capital planning. Academic institutes capture earliest access to detector innovations through research partnerships.
Technology:
Signal processing architectures separate legacy energy-integrating platforms from emerging photon-counting systems that redefine dose-efficiency tradeoffs.
- Digital CT:Solid-state detector arrays with direct digital readout dominate replacement demand across South Korean provider networks. These systems eliminate analog-to-digital conversion stages, reducing electronic noise floors that constrain low-dose pediatric protocols.
- Spectral CT:Energy-resolved detection enables material-specific quantification beyond conventional Hounsfield unit measurements. MFDS reimbursement alignment for iodine mapping procedures accelerates adoption in hepatocellular carcinoma surveillance programs.
- Dual Energy CT:Rapid kV-switching and split-filter approaches provide intermediate spectral capability at lower capital cost than full detector-layer architectures.
- Analog CT:Gas-filled detector systems with scintillator-photodiode chains persist only in dated installations approaching technical obsolescence.
Digital CT platforms command widest installed base penetration. Spectral CT installations are climbing the fastest among technology tiers as MFDS expands diagnostic imaging coverage codes.
Application:
Clinical use cases determine scanner specification requirements, with oncology workflows driving highest resolution and spectral capability demands.
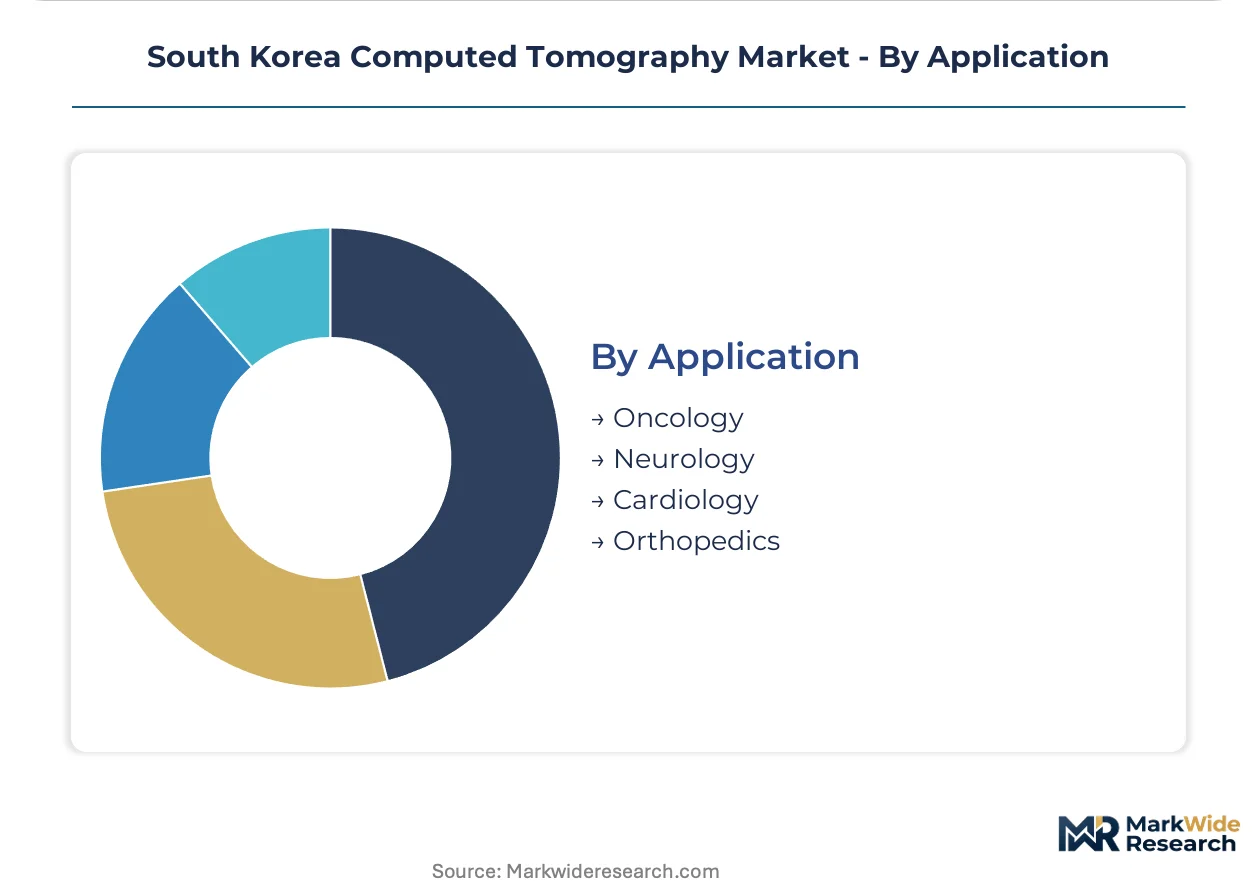
- Oncology:Tumor staging and treatment response monitoring require sub-millimeter spatial resolution and iodine quantification accuracy. Seoul National University Cancer Hospital and National Cancer Center Goyang anchor demand for spectral CT in hepatocellular carcinoma and lung nodule characterization protocols.
- Neurology:Perfusion imaging and stroke protocol automation prioritize rapid scan initiation and motion-robust reconstruction. Regional stroke centers in Busan and Daegu invest in wide-coverage detector arrays that capture entire cerebral vasculature in single rotations.
- Cardiology:Coronary CT angiography demands high temporal resolution and prospective ECG triggering to freeze cardiac motion.
- Orthopedics:Metal artifact reduction algorithms enable post-arthroplasty assessment in high-volume joint replacement centers.
Oncology applications command premium system specifications across metropolitan Seoul. Neurology protocols are expanding most quickly in regional networks establishing comprehensive stroke care certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's CT scanner production concentrates among domestic electronics conglomerates, while consumption spreads across metropolitan hospital networks and provincial secondary facilities seeking fleet modernization.
Seoul Capital Area
Tertiary oncology centers in Gangnam and Jongno districts drive spectral CT procurement for hepatocellular carcinoma staging protocols. MFDS reimbursement alignment for iodine mapping procedures accelerates replacement cycles at Samsung Medical Center and Asan Medical Center. Hospital networks in the metropolitan core negotiate fleet-wide managed equipment service agreements with bundled maintenance provisions.
Busan-Ulsan
Regional health network consolidation centralizes procurement authority across university-affiliated hospitals and municipal medical centers. The Health Insurance Review and Assessment Service expands diagnostic imaging coverage codes, shortening payback periods for high-end installations. Stroke care certification programs in Busan National University Hospital pull demand for wide-coverage detector arrays.
Daegu-Gyeongbuk
Mid-tier regional hospitals operate aging single-slice systems approaching technical obsolescence thresholds. Capital intensity barriers compress operating margins and delay scanner replacement beyond equipment lifecycle norms. Kyungpook National University Hospital anchors photon-counting adoption for research-tier imaging protocols in the regional cluster.
Daejeon-Sejong
Government-funded research institutes prioritize detector innovation partnerships with domestic manufacturers. The Korea Institute of Science and Technology hosts clinical validation trials for next-generation reconstruction algorithms. Sejong administrative city health facilities standardize on digital CT platforms with AI-integrated noise reduction for pediatric protocols.
Gwangju-Honam
Secondary hospitals in the southwestern corridor represent replacement white space for mid-range digital CT platforms. Chonnam National University Hospital anchors regional demand while surrounding provincial facilities rely on outdated analog detector systems. MFDS streamlined approval pathways for MDR-certified devices accelerate market entry timelines for European suppliers targeting this underserved segment.
South Korea Computed Tomography Market Competitive Landscape
The competitive structure tilts toward multinational imaging conglomerates with established service infrastructure. Three to four global manufacturers command premium positioning through photon-counting R&D pipelines, while domestic electronics groups leverage manufacturing scale and channel proximity. Strategic archetypes separate technology leaders pursuing detector innovation, portfolio diversifiers integrating AI reconstruction, and scale players optimizing production economics. Dominant competitive moves include managed equipment service contract expansion and research partnership anchoring at academic medical centers.
Among multinational imaging specialists, GE Healthcare, Siemens Healthineers, and Philips anchor the premium-tier segment through long-term service relationships with Seoul metropolitan hospital networks. Samsung Electronics occupies a distinct position as the domestic scale player controlling manufacturing proximity to regional health networks. These three exemplify the market's structural division between global technology leadership and local supply chain integration.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| United Imaging Healthcare |
| Carestream Health |
| Samsung Electronics |
| Planmeca Group |
| Others |
Value Network & Pricing Analysis
Detector-tier bifurcation between photon-counting premium systems and energy-integrating mid-range platforms manifests in divergent procurement economics and semiconductor supply dependencies across South Korean hospital networks. Premium-tier spectral CT commands managed equipment service contracts with bundled upgrade provisions, while standard digital CT procurement concentrates in regional networks with compressed capital cycles and shorter depreciation horizons.
Pricing Analysis
Cost-down pressure on mid-range digital CT accelerates because provincial hospital networks in Gwangju and Daejeon aggregate purchasing volume to extract fleet-scale discounts from domestic manufacturers. Three-tier pricing structure across premium photon-counting, standard multi-slice, and economy refurbished systems separates academic medical centers from secondary hospitals and independent imaging clinics. MFDS reimbursement rate negotiations between the Health Insurance Review and Assessment Service and hospital consortia intensify price sensitivity among regional networks with thinner operating margins, while Seoul metropolitan tertiary centers prioritize spectral capability over acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with Asian semiconductor foundries fabricating photon-counting sensor substrates for next-generation detector arrays. Domestic CT manufacturing draws from Japan, Germany, and the United States for precision gantry bearings, high-voltage X-ray tubes, and reconstruction algorithm chipsets. Tariff exposure on imported semiconductor components creates procurement timeline risk for Korean manufacturers scaling photon-counting production. Distribution runs through manufacturer-direct service engineers and authorized regional distributors serving hospital networks with localized maintenance response requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea CT market functions as a vertical-integration race where control over photon-counting detector fabrication and AI reconstruction software development determines margin capture and service contract renewals.
For Market Incumbents: To counter emerging Chinese manufacturers with cost-optimized digital CT platforms, GE Healthcare and Siemens Healthineers should anchor photon-counting R&D partnerships at Seoul National University Hospital and Asan Medical Center, locking in early-adopter reference sites that shape procurement standards for regional network consolidation. For New Entrants and Emerging Players: Cloud-based AI reconstruction licensing offers a service-layer entry point without capital-intensive hardware manufacturing, enabling software specialists to penetrate mid-tier provincial hospitals in Daejeon and Gwangju through subscription pricing that bypasses upfront scanner procurement cycles. For Investors and Strategic Acquirers: Re-rating potential sits with domestic semiconductor component suppliers given MFDS alignment with EU MDR equivalence standards accelerating import substitution timelines for photon-counting sensor substrates. Acquisition targets should demonstrate captive detector fabrication capability or exclusive service contracts with Busan-Ulsan hospital networks. The signal to watch is Health Insurance Review and Assessment Service reimbursement code expansion for spectral CT procedures, which would inflect replacement demand curves across the installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Partnership | Secures technology roadmap alignment with Samsung Medical Center and Asan Medical Center research protocols. |
| Managed Equipment Service Expansion | Converts capital expenditure into recurring revenue streams across Busan regional health network consolidation. |
| MFDS MDR Equivalence Pathway Investment | Accelerates market entry timelines for European manufacturers targeting Gwangju-Honam replacement white space. |
| AI Reconstruction Software Licensing | Enables service-layer penetration of mid-tier hospitals without hardware manufacturing investment. |
| Semiconductor Substrate Backward Integration | Reduces dependency on concentrated Asian foundry capacity for photon-counting detector production. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and MFDS regulatory affairs leads. Primary fieldwork validated scanner procurement timelines, reimbursement code utilization patterns, and service contract structures across Seoul metropolitan and provincial hospital networks. Secondary sources included MFDS device approval databases, Health Insurance Review and Assessment Service reimbursement schedules, Korean Hospital Association fleet surveys, and import-export statistics from Korea Customs Service. Bottom-up installation base modeling triangulated against top-down market value estimates derived from manufacturer revenue disclosures.
Data-stream reconciliation across shipment volumes, installed base age profiles, and replacement cycle assumptions generated consistent trajectory outputs across the projection horizon. Segmentation dimensions modeled included slice-count architecture, detector technology tier, end-user institutional scale, clinical application intensity, and regional health network consolidation status. CAGRs emerged from curve-fitting replacement demand waves against MFDS regulatory milestone timelines and reimbursement expansion schedules. Industry-specific inputs incorporated photon-counting detector yield rates and semiconductor foundry capacity allocation patterns affecting procurement lead times.
The model holds under stable MFDS reimbursement alignment and continued regional hospital network consolidation; deviation in semiconductor supply chain disruptions or tariff regime shifts would shift replacement cycle timing. Forecasts reflect documented assumptions regarding technology adoption curves and procurement authority centralization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
Brazil Mammography Market
Medical Imaging
Global Micro-Ultrasound Systems Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
New Born Eye Imaging Systems Market