
 Saudi Arabia Diagnostic Imaging Market | 2026-2036
Saudi Arabia Diagnostic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Diagnostic Imaging Market Analytics
Saudi Arabia is reconfiguring its diagnostic imaging supply base through localized service infrastructure and direct procurement partnerships. GE HealthCare leverages its established Riyadh training center and spare parts hub to sustain long-term maintenance contracts across Ministry of Health facilities. Siemens Healthineers anchors its position through hybrid imaging installations at flagship tertiary sites, while United Imaging Healthcare competes aggressively on total cost-of-ownership terms for mid-tier hospital deployments.
Diagnostic imaging encompasses non-invasive visualization technologies that generate anatomical and functional data through ionizing radiation, magnetic fields, or acoustic waves, with spatial resolution thresholds ranging from sub-millimeter CT slices to whole-body MRI sequences; these systems enable clinicians to detect pathology, guide interventions, and monitor treatment response across disease states. X-ray and ultrasound equipment occupy the highest volume tier due to broad primary-care deployment, whereas CT and MRI segments command concentrated margin pools at centralized referral hospitals. Digital imaging technology leads conversion momentum as analog systems face accelerated replacement cycles, and mobile imaging units are gaining traction for rural outreach under health equity mandates.
The Saudi Food and Drug Authority enforces medical device registration and post-market surveillance protocols that shape vendor qualification timelines and product standard compliance costs. SFDA alignment with GCC harmonization initiatives and MOHAP technical guidelines streamlines cross-border approvals but raises documentation burdens for non-GCC manufacturers. Stakeholders must monitor procurement decentralization toward private hospital operators and the emerging preference for outcome-based service contracts over capital purchase models.
Market Dynamics
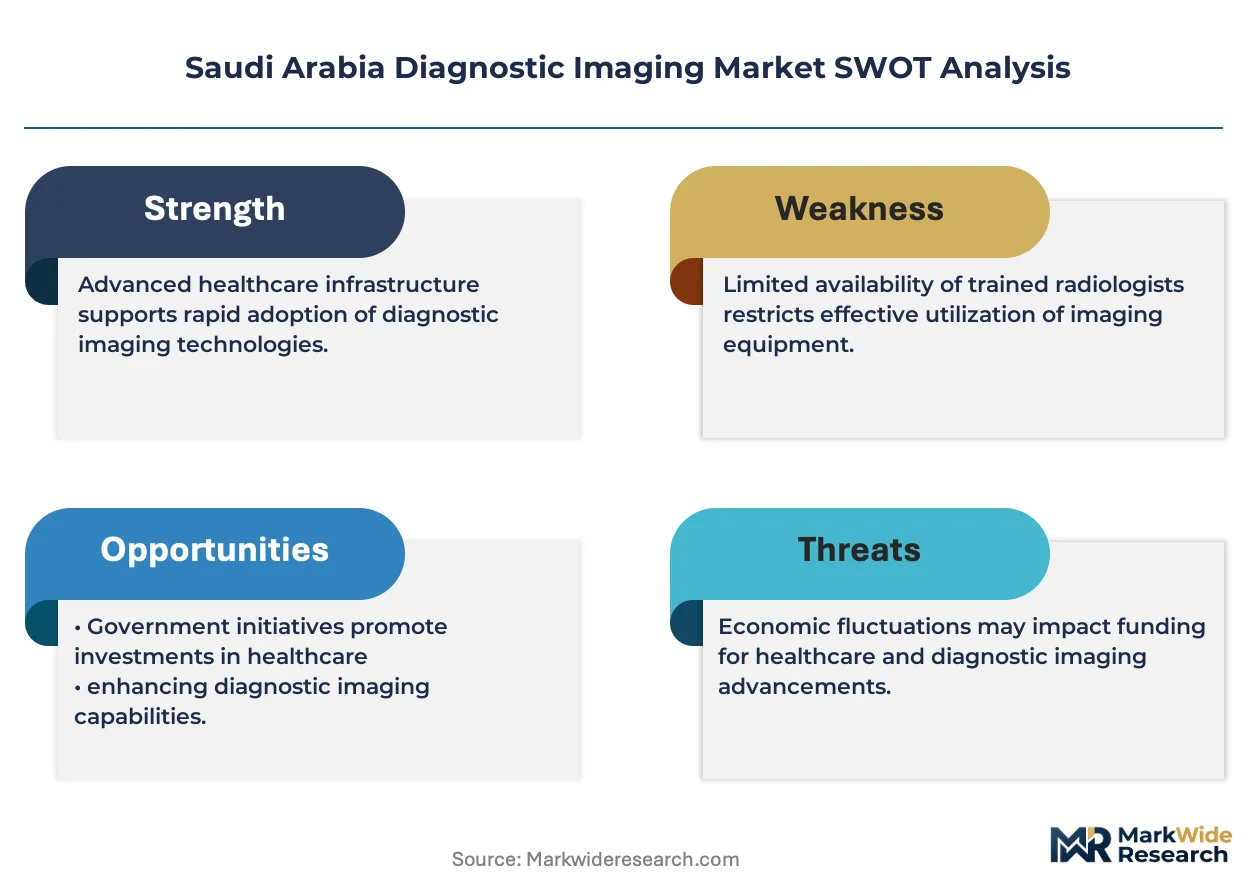
Saudi Arabia's diagnostic imaging sector is undergoing a fundamental reconfiguration as Vision 2030 healthcare privatization mandates redirect procurement authority from centralized Ministry of Health budgets toward independent hospital operators and public-private partnership entities.
Growth Catalysts
- Vision 2030 Healthcare Privatization:The policy framework is decentralizing capital allocation across Riyadh and Jeddah hospital networks, accelerating replacement cycles for aging analog radiography systems.
- SFDA Registration Harmonization:Alignment with GCC technical guidelines is compressing vendor qualification timelines for manufacturers holding existing MOHAP approvals in neighboring UAE markets.
- Tertiary Hospital Expansion:King Faisal Specialist Hospital networks in the Central Province are consolidating high-end imaging procurement into centralized radiology departments with dedicated MRI and CT suites.
Market Restraints
- Import Dependency for Critical Components:Superconducting magnet assemblies and gradient coil systems concentrate supply among German and US specialty manufacturers, exposing procurement timelines to transatlantic shipping volatility.
- SFDA Documentation Burden:Post-market surveillance protocols require extensive clinical evidence packages for digital imaging platforms, extending registration cycles for non-GCC manufacturers unfamiliar with Arabic labeling requirements.
- Technician Training Bottlenecks:Magnetic resonance spectroscopy and dual-energy CT applications demand specialized radiologist expertise that remains scarce outside King Saud University-affiliated teaching hospitals.
Strategic Opportunities
- Mobile Imaging Units for Rural Outreach:Health equity mandates under Vision 2030 are creating tender opportunities for truck-mounted MRI and CT systems serving Asir and Northern Borders provinces.
- Artificial Intelligence Integration:Computer-aided detection algorithms for mammography and lung nodule screening are converging with PACS infrastructure upgrades at Ministry of Health facilities.
- Service Contract Unbundling:Private hospital operators in Jeddah are separating equipment procurement from maintenance agreements, opening margins for independent technical service providers.
Industry Challenges
- Biomedical Engineer Shortage:Field service capacity for MRI cryogen systems and CT tube replacements remains concentrated among manufacturer-employed specialists, limiting response times for mid-tier hospitals.
- Legacy PACS Integration Complexity:Digital imaging platforms must interface with decade-old archiving infrastructure at regional Ministry of Health facilities, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Diagnostic Imaging Market |
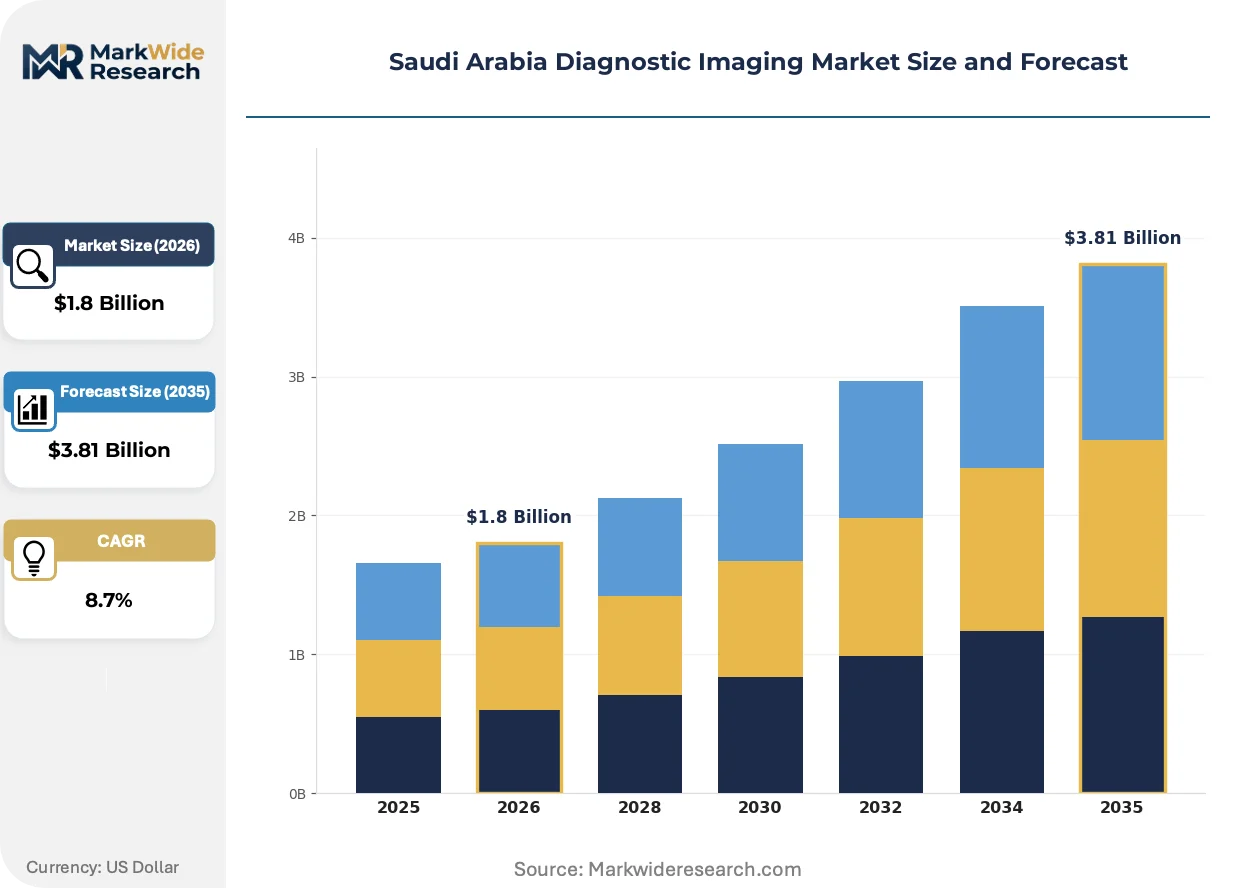
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, MRI, CT Scan, Ultrasound End User: Hospitals, Diagnostic Centers, Clinics, Specialty Centers Technology: Digital Imaging, Analog Imaging, Hybrid Imaging, Mobile Imaging Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | Canon Medical Systems Corporation, United Imaging Healthcare, GE HealthCare, Shimadzu Corp., Hitachi Healthcare, Siemens Healthineers AG, Fujifilm Holdings Corporation, Mindray Bio-Medical Electronics, Koninklijke Philips N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Diagnostic Imaging Market Evolving Landscape
Digital transformation is collapsing traditional equipment lifecycle assumptions as Saudi hospitals accelerate replacement of analog radiography systems with detector-based platforms capable of immediate DICOM integration.
Photostimulable phosphor plates and computed radiography cassettes are approaching functional obsolescence as flat-panel detector technology achieves price parity at equivalent field-of-view specifications. Ministry of Health primary health centers in Riyadh are adopting wireless DR retrofit kits for existing bucky stands, compressing capital expenditure while extending room utilization. This transition is digitizing image acquisition workflows and eliminating chemical processing infrastructure from radiology departments.
SFDA medical device registration requirements are tightening post-market surveillance obligations for imaging software incorporating machine learning algorithms. The regulator now demands algorithm validation datasets representative of Saudi patient demographics, forcing vendors to establish local clinical evidence generation partnerships. AI-enabled mammography and chest X-ray screening tools face extended approval timelines compared to conventional hardware-only submissions.
Public hospital procurement committees are fragmenting into specialty-driven purchasing cells with independent radiology department input on modality selection. This behavioral shift displaces centralized Ministry of Health capital equipment tenders with hospital-specific technical specifications and outcome-based service level agreements. The pattern is most visible at King Faisal Specialist Hospital networks, where radiology chiefs now negotiate directly with vendor clinical applications specialists.
Saudi Arabia Diagnostic Imaging Market Segmentation
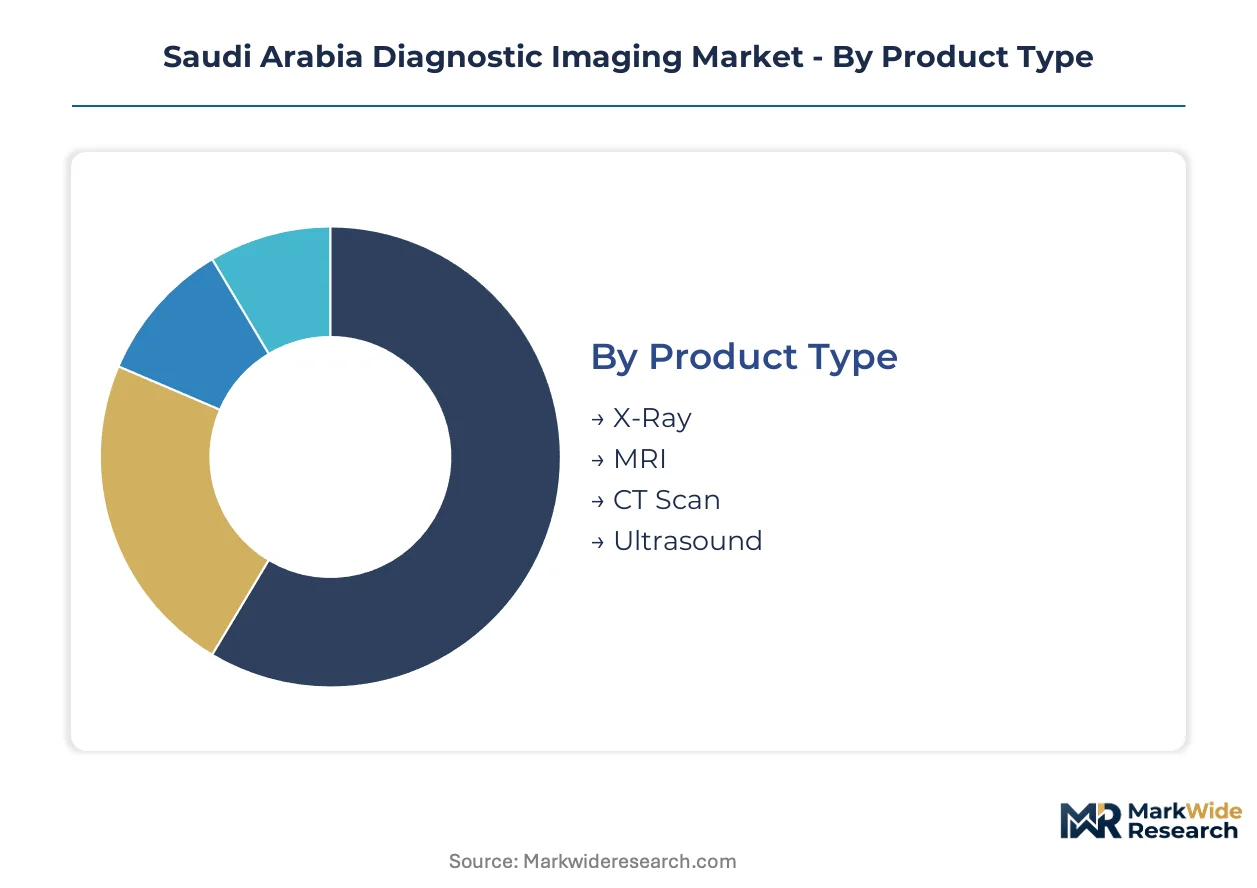
Diagnostic imaging procurement in Saudi Arabia fragments across multiple decision-making axes. Hospital administrators weigh capital intensity against clinical throughput, while SFDA registration pathways favor certain technology platforms over others.
Product Type:
Cost tier separates the installed base from replacement momentum across Saudi hospital networks.
- X-Ray:Flat-panel detector systems now dominate new installations at Ministry of Health primary health centers. Riyadh-based government hospitals are retiring computed radiography cassettes under Vision 2030 facility upgrade mandates.
- MRI:Superconducting 1.5T and 3T systems generate the highest per-procedure revenue at King Faisal Specialist Hospital networks. Procurement concentrates in the Central Province where radiologist staffing supports advanced spectroscopy applications.
- CT Scan:Dual-energy configurations address cardiac and perfusion imaging demand at tertiary referral centers.
- Ultrasound:Cart-based and portable systems serve obstetrics and point-of-care deployment across Jeddah hospital clusters.
X-Ray commands the established base. The steepest expansion runs through MRI.
End User:
Customer type determines procurement authority and contract structure under healthcare privatization.
- Hospitals:Tertiary complexes in Riyadh and Jeddah consolidate multi-modality purchasing into centralized radiology departments with dedicated capital budgets.
- Diagnostic Centers:Independent operators in Jeddah are separating equipment acquisition from maintenance agreements, creating openings for third-party service providers.
- Clinics:Primary care facilities prioritize wireless DR retrofit kits to digitize existing bucky stands without room reconstruction.
- Specialty Centers:Cardiology and oncology-focused institutions drive demand for hybrid imaging configurations with integrated PET-CT capabilities.
Hospitals anchor current revenue concentration. Diagnostic centers are gaining share fastest as procurement decentralizes.
Technology:
Maturity curves and integration complexity shape adoption timelines across Saudi facilities.
- Digital Imaging:Detector-based platforms with immediate DICOM output are displacing analog workflows. SFDA post-market surveillance protocols now demand algorithm validation for AI-enabled digital systems using Saudi patient demographic data.
- Analog Imaging:Screen-film and computed radiography systems persist in remote Ministry of Health facilities with limited technical service access.
- Hybrid Imaging:PET-CT and PET-MRI installations concentrate at King Faisal Specialist Hospital networks where nuclear medicine infrastructure supports molecular imaging protocols.
- Mobile Imaging:Truck-mounted MRI and CT units serve Asir and Northern Borders provinces under health equity mandates, though maintenance logistics remain challenging outside urban corridors.
Digital imaging holds dominant installed position. Mobile imaging climbs the fastest as rural outreach requirements harden.
Application:
Clinical volume and reimbursement alignment direct modality selection at Saudi hospital purchasing committees.
- Oncology:Staging and treatment monitoring applications drive demand for multi-parametric MRI and PET-CT at tertiary cancer centers.
- Cardiology:Coronary CT angiography and cardiac MRI stress testing require specialized technologist training available mainly at teaching hospital affiliates.
- Neurology:Functional MRI and diffusion tensor imaging support neurosurgical planning at King Saud University-affiliated facilities.
- Orthopedics:Weight-bearing CT and dedicated extremity MRI address sports medicine demand from the kingdom's expanding athletic infrastructure.
Oncology commands priority capital allocation. Orthopedics is expanding most quickly as specialized sports medicine facilities multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Superconducting magnet and gradient coil supply chains concentrate among German and US specialty manufacturers, exposing Saudi procurement timelines to transatlantic shipping volatility while Vision 2030 healthcare privatization redirects capital allocation toward independent hospital operators.
Riyadh
King Faisal Specialist Hospital networks anchor high-end imaging procurement with dedicated MRI and CT suites. SFDA medical device registration protocols shape vendor qualification timelines for centralized radiology departments. Government hospital expansion under Vision 2030 mandates accelerates replacement cycles for aging analog systems across Ministry of Health facilities.
Jeddah
Private hospital operators are separating equipment procurement from maintenance agreements, creating openings for independent technical service providers. Diagnostic centers cluster along the Red Sea coast with concentrated ultrasound and portable X-ray deployment. SFDA post-market surveillance requirements raise documentation burdens for digital imaging platforms seeking rapid market entry.
Eastern Province
Industrial cities around Dammam and Al-Khobar generate demand for occupational health imaging and emergency trauma CT capabilities. The region's petrochemical workforce drives specialized chest X-ray screening programs. Procurement decentralization under healthcare privatization redirects capital budgets toward hospital-specific technical specifications.
Central Province
King Saud University-affiliated teaching hospitals concentrate advanced magnetic resonance spectroscopy and dual-energy CT applications requiring specialized radiologist expertise. Tertiary hospital complexes consolidate multi-modality purchasing into centralized radiology departments. Mobile imaging units face maintenance logistics challenges outside urban corridors despite health equity mandates.
Saudi Arabia Diagnostic Imaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base organizes around three structural tiers: multinational imaging conglomerates with full-modality portfolios, mid-tier challengers competing on total cost-of-ownership, and regional service specialists capturing maintenance contract unbundling. Dominant competitive moves include strategic partnerships with local training infrastructure and outcome-based service contract models displacing capital purchase frameworks.
Within the multinational tier, GE HealthCare, Siemens Healthineers AG, and United Imaging Healthcare occupy positions shaped by localized service capabilities and direct procurement relationships with Ministry of Health facilities. GE HealthCare exemplifies the training-center archetype through established Riyadh infrastructure. Siemens Healthineers represents the hybrid-imaging specialist anchored at flagship tertiary sites. United Imaging Healthcare sits within the cost-optimized challenger archetype targeting mid-tier hospital deployments with aggressive total cost-of-ownership positioning.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| United Imaging Healthcare |
| GE HealthCare |
| Shimadzu Corp. |
| Hitachi Healthcare |
| Siemens Healthineers AG |
| Fujifilm Holdings Corporation |
| Mindray Bio-Medical Electronics |
| Koninklijke Philips N.V. |
| Others |
Value Network & Pricing Analysis
German and US specialty manufacturers control superconducting magnet assemblies and gradient coil systems, anchoring margin capture at the component tier while Saudi hospital procurement committees negotiate system-level contracts. This upstream concentration transfers pricing power downstream to integrated modality vendors who bundle hardware with outcome-based service agreements.
Pricing Analysis
SFDA medical device registration protocols dictate the pricing tier structure across Saudi Arabia's diagnostic imaging market. Three-tier pricing structure across premium, standard, and economy levels separates 3T MRI configurations at King Faisal Specialist Hospital networks from 1.5T mid-tier deployments and refurbished analog replacements at primary health centers. Cost compression in the mid-tier segment is intensifying because United Imaging Healthcare and regional challengers compete aggressively on total cost-of-ownership metrics. Ministry of Health primary health centers exhibit highest price sensitivity due to constrained capital budgets under decentralized procurement, while tertiary hospital radiology departments prioritize clinical throughput over acquisition cost.
Supply Chain Analysis
Superconducting wire feedstock draws from niobium-titanium alloy suppliers concentrated in Germany, Japan, and the United States. Rare earth element sourcing for MRI permanent magnets rests on Chinese separation facilities, while precision-machined gradient coils hinge on specialized windings from Austrian and Swiss component houses. Single-source vulnerability persists for cryogen cooling systems where Linde and Air Liquide dominate liquid helium distribution to Saudi hospital sites. Distribution runs through manufacturer-direct field service organizations rather than independent distributors, limiting price transparency for maintenance contract negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare privatization under Vision 2030 fragments procurement authority across independent hospital operators, creating specialized niches for service providers and mid-tier equipment challengers. This demand-side decentralization rewards targeted positioning over broad portfolio plays.
For Market Incumbents: Insulate maintenance revenue streams by embedding biomedical engineer training programs within Ministry of Health technical colleges, creating captive service capacity that emerging competitors cannot replicate. Deepen spare parts hub operations in Riyadh to compress response times below 24 hours for MRI cryogen failures, defending contract renewal rates against third-party service unbundling.
For New Entrants and Emerging Players: Build out mobile imaging unit deployment capabilities targeting Asir and Northern Borders provinces where health equity mandates create tender opportunities underserved by established vendors. Focus initial market penetration on wireless DR retrofit kits for Ministry of Health primary health centers, leveraging lower capital intensity and faster installation cycles against full-system competitors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional service specialists holding maintenance contracts at mid-tier Jeddah hospitals. Long-term viability centers on outcome-based contract conversion rates and AI-enabled software attachment revenue. Watch SFDA algorithm validation timelines for machine learning mammography tools as the inflection signal for platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Harmonization | Alignment with MOHAP technical guidelines accelerates market entry for UAE-approved manufacturers. |
| Hospital System Partnership | Direct procurement relationships with King Faisal Specialist Hospital networks anchor high-end imaging installations. |
| Software Companion Development | AI-enabled mammography algorithms face extended SFDA validation requiring Saudi demographic datasets. |
| Backward Integration into Service | Independent technical service providers capture margins from maintenance contract unbundling at private Jeddah operators. |
| Geographic Expansion | Truck-mounted MRI and CT units address rural outreach mandates in Asir and Northern Borders provinces. |
Research Methodology
Cross-validation between hospital procurement database analysis and vendor contract documentation anchors the qualitative findings. Primary interviews with radiology department chiefs, biomedical engineering directors, SFDA regulatory affairs specialists, and GPO contracts managers were combined with secondary validation from SFDA medical device registration filings, Ministry of Health capital expenditure disclosures, and GCC harmonization initiative technical guidelines. Bottom-up equipment installation tracking and top-down healthcare budget allocation analysis were triangulated to constrain estimate variance.
Calibration against historical procurement cycles and Vision 2030 facility upgrade schedules shaped the analytical framework across the analysis window. Segmentation dimensions modeled include modality type, hospital tier, technology platform, and application area, with CAGRs derived from weighted average replacement cycle assumptions and privatization-driven procurement acceleration. Forecast inputs incorporated SFDA registration timeline distributions and radiologist staffing constraints at teaching hospital affiliates.
Stress conditions across import tariff volatility, superconducting magnet supply disruptions, and technician training bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about healthcare privatization implementation pace and SFDA regulatory alignment timelines. Cross-checking against Ministry of Health announced facility expansion commitments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
North America Computed Tomography (CT) Market