
 Veterinary Diagnostic Services Market | 2026-2036
Veterinary Diagnostic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Diagnostic Services Market Analytics
Companion animal hospitals is rebalancing toward in-house molecular testing as pet owners expect same-day results for infectious disease screening. IDEXX Laboratories, Inc. dominates the reference laboratory channel with proprietary Catalyst and SNAP platforms. Zoetis Services LLC extends its diagnostics footprint through integrated livestock and companion animal portfolios. Thermo Fisher Scientific, Inc. leverages its Applied Biosystems PCR instrumentation to supply both clinical and research veterinary workflows.
Veterinary diagnostic services encompass laboratory analysis, imaging interpretation, and point-of-care testing performed on biological specimens from animals to detect pathogens, metabolic disorders, or structural abnormalities; core technologies include polymerase chain reaction amplification, enzyme-linked immunoassay detection, and digital radiography with spatial resolution typically exceeding 5 line pairs per millimeter. Laboratory Testing generates the largest revenue share due to recurring reference lab submissions for histopathology and microbiology, while Point-of-Care Testing captures the fastest expansion as cartridge-based chemistry analyzers migrate into general practice settings. Imaging Services maintains stable demand tied to orthopedic and cardiac referrals, with margin pools concentrating in teleradiology interpretation networks.
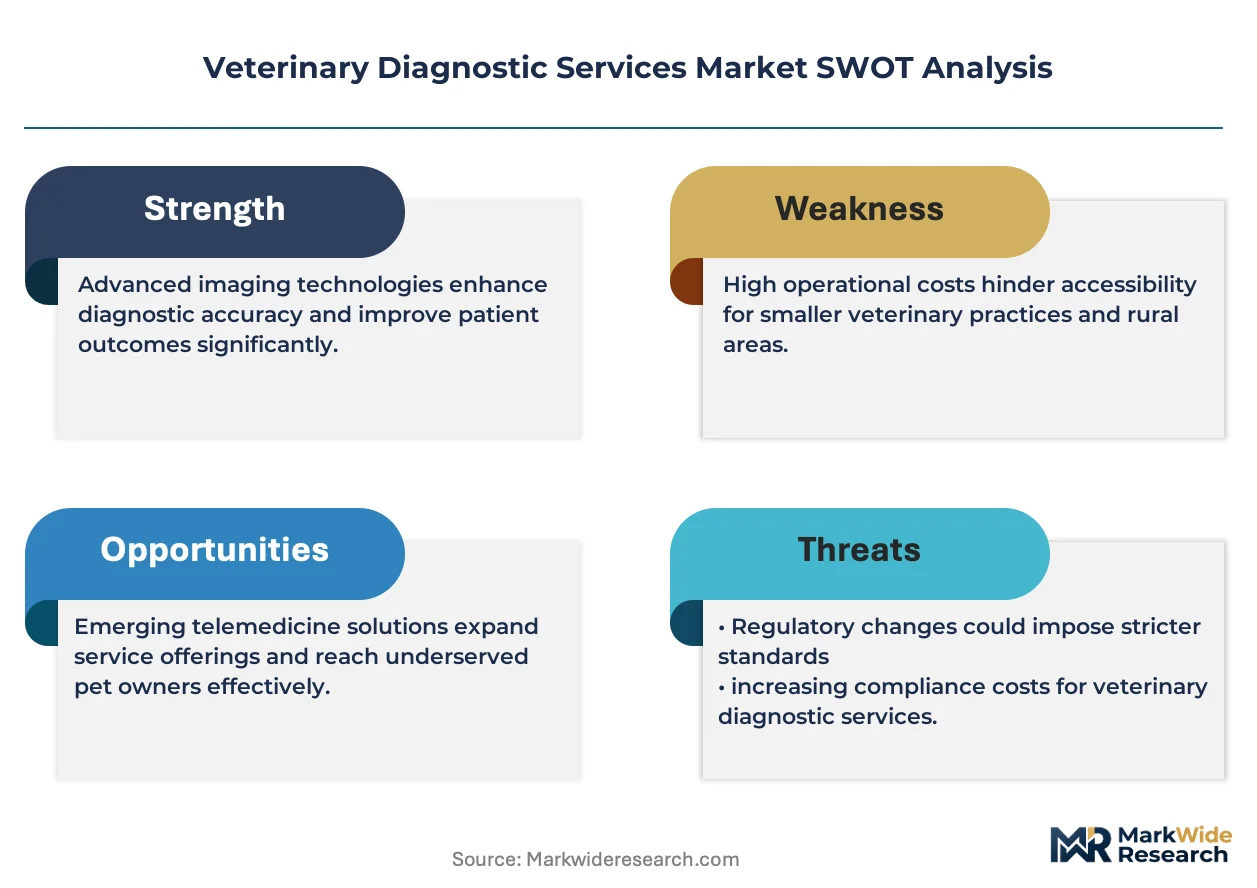
The FDA Center for Veterinary Medicine regulates diagnostic test kit accuracy claims and manufacturing quality systems, while USDA APHIS oversees interstate movement testing for reportable diseases in livestock. ISO 17025 accreditation requirements from laboratory accrediting bodies shape competitive access for independent diagnostic providers seeking contracts with corporate veterinary groups. Stakeholders must monitor how telemedicine reimbursement policy evolution affects the economics of remote diagnostic consultation versus physical specimen submission.
Market Dynamics
The veterinary diagnostic services sector is experiencing a fundamental reconfiguration as point-of-care molecular platforms compress the traditional reference laboratory workflow. Corporate veterinary groups now demand same-day pathogen detection capabilities, forcing equipment suppliers to bundle instrumentation with proprietary reagent subscriptions.
Growth Catalysts
- ISO 17025 Accreditation Mandates:Corporate veterinary groups now require third-party laboratory certification for contract eligibility, elevating quality standards across independent diagnostic providers.
- Livestock Biosecurity Protocols:USDA APHIS maintains interstate movement testing requirements for reportable diseases, sustaining recurring revenue streams for regional diagnostic laboratories serving cattle and swine operations.
- Cartridge-Based Chemistry Analyzers:General practice clinics are adopting compact immunoassay platforms that deliver quantitative results within fifteen minutes, reducing specimen transport dependency.
Market Restraints
- Reagent Supply Concentration:Polymerase chain reaction master mixes and fluorescent probes concentrate among three specialty chemical suppliers, creating vulnerability to batch contamination events.
- FDA CVM Pre-Market Review Timelines:Diagnostic test kit accuracy claims require extensive validation studies, extending product commercialization cycles by eighteen to thirty-six months.
- Imaging Equipment Depreciation Burden:Digital radiography systems require capital outlays exceeding one hundred fifty thousand dollars per unit, straining independent clinic cash flows.
Strategic Opportunities
- Teleradiology Network Expansion:After-hours imaging interpretation services enable general practitioners to capture specialist referral revenue without maintaining board-certified radiologists on staff.
- Telemedicine Reimbursement Evolution:State veterinary medical boards are revising practice acts to permit remote diagnostic consultation, creating new service delivery channels.
- Multi-Species Assay Development:Zoonotic disease surveillance programs require cross-reactive detection platforms capable of identifying pathogens across companion animals, livestock, and wildlife reservoirs.
Industry Challenges
- Veterinary Clinical Pathologist Shortage:Board-certified specialists in histopathology and clinical chemistry remain scarce, creating diagnostic backlogs at reference laboratories.
- Legacy Practice Management Integration:Point-of-care instruments often lack seamless data exchange with existing electronic medical record systems, requiring manual result entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Diagnostic Services Market |
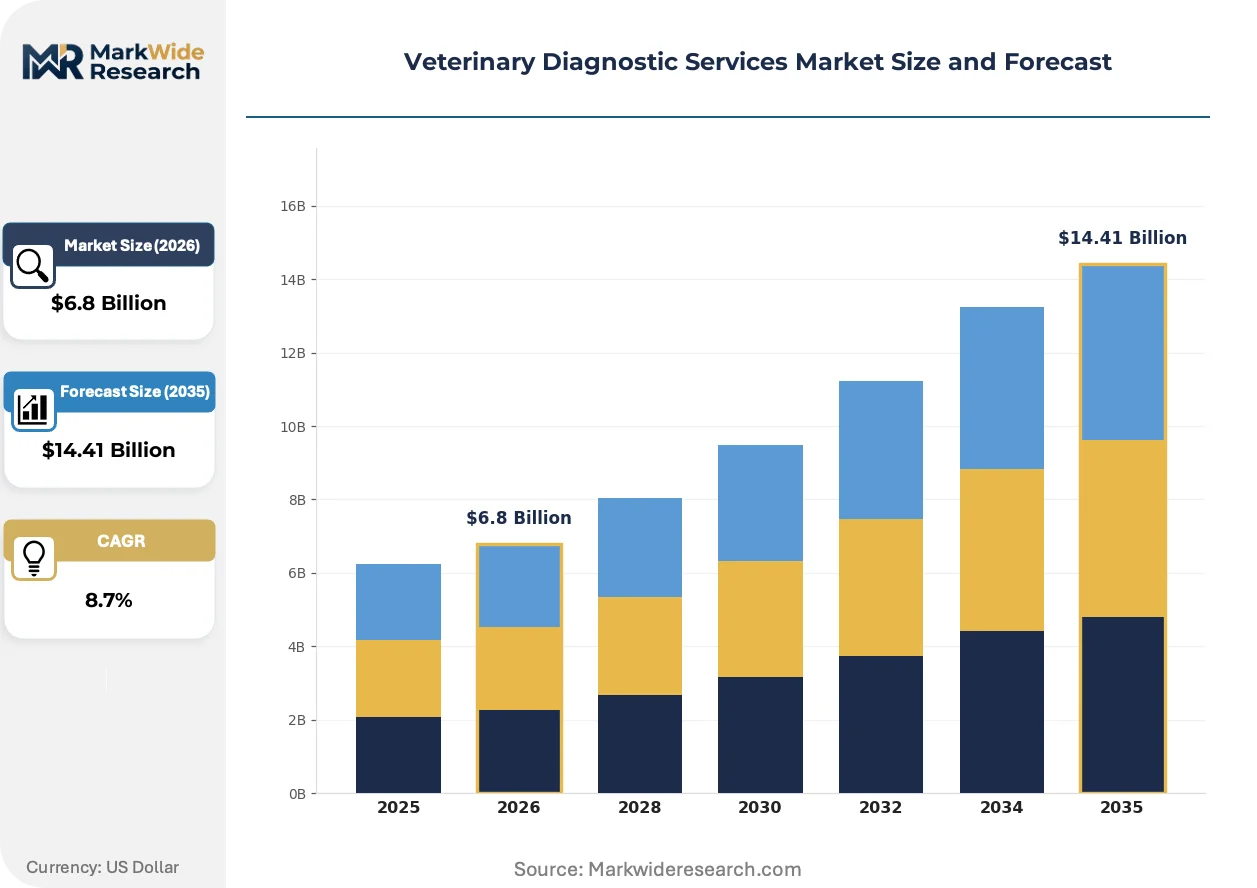
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Laboratory Testing, Imaging Services, Point-of-Care Testing, Consultation Technology: PCR, Immunoassays, Ultrasound, Radiography Animal Type: Companion Animals, Livestock, Exotic Species, Aquatic Animals End User: Veterinary Clinics, Research Institutions, Animal Hospitals, Zoos |
| Companies Covered | IDEXX Laboratories, Inc., Zoetis Services LLC, Antech Diagnostics, Inc., Thermo Fisher Scientific, Inc., Neogen Corporation, NationWide Laboratories, Heska Corporation, bioMérieux, Virbac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Diagnostic Services Market Evolving Landscape
Real-time polymerase chain reaction instrumentation is migrating from centralized reference laboratories into general practice settings. This spatial redistribution of molecular capability is compressing diagnostic turnaround expectations and reshaping equipment procurement patterns across the veterinary channel.
Quantitative polymerase chain reaction platforms with automated nucleic acid extraction are consolidating infectious disease screening workflows previously fragmented across multiple laboratory sites. Companion animal hospitals with annual transaction volumes exceeding five thousand cases are installing these systems to capture reference laboratory margin. The technology is consolidating diagnostic purchasing power within corporate veterinary groups that negotiate enterprise reagent pricing.
The FDA Center for Veterinary Medicine finalized guidance on in vitro diagnostic test kit validation requirements in 2023, tightening evidentiary standards for sensitivity and specificity claims. Manufacturers must now submit multi-site clinical studies demonstrating performance across diverse geographic populations. Small and mid-sized diagnostic developers face compliance cost barriers that favor established players with dedicated regulatory affairs infrastructure.
Pet owner expectations for same-day diagnostic results are compressing the traditional send-out model for infectious disease screening. General practitioners now prioritize in-house immunoassay platforms over reference laboratory relationships, particularly for vector-borne pathogen detection. This behavioral shift concentrates in metropolitan markets where corporate veterinary groups advertise immediate diagnostic capabilities as competitive differentiation.
Veterinary Diagnostic Services Market Segmentation
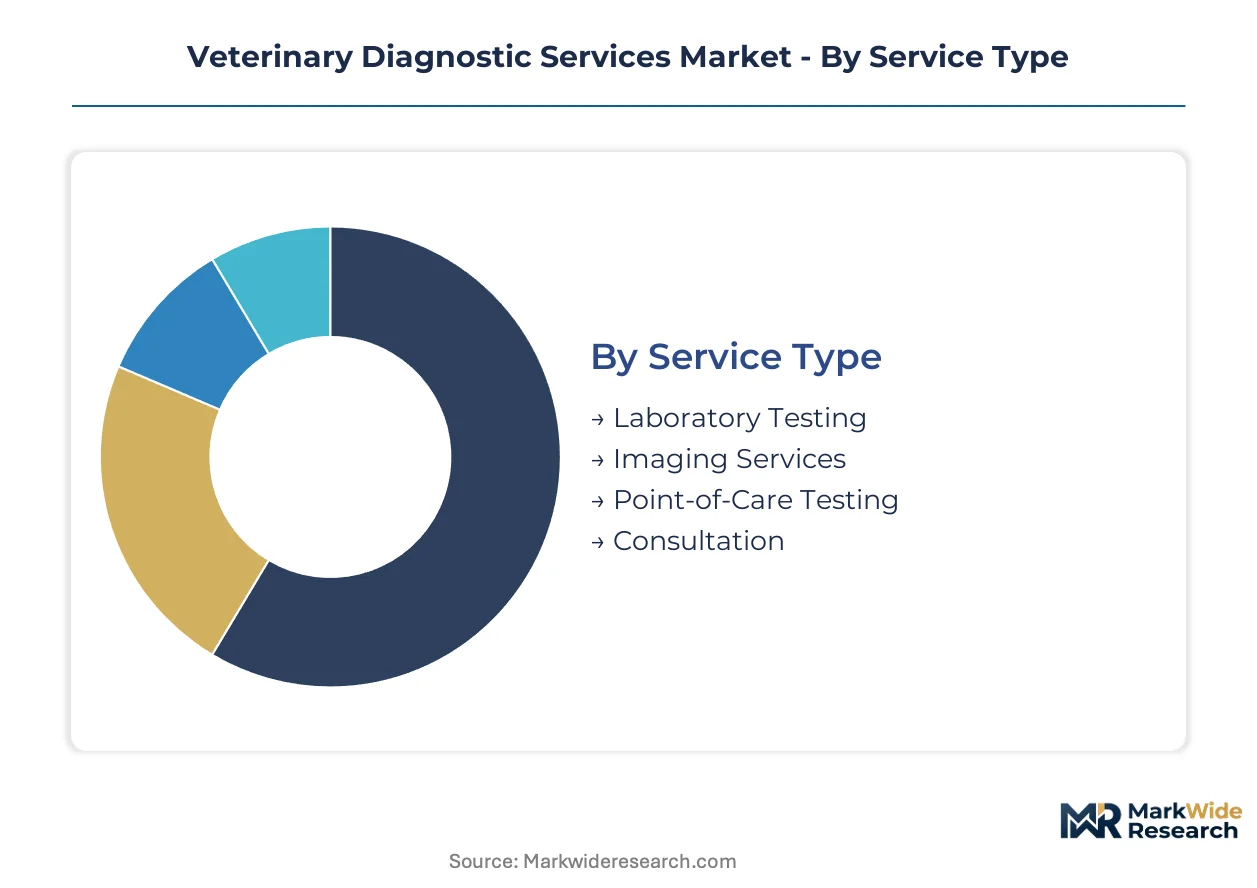
Veterinary diagnostic services fragment across service delivery models, underlying technologies, animal categories, and institutional end-users. Each dimension shapes procurement patterns, margin structures, and regulatory compliance burdens differently across the value chain.
Service Type:
Clinic procurement decisions hinge on balancing capital deployment against turnaround time expectations and referral revenue capture.
- Laboratory Testing:Histopathology, microbiology, and clinical chemistry performed at centralized reference facilities with ISO 17025 accreditation. Corporate veterinary groups in the United States negotiate enterprise pricing for high-volume submissions, consolidating purchasing power across multi-site networks.
- Imaging Services:Digital radiography, computed tomography, and magnetic resonance interpretation delivered through teleradiology networks or in-house specialists. Metropolitan companion animal hospitals in California and Texas deploy these capabilities to retain orthopedic and cardiac referral cases that previously exited to specialty centers.
- Point-of-Care Testing:Cartridge-based chemistry and immunoassay platforms generating quantitative results within fifteen minutes.
- Consultation:Remote specialist interpretation of complex cases via telemedicine platforms.
Laboratory Testing leads on scale; Point-of-Care Testing leads on momentum.
Technology:
Equipment selection tracks the spatial redistribution of diagnostic capability from centralized laboratories into general practice settings.
- PCR:Real-time and quantitative polymerase chain reaction platforms with automated nucleic acid extraction. High-volume companion animal hospitals in Florida and New York install these systems to capture infectious disease screening margin previously retained by reference laboratories.
- Immunoassays:Enzyme-linked immunosorbent assays and lateral flow devices detecting antibodies or antigens in serum, plasma, or whole blood. General practitioners in Illinois and Ohio prioritize these platforms for vector-borne pathogen screening where same-day results drive client retention.
- Ultrasound:Portable and cart-based systems for soft tissue and cardiac imaging.
- Radiography:Digital detector systems replacing computed radiography in clinic upgrades.
PCR commands the steepest expansion trajectory as in-house molecular platforms compress reference laboratory workflows.
Animal Type:
Species-specific regulatory requirements and disease surveillance mandates create divergent service demand profiles.
- Companion Animals:Dogs, cats, and horses receiving preventive care and illness diagnosis in private practice settings. Pet owner expectations for immediate results in Georgia and North Carolina drive adoption of in-house testing platforms.
- Livestock:Cattle, swine, and poultry subject to USDA APHIS interstate movement testing requirements. Regional diagnostic laboratories in Iowa and Nebraska maintain recurring revenue streams from brucellosis and tuberculosis screening protocols.
- Exotic Species:Avian, reptile, and small mammal patients requiring specialized reference laboratory partnerships.
- Aquatic Animals:Farmed fish and ornamental species with limited domestic testing infrastructure.
Livestock anchors volume through regulatory mandate; Companion Animals delivers the fastest share gains.
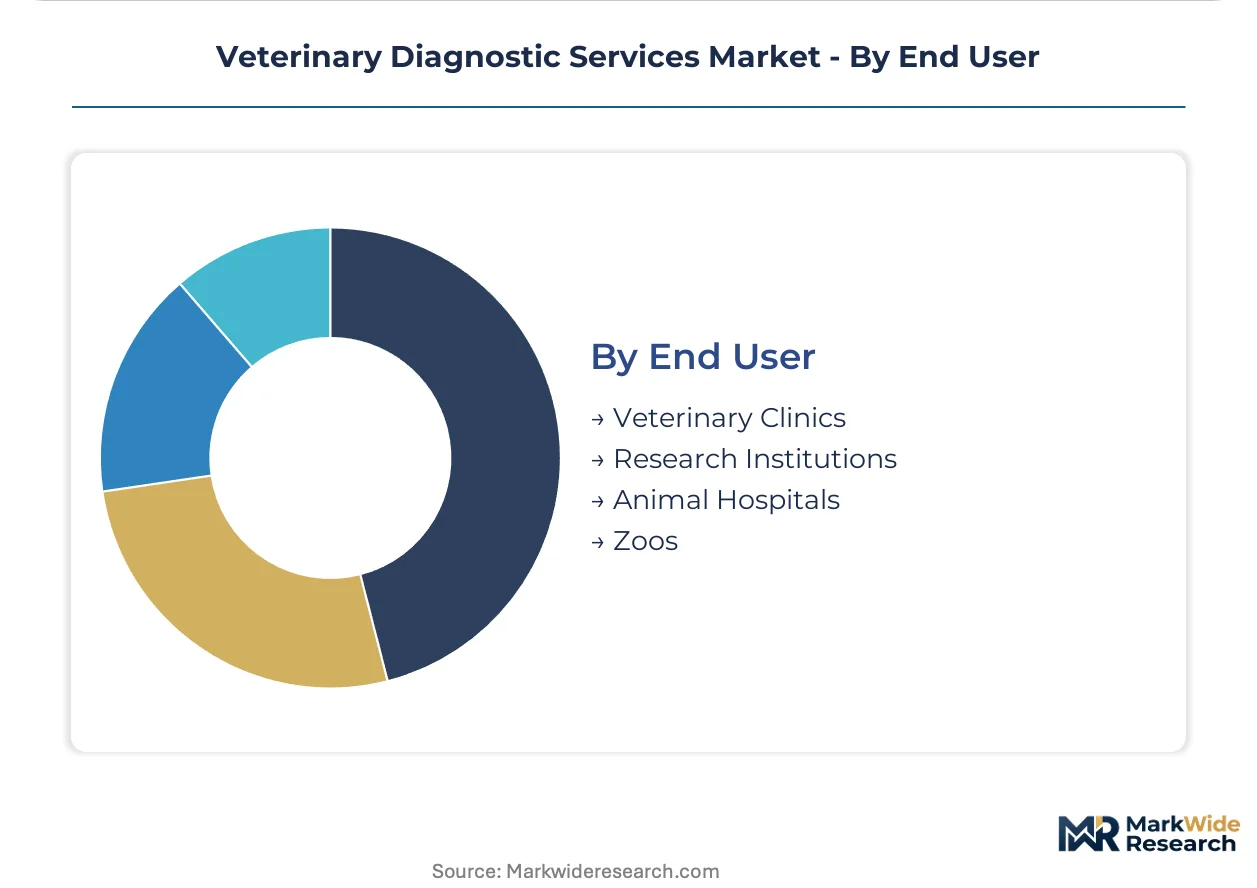
End User:
Facility type determines capital availability, staffing models, and reimbursement pathways for diagnostic services.
- Veterinary Clinics:General practice settings with annual transaction volumes below five thousand cases. Independent operators in Pennsylvania and Michigan face equipment depreciation burdens that favor point-of-care platforms with reagent rental arrangements over outright purchase.
- Research Institutions:Academic and contract research organizations requiring Good Laboratory Practice-compliant pathology support. Universities in Massachusetts and California sustain demand for specialized immunohistochemistry and molecular diagnostics.
- Animal Hospitals:Multi-specialty and emergency facilities with twenty-four-hour staffing.
- Zoos:Conservation institutions requiring exotic species expertise and necropsy services.
Veterinary Clinics dominate transaction volume; Research Institutions concentrate premium-margin specialized testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate veterinary groups in the United States are consolidating diagnostic purchasing power across multi-site clinic networks, establishing the country as the primary demand center for advanced veterinary diagnostic services and point-of-care molecular platforms.
United States
Companion animal hospitals in Florida and New York are installing quantitative PCR systems with automated nucleic acid extraction to capture infectious disease screening margin previously retained by reference laboratories. The FDA Center for Veterinary Medicine finalized guidance on in vitro diagnostic test kit validation requirements in 2023, tightening evidentiary standards for sensitivity and specificity claims. Metropolitan markets in California and Texas deploy digital radiography and teleradiology capabilities to retain orthopedic and cardiac referral cases.
Germany
Livestock diagnostic laboratories in Lower Saxony maintain recurring revenue streams from brucellosis and tuberculosis screening protocols mandated for interstate cattle movement. EFSA and national veterinary authorities enforce stringent quality standards for diagnostic reagents used in food-producing animal testing. The Baden-Württemberg region concentrates specialized pathology services supporting both clinical veterinary practice and pharmaceutical research contracts.
United Kingdom
Corporate veterinary groups in Greater London negotiate enterprise pricing for high-volume reference laboratory submissions, consolidating purchasing power across multi-site companion animal networks. The Veterinary Medicines Directorate aligns with ISO 17025 accreditation requirements shaping competitive access for independent diagnostic providers. The Southeast England corridor anchors teleradiology interpretation networks serving after-hours imaging needs for general practitioners.
Japan
Research institutions in the Kanto region sustain demand for specialized immunohistochemistry and molecular diagnostics compliant with Good Laboratory Practice standards. METI and PMDA oversight shapes the regulatory pathway for novel diagnostic platforms entering the companion animal market. Osaka-based veterinary specialty hospitals are adopting cartridge-based chemistry analyzers to deliver quantitative results within fifteen minutes for vector-borne pathogen screening.
Australia
Regional diagnostic laboratories in New South Wales and Victoria serve cattle and swine operations subject to livestock biosecurity protocols for reportable disease surveillance. The TGA and state veterinary authorities maintain quality standards for diagnostic test kits used in both companion animal and agricultural settings. The Queensland corridor concentrates exotic species diagnostic expertise supporting zoo and wildlife conservation institutions.
Veterinary Diagnostic Services Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment suppliers bundle instrumentation with proprietary reagent subscriptions to secure recurring revenue streams. The market structure concentrates around three distinct tiers: integrated life sciences conglomerates with diversified human and animal health portfolios, specialized veterinary diagnostic companies with reference laboratory networks, and emerging point-of-care platform developers. Equipment bundling and geographic expansion represent the primary competitive moves, while regulatory compliance infrastructure serves as a critical differentiator for market access.
Within the integrated diagnostics tier, IDEXX Laboratories, Inc. and Zoetis Services LLC exemplify archetypes combining reference laboratory scale with proprietary platform development. Thermo Fisher Scientific, Inc. occupies a position leveraging applied biosystems PCR instrumentation across both clinical and research veterinary workflows. These three entities anchor the competitive structure through their capacity to negotiate enterprise reagent pricing with corporate veterinary groups while maintaining regulatory affairs infrastructure capable of navigating FDA Center for Veterinary Medicine pre-market review timelines.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| Zoetis Services LLC |
| Antech Diagnostics, Inc. |
| Thermo Fisher Scientific, Inc. |
| Neogen Corporation |
| NationWide Laboratories |
| Heska Corporation |
| bioMérieux |
| Virbac |
| Others |
Value Network & Pricing Analysis
Specialty chemical indices for polymerase chain reaction master mixes and fluorescent probes cascade through three distinct pricing tiers as reagent suppliers negotiate enterprise contracts with corporate veterinary groups while independent clinics face cartridge-based per-test economics.
Pricing Analysis
Input-cost pass-through from concentrated specialty chemical suppliers drives subscription-based reagent pricing bundled with instrumentation leases. Price differentiation rests on ISO 17025 accreditation tier and annual test volume scale, with corporate veterinary groups capturing 40-60% discounts against independent operators. Pricing pressure intensifies as point-of-care platforms displace reference laboratory margins in metropolitan companion animal markets. Independent clinics in Pennsylvania and Michigan exhibit highest price sensitivity due to equipment depreciation burdens, while research institutions in Massachusetts show lowest sensitivity given grant-funded procurement.
Supply Chain Analysis
Reverse-logistics flows for refurbished PCR thermal cyclers and recalibrated chemistry analyzers concentrate in secondary equipment markets serving budget-constrained independent practices. Manufacturing concentrates in the United States, Germany, and Japan for precision instrumentation, while China and South Korea dominate consumable component fabrication. Raw material dependencies include optical-grade plastics, semiconductor-grade silicon for microfluidic chips, and stabilized enzyme preparations. Single-source vulnerability concentrates in fluorescent probe chemistries from three specialty suppliers. Distribution runs through authorized dealer networks for capital equipment and direct-to-clinic replenishment for consumable reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary diagnostic services present geographic-arbitrage value as FDA Center for Veterinary Medicine pre-market review timelines extend product commercialization cycles eighteen to thirty-six months in the United States versus accelerated pathways in Japan under PMDA guidance.
For Market Incumbents: Lock in reagent subscription renewals with corporate veterinary groups through multi-year enterprise pricing agreements before emerging point-of-care molecular platforms achieve FDA CVM validation. Deepen backward integration into specialty chemical manufacturing to insulate margins from probe supplier concentration risk. Prioritize regulatory affairs infrastructure expansion to compress pre-market review timelines against smaller competitors lacking dedicated compliance teams.
For New Entrants and Emerging Players: Cloud-connected teleradiology platforms with AI-assisted preliminary reads offer the most penetrable wedge against established interpretation networks in the United Kingdom and Australia. Target independent companion animal hospitals in secondary US metropolitan markets where corporate group consolidation has not yet concentrated purchasing power. Pursue veterinary medical school partnerships for clinical validation studies that satisfy FDA CVM multi-site performance requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 17025 accreditation mandates create compliance cost barriers for independent diagnostic laboratories serving livestock operations in Iowa and Nebraska. Long-term viability favors platforms with multi-species assay capabilities spanning companion animal, livestock, and wildlife reservoirs. Monitor state veterinary medical board telemedicine practice act revisions as inflection signal for remote diagnostic consultation revenue models.
| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Subscription Bundling | Secures recurring revenue streams from corporate veterinary groups through multi-year enterprise contracts. |
| Point-of-Care PCR Platform Launch | Captures infectious disease screening margin previously retained by IDEXX reference laboratory networks. |
| ISO 17025 Accreditation Investment | Unlocks contract eligibility with corporate veterinary groups consolidating diagnostic purchasing power. |
| Teleradiology Network Expansion | Enables general practitioners in California and Texas to retain specialist referral revenue. |
| Multi-Species Assay Development | Addresses zoonotic disease surveillance requirements across USDA APHIS and EFSA jurisdictions. |
Research Methodology
Bottom-up veterinary clinic transaction modeling reconciled against top-down reagent supplier shipment tracking forms the analytical core of this study. Primary interviews with reference laboratory directors, corporate veterinary group procurement officers, point-of-care platform engineers, and FDA CVM regulatory consultants combined with secondary validation from USDA APHIS disease surveillance reports, FDA 510(k) pre-market notification databases, ISO 17025 accreditation registries, and corporate veterinary group SEC filings. Triangulation across these sources ensures dimensional consistency between clinic-level adoption patterns and manufacturer-reported instrument placements.
Historical trendline analysis of reference laboratory submission volumes, point-of-care analyzer installations, and teleradiology interpretation revenues established baseline growth trajectories across the projection horizon. The forecast framework segments by service delivery model, underlying technology platform, animal category, and institutional end-user type, with additional dimensionality for regulatory compliance tier. CAGRs derive from slope-adjusted trend extrapolation incorporating technology substitution elasticities and corporate consolidation pace. Industry-specific inputs include veterinary clinical pathologist supply constraints, telemedicine reimbursement policy evolution, and livestock biosecurity protocol expansion.
The model holds under stable FDA CVM review timelines and continued corporate veterinary group consolidation; deviation in reagent supply disruptions or state-level telemedicine practice act reversals would shift instrument placement forecasts. Practitioners should monitor specialty chemical supplier batch contamination events and USDA APHIS reportable disease list revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Veterinary Diagnostics Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Immunodiagnostics Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
Psychosis Diagnostics Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
Fertility Test Market
Diagnostics
Global Liver Disease Diagnostics Market