
 Global Pulse Oximetry Market | 2026-2036
Global Pulse Oximetry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pulse Oximetry Market Outlook
ISO 80601-2-61 certification for pulse oximeter accuracy is collapsing the competitive field to manufacturers with dedicated metrology labs and regulatory affairs teams. Masimo Corporation leverages its signal extraction technology to sustain premium positioning in hospital critical care. Nonin Medical anchors its position through FDA-cleared fingertip devices engineered for extreme temperature stability. Contec Medical Systems competes on manufacturing scale from its Shenzhen base, shipping millions of units annually.
Pulse oximetry measures arterial oxygen saturation non-invasively by comparing light absorption at red and infrared wavelengths through perfused tissue, typically reporting SpO2 values between 70% and 100% with a specified accuracy of ±2% in the 70-100% range for FDA-cleared devices. The technology serves continuous patient monitoring in perioperative, emergency, and ambulatory settings where early hypoxemia detection prevents organ injury. Fingertip devices dominate unit volume due to low cost and pharmacy channel penetration, while wearable pulse oximeters represent the fastest-expanding margin pool as consumer health platforms integrate overnight SpO2 trending. Tabletop systems retain stable demand in operating rooms and neonatal intensive care units where multi-parameter integration justifies capital expenditure.
FDA premarket notification requirements under 21 CFR 870.2700 and EU MDR Class IIa designation shape product development timelines and clinical evidence burdens for manufacturers seeking dual-market access. China's NMPA implements GB 9706.1 electrical safety standards alongside specific pulse oximeter registration guidelines that delay market entry for foreign firms without local testing partnerships. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under EU MDR as connected pulse oximeters transmit patient data through cloud platforms.
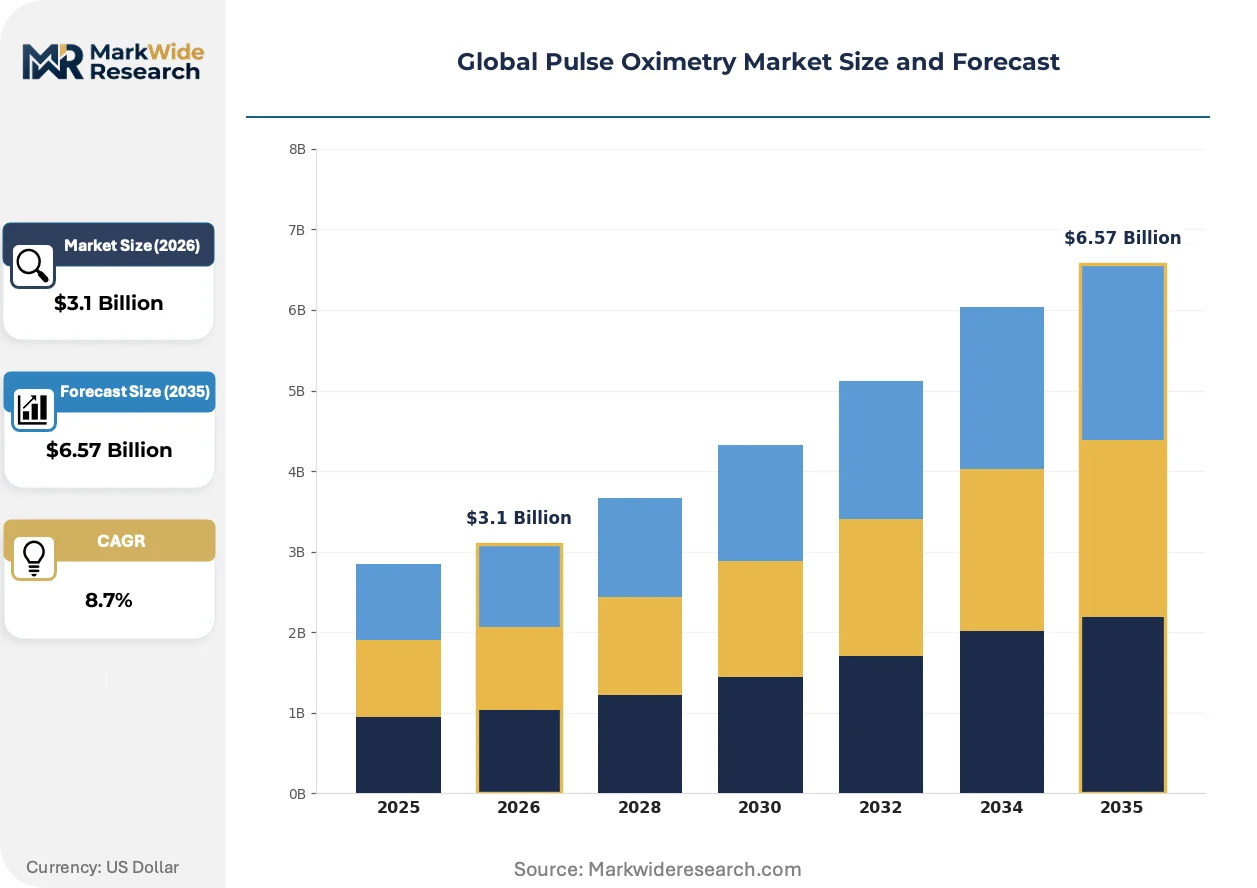
Market Dynamics
ISO 80601-2-61 certification requirements are compressing the competitive field to manufacturers with dedicated metrology infrastructure, forcing mid-tier players to exit or consolidate as regulatory compliance costs escalate beyond standalone viability.
Growth Catalysts
- FDA 21 CFR 870.2700 premarket pathways:Stringent accuracy requirements for clinical-grade devices create durable competitive moats for certified manufacturers serving hospital networks.
- Home care expansion in Germany and Japan:Aging demographics and reimbursement policy shifts accelerate procurement of fingertip and wearable devices for remote patient monitoring.
- Signal extraction algorithms:Advanced motion-tolerant processing enables reliable SpO2 measurement during patient movement, opening ambulatory and athletic monitoring applications previously closed to optical methods.
Market Restraints
- Optical component supply concentration:High-performance photodiodes and specific-wavelength LEDs concentrate among Japanese and German specialty component suppliers, exposing manufacturers to allocation risk.
- EU MDR Class IIa clinical evidence burdens:Expanded post-market surveillance obligations and notified body capacity constraints extend product registration timelines by 12-18 months for dual-market applicants.
- Peripheral perfusion limitations:Low perfusion states compromise measurement reliability in shock, hypothermia, and cardiac arrest patients, restricting device utility in critical emergency indications.
Strategic Opportunities
- India's hospital infrastructure upgrade cycle:Government-funded critical care expansion in tier-2 and tier-3 cities creates first-time demand for multi-parameter monitoring systems with integrated pulse oximetry.
- Overnight SpO2 trending integration:Consumer health platforms are embedding continuous oximetry into sleep wellness ecosystems, generating recurring data subscription revenue streams.
- Cybersecurity guidance alignment:FDA's premarket cybersecurity expectations for connected devices favor manufacturers with established secure-by-design architectures and cloud platform partnerships.
Industry Challenges
- Metrology talent scarcity:ISO 17025-compliant calibration laboratories require specialized biomedical optics expertise that concentrates among legacy device manufacturers and national standards bodies.
- Legacy HIS integration complexity:Hospital information systems operate on fragmented data standards, forcing device manufacturers to maintain multiple connectivity protocols and interface engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pulse Oximetry Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fingertip, Tabletop, Wearable Technology: Optical, Electromagnetic, Hybrid, Remote Monitoring End User: Hospitals, Home Care, Emergency Services, Rehabilitation Centers Distribution Channel: Online, Offline, Direct Sales, Third-Party Distributors |
| Companies Covered | Nonin Medical Inc., GE Healthcare, Medtronic plc, ICU Medical, Inc., Contec Medical Systems Co., Ltd., Masimo Corporation, Nihon Kohden Corporation, Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pulse Oximetry Market Strategic Shifts
Reflectance-mode photoplethysmography is displacing transmission-mode architectures across wrist-worn and forehead-mounted form factors, enabling continuous monitoring outside the constraints of digit-based perfusion requirements.
Reflectance-mode sensors eliminate the optical path through the fingertip by detecting backscattered light from superficial vascular beds. Wearable manufacturers in South Korea and Switzerland are integrating these modules into smartwatch platforms for 24-hour SpO2 tracking. The technology is miniaturizing module dimensions below 4mm × 4mm while maintaining clinical-grade accuracy, collapsing the size differential between consumer and medical devices.
EU MDR post-market clinical follow-up obligations now mandate systematic collection of real-world performance data for Class IIa devices. Manufacturers must establish PMCF plans with defined endpoints and periodic safety update reports. Hospital procurement committees in France and the Netherlands are prioritizing suppliers with demonstrated PMCF infrastructure, shifting contract awards toward established regulatory affairs organizations.
Direct-to-consumer channel expansion is fragmenting traditional distributor relationships as pharmacy chains and telehealth platforms build private-label oximetry portfolios. Amazon and Alibaba health marketplaces now account for substantial fingertip device volume, compressing wholesale margins and forcing manufacturers to manage multi-channel pricing discipline. This disintermediation is most pronounced in the United States and China, where platform logistics infrastructure enables same-day delivery of regulated medical devices.
Global Pulse Oximetry Market Segmentation
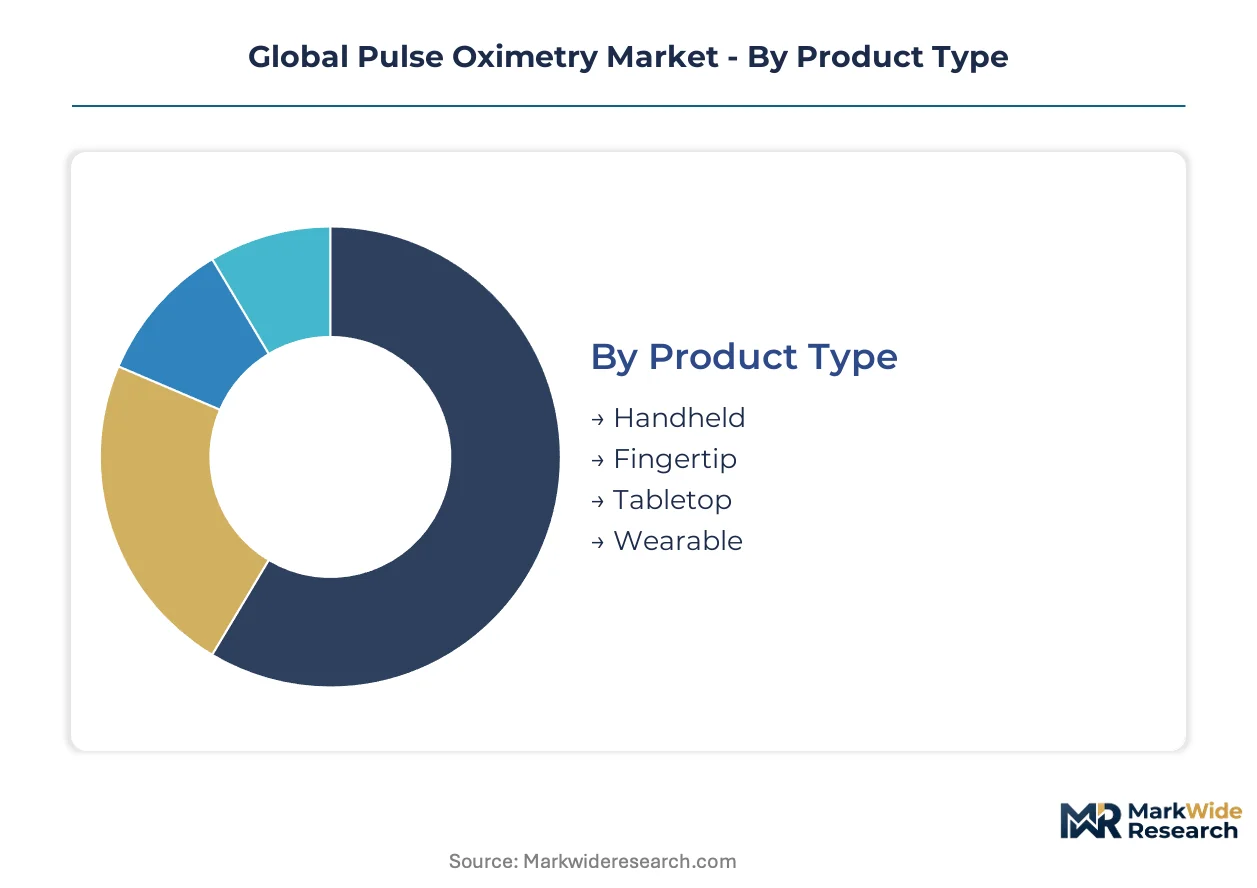
Pulse oximetry segmentation reflects divergent accuracy requirements, form factor constraints, and channel economics across clinical and consumer applications. Technology choices determine regulatory pathway complexity, while end-user concentration shapes procurement behavior and pricing power.
Product Type:
Substitution pressure intensifies as reflectance-mode miniaturization collapses performance gaps between consumer wearables and clinical fingertip devices, forcing incumbents to defend position through FDA-cleared accuracy claims.
- Fingertip:Clip-on transmission-mode devices dominate pharmacy and direct-to-consumer channels with sub-$30 price points. Demand concentrates in United States and China home care segments where COVID-19 habit formation sustained post-pandemic purchase rates for wellness monitoring.
- Wearable:Wrist-worn and ring-form reflectance sensors enable 24-hour SpO2 trending integrated with sleep and fitness platforms. South Korean and Swiss manufacturers are driving fastest adoption in consumer health subscriptions where overnight data generates recurring revenue.
- Handheld:Portable battery-operated units serve ambulance and mobile clinic applications requiring clinical-grade accuracy outside fixed installations.
- Tabletop:Multi-parameter monitoring systems retain stable demand in United States and German operating rooms where integration with anesthesia workstations justifies capital expenditure.
Fingertip devices retain volume leadership across all geographies; wearable formats hold the steepest expansion curve as consumer platform integration accelerates.
Technology:
Cost tier stratification separates premium signal-extraction algorithms from commodity optical implementations, with electromagnetic approaches commanding 3-4x hardware premiums for motion-tolerant critical care applications.
- Optical:Dual-wavelength photoplethysmography at 660nm and 940nm remains the dominant architecture. Japanese and German component suppliers control high-performance photodiode supply, exposing manufacturers to allocation constraints during demand surges.
- Remote Monitoring:Cloud-connected devices with cellular or Wi-Fi transmission enable hospital-at-home programs and post-acute surveillance. FDA cybersecurity guidance and EU MDR post-market surveillance obligations favor manufacturers with established secure-by-design architectures and PMCF infrastructure.
- Hybrid:Combined optical and electromagnetic sensing addresses low-perfusion states in shock and cardiac arrest patients where pure optical methods fail.
- Electromagnetic:Non-optical approaches eliminate perfusion dependency but require specialized hardware limiting deployment to critical care settings in tertiary hospitals.
Optical technologies retain volume leadership; remote monitoring capabilities are gaining share fastest as reimbursement shifts toward value-based hospital-at-home models.
End User:
Customer type concentration creates divergent procurement patterns, with hospital networks demanding multi-parameter integration while home care segments prioritize single-parameter simplicity and price accessibility.
- Hospitals:Critical care, perioperative, and emergency departments drive demand for FDA-cleared devices with ISO 80601-2-61 certification. German and Japanese hospital networks are upgrading monitoring infrastructure amid aging demographics and surgical backlog clearance programs.
- Home Care:Aging-in-place programs and remote patient monitoring reimbursement expansion accelerate procurement in Germany and Japan. India's tier-2 and tier-3 city hospital infrastructure upgrades are creating first-time demand for affordable fingertip devices.
- Emergency Services:Pre-hospital and ambulance applications require motion-tolerant algorithms and ruggedized hardware for field conditions.
- Rehabilitation Centers:Post-acute and pulmonary rehabilitation settings utilize continuous monitoring during exercise tolerance testing and oxygen titration protocols.
Hospitals retain volume leadership; home care segments are expanding most quickly as policy shifts reimburse remote monitoring outside institutional settings.
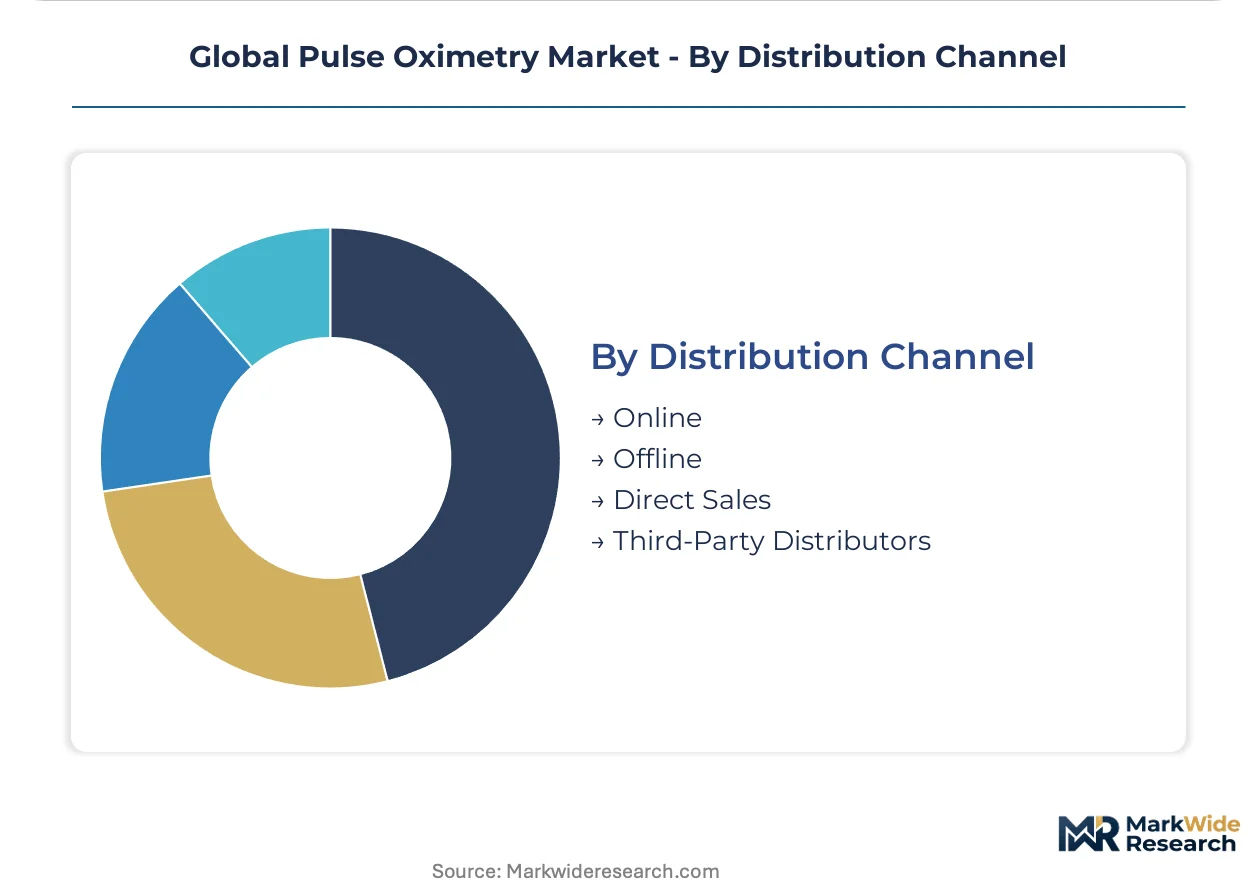
Distribution Channel:
Channel margin compression intensifies as Amazon and Alibaba health marketplaces disintermediate traditional distributors, forcing manufacturers to maintain multi-channel pricing discipline across same-day delivery platforms.
- Online:E-commerce platforms and telehealth marketplaces now account for substantial United States and China volume. Direct-to-consumer channel expansion fragments traditional distributor relationships as pharmacy chains build private-label oximetry portfolios.
- Offline:Brick-and-mortar pharmacy and medical equipment retailers retain importance for device fitting and immediate purchase needs.
- Direct Sales:Manufacturer field forces serve hospital networks and integrated delivery networks requiring contract negotiation and clinical training support.
- Third-Party Distributors:Regional medical device distributors maintain relationships with smaller clinics and international markets where direct presence is uneconomical.
Online channels are gaining share fastest; direct sales retain margin leadership in hospital network contracts requiring clinical evidence and integration support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-funded critical care expansion and aging-in-place reimbursement policies are redirecting procurement flows toward home care channels in developed economies while hospital infrastructure buildouts dominate emerging market investment cycles.
United States
Hospital networks in Texas and Florida are upgrading perioperative monitoring infrastructure amid surgical backlog clearance programs. FDA premarket notification requirements under 21 CFR 870.2700 enforce clinical-grade accuracy standards that compress vendor qualification lists. Amazon's health marketplace logistics infrastructure enables same-day delivery of fingertip devices, fragmenting traditional distributor relationships.
Germany
Aging demographics and statutory health insurance reimbursement shifts accelerate procurement of wearable devices for remote patient monitoring. EU MDR Class IIa designation and post-market surveillance obligations extend registration timelines for dual-market applicants. Medical technology clusters in Baden-Württemberg concentrate metrology infrastructure for ISO 80601-2-61 certification compliance.
China
Tier-2 and tier-3 city hospital infrastructure upgrades create first-time demand for affordable multi-parameter monitoring systems. NMPA implements GB 9706.1 electrical safety standards alongside specific pulse oximeter registration guidelines that delay market entry without local testing partnerships. Shenzhen-based manufacturing operations ship millions of units annually through Alibaba health marketplaces.
Japan
Home care providers expand procurement of fingertip devices as METI reimbursement policies shift toward aging-in-place models. PMDA regulatory requirements align with international standards while maintaining distinct clinical evidence expectations. Osaka-based component suppliers control high-performance photodiode supply for optical sensor architectures.
India
Government-funded critical care expansion in Maharashtra and Karnataka generates demand for affordable fingertip devices in first-time hospital installations. CDSCO medical device registration guidelines are tightening quality control requirements for imported equipment. Tamil Nadu medical device manufacturing zones are attracting contract assembly operations for regional supply.
Global Pulse Oximetry Market Competitive Environment
Listed leaders compete with private specialists across regulatory certification capabilities, with public companies leveraging capital market access to fund metrology infrastructure while private operators retain agility in niche form factor development. The field compresses toward manufacturers with dedicated ISO 17025-compliant calibration laboratories as ISO 80601-2-61 requirements escalate. Three archetypes dominate: diversified medical technology conglomerates with multi-parameter integration capabilities, pure-play pulse oximetry specialists with signal extraction intellectual property, and scaled manufacturing operators competing on unit economics. Competitive moves concentrate on strategic partnerships with cloud platform providers and geographic expansion through distributor acquisition.
Within the signal extraction specialist tier, Masimo Corporation and Nonin Medical occupy positions defined by motion-tolerant algorithm portfolios and FDA-cleared accuracy claims. Contec Medical Systems Co., Ltd. exemplifies the scale-driven manufacturing archetype with Shenzhen-based production operations. These three anchors illustrate the competitive tension between premium positioning through regulatory certification and volume leadership through manufacturing scale.
| Leading Market Players |
|---|
| Nonin Medical Inc. |
| GE Healthcare |
| Medtronic plc |
| ICU Medical, Inc. |
| Contec Medical Systems Co., Ltd. |
| Masimo Corporation |
| Nihon Kohden Corporation |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for high-performance photodiodes from Osaka-based suppliers concentrate pricing power among manufacturers with established component allocation agreements, while inventory buffers at Shenzhen assembly operations compress margins for uncontracted buyers. This supply asymmetry feeds into tiered hardware economics where FDA-cleared accuracy claims command sustainable premiums over commodity fingertip alternatives.
Pricing Analysis
Certification level creates the primary spread across hardware tiers. ISO 80601-2-61-compliant devices with FDA 510(k) clearance price at 3-4x multiples above uncertified consumer units, while CE marking under EU MDR adds intermediate positioning for dual-market applicants. Cost compression in the pharmacy channel intensifies as Amazon and Alibaba logistics enable same-day delivery, forcing manufacturers to absorb freight subsidies. Home care segments in Germany and Japan exhibit lowest price sensitivity due to reimbursement coverage, whereas India's tier-2 hospital procurement committees prioritize unit economics over accuracy specifications.
Supply Chain Analysis
Japan and Germany anchor specialized optical component production, with Hamamatsu and Osram supplying 660nm and 940nm LEDs and silicon photodiodes that determine measurement precision. Shenzhen and Dongguan in China feed from these inputs for final device assembly, while South Korean wearable manufacturers integrate reflectance-mode modules into smartwatch platforms. Single-source vulnerability concentrates in Japanese photodiode foundries, where earthquake exposure and allocation rationing during demand surges disrupt downstream production. Distribution runs through three channels: direct sales to hospital networks, third-party medical distributors for regional clinics, and platform marketplaces for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are flattening as reflectance-mode miniaturization collapses performance gaps, making data subscription layers and clinical integration services the faster-expanding profit pools. Recurring revenue from overnight SpO2 trending platforms now outpaces device shipment growth in the wearable segment.
For Market Incumbents: Compound regulatory certification advantages by deepening ISO 17025 metrology infrastructure before EU MDR post-market surveillance obligations fully mature. Acquire distributor relationships in India's tier-2 cities to preempt government-funded hospital infrastructure awards. Motion-tolerant algorithm portfolios must extend into hospital-at-home reimbursement pathways to defend against consumer wearable encroachment. For New Entrants and Emerging Players: Anchor in reflectance-mode sensor miniaturization for sleep wellness platforms, where clinical accuracy claims remain underdeveloped and platform partnerships determine adoption. India's CDSCO registration pathway for affordable fingertip devices offers the most penetrable regulatory entry point. Pursue telehealth marketplace listings before incumbent pricing discipline hardens on Amazon and Alibaba channels. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because ISO 80601-2-61 certification scarcity will intensify as notified body capacity constraints extend EU MDR timelines. Target acquisition profiles emphasize manufacturers with established PMCF infrastructure and cloud platform partnerships rather than pure hardware scale. The signal to watch is FDA cybersecurity guidance enforcement, which will accelerate consolidation toward secure-by-design architectures.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 80601-2-61 Certification Investment | Collapses competitive field to metrology-capable manufacturers as regulatory costs escalate. |
| Hospital System Partnership | Locks in multi-parameter integration contracts with anesthesia workstation vendors in German and US operating rooms. |
| Software Companion Development | Enables overnight SpO2 trending subscriptions that outpace hardware margin expansion in consumer wearables. |
| Reimbursement Strategy | Aligns device procurement with Germany's statutory health insurance remote monitoring coverage expansion. |
| CE Marking Pathway | Secures EU MDR Class IIa access before notified body capacity constraints extend competitor timelines. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at device manufacturers, then refined against secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up volume estimates by product type and technology tier were triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics, with segmentation modeling across product type, technology architecture, end-user setting, and distribution channel. CAGRs were derived from fitted growth curves rather than linear extrapolation, incorporating pulse oximetry-specific inputs including surgical backlog clearance rates, aging-in-place reimbursement policy shifts, and photodiode supply allocation cycles.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EU MDR regulatory stringency; material deviation in notified body capacity or component supply concentration would warrant model refresh. Recalibration cycles align with material shifts in reimbursement policy, cybersecurity guidance enforcement, and reflectance-mode sensor cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Implant Handpiece Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
Needle-Free IV Connectors Market
Medical Devices
Global Ventilators Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Portable Medical Electronic Products Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Canada General Surgical Devices Market