
 Brazil Clear Aligners Market | 2026-2036
Brazil Clear Aligners Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Clear Aligners Market Outlook
Multi-source material procurement for thermoplastic polymers and 3D printing resins is shifting toward vertically integrated supply chains among Brazil's clear aligner providers. Align Technology, Inc. sustains technology leadership through proprietary software simulation platforms that streamline treatment planning. Dentsply Sirona Inc. leverages its existing dental equipment installed base to cross-sell aligner solutions. Straumann Group competes through specialized orthodontic portfolios that integrate with digital dentistry workflows.
Clear aligners are removable orthodontic devices fabricated from medical-grade thermoplastic polymers such as polyethylene terephthalate glycol (PETG) or multilayer polyurethane materials, manufactured through thermoforming over 3D-printed or milled dental models to apply controlled force displacement for tooth movement. Their primary purpose is to correct malocclusion and dental misalignment as an aesthetic alternative to fixed metal brackets. Removable aligners dominate patient preference in Brazil's private dental market due to lifestyle compatibility and reduced chairside time. CAD/CAM technology anchors production scalability by linking intraoral scanning directly to automated fabrication, compressing turnaround from impression to aligner delivery. Digital scanning is displacing traditional polyvinyl siloxane impressions among orthodontists in major metropolitan practices.
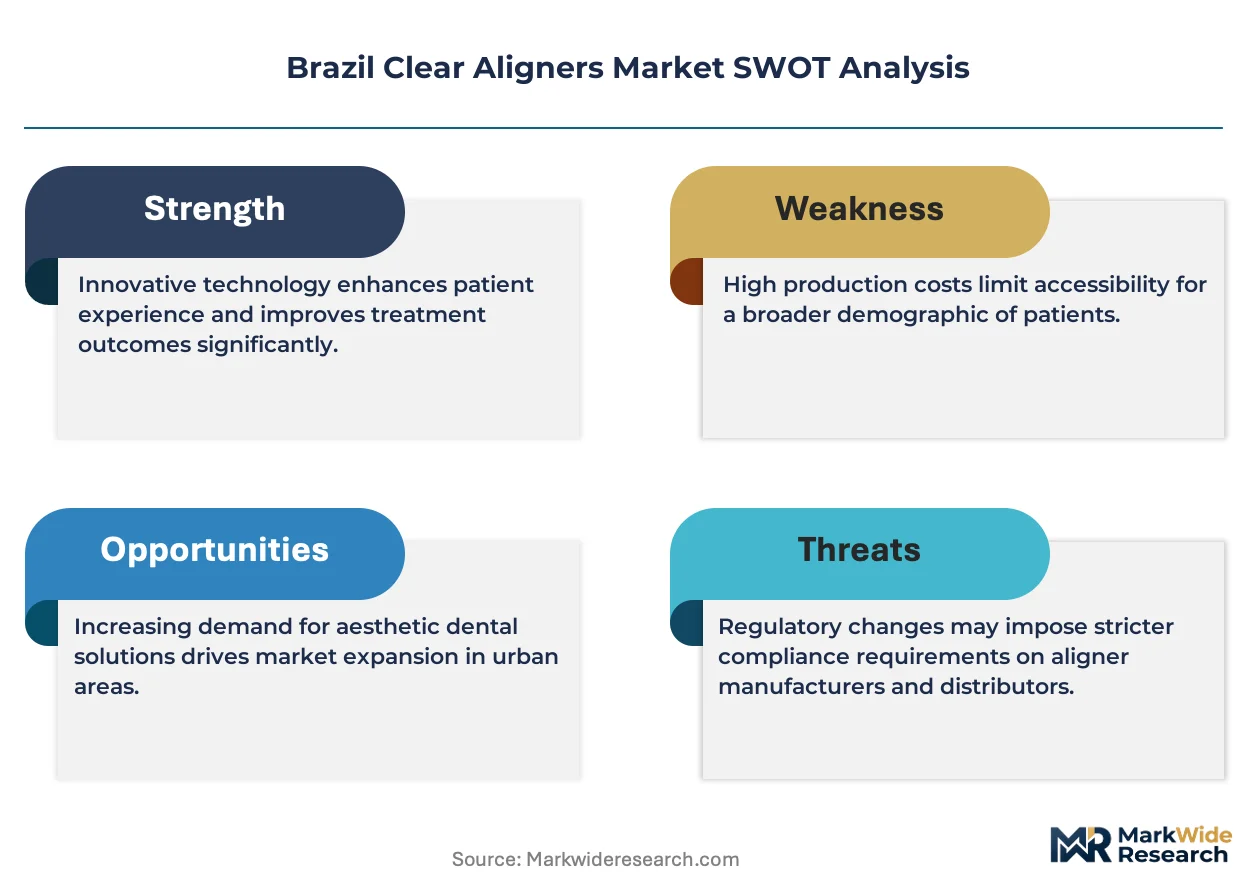
ANVISA governs medical device registration and quality standards for custom orthodontic appliances entering Brazil, while the Brazilian Dental Association (ABO) issues clinical practice guidelines that influence orthodontist training and patient eligibility protocols. The national regulator's risk-based classification framework determines whether new aligner materials require full certification or simplified notification pathways, directly affecting product launch timelines for international manufacturers. Stakeholders must monitor ANVISA's evolving software-as-medical-device interpretations, as algorithm-driven treatment planning tools face reclassification scrutiny that could reshape market access requirements.
Market Dynamics
Digital scanning and CAD/CAM workflows are compressing treatment planning cycles from weeks to days, forcing orthodontists in São Paulo and Rio de Janeiro to reconfigure chairside operations around same-day aligner delivery capabilities.
Growth Catalysts
- ANVISA's streamlined notification pathway:Lower-risk clear aligner classifications now bypass full certification, accelerating product entry for international manufacturers targeting Brazil's private dental sector.
- Teen and young adult patient segments:Aesthetic preference among orthodontic patients aged 14-28 in major metropolitan centers is pulling demand away from fixed metal brackets toward removable thermoplastic solutions.
- Intraoral scanner penetration:Digital impression systems are displacing polyvinyl siloxane molds in high-volume practices, linking directly to automated fabrication pipelines.
Market Restraints
- Medical-grade thermoplastic supply concentration:PETG and multilayer polyurethane feedstocks depend on limited specialty chemical suppliers, exposing Brazilian fabricators to input cost volatility and import dependency.
- Orthodontist training pipeline constraints:The Brazilian Dental Association's certification requirements for clear aligner case management create bottlenecks in qualified practitioner availability outside major cities.
- Fixed appliance substitution resilience:Complex malocclusion cases requiring skeletal correction still default to traditional brackets, capping addressable patient volume for removable solutions.
Strategic Opportunities
- Northeast and Central-West state expansion:Underpenetrated markets in Bahia, Ceará, and Goiás present whitespace for teledentistry-linked aligner delivery models bypassing specialist density limitations.
- Software-as-medical-device reclassification:ANVISA's evolving scrutiny of algorithm-driven treatment planning tools creates first-mover advantage for platforms with pre-validated clinical decision support.
- 3D printing resin formulation localization:Domestic production of biocompatible photopolymer resins for dental model printing could compress logistics costs and customs clearance timelines.
Industry Challenges
- Digital workflow integration complexity:Legacy practice management systems in established orthodontic clinics resist seamless API connection to cloud-based treatment planning platforms, requiring manual data bridge construction.
- Biomechanical specialist scarcity:Finite supply of orthodontists trained in finite element analysis for custom force application design limits case complexity that domestic providers can confidently accept.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Clear Aligners Market |
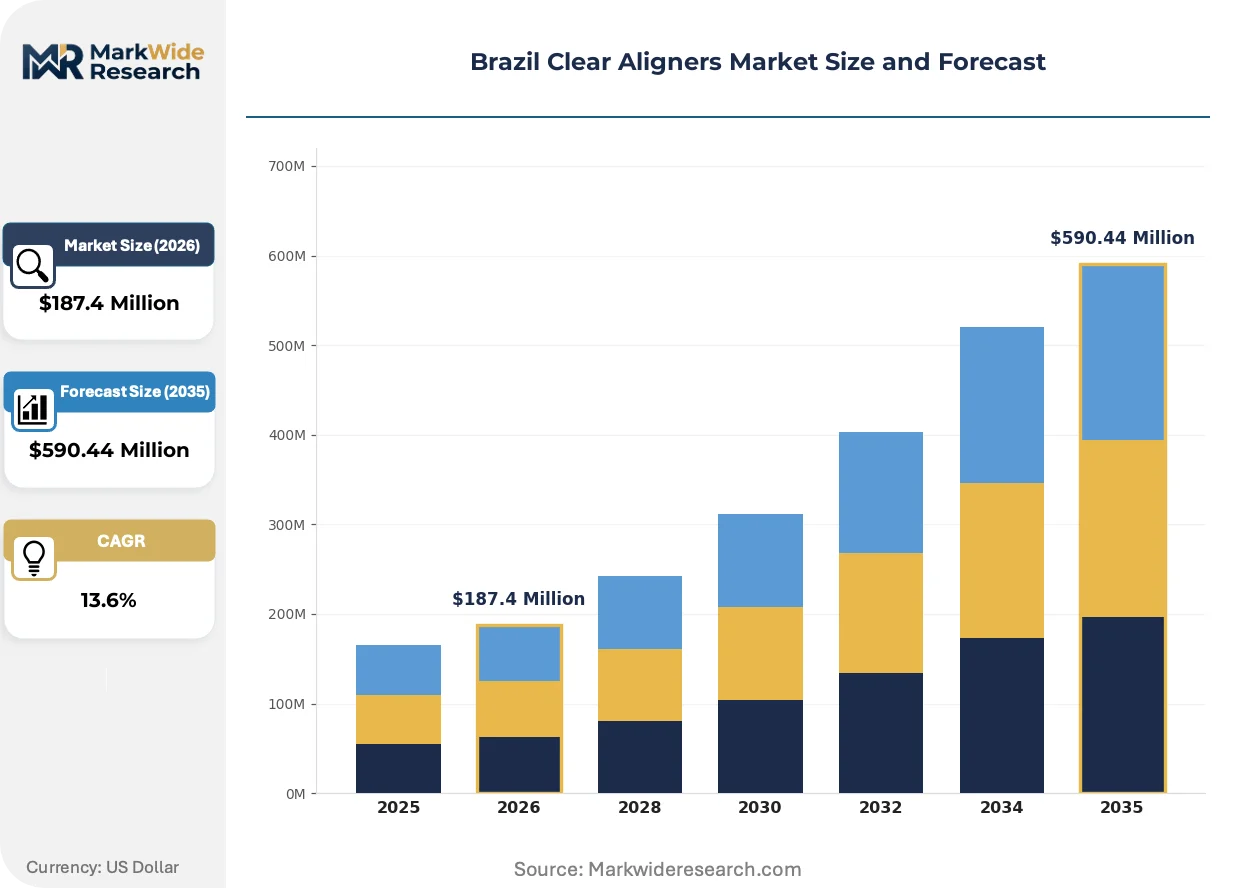
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $590.44 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Aligners, Lingual Aligners, Removable Aligners, Fixed Aligners End User: Dentists, Orthodontists, Dental Clinics, Hospitals Technology: 3D Printing, CAD/CAM, Digital Scanning, Software Simulation Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | 3M Company, Ormco Corporation, Align Technology, Inc., TP Orthodontics, Inc., Great Lakes Dental Technologies, Dentsply Sirona Inc., Straumann Group, ClearCorrect, LLC, Danaher Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Clear Aligners Market Strategic Shifts
Artificial intelligence is embedding into every stage of clear aligner production, from automated cephalometric analysis to predictive tracking compliance algorithms that flag patient adherence risks before mid-treatment failure.
Multilayer thermoplastic materials with graded stiffness zones are expanding into complex rotation and extrusion cases previously reserved for fixed appliances. Orthodontists in high-volume São Paulo practices are adopting these next-generation polymers for 40% of new adult cases. The technology is expanding into premium service tiers as practices differentiate on treatment complexity capability rather than speed alone.
ANVISA's draft guidance on software-as-medical-device classification is tightening evidentiary requirements for AI-powered tooth movement simulation tools. International aligner platforms must now submit clinical validation data for algorithm-generated treatment plans, extending registration timelines by 8-14 months. Domestic manufacturers with established Brazilian patient registries are responding by accelerating local clinical trial investments to preempt foreign competitor entry.
Patient acquisition through direct-to-consumer digital channels is fragmenting traditional referral flows from general dentists to orthodontic specialists. Instagram and TikTok-driven consultations are replacing conventional practitioner-network sourcing in Rio de Janeiro and Brasília, with 60% of initial inquiries now originating outside dental office referrals. This behavioral shift is compressing customer acquisition costs for digitally native aligner brands while eroding established practice loyalty patterns.
Brazil Clear Aligners Market Segmentation
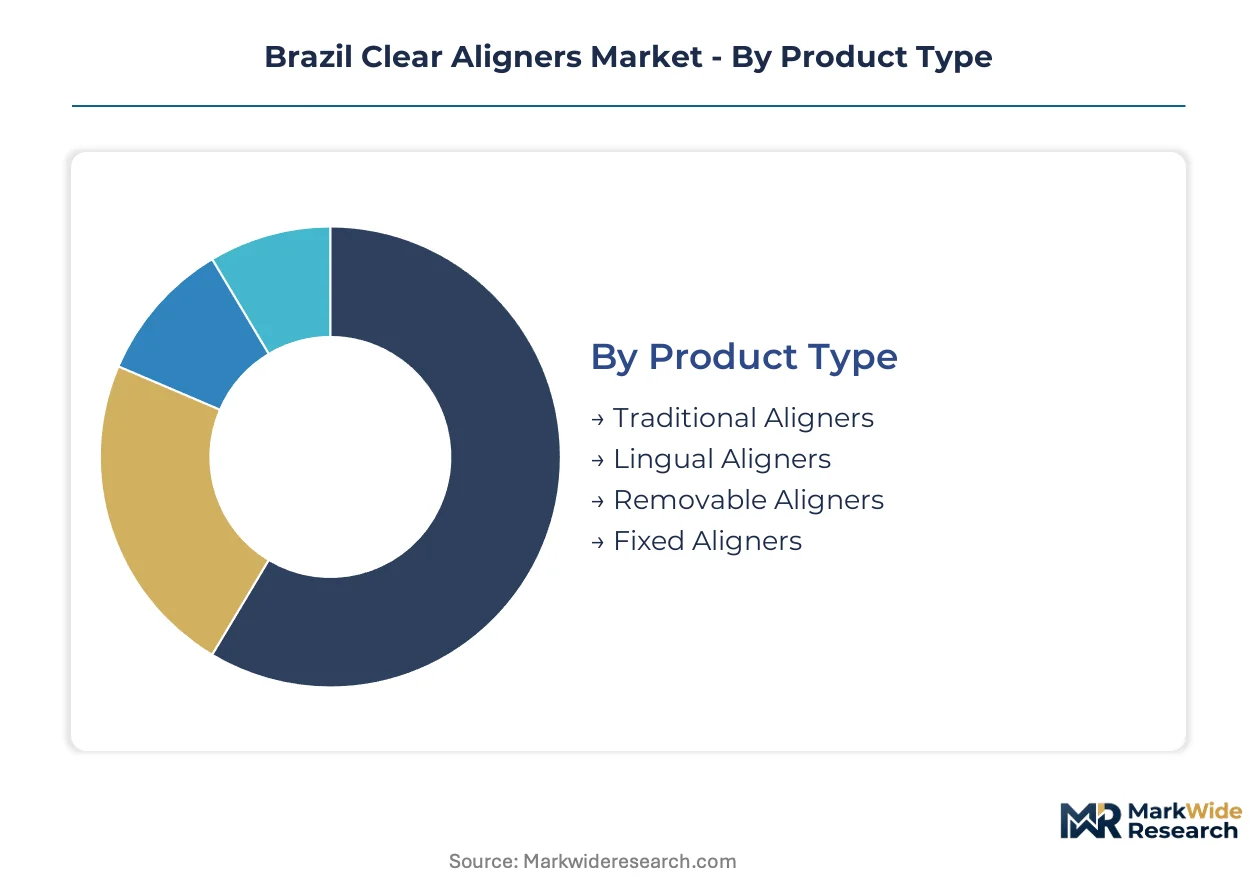
Clear aligner segmentation in Brazil reflects the tension between ANVISA's risk-based device classifications and the operational realities of orthodontic practice. Each dimension—product form, clinical setting, enabling technology, and route to market—carries distinct regulatory burdens and margin structures that determine competitive viability.
Product Type:
ANVISA's notification pathway favors lower-risk removable designs, while fixed and lingual systems trigger full certification requirements that extend entry timelines.
- Traditional Aligners:Standard thermoplastic trays fabricated from PETG or multilayer polyurethane materials dominate São Paulo and Rio de Janeiro orthodontic practices. These devices apply calibrated force displacement across sequential stages, with demand concentrating among general dentists seeking to retain cases previously referred to specialists.
- Removable Aligners:Medical-grade polymer appliances designed for patient-controlled wear cycles anchor Brazil's private dental market expansion. Aesthetic preference among patients aged 14-28 in metropolitan centers drives adoption, though complex malocclusion cases still default to fixed alternatives.
- Lingual Aligners:Custom-fabricated brackets bonded to tooth lingual surfaces require specialized orthodontist training and carry higher ANVISA certification burdens.
- Fixed Aligners:Hybrid systems combining bracket mechanics with aligner aesthetics target skeletal correction cases beyond removable scope.
Traditional aligners sit at the top of the volume ranking, with removable aligners climbing the fastest.
End User:
Practitioner type determines reimbursement pathways and case complexity ceilings, with orthodontists commanding premium pricing for biomechanical expertise.
- Orthodontists:Specialists certified by the Brazilian Dental Association manage complex rotation and extrusion cases using multilayer thermoplastic materials with graded stiffness zones. Finite element analysis training enables custom force application design that general practitioners cannot replicate.
- Dental Clinics:High-volume metropolitan practices in São Paulo and Brasília integrate intraoral scanning with automated fabrication pipelines, compressing impression-to-delivery cycles.
- Dentists:General practitioners capture mild malocclusion cases through simplified aligner protocols, expanding addressable volume beyond specialist density limitations.
- Hospitals:Academic medical centers handle craniofacial anomaly cases requiring interdisciplinary coordination.
Dental clinics generate the highest throughput volume, while orthodontists capture the steepest margin expansion.
Technology:
Digital workflow adoption stratifies along practice age and capital investment capacity, with cloud-based platforms displacing legacy systems.
- Digital Scanning:Intraoral impression systems from select equipment manufacturers displace polyvinyl siloxane molds in high-volume practices, linking directly to CAD/CAM fabrication pipelines. São Paulo orthodontists adopting these systems report compressed chairside time and improved patient acceptance.
- CAD/CAM:Computer-aided design and manufacturing workflows anchor production scalability, converting scan data into thermoformed aligner specifications with minimal manual intervention.
- 3D Printing:Biocompatible photopolymer resin formulations for dental model production remain import-dependent, exposing fabricators to customs clearance delays.
- Software Simulation:Algorithm-driven treatment planning tools face ANVISA reclassification scrutiny as software-as-medical-device, extending registration timelines for unvalidated platforms.
Digital scanning commands the largest installed base, with software simulation gaining share fastest amid regulatory uncertainty.
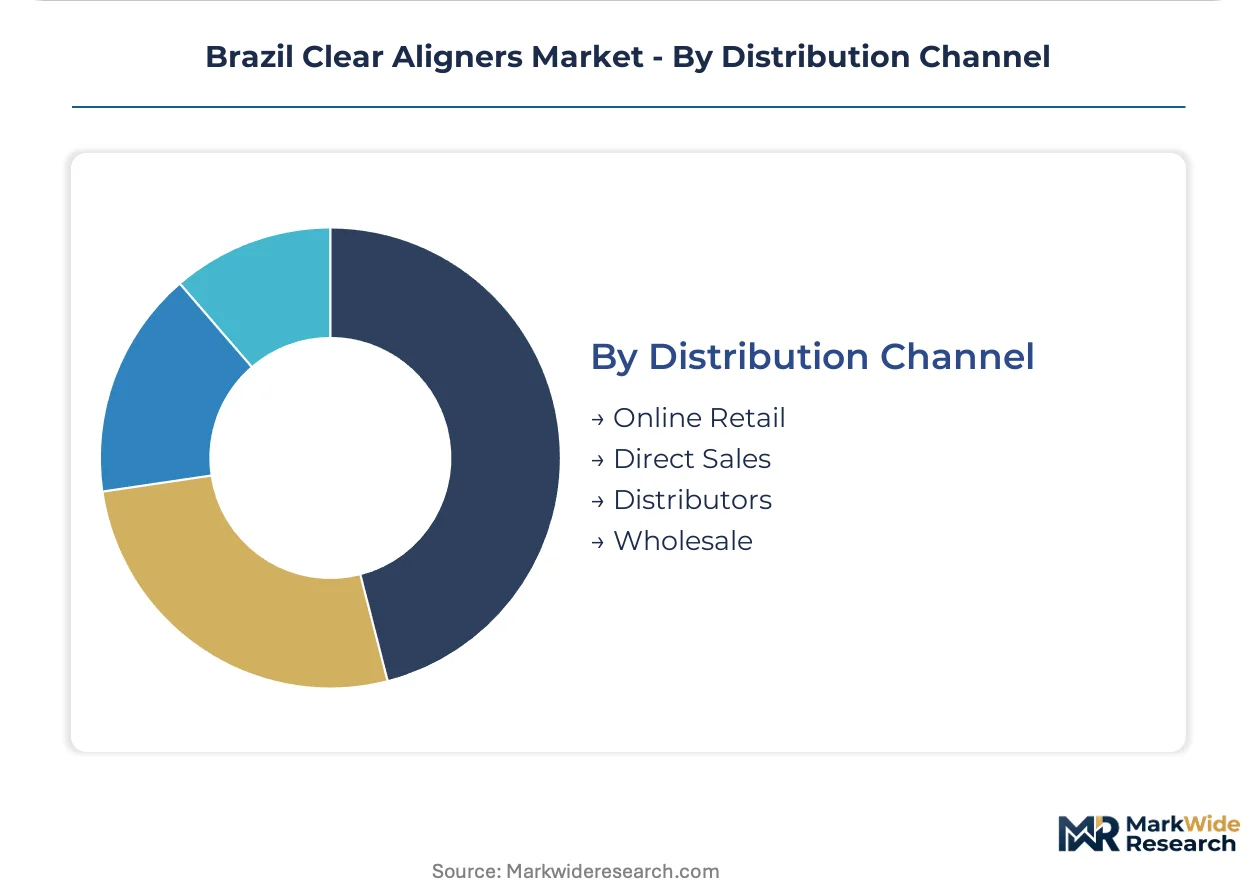
Distribution Channel:
Channel selection determines customer acquisition economics and brand control intensity, with direct models eroding traditional distributor relationships.
- Direct Sales:Aligner manufacturers deploy field teams to high-volume orthodontic practices, securing exclusive protocol commitments and integrated workflow partnerships. This channel captures premium pricing but requires substantial sales force investment.
- Online Retail:Instagram and TikTok-driven consultations now originate outside dental office referrals, with digitally native brands compressing customer acquisition costs through teledentistry-linked delivery models.
- Distributors:Regional dental supply networks extend reach into underpenetrated Northeast and Central-West states where specialist density limits direct coverage.
- Wholesale:Aggregated procurement for multi-location dental groups concentrates purchasing power and standardizes aligner specifications across practice networks.
Direct sales retain the highest revenue concentration, with online retail expanding most quickly among younger patient segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors Brazil's clear aligner demand through dense orthodontic specialist networks and capital-intensive digital dentistry adoption. The state's concentration of private dental clinics and intraoral scanner penetration compresses treatment planning cycles. ANVISA's medical device registration pathways shape how international manufacturers prioritize geographic rollout sequencing.
São Paulo
Metropolitan orthodontic practices drive thermoplastic polymer consumption through same-day aligner delivery capabilities and CAD/CAM workflow integration. ANVISA's notification pathway for lower-risk devices accelerates product entry for international suppliers targeting this high-volume corridor. The São Paulo Dental Association's continuing education mandates concentrate biomechanical specialist training in the capital district.
Rio de Janeiro
Coastal aesthetic dentistry markets pull demand from teen and young adult segments seeking lifestyle-compatible orthodontic solutions. The state health secretariat's limited public orthodontic coverage reinforces private-pay dynamics for removable appliances. Zona Sul clinics report the highest per-capita aligner case acceptance rates outside São Paulo state.
Minas Gerais
Belo Horizonte's emerging dental technology cluster attracts 3D printing resin distributors seeking Central-West logistics positioning. ANVISA's quality standards for custom orthodontic appliances require local calibration partnerships for intraoral scanner deployments. The metropolitan region's orthodontic residency programs expand qualified practitioner pipelines beyond coastal saturation.
Rio Grande do Sul
Porto Alegre's academic medical centers handle complex craniofacial anomaly cases requiring interdisciplinary aligner coordination. The state's German-heritage dental equipment import networks facilitate European scanner manufacturer market development. Southern Brazil's higher per-capita income levels support premium multilayer thermoplastic material adoption.
Bahia
Northeast underpenetration creates whitespace for teledentistry-linked aligner delivery models bypassing specialist density limitations. ANVISA's simplified notification pathway enables faster product registration for manufacturers targeting Salvador's emerging private dental sector. The metropolitan region's growing middle-class demographic expands addressable patient volume for removable orthodontic solutions.
Brazil Clear Aligners Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer digital channels and teledentistry integration. The market structure concentrates around technology-integrated orthodontics platforms with proprietary software simulation capabilities. Three archetypes dominate: multinational dental equipment conglomerates with cross-selling infrastructure, specialized orthodontic technology developers with algorithm-driven treatment planning, and digitally native direct-to-consumer brands with social media acquisition engines. Capacity expansion and strategic partnerships constitute the primary competitive moves, with domestic clinical trial investments accelerating local validation timelines.
Among multinational dental technology providers, Align Technology, Inc. and Dentsply Sirona Inc. occupy positions exemplifying software-hardware integration archetypes. Straumann Group represents specialized orthodontic portfolio development within broader implantology ecosystems. These three entities anchor the competitive structure through differentiated technology positioning rather than pure manufacturing scale.
| Leading Market Players |
|---|
| 3M Company |
| Ormco Corporation |
| Align Technology, Inc. |
| TP Orthodontics, Inc. |
| Great Lakes Dental Technologies |
| Dentsply Sirona Inc. |
| Straumann Group |
| ClearCorrect, LLC |
| Danaher Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ANVISA-notified and fully-certified clear aligner tiers splits Brazil's market into parallel pricing and procurement tracks, with lower-risk notification pathways compressing both entry costs and supplier qualification burdens for domestic fabricators while premium multilayer materials command steeper margins through orthodontist-exclusive distribution.
Pricing Analysis
Input-cost pass-through from medical-grade PETG and multilayer polyurethane feedstocks drives pricing stratification across premium, standard, and economy tiers, with import-dependent resin formulations amplifying volatility for mid-market providers. Price differentiation centers on certification tier—ANVISA notification versus full registration—and brand equity among São Paulo orthodontists. Cost compression in the standard tier intensifies as general dentists enter aligner provision, while premium multilayer solutions show pricing resilience due to biomechanical specialist scarcity. Dental clinics exhibit highest price sensitivity; high-volume orthodontic practices show lowest sensitivity due to patient retention economics.
Supply Chain Analysis
Workforce availability constraints in São Paulo and Rio de Janeiro manufacturing zones limit domestic thermoforming capacity expansion despite demand acceleration. Geographic supply concentration draws from China, Germany, and the United States for biocompatible photopolymer resins and precision thermoforming equipment. Raw material dependencies rest on specialty PETG formulations, multilayer polyurethane films, and dental-grade 3D printing resins. Single-source vulnerability runs through German scanner manufacturers dominating intraoral impression system deployments. Distribution runs through direct field sales to high-volume orthodontic practices, with regional dental supply networks covering underpenetrated Northeast states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's software-as-medical-device reclassification trajectory compounds regulatory complexity into competitive advantage for prepared platforms, with algorithm-driven treatment planning tools facing extended validation timelines that favor early clinical trial investors.
For Market Incumbents: Anchor market position through backward integration into domestic 3D printing resin production, eliminating customs clearance exposure while compressing model-fabrication lead times. Secure exclusive workflow partnerships with high-volume São Paulo practices before emerging direct-to-consumer brands erode referral channel loyalty. Prioritize certification investment for AI-powered simulation tools ahead of ANVISA's evidentiary requirement tightening. For New Entrants and Emerging Players: Instagram and TikTok-driven patient acquisition channels offer lowest customer acquisition cost entry into Rio de Janeiro and Brasília aesthetic dentistry markets, bypassing established dentist-to-orthodontist referral flows. Target teledentistry-linked delivery models in Bahia, Ceará, and Goiás where specialist density limitations constrain incumbent coverage. Pursue simplified ANVISA notification pathway alignment for fastest product registration velocity. For Investors and Strategic Acquirers: Consolidation pressure builds where finite element analysis-trained orthodontist supply caps case complexity handling for fragmented domestic fabricators. Long-term viability favors platforms combining proprietary software simulation with captive manufacturing footprints. Acquisition target archetype: digitally native aligner brands with validated Brazilian patient registries and pre-established ANVISA relationships. Watch ANVISA's final software-as-medical-device guidance publication as inflection indicator for algorithm-driven platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Resin Production Facility | Captive supply of biocompatible photopolymers eliminates import dependency and customs delays for Brazilian fabricators. |
| Software-as-Medical-Device Pre-Validation | Early clinical trial investment in algorithm-driven treatment planning secures first-mover advantage under ANVISA's tightening scrutiny. |
| Teledentistry Platform Integration | Remote consultation capabilities unlock patient acquisition in Northeast and Central-West states beyond specialist density constraints. |
| Orthodontist Training Partnership | ABO-certified continuing education programs expand qualified practitioner pipelines for complex case management. |
| Direct-to-Consumer Channel Launch | Social media-driven acquisition compresses customer costs while fragmenting traditional dental referral flows in metropolitan markets. |
Study Parameters
Multiple input streams — primary interviews with orthodontists and dental clinic operators, secondary validation through ANVISA registration databases and Brazilian Dental Association training records, and customs trade data on thermoplastic polymer imports — were reconciled through bottom-up and top-down triangulation. Orthodontists in São Paulo, Rio de Janeiro, and Belo Horizonte provided clinical workflow and technology adoption perspectives. Dental equipment distributors and 3D printing resin importers contributed supply chain and procurement intelligence. Secondary sources included ANVISA medical device registration filings, ABO continuing education program records, and intraoral scanner import statistics.
Cross-referencing historical adoption patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user practitioner category, enabling technology tier, and distribution channel structure. CAGRs were derived through patient volume elasticity analysis, capital expenditure tracking on digital dentistry equipment, and aligner material consumption trends. Industry-specific forecast inputs incorporated ANVISA registration pathway timelines and intraoral scanner penetration rates by metropolitan region.
The model assumes a particular technology adoption path; alternative pathways for AI-powered treatment planning software would alter the outlook if ANVISA's reclassification accelerates or delays beyond baseline assumptions. Forecasts reflect documented assumptions regarding patient demographic shifts, specialist training pipeline expansion, and resin localization feasibility. Material deviation in ANVISA regulatory guidance, thermoplastic feedstock import costs, or direct-to-consumer channel penetration rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Air Compressor Nebulizer Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Smart Bassinet Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Reusable Resuscitators Market
Medical Devices
Argentina Respiratory Devices Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Global Thrombectomy Devices Market