
 Global Medical Devices Market | 2026-2036
Global Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Devices Market Outlook
Aftermarket service revenue is reconfiguring how device manufacturers capture lifetime value from installed bases. Medtronic leverages its remote monitoring platforms to sustain recurring revenue streams across cardiac rhythm management. Siemens Healthineers anchors its margin profile through long-term service contracts on imaging systems. Johnson & Johnson MedTech differentiates by embedding digital analytics into surgical instrument fleets.
Medical devices encompass instruments, apparatus, machines, and implants used for diagnosis, prevention, monitoring, or treatment of disease, typically requiring biocompatibility testing and sterilization validation under ISO 13485 quality management systems. Their primary commercial purpose centers on improving patient outcomes while reducing procedural invasiveness and recovery duration. Diagnostic equipment occupies the largest revenue pool as health systems prioritize early disease detection, while robotic surgery technology commands premium pricing and represents the fastest-expanding margin segment. Imaging systems remain mature with replacement cycles tied to hospital capital budgets, whereas wearable monitoring devices are penetrating home care channels.
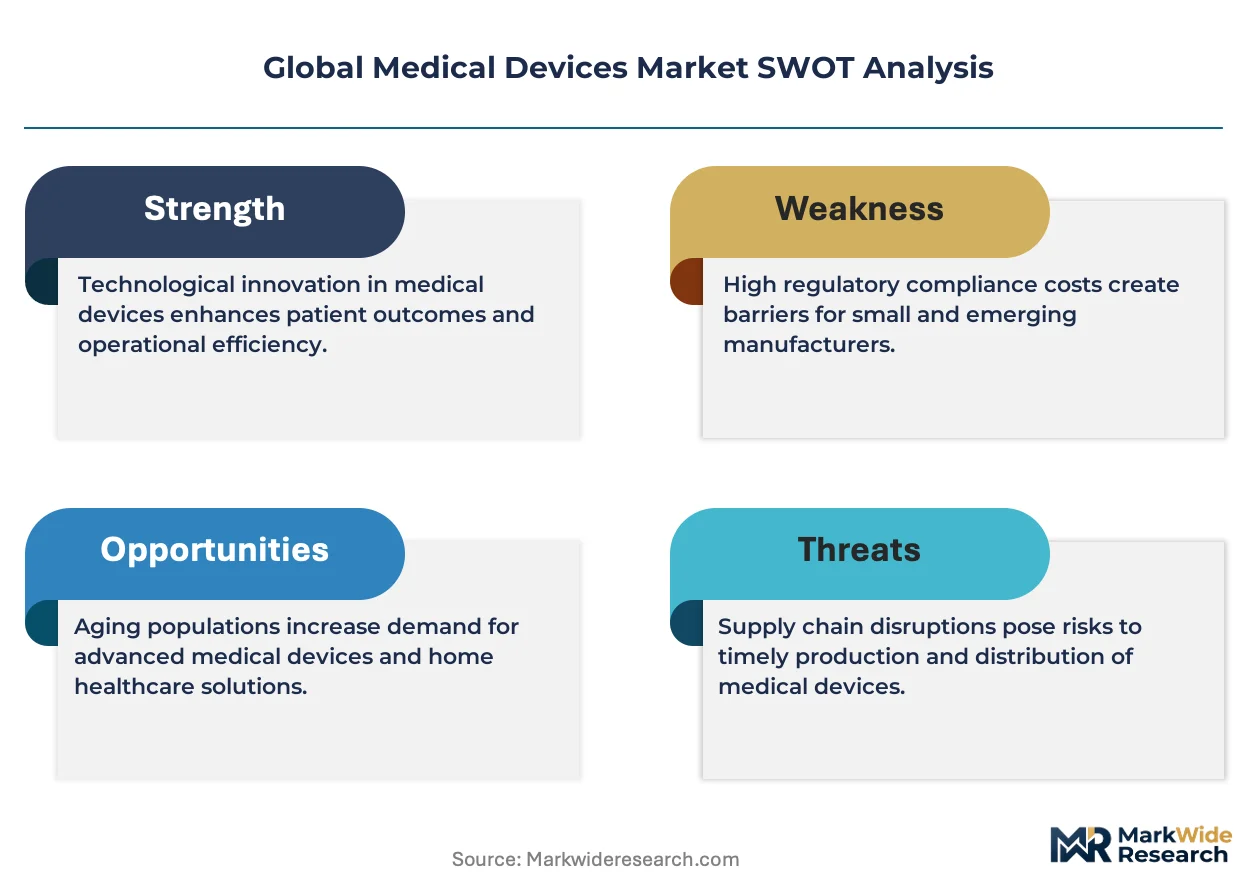
The FDA enforces premarket notification and quality system regulation for US market access, while the EU Medical Device Regulation mandates notified body oversight and unique device identification. Japan's PMDA imposes stringent clinical evidence requirements that shape product development timelines for Asian market entry. Stakeholders must monitor how divergent regulatory timelines across the FDA, EMA, and PMDA will reshape competitive positioning in connected device categories.
Market Dynamics
Aftermarket service revenue streams are reconfiguring manufacturer business models as installed bases expand across cardiac rhythm management, imaging systems, and surgical instrument fleets. This shift from transactional hardware sales toward recurring digital services represents the dominant structural force reshaping competitive economics.
Growth Catalysts
- EU Medical Device Regulation:The MDR's tightened conformity assessment requirements are accelerating consolidation among notified body-approved manufacturers, privileging established players with robust quality management systems.
- Home care settings:Portable monitoring equipment penetration into residential environments is creating new demand pools outside traditional hospital procurement channels.
- Digital health infrastructure:Government investments in the United States, Germany, and Japan are scaling reimbursement frameworks for connected diagnostic and therapeutic devices.
Market Restraints
- Platinum group metal volatility:Electrode and implantable component costs fluctuate with palladium and rhodium supply disruptions from South African mining concentration.
- PMDA clinical evidence requirements:Japan's pharmaceutical and medical devices agency imposes extended trial timelines that compress Asian market entry windows for novel therapeutic technologies.
- Polymer supply concentration:Medical-grade silicone and thermoplastic elastomer production clusters in Northeast Asia create single-source vulnerability for catheter and tubing manufacturers.
Strategic Opportunities
- Brazil's ANVISA pathway acceleration:Streamlined registration for FDA- and CE-marked devices opens Latin America's largest healthcare market to accelerated commercialization.
- AI-embedded surgical navigation:Convergence of computer vision and haptic feedback systems enables real-time tissue differentiation in minimally invasive procedures.
- Remote patient monitoring reimbursement:CMS coding expansions in the United States create sustainable revenue models for continuous glucose and cardiac rhythm surveillance.
Industry Challenges
- ISO 13485 auditor capacity:Notified body resource constraints extend quality management system certification timelines, delaying product launches.
- Cybersecurity validation costs:FDA premarket submission requirements for connected device security architecture demand specialized engineering talent scarce outside Boston and Tel Aviv clusters.
- Legacy imaging system integration:PACS interoperability with cloud-native AI diagnostic tools requires expensive middleware development for hospital IT departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Devices Market |
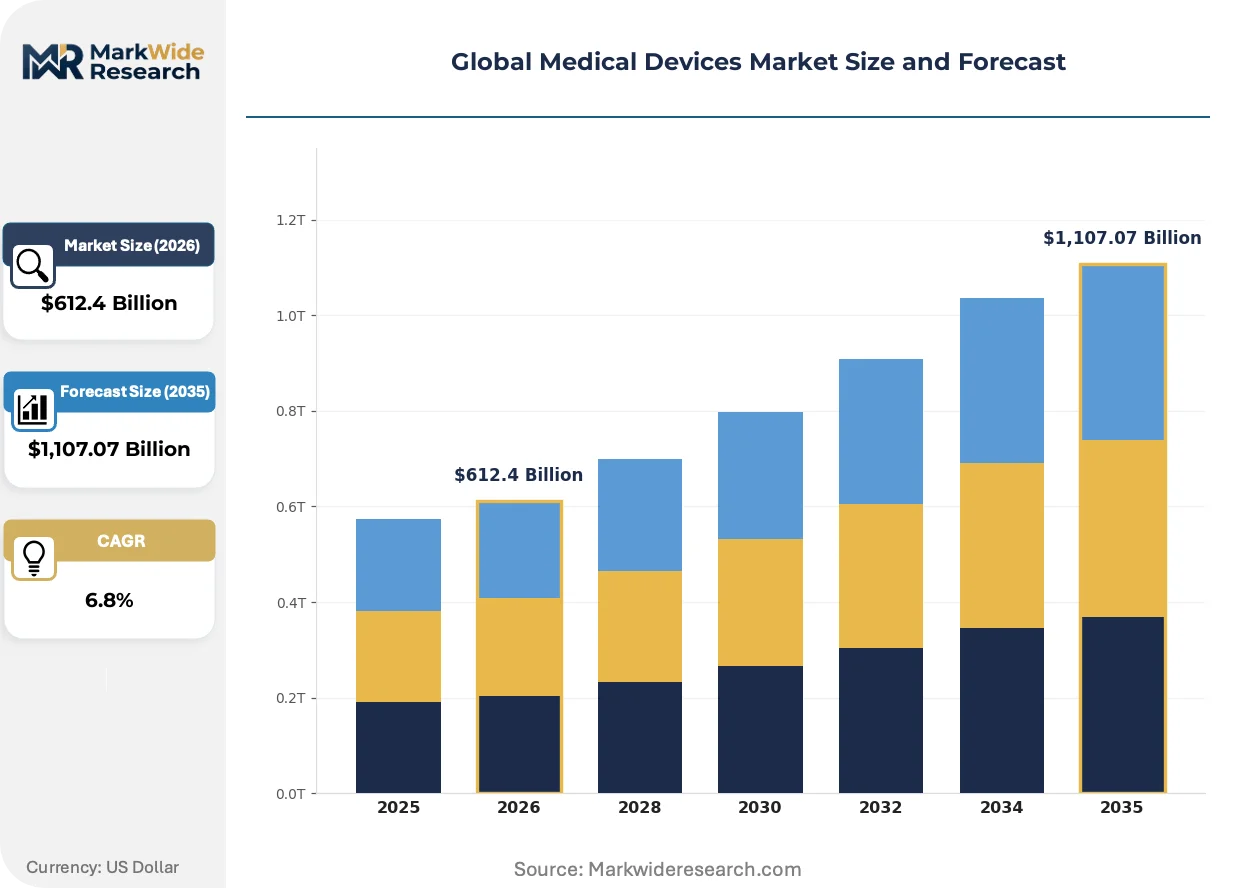
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,107.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Surgical Instruments, Monitoring Devices, Imaging Systems End User: Hospitals, Clinics, Home Care, Research Facilities Technology: Wearable Devices, Robotic Surgery, Telemedicine, 3D Printing Application: Cardiology, Orthopedics, Neurology, Urology |
| Companies Covered | Medtronic, Johnson & Johnson MedTech, Siemens Healthineers, Abbott, Stryker, GE HealthCare, Royal Philips, Boston Scientific, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Devices Market Strategic Shifts
Computational biomarker analysis and miniaturized sensor architectures are compressing diagnostic workflows while expanding the treatable patient population outside clinical settings. These converging capabilities are dissolving traditional boundaries between acute care and continuous monitoring.
Embedded machine learning inference engines are digitizing point-of-care diagnostic workflows by enabling real-time pattern recognition in handheld ultrasound and ECG devices. Emergency departments and rural clinics are deploying these tools to reduce specialist referral bottlenecks. The technology is digitizing how frontline clinicians access specialist-grade interpretive capabilities without physical infrastructure investment.
REACH substance restrictions and the EU Green Deal circular economy mandates are forcing medical device manufacturers to requalify polymer formulations and sterilization methods. Industrial consequence includes accelerated substitution of phthalate plasticizers and single-use instrument redesign for reprocessing compatibility. Electromechanical implantable devices face the steepest compliance burden as battery chemistry disclosure requirements intensify.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, compressing vendor margins on imaging and surgical robot installations. Third-party independent service organizations are capturing preventive maintenance revenue previously retained by original manufacturers. This disintermediation is most visible in German and Dutch hospital systems where centralized purchasing cooperatives dominate capital allocation.
Global Medical Devices Market Segmentation
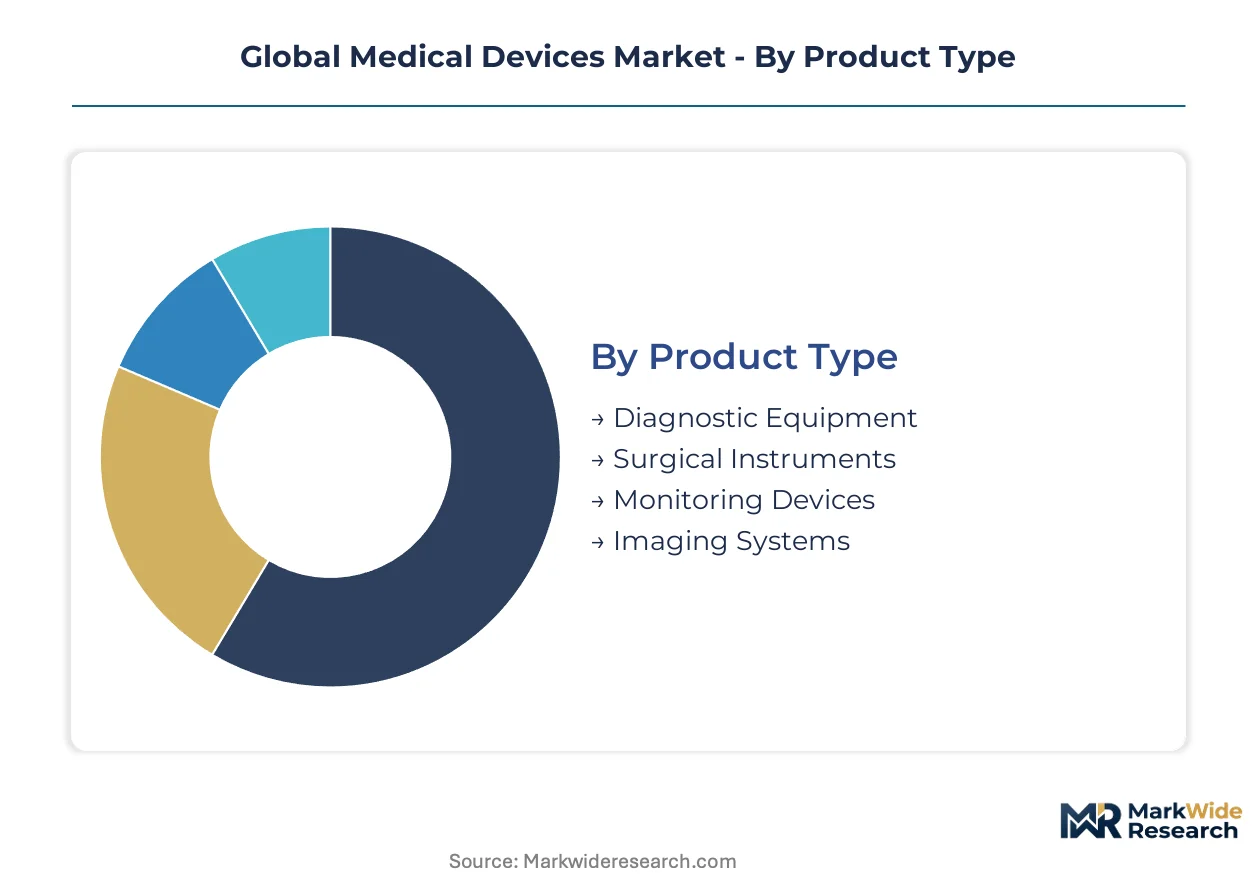
Medical device segmentation reveals how clinical workflows, reimbursement pathways, and regulatory frameworks reshape purchasing authority across care settings. Understanding these divisions exposes where hardware margins concentrate versus where software and service revenue pools are forming.
Product Type:
Clinical utility spans acute intervention, chronic surveillance, and preventive screening, with capital intensity and replacement cycles varying dramatically across these functional roles.
- Diagnostic Equipment:Benchtop analyzers and point-of-care testing platforms process biomarker detection, immunoassay, and molecular diagnostics. Demand clusters in hospital central laboratories and outpatient reference networks as health systems prioritize early disease detection protocols.
- Surgical Instruments:Electromechanical cutters, staplers, and energy devices enable minimally invasive access across laparoscopic and open procedures. German and Japanese hospital procurement cooperatives are unbundling service contracts from capital purchases, compressing vendor margins on installation bases.
- Monitoring Devices:Continuous physiologic trackers for glucose, cardiac rhythm, and respiratory function.
- Imaging Systems:MRI, CT, and ultrasound modalities with replacement cycles tied to hospital capital budgets.
The dominant share belongs to Diagnostic Equipment, while Monitoring Devices is closing the gap fastest.
End User:
Purchasing authority shifts from centralized hospital supply chains toward distributed patient-managed acquisition as reimbursement codes expand for remote therapeutic monitoring.
- Hospitals:Integrated delivery networks with capital committees governing imaging and surgical robot procurement.
- Clinics:Outpatient facilities prioritizing point-of-care diagnostic throughput.
- Home Care:Wearable monitors and portable therapeutic devices for residential disease management. United States CMS coding expansions for continuous glucose and cardiac surveillance are accelerating patient-direct purchasing outside institutional procurement channels.
- Research Facilities:Academic medical centers and contract research organizations driving preclinical device validation.
Hospitals retain the largest procurement volume, though Home Care is expanding most quickly as digital health infrastructure scales.
Technology:
Engineering maturity separates proven platforms with established reimbursement from emerging modalities still navigating clinical evidence requirements.
- Wearable Devices:Skin-adherent biosensors and wrist-worn health trackers capturing continuous physiologic data streams.
- Robotic Surgery:Computer-assisted instrument positioning with haptic feedback and tremor filtration. Premium pricing and long procedure learning curves concentrate adoption in United States academic medical centers and Japanese tertiary hospitals with dedicated training programs.
- Telemedicine:Remote consultation platforms integrating diagnostic peripherals for virtual specialist access.
- 3D Printing:Patient-specific implant fabrication and surgical guide production from DICOM imaging datasets.
Robotic Surgery commands the highest capital investment per unit, while Wearable Devices is gaining share fastest through consumer-direct and prescription channels.
Application:
Therapeutic area specialization determines regulatory pathway complexity, with cardiovascular and orthopedic segments benefiting from mature predicate device libraries.
- Cardiology:Rhythm management devices, interventional catheters, and hemodynamic monitors. PMDA clinical evidence requirements in Japan compress Asian market entry timelines for novel electrophysiology technologies.
- Orthopedics:Joint reconstruction implants, spinal fixation systems, and arthroscopic instruments.
- Neurology:Deep brain stimulators, seizure monitoring systems, and cerebrovascular intervention devices.
- Urology:Endoscopic visualization systems, stone management tools, and continence restoration implants.
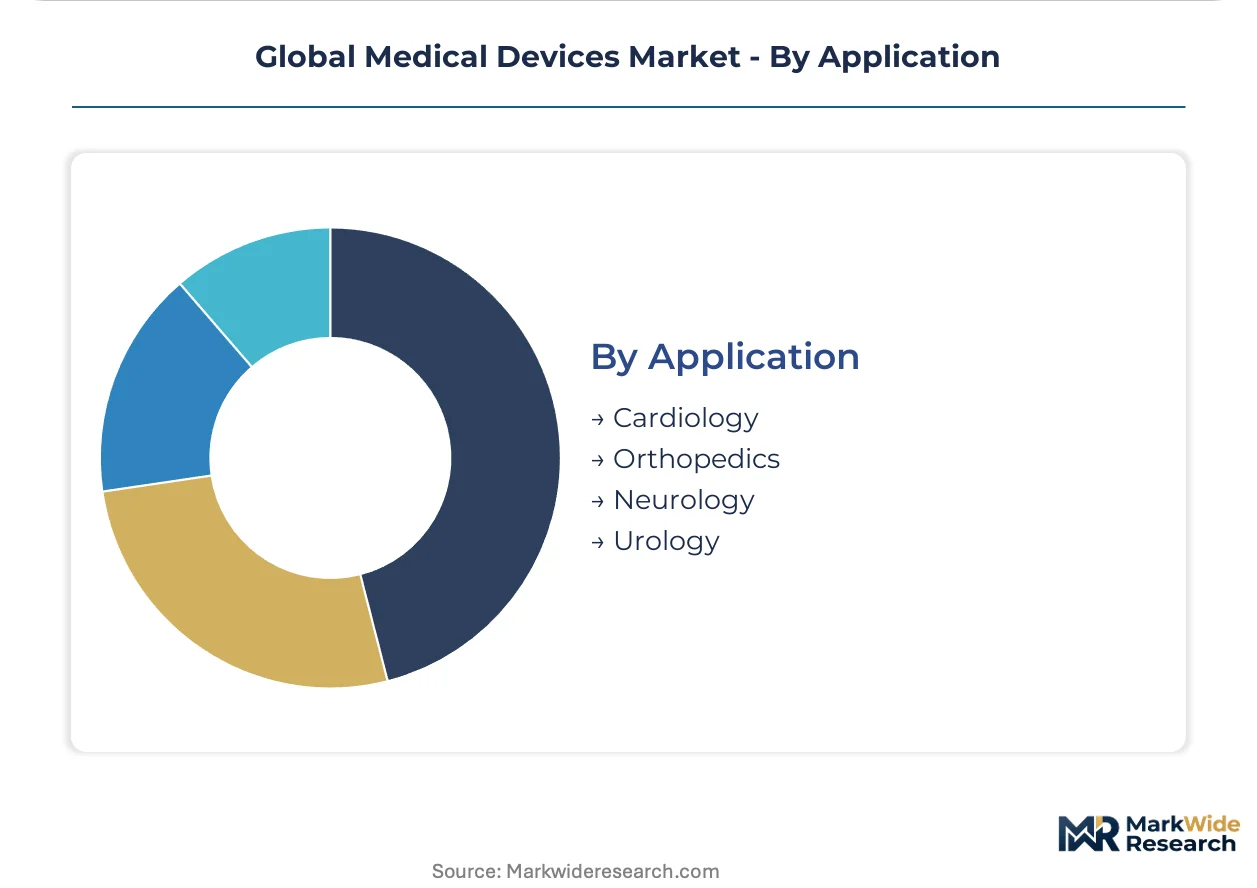
Cardiology holds the dominant revenue position, while Neurology is climbing the fastest as aging populations expand addressable patient populations for movement and cognitive disorders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals deploy cardiac rhythm monitors and surgical robots at triple the per-capita rate of German facilities, while Japanese clinics concentrate investment in compact imaging systems optimized for constrained physical footprints.
United States
Integrated delivery networks in Texas and Florida are consolidating procurement authority for imaging systems and surgical platforms. CMS reimbursement code expansions for remote therapeutic monitoring accelerate patient-direct purchasing of continuous glucose and cardiac surveillance devices. The Minneapolis-St. Paul corridor anchors cardiac rhythm management device engineering and manufacturing.
Germany
Hospital purchasing cooperatives in North Rhine-Westphalia and Bavaria are unbundling service contracts from capital equipment acquisitions, compressing vendor margins on installation bases. The EU MDR tightens conformity assessment requirements, privileging notified body-approved manufacturers with robust ISO 13485 quality management systems. The Baden-Württemberg cluster around Tübingen concentrates surgical instrument and endoscopy system production.
Japan
Tertiary hospitals in Tokyo and Osaka prioritize compact diagnostic equipment for space-constrained clinical environments. PMDA clinical evidence requirements impose extended trial timelines that compress Asian market entry windows for novel electrophysiology technologies. The Kobe biomedical cluster specializes in minimally invasive surgical device development and precision component manufacturing.
China
Provincial hospital networks in Jiangsu and Guangdong are scaling procurement of domestic-brand imaging and monitoring equipment under centralized bulk purchasing programs. NMPA regulatory harmonization with international standards accelerates market authorization for imported predicate devices. The Suzhou industrial park concentrates contract manufacturing for catheter and implantable component production.
Brazil
Private hospital chains in São Paulo and Rio de Janeiro are expanding surgical robot and advanced imaging system installations. ANVISA pathway acceleration for FDA- and CE-marked devices opens Latin America's largest healthcare market to streamlined commercialization. The São Paulo metropolitan area anchors regional distribution and technical service operations for multinational device manufacturers.
Global Medical Devices Market Competitive Environment
Capability concentration sits with diversified conglomerates possessing integrated digital platforms; scale advantage sits with specialized manufacturers commanding narrow but deep product portfolios. The vendor base organizes around three strategic archetypes: diversified health technology conglomerates with service-anchored revenue models, mid-cap specialists with category-dominant positions in orthopedics or cardiovascular, and emerging platform players commercializing AI-embedded diagnostic workflows. Competitive moves center on aftermarket service contract capture and software-enabled recurring revenue attachment to hardware installations.
Within the diversified conglomerate tier, Medtronic and Johnson & Johnson MedTech exemplify the service-revenue transition, anchoring margin profiles through long-term monitoring platform contracts and digital analytics integration. Siemens Healthineers occupies a position representing the imaging-system incumbent archetype, with business model evolution tied to predictive maintenance and workflow software attachment. These three entities collectively illustrate how installed base scale translates into recurring revenue capture across cardiac, surgical, and diagnostic domains.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson MedTech |
| Siemens Healthineers |
| Abbott |
| Stryker |
| GE HealthCare |
| Royal Philips |
| Boston Scientific |
| BD |
| Others |
Value Chain & Pricing Dynamics
The Suzhou industrial park anchors catheter and implantable component manufacturing capacity, with contract manufacturers there translating polymer supply concentration into asymmetric pricing power for tubing and electrode assemblies. Downstream device OEMs absorb cost volatility through long-term offtake agreements while spot-market exposure concentrates in single-use consumables.
Pricing Analysis
Long-term service contracts dominate capital equipment transactions, with imaging and surgical robot vendors bundling preventive maintenance into multi-year offtake structures. Price differentiation hinges on FDA breakthrough device designation and ISO 13485 certification tier, with premium tiers commanding margins through remote monitoring software attachment. Cost compression in mid-range diagnostic equipment intensifies as hospital purchasing cooperatives unbundle service obligations from hardware acquisition. Price sensitivity peaks among outpatient clinics in competitive metropolitan markets, while integrated delivery networks in concentrated hospital systems exhibit lowest elasticity due to switching costs.
Supply Chain Analysis
Flex, Jabil, and Benchmark Electronics hold concentrated contract manufacturing capacity for electromechanical surgical instruments and monitoring device assemblies. Supply draws from China, Mexico, and Malaysia for final assembly, with critical dependencies on South African platinum group metals for implantable electrodes and Northeast Asian medical-grade silicone for catheter production. Single-source vulnerability in polymer feedstock creates exposure to REACH substance restriction compliance timelines. Distribution runs through group purchasing organizations and regional distributors serving hospital systems, with direct-to-patient channels emerging for home care monitoring devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote patient monitoring reimbursement expansion signals early-cycle penetration acceleration, with CMS coding creating sustainable revenue models outside institutional procurement channels.
For Market Incumbents: Harden installed base retention through predictive maintenance platform deployment and ISO 13485 auditor capacity pre-commitment. Consolidate service contract capture against third-party independent service organization encroachment in German and Dutch hospital systems. Prioritize backward integration into battery chemistry supply for implantable devices facing EU Green Deal circular economy mandates. For New Entrants and Emerging Players: Build out AI-embedded surgical navigation capabilities targeting academic medical centers in Texas and Florida with dedicated training program infrastructure. Brazil's ANVISA pathway acceleration offers the most penetrable regulatory entry point for FDA- and CE-marked predicate devices. Pursue hospital system partnership models that bundle software analytics with hardware placement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform players with recurring revenue attachment to hardware installations over pure-play device manufacturers. Five-to-ten year viability hinges on digital service revenue ratio expansion and remote monitoring platform scale. Monitor CMS reimbursement code expansion velocity for continuous glucose and cardiac surveillance as inflection indicator for home care channel acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment acceleration privileges notified body-approved manufacturers with robust quality systems. |
| Hospital System Partnership | Integrated delivery networks in Texas consolidate procurement authority for imaging and surgical platform installations. |
| Software Companion Development | Embedded machine learning inference engines digitize point-of-care diagnostic workflows in emergency departments. |
| Reimbursement Strategy | CMS coding expansions create sustainable revenue models for continuous glucose and cardiac rhythm surveillance. |
| FDA Submission | Premarket notification pathways for connected devices demand cybersecurity validation architecture from specialized engineering clusters. |
Study Parameters
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers and secondary validation through FDA filings, CMS Medicare reimbursement databases, and hospital procurement records anchors the qualitative findings. Clinicians and regulatory affairs leads at notified bodies provided perspective on EU MDR implementation timelines. Bottom-up segmentation modeling triangulates against top-down market sizing from trade data and capital expenditure disclosures.
Calibration against historical replacement cycles and capital budget elasticity informs the analytical framework across the projection horizon. Segmentation dimensions span product type, end user setting, technology maturity, and therapeutic application area. CAGRs derive from installed base expansion rates, reimbursement pathway velocity, and regulatory approval timeline distributions. Forecast inputs incorporate platinum group metal price volatility coefficients and polymer supply concentration risk premiums.
Stress conditions across FDA premarket review duration, notified body auditor capacity constraints, and CMS coding expansion velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding digital health infrastructure investment continuity and remote monitoring reimbursement sustainability. Quarterly review of hospital capital committee procurement patterns and GPO contract renewal rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Laser Cutting Device Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Massage Equipment Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Toe Fixation System Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Medical Fiber Optics Market