
 Global Microelectronic Medical Implants Market | 2026-2036
Global Microelectronic Medical Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microelectronic Medical Implants Market Foresight
Silicon-on-insulator substrates is rebalancing cost-performance tradeoffs in implantable signal processors. Medtronic leverages captive wafer supply agreements to secure semiconductor capacity for its pacemaker and neurostimulator lines. Abbott Laboratories anchors its cardiac rhythm portfolio through in-house fabrication of application-specific integrated circuits. Biotronik differentiates via German-engineered hermetic sealing technologies that extend device longevity in cardiac implants.
Microelectronic medical implants are implantable devices incorporating semiconductor-based circuitry, sensors, and wireless transceivers within biocompatible enclosures, typically operating at sub-milliwatt power budgets and communicating via inductive or radio-frequency coupling for telemetry and programming. These systems perform real-time physiological monitoring, electrical stimulation, or drug delivery control inside the human body. Neurostimulators command substantial margin pools as spinal cord and deep brain applications expand, while energy harvesting technologies represent the fastest-growing technology dimension as manufacturers eliminate transcutaneous battery replacement surgeries. Glycemic monitors face pricing pressure from continuous external alternatives, though fully implantable closed-loop artificial pancreas systems sustain premium positioning in diabetes management.
The FDA enforces Class III premarket approval pathways that mandate clinical evidence for novel implantable electronics, while the EU MDR requires notified body oversight and post-market surveillance systems for active implantable devices. Japan's PMDA applies parallel consultation tracks that compress review timelines for breakthrough-designated neuromodulation systems. Stakeholders must monitor reimbursement recalibrations in Germany, Japan, and the United States as health technology assessment bodies weigh cost-effectiveness of next-generation implantable therapies against conservative management protocols.
Market Dynamics
Silicon-on-insulator substrate shortages are forcing cardiac implant manufacturers into multi-year wafer supply commitments, fundamentally restructuring procurement relationships between device makers and foundry partners.
Growth Catalysts
- Breakthrough Device Designation:The FDA's accelerated pathway compresses commercialization timelines for novel neuromodulation platforms, reducing regulatory friction for spinal cord stimulator innovators.
- Japan:METI reimbursement reforms expand coverage categories for implantable cardiac monitors, broadening patient access to remote rhythm management.
- Energy Harvesting:Piezoelectric and thermoelectric scavenging technologies eliminate transcutaneous battery replacement surgeries, reducing lifetime healthcare costs.
Market Restraints
- Wafer Supply Concentration:Taiwan-based foundries control advanced SOI substrate fabrication, creating single-source vulnerability for pacemaker signal processors.
- EU MDR Transition Costs:Notified body capacity constraints extend recertification timelines for legacy active implantable devices, freezing product portfolios.
- External CGM Substitution:Continuous external glucose monitors capture Type 1 diabetes monitoring volume, compressing addressable market for implantable glycemic sensors.
Strategic Opportunities
- Closed-Loop Artificial Pancreas:Fully implantable insulin delivery systems with automated glucose-responsive dosing command premium positioning against external alternatives.
- India:CDSCO streamlined approval pathways for Class D active implantables create first-mover advantage for cardiac rhythm device entrants.
- AI-Enabled Predictive Stimulation:Machine learning algorithms integrated into neurostimulators enable adaptive therapy adjustment, differentiating next-generation platforms.
Industry Challenges
- Biocompatibility Engineering Talent:Hermetic sealing specialists with semiconductor packaging expertise command scarcity premiums, constraining R&D velocity.
- ISO 14155 Compliance Burden:Clinical investigation standards for active implantable medical devices extend study timelines and inflate development budgets.
- Legacy System Integration:New wireless telemetry protocols must maintain backward compatibility with installed programmer bases, limiting protocol innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microelectronic Medical Implants Market |
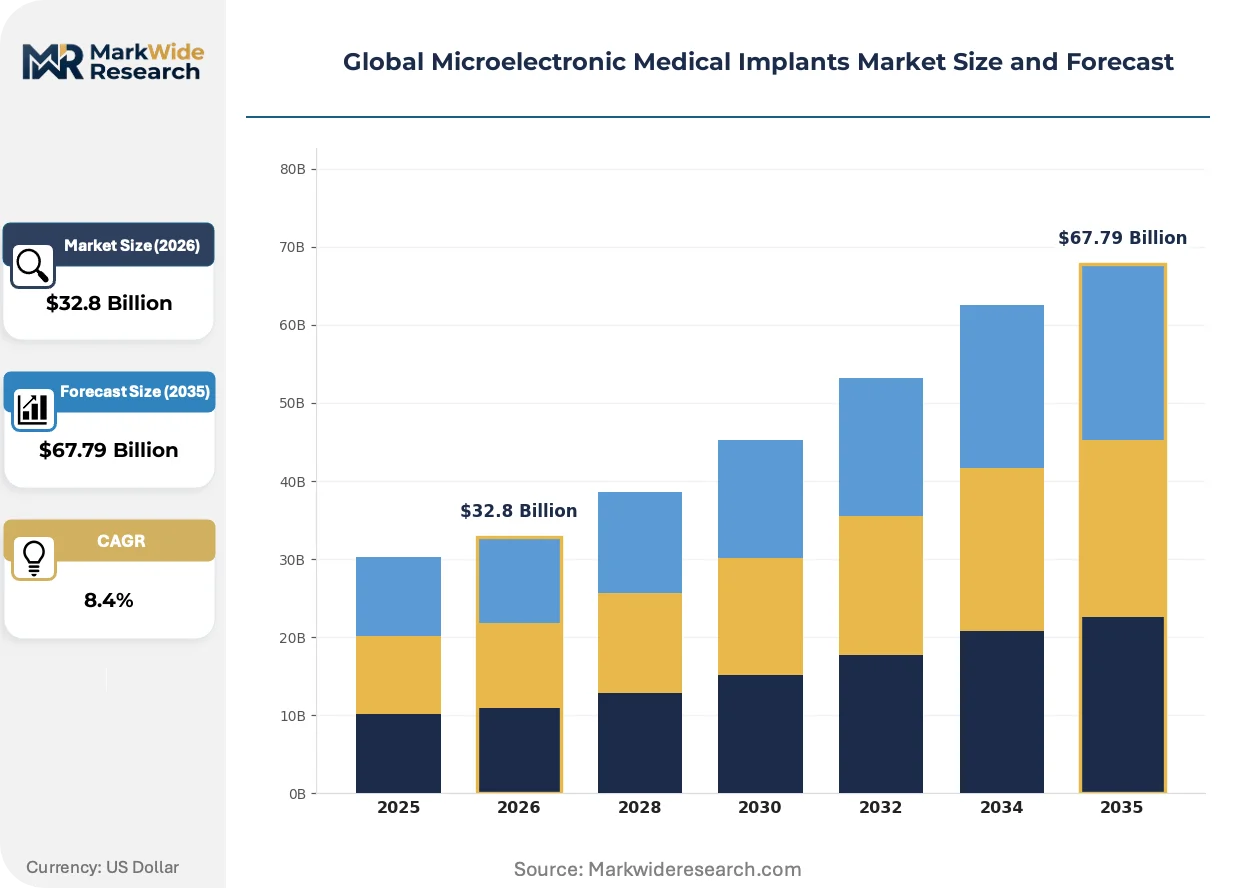
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulators, Cardiac Pacemakers, Cochlear Implants, Retinal Implants, Glycemic Monitors Technology: Wireless Communication, Biocompatible Coatings, Energy Harvesting, Miniaturization, Motion Sensors Application: Neurological Disorders, Cardiology, Auditory Rehabilitation, Ophthalmology, Diabetes Management End User: Hospitals, Specialized Clinics, Biomedical Research Institutes, Rehabilitation Centers, Implant Manufacturers |
| Companies Covered | Cochlear Limited, LivaNova PLC, Medtronic, Schiller AG, Zimmer Biomet, Abbott Laboratories, Biotronik, Sonova Holding AG, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microelectronic Medical Implants Market Shifts & Advancements
Neuromodulation platforms are absorbing sensing, processing, and stimulation functions into single-chip architectures, collapsing discrete component supply chains while demanding new competencies in mixed-signal design.
Machine learning inference engines embedded directly into implantable pulse generators are automating real-time therapy parameter adjustment. Deep brain stimulation programs at academic medical centers in Germany and the United States are piloting these adaptive systems. The technology is automating physician workload reduction while compressing revision surgery rates through predictive intervention.
The EU MDR's post-market surveillance requirements mandate active implantable device manufacturers maintain clinical follow-up registries spanning device lifetime. Manufacturers must fund extended patient monitoring infrastructure. Cardiac implant portfolios face the steepest compliance cost escalation as legacy devices require retrospective clinical data generation.
Hospital procurement committees are consolidating implantable device purchasing through single-source agreements with preferred manufacturers. Cardiology departments in Japan and the United States are negotiating multi-year volume commitments in exchange of guaranteed supply allocation and technical training support. Germany's hospital procurement centralization is accelerating this concentration, squeezing smaller device vendors from tender participation.
Global Microelectronic Medical Implants Market Segmentation
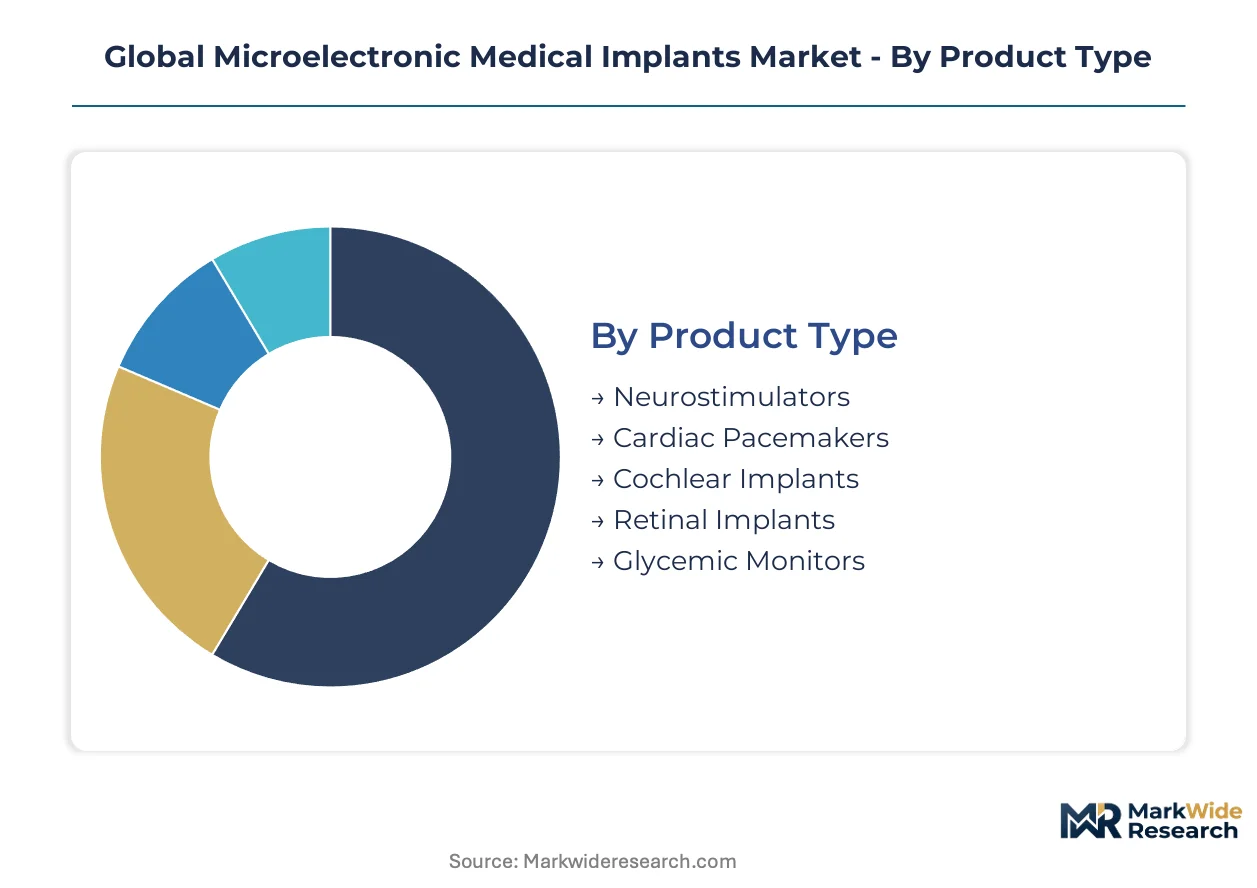
Segmentation in microelectronic medical implants reveals how semiconductor supply constraints and clinical specialization reshape competitive boundaries. Manufacturers configure product portfolios around wafer allocation priorities and reimbursement pathway viability rather than traditional anatomical categories.
Product Type:
Supply concentration in SOI wafer fabrication forces cardiac and neuromodulation manufacturers into divergent sourcing strategies with unequal bargaining leverage.
- Neurostimulators:Deep brain and spinal cord platforms integrate mixed-signal ASICs with hermetic titanium enclosures. Demand concentrates in Germany and the United States where academic medical centers pilot adaptive stimulation algorithms. The FDA's breakthrough designation accelerates commercial timelines for novel platforms.
- Cardiac Pacemakers:Sub-milliwatt signal processors with inductive telemetry dominate rhythm management. United States hospital systems expand electrophysiology programs as aging populations drive implant volume. Wafer supply commitments from Taiwan-based foundries constrain procurement flexibility.
- Cochlear Implants:Multi-channel electrode arrays with speech processing algorithms restore auditory function.
- Retinal Implants:Photodiode arrays with epiretinal or subretinal placement address degenerative vision loss.
- Glycemic Monitors:Fully implantable glucose sensors face substitution pressure from external continuous monitoring alternatives.
Today's leader: Cardiac Pacemakers. Tomorrow's challenger: Neurostimulators.
Technology:
Cost tiers separate legacy inductive systems from premium radio-frequency and energy-autonomous platforms with divergent lifetime value propositions.
- Wireless Communication:Inductive coupling dominates legacy telemetry while Bluetooth Low Energy and proprietary RF protocols enable smartphone connectivity. Japan's PMDA accelerates review for breakthrough-designated wireless neuromodulation systems. Backward compatibility requirements with installed programmer bases constrain protocol innovation.
- Energy Harvesting:Piezoelectric and thermoelectric scavenging eliminate transcutaneous battery replacement surgeries. Germany's hospital procurement centralization favors lifetime cost reduction through energy-autonomous designs. These systems command premium positioning against conventional battery-dependent alternatives.
- Biocompatible Coatings:Parylene and diamond-like carbon films reduce fibrotic encapsulation.
- Miniaturization:System-in-package integration collapses discrete component footprints.
- Motion Sensors:Accelerometers enable activity-responsive therapy adjustment.
Energy Harvesting expands most quickly; Wireless Communication retains installed base dominance.
Application:
Volume concentration in cardiology and neurology leaves auditory and ophthalmic applications as specialized niches with distinct regulatory pathways.
- Cardiology:Rhythm management and heart failure therapy absorb the majority of implantable electronic volume. United States reimbursement frameworks support remote monitoring with automatic alerts. Hospital procurement committees consolidate purchasing through multi-year single-source agreements.
- Neurological Disorders:Deep brain stimulation for Parkinson's disease and spinal cord stimulation for chronic pain command substantial margin pools. Germany's academic medical centers lead adaptive algorithm pilot programs. METI reimbursement reforms in Japan expand coverage for implantable cardiac monitors with neurological comorbidity tracking.
- Auditory Rehabilitation:Cochlear implant programs concentrate in pediatric and adult post-lingual deafness.
- Ophthalmology:Retinal prostheses address age-related macular degeneration and retinitis pigmentosa.
- Diabetes Management:Closed-loop artificial pancreas systems sustain premium positioning against external continuous glucose monitors.
Cardiology anchors current volume. Neurological Disorders gain share fastest through adaptive stimulation differentiation.
End User:
Customer type stratification separates high-volume hospital systems from research-driven early adoption at academic institutes and manufacturers' captive clinical trial networks.
- Hospitals:Integrated delivery networks in the United States and Germany centralize implantable device procurement through value-based purchasing agreements. Cardiology departments negotiate guaranteed supply allocation and technical training support. EU MDR post-market surveillance requirements mandate extended patient monitoring infrastructure.
- Specialized Clinics:Ambulatory surgery centers focus on high-volume rhythm device implants with rapid discharge protocols. Japan's clinic-based electrophysiology programs expand as METI reforms broaden remote monitoring reimbursement. These facilities prioritize devices with simplified programmer interfaces.
- Biomedical Research Institutes:Academic medical centers pilot next-generation adaptive algorithms and closed-loop systems.
- Rehabilitation Centers:Auditory and mobility-focused facilities manage cochlear and neurostimulator patient onboarding.
- Implant Manufacturers:Captive clinical trial networks generate premarket approval data under ISO 14155 standards.
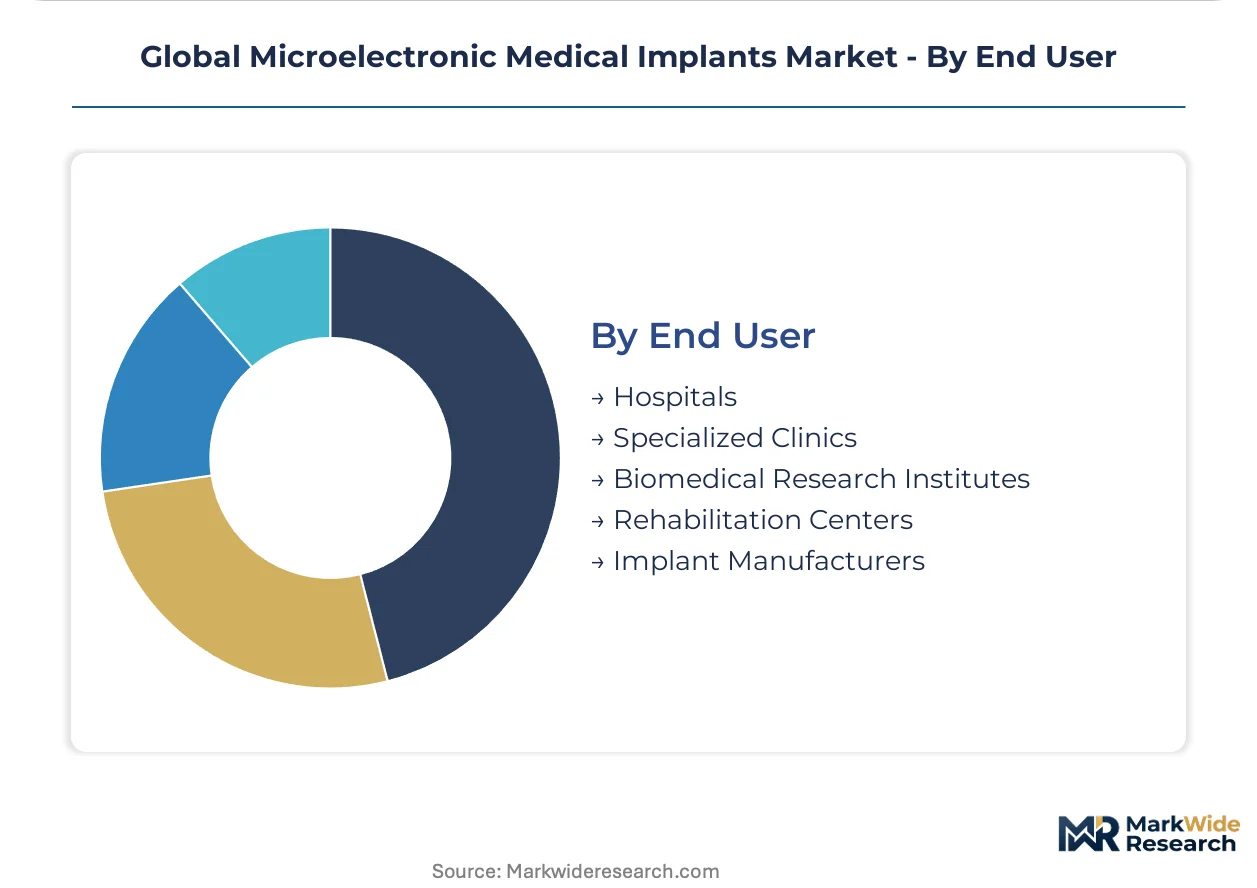
Hospitals dominate procurement volume. Specialized Clinics represent the steepest expansion trajectory through ambulatory site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minnesota's Twin Cities corridor anchors global neurostimulator and pacemaker production, with Medtronic's headquarters driving concentrated R&D employment and supplier clustering across the Upper Midwest.
United States
Hospital systems in the United States expand electrophysiology programs as aging populations require rhythm management devices. The FDA's breakthrough device designation pathway accelerates commercial timelines for novel neuromodulation platforms. The Minneapolis-Saint Paul metropolitan area concentrates cardiac implant engineering talent and captive wafer supply agreements.
Germany
Germany's academic medical centers pilot adaptive deep brain stimulation algorithms while hospital procurement centralization squeezes smaller vendors from tender participation. The EU MDR mandates notified body oversight and post-market surveillance systems for active implantable devices. The Berlin-Brandenburg corridor hosts Biotronik's hermetic sealing engineering operations.
Japan
Japan's aging demographic drives implantable cardiac monitor volume through clinic-based electrophysiology programs. METI reimbursement reforms expand coverage categories for remote rhythm management under PMDA parallel consultation tracks. The Kanto region around Tokyo concentrates distribution infrastructure for imported and domestically manufactured devices.
India
India's private hospital chains build electrophysiology capacity as cardiac disease burden rises among urban populations. CDSCO streamlined approval pathways for Class D active implantables create first-mover advantage for cardiac rhythm device entrants. Maharashtra's Mumbai-Pune pharmaceutical corridor attracts medical device assembly operations seeking export access.
Switzerland
Switzerland's precision manufacturing heritage supports microelectronic packaging for implantable signal processors. Swissmedic maintains rigorous premarket review standards that align with EU MDR technical documentation requirements. The Zurich- Basel corridor houses specialized hermetic sealing subcontractors serving European device manufacturers.
Global Microelectronic Medical Implants Market Competitive Landscape
Wafer supply commitments dominate the current landscape as cardiac and neuromodulation manufacturers lock in multi-year foundry agreements. The vendor base separates into integrated device manufacturers with captive semiconductor capacity, specialized neuromodulation platforms with breakthrough designations, and European hermetic sealing specialists. Three archetypes define positioning: scale-driven pacemaker producers, adaptive algorithm neuromodulation innovators, and component-integrated cochlear platforms. Capacity expansion and strategic partnerships represent the dominant competitive vectors as manufacturers secure silicon-on-insulator substrate allocation.
Among diversified medical technology conglomerates, Medtronic and Abbott Laboratories anchor the integrated manufacturer archetype through upstream control over application-specific integrated circuit fabrication. Boston Scientific Corporation occupies a position within the neuromodulation specialization tier, while Cochlear Limited exemplifies the auditory rehabilitation-focused segment. These three entities represent distinct strategic postures across cardiac rhythm management, adaptive neurostimulation, and sensory restoration applications without overlapping core technology emphasis.
| Leading Market Players |
|---|
| Cochlear Limited |
| LivaNova PLC |
| Medtronic |
| Schiller AG |
| Zimmer Biomet |
| Abbott Laboratories |
| Biotronik |
| Sonova Holding AG |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Performance-grade divergence between energy-autonomous implants and battery-dependent alternatives bifurcates procurement economics, with premium-tier manufacturers commanding multi-year wafer allocation commitments while standard-tier competitors face spot-market silicon pricing volatility. This tier separation manifests in divergent supply chain architectures: premium platforms anchor through captive foundry relationships in Taiwan and South Korea, whereas cost-optimized lines depend on merchant semiconductor distributors with quarterly repricing exposure.
Pricing Analysis
Input-cost pass-through from silicon-on-insulator wafer contracts governs implantable device pricing, with three-tier pricing structure across premium, standard, and economy levels anchored to hermetic sealing certification grades and battery longevity specifications. Price differentiation separates FDA breakthrough-designated neuromodulation platforms from legacy cardiac rhythm devices, with the latter experiencing cost compression from hospital procurement centralization in Germany and Japan. Buyers in India's private hospital chains exhibit highest price sensitivity, while United States integrated delivery networks prioritize lifetime value metrics over acquisition cost.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume cardiac implant demand from United States integrated delivery networks, while specialized clinics in Japan and Germany source through regional distributors with technical training bundling. Manufacturing concentrates in Taiwan for advanced SOI substrates, Germany for hermetic sealing components, and Switzerland for precision microelectronic packaging. Raw material dependencies span titanium biocompatible enclosures, platinum-iridium electrode alloys, and medical-grade parylene coatings. Single-source vulnerability in Taiwan-based foundry capacity for pacemaker signal processors represents the dominant structural risk, with distribution running through manufacturer-direct sales forces for tier-one hospital systems and authorized distributors for mid-tier facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA breakthrough device designations and EU MDR recertification mandates continuously reshape competitive viability and demand trajectories.
For Market Incumbents: Hedge against wafer supply concentration by diversifying foundry partnerships beyond Taiwan into South Korea and domestic United States facilities, while accelerating backward integration into application-specific integrated circuit design to reduce merchant semiconductor exposure. Defensive consolidation of hermetic sealing engineering talent through targeted acquisition of Swiss and German packaging specialists counters scarcity-driven R&D delays. Priority lever rests on securing multi-year hospital procurement agreements before EU MDR transition costs freeze competitor product portfolios. For New Entrants and Emerging Players: CDSCO streamlined approval pathways for Class D active implantables in India open a window for cardiac rhythm device market entry before incumbent volume commitments solidify. White-space targets include clinic-based electrophysiology programs in Japan's Kanto region and ambulatory surgery centers migrating from hospital-based implant procedures. Go-to-market angle emphasizes simplified programmer interfaces and remote monitoring compatibility to capture METI reimbursement reform tailwinds without legacy system integration burdens. For Investors and Strategic Acquirers: Asymmetric upside sits with adaptive algorithm neuromodulation platforms possessing FDA breakthrough designations and proprietary machine learning inference engines embedded in implantable pulse generators. Long-term viability over the projection horizon favors manufacturers with demonstrated ISO 14155 clinical investigation execution and established post-market surveillance infrastructure. Signal to watch: PMDA parallel consultation track approvals for energy-harvesting spinal cord stimulators as inflection indicator for next-generation platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates commercial timelines for novel neuromodulation platforms in spinal cord and deep brain applications. |
| CE Marking Pathway under EU MDR | Mandates notified body oversight and post-market surveillance systems for active implantable device market access. |
| Hospital System Partnership | Secures multi-year volume commitments through value-based purchasing agreements with United States integrated delivery networks. |
| Software Companion Development | Enables smartphone connectivity via Bluetooth Low Energy protocols for patient-facing remote monitoring interfaces. |
| Reimbursement Strategy | Aligns product positioning with METI reforms in Japan and CMS remote monitoring coverage determinations. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and Switzerland, with primary inputs from each market combining structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at active implantable device manufacturers. Secondary validation draws from FDA 510(k) and PMA filings, EUDAMED post-market surveillance databases, PMDA consultation track records, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up implant volume modeling triangulates against top-down market value estimates across the analysis window.
Granularity-level modeling disaggregates volume and value outputs by product type, technology tier, clinical application, and end-user facility category, with additional dimensioning by regional regulatory cluster and wafer supply commitment status. CAGRs derive from regression analysis of historical implant procedure volumes against demographic projections and reimbursement policy trajectories. Industry-specific forecast inputs include electrophysiology program expansion rates at United States hospital systems and METI coverage category recalibrations for remote rhythm management.
Revisions become necessary when Taiwan foundry capacity allocations shift, EU MDR notified body capacity constraints extend beyond current estimates, or external continuous glucose monitor substitution accelerates faster than artificial pancreas closed-loop adoption. Forecasts reflect documented assumptions regarding reimbursement stability and semiconductor supply normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Image-Based Cytometer Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Smart Stairlift Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Spherical IOL Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Chile Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Medical Connector Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Polymer-Based Prefilled Syringe Market