
 Wearable Medical Device Connectivity and Cybersecurity Test Systems Market | 2026-2036
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market Insights
Class III cybersecurity certification is redrawing procurement standards for wearable medical devices. Abbott leverages in-house protocol testing labs to accelerate FDA premarket submissions for continuous glucose monitors. Dexcom sustains technology leadership through specialized firmware emulation capabilities that validate encryption across Bluetooth Low Energy stacks. Samsung Electronics anchors its position by controlling end-to-end test environments for Wi-Fi and 5G health wearables.
Wearable medical device connectivity and cybersecurity test systems comprise calibrated instrumentation that validates radio frequency performance, protocol conformance, and vulnerability resistance in body-worn health monitors operating across multiple wireless standards. These systems measure packet error rates below 0.1 percent, simulate man-in-the-middle attacks against AES-256 implementations, and verify that biometric data streams maintain integrity during transmission to electronic health record platforms. Penetration testing tools and firmware emulators capture the deepest margin pools as device manufacturers face liability exposure from unpatched vulnerabilities in fielded units. Protocol analyzers for Bluetooth Low Energy and LTE-M represent the fastest-expanding technology dimension, driven by power-constrained cardiac and metabolic wearables that demand reliable low-bandwidth telemetry.
FDA premarket cybersecurity guidance, EU Cyber Resilience Act conformity requirements, and Japan's Ministry of Health, Labour and Welfare technical standards for connected medical devices collectively shape test system specifications and market access timelines. The EU AI Act adds algorithmic transparency mandates for diagnostic wearables that process data locally before transmission, expanding validation scope beyond connectivity alone. Stakeholders must monitor whether FDA will mandate third-party penetration testing as a 510(k) prerequisite rather than accepting manufacturer self-attestation.
Market Dynamics
FDA premarket cybersecurity guidance and the EU Cyber Resilience Act are compressing validation timelines for connected wearables, forcing test system vendors to automate protocol emulation and vulnerability scanning to match regulatory throughput demands.
Growth Catalysts
- EU Cyber Resilience Act conformity mandates:Device manufacturers must demonstrate pre-market cybersecurity validation, expanding third-party test system procurement across Germany, France, and the Netherlands.
- Remote patient monitoring program expansion:Hospital networks in the United States and Japan now require pre-certification of Bluetooth Low Energy-enabled cardiac wearables before reimbursement eligibility.
- LTE-M protocol proliferation:Power-constrained metabolic monitors for continuous glucose tracking drive demand for specialized protocol analyzers that validate low-bandwidth telemetry integrity.
Market Restraints
- Specialized RF instrumentation cost structure:Calibrated spectrum analyzers and vector network analyzers for millimeter-wave 5G health wearables carry capital intensity that excludes mid-tier test houses.
- Firmware emulation talent concentration:Embedded security specialists capable of AES-256 penetration testing cluster in Boston, Tel Aviv, and Munich, creating geographic supply bottlenecks.
- Regulatory fragmentation friction:Divergent FDA 510(k) cybersecurity documentation requirements and Japan PMDA technical standards force test system vendors to maintain parallel validation protocols.
Strategic Opportunities
- India CDSCO connected device pathway:The regulator's emerging framework for wireless medical device approval creates first-mover positioning for test vendors establishing local calibration laboratories.
- Edge AI diagnostic wearable convergence:On-device algorithm processing before data transmission expands validation scope to encompass ML model integrity alongside connectivity testing.
- Third-party penetration testing mandate speculation:FDA contemplation of mandatory external cybersecurity assessment for Class II wearables would displace manufacturer self-attestation models.
Industry Challenges
- Firmware reverse engineering skill scarcity:Test facilities struggle to recruit engineers proficient in ARM Cortex-M exploitation techniques for medical IoT vulnerability assessment.
- Multi-protocol stack integration complexity:Wearables combining Bluetooth Low Energy, NFC, and Wi-Fi 6 demand test systems capable of concurrent cross-protocol interference analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Medical Device Connectivity and Cybersecurity Test Systems Market |
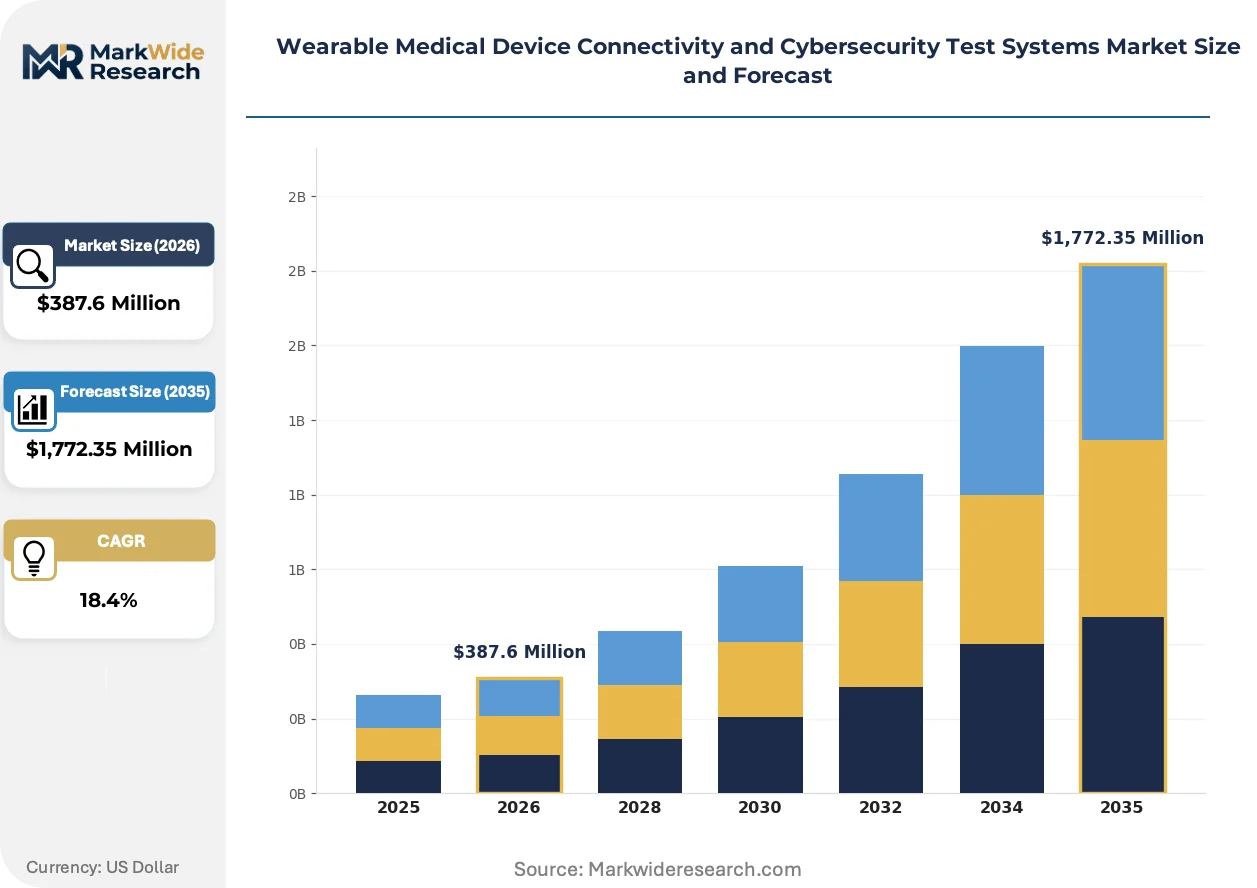
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Signal Analyzers, Network Simulators, Protocol Analyzers, Penetration Testing Tools, Firmware Emulators Technology: Bluetooth Low Energy, Wi-Fi, NFC, Zigbee, LTE-M, 5G Use Case: Data Transmission Testing, Encryption Validation, Threat Detection, Compliance Verification, Authentication Testing End User: Device Manufacturers, Testing Laboratories, Certification Bodies, Research Institutes |
| Companies Covered | Apple, Samsung Electronics, Abbott, Dexcom, Medtronic, Koninklijke Philips, GE HealthCare, OMRON, Boston Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market Trends and Innovations
Test system architecture is bifurcating between high-throughput automated validation platforms for large device OEMs and modular benchtop systems serving mid-tier manufacturers with heterogeneous protocol requirements.
Digital twin emulation for wireless medical devices is bifurcating test workflows by replacing physical device samples with firmware-in-the-loop simulation. Large CGM manufacturers in the United States adopt this approach to compress FDA pre-submission validation cycles. The technology is bifurcating capital allocation between hardware-based RF chambers and software-defined radio environments.
EU AI Act algorithmic transparency mandates are extending connectivity test scope to encompass local inference integrity in diagnostic wearables. Device manufacturers must now document how on-edge processing maintains decision audit trails before transmission. Cardiac arrhythmia detection wearables face the steepest compliance burden under these requirements.
Hospital procurement departments are consolidating vendor qualification around pre-certified test reports from accredited laboratories. This behavioral shift displaces direct manufacturer-to-health-system technical validation discussions. The United States exhibits the most pronounced concentration, with IDNs in Texas and California mandating third-party cybersecurity attestation as a contract prerequisite.
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market Segmentation
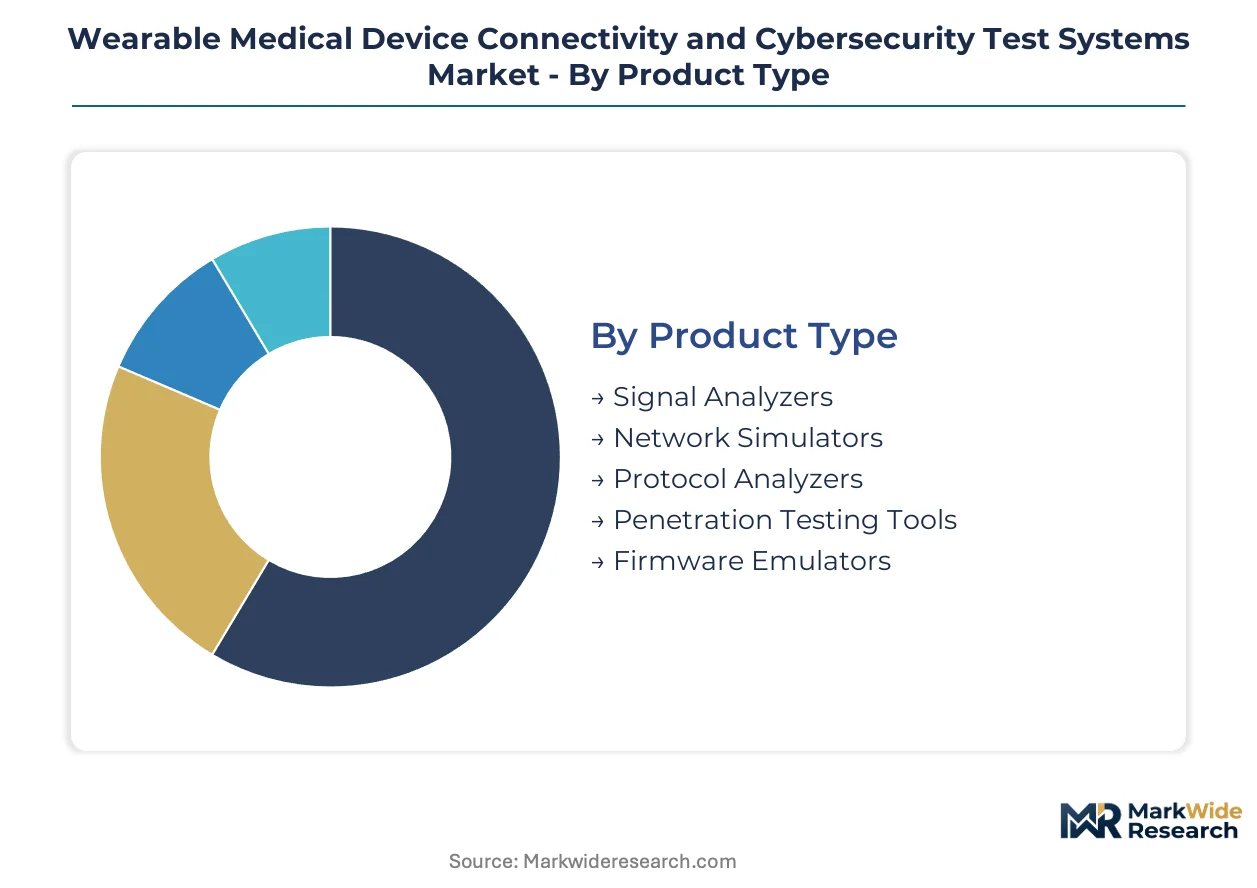
Test system procurement patterns diverge sharply across regulatory environments, with FDA premarket requirements, EU Cyber Resilience Act mandates, and Japan PMDA technical standards each favoring distinct instrumentation combinations. Segmentation reveals how compliance geography dictates capital allocation among device OEMs and third-party validation houses.
Product Type:
FDA 510(k) submissions for Class II wearables demand instrumentation depth that EU CE marking processes treat as optional, creating a two-tier equipment market.
- Penetration Testing Tools:Automated vulnerability scanners and manual exploit frameworks that probe AES-256 implementations in Bluetooth Low Energy stacks. Abbott and Dexcom procurement in the United States concentrates here as FDA cybersecurity guidance tightens premarket documentation requirements.
- Firmware Emulators:Software-defined environments that replicate ARM Cortex-M behavior without physical device samples. Samsung Electronics deploys these for 5G health wearable validation, compressing certification timelines by eliminating chamber-based RF testing for early design iterations.
- Signal Analyzers:Calibrated spectrum instrumentation measuring spurious emissions and occupied bandwidth across sub-6 GHz medical ISM bands.
- Network Simulators:Hardware-in-the-loop platforms that replicate LTE-M and 5G network conditions for metabolic monitor field behavior prediction.
- Protocol Analyzers:Packet capture systems verifying Bluetooth Low Energy and Zigbee stack conformance against IEEE and Bluetooth SIG specifications.
Penetration testing tools handle the majority of throughput; firmware emulators are the fastest mover on share.
Technology:
Power constraints in cardiac and glucose monitoring wearables favor low-bandwidth protocols, while diagnostic imaging peripherals exploit higher throughput standards.
- Bluetooth Low Energy:Dominant protocol for continuous glucose monitors and cardiac arrhythmia detectors, with 2.4 GHz ISM band operation demanding coexistence testing against Wi-Fi interference. United States hospital network procurement mandates pre-certification of BLE-enabled devices before reimbursement eligibility.
- LTE-M:Cellular IoT standard enabling direct cloud connectivity without smartphone tethering, critical for elderly patient monitors in Japan where smartphone penetration among users over 75 remains limited.
- Wi-Fi:Higher throughput protocol reserved for diagnostic wearables streaming multi-lead ECG data or ultrasound imaging.
- 5G:Millimeter-wave and sub-6 GHz bands supporting ultra-reliable low-latency communication for surgical robotics peripherals and remote procedure assistance.
- NFC:Near-field pairing and authentication for insulin pump-to-smartphone secure channel establishment.
- Zigbee:Mesh networking for in-hospital patient tracking badges and environmental sensors.
Bluetooth Low Energy dominates installed base; LTE-M is climbing the fastest as metabolic monitor manufacturers bypass smartphone dependency.
Use Case:
Validation scope expands beyond connectivity integrity to encompass algorithmic decision audit trails under EU AI Act diagnostic wearable mandates.
- Compliance Verification:Structured documentation of FDA 510(k) cybersecurity controls, EU Cyber Resilience Act conformity, and Japan PMDA technical standard adherence. German testing laboratories report this as their highest-margin service line given documentation intensity.
- Encryption Validation:Verification that biometric data streams maintain end-to-end integrity during transmission to electronic health record platforms.
- Data Transmission Testing:Packet error rate measurement below 0.1 percent thresholds under simulated interference conditions.
- Threat Detection:Man-in-the-middle attack simulation and anomaly behavior identification in fielded device firmware.
- Authentication Testing:Validation of secure pairing protocols and certificate chain integrity for wearable-to-gateway connections.
Compliance verification commands premium pricing; encryption validation is gaining share fastest as liability exposure from data breaches intensifies.
End User:
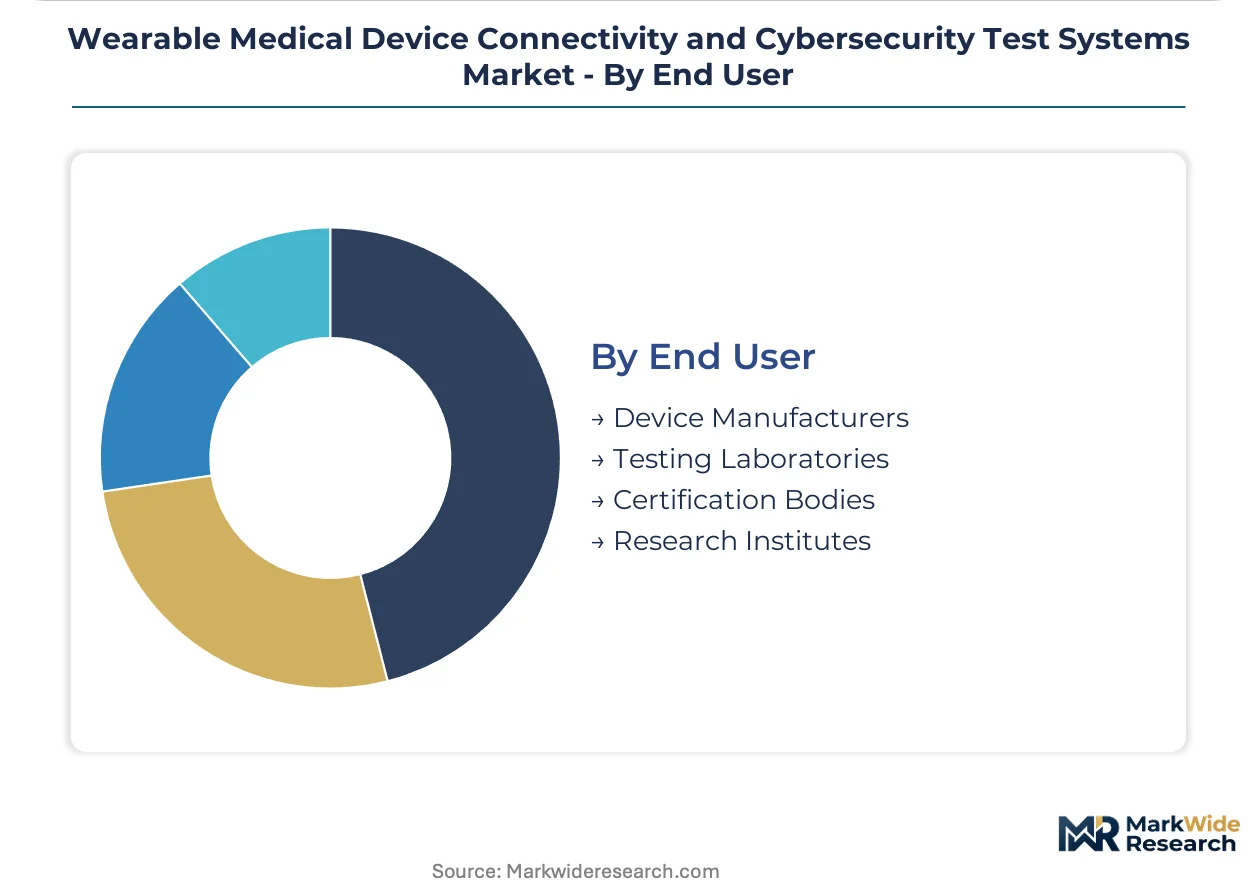
Procurement authority is shifting from device manufacturers to hospital network supply chain departments mandating third-party attestation.
- Device Manufacturers:Abbott, Dexcom, and Samsung Electronics maintain in-house protocol testing labs to accelerate regulatory submissions and protect proprietary firmware architectures.
- Testing Laboratories:Third-party validation houses in Boston, Tel Aviv, and Munich capture outsourced compliance work from mid-tier wearable OEMs lacking capital for calibrated RF instrumentation.
- Certification Bodies:Notified bodies under EU MDR and FDA-recognized accreditation organizations performing final conformity assessment before market authorization.
- Research Institutes:Academic medical centers and government laboratories developing next-generation wireless health standards and vulnerability assessment methodologies.
Device manufacturers retain the largest equipment footprint; testing laboratories are expanding fastest as procurement departments consolidate vendor qualification around external attestation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in Germany tolerate 40 percent test system cost premiums for EU Cyber Resilience Act pre-certification, while mid-tier device OEMs in India prioritize modular benchtop systems under fifteen thousand dollars. Japanese metabolic monitor manufacturers accept the highest calibration service fees globally.
United States
Abbott and Dexcom drive concentrated demand for FDA 510(k) cybersecurity validation suites. FDA premarket guidance on Bluetooth Low Energy encryption documentation tightens quarterly. Boston anchors penetration testing talent clusters serving cardiac wearable manufacturers.
Germany
Notified bodies under EU MDR process the highest volume of wireless medical device conformity assessments in Europe. EU Cyber Resilience Act implementation timelines compress validation windows for glucose monitor exports. Munich firmware emulation specialists command premium rates from mid-tier wearable OEMs.
Japan
PMDA technical standards for LTE-M cardiac monitors create specialized protocol analyzer demand among elderly care device suppliers. METI subsidies for remote patient monitoring infrastructure accelerate hospital network procurement. Tokyo testing laboratories expand capacity for 5G health wearable certification.
India
CDSCO's emerging connected device approval pathway attracts calibration laboratory investment from multinational test vendors. Domestic glucose monitor startups drive demand for affordable Bluetooth Low Energy conformance systems. Bengaluru medical IoT clusters source validation services from third-party testing houses.
United Kingdom
Post-MDR transition, UKCA marking requirements for wireless medical devices sustain test system procurement from NHS supply chain qualifiers. MHRA guidance on cybersecurity documentation aligns partially with EU standards. Cambridge firmware security specialists serve diagnostic wearable developers.
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with in-house protocol testing labs at large device OEMs setting performance benchmarks while third-party testing laboratories capture price-sensitive mid-tier validation work. The market structure bifurcates between integrated manufacturers maintaining captive testing capabilities and independent validation houses serving heterogeneous client bases. Three archetypes dominate: vertically integrated device OEMs with proprietary firmware emulation infrastructure, specialized third-party testing laboratories with accredited RF chambers, and modular test system vendors supplying benchtop equipment to distributed validation networks. Competitive moves concentrate on geographic laboratory expansion and automated protocol emulation software licensing.
Among vertically integrated device OEMs, Apple, Samsung Electronics, and Abbott occupy positions that exemplify the captive testing archetype, each maintaining in-house validation infrastructure to compress regulatory submission timelines and protect proprietary wireless stack implementations. These entities represent the technology leadership tier, where control over end-to-end test environments substitutes for third-party laboratory relationships. Their positioning anchors the premium segment of the competitive landscape.
| Leading Market Players |
|---|
| Apple |
| Samsung Electronics |
| Abbott |
| Dexcom |
| Medtronic |
| Koninklijke Philips |
| GE HealthCare |
| OMRON |
| Boston Scientific |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) cybersecurity documentation requirements and EU Cyber Resilience Act conformity mandates gate both supplier qualification and price differentiation simultaneously, compressing procurement timelines for device OEMs while elevating calibration service premiums for accredited test houses. Hospital network procurement departments now mandate third-party attestation as a contract prerequisite, shifting price-setting power toward validation laboratories with recognized accreditation.
Pricing Analysis
Calibration service contracts and extended warranty agreements drive lifetime value for test system vendors, with three-tier pricing structure across premium, standard, and economy levels separating FDA-recognized laboratories from regional validation houses. Price differentiation rests on certification tier and geographic proximity to device manufacturing clusters, with Boston and Munich specialists commanding premiums for firmware emulation expertise. Pricing pressure stems from mid-tier wearable OEMs sourcing modular benchtop systems under fifteen thousand dollars. Hospital procurement departments exhibit lowest price sensitivity; domestic glucose monitor startups in India show highest.
Supply Chain Analysis
Port congestion on trans-Pacific trade lanes elevates inbound logistics costs for calibrated RF instrumentation sourced from Germany, Japan, and the United States. Test system manufacturing draws from precision analog semiconductors, machined aluminum enclosures, and specialized coaxial cable assemblies. Single-source vulnerability concentrates in FPGA suppliers for software-defined radio platforms. Distribution runs through authorized distributors serving academic medical centers and third-party validation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable medical device connectivity and cybersecurity test systems represent a high-growth disruption as FDA premarket guidance and EU Cyber Resilience Act implementation compress validation timelines while expanding mandatory test scope beyond connectivity to algorithmic integrity.
For Market Incumbents: Fortify captive testing infrastructure through backward integration into firmware emulation software development, protecting proprietary wireless stack implementations from third-party exposure. Expand calibration laboratory footprint in Japan and Germany to capture EU MDR and PMDA conformity assessment volume before mid-tier competitors establish local presence. Prioritize automated protocol emulation licensing to hospital network procurement departments consolidating vendor qualification. For New Entrants and Emerging Players: Anchor in India's CDSCO emerging connected device approval pathway, where domestic glucose monitor startups drive demand for affordable Bluetooth Low Energy conformance systems. Target modular benchtop protocol analyzers for mid-tier metabolic monitor manufacturers lacking capital for full RF chamber infrastructure. Pursue go-to-market partnerships with Bengaluru medical IoT clusters seeking outsourced validation services. For Investors and Strategic Acquirers: FDA third-party penetration testing mandate speculation reshapes the acquisition landscape toward specialized testing laboratories with accredited RF chambers and firmware security expertise. Long-term viability centers on regulatory compliance services rather than equipment sales alone. Monitor FDA 510(k) cybersecurity guidance quarterly releases as inflection signal for mandatory external assessment displacement of manufacturer self-attestation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Cybersecurity Submission | Abbott accelerates continuous glucose monitor premarket clearance through in-house protocol validation. |
| EU CE Marking Pathway | Notified bodies under MDR process highest wireless medical device conformity assessment volume in Germany. |
| Hospital System Partnership | Texas and California IDNs mandate third-party cybersecurity attestation as contract prerequisite. |
| Software Companion Development | Dexcom firmware emulation capabilities validate encryption across Bluetooth Low Energy stacks. |
| Reimbursement Strategy | United States hospital networks require pre-certification before Bluetooth Low Energy device reimbursement eligibility. |
Research Methodology
Desk research of FDA 510(k) submission databases, EU MDR notified body registers, and Bluetooth SIG qualification listings preceded structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at device OEMs. Primary fieldwork combined with secondary validation against SEC filings of publicly traded test equipment vendors and CMS Medicare remote patient monitoring reimbursement data. Bottom-up equipment procurement estimates triangulated against top-down regulatory throughput projections.
Variance decomposition across product type, technology protocol, use case, and end user segments shaped the analytical framework over the projection horizon. CAGRs derived from regression against historical FDA submission volumes and EU Cyber Resilience Act implementation timelines. Modeled inputs included hospital network procurement mandate adoption curves and firmware emulation software licensing velocity.
Material uncertainties — FDA mandate timing for third-party penetration testing, EU AI Act algorithmic transparency enforcement intensity, Japan METI subsidy renewal for remote patient monitoring infrastructure — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance scope expansion and hospital procurement behavioral shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Plethysmograph Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Pocket Otoscope Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
Prefillable Inhalers Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Electromagnetic Navigation Bronchoscopy Market
Medical Devices
Near Vision Devices Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Catheter Systems Market
Medical Devices
Global Nebuliser Market