
 Global Occlusion Devices Market | 2026-2036
Global Occlusion Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Occlusion Devices Market Outlook
Germany is narrowing its import dependency for precision-manufactured occlusion implants through dedicated cleanroom expansions near Stuttgart and Tuttlingen. Boston Scientific Corporation leverages its integrated catheter-occluder platforms to control supply continuity across European cath labs. Medtronic anchors its structural heart portfolio with extensive clinical validation databases that sustain physician preference in high-volume centers. Abbott Laboratories differentiates through bioresorbable material research programs that target reduced long-term implant complications.
Occlusion devices are implantable or catheter-delivered instruments engineered from nitinol alloys, platinum-iridium coils, or polymeric matrices to achieve mechanical blockage of abnormal cardiac or vascular channels, typically deployed via 4–14 French delivery sheaths under fluoroscopic guidance. Coil occluders retain dominance in peripheral vascular applications where tortuous anatomy demands navigability, while plug occluders capture expanding share in septal defect closure due to conformable waist designs that reduce residual shunting. Balloon occluders occupy a mature utility role in temporary flow interruption during complex hybrid procedures, with margin pools shifting toward permanent implantable formats.
The FDA's Class III PMA pathway and the EU MDR's enhanced clinical evidence requirements for implantable cardiovascular devices are reshaping product development timelines and market access economics for manufacturers. Japan's PMDA enforces stringent biocompatibility testing protocols under JIS T 0301 that filter out lower-capability suppliers from its reimbursement-eligible device registry. Stakeholders must monitor evolving health technology assessment methodologies in major markets, as payers increasingly predicate coverage on randomized trial data demonstrating superiority to surgical closure alternatives.
Market Dynamics
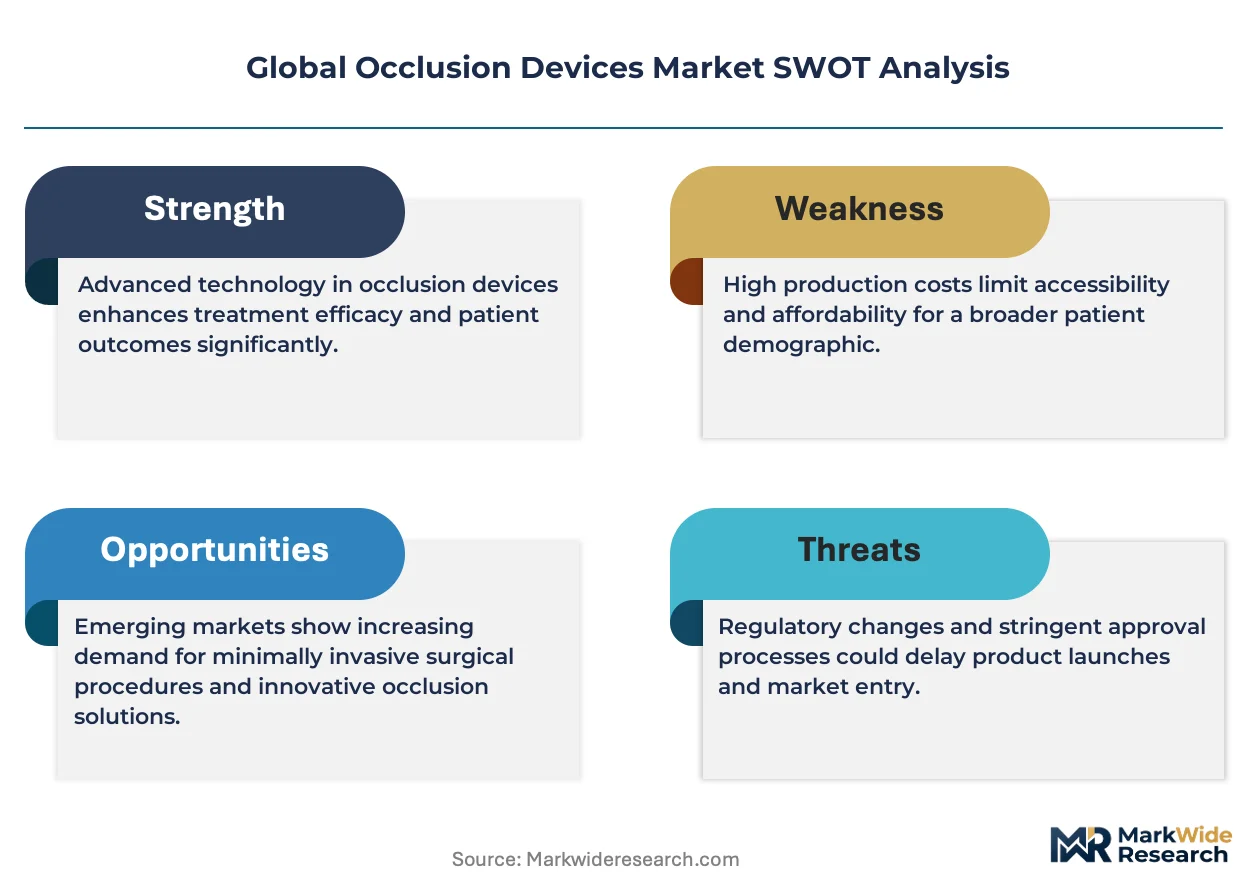
The FDA's breakthrough device designation pathway is compressing commercialization timelines for novel occluder architectures while EU MDR clinical evidence requirements simultaneously extend development cycles, creating asymmetric competitive pressure across regulatory jurisdictions.
Growth Catalysts
- Structural heart procedure expansion:Hospital systems in the United States, Germany, and Japan are dedicating capital to interventional suite construction, anchoring demand for catheter-delivered occlusion systems.
- EU MDR Article 61:Enhanced clinical evidence requirements for implantable cardiovascular devices are filtering marginal competitors, consolidating volume among validated manufacturers with robust PMCF infrastructures.
- Nitinol alloy advances:Superelastic wireform engineering is enabling lower-profile delivery sheaths that expand addressable anatomy in pediatric and elderly patient cohorts previously excluded from percutaneous closure.
Market Restraints
- Platinum-iridium coil cost volatility:Precious metal input fluctuations compress margin pools for peripheral vascular coil manufacturers without captive refining arrangements.
- Cleanroom concentration risk:Precision manufacturing for occlusion implants clusters in southern Germany and Tuttlingen, exposing supply continuity to localized infrastructure disruption.
- Japan PMDA JIS T 0301 biocompatibility protocols:Extended testing timelines for novel polymeric matrices delay market entry by 18-24 months relative to FDA PMA pathways.
Strategic Opportunities
- Bioresorbable material platforms:Research programs targeting polymeric matrices that eliminate long-term implant complications open premium positioning in pediatric septal defect closure where device longevity concerns dominate.
- India CDSCO regulatory harmonization:Emerging alignment with IMDRF standards is reducing duplicate clinical trial requirements, accelerating access to a cardiovascular procedure market with underpenetrated structural heart capabilities.
- Hybrid procedure integration:Temporary balloon occluder deployment during complex congenital repairs is converging with surgical planning software, creating bundled service models in high-volume cardiac centers.
Industry Challenges
- Fluoroscopy-trained interventionalist scarcity:Complex septal defect closure demands operators with 500+ structural heart procedures, constraining procedure volume expansion faster than fellowship pipelines can supply.
- EU MDR notified body capacity:Certification backlog for Class III implantable cardiovascular devices extends time-to-revenue by 12-18 months, freezing R&D amortization schedules.
- Legacy surgical closure preference:Established cardiac surgeons in mature markets retain institutional influence over referral patterns, slowing catheter-based adoption despite randomized trial equivalence data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Occlusion Devices Market |
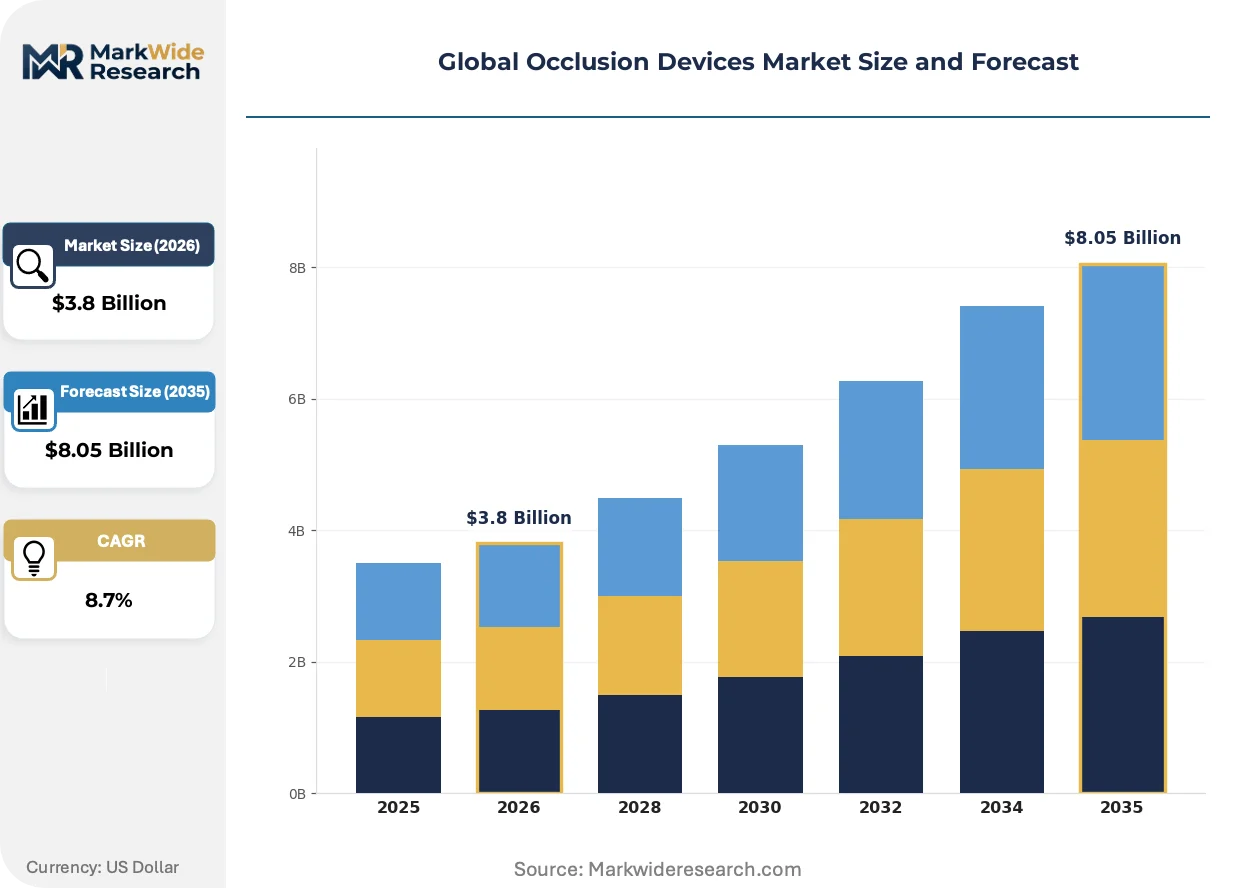
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Occluders, Stent Occluders, Coil Occluders, Plug Occluders End User: Hospitals, Clinics, Surgical Centers, Ambulatory Surgical Facilities Delivery Mode: Transfemoral, Transcatheter, Surgical, Endovascular Application: Atrial Septal Defect, Ventricular Septal Defect, Patent Foramen Ovale, Others |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott Laboratories, Johnson & Johnson, Stryker Corporation, Terumo Corporation, Cook Group, Edwards Lifesciences Corporation, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Occlusion Devices Market Strategic Shifts
Material science convergence with computational modeling is redefining occluder performance benchmarks, while regulatory pathway divergence between jurisdictions is fragmenting competitive timelines.
Shape-memory nitinol lattice engineering is hybridizing with patient-specific 3D-printed deployment guides. High-volume structural heart centers in Germany and Japan are adopting these integrated platforms within 18-month procurement cycles. The technology is hybridizing surgical planning with catheter-based execution, compressing the boundary between interventional and operative closure modalities.
EU MDR's Post-Market Clinical Follow-up requirements are mandating decade-long implant surveillance registries. Manufacturers must now architect data infrastructure capable of capturing real-world performance across distributed hospital networks. High-volume implanting centers in France and the Netherlands are consolidating purchasing around vendors with demonstrated PMCF execution capabilities, displacing smaller competitors lacking longitudinal data systems.
Hospital procurement committees are unbundling device procurement from procedure support services. Cardiology departments in the United States are negotiating direct-to-manufacturer contracts that exclude traditional distributor margins, replacing bundled offerings with transparent component pricing. This disintermediation is most visible in integrated delivery networks with captive cath lab operations across multiple states.
Global Occlusion Devices Market Segmentation
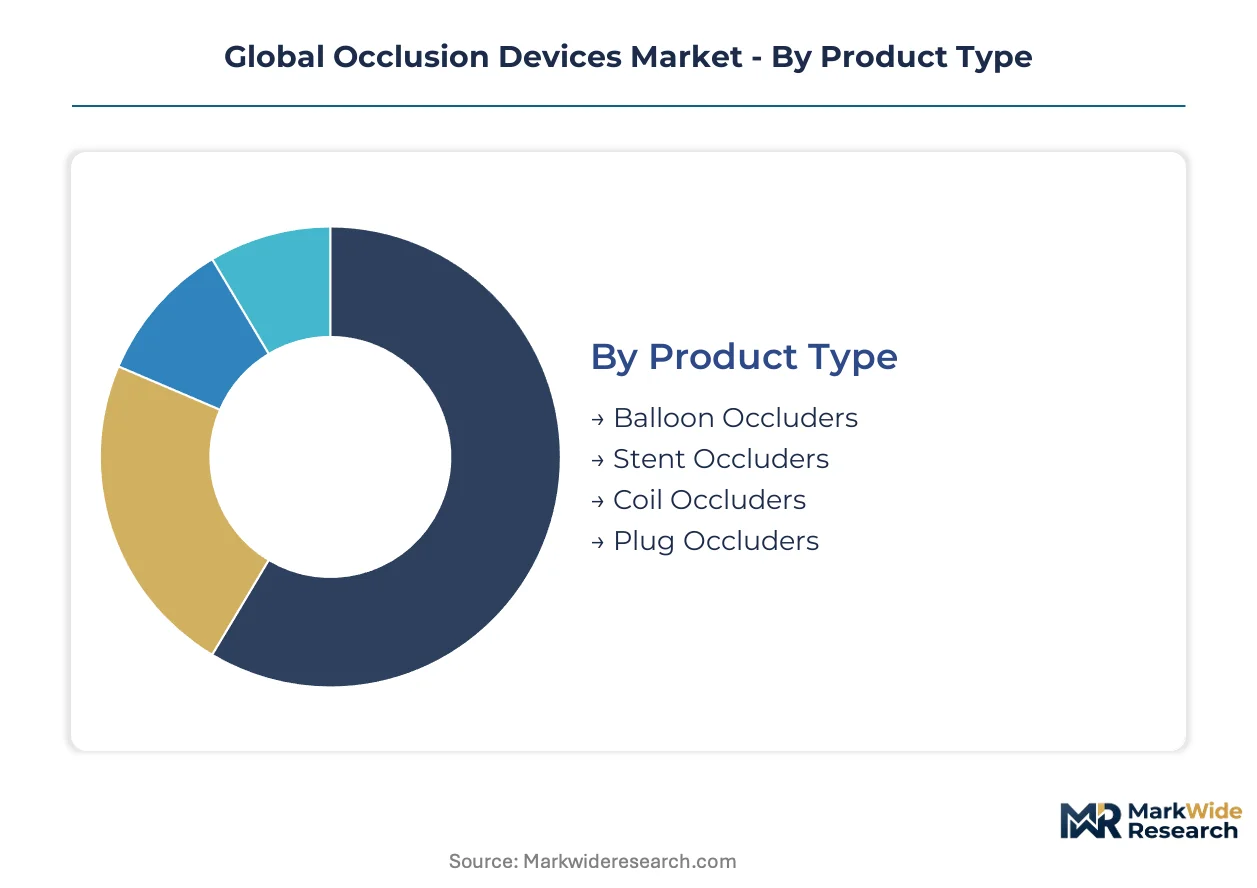
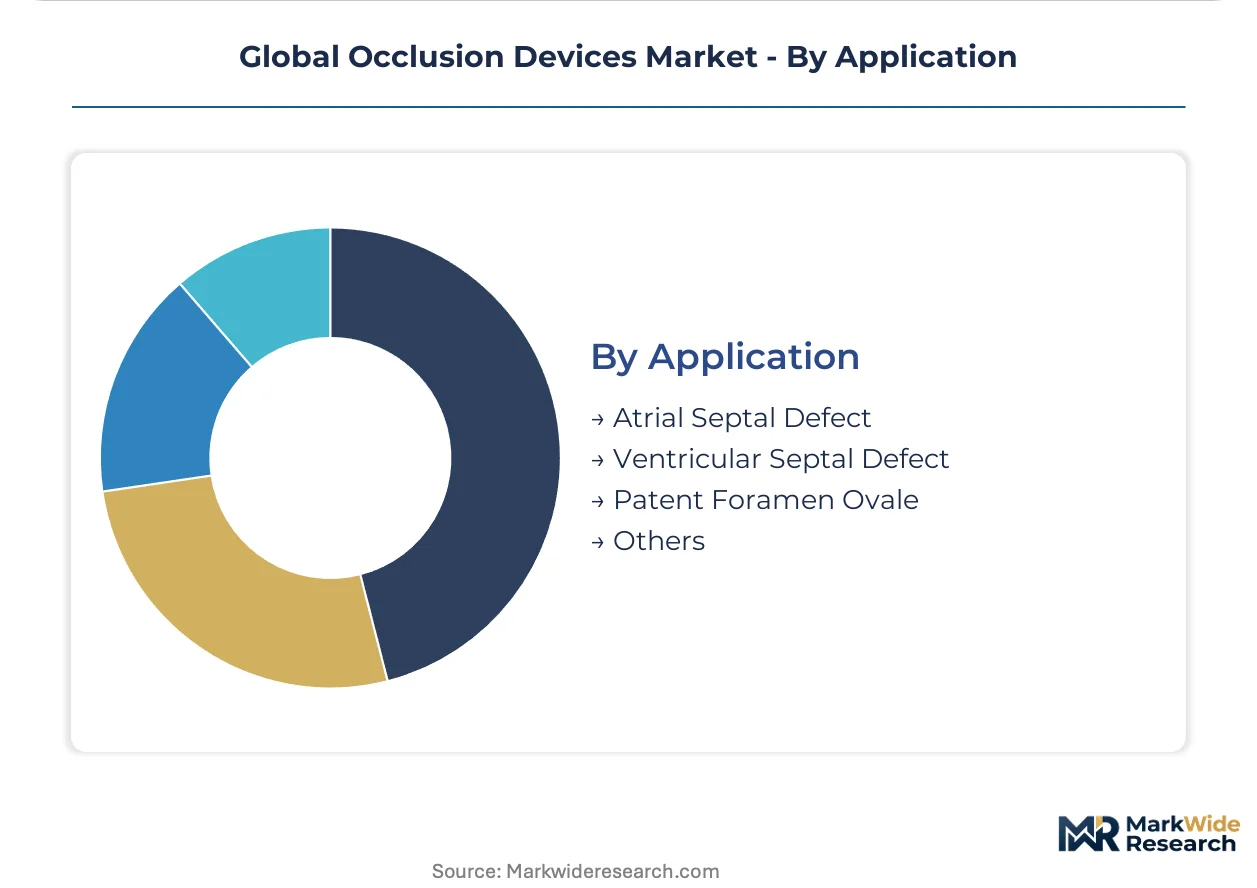
Product architecture and delivery modality determine reimbursement pathways and clinical training requirements across occlusion device categories. Segment-level demand patterns diverge sharply between emergency deployment scenarios and elective structural heart procedures.
Product Type:
Replacement cycles stretch from single-use balloon systems to decade-durable nitinol implants, creating divergent revenue recognition timelines for manufacturers.
- Coil Occluders:Platinum-iridium wire constructs deliver navigability through tortuous peripheral vasculature where plug geometries fail. Demand concentrates in United States interventional radiology suites treating pulmonary arteriovenous malformations, constrained by precious metal cost volatility.
- Plug Occluders:Nitinol mesh discs with conformable waists achieve residual shunt rates below 5% in septal defect closure. German hospital systems in Stuttgart and Tuttlingen regions anchor procurement volumes for pediatric and adult structural heart programs.
- Balloon Occluders:Temporary flow interruption during hybrid congenital repairs; mature utility role with margin compression toward commodity pricing tiers.
- Stent Occluders:Hybrid scaffold-occlusion platforms for complex ductal anatomy; limited commercial penetration outside Japan PMDA-approved indications.
Coil occluders anchor the volume base in peripheral vascular applications while plug occluders gain share at the steepest rate in septal defect closure.
End User:
Capital intensity and procedure reimbursement tiers stratify customer economics from integrated hospital networks to standalone ambulatory facilities.
- Hospitals:Integrated delivery networks in the United States negotiate direct manufacturer contracts bypassing distributor margins; interventional suite construction drives catheter-delivered occlusion system procurement.
- Ambulatory Surgical Facilities:Lower-acuity patent foramen ovale closures shift to outpatient settings where procedure volume economics favor streamlined plug deployment protocols.
- Surgical Centers:Hybrid congenital repair capabilities concentrate in high-volume cardiac centers combining temporary balloon occlusion with operative planning software.
- Clinics:Diagnostic and referral functions with limited procedural capacity; dependent on hospital-based interventionist networks.
Hospitals retain the dominant revenue share while ambulatory surgical facilities expand most quickly as payers migrate low-complexity closures to lower-cost settings.
Delivery Mode:
Access site selection determines fluoroscopy time, operator radiation exposure, and patient recovery trajectories across closure procedures.
- Transcatheter:Dominant approach for atrial septal defect and patent foramen ovale closure; 4–14 French sheath compatibility expands addressable anatomy in pediatric cohorts.
- Transfemoral:Standard venous access for septal procedures; femoral artery crossover required for certain ductal occlusions.
- Endovascular:Peripheral vascular coil deployment via microcatheter systems; demands specialized interventional radiology training.
- Surgical:Direct access for complex congenital repairs where catheter-based approaches fail; declining share as transcatheter indications expand.
Transcatheter delivery anchors procedural volume while endovascular approaches climb fastest as interventional radiology capabilities penetrate community hospital settings.
Application:
Defect anatomy and hemodynamic consequence determine device sizing requirements and long-term surveillance protocols.
- Patent Foramen Ovale:Cryptogenic stroke prevention drives volume; United States hospital systems expand interventional suites to capture migrainectomy and decompression sickness indications.
- Atrial Septal Defect:Secundum defects dominate occluder placement; German reimbursement frameworks support adult closure programs previously managed surgically.
- Ventricular Septal Defect:Muscular and perimembranous variants require specialized device geometries; constrained by operator scarcity in 500+ procedure-trained interventionalists.
- Others:Patent ductus arteriosus, coronary fistulae, and paravalvular leaks; fragmented indications with device-specific regulatory pathways.
Patent foramen ovale closure anchors the volume base while atrial septal defect applications show the steepest expansion trajectory as adult diagnostic screening penetrates aging populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision manufacturing for occlusion implants clusters in southern Germany near Stuttgart and Tuttlingen, creating geographic concentration risk that shapes procurement security calculations across European hospital networks.
United States
Hospital systems in the United States dedicate capital to interventional suite construction for structural heart procedures, anchoring demand for catheter-delivered occlusion systems. The FDA's breakthrough device designation pathway compresses commercialization timelines for novel occluder architectures. Integrated delivery networks negotiate direct manufacturer contracts that bypass traditional distributor margins.
Germany
German reimbursement frameworks support adult atrial septal defect closure programs previously managed surgically, expanding addressable procedure volumes. The EU MDR's enhanced clinical evidence requirements filter marginal competitors, consolidating volume among validated manufacturers. Cleanroom expansions near Stuttgart and Tuttlingen narrow import dependency for precision-manufactured occlusion implants.
Japan
Aging demographics and established reimbursement frameworks support procedure volumes for septal defect closure in Japanese hospital systems. The PMDA enforces stringent biocompatibility testing protocols under JIS T 0301 that filter out lower-capability suppliers from its reimbursement-eligible device registry. High-volume structural heart centers in Tokyo and Osaka adopt integrated catheter-occluder platforms within compressed procurement cycles.
India
Emerging alignment between India's CDSCO and IMDRF standards reduces duplicate clinical trial requirements, accelerating access to a cardiovascular procedure market with underpenetrated structural heart capabilities. The country's national pharmaceutical regulator harmonizes with international frameworks to streamline market entry. Metropolitan hospital networks in Mumbai and Delhi expand interventional cardiology capabilities to capture growing domestic demand.
United Kingdom
Health technology assessment methodologies in the United Kingdom increasingly predicate coverage on randomized trial data demonstrating superiority to surgical closure alternatives. The MHRA operates under retained EU MDR alignment while developing independent post-market surveillance capabilities. London-based cardiac centers consolidate purchasing around vendors with demonstrated post-market clinical follow-up execution capabilities.
Global Occlusion Devices Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying precision-manufactured nitinol wireforms and platinum-iridium constructs. The competitive structure consolidates around validated manufacturers with robust post-market clinical follow-up infrastructures capable of satisfying EU MDR decade-long surveillance requirements. Three archetypes dominate: integrated catheter-occluder platform providers, bioresorbable material research specialists, and precision alloy component fabricators. M&A activity targets captive refining arrangements for precious metal inputs, while strategic partnerships address fluoroscopy-trained interventionalist scarcity through bundled training and deployment support services.
Among diversified medical technology conglomerates, Boston Scientific Corporation, Medtronic, and Abbott Laboratories exemplify the platform integrator archetype, anchoring competitive positioning through integrated catheter-occluder systems and extensive clinical validation databases. These entities occupy positions where physician preference in high-volume centers translates into procurement committee consolidation, particularly in German and Japanese hospital systems with stringent post-market surveillance requirements. Their scale enables sustained investment in bioresorbable material research programs and superelastic wireform engineering that expands addressable anatomy in previously excluded patient cohorts.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott Laboratories |
| Johnson & Johnson |
| Stryker Corporation |
| Terumo Corporation |
| Cook Group |
| Edwards Lifesciences Corporation |
| Cardinal Health |
| Others |
Value Chain & Pricing Dynamics
Platinum-iridium cost volatility determines both the spread between premium and economy coil tiers and the geographic clustering of precision manufacturing capacity. Manufacturers without captive refining arrangements face margin compression that forces supply chain consolidation toward southern Germany's nitinol wireform clusters.
Pricing Analysis
The FDA's Class III PMA pathway dictates the pricing tier structure across occlusion device categories, separating breakthrough-designated premium architectures from standard PMA-track alternatives. Price differentiation rests on clinical validation depth and EU MDR PMCF infrastructure maturity, with German hospital systems least sensitive due to reimbursement security and ambulatory surgical facilities most exposed to procurement committee pressure. Cost compression in peripheral vascular coils is intensifying because precious metal input fluctuations transfer directly to spot-contract buyers.
Supply Chain Analysis
Export control restrictions on superelastic nitinol alloys and precision wireform manufacturing equipment limit technology transfer to emerging production hubs. Supply concentrates in Germany, Japan, and the United States, with raw material dependencies spanning nickel-titanium feedstock, platinum-iridium coil wire, and medical-grade polymeric matrices. Single-source vulnerability runs through Tuttlingen's cleanroom cluster for conformable waist plug geometries. Distribution runs through direct manufacturer contracts with integrated delivery networks, displacing traditional distributor margins in United States hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of fluoroscopy-trained interventionalists with 500-plus structural heart procedures creates a bottleneck that shapes competitive strategy across all stakeholder archetypes. This capability gap limits procedure volume expansion faster than fellowship pipelines can supply qualified operators.
For Market Incumbents: Build post-market clinical follow-up data moats that satisfy EU MDR decade-long surveillance requirements and consolidate purchasing around vendors with demonstrated registry execution. Deepen backward integration into nitinol alloy refining to offset platinum-iridium cost volatility. Capture channel control through direct-to-hospital contracts that exclude distributor margins in integrated delivery networks. For New Entrants and Emerging Players: India's underpenetrated structural heart capabilities offer the most accessible white-space expansion as CDSCO regulatory harmonization with IMDRF standards accelerates market entry. Target pediatric septal defect closure segments where bioresorbable material research programs command premium positioning. Deploy bundled training and deployment support services to address interventionalist scarcity in high-volume cardiac centers. For Investors and Strategic Acquirers: The EU MDR notified body capacity bottleneck reshapes the acquisition landscape by freezing time-to-revenue for uncertified assets and privileging validated manufacturers with existing PMCF infrastructures. Long-term viability across the analysis window favors precision alloy component fabricators with captive cleanroom capacity and demonstrated regulatory pathway execution. Watch for consolidation signals when notified body certification backlogs extend beyond eighteen months.| Strategic Initiative | Industry Significance |
|---|---|
| PMCF Infrastructure Investment | EU MDR Article 61 mandates decade-long implant surveillance that filters marginal competitors from German hospital procurement. |
| Bioresorbable Material R&D | Pediatric septal defect closure applications reward polymeric matrices that eliminate long-term implant complications. |
| Direct Hospital Contracting | United States integrated delivery networks negotiate manufacturer-direct agreements that disintermediate traditional distributor margins. |
| Interventionalist Training Partnerships | Fluoroscopy-trained operator scarcity constrains procedure volume expansion faster than fellowship pipelines can supply. |
| Nitinol Alloy Backward Integration | Captive refining arrangements insulate margin pools from platinum-iridium input volatility in peripheral vascular coils. |
Study Parameters
Initial hypotheses were tested against primary input from interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA PMA filings, EU MDR notified body certification databases, hospital procurement registries, and CMS Medicare procedure volume data. Bottom-up segmentation modeling triangulated with top-down macroeconomic drivers across product architecture, delivery modality, and application categories.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling coil occluders, plug occluders, balloon occluders, and stent occluders against end-user capital intensity tiers and regulatory pathway divergence. CAGRs derived from procedure volume elasticity to interventional suite construction, aging demographic penetration, and reimbursement framework stability. Forecast inputs incorporated nitinol alloy superelasticity advances and EU MDR PMCF infrastructure requirements as segment-specific growth modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by mid-cap specialists or accelerated FDA breakthrough designations would shift outcomes. Material shifts in Japan PMDA JIS T 0301 biocompatibility protocols or EU MDR notified body capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Acoustic Puncture Assist Devices Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Vaginal Pessary Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
External Defibrillator Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Endoprosthesis Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Global Large Volume Wearable Injectors Market