
 Global Transfection Reagents and Equipment Market | 2026-2036
Global Transfection Reagents and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transfection Reagents and Equipment Market Intelligence
Reagent customization revenue is rewriting margin economics across the transfection supply base. Thermo Fisher Scientific leverages its end-to-end platform breadth to capture recurring consumable spend. Promega Corporation anchors its position through specialized luciferase-based transfection validation workflows. Lonza Group Ltd. competes by dominating GMP-grade reagent production for clinical-grade cell engineering.
Transfection reagents and equipment comprise formulated lipid, polymer, or chemical carriers and physical delivery systems that introduce nucleic acids into eukaryotic cells with defined efficiency thresholds, typically measured by reporter gene expression percentages or cell viability retention. The primary purpose centers on enabling gene function studies, therapeutic protein expression, and cell line engineering across research and bioproduction settings. Lipofection agents and electroporation kits command the largest revenue pools, while nucleic acid delivery systems and viral vectors represent the fastest-growing categories as in vivo gene therapy manufacturing demands intensify. Chemical reagents retain maturity in standard plasmid DNA workflows, though margin compression pushes suppliers toward application-specific formulations.
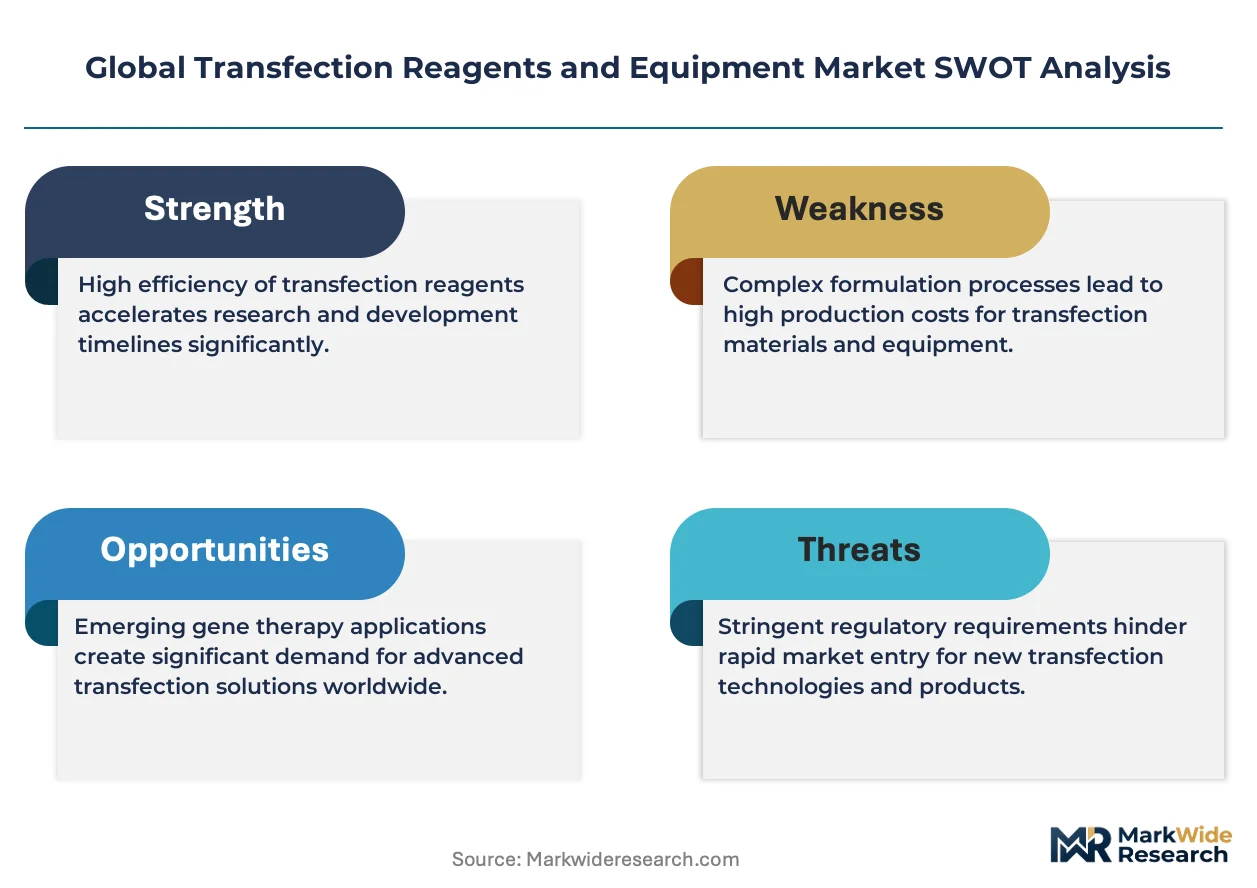
FDA gene therapy guidance and EMA advanced therapy medicinal product frameworks enforce potency assay and viral safety standards that elevate reagent qualification burdens. China's NMPA cell therapy technical guidelines and Japan's PMDA regenerative medicine frameworks add parallel compliance layers for cross-border clinical material supply. ISO 13485 and GMP annex expectations for ancillary materials further constrain supplier eligibility, concentrating procurement authority among certified manufacturers. Stakeholders must monitor evolving pharmacopeial monographs for synthetic vectors and electroporation buffer constituents to anticipate qualification-driven supplier consolidation.
Market Dynamics
Gene therapy manufacturing scale-up is compressing transfection technology cycles, forcing suppliers to bridge research-grade flexibility with GMP-grade reproducibility in single platforms.
Growth Catalysts
- EMA Advanced Therapy Medicinal Product frameworks:These guidelines mandate potency assay standardization that requires validated transfection workflows, pulling demand toward qualified reagent suppliers.
- Electroporation miniaturization:Microfluidic cell processing platforms now integrate nanoliter-scale electroporation, opening high-throughput screening applications previously blocked by volume constraints.
- China's NMPA cell therapy technical guidelines:Cross-border clinical material supply rules are concentrating procurement authority among certified ancillary material manufacturers with dual-hemisphere compliance capabilities.
Market Restraints
- Specialized lipid raw material concentration:Ionizable lipid synthesis capacity clusters among contract manufacturers in Switzerland and Germany, creating input bottlenecks for LNP-formulated reagents.
- ISO 13485 certification timelines:Ancillary material qualification under GMP annex expectations extends supplier onboarding to 18-24 months, freezing out emerging reagent developers.
- Viral vector persistence in workflows:Established gene therapy pipelines maintain dependence on lentiviral and AAV delivery systems, limiting near-term displacement by synthetic transfection alternatives.
Strategic Opportunities
- India's CDSCO regenerative medicine pathway:Accelerated cell therapy approval timelines are attracting CRO investment, creating demand for GMP-compatible transfection platforms in Bangalore and Hyderabad clusters.
- AI-driven formulation optimization:Machine learning models trained on lipid-nucleic acid interaction datasets are compressing reagent development cycles from years to months.
- Point-of-care cell engineering:Closed-system electroporation devices are enabling decentralized CAR-T manufacturing, bypassing centralized cleanroom infrastructure requirements.
Industry Challenges
- Cell therapy process engineer scarcity:GMP-grade transfection protocol development requires hybrid skill sets spanning immunology, bioprocessing, and regulatory science that outpace academic pipeline output.
- Legacy plasmid DNA workflow integration:Established research labs face technical debt when retrofitting chemically optimized transfection protocols into automated liquid handling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transfection Reagents and Equipment Market |
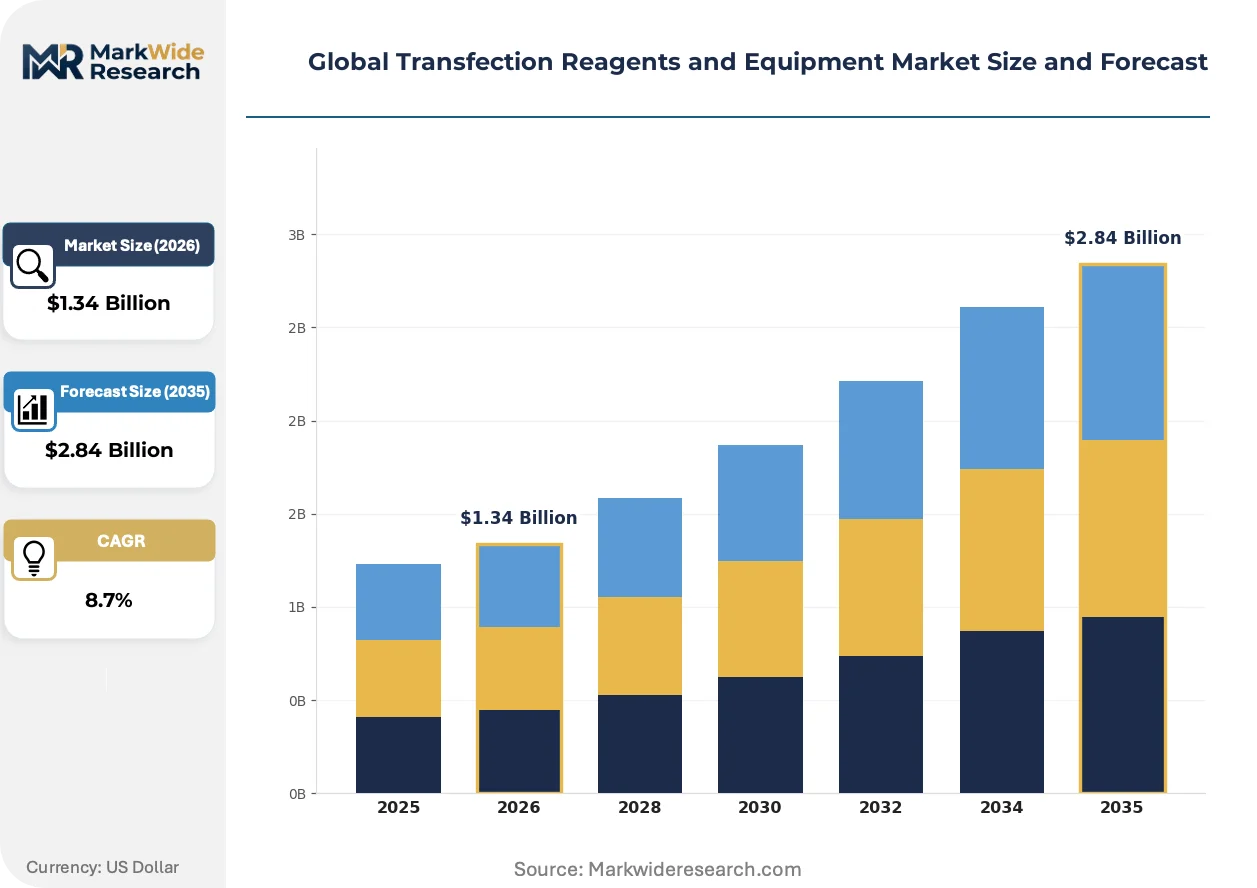
| Market Size in 2026 | $1.34 Billion |
| Market Size in 2035 | $2.84 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lipofection Agents, Electroporation Kits, Viral Vectors, Chemical Reagents, Nucleic Acid Delivery Systems Technology: Calcium Phosphate, Cationic Lipids, Polymeric Carriers, Electroporation Devices, Microinjection Application: Gene Expression Studies, RNA Interference, Protein Production, Cell Line Development, Vaccine Research End User: Biotechnology Firms, Academic Institutions, Pharmaceutical Developers, Contract Research Organizations, Diagnostic Companies |
| Companies Covered | Thermo Fisher Scientific Inc., Promega Corporation, F. Hoffmann-La Roche Ltd., Bio-Rad Laboratories Inc., QIAGEN N.V., Lonza Group Ltd., Merck KGaA, MaxCyte Inc., Polyplus-transfection SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transfection Reagents and Equipment Market Strategic Shifts & Innovations
Performance benchmarking is migrating from transfection efficiency percentages to integrated cell viability-productivity metrics that mirror bioproduction economics rather than research-grade optimization.
Microfluidic electroporation is migrating from specialized neuroscience applications toward mainstream T-cell engineering workflows. Academic labs and emerging cell therapy developers are adopting nanoliter-scale processing to preserve limited patient-derived material. The technology is migrating from boutique instrumentation toward platform-agnostic modules that slot into existing automated cell culture infrastructure, compressing capital barriers for mid-scale manufacturers.
REACH regulation amendments targeting nanomaterial classification are reshaping lipid nanoparticle reagent registration requirements in Europe. Suppliers must now document full substance characterization and exposure scenarios for ionizable lipids previously treated as standard formulation components. Contract manufacturers serving EMA-regulated trials are consolidating procurement around pre-registered lipid libraries to avoid registration delays.
Buying patterns are fragmenting between centralized bulk reagent procurement for GMP manufacturing and distributed, application-specific kit purchasing for discovery-stage programs. Large biopharma organizations are unbundling these categories, creating separate vendor pools and qualification tracks. The split is most visible in United States and German markets where gene therapy pipelines have matured into distinct research and clinical-stage operations with incompatible sourcing protocols.
Global Transfection Reagents and Equipment Market Segmentation
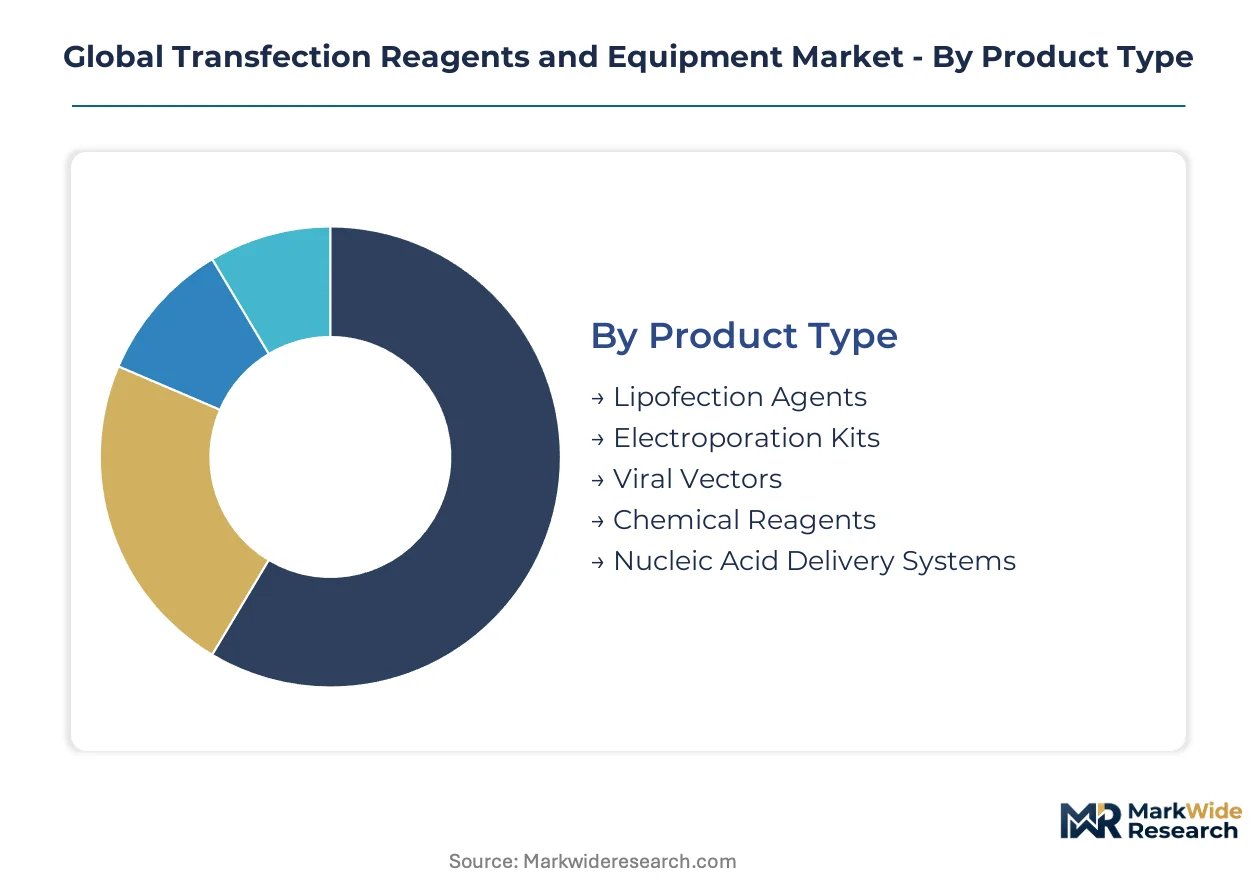
Segmentation in transfection markets reveals divergent procurement patterns between research-grade flexibility and GMP-grade reproducibility requirements. Suppliers must architect distinct service models for each tier, as after-sales technical support intensity varies dramatically across validation, qualification, and troubleshooting demands.
Product Type:
After-sales service intensity peaks with electroporation platforms requiring field calibration and protocol optimization, while reagent categories demand formulation troubleshooting and lot-to-lot consistency support.
- Electroporation Kits:These devices apply controlled electrical pulses to transiently permeabilize cell membranes, enabling nucleic acid entry without chemical carriers. Demand concentrates in United States and German cell therapy manufacturing facilities where GMP-compliant protocol validation drives recurring service contracts. Field engineers spend 40-60 hours per installation optimizing voltage parameters for specific cell types.
- Lipofection Agents:Cationic lipid formulations complex with nucleic acids to facilitate endosomal escape and cytoplasmic delivery. Academic institutions in China and Japan anchor volume procurement for plasmid DNA workflows, though margin compression pushes suppliers toward application-specific customization services.
- Viral Vectors:Lentiviral and adeno-associated virus packaging systems dominate persistent gene therapy pipelines.
- Chemical Reagents:Calcium phosphate and DEAE-dextran formulations retain maturity in legacy research protocols.
- Nucleic Acid Delivery Systems:Lipid nanoparticle and polymer-based platforms are gaining share in mRNA therapeutics manufacturing.
By volume, lipofection agents lead. By growth pace, nucleic acid delivery systems are expanding most quickly.
Technology:
Cost tier differentiation separates premium instrument platforms from commodity reagent chemistries, with hybrid offerings capturing mid-market budgets.
- Electroporation Devices:Benchtop and high-throughput systems deliver pulsed electric fields with programmable waveform parameters. Biotechnology firms in Boston and San Diego clusters drive premium instrument procurement as CAR-T manufacturing scales. Capital equipment sales bundle multi-year service agreements covering electrode replacement and software updates.
- Cationic Lipids:Ionizable and permanently charged lipid molecules form complexes with negatively charged nucleic acids through electrostatic interaction. Swiss and German contract manufacturers control synthesis capacity for clinical-grade material, creating supply concentration for EMA-regulated trials. Formulation optimization services command 15-25% price premiums over standard catalog offerings.
- Polymeric Carriers:Polyethylenimine and chitosan derivatives offer alternative complexation chemistry for sensitive cell types.
- Calcium Phosphate:Established co-precipitation method retains use in stable cell line generation workflows.
- Microinjection:Direct physical delivery remains specialized for embryo manipulation and single-cell applications.
By installed base, electroporation devices dominate. By revenue expansion, cationic lipids are climbing the fastest.
Application:
Customer type fragmentation splits procurement between centralized bioproduction facilities and distributed discovery laboratories with incompatible sourcing protocols.
- Cell Line Development:Stable transfection workflows for biopharmaceutical production cell engineering demand GMP-grade reagent qualification. Pharmaceutical developers in Germany and Switzerland enforce ancillary material certification under ISO 13485 and EMA guidelines. Supplier audits consume 6-12 months before approved vendor status.
- Gene Expression Studies:Transient transfection for protein function research prioritizes efficiency and throughput over regulatory documentation. Academic institutions across United States, China, and Japan represent high-volume, price-sensitive demand with minimal after-sales service requirements.
- Vaccine Research:mRNA and DNA vaccine platform development is pulling demand toward scalable transfection technologies.
- RNA Interference:siRNA and shRNA delivery applications concentrate in oncology and infectious disease research programs.
- Protein Production:Recombinant protein expression workflows span both research and GMP-grade manufacturing tiers.
By project volume, gene expression studies lead. By qualification intensity, cell line development is gaining share fastest.
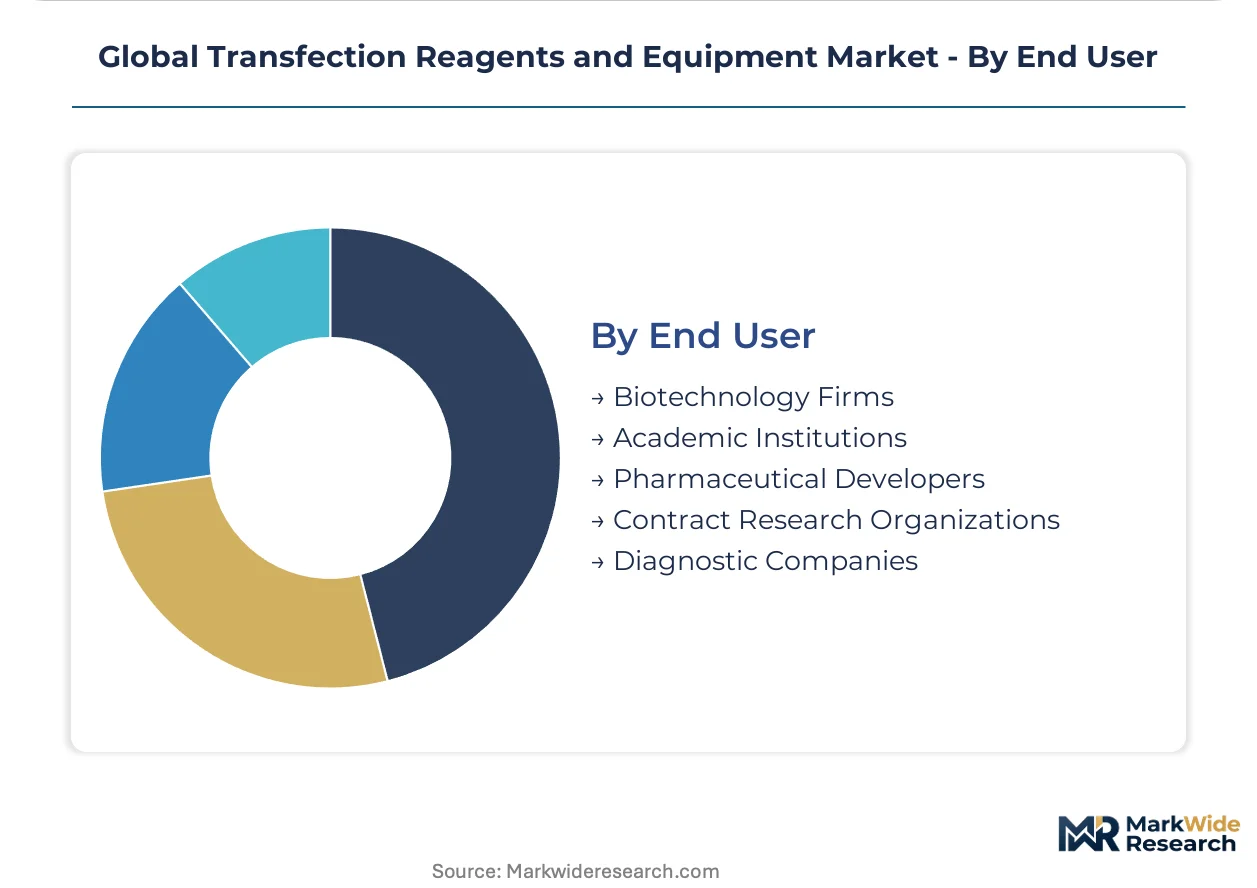
End User:
Supply concentration among certified manufacturers shapes vendor eligibility, with procurement authority clustering among organizations with dual-hemisphere compliance capabilities.
- Biotechnology Firms:Cell and gene therapy developers integrate transfection platforms into automated manufacturing workflows. United States-based firms in Cambridge and South San Francisco clusters are driving instrument procurement as pipeline assets advance toward commercialization. Technical support demands span installation, validation, and continuous process improvement.
- Contract Research Organizations:CDMOs serving multiple sponsor programs require flexible platform configurations with rapid protocol switching capabilities. Bangalore and Hyderabad clusters in India are attracting investment under CDSCO accelerated pathways, creating demand for GMP-compatible systems with localized service coverage.
- Pharmaceutical Developers:Large biopharma organizations maintain separate vendor pools for research and clinical-stage operations.
- Academic Institutions:University labs prioritize cost efficiency and publication-grade reproducibility over regulatory documentation.
- Diagnostic Companies:Cell-based assay developers require validated transfection for reference standard production.
By spending volume, biotechnology firms lead. By procurement growth, contract research organizations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic buyers in China and Japan exhibit the sharpest price sensitivity, while United States and German biotechnology firms absorb premium pricing for GMP-grade qualification documentation without volume elasticity.
United States
FDA gene therapy guidance enforces potency assay standards that pull procurement toward qualified ancillary material suppliers. The Cambridge and South San Francisco clusters anchor CAR-T manufacturing scale-up, driving electroporation platform installations with bundled multi-year service agreements. Biotechnology firms here prioritize single-platform solutions bridging research flexibility and GMP reproducibility.
Germany
EMA advanced therapy medicinal product frameworks mandate viral safety documentation that extends supplier onboarding timelines. Swiss and German contract manufacturers concentrate ionizable lipid synthesis capacity, creating input bottlenecks for lipid nanoparticle reagents. The Munich and Heidelberg regions host cell therapy process development facilities requiring ISO 13485-certified reagent streams.
China
NMPA cell therapy technical guidelines impose cross-border clinical material rules that concentrate procurement authority among dual-hemisphere compliant manufacturers. Beijing and Shanghai academic institutions drive lipofection agent volume for plasmid DNA workflows. Price competition here compresses margins, pushing suppliers toward application-specific formulation services.
Switzerland
Swissmedic enforcement of GMP annex expectations for ancillary materials constrains supplier eligibility to certified manufacturers. Basel and Zurich anchor clinical-grade lipid production for EMA-regulated trials. Contract manufacturers here consolidate procurement around pre-registered lipid libraries to avoid REACH nanomaterial registration delays.
India
CDSCO accelerated regenerative medicine pathways attract CRO investment to Bangalore and Hyderabad clusters. Demand concentrates for GMP-compatible transfection platforms with localized service coverage. Procurement growth here outpaces mature markets as cell therapy developers seek cost-efficient manufacturing infrastructure.
Global Transfection Reagents and Equipment Market Key Industry Players
Capability concentration sits with specialized reagent formulators; scale advantage sits with diversified life science conglomerates. The market structures around three tiers: end-to-end platform providers capturing recurring consumable spend, GMP-grade specialists dominating clinical material supply, and regional reagent houses serving price-sensitive academic segments. Dominant competitive moves include strategic partnerships for lipid synthesis capacity and portfolio diversification into automated delivery systems.
Within the GMP-grade specialist tier, Lonza Group Ltd. and Polyplus-transfection SA exemplify qualification-focused positioning. Thermo Fisher Scientific Inc. anchors the diversified platform tier with breadth spanning research through clinical-grade workflows. These three represent distinct archetypes: the Swiss-based GMP pure-play, the French transfection-focused developer, and the United States-based conglomerate integrating instrumentation with consumable streams.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Promega Corporation |
| F. Hoffmann-La Roche Ltd. |
| Bio-Rad Laboratories Inc. |
| QIAGEN N.V. |
| Lonza Group Ltd. |
| Merck KGaA |
| MaxCyte Inc. |
| Polyplus-transfection SA |
| Others |
Cost & Logistics Intelligence
Basel and Zurich anchor clinical-grade ionizable lipid synthesis for EMA-regulated trials, concentrating upstream capacity among Swiss-German contract manufacturers and amplifying pricing power for GMP-certified reagent streams over standard research-grade alternatives.
Pricing Analysis
Multi-year service contracts covering electrode replacement, field calibration, and protocol optimization drive lifetime value for electroporation platforms, with pricing stratifying across premium GMP-qualified, standard research-grade, and economy catalog tiers. Certification under ISO 13485 and EMA advanced therapy frameworks commands 15-25% premiums over unqualified alternatives. Cost compression in academic lipofection segments intensifies as Chinese and Japanese institutions consolidate procurement around domestic suppliers. Biotechnology firms in United States and German clusters absorb premium pricing without volume elasticity; academic buyers exhibit sharpest price sensitivity.
Supply Chain Analysis
Export-control scrutiny on microfluidic electroporation instrumentation and lipid nanoparticle manufacturing equipment constrains technology transfer to certain jurisdictions, complicating cross-border platform deployment. Ionizable lipid synthesis capacity clusters in Switzerland, Germany, and select United States contract manufacturing organizations; polynucleotide raw materials and specialized electrode alloys draw from East Asian and North American suppliers. Single-source vulnerability persists for clinical-grade cationic lipid libraries qualified under REACH nanomaterial frameworks. Distribution runs through direct field service teams for capital equipment and authorized distributors for consumable reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from GMP qualification support, field protocol optimization, and recurring consumable streams is expanding faster than hardware sales, making after-sales intensity the defining profit architecture for suppliers bridging research and clinical-grade workflows.
For Market Incumbents: Entrench platform dominance by deepening captive supply of ionizable lipid libraries through backward integration into Swiss-German synthesis capacity, and by embedding field engineering teams within CAR-T manufacturing clusters to capture multi-year service contracts that emerging competitors cannot replicate. For New Entrants and Emerging Players: Establish a beachhead in India's Bangalore and Hyderabad CRO clusters by offering GMP-compatible electroporation platforms with localized service coverage at 30-40% capital cost disadvantage to premium incumbents, targeting CDSCO-accelerated cell therapy developers seeking cost-efficient manufacturing infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized reagent formulators with locked EMA-FDA dual-hemisphere qualification over diversified conglomerates facing margin compression in commoditized research segments. Long-term viability hinges on lipid-nucleic acid formulation IP and installed base service density. Watch for inflection when AI-driven formulation optimization compresses development cycles below 12 months, eroding specialist moats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lipid Synthesis | Captive supply of ionizable lipids insulates margins from Swiss-German contract manufacturer bottlenecks. |
| GMP Qualification Service Bundling | Multi-year validation contracts with CAR-T developers lock out emerging reagent competitors. |
| AI-Driven Formulation Optimization | Machine learning compression of reagent development cycles from years to months reshapes R&D economics. |
| Localized Service Coverage in India | Bangalore and Hyderabad field teams capture CDSCO-accelerated cell therapy procurement growth. |
| REACH Nanomaterial Pre-Registration | Pre-registered lipid libraries avoid registration delays that freeze out uncertified suppliers. |
Research Approach
Initial hypotheses were tested against primary input from cell therapy process engineers, regulatory affairs specialists at gene therapy developers, GMP facility quality directors, and academic lab procurement managers, and refined through secondary validation against FDA gene therapy guidance documents, EMA advanced therapy medicinal product submissions, NMPA cell therapy technical guidelines, ISO 13485 certification databases, and REACH nanomaterial registration records. Bottom-up reagent volume estimates and top-down instrument installation counts were triangulated to resolve segmentation splits.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by reagent chemistry and device platform, technology tiering by GMP qualification status, application splits between research and clinical-grade workflows, and end-user concentration among biotechnology firms, CROs, and academic institutions. CAGRs were derived from weighted regression of segment growth rates against pipeline advancement timelines and regulatory approval velocity, with specific inputs from CAR-T manufacturing scale-up trajectories and mRNA therapeutic platform expansion.
Sensitivities concentrate around EMA-FDA regulatory divergence on potency assay standards, REACH nanomaterial classification amendments, and ionizable lipid synthesis capacity expansion timelines. Forecasts reflect documented assumptions on gene therapy pipeline maturation and electroporation miniaturization adoption curves. Material shifts in GMP ancillary material qualification requirements or export control regimes on microfluidic instrumentation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Lab Automation in Bioanalysis Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
PCR Consumables Market
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market